
 Asia-Pacific Data Center Robotics Market | 2026-2036
Asia-Pacific Data Center Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Data Center Robotics Market Analytics
The gap between premium robotics systems with full sensor fusion and commodity units with basic navigation is recalibrating procurement patterns across Asia-Pacific data centers. Huawei Technologies leverages its in-house chip design to anchor integrated robot-server ecosystems in Chinese facilities. FANUC Corporation dominates precision servo manufacturing for robotic arms deployed in Japanese hyperscale sites. ABB Ltd competes through its electrification-robotics convergence strategy across Southeast Asian markets.
Data center robotics encompasses autonomous machines engineered for environmental monitoring, server rack manipulation, and infrastructure maintenance within climate-controlled computing facilities, typically operating within temperature ranges of 18°C to 27°C and humidity bands of 40% to 60% RH to preserve equipment integrity. Autonomous Mobile Robots lead current deployment volumes as facility operators prioritize floor patrol and thermal mapping applications. Robotic Arms capture concentrated margin pools in rack-dense environments where millimeter-precision component handling reduces human error rates. Cloud-Based deployment architectures for robot fleet management are expanding fastest as colocation providers seek centralized oversight across distributed sites.
Japan's METI enforces energy efficiency benchmarks that directly shape robot procurement specifications for cooling system automation. China's MIIT and GB standards mandate data center power usage effectiveness thresholds that drive robotics integration in facility optimization. Australia's TGA-equivalent electrical safety frameworks and South Korea's MFDS-aligned industrial equipment certifications govern product access across their respective markets. Stakeholders must weigh sovereign cloud requirements against cross-border robot software update protocols when selecting deployment architectures.
Market Dynamics
China's MIIT power usage effectiveness mandates are compressing hardware refresh cycles and forcing facility operators to automate thermal management through robotics integration rather than incremental cooling upgrades.
Growth Catalysts
- Japan's METI energy benchmarks:Cooling system automation specifications now require robotic precision for chiller optimization and airflow management in hyperscale facilities.
- Server rack density escalation:AI training clusters exceeding 50kW per rack demand millimeter-accurate component handling that exceeds human physical limits.
- Tokyo-Osaka corridor labor shortages:Aging facility workforces are accelerating replacement timelines for autonomous mobile robots in floor patrol applications.
Market Restraints
- Precision servo supply concentration:Japanese and German component suppliers control critical motion control hardware, creating procurement bottlenecks for Chinese integrators.
- Sensor fusion cost structure:LiDAR and thermal imaging arrays constitute 35-45% of autonomous robot bill-of-materials, constraining deployment scale.
- Cross-border software update protocols:China's cybersecurity law and Australia's TGA-equivalent frameworks impose conflicting data sovereignty requirements on cloud-based fleet management.
Strategic Opportunities
- Southeast Asian colocation expansion:Singapore and Indonesia greenfield builds lack legacy infrastructure constraints, enabling native robotics architecture from commissioning.
- GB standard compliance services:Robotics vendors can bundle energy optimization software with hardware sales to meet China's dual carbon goals.
- Robotic arms plus digital twin convergence:Real-time physics simulation enables predictive maintenance before physical intervention, reducing mean time to repair.
Industry Challenges
- Multi-protocol integration complexity:Facilities operate mixed vendor environments where proprietary robot APIs conflict with existing building management systems.
- MFDS-aligned certification timelines:South Korea's industrial equipment safety validation extends product launch cycles by 8-14 months for foreign suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Data Center Robotics Market |
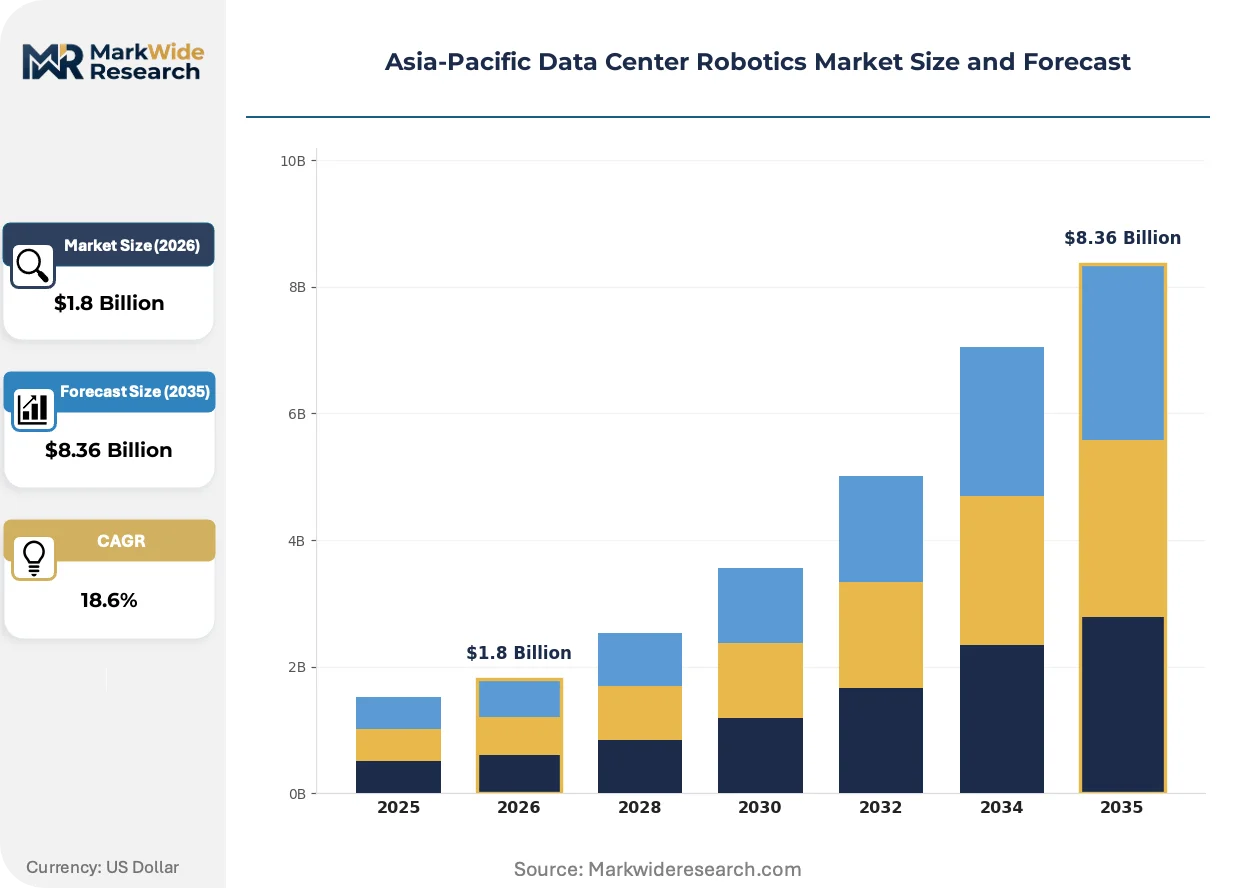
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autonomous Mobile Robots, Robotic Arms, Automated Guided Vehicles, Collaborative Robots End User: Telecommunications, Cloud Service Providers, Enterprises, Colocation Providers Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Service Type: Maintenance, Integration, Consulting, Managed Services |
| Companies Covered | Huawei Technologies, ABB Ltd, Cisco Systems Inc, Equinix Inc, Microsoft Corp, NTT Data Group Corp, Siemens AG, FANUC Corporation, Yaskawa Electric Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Data Center Robotics Market Evolving Landscape
Sensor fusion architectures and sovereign cloud requirements are bifurcating product roadmaps across Asia-Pacific facilities, with premium systems separating from commodity navigation units.
Digital twin simulation for predictive maintenance is electrifying deployment economics for cloud service providers. Microsoft Azure and Alibaba Cloud facilities are integrating physics-based models that forecast thermal anomalies 72 hours before hardware failure. This capability compresses service contract pricing by unbundling reactive maintenance from capital equipment sales.
China's MIIT guidelines on data center energy efficiency are mandating real-time power usage effectiveness monitoring that robotics vendors must embed at the firmware level. Facilities in Beijing and Shanghai now require automated reporting interfaces that bypass traditional building management system middleware. This regulatory architecture favors integrated robot-server ecosystems over standalone automation units.
Colocation buyers are consolidating vendor relationships around full-stack thermal optimization providers. Equinix and Digital Realty are phasing out point solutions for floor patrol in favor of contracts spanning autonomous mobile robots, robotic arms, and AI-driven cooling software. Australia and South Korea exhibit the fastest channel consolidation as facility operators seek single-accountability partners for uptime guarantees.
Asia-Pacific Data Center Robotics Market Segmentation
Hardware refresh cycles and cooling optimization mandates across Asia-Pacific facilities are fragmenting procurement patterns. Buyers now select robot architectures based on specific workload densities and regulatory compliance tiers rather than universal platform standards.
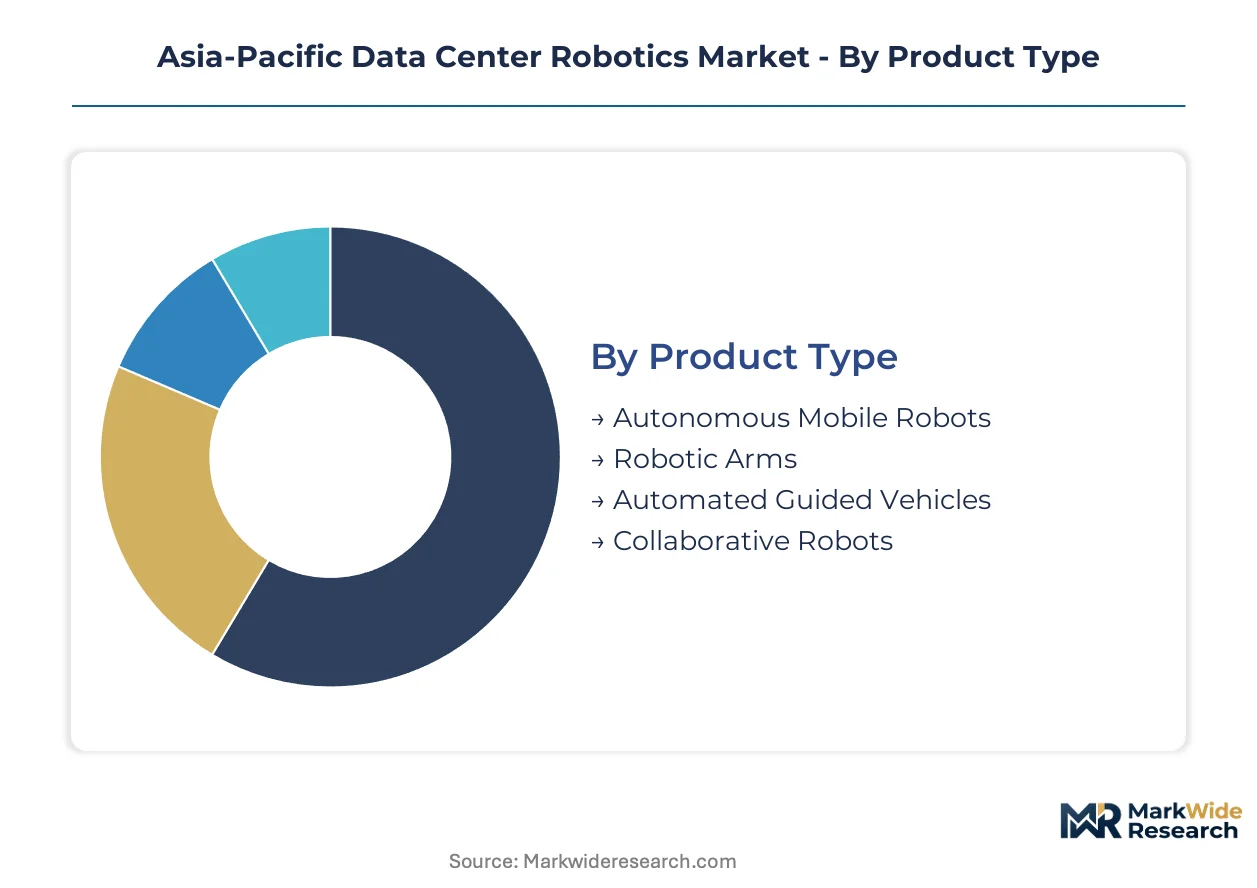
Product Type:
Upgrade cycles favor systems with embedded sensor fusion over basic navigation units as facilities replace first-generation deployments.
- Autonomous Mobile Robots:These units integrate LiDAR, thermal imaging, and SLAM navigation for floor patrol and thermal mapping. Demand concentrates in Japan's Tokyo-Osaka corridor where aging workforces accelerate replacement timelines for facility surveillance.
- Robotic Arms:Precision servo systems enable millimeter-accurate server component handling in rack-dense environments. Cloud service providers in China prioritize these units for AI training clusters exceeding 50kW per rack where human physical limits constrain manual intervention.
- Automated Guided Vehicles:Magnetic tape or QR-code guided transport systems move hardware between staging and operational zones.
- Collaborative Robots:Force-limited articulated arms operate alongside technicians during maintenance windows.
Volume placements concentrate in Autonomous Mobile Robots; the faster expansion belongs to Robotic Arms.
End User:
Cost tier differentiation separates hyperscale operators with captive engineering teams from mid-market buyers dependent on system integrators.
- Cloud Service Providers:Alibaba Cloud and Microsoft Azure facilities deploy physics-based digital twins for predictive maintenance. These operators unbundle reactive service contracts from capital equipment sales, compressing vendor pricing power.
- Colocation Providers:Equinix and Digital Realty consolidate vendor relationships around full-stack thermal optimization spanning mobile robots, arms, and AI-driven cooling software. Australia's channel consolidation accelerates fastest as operators seek single-accountability uptime partners.
- Telecommunications:NTT and Singtel facilities prioritize edge computing robotics for distributed 5G infrastructure.
- Enterprises:Financial services and healthcare captive data centers favor on-premise deployment with strict data sovereignty controls.
Cloud Service Providers dominate current procurement volumes; Colocation Providers are climbing the fastest as greenfield builds in Southeast Asia adopt native robotics architecture.
Deployment:
Application requirements dictate architecture selection between centralized oversight and localized autonomy.
- Cloud-Based:Fleet management platforms enable centralized oversight across distributed sites. China's cybersecurity law and Australia's TGA-equivalent frameworks impose conflicting data sovereignty requirements that constrain cross-border software update protocols.
- On-Premises:Localized control systems satisfy sovereign cloud mandates in government and defense facilities.
- Hybrid:Split architectures process sensitive telemetry locally while pushing non-critical analytics to central clouds.
- Edge Computing:Minimal-footprint units operate with intermittent connectivity at remote cell towers and factory floors.
Cloud-Based architectures lead deployment volumes; Edge Computing configurations are gaining share fastest as 5G infrastructure proliferates.
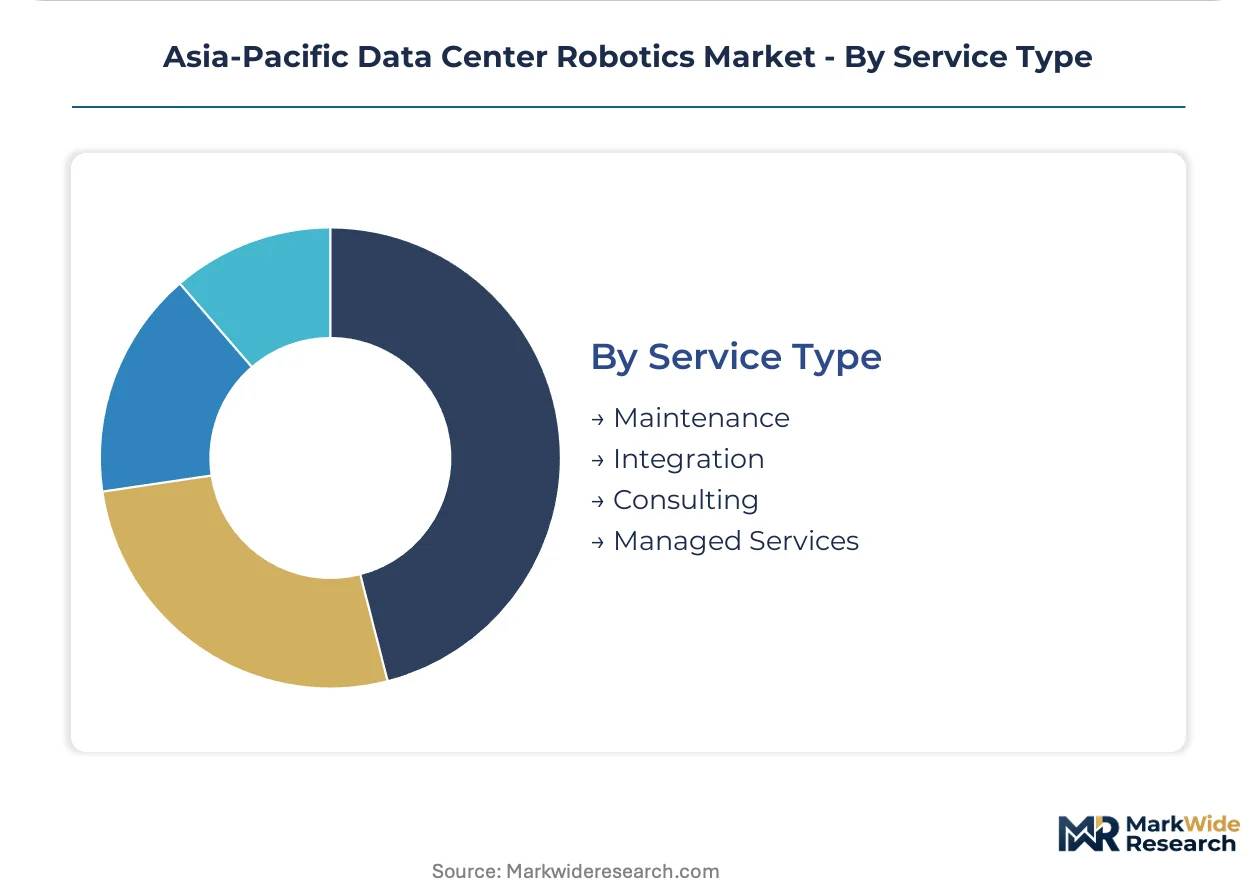
Service Type:
Customer maturity determines whether buyers purchase standalone hardware or bundled lifecycle support.
- Integration:System architects configure robot APIs with existing building management systems. Multi-protocol complexity in mixed-vendor environments extends deployment timelines and inflates professional services margins.
- Maintenance:Predictive service contracts leverage thermal anomaly forecasting to preempt hardware failures.
- Consulting:GB standard compliance advisory helps vendors bundle energy optimization software with hardware sales.
- Managed Services:Full outsourcing of robot fleet operations appeals to enterprises lacking captive robotics expertise.
Integration services capture the largest contract values; Managed Services are expanding most quickly as skills shortages persist.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo anchors the Asia-Pacific data center robotics landscape through its hyperscale corridor with Osaka, where aging facility workforces and METI energy mandates converge to accelerate automation procurement.
Japan
Japan's METI enforces energy efficiency benchmarks that directly shape robot procurement specifications for cooling system automation. The Tokyo-Osaka corridor concentrates demand as aging facility workforces accelerate replacement timelines for autonomous mobile robots in floor patrol applications. Osaka-based hyperscale operators prioritize millimeter-precision robotic arms for rack-dense environments exceeding 50kW per rack.
China
China's MIIT power usage effectiveness mandates compress hardware refresh cycles and force facility operators to automate thermal management through robotics integration. Beijing and Shanghai facilities now require automated reporting interfaces that bypass traditional building management system middleware. Huawei Technologies anchors integrated robot-server ecosystems in these Tier-1 cities.
Australia
Australia's TGA-equivalent electrical safety frameworks govern product access while colocation buyers consolidate vendor relationships around full-stack thermal optimization providers. Sydney and Melbourne exhibit the fastest channel consolidation as facility operators seek single-accountability partners for uptime guarantees. Greenfield builds in these metros lack legacy infrastructure constraints.
South Korea
South Korea's MFDS-aligned industrial equipment certifications extend product launch cycles by 8-14 months for foreign suppliers. Seoul Capital Area facilities prioritize edge computing robotics for distributed 5G infrastructure. Busan-Ulsan corridor operators navigate certification timelines while deploying autonomous mobile robots for environmental monitoring.
Singapore
Singapore's greenfield colocation expansion lacks legacy infrastructure constraints, enabling native robotics architecture from commissioning. The city-state's sovereign cloud requirements shape deployment architecture selection between centralized oversight and localized autonomy. Regional headquarters for global cloud providers anchor procurement decisions for Southeast Asian distributed sites.
Asia-Pacific Data Center Robotics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across sensor fusion capability and integrated ecosystem depth. The vendor base stratifies into three tiers: full-stack thermal optimization providers commanding service contract bundling, precision servo specialists capturing concentrated margin pools in rack-dense environments, and commodity navigation unit assemblers facing procurement pattern compression. Strategic archetypes include integrated robot-server ecosystem builders, precision motion control hardware suppliers, and electrification-robotics convergence specialists. Dominant competitive moves span vendor relationship consolidation around single-accountability uptime partners and firmware-level regulatory compliance embedding.
Within the integrated ecosystem tier, Huawei Technologies exemplifies the captive chip design-to-deployment model, while ABB Ltd occupies a position representing electrification-robotics convergence strategies across Southeast Asian markets. FANUC Corporation anchors the precision servo manufacturing archetype for robotic arms deployed in Japanese hyperscale sites. These three companies represent the strategic positioning spectrum from hardware-centric to software-integrated competitive approaches.
| Leading Market Players |
|---|
| Huawei Technologies |
| ABB Ltd |
| Cisco Systems Inc |
| Equinix Inc |
| Microsoft Corp |
| NTT Data Group Corp |
| Siemens AG |
| FANUC Corporation |
| Yaskawa Electric Corporation |
| Others |
Value Network & Pricing Analysis
Precision servo motors from Japanese and German suppliers cascade through three pricing tiers as they reach Chinese integrators and Southeast Asian facility operators, with LiDAR and thermal imaging arrays constituting the dominant cost stack in autonomous robot bill-of-materials.
Pricing Analysis
Uptime guarantees anchor value-based pricing for data center robotics, with colocation providers contracting full-stack thermal optimization spanning mobile robots, arms, and AI-driven cooling software. Price differentiation rests on sensor fusion capability and GB standard firmware compliance, with premium systems commanding service contract bundling. Cost compression in commodity navigation units is intensifying because Chinese integrators face procurement bottlenecks for precision motion control hardware. Mid-market buyers dependent on system integrators exhibit highest price sensitivity; hyperscale operators with captive engineering teams prioritize performance over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for robotic arms in rack-dense environments, while system integrators serve mid-market colocation providers across Southeast Asia. Component manufacturing concentrates in Japan, Germany, and China, with precision servo supply anchored in Japanese suppliers and LiDAR sensor production centered on Chinese and German sources. The supply chain draws from rare earth magnet dependencies for servo motors and semiconductor content for sensor fusion chipsets. Single-source vulnerability in precision motion control hardware creates procurement risk for facility operators automating thermal management. Distribution runs through certified integration partners in Australia and South Korea where MFDS-aligned certification extends validation timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around full-stack thermal optimization providers as colocation buyers phase out point solutions, with sensor fusion cost structure forcing weaker assemblers into margin compression or exit.
For Market Incumbents: Anticipate procurement pattern compression by deepening backward integration into precision servo manufacturing or captive chip design-to-deployment ecosystems. Defensive consolidation moves include bundling GB standard compliance software with hardware sales to meet China's dual carbon goals, and embedding firmware-level regulatory interfaces that bypass traditional building management system middleware. Threats include Huawei Technologies' integrated robot-server ecosystems and FANUC Corporation's precision servo dominance in Japanese hyperscale sites. For New Entrants and Emerging Players: Enter via edge computing robotics for distributed 5G infrastructure in South Korea's Seoul Capital Area and Singapore's greenfield colocation expansion, where native robotics architecture lacks legacy infrastructure constraints. The most penetrable segment is managed services for enterprises lacking captive robotics expertise. A specific go-to-market angle is physics-based digital twin convergence for predictive maintenance, compressing reactive service contract pricing before physical intervention. For Investors and Strategic Acquirers: MFDS-aligned certification timeline extensions for foreign suppliers is the leading indicator that South Korean market access will favor acquired capabilities over organic buildout. Long-term viability centers on vendors with integrated ecosystem depth spanning sensor fusion, regulatory firmware embedding, and cloud-based fleet management architectures. Acquisition target archetype: precision motion control specialists with existing certification pathways in Japan and South Korea. Signal to watch: colocation provider consolidation around single-accountability uptime partners in Australia and Southeast Asia.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Servo Manufacturing | FANUC Corporation's dominance in Japanese hyperscale sites demonstrates captive motion control value. |
| Firmware-Level GB Standard Compliance Embedding | Beijing and Shanghai facilities now require automated reporting interfaces bypassing traditional middleware. |
| Digital Twin Convergence for Predictive Maintenance | Microsoft Azure and Alibaba Cloud facilities integrate physics-based models forecasting thermal anomalies. |
| Single-Accountability Uptime Partnership Consolidation | Equinix and Digital Realty are phasing out point solutions for full-stack thermal optimization contracts. |
| Edge Computing Robotics for 5G Infrastructure | NTT and Singtel facilities prioritize distributed robotics at remote cell towers and factory floors. |
Research Methodology
Independent corroboration across facility operations directors, robotics procurement leads, and system integration specialists underwrites the qualitative findings, validated against MIIT regulatory filings, METI energy benchmark disclosures, hyperscaler capex reports, and customs trade data for precision servo imports. Primary interviews with data center engineering heads and colocation provider vendor management teams combined with secondary source triangulation anchors the analysis. Bottom-up unit deployment estimates and top-down market sizing reconciliation stress-test segmentation assumptions across product type, end user, and deployment architecture dimensions.
Comparable-period historical reference anchored the forecast window to observed hardware refresh cycles and regulatory mandate implementation timelines across the projection horizon. The analytical framework models segmentation dimensions including robot product type, end-user category, deployment architecture, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to facility automation penetration rates and cooling optimization investment cycles. Industry-specific forecast inputs include power usage effectiveness mandate compliance deadlines and aging workforce replacement timelines in Japan's Tokyo-Osaka corridor.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sovereign cloud requirement shifts or cross-border software update protocol disruptions. Periodic stress-testing of base assumptions is recommended, particularly regarding precision servo supply concentration and sensor fusion cost trajectory assumptions that could revise deployment scale projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Search and Rescue Robots Market
Robotics and Automation
Robotics for NDT Market
Robotics and Automation
AI Assisted Robots Market
Robotics and Automation
Underwater Rescue Robot Market
Robotics and Automation
North America AUV and ROV Market
Robotics and Automation
Global Underwater Robotics Market
Robotics and Automation
Virtual 3D Nanorobots Market
Robotics and Automation
Robotics and Automation Actuators Market
Robotics and Automation
Soft Exoskeleton Market
Robotics and Automation
Autonomous Security Robots Market
Robotics and Automation
United Kingdom Cloud Robotics Market
Robotics and Automation
Mobile Stabilizer Market
Robotics and Automation
Service Robotics Market
Robotics and Automation
Commercial Security Robots Market
Robotics and Automation
Global Robotics Market
Robotics and Automation
United States Articulated Robot Market