
 Virtual 3D Nanorobots Market | 2026-2036
Virtual 3D Nanorobots Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual 3D Nanorobots Market Analytics
The capital-intensity divergence between well-funded synthetic biology platforms and specialized instrumentation houses is rotating competitive dynamics across the sector. Ginkgo Bioworks leverages its automated foundry infrastructure to dominate prototype-to-scale workflows for nanoscale agents. Bruker Corporation anchors its position through advanced metrology systems that sustain precision requirements in 3D nanorobotics fabrication.
Virtual 3D nanorobots comprise computationally designed nanoscale machines—typically 1-100 nm in dimension—engineered through biomimetic architectures or magnetic manipulation frameworks to perform programmed tasks in simulated or physical environments. Their primary commercial purpose centers on precision intervention at cellular or molecular scales, particularly for targeted drug delivery and diagnostics. Nanoscale agents and swarm systems attract the deepest R&D investment pools, while machine learning integration represents the fastest-expanding technology dimension as algorithmic control replaces manual parametric tuning. Magnetic manipulation retains mature industrial adoption in materials science applications where optical tweezers remain cost-prohibitive at production scale.
The FDA oversees clinical translation pathways for nanotechnology-enabled therapeutics, while ISO nanotechnology technical committees establish dimensional and safety benchmarks for cross-border commercialization. REACH compliance in Europe shapes material selection constraints for companies pursuing dual-market access. Stakeholders must monitor evolving preclinical validation standards as regulatory bodies harmonize nanorobot-specific efficacy thresholds across jurisdictions.
Market Dynamics
Machine learning integration is fragmenting control architectures across nanorobotics platforms, compressing development cycles from months to weeks while elevating algorithmic precision requirements for FDA pre-submission packages.
Growth Catalysts
- Biomimetic engineering frameworks:Pharmaceutical manufacturers in Boston and San Francisco deploy synthetic biology platforms to accelerate nanoscale agent prototyping. Automated foundry infrastructure reduces iteration costs for targeted therapeutic designs.
- REACH material compliance pathways:European manufacturers gain dual-market access through harmonized safety benchmarks. ISO nanotechnology technical committees establish dimensional standards that streamline cross-border commercialization.
- Magnetic manipulation maturation:Materials science applications in Germany and Japan adopt production-scale magnetic control systems. Cost structures now favor these frameworks over optical tweezers at industrial volume.
Market Restraints
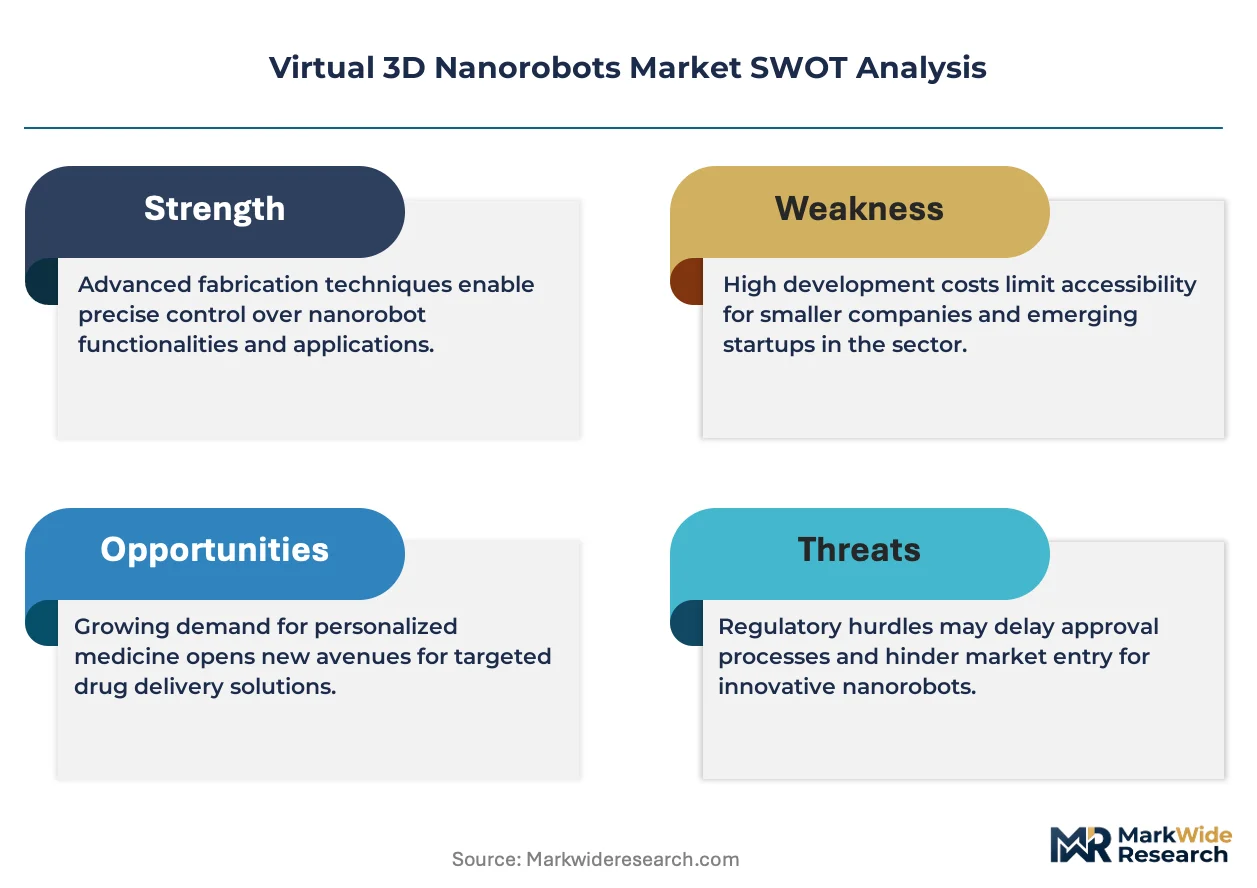
- Metrology equipment concentration:Advanced characterization systems for 3D nanorobotics fabrication concentrate among specialized instrumentation houses. Supply vulnerability elevates capital requirements for precision manufacturing scale-up.
- Preclinical validation heterogeneity:FDA efficacy thresholds for nanotechnology-enabled therapeutics diverge from EMA and PMDA standards. Regulatory friction extends clinical translation timelines for multi-jurisdiction filings.
- Optical tweezers substitution ceiling:Magnetic manipulation frameworks displace laser-based positioning in production environments. Technical limitations in optical systems persist for sub-10 nm precision requirements.
Strategic Opportunities
- Swarm intelligence architectures:Coordinated nanorobot collectives enable complex tissue penetration patterns impossible for single-agent systems. Algorithmic coordination protocols represent emergent white space for platform developers.
- India CDSCO fast-track pathways:The country's national pharmaceutical regulator accelerates nanomedicine review timelines. Localized clinical trials reduce cost barriers for novel therapeutic modalities.
- Digital twin convergence:Physics simulation engines merge with biological modeling platforms. Virtual validation environments compress preclinical development cycles before physical prototype investment.
Industry Challenges
- Multiphysics simulation expertise scarcity:Computational biologists with nanoscale fluid dynamics training command premium compensation. Talent acquisition friction constrains platform development velocity.
- ISO 10993 biological evaluation timelines:Cytotoxicity and sensitization testing for nanomaterials extends certification cycles. Compliance documentation requirements outpace standard medical device pathways.
- Legacy electron microscopy integration:Existing metrology infrastructure requires firmware adaptation for real-time nanorobot tracking. Capital reallocation debates delay facility upgrade decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual 3D Nanorobots Market |
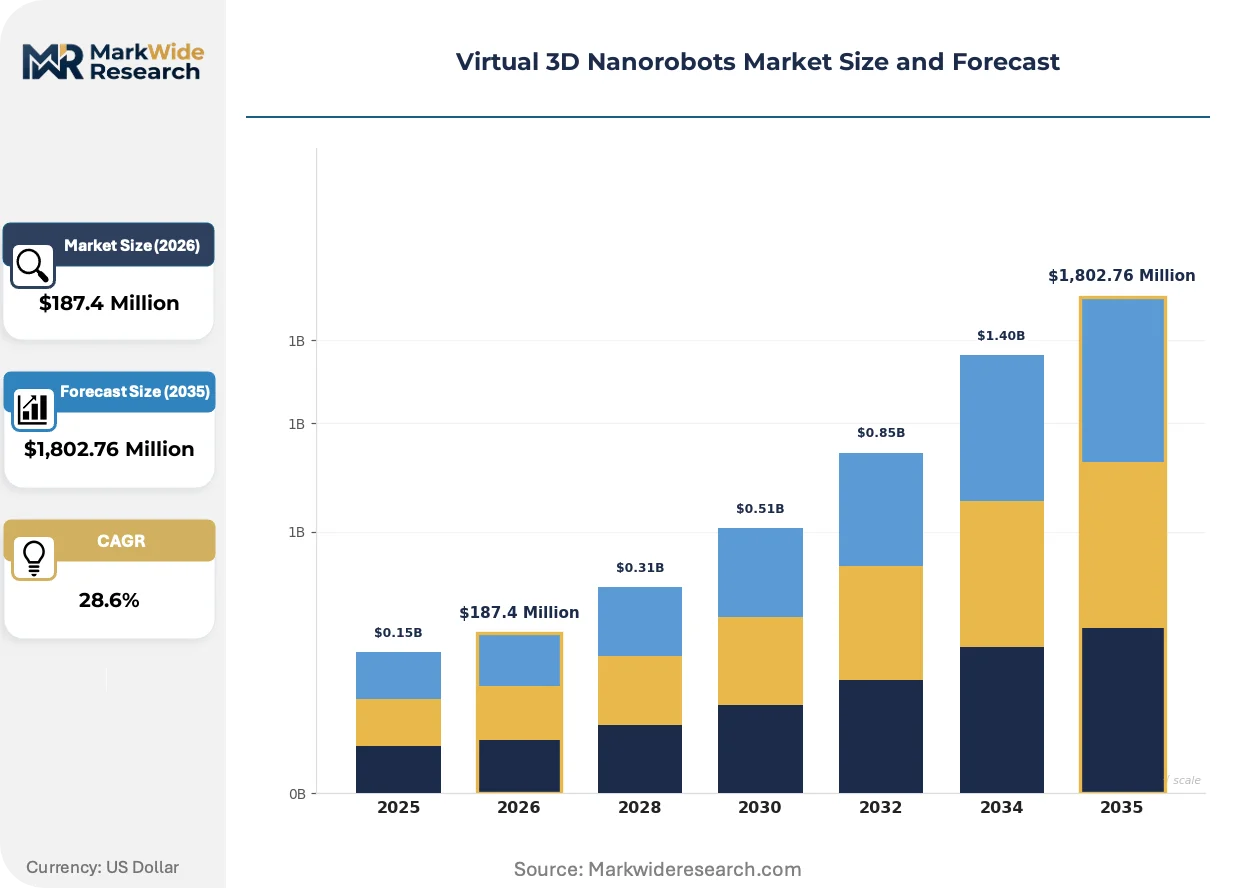
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,802.76 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nanoscale Agents, Actuators, Sensors, Swarm Systems Technology: Biomimetic Designs, Magnetic Manipulation, Optical Tweezers, Machine Learning End User: Pharmaceuticals, Healthcare, Environmental Monitoring, Materials Science Application: Targeted Drug Delivery, Diagnostics, Pollution Detection, Cancer Treatment |
| Companies Covered | Ginkgo Bioworks, Synthace, Zymergen Inc., Advanced Diamond Technologies, Advanced Nano Products Co. Limited, Thermo Fisher Scientific, Bruker Corporation, Oxford Instruments, JEOL Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual 3D Nanorobots Market Evolving Landscape
Algorithmic control architectures are displacing manual parametric tuning as the dominant development paradigm. Three concurrent shifts reshape competitive positioning across hardware, software, and service layers.
Generative design algorithms for nanoscale machine geometries are fragmenting traditional CAD-to-fabrication workflows. Biopharmaceutical engineering teams in Cambridge and Basel adopt topology optimization tools that autonomously generate biomimetic structures. These platforms compress prototype iteration cycles while elevating computational infrastructure requirements for research clusters.
FDA draft guidance on nanotechnology-based medical products is reshaping premarket notification pathways. The regulator's evolving framework elevates characterization data requirements for physicochemical properties. Sponsors in the United States respond by front-loading analytical method development before IND submission.
Research procurement is consolidating around integrated platform providers rather than discrete instrument vendors. Academic laboratories and contract research organizations now favor foundry-style service contracts encompassing design, fabrication, and validation. This preference shift concentrates contract value among automated infrastructure operators in Massachusetts and California.
Virtual 3D Nanorobots Market Segmentation
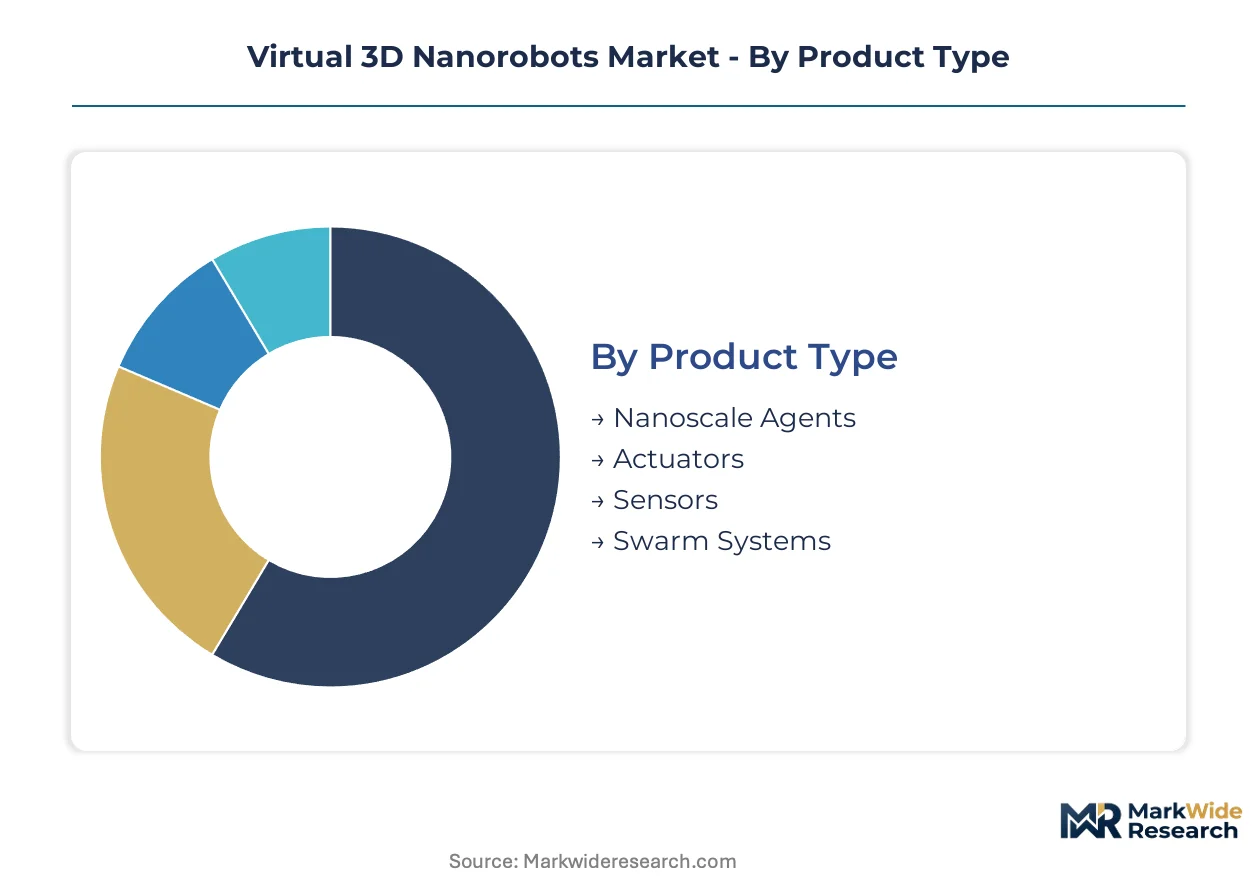
Segmentation in the Virtual 3D Nanorobots Market reveals how technology maturity and regulatory pathways create divergent investment profiles across product architectures and control systems. Understanding these fault lines enables stakeholders to allocate R&D resources toward segments with the clearest commercialization trajectories.
Product Type:
Magnetic manipulation frameworks exert substitution pressure on optical-based positioning systems, compressing addressable margins for precision hardware segments while elevating algorithmic coordination platforms.
- Nanoscale Agents:These 1-100 nm functionalized particles integrate targeting ligands with therapeutic payloads for cellular-scale intervention. Pharmaceutical manufacturers in Boston and San Francisco concentrate procurement around synthetic biology-enabled designs that FDA draft guidance favors for IND pathways. Biomimetic surface engineering reduces immunogenicity clearance rates.
- Swarm Systems:Coordinated collectives of 10-1000 nanorobots execute emergent behaviors through local interaction rules rather than centralized control. Algorithmic coordination protocols from Cambridge research clusters attract venture allocation for tissue penetration applications impossible with single-agent architectures. Machine learning integration compresses behavioral programming cycles.
- Actuators:Nanoscale mechanical transducers convert external energy fields into directed motion for positional control.
- Sensors:Molecular-scale detection elements report local biochemical conditions through optical or electrical readout mechanisms.
Nanoscale agents anchor the volume base while swarm systems gain share at the steepest rate.
Technology:
Cost tier stratification separates capital-intensive fabrication methods from software-heavy control architectures, with algorithmic platforms capturing margin expansion as hardware commoditizes.
- Machine Learning:Neural network architectures now replace manual parametric tuning for nanorobot trajectory optimization and swarm coordination. Boston-based foundry operators deploy reinforcement learning pipelines that compress development cycles from months to weeks. FDA pre-submission packages increasingly require algorithmic validation datasets alongside physical characterization.
- Biomimetic Designs:Topology optimization tools autonomously generate structures mimicking natural molecular machines—flagellar motors, viral capsids, motor proteins. Basel engineering teams integrate generative algorithms with DNA origami fabrication for targeted therapeutic scaffolds. Automated design-to-fabrication workflows reduce iteration costs for pharmaceutical sponsors.
- Magnetic Manipulation:External field gradients enable wireless actuation without onboard power systems for materials science applications.
- Optical Tweezers:Laser-based trapping achieves sub-nanometer positioning precision for research-scale characterization at elevated capital cost.
Magnetic manipulation commands the installed base while machine learning expands most quickly.
End User:
Application maturity varies sharply across customer verticals, with regulatory-validated therapeutic pathways commanding premium pricing against exploratory industrial deployments.
- Pharmaceuticals:Sponsors pursue nanorobot-enabled therapeutics through FDA's evolving nanotechnology guidance framework. IND-enabling studies for targeted drug delivery concentrate investment in characterization method development before submission. REACH compliance pathways enable dual-market access for European trial expansion.
- Healthcare:Clinical diagnostic applications leverage nanoscale sensing for early disease detection at point-of-care scales.
- Materials Science:German and Japanese manufacturers adopt production-scale magnetic control for surface modification and composite fabrication.
- Environmental Monitoring:Pollution detection deployments remain pilot-scale pending field validation standardization.
Pharmaceuticals concentrate current revenue while healthcare diagnostic applications climb the fastest.
Application:
Volume scale correlates inversely with technical complexity, with established therapeutic modalities subsidizing development of higher-precision intervention platforms.
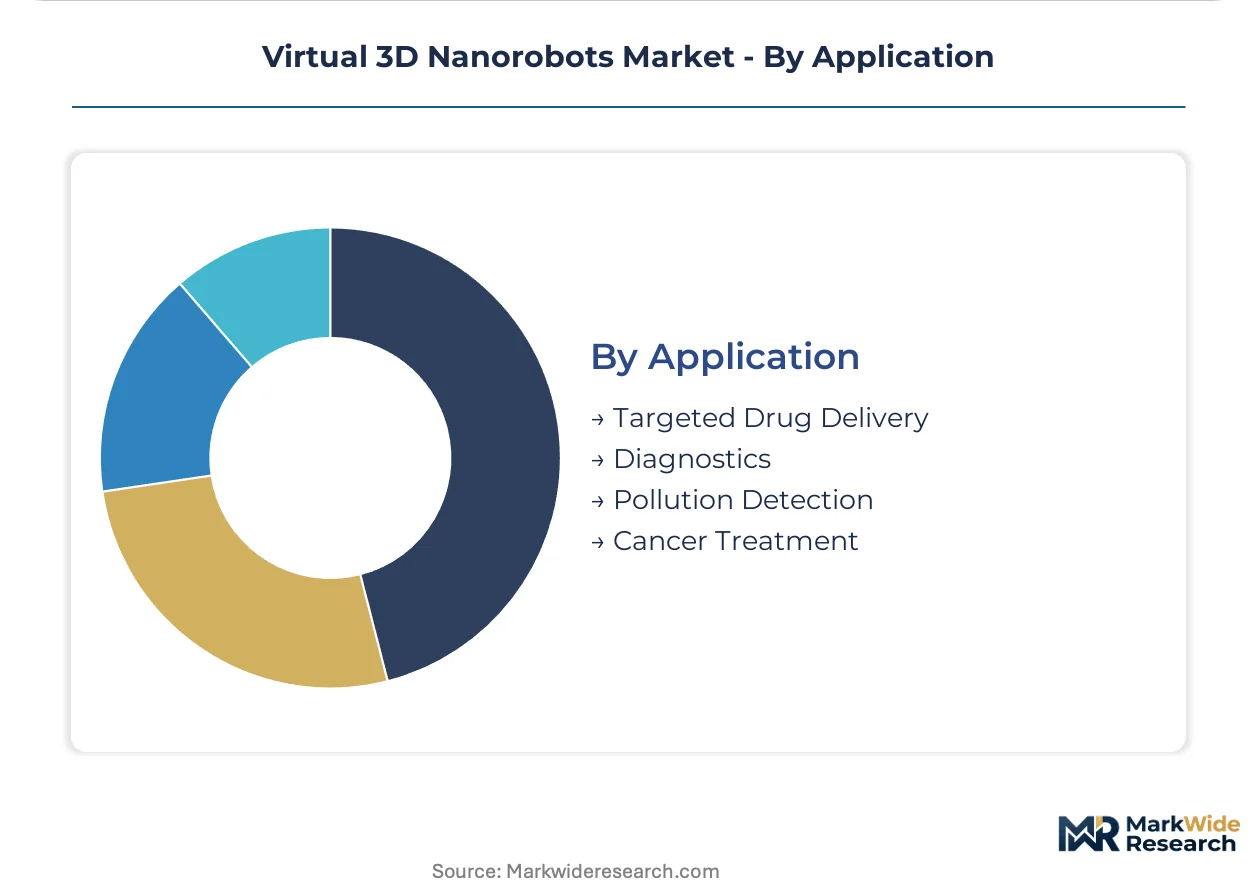
- Targeted Drug Delivery:Nanoscale agents navigate vascular networks to release payloads at disease sites, minimizing systemic toxicity. FDA efficacy thresholds for oncology applications drive front-loaded analytical investment. CDSCO fast-track pathways in India reduce cost barriers for localized clinical validation.
- Cancer Treatment:Thermal ablation and mechanical disruption protocols target tumor microenvironments with cellular specificity.
- Diagnostics:Biomarker detection at femtomolar sensitivity enables early-stage disease identification.
- Pollution Detection:Heavy metal and organic contaminant sensing remains pre-commercial pending field deployment standards.
Targeted drug delivery anchors the volume base while cancer treatment gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Switzerland where pharmaceutical sponsors absorb premium characterization costs, while Indian and Chinese manufacturers compete on scaled production economics for nanoscale agent supply.
United States
FDA draft guidance on nanotechnology-based medical products accelerates IND submissions from Boston and San Francisco research clusters. The agency's evolving characterization requirements elevate front-loaded analytical investment for physicochemical property documentation. Massachusetts-based foundry operators capture contract value through integrated design-fabrication-validation service bundles.
Germany
Materials science applications in Baden-Württemberg and Bavaria adopt production-scale magnetic manipulation frameworks for surface modification workflows. REACH compliance pathways enable dual-market access for nanomaterial manufacturers targeting EMA-validated therapeutic pathways. Stuttgart engineering clusters specialize in precision metrology systems for real-time nanorobot tracking.
Japan
PMDA harmonization efforts with FDA standards reduce regulatory friction for multi-jurisdiction filings of nanorobot-enabled therapeutics. METI funding programs support swarm intelligence architecture development in Osaka and Nagoya research institutes. Japanese manufacturers leverage optical tweezer precision for sub-10 nm characterization requirements in semiconductor-adjacent applications.
India
CDSCO fast-track pathways for nanomedicine reduce clinical trial cost barriers for targeted drug delivery modalities. Maharashtra and Telangana pharmaceutical clusters localize manufacturing for export-oriented nanoscale agent production. Indian contract research organizations attract Western sponsor investment through accelerated biosimilar-equivalent validation timelines.
Switzerland
Swissmedic's alignment with EMA nanotechnology frameworks positions Basel as a regulatory bridge for EU market access. Topology optimization tools from ETH Zurich spinouts automate biomimetic structure generation for pharmaceutical engineering teams. Swiss precision instrumentation houses supply metrology systems sustaining fabrication tolerances across European research clusters.
Virtual 3D Nanorobots Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics across the sector. Synthetic biology platforms with automated foundry infrastructure command premium positioning in prototype-to-scale workflows, while specialized instrumentation houses anchor precision manufacturing supply. Three strategic archetypes dominate: integrated platform operators, precision metrology specialists, and contract research service providers. Competitive moves concentrate on strategic partnerships bridging design-to-fabrication capabilities and geographic expansion into fast-track regulatory jurisdictions.
Among synthetic biology platform operators, Ginkgo Bioworks and Zymergen Inc. exemplify the automated foundry archetype, occupying positions where algorithmic control compresses development cycles. Bruker Corporation anchors the precision metrology specialist tier, representing instrumentation houses whose characterization systems sustain fabrication tolerances for 3D nanorobotics production. Thermo Fisher Scientific sits within the diversified life sciences conglomerate archetype, leveraging cross-divisional capabilities spanning reagent supply through analytical instrumentation.
| Leading Market Players |
|---|
| Ginkgo Bioworks |
| Synthace |
| Zymergen Inc. |
| Advanced Diamond Technologies |
| Advanced Nano Products Co. Limited |
| Thermo Fisher Scientific |
| Bruker Corporation |
| Oxford Instruments |
| JEOL Ltd |
| Others |
Value Network & Pricing Analysis
Ninety-to-one-hundred-twenty-day lead times for precision metrology systems concentrate procurement power among Massachusetts and California foundry operators, compressing margin capture for nanoscale agent manufacturers while elevating pricing premiums for algorithmic coordination platforms with validated FDA pathways.
Pricing Analysis
Configured-to-order pricing for biomimetic nanorobot designs commands forty-to-sixty-percent premiums over standard magnetic manipulation frameworks. Project-based contracting dominates pharmaceutical sponsor relationships, with FDA tier certification and swarm intelligence capability serving as primary price differentiation drivers. Cost compression in optical tweezer-based characterization tiers is intensifying because magnetic frameworks achieve production-scale displacement. Academic laboratories exhibit highest price sensitivity; integrated platform providers with automated foundry infrastructure demonstrate lowest sensitivity due to captive validation workflows.
Supply Chain Analysis
Strategic stockpiling of rare-earth magnetic materials and specialized photoresists characterizes procurement behavior among German and Japanese precision manufacturers, contrasting with just-in-time inventory preferences at Boston-based synthetic biology platforms. Supply concentration rests on China for neodymium-based magnetic components, Switzerland for precision metrology systems, and India for contract manufacturing of nanoscale agent precursors. Raw material dependencies include DNA origami scaffolds, superparamagnetic iron oxide nanoparticles, and electron-beam lithography resists. Single-source vulnerability in advanced electron microscopy supply elevates risk exposure. Distribution runs through direct foundry-service contracts with pharmaceutical sponsors rather than instrument vendor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across control architectures and regulatory validation pathways creates multiple entry niches for specialized platform developers, as pharmaceutical sponsors disaggregate procurement between design-automation software, fabrication infrastructure, and characterization services.
For Market Incumbents: Secure algorithmic coordination IP through targeted acquisition of Cambridge and Basel-based machine learning startups, as manual parametric tuning faces displacement. Deepen backward integration into superparamagnetic nanoparticle supply to offset rare-earth price volatility. Fortify FDA pre-submission service offerings against emerging CDSCO-fast-track competitors in India. For New Entrants and Emerging Players: Lead with swarm intelligence architecture development for tissue penetration applications, the most penetrable white space absent dominant platform control. Target Maharashtra-based contract research organizations as beachhead customers for algorithmic validation tools. Deploy physics-simulation-engine partnerships as differentiated go-to-market positioning against integrated foundry incumbents. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life sciences conglomerates with underutilized nanorobot characterization divisions. Five-to-ten-year viability hinges on regulatory pathway breadth rather than single-jurisdiction approval. Signal to monitor: CDSCO and PMDA harmonization velocity with FDA nanotechnology guidance frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Foundry Infrastructure Expansion | Massachusetts-based platforms compress client development cycles from months to weeks through integrated design-fabrication-validation workflows. |
| Algorithmic Coordination IP Acquisition | Machine learning startups in Cambridge and Basel enable swarm intelligence capabilities impossible with manual programming approaches. |
| CDSCO Fast-Track Regulatory Investment | Indian clinical trial localization reduces cost barriers for novel therapeutic modalities seeking accelerated validation timelines. |
| Backward Integration into Magnetic Materials | Captive supply of superparamagnetic iron oxide nanoparticles insulates margin structures from rare-earth commodity volatility. |
| Digital Twin Platform Convergence | Physics simulation engines merging with biological modeling compress preclinical development cycles before physical prototype investment. |
Research Methodology
Cross-validation between primary interviews with nanorobot platform engineers, FDA regulatory affairs specialists, pharmaceutical development executives, and precision metrology procurement managers anchors the qualitative findings. Secondary validation draws from FDA nanotechnology guidance documents, ISO nanotechnology technical committee publications, CDSCO fast-track pathway notifications, and EMA nanomedicine reflection papers. Bottom-up segmentation modeling triangulates against top-down market sizing from automated foundry capacity announcements and research procurement database tracking.
Sensitivity analysis across technology adoption curves, regulatory harmonization scenarios, and magnetic materials cost trajectories informs the analytical framework. Segmentation dimensions include product architecture, control system technology, end-user vertical, application complexity, and regional regulatory cluster. CAGRs derive from installed base growth rates, replacement cycle compression, and penetration assumptions across the projection horizon. Industry-specific inputs encompass IND submission velocity from Boston and San Francisco clusters, REACH compliance pathway adoption rates, and swarm intelligence venture allocation trends.
The analysis sits within stated boundaries; outcomes outside sustained FDA draft guidance finalization, stable rare-earth supply chains, or continued machine learning algorithm advancement would require recalibration. Forecasts reflect documented assumptions regarding clinical translation timelines and characterization method standardization. Regulatory friction between FDA, EMA, and PMDA efficacy thresholds represents primary revision risk. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Underwater Exploration Robots Market
Robotics and Automation
France Cloud Robotics Market
Robotics and Automation
Surgical Robots Market
Robotics and Automation
Gimbal Stabilizers Market
Robotics and Automation
SLAM Robots Market
Robotics and Automation
Waste Sorting Robots Market
Robotics and Automation
Household Cleaning Robotics Market
Robotics and Automation
Food Robotics Market
Robotics and Automation
Global Wafer Handling Robots Market
Robotics and Automation
Robotic Process Automation in Legal Services Market
Robotics and Automation
Commercial Robotics Market
Robotics and Automation
Quadruped Robot Market
Robotics and Automation
Global Machine Vision and Vision Guided Robotics Market
Robotics and Automation
Singapore Cloud Robotics Market
Robotics and Automation
Sweden Robotic Lawn Mower Market
Robotics and Automation
Cleanroom Robots in Healthcare Market