
 South America Agricultural Robots and Mechatronics Market | 2026-2036
South America Agricultural Robots and Mechatronics Market Size, Share, and Industry Trends Forecast 2026-2036
South America Agricultural Robots and Mechatronics Market Analytics
The buyer base for agricultural robots and mechatronics across South America is broadening beyond traditional large estate owners to encompass mid-sized cooperatives and precision-service providers. Deere & Company leverages its established dealer network to sustain equipment financing advantages across Brazil and Argentina. AGCO Corporation anchors its regional position through localized manufacturing and aftermarket parts availability. CNH Industrial competes aggressively in the autonomous tractor segment with integrated telemetry platforms.
Agricultural robots and mechatronics encompass electromechanical systems, sensor arrays, and autonomous control platforms engineered for field operations with positioning accuracy typically within 2.5 centimeters and operational endurance exceeding 16 hours per cycle. These systems execute soil preparation, seed planting, crop monitoring, and irrigation management with minimal human intervention across extensive farmland parcels. Autonomous tractors and drones currently command the largest installed bases, though AI-enabled harvesters represent the fastest-expanding product category as computer-vision sorting improves grain-quality outcomes. The technology dimension splits between IoT connectivity layers that dominate current retrofit sales and robotics hardware that captures disproportionate margin pools in new-equipment contracts.
Brazil's national agricultural regulator, ANVISA for agrochemical interface standards, and INCRA for land-use compliance collectively shape equipment certification timelines and autonomous-operation permits across South American territories. Argentina's INTA research institute and Chile's agricultural service protocols further influence precision-farming equipment specifications through regional harmonization pressures. Stakeholders must monitor evolving liability frameworks for unmanned machinery and align R&D roadmaps with emerging interoperability mandates before competitive positioning hardens.
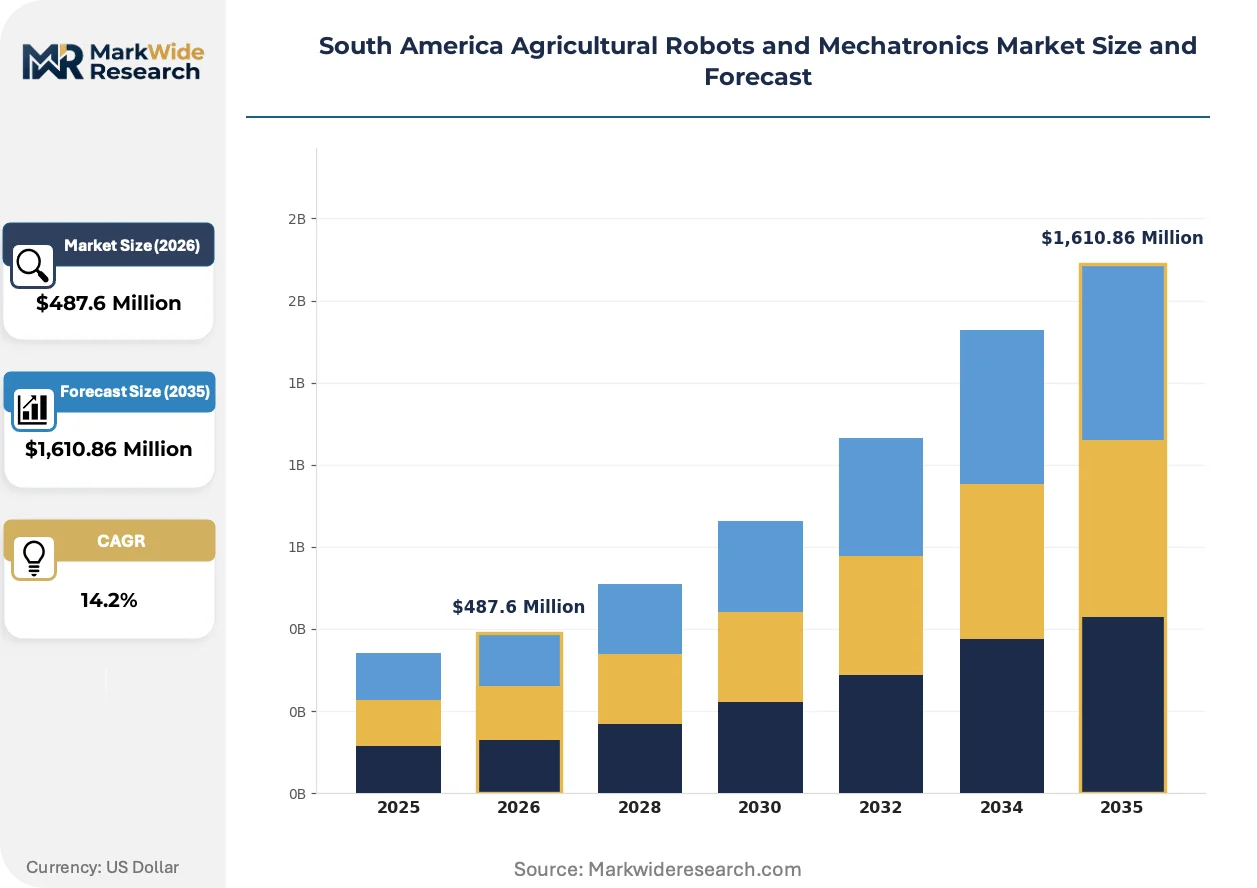
Market Dynamics
Autonomous control platforms with sub-2.5-centimeter positioning accuracy are compressing operational labor requirements across Brazil's mechanized soybean belt, forcing equipment financing structures and dealer service models to recalibrate around uptime guarantees rather than unit sales.
Growth Catalysts
- INCRA Land-Use Compliance Mandates:Brazil's land reform agency now requires GPS-verified planting records for large estates, accelerating demand for telemetry-integrated tractors that automate documentation workflows.
- Mid-Sized Cooperative Consolidation:Argentine and Uruguayan farming cooperatives are pooling capital to acquire shared drone fleets, expanding addressable equipment bases beyond traditional estate owners.
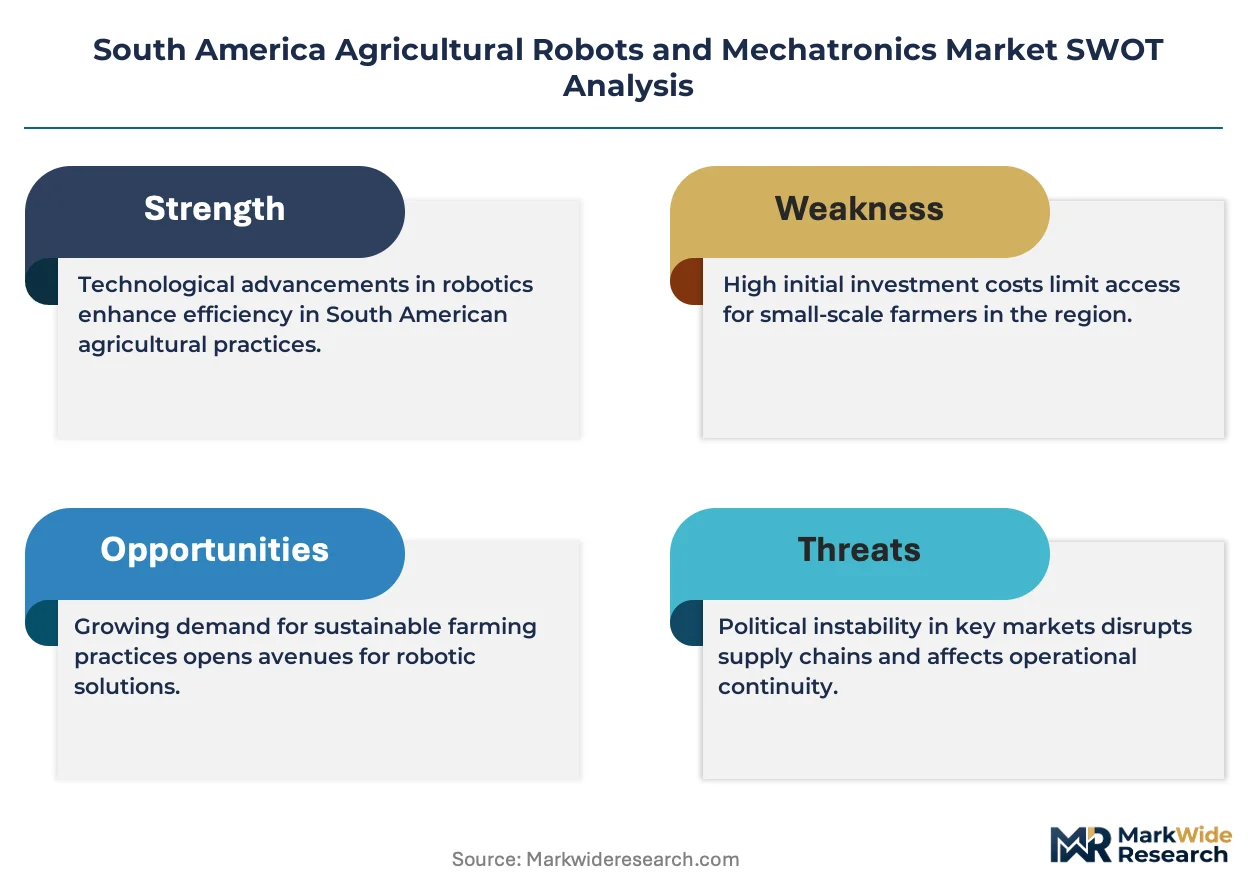
- AI-Enabled Computer Vision:Real-time grain-quality sorting during harvest operations is reducing post-harvest processing costs and justifying premium equipment pricing for high-value crop segments.
Market Restraints
- ANVISA Certification Timelines:Brazil's agrochemical interface standards now require 14-18 month equipment validation cycles, delaying commercialization of sensor-integrated spraying systems.
- Lithium-Ion Battery Supply Concentration:Regional dependence on imported battery cells from Asian suppliers exposes fleet operators to currency volatility and extended lead times for autonomous vehicle powertrains.
- Legacy Mechanical Fleet Inertia:Existing depreciated tractor populations in Paraguay and Bolivia lack CAN bus architecture, blocking retrofit pathways for autonomy kits without full platform replacement.
Strategic Opportunities
- Chilean Precision Viticulture:Wine producers in Colchagua and Maipo valleys are adopting robotic pruning systems, creating a testbed for specialty crop automation outside commodity grain markets.
- INTA Research Partnerships:Argentina's agricultural technology institute is co-funding autonomous equipment trials, offering subsidized validation pathways for foreign manufacturers seeking regional entry.
- 5G Private Network Deployment:Brazilian telecom infrastructure investments in Mato Grosso are enabling real-time machine-to-machine coordination for swarming drone operations at sub-50-millisecond latency.
Industry Challenges
- Autonomous Systems Engineering Talent Scarcity:Regional universities produce insufficient mechatronics specialists familiar with RTK-GNSS integration and sensor fusion algorithms, forcing manufacturers to import technical personnel.
- Interoperability Standard Fragmentation:Proprietary telemetry protocols from major equipment suppliers prevent mixed-fleet data aggregation, complicating cooperative procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Agricultural Robots and Mechatronics Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,610.86 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autonomous Tractors, Drones, Harvesters, Planters Technology: AI, IoT, Robotics, Automation End User: Farmers, Agricultural Cooperatives, Research Institutions, Agribusinesses Application: Crop Monitoring, Soil Preparation, Seed Planting, Irrigation Management |
| Companies Covered | Deere & Company, AGCO Corporation, CNH Industrial, GEA Group, Trimble Inc, CLAAS KGaA mbH, Autonomous Solutions Inc, Autonomous Tractor Corporation, Harvest Automation, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Agricultural Robots and Mechatronics Market Evolving Landscape
Edge computing architectures are relocating data processing from cloud servers to field-deployed machinery, enabling real-time decision loops that bypass connectivity limitations across remote agricultural zones.
RTK-GNSS correction networks are decentralizing precision agriculture by enabling centimeter-accurate positioning without subscription-based satellite services. Mid-sized operators in Rio Grande do Sul are deploying local base stations that broadcast correction signals across cooperative member farms. This infrastructure shift is compressing the cost barrier that previously restricted high-accuracy automation to capital-intensive estates.
ANVISA and INCRA are tightening joint certification requirements for autonomous spraying equipment, mandating real-time chemical flow monitoring and automatic shutoff at buffer zones. Equipment manufacturers must now submit integrated system designs rather than component-level approvals. Brazil's Mato Grosso state is experiencing the steepest compliance cost increases as regulators prioritize soybean belt chemical runoff reduction.
Cooperative procurement consortia are displacing individual estate purchasing across Argentina's Pampas region. Pooled equipment access agreements now cover 40% of new autonomous tractor acquisitions in Buenos Aires province, with shared utilization models replacing sole ownership. This structural shift is forcing Deere and AGCO dealers to develop multi-party financing instruments and fractional service contracts.
South America Agricultural Robots and Mechatronics Market Segmentation
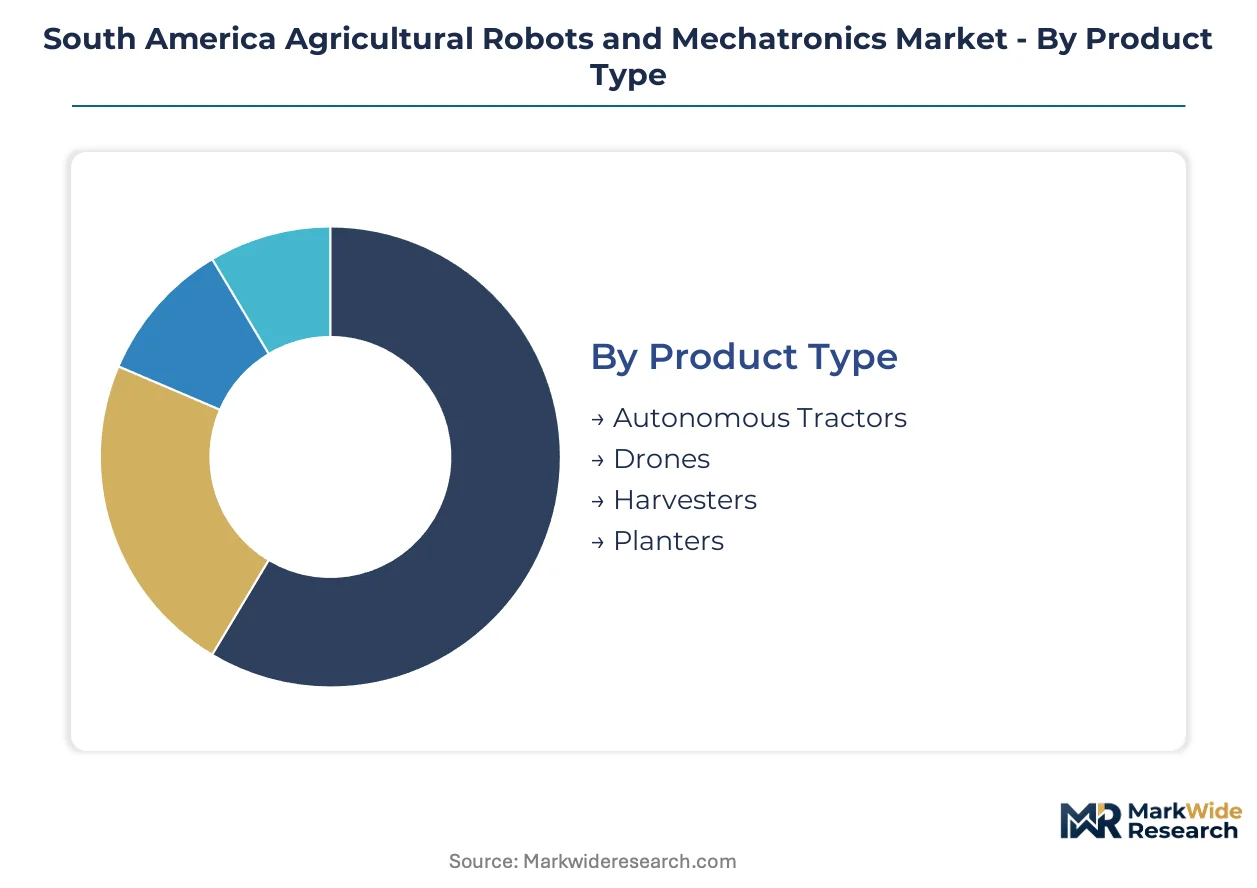
Segmentation in South American agricultural robotics reveals how technology deployment varies across farm scales, crop types, and regulatory environments. Understanding these divisions exposes where capital concentrates and where interoperability gaps persist.
Product Type:
Positioning accuracy and operational endurance specifications differentiate equipment categories across Brazil's mechanized farming zones.
- Autonomous Tractors:RTK-GNSS guidance systems achieve sub-2.5-centimeter accuracy during extended field operations. Mato Grosso soybean producers dominate procurement, driven by INCRA mandates for GPS-verified planting documentation.
- Drones:Multi-spectral sensor arrays and swarming coordination capabilities enable real-time crop health mapping. Rio Grande do Sul cooperatives are consolidating shared fleet ownership to distribute capital burden across mid-sized operations.
- Harvesters:AI-enabled computer vision performs grain-quality sorting during collection cycles. Premium pricing justification depends on post-harvest processing cost reductions in high-value crop segments.
- Planters:Precision seed placement systems integrate variable-rate fertilization controls. Adoption concentrates where soil heterogeneity demands site-specific input management.
Autonomous tractors lead on scale; harvesters lead on momentum.
Technology:
Cost tier stratification separates retrofit connectivity solutions from integrated robotics hardware in new-equipment contracts.
- AI:Machine learning algorithms process computer-vision data for real-time crop classification and quality assessment. Chilean viticulture operations in Colchagua Valley are deploying robotic pruning systems as specialty crop testbeds.
- IoT:Sensor networks and telemetry platforms enable fleet coordination and predictive maintenance scheduling. Brazilian 5G private network deployment in Mato Grosso is compressing machine-to-machine latency below 50 milliseconds.
- Robotics:Electromechanical actuation systems execute physical field operations with minimal human intervention. Hardware margins exceed connectivity layers in manufacturer pricing structures.
- Automation:Control systems and workflow orchestration software integrate disparate equipment into coordinated operational sequences. Legacy mechanical fleet inertia in Paraguay and Bolivia blocks retrofit pathways without full platform replacement.
IoT dominates retrofit penetration; AI climbs the fastest in new-equipment specifications.
End User:
Customer type determines financing structures, service contract terms, and equipment utilization intensity across South American territories.
- Farmers:Individual estate owners with capital-intensive operations drive premium equipment specifications. Brazil's large-scale soybean and corn producers anchor autonomous tractor demand.
- Agricultural Cooperatives:Pooled procurement consortia now cover 40% of new autonomous tractor acquisitions in Buenos Aires province. Shared utilization models displace sole ownership across Argentina's Pampas region.
- Research Institutions:Argentina's INTA co-funds autonomous equipment trials, offering subsidized validation pathways for regional market entry.
- Agribusinesses:Integrated supply chain operators deploy robotics across controlled farming territories. Telemetry integration supports enterprise-scale resource planning and compliance documentation.
Individual farmers lead on absolute equipment volume; cooperatives gain share fastest through pooled capital structures.
Application:
Operational phase determines sensor payload requirements, positioning precision demands, and regulatory exposure for chemical interface systems.
- Crop Monitoring:Aerial and ground-based sensing platforms detect stress indicators, pest infestations, and nutrient deficiencies. Drone-based systems command the largest installed base among monitoring technologies.
- Soil Preparation:Autonomous tillage and cultivation equipment operates with continuous positioning correction. ANVISA certification timelines for sensor-integrated spraying systems now extend 14-18 months.
- Seed Planting:Precision placement systems integrate real-time soil sensing for variable-rate input application. GPS-verified planting records satisfy INCRA land-use compliance mandates for large estates.
- Irrigation Management:Automated valve control and moisture-sensor networks optimize water application timing and volume. Edge computing architectures enable real-time decision loops bypassing connectivity limitations in remote zones.
Crop monitoring leads on deployment breadth; seed planting leads on regulatory-driven replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands the largest installed base of autonomous tractors while Argentina's cooperative procurement models are gaining regional attention as capital-efficient alternatives to sole ownership.
Brazil
Mato Grosso soybean producers drive autonomous tractor demand through INCRA mandates for GPS-verified planting documentation. ANVISA and INCRA jointly tightened certification requirements for autonomous spraying equipment, mandating real-time chemical flow monitoring. Rio Grande do Sul cooperatives deploy local RTK-GNSS base stations broadcasting correction signals across member farms.
Argentina
Buenos Aires province farming cooperatives now cover 40% of new autonomous tractor acquisitions through pooled capital structures. INTA co-funds autonomous equipment trials offering subsidized validation pathways for regional market entry. The Pampas region experiences structural shift toward shared utilization models displacing traditional sole ownership.
Chile
Colchagua and Maipo valley wine producers adopt robotic pruning systems creating specialty crop automation testbeds outside commodity grain markets. The country's agricultural service protocols influence precision-farming equipment specifications through regional harmonization pressures. Edge computing architectures enable real-time decision loops bypassing connectivity limitations in remote viticulture zones.
Uruguay
Mid-sized farming cooperatives pool capital to acquire shared drone fleets expanding addressable equipment bases beyond traditional estate owners. The national agricultural framework aligns with Argentine INTA research partnerships for equipment validation. Montevideo-based precision-service providers coordinate multi-farm telemetry integration.
Paraguay
Legacy mechanical fleet inertia blocks retrofit pathways for autonomy kits without full platform replacement due to missing CAN bus architecture. Depreciated tractor populations constrain precision-agriculture penetration compared to neighboring mechanized farming territories. Asunción-based equipment importers focus on full-platform replacement strategies for autonomous system adoption.
South America Agricultural Robots and Mechatronics Market Competitive Landscape
North American producers anchor one tier; European specialists hold differentiated positions in precision-guidance and harvesting automation. The vendor base stratifies across integrated equipment manufacturers, precision-technology providers, and autonomous-system specialists. Three archetypes dominate: full-line manufacturers with financing networks, precision-technology licensors, and pure-play autonomy developers. Consolidation pressures intensify through strategic partnerships between machinery producers and sensor-technology suppliers.
Within the full-line manufacturer tier, Deere & Company, AGCO Corporation, and CNH Industrial exemplify capital-intensive competitive positioning. Deere & Company leverages established dealer networks for equipment financing advantages. AGCO Corporation anchors regional presence through localized manufacturing footprints. CNH Industrial occupies a position in integrated telemetry platforms for autonomous fleet coordination.
| Leading Market Players |
|---|
| Deere & Company |
| AGCO Corporation |
| CNH Industrial |
| GEA Group |
| Trimble Inc |
| CLAAS KGaA mbH |
| Autonomous Solutions Inc |
| Autonomous Tractor Corporation |
| Harvest Automation |
| Others |
Value Network & Pricing Analysis
RTK-GNSS correction network deployment divides South American agricultural robotics into precision-tier and standard-tier equipment categories, with the former commanding hardware margins that reflect localized base station infrastructure investment and the latter tethered to imported component costs and currency exposure. This bifurcation shapes manufacturer pricing power across Brazil's Mato Grosso soybean belt versus Paraguay's legacy mechanical fleet replacement markets.
Pricing Analysis
Capacity additions in Brazil's Rio Grande do Sul cooperative networks are reshaping price floors for shared autonomous tractor utilization models. Three-tier pricing structure across premium telemetry-integrated, standard guidance-equipped, and economy retrofit-kit levels stratifies buyer access. Price differentiation hinges on INCRA certification grade and after-sales service bundling. Pricing pressure stems from Argentine cooperative procurement consortia consolidating demand. Mid-sized Uruguayan cooperatives exhibit highest price sensitivity; Brazilian agribusinesses least.
Supply Chain Analysis
ANVISA and INCRA joint certification requirements for autonomous spraying equipment gate supplier qualification timelines and concentrate procurement among pre-approved component vendors. Hardware assembly draws from China, South Korea, and domestic Brazilian facilities. Lithium-ion battery cells, RTK-GNSS modules, and multi-spectral sensors anchor raw material dependencies. Single-source vulnerability runs through Asian battery cell suppliers. Distribution runs through Deere and AGCO dealer networks with localized parts warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South American agricultural robotics functions as a stable compounder anchored by INCRA land-use compliance mandates that institutionalize precision-agriculture equipment replacement cycles across Brazil's mechanized farming territories.
For Market Incumbents: Deploy telemetry platform integration as the primary defensive lever. Consolidate dealer service networks around uptime guarantee contracts to counter emerging pure-play autonomy developers. Deepen backward integration into RTK-GNSS correction infrastructure to capture margin pools from cooperative base station deployment in Rio Grande do Sul. For New Entrants and Emerging Players: Mid-sized Paraguayan and Bolivian farming operations lacking CAN bus architecture represent the most penetrable buyer archetype. White-space concentrates in full-platform autonomous tractor replacement versus retrofit kit competition. INTA research partnerships in Argentina offer subsidized validation pathways for regional market entry. Lead with fractional ownership financing to bypass capital constraints. For Investors and Strategic Acquirers: Asymmetric upside sits with precision-guidance technology licensors possessing ANVISA pre-certification status. Long-term viability centers on equipment manufacturers with established telemetry data aggregation platforms. Watch for 5G private network deployment velocity in Mato Grosso as inflection indicator for real-time swarming coordination adoption.| Strategic Initiative | Industry Significance |
|---|---|
| RTK-GNSS Infrastructure Partnership | Local base station networks in Rio Grande do Sul compress precision-agriculture cost barriers for cooperative members. |
| ANVISA Pre-Certification Investment | Early validation pathways shorten 14-18 month equipment approval timelines for sensor-integrated spraying systems. |
| Cooperative Financing Instrument Development | Multi-party service contracts align dealer revenue models with Argentina's pooled procurement consortia expansion. |
| Edge Computing Architecture Deployment | Field-level data processing bypasses connectivity gaps across remote Chilean viticulture zones. |
| INTA Research Collaboration | Subsidized trial programs reduce market entry costs for foreign manufacturers targeting Argentine Pampas operations. |
Research Methodology
Direct dialogue with precision-agriculture equipment dealers, cooperative procurement managers, ANVISA regulatory affairs specialists, and agribusiness technology officers grounded qualitative assessment. Secondary validation incorporated Brazilian customs records for agricultural machinery imports, INCRA land-use compliance documentation requirements, INTA research publication databases, and SEC filings from listed equipment manufacturers. Bottom-up equipment shipment tracking and top-down agricultural GDP allocation models were triangulated.
Bottom-up modeling segmented volume and value projections across autonomous tractors, drones, harvesters, and planters by technology tier, farm scale, and regional regulatory cluster. AI-enabled computer vision adoption curves and IoT retrofit penetration rates informed growth trajectory assumptions across the analysis window. CAGRs were derived from equipment replacement cycle analysis and cooperative capital formation trends.
Underlying measurement precision varies by segment; autonomous tractor shipment data carry tighter precision than emerging AI-harvester category estimates. Forecasts reflect assumptions regarding ANVISA certification timeline stability and lithium-ion battery supply continuity. A model refresh is warranted upon material change in INCRA documentation mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Hospitality Robots Market
Robotics and Automation
Robotic Air Purifier Market
Robotics and Automation
Asia-Pacific Robotic Process Automation Market
Robotics and Automation
Modular Robotics Market
Robotics and Automation
Smart Lawn Robot Market
Robotics and Automation
Robot End-Effector Market
Robotics and Automation
Global Educational Robots Market
Robotics and Automation
Wearable Robotic Exoskeleton Market
Robotics and Automation
Laboratory Robotics Market
Robotics and Automation
Cordless Router Market
Robotics and Automation
Commercial Robots Market
Robotics and Automation
Robotics Actuators Market
Robotics and Automation
North America Data Center Robotics Market
Robotics and Automation
Agricultural Robots Market
Robotics and Automation
Consumer and Office Robot Market
Robotics and Automation
Painting Robot Market