
 Clean Room Robot Market | 2026-2036
Clean Room Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Clean Room Robot Market Analysis
Japanese precision equipment manufacturing is realigning around contamination-controlled automation for next-generation chip fabrication. FANUC Corporation leverages its CNC heritage to dominate high-repeatability clean room arm production. Yaskawa Electric Corporation anchors Asia-Pacific supply through specialized servo architectures for ISO Class 1 environments. KUKA AG competes in European pharmaceutical installations with modular cell designs that reduce particle generation during aseptic processing.
Clean room robots are electromechanical manipulators engineered to ISO 14644-1 particulate standards, typically employing sealed harmonic drives and stainless steel enclosures to prevent contamination in controlled environments. These systems execute material transfer, assembly, and inspection tasks where human presence introduces unacceptable particulate or microbial risk. Collaborative robots represent the fastest-expanding product category as biopharma facilities retrofit existing suites without full isolation infrastructure. Sensor technology integration creates margin concentration among suppliers offering real-time environmental feedback loops embedded directly in robotic end-effectors. Mobile robots for clean room material handling remain a mature, price-competitive segment where differentiation depends on navigation algorithm reliability rather than hardware novelty.
The FDA enforces current Good Manufacturing Practice requirements that effectively mandate robotic intervention in Grade A aseptic zones, while ISO 14644 revisions tighten particulate classification thresholds for robotic operating environments. EMA's Annex 1 updates on sterile manufacturing push European pharmaceutical operators toward validated automated systems with isolator-integrated robotics. Stakeholders must monitor how evolving clean room classification standards in major jurisdictions reshape certification requirements for multi-site robot deployments.
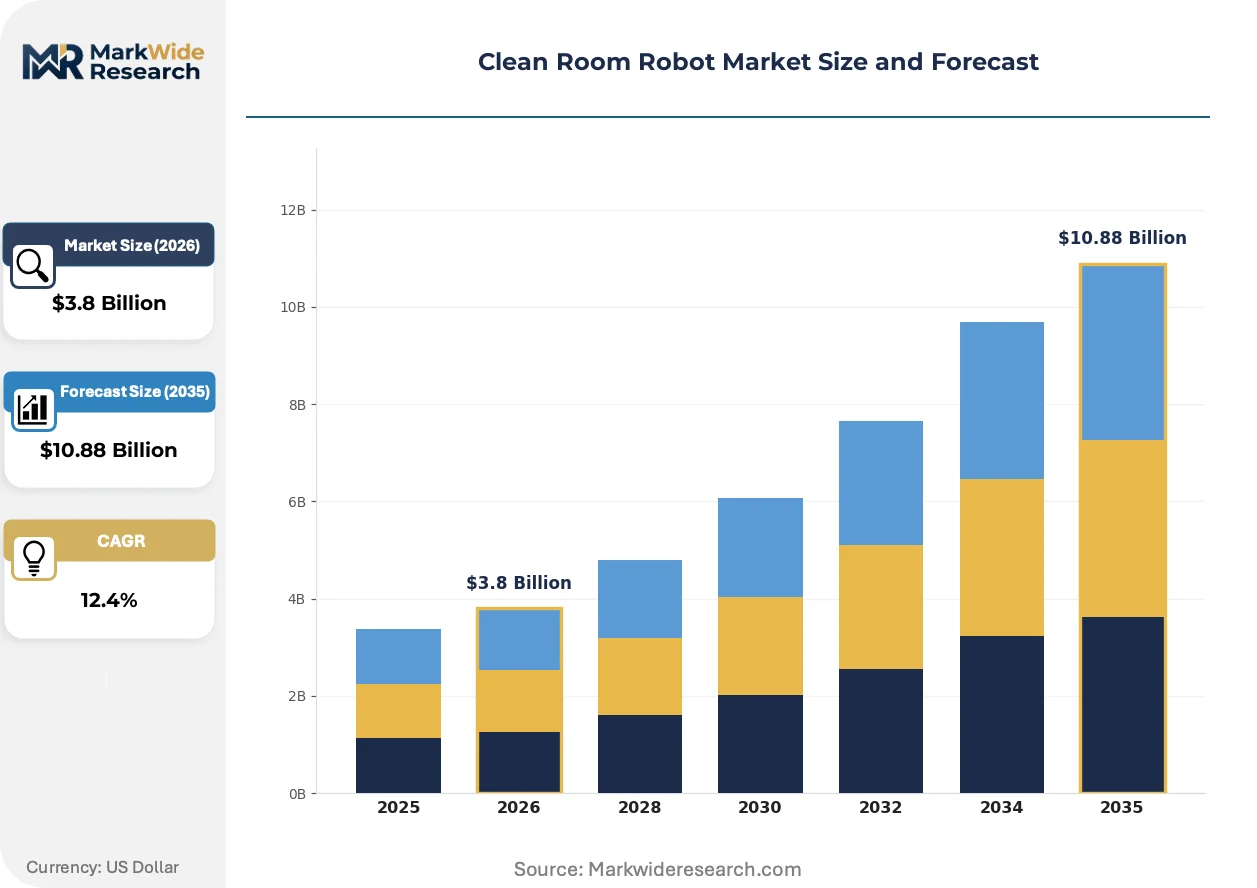
Market Dynamics
Semiconductor fabs in Taiwan and South Korea are accelerating automated clean room deployments as sub-3nm lithography nodes demand ISO Class 1 environments where human operators introduce unacceptable contamination risk.
Growth Catalysts
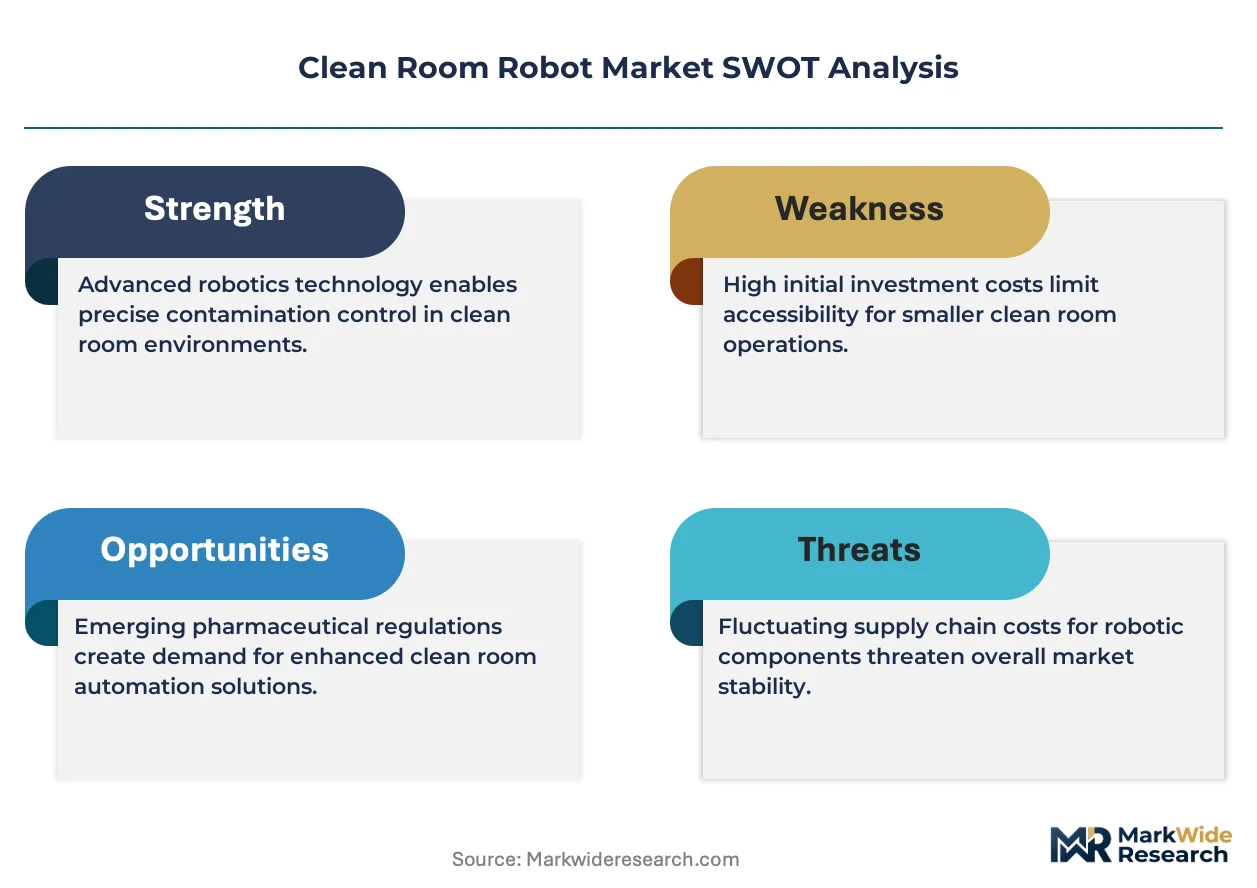
- FDA aseptic guidance:Updated Grade A zone requirements mandate robotic intervention in sterile pharmaceutical manufacturing, eliminating manual filling operations from critical environments.
- Harmonic drive sealing:Advanced drive architectures prevent particulate generation at motion interfaces, enabling continuous operation in Class 1 semiconductor lithography bays.
- Taiwan fab expansion:Concentrated capital investment in Hsinchu and Tainan science parks creates concentrated demand for validated clean room automation systems.
Market Restraints
- Stainless steel supply concentration:Premium 316L enclosure material sourcing concentrates in German and Japanese specialty mills, exposing lead times to geopolitical friction.
- Validation timeline compression:FDA process validation protocols for robotic aseptic systems extend deployment cycles by 18-24 months versus conventional automation.
- Isolator integration complexity:Physical coupling between robotic arms and rigid barrier systems creates vibration transmission challenges that degrade particulate performance.
Strategic Opportunities
- Indian biopharma retrofit:CDSCO alignment with international GMP standards drives demand for collaborative clean room robots in existing suite infrastructure without full isolation rebuilds.
- Sensor-embedded end-effectors:Real-time particulate monitoring at the point of manipulation creates service revenue streams beyond hardware sale margins.
- EU MDR sterile device manufacturing:Medical device reclassification under the Medical Device Regulation expands validated robotic assembly requirements for implantable products.
Industry Challenges
- Clean room robotics technician scarcity:Cross-disciplinary expertise combining ISO 14644 protocols with servo maintenance commands wage premiums exceeding 40% in Hsinchu and Seoul clusters.
- Legacy SCADA integration:Pharmaceutical facilities operating 1990s-era building management systems face protocol translation failures when connecting modern robotic environmental feedback loops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clean Room Robot Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.88 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autonomous Robots, Collaborative Robots, Mobile Robots, Industrial Robots Technology: Artificial Intelligence, Robotics, Computer Vision, Sensor Technology End User: Pharmaceuticals, Biotechnology, Electronics, Healthcare Application: Material Handling, Disinfection, Clean Room Monitoring, Assembly |
| Companies Covered | ABB Ltd, FANUC Corporation, Yaskawa Electric Corporation, KUKA AG, Denso Corporation, Mitsubishi Electric Corporation, Kawasaki Heavy Industries, Omron Corporation, Universal Robots, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clean Room Robot Market Emerging Trajectories
Edge computing architectures embedded directly in robotic controllers are compressing response latencies for environmental monitoring, while regulatory convergence between FDA and EMA sterile manufacturing standards is harmonizing validation protocols across Atlantic supply chains.
Collaborative robot platforms with sealed joint architectures are decentralizing clean room automation deployment decisions from centralized capital planning to individual suite managers. Biopharma facilities in Basel and Boston are piloting these systems for secondary packaging operations without full isolator infrastructure. This shift is decentralizing procurement authority from corporate engineering to site-level quality directors who can justify smaller capital outlays against immediate contamination risk reduction.
EMA Annex 1 revisions on sterile manufacturing are mandating continuous viable and non-viable particle monitoring in Grade A zones with documented intervention risk assessments. European pharmaceutical operators in Ireland and Switzerland are retrofitting existing lines with isolator-integrated robotics to eliminate human presence during critical operations. The sterile injectables segment faces the steepest compliance timeline, with Q4 2025 deadlines forcing accelerated validation schedules.
Biopharma procurement teams are unbundling after-sales service contracts from initial equipment purchase, creating competitive pressure on traditional bundled pricing models. Large molecule manufacturers in Research Triangle Park and Cambridge UK are separately negotiating sensor calibration and preventive maintenance agreements with third-party metrology specialists. This pattern is most pronounced among CDMOs operating multi-client facilities where uptime guarantees carry contractual penalties.
Clean Room Robot Market Segmentation
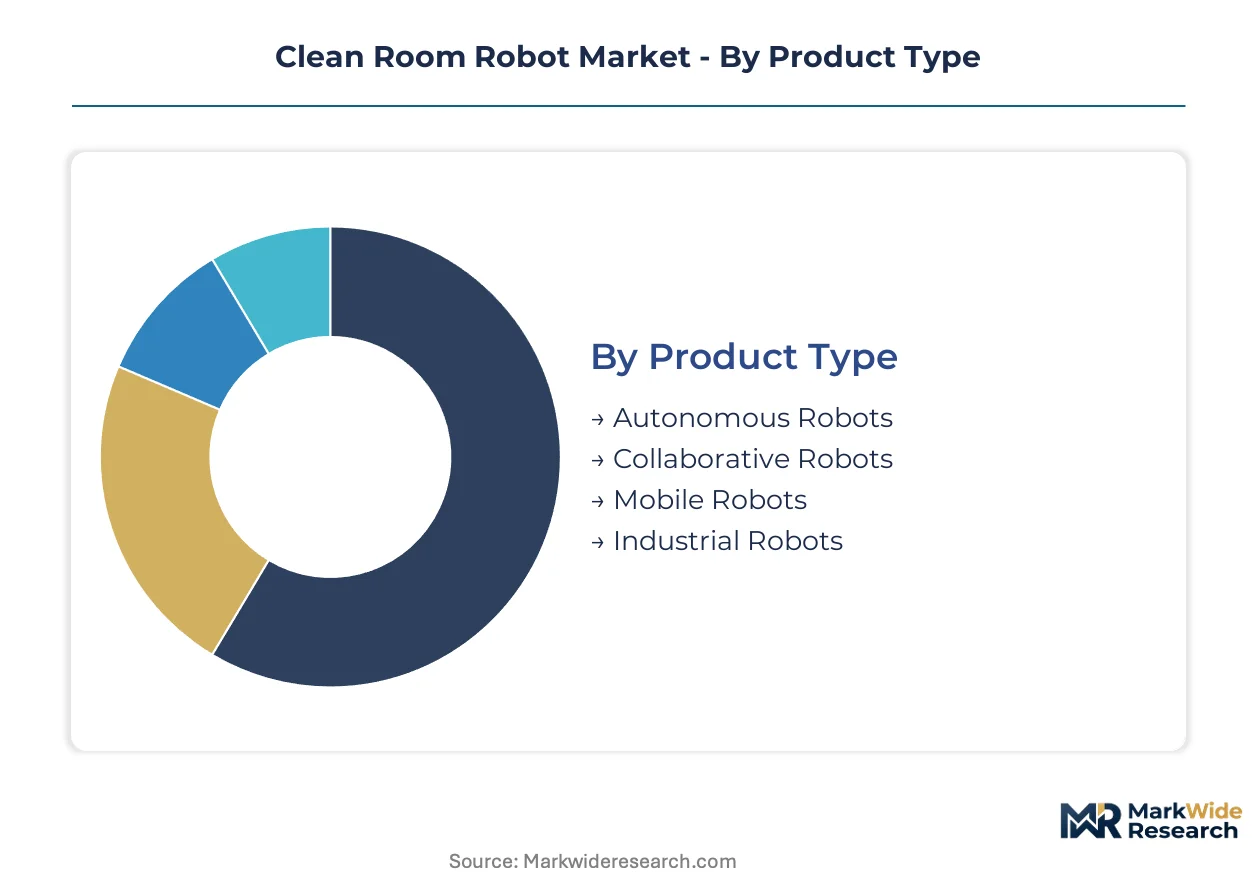
Clean room robot procurement decisions pivot on contamination risk profiles, with semiconductor fabs prioritizing particulate suppression while pharmaceutical operators balance isolator compatibility against retrofit economics. Segmentation reveals how technical specifications diverge across end-use environments, from ISO Class 1 lithography bays to Grade A aseptic filling suites.
Product Type:
Buyers segment first by automation architecture, weighing capital intensity against contamination control rigor.
- Collaborative Robots:Sealed joint architectures enable deployment within existing pharmaceutical suites without full isolator rebuilds. Basel and Boston biopharma facilities pilot these systems for secondary packaging, with site-level quality directors justifying smaller capital outlays against immediate contamination risk reduction.
- Mobile Robots:Autonomous material transport systems navigate clean room corridors using lidar and magnetic tape guidance. Taiwan semiconductor fabs deploy fleets in Hsinchu and Tainan science parks for wafer cassette transport between lithography tools.
- Autonomous Robots:Fully self-directed systems integrate environmental sensing with adaptive path planning for dynamic contamination avoidance.
- Industrial Robots:High-payload articulated arms execute precision assembly in electronics manufacturing with sub-micron repeatability.
Collaborative robots lead on momentum; mobile robots lead on installed base scale.
Technology:
Technology selection tracks the sophistication of environmental feedback requirements, with premium systems embedding real-time monitoring at the manipulation point.
- Sensor Technology:End-effector-embedded particulate counters and viable particle detectors enable continuous environmental verification during manipulation. CDMOs in Research Triangle Park separately negotiate sensor calibration contracts with third-party metrology specialists.
- Artificial Intelligence:Machine learning algorithms predict contamination events from vibration signatures and air pressure differentials. Edge computing architectures embedded in robotic controllers compress response latencies for environmental monitoring.
- Robotics:Core motion control platforms with harmonic drive sealing prevent particulate generation at motion interfaces.
- Computer Vision:Optical inspection systems verify component placement and surface cleanliness without physical contact.
Sensor technology leads on margin expansion; artificial intelligence leads on capability differentiation.
End User:
End-use concentration determines validation protocol complexity, with pharmaceutical applications demanding documented intervention risk assessments.
- Pharmaceuticals:Aseptic filling and sterile injectables manufacturing drive demand for isolator-integrated systems. FDA Grade A zone requirements mandate robotic intervention, eliminating manual filling from critical environments.
- Electronics:Sub-3nm lithography nodes in Taiwan and South Korea require ISO Class 1 environments where human presence introduces unacceptable contamination risk.
- Biotechnology:Large molecule production suites adopt collaborative platforms for flexible batch manufacturing.
- Healthcare:Hospital pharmacy compounding and sterile preparation areas deploy mobile robots for medication transport.
Electronics leads on volume concentration; pharmaceuticals leads on regulatory-driven replacement cycles.
Application:
Application segmentation reflects task criticality, with direct product contact operations commanding premium system specifications.
- Material Handling:Wafer transport, vial movement, and component logistics dominate operational deployments. Navigation algorithm reliability differentiates suppliers in this mature, price-competitive segment.
- Assembly:Precision component joining in semiconductor and medical device manufacturing demands sub-micron positioning accuracy. EU MDR sterile device reclassification expands validated robotic assembly requirements for implantable products.
- Disinfection:UV-C and hydrogen peroxide vapor systems automate surface decontamination between production campaigns.
- Clean Room Monitoring:Mobile sensor platforms conduct continuous viable and non-viable particle surveys across classified zones.
Material handling leads on unit shipments; assembly leads on average selling price premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea and Taiwan concentrate semiconductor-grade clean room robot demand, while Germany and Switzerland anchor pharmaceutical automation systems. India emerges as the fastest-growing retrofit market for collaborative platforms in existing biopharma suites.
United States
FDA Grade A zone mandates drive pharmaceutical robot adoption in sterile injectables manufacturing. The agency's updated aseptic guidance eliminates manual filling from critical environments. Boston and Research Triangle Park biopharma clusters deploy collaborative robots for secondary packaging without full isolator rebuilds.
Germany
EMA Annex 1 revisions on sterile manufacturing push validated robotic systems for Grade A operations. The country's national pharmaceutical regulator enforces continuous particle monitoring requirements. Bavarian and North Rhine-Westphalian pharmaceutical hubs retrofit existing lines with isolator-integrated robotics ahead of compliance deadlines.
Japan
PMDA alignment with international GMP standards accelerates domestic clean room automation adoption. METI industrial policy supports precision equipment manufacturing for next-generation chip fabrication. Tokyo and Osaka industrial corridors supply harmonic drive architectures for ISO Class 1 semiconductor environments.
South Korea
Sub-3nm lithography nodes at Samsung and SK Hynix facilities demand ISO Class 1 robotic systems where human presence introduces contamination risk. MFDS pharmaceutical regulations mirror FDA aseptic standards. Seoul and Yongin science parks concentrate capital investment in validated clean room automation.
India
CDSCO alignment with international GMP standards drives demand for collaborative clean room robots in existing biopharma infrastructure. The national pharmaceutical regulator mandates contamination-controlled automation for sterile manufacturing. Hyderabad and Bengaluru biotech clusters retrofit legacy suites without full isolation rebuilds.
Clean Room Robot Market Vendor Landscape
Japanese producers anchor one tier; German specialists hold another in pharmaceutical-grade systems. The vendor base splits between consolidated precision equipment conglomerates and focused clean room automation boutiques. Two strategic archetypes dominate: CNC heritage manufacturers leveraging motion control expertise, and servo architecture specialists building contamination-sealed drive systems. Capacity expansion in East Asian electronics clusters and technology licensing for pharmaceutical validation protocols represent the dominant competitive moves.
Among Japanese precision equipment manufacturers, FANUC Corporation and Yaskawa Electric Corporation exemplify the CNC heritage archetype, occupying positions where harmonic drive sealing and servo architectures intersect with ISO Class 1 requirements. KUKA AG represents the European pharmaceutical automation specialist, sitting within the modular cell design tier for aseptic processing environments.
| Leading Market Players |
|---|
| ABB Ltd |
| FANUC Corporation |
| Yaskawa Electric Corporation |
| KUKA AG |
| Denso Corporation |
| Mitsubishi Electric Corporation |
| Kawasaki Heavy Industries |
| Omron Corporation |
| Universal Robots |
| Others |
Supply Flow & Price Mechanics
Harmonic drive sealing architectures are compressing particulate generation thresholds while simultaneously concentrating production expertise in Japanese and German precision equipment corridors. This technical transition elevates cost structures for ISO Class 1 certification tiers while fragmenting price competition across lower-grade pharmaceutical retrofit segments.
Pricing Analysis
Capacity additions in Taiwan and South Korea are reshaping price floors for semiconductor-grade systems as Hsinchu and Tainan science parks absorb concentrated capital deployment. Three-tier pricing structure across premium, standard, and economy levels separates isolator-integrated pharmaceutical systems from collaborative retrofit platforms and mobile material handling fleets. Price differentiation hinges on FDA validation documentation depth and harmonic drive origin from Japanese specialty manufacturers. Cost compression in mobile robot tiers is intensifying because navigation algorithm commoditization erodes hardware margins. CDMOs operating multi-client facilities exhibit highest price sensitivity due to uptime guarantee penalties; semiconductor fabs in East Asian clusters demonstrate lowest sensitivity given yield-loss risk from contamination events.
Supply Chain Analysis
Domestic-content mandates in India's pharmaceutical sector and South Korea's semiconductor equipment procurement policies are reshaping component sourcing patterns for regional system integrators. Premium 316L stainless steel enclosures draw from German and Japanese specialty mills; harmonic drive architectures feed from Tokyo and Osaka industrial corridors; servo motor assemblies source from Bavarian and North Rhine-Westphalian precision manufacturers. Single-source vulnerability concentrates in Japanese harmonic drive suppliers serving ISO Class 1 lithography applications. Distribution runs through validated system integrators with FDA/EMA qualification credentials rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The clean room robot market compounds steadily as regulatory mandates for aseptic manufacturing automation harden across FDA and EMA jurisdictions. This structural force generates predictable replacement cycles and validation service revenue streams.
For Market Incumbents: Anchor defensive positioning through captive supply of harmonic drive sealing technologies and ISO Class 1 certification infrastructure. Deepen backward integration into servo architecture production to offset Japanese specialty mill concentration risk. Expand validation protocol libraries across EMA Annex 1 and FDA Grade A zone requirements to entrench switching costs among pharmaceutical operators facing compressed compliance timelines. For New Entrants and Emerging Players: CDSCO alignment with international GMP standards in India opens a window for collaborative robot platforms targeting biopharma retrofit applications without full isolator rebuilds. Concentrate initial deployment in Hyderabad and Bengaluru clusters where site-level quality directors control decentralized procurement authority. Pursue sensor-embedded end-effector architectures to capture recurring calibration service revenue beyond hardware margins. For Investors and Strategic Acquirers: Valuations sit cheapest among European pharmaceutical automation boutiques with EMA validation credentials but limited East Asian electronics exposure. Frame long-term viability around isolator-integrated robotics capability as sterile injectables compliance deadlines force accelerated replacement cycles. Monitor CDSCO enforcement intensity in Indian biopharma corridors as inflection indicator for collaborative platform demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Validation Protocol Harmonization | EMA Annex 1 and FDA Grade A convergence reduces multi-site certification costs for pharmaceutical operators. |
| Sensor-Embedded End-Effector Development | Real-time particulate monitoring at manipulation points creates recurring service revenue beyond hardware margins. |
| Regional Capacity Expansion | Taiwan fab investments in Hsinchu and Tainan concentrate demand for ISO Class 1 robotic systems. |
| Collaborative Platform Certification | Sealed joint architectures enable pharmaceutical suite retrofits without full isolator infrastructure rebuilds. |
| Technician Training Ecosystem Buildout | Cross-disciplinary ISO 14644 and servo maintenance expertise commands wage premiums exceeding 40% in Seoul clusters. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture both installed base dynamics and regulatory interpretation variance. Primary engagement with clean room engineering directors, pharmaceutical quality assurance leads, semiconductor fab automation managers, and robotic system validation specialists informed demand segmentation. Secondary validation drew from FDA guidance documents, EMA Annex 1 revisions, ISO 14644 certification databases, and SEC filings of listed precision equipment manufacturers. Bottom-up unit shipment modeling triangulated against top-down capital expenditure projections across electronics and pharmaceutical manufacturing clusters.
Segment-weighting approaches distributed value estimates across product type, technology tier, end-use industry, and application intensity dimensions. Modeled variables included collaborative versus industrial robot architecture mix, sensor integration depth, and isolator compatibility grades. CAGR derivation incorporated semiconductor node transition timelines and pharmaceutical regulatory compliance deadline clustering. Forecast inputs captured harmonic drive supply constraints and technician wage inflation in East Asian manufacturing corridors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden ISO 14644 threshold revisions or geopolitical disruption to Japanese harmonic drive supply chains. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and capital commitment continuity in Taiwan fab expansion programs. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global Automated Guided Vehicle (AGV) Software Market
Robotics and Automation
Global Robotics Market
Robotics and Automation
Cleanroom Robots in Healthcare Market
Robotics and Automation
Autonomous Drilling Robots Market
Robotics and Automation
Asia-Pacific Service Robotics Market
Robotics and Automation
Autonomous Polishing Machine Market
Robotics and Automation
Asia-Pacific Robotics Technology Market
Robotics and Automation
Bionic Glove's Market
Robotics and Automation
LAMEA Demolition Robot Market
Robotics and Automation
Global Robotic Process Automation in Healthcare Market
Robotics and Automation
Search and Rescue Robots Market
Robotics and Automation
Hospital Robots Market
Robotics and Automation
Solar Panel Cleaning Robot Market
Robotics and Automation
Social Robots Market
Robotics and Automation
North America Automated Guided Vehicle (AGV) Market
Robotics and Automation
AGV Dispatch Management Platforms Market