
 Hospital Robots Market | 2026-2036
Hospital Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Hospital Robots Market Insights
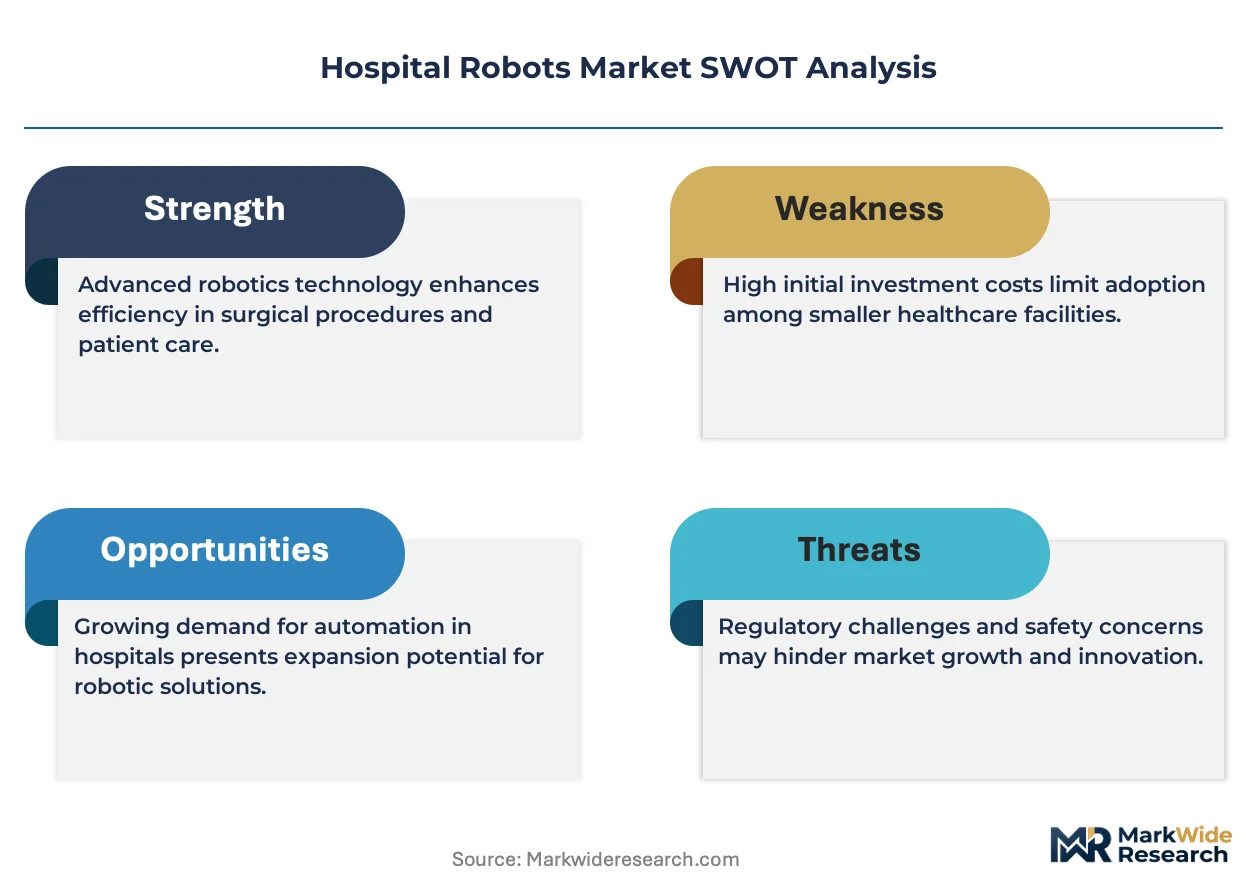
ISO 13485 certification is reorganizing the competitive landscape for hospital robotics manufacturers, raising barriers for unqualified entrants while privileging incumbents with established quality management systems. Intuitive Surgical leverages decades of da Vinci platform refinement to dominate soft-tissue surgical robotics. Stryker Corporation anchors its position through integrated orthopedic navigation systems and Mako robotic-arm technology. Medtronic competes by extending its Hugo RAS platform into geographies previously underserved by robotic surgery.
Hospital robots encompass electromechanical systems engineered for clinical environments, typically operating with sub-millimeter precision, ISO 14644 cleanroom compatibility, and electromagnetic interference shielding to prevent disruption of patient monitoring equipment. Surgical robots command the largest installed base and highest average selling prices, while disinfection robots are expanding fastest as hospitals prioritize automated terminal cleaning to reduce healthcare-associated infections. Transport robots occupy a maturing segment where margin pools have compressed amid commoditization of autonomous mobile robot platforms.
FDA premarket notification requirements and the EU MDR conformity assessment process shape product development cycles, forcing manufacturers to front-load clinical validation spending before commercial release. Japan's PMDA and METI jointly influence robotics adoption through reimbursement coding decisions and industrial policy incentives for healthcare automation. Stakeholders must monitor evolving regulatory harmonization between FDA and EU notified bodies, as divergent approval pathways threaten to fragment product portfolios and strain R&D budgets across multiple compliance regimes.
Market Dynamics
Hospital capital allocation committees are compressing vendor selection cycles as ISO 13485 certification becomes a binary filter, forcing procurement departments to disqualify non-compliant suppliers before technical evaluation begins.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated premarket notification reviews for predicate-device robotics are shortening commercialization timelines for minimally invasive surgical platforms in United States health systems.
- Germany's Hospital Future Act funding:Federal investment pools for digital infrastructure are directly subsidizing robotic system acquisitions in university hospitals and municipal Klinikum networks.
- Autonomous navigation stack maturation:Lidar-vision sensor fusion from industrial automation is transferring to disinfection and transport robots, reducing per-unit software development costs.
Market Restraints
- Surgical robot capital intensity:Da Vinci-class systems require dedicated operating room construction, sterile supply chain reconfiguration, and instrument sterilization infrastructure that locks hospitals into single-vendor ecosystems.
- EU MDR conformity assessment backlog:Notified body capacity constraints are extending EU market entry timelines to 18-24 months for novel robotic platforms without established predicate devices.
- Disinfection robot commoditization:Autonomous mobile robot chassis from Chinese industrial suppliers are eroding hardware margins for established terminal cleaning equipment manufacturers.
Strategic Opportunities
- Japan's PMDA reimbursement expansion:New procedure codes for robotic-assisted thoracic and colorectal surgery are unlocking hospital budget lines previously reserved for conventional laparoscopy.
- Telepresence surgical consultation:5G-enabled remote proctoring is creating subscription revenue streams for academic medical centers with established robotic surgery programs.
- India's medical device PLI scheme:Production-linked incentives for local manufacturing are attracting component suppliers to establish cleanroom assembly for export-qualified surgical robots.
Industry Challenges
- Electromechanical technician scarcity:Hospital biomedical engineering departments lack personnel trained in harmonic drive maintenance and force-sensor calibration for articulated surgical arms.
- Legacy EMR integration friction:Robotic system data outputs require custom HL7 FHIR mapping to populate electronic health records, extending implementation timelines.
- IP thickets in haptic feedback:Patent portfolios covering force-reflection algorithms are forcing second-tier manufacturers to license or design around foundational university research.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hospital Robots Market |
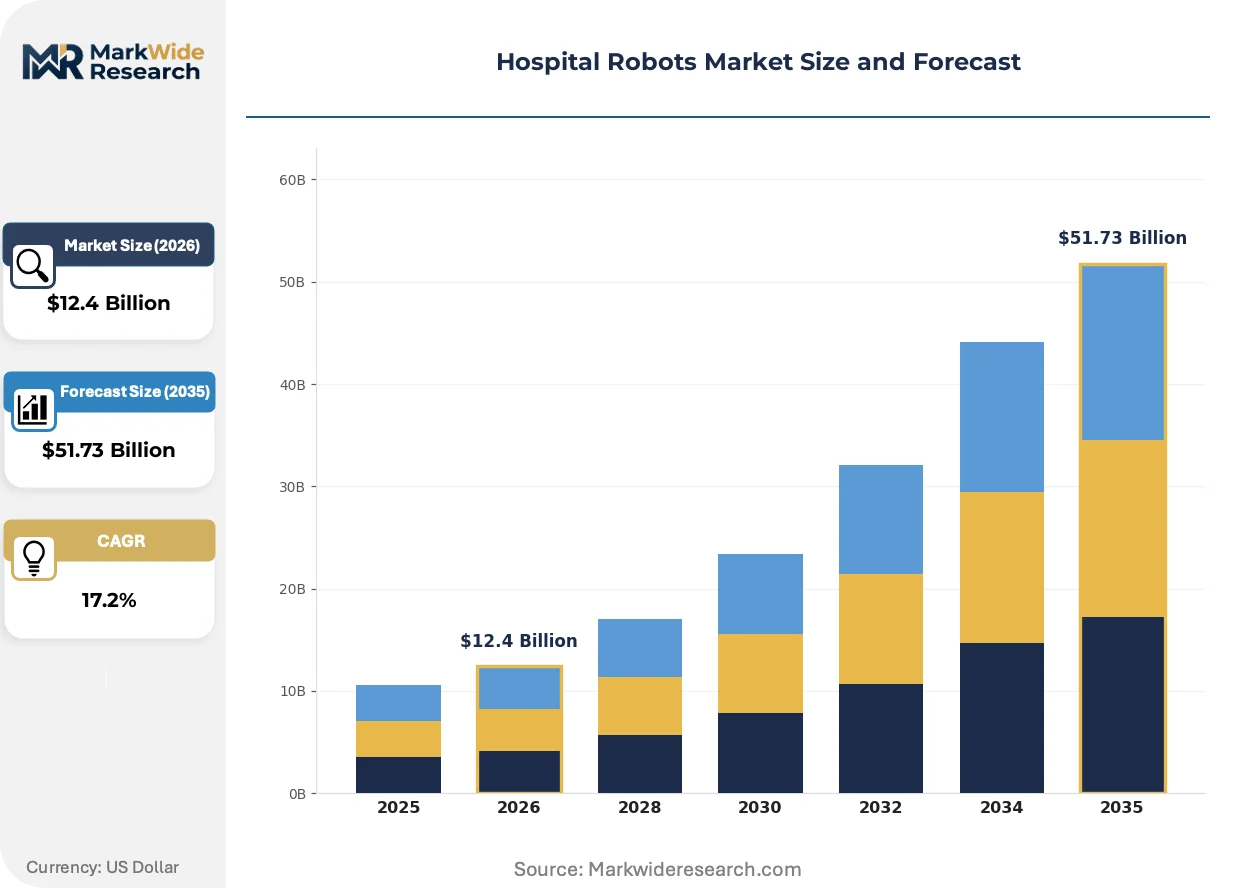
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $51.73 Billion |
| CAGR (2026 – 2036) | 17.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Robots, Rehabilitation Robots, Disinfection Robots, Transport Robots Technology: Artificial Intelligence, Autonomous Navigation, Remote Control, Computer Vision End User: Hospitals, Clinics, Rehabilitation Centers, Surgery Centers Application: Minimally Invasive Surgery, Patient Care, Sterilization, Logistics |
| Companies Covered | Intuitive Surgical, Stryker Corporation, Medtronic, Zimmer Biomet, Smith & Nephew, Johnson & Johnson, Omron Corporation, Aethon, Xenex Disinfection Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hospital Robots Market Trends and Innovations
Electromechanical architectures are diverging as single-platform dominance gives way to specialized systems optimized for specific anatomical procedures and hospital workflows.
Modular surgical robot designs are fragmenting the historical integrated-system model. Independent arm carts with detachable instrument drives allow hospitals to stage capital expenditure across multiple budget cycles. Academic medical centers in Germany and Japan are piloting vendor-agnostic operating rooms where interchangeable patient-side manipulators dock to shared vision towers. This interoperability is compressing switching costs and enabling multi-vendor procurement strategies that were technically impossible with first-generation platforms.
EU MDR Article 10 post-market surveillance requirements are mandating systematic clinical follow-up data collection for implantable and active therapeutic devices. Robotic surgery manufacturers must now fund prospective registry studies or risk certificate suspension. German notified bodies are interpreting this most strictly, requiring annual safety update reports that include real-world adverse event rates. High-volume surgical centers in Stuttgart and Munich are becoming preferred clinical evidence generation sites.
Hospital purchasing consortia are consolidating vendor negotiations for robotic systems. GPOs in the United States are bundling capital equipment, disposable instruments, and service contracts into multi-year agreements with volume commitments. This aggregation is shifting negotiation leverage toward buyers with da Vinci case volumes above 500 annually. Tertiary hospitals in Texas and Florida are leading this consolidation, extracting extended warranty terms and training credits that independent facilities cannot match.
Hospital Robots Market Segmentation
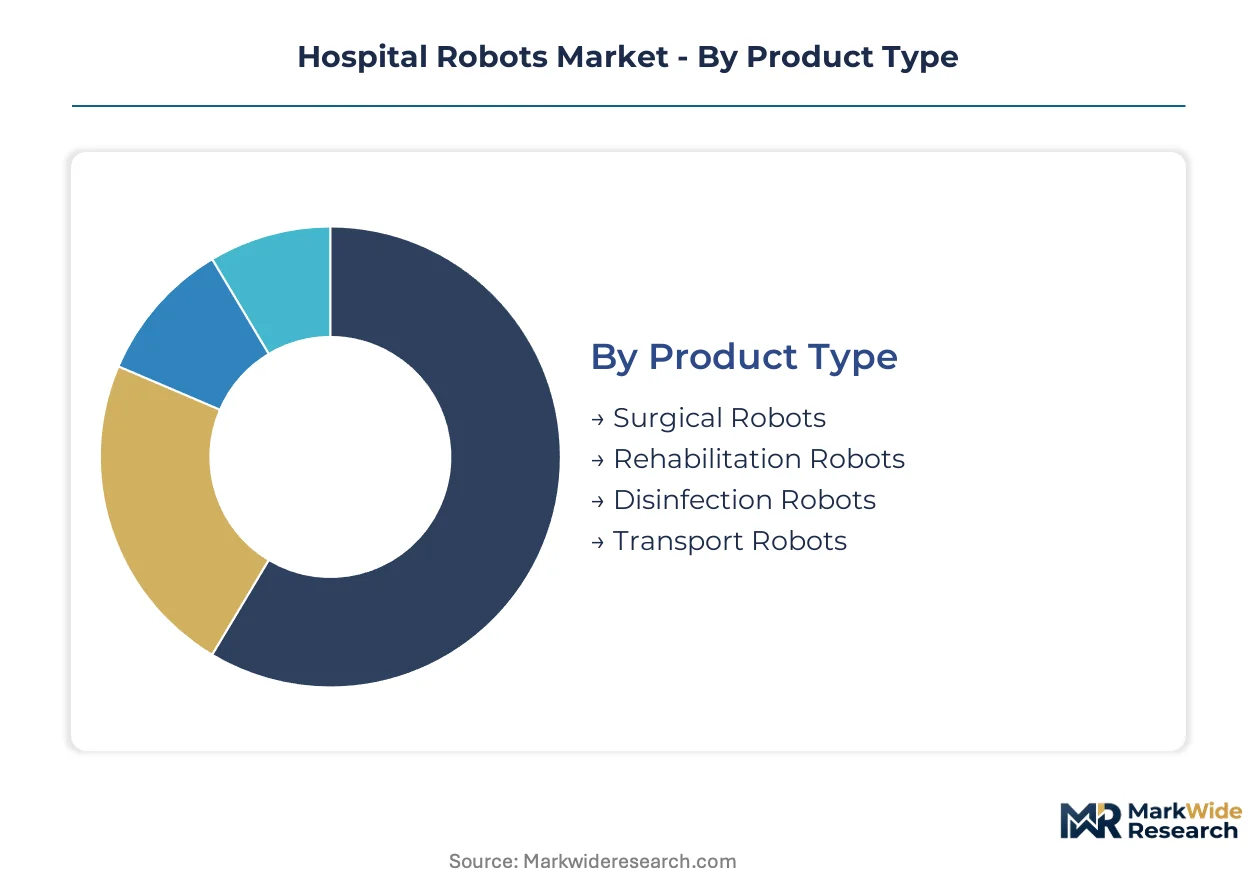
Hospital robotics procurement channels diverge sharply by product complexity. Surgical platforms flow through capital equipment committees with multi-year depreciation schedules, while disinfection and transport units increasingly bypass traditional distribution through direct-to-hospital SaaS models.
Product Type:
Surgical robots command dedicated sales cycles through hospital value analysis committees, whereas disinfection and transport categories penetrate via infection control and facilities departments with abbreviated procurement timelines.
- Surgical Robots:Articulated manipulator arms with haptic feedback and stereoscopic vision systems enable sub-millimeter precision in soft-tissue procedures. Demand concentrates in German university hospitals and Japanese cancer centers where da Vinci case volumes exceed 400 annually, though capital intensity locks purchasers into single-vendor instrument ecosystems.
- Disinfection Robots:Autonomous mobile platforms equipped with UV-C arrays or hydrogen peroxide vapor systems execute terminal cleaning protocols without human exposure to biocidal agents. Texas and Florida hospital systems are expanding fleets fastest as healthcare-associated infection penalties stiffen under CMS quality programs.
- Rehabilitation Robots:Exoskeleton and end-effector devices deliver repetitive motion therapy for stroke and spinal cord recovery.
- Transport Robots:Autonomous mobile robots shuttle pharmaceuticals, specimens, and supplies through hospital corridors using lidar-vision navigation.
By volume, Transport Robots lead through commoditized chassis deployment. By growth pace, Disinfection Robots are expanding most quickly as infection control budgets detach from general capital constraints.
Technology:
Technology selection determines regulatory pathway complexity and R&D amortization horizons, with AI-enabled systems facing heightened FDA scrutiny compared to remote-control platforms with established predicate devices.
- Artificial Intelligence:Machine learning algorithms for intraoperative decision support and predictive maintenance require extensive clinical validation under FDA software-as-medical-device guidance. PMDA in Japan is advancing reimbursement frameworks for AI-augmented surgical planning faster than EU notified bodies, concentrating pilot deployments in Tokyo and Osaka academic networks.
- Autonomous Navigation:SLAM-based positioning and dynamic obstacle avoidance enable unsupervised operation in unstructured clinical environments. German hospitals are standardizing on this stack for disinfection fleets to minimize IT integration overhead.
- Remote Control:Teleoperation architectures with force feedback allow surgeon console separation from patient-side manipulators.
- Computer Vision:Real-time anatomical recognition and instrument tracking support autonomous camera control and tissue classification.
By installed base, Remote Control dominates through mature surgical teleoperation platforms. By capability expansion, Artificial Intelligence is gaining share fastest as training data pools deepen.
End User:
End-user type shapes contract structure, with hospitals demanding comprehensive service agreements while surgery centers prioritize pay-per-use instrument access to preserve liquidity.
- Hospitals:Tertiary medical centers with embedded biomedical engineering departments absorb full lifecycle ownership of robotic platforms, including preventive maintenance and software update management. US health systems with 500+ beds are consolidating purchasing through GPOs to extract volume-based instrument pricing.
- Surgery Centers:Ambulatory facilities prioritize compact footprints and rapid sterilization turnaround to maximize block utilization. Arizona and California outpatient networks are leading adoption of modular robotic arms with detachable instrument drives.
- Clinics:Primary and specialty care settings deploy rehabilitation and point-of-care diagnostic robots.
- Rehabilitation Centers:Dedicated physical therapy facilities utilize exoskeleton and robotic gait trainers for intensive neurorehabilitation protocols.
By capital deployment, Hospitals absorb the largest absolute investment. By penetration rate, Surgery Centers are climbing the fastest as outpatient migration accelerates.
Application:
Application focus determines competitive set and margin structure, with minimally invasive surgery attracting dedicated robotics incumbents while logistics applications face encroachment from industrial automation suppliers.
- Minimally Invasive Surgery:Robotic platforms enable single-port and natural-orifice approaches through wristed instrumentation and tremor filtration. Stuttgart and Munich surgical centers are becoming preferred sites for EU MDR post-market surveillance data generation due to high case volumes and systematic outcomes tracking.
- Sterilization:Automated terminal cleaning reduces environmental services labor costs and improves compliance with Joint Commission infection control standards. Japanese hospitals are integrating these systems with building management platforms under METI smart hospital initiatives.
- Patient Care:Robotic assistance for mobilization, feeding, and vital sign monitoring addresses nursing workforce shortages.
- Logistics:Autonomous material transport within hospital campuses streamlines pharmacy and laboratory workflows.
By revenue concentration, Minimally Invasive Surgery leads through high system and disposable pricing. By deployment velocity, Sterilization is expanding most rapidly as labor cost pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Hospital Future Act and Japan's METI smart hospital directives are accelerating capital deployment for robotic systems, while FDA clearance timelines in the United States compress competitive windows for new platform entrants.
United States
Texas and Florida health systems lead procurement of disinfection robot fleets as CMS healthcare-associated infection penalties stiffen. FDA 510(k) pathway streamlining shortens premarket notification reviews for predicate-device surgical platforms. Academic medical centers in Houston and Miami extract volume-based instrument pricing through GPO consolidation.
Germany
Federal investment pools under the Hospital Future Act directly subsidize robotic acquisitions in university hospitals and municipal Klinikum networks. EU MDR Article 10 post-market surveillance requirements mandate systematic clinical follow-up data collection, with German notified bodies interpreting standards most strictly. Stuttgart and Munich surgical centers generate preferred clinical evidence for registry studies.
Japan
PMDA reimbursement expansion for robotic-assisted thoracic and colorectal surgery unlocks hospital budget lines previously reserved for conventional laparoscopy. METI industrial policy incentives coordinate building management platform integration for automated terminal cleaning systems. Tokyo and Osaka academic networks concentrate pilot deployments of AI-augmented surgical planning.
India
Production-linked incentives under the medical device PLI scheme attract component suppliers to establish cleanroom assembly for export-qualified surgical robots. CDSCO regulatory harmonization efforts with FDA and EU notified bodies streamline dual-market product development. Karnataka and Telangana host emerging clusters for precision electromechanical manufacturing.
Hospital Robots Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and regulatory certification dimensions. The market exhibits tiered consolidation around integrated surgical platform incumbents and fragmented competition in commoditized disinfection and transport segments. Three strategic archetypes dominate: full-stack surgical system providers, modular component specialists, and autonomous mobile robot chassis fabricators. M&A activity concentrates on haptic feedback IP acquisitions, while capacity expansion focuses on ISO 13485-certified cleanroom assembly for dual-market qualification.
Within the full-stack surgical tier, Intuitive Surgical and Stryker Corporation exemplify decades-long platform refinement strategies that lock hospitals into single-vendor instrument ecosystems. Medtronic occupies a geographic expansion position, extending RAS platform reach into previously underserved markets. Among autonomous navigation specialists, Omron Corporation represents industrial automation technology transfer into clinical environments.
| Leading Market Players |
|---|
| Intuitive Surgical |
| Stryker Corporation |
| Medtronic |
| Zimmer Biomet |
| Smith & Nephew |
| Johnson & Johnson |
| Omron Corporation |
| Aethon |
| Xenex Disinfection Services |
| Others |
Pricing and Supply Chain Analysis
Long-term instrument supply agreements lock hospital systems into predictable per-procedure costs while securing exclusive access to proprietary robotic arm consumables and sterilization-compatible instrument trays. These multi-year contracts bundle capital depreciation, disposable instrument flows, and preventive maintenance into fixed annual commitments that compress working capital volatility for procurement committees.
Pricing Analysis
Certification level creates the primary spread between ISO 13485-certified surgical platforms and uncertified chassis imports. Three-tier pricing structure across premium, standard, and economy levels reflects FDA clearance status, EU MDR conformity depth, and after-sales service bundling. Cost compression in the economy tier intensifies as Chinese autonomous mobile robot suppliers flood disinfection and transport segments with commodity hardware. Surgery centers exhibit highest price sensitivity due to constrained capital budgets and rapid block utilization requirements, while tertiary hospitals absorb premium pricing through GPO-negotiated volume commitments.
Supply Chain Analysis
Container availability on Asia-Europe trade lanes and port congestion at Rotterdam and Hamburg are extending lead times for precision electromechanical components sourced from East Asian manufacturing clusters. Supply concentrates in Germany, Japan, and the United States for harmonic drives, force sensors, and surgical-grade stainless steel instrument forgings. Raw material dependencies include rare earth magnets for servo motors, high-purity aluminum for lightweight arm structures, and medical-grade polymers for disposable instrument housings. Single-source vulnerability persists in haptic feedback controller ASICs. Distribution runs through authorized distributor networks for surgical platforms and direct-to-hospital SaaS provisioning for disinfection fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are shifting toward vendor-agnostic operating rooms where interchangeable patient-side manipulators dock to shared vision towers, collapsing historical switching costs and enabling multi-vendor procurement strategies.
For Market Incumbents: Consolidate instrument ecosystem lock-in through expanded sterilization infrastructure partnerships and exclusive GPO contract extensions. Acquire haptic feedback IP portfolios to neutralize patent litigation exposure from university research spinouts. Prioritize backward integration into precision gearbox manufacturing to defend margin position against component cost volatility. For New Entrants and Emerging Players: Lead with modular surgical arm architectures targeting ambulatory surgery centers in Arizona and California where rapid sterilization turnaround and compact footprints command premium positioning. Exploit reimbursement coding gaps in Japan's PMDA framework for robotic-assisted thoracic procedures. Deploy subscription-based instrument access models to preserve customer liquidity and accelerate adoption velocity. For Investors and Strategic Acquirers: Capital is best deployed toward ISO 13485-certified component specialists with established cleanroom assembly capacity for dual-market FDA-EU qualification. Long-term viability hinges on regulatory harmonization execution and post-market surveillance infrastructure scalability. Watch for EU MDR notified body capacity expansion as the definitive inflection signal for novel platform commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Unlocks EU MDR conformity assessment pathways and hospital procurement committee eligibility. |
| Modular Surgical Arm Development | Enables staged capital expenditure across budget cycles for cost-constrained surgery centers. |
| Hospital System Partnership | Secures preferred clinical evidence generation sites for EU MDR post-market surveillance compliance. |
| Software Companion Development | Supports HL7 FHIR EMR integration and AI-augmented surgical planning reimbursement expansion. |
| Reimbursement Strategy | Aligns PMDA procedure codes with hospital budget line unlocks in Japan's academic networks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and robotic surgery program coordinators. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR notified body conformity assessment records, CMS Medicare reimbursement coding updates, and hospital procurement consortium contract disclosures. Bottom-up installed base modeling and top-down capital expenditure forecasting were triangulated to anchor volume and value estimates.
Across the analysis window, projections incorporate segmentation by product type, technology stack, end-user facility class, and application focus. CAGRs were derived from regression analysis against historical capital equipment procurement cycles, reimbursement expansion trajectories, and regulatory clearance velocity. Industry-specific inputs include EU MDR Article 10 post-market surveillance compliance costs and Japan METI smart hospital infrastructure subsidy allocation patterns.
Forecasts assume regulatory continuity in FDA 510(k) pathway operations and EU MDR notified body capacity; material policy shifts would require re-modeling. Specific risks that could revise projections include electromechanical technician labor scarcity, legacy EMR integration friction, and divergence in transatlantic regulatory harmonization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Underwater Drone Market
Robotics and Automation
France Cloud Robotics Market
Robotics and Automation
Asia-Pacific AUV Market
Robotics and Automation
Robot End-Effector Market
Robotics and Automation
Global Exoskeleton Market
Robotics and Automation
AI Powered Robot Market
Robotics and Automation
Exoskeleton Systems Market
Robotics and Automation
Dispensing Robots Market
Robotics and Automation
Security and Law Enforcement Robot Market
Robotics and Automation
Underwater Robot Market
Robotics and Automation
Servo Gripper Market
Robotics and Automation
Virtual 3D Nanorobots Market
Robotics and Automation
SLAM Robots Market
Robotics and Automation
Collaborative Robots Market
Robotics and Automation
Laboratory Robotics Market
Robotics and Automation
Cloud Robotics Market