
 Hoist Sling Chains Assemblies Market | 2026-2036
Hoist Sling Chains Assemblies Market Size, Share, and Industry Trends Forecast 2026-2036
Hoist Sling Chains Assemblies Market Intelligence
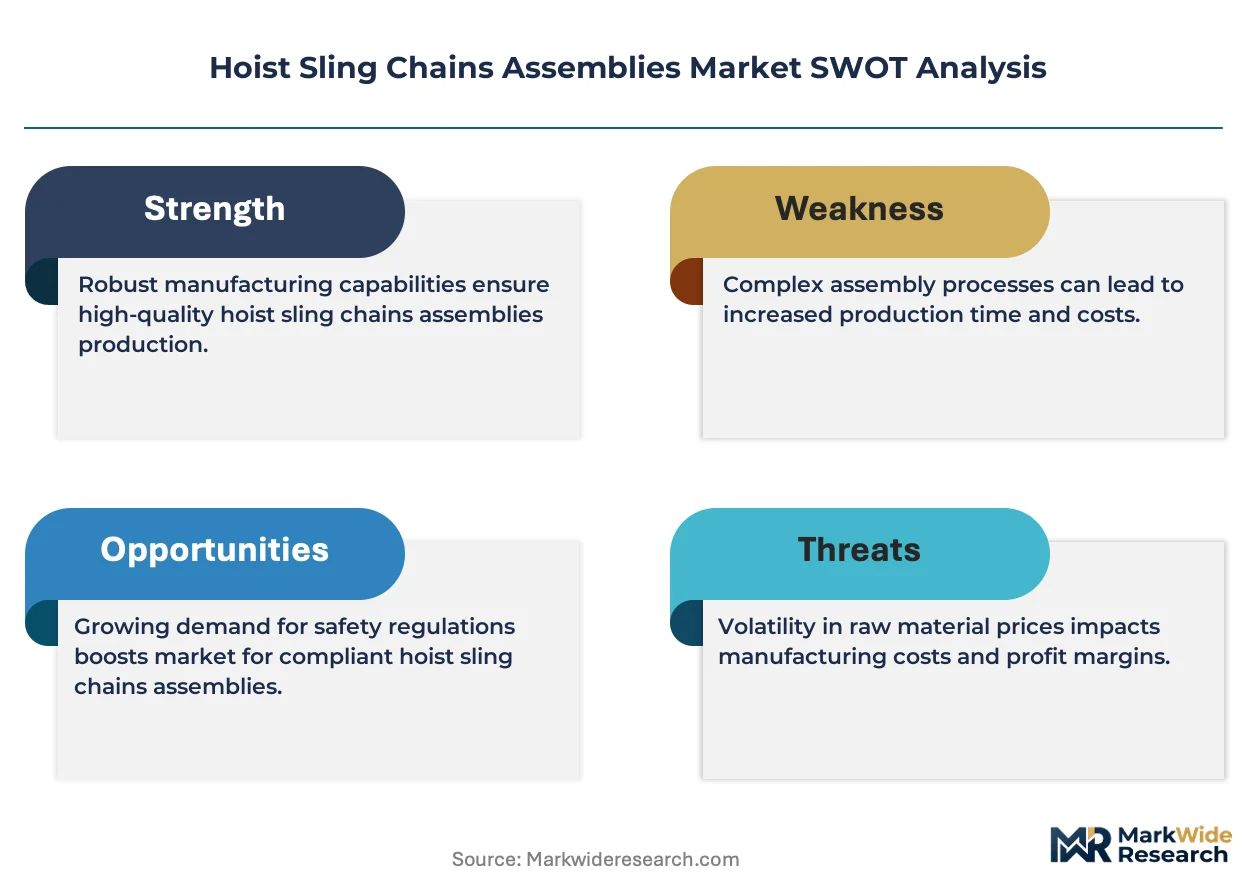
Multi-source procurement is realigning how construction firms and mining operators secure hoist sling chains assemblies, shifting away from sole-source contracts toward qualified vendor panels. Columbus McKinnon Corporation leverages its North American manufacturing footprint to anchor supply agreements with major infrastructure contractors. RUD Group competes through specialized alloy chain expertise for offshore and subsea rigging applications. Gunnebo Industries sustains European market presence with vertically controlled heat treatment facilities that guarantee Grade 100 consistency.
Hoist sling chains assemblies are engineered lifting devices composed of welded alloy steel links, typically manufactured to Grade 80 or Grade 100 strength classifications with proof-load testing at two times the working load limit, designed to suspend and maneuver heavy materials in industrial environments where wire rope or synthetic alternatives face abrasion or temperature constraints. Grade 100 chains command premium positioning due to their higher strength-to-weight ratio, which permits downsized rigging configurations without sacrificing load capacity. Construction Equipment Handling represents the most mature application segment, while Mining Lifting generates faster replacement cycles and aftermarket attachment sales because of abrasive operating conditions.
OSHA sling inspection mandates in the United States and REACH material compliance requirements in Europe impose recurring replacement schedules and restricted substance protocols that elevate product quality thresholds and documentation burdens. China's SAMR enforces GB standards certification for imported lifting chains, creating market access friction for uncertified foreign suppliers. Stakeholders must monitor evolving alloy traceability requirements and pre-qualify dual-source manufacturing footprints before tender windows compress.
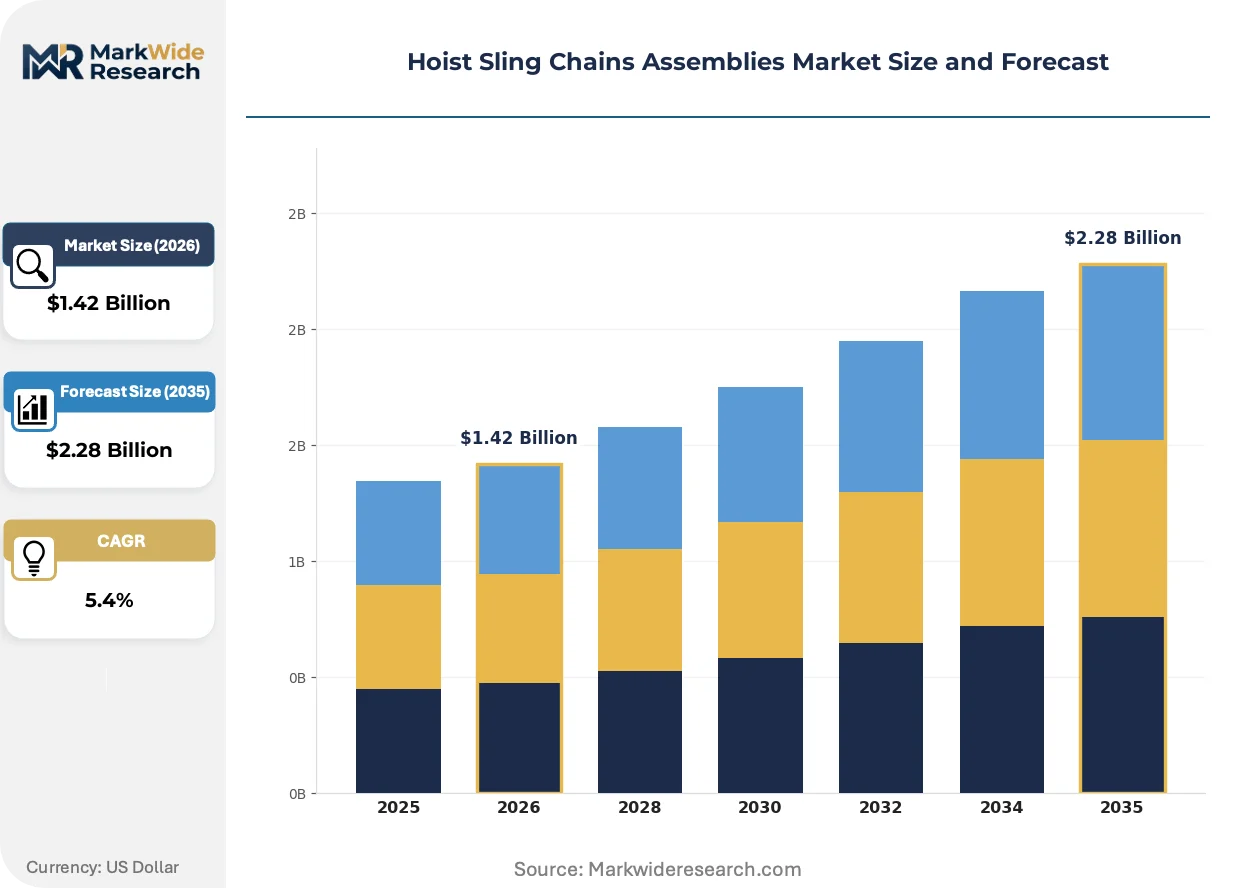
Market Dynamics
Grade 100 alloy chains are compressing Grade 80 configurations across heavy-lifting applications, driven by regulatory mandates for lighter rigging without load sacrifice and by mining operators seeking reduced manual handling exposure.
Growth Catalysts
- OSHA inspection mandates:US construction and maritime sectors face quarterly documented sling inspections, forcing predictable replacement cycles and certified product demand.
- Mining abrasive conditions:Australian and Chilean open-pit copper operations generate 18-24 month replacement intervals versus 5-7 years in general industry, amplifying aftermarket attachment sales.
- Subsea rigging expansion:North Sea and Gulf of Mexico decommissioning projects require corrosion-resistant Grade 100 assemblies with magnetic particle inspection traceability.
Market Restraints
- Alloy steel price volatility:Nickel and chromium input costs fluctuate with stainless steel market dynamics, squeezing margin on fixed-price infrastructure contracts.
- China SAMR certification friction:GB standards compliance adds 6-9 month import delays for uncertified European and North American suppliers.
- Synthetic sling substitution:High-performance aramid fiber alternatives capture below-10-ton lifting in controlled environments where abrasion risk is minimal.
Strategic Opportunities
- India infrastructure build-out:Dedicated Freight Corridor and metro rail projects require Grade 80 and Grade 100 assemblies for precast segment erection.
- REACH material traceability:European importers must document alloy origin and heat treatment batch records, favoring suppliers with captive foundry-to-finish control.
- Rental fleet digitization:RFID-embedded chains enable usage-hour tracking and predictive replacement, opening software-integrated hardware revenue streams.
Industry Challenges
- Magnetic particle inspection technician shortage:Certified NDT personnel for crack detection in high-cycle chains command premium wages and limit testing throughput.
- Dual-source qualification timelines:Major contractors require 12-18 month parallel supplier validation before tender acceptance, freezing out new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hoist Sling Chains Assemblies Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grade 80 Chains, Grade 100 Chains, Alloy Chains, Stainless Steel Chains, Heat Treated Chains Application: Construction Equipment Handling, Shipyard Rigging, Mining Lifting, Manufacturing Assembly, Heavy Load Transport End User: Construction Firms, Shipbuilding Companies, Mining Operators, Manufacturing Plants, Logistics Providers Installation Type: Fixed Lifting Points, Portable Hoist Systems, Overhead Cranes, Gantry Cranes, Mobile Lifting Devices |
| Companies Covered | Columbus McKinnon Corporation, RUD Group, Gunnebo Industries, Pewag Group, The Crosby Group LLC, Peerless Industrial Group, KITO Corporation, Apex Tool Group LLC, J.D. Theile GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hoist Sling Chains Assemblies Market Strategic Shifts & Innovations
Digital traceability and automated inspection protocols are reconfiguring how sling chains are specified, monitored, and retired across asset-intensive industries.
Grade 100 quenched and tempered alloy steel is consolidating market position in overhead lifting applications where weight reduction translates to crane capacity gains. Offshore wind installation contractors in the North Sea and Taiwan Strait have standardized on Grade 100 master links and sub-assemblies for nacelle lifts above 500 tons. This material transition is consolidating supplier bases around heat-treatment capabilities that smaller forges cannot replicate.
REACH substance restrictions and SCIP database obligations in Europe now require full material disclosure for alloy trace elements and surface coating chemistries. Importers must register chain compositions in the ECHA database before customs release. German heavy transport fleets under KBA inspection protocols have responded by mandating supplier-provided batch certificates with every delivery.
Asset owners are unbundling inspection services from original equipment purchases, contracting third-party NDT providers for periodic magnetic particle and ultrasonic testing. This disintermediation pressures manufacturers to compete on unit economics rather than bundled service contracts. The shift is most pronounced in Australian mining and US Gulf Coast petrochemical clusters where safety-critical lifting schedules demand independent verification.
Hoist Sling Chains Assemblies Market Segmentation
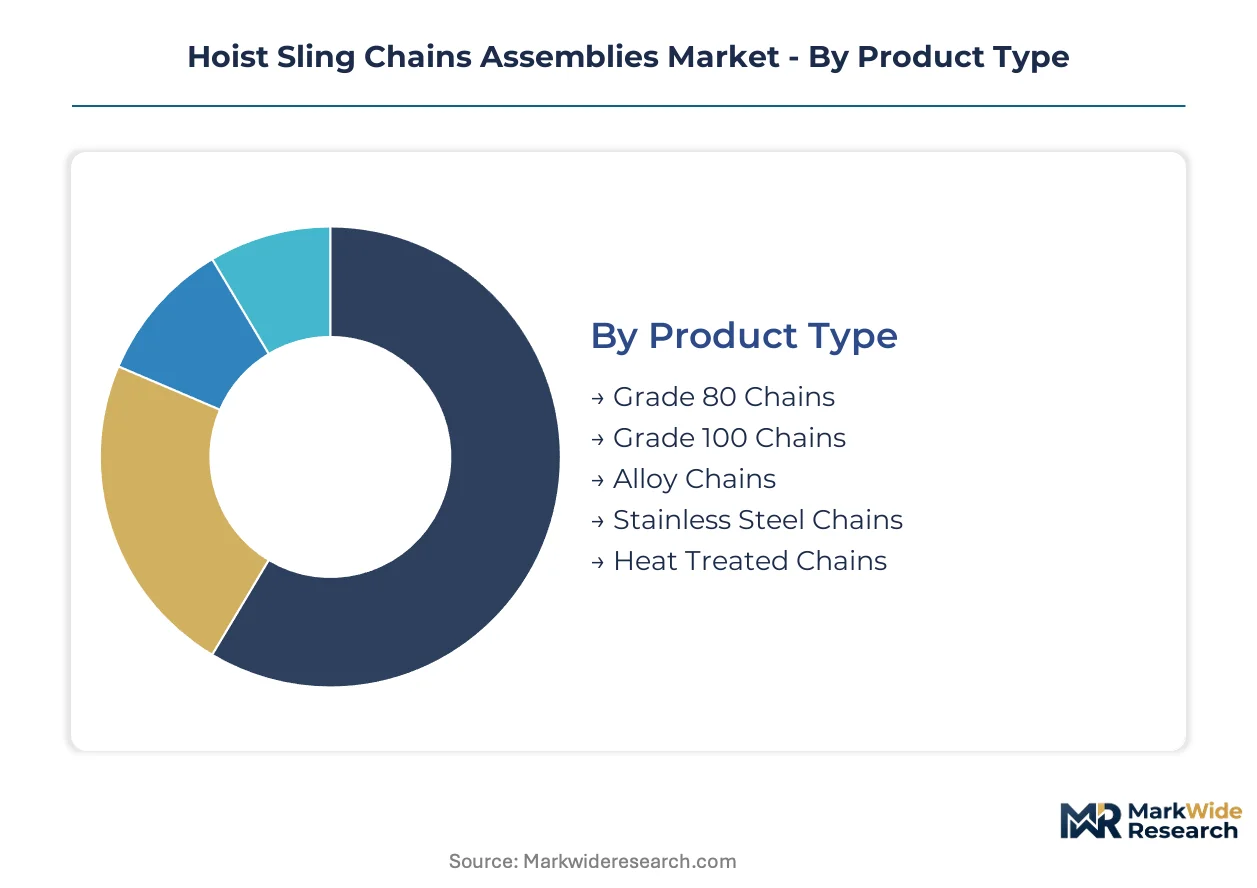
Hoist sling chains assemblies segment across four dimensions that dictate procurement patterns, certification requirements, and replacement cycles. Product grade determines regulatory compliance thresholds, while application environment governs abrasion exposure and inspection frequency. End-user scale shapes contract structure, and installation type fixes safety margin calculations.
Product Type:
Standardization dominates at the commodity end, while Grade 100 and specialty alloys command engineered-to-order specifications with full batch traceability.
- Grade 80 Chains:Quenched and tempered carbon steel construction rated for four-to-one safety factor under EN 818-2. Construction firms in Germany's Ruhr corridor specify Grade 80 for general lifting below 50 tons where weight savings do not justify premium alloys.
- Grade 100 Chains:Alloy steel composition delivers 25% higher strength-to-weight ratio than Grade 80, enabling downsized master link configurations. North Sea offshore wind contractors have standardized on Grade 100 for nacelle lifts exceeding 500 tons, driven by crane capacity constraints and REACH material disclosure mandates.
- Alloy Chains:Custom chromium-nickel-molybdenum formulations for subsea and corrosive environments. Australian mining operators under TGA protocols specify alloy chains for open-pit copper extraction with 18-24 month replacement cycles.
- Stainless Steel Chains:AISI 316 grade for chemical processing and food-grade lifting where corrosion resistance overrides strength optimization.
- Heat Treated Chains:Captive furnace-controlled tempering for critical-path infrastructure projects requiring magnetic particle inspection certificates with every delivery.
Leading the category by volume: Grade 80 Chains. Expanding most quickly: Grade 100 Chains.
Application:
Volume concentrates in mature handling operations, while replacement frequency and attachment sales cluster in abrasive and safety-critical environments.
- Construction Equipment Handling:The most mature segment with predictable five-to-seven-year replacement cycles. US infrastructure contractors under OSHA quarterly inspection mandates drive certified product demand with documented sling retirement protocols.
- Mining Lifting:Abrasive operating conditions in Chilean and Australian open-pit copper operations compress replacement intervals to 18-24 months. This segment generates disproportionate aftermarket attachment sales for hook assemblies and shortening clutches.
- Shipyard Rigging:Salt-air exposure demands corrosion-resistant Grade 100 configurations with full material traceability for naval and commercial newbuild programs.
- Manufacturing Assembly:Repetitive lifting cycles in automotive and aerospace plants favor RFID-embedded chains for usage-hour tracking and predictive replacement scheduling.
- Heavy Load Transport:German KBA-inspected fleets require frequent sling chain replacement with supplier-provided batch certificates for every delivery under road safety protocols.
Construction Equipment Handling generates the largest absolute volume. Mining Lifting shows the steepest expansion trajectory in replacement revenue.
End User:
Procurement scale separates integrated operators with captive inspection capabilities from fragmented buyers relying on third-party NDT services.
- Construction Firms:Multi-source procurement panels now dominate, with 12-18 month dual-source qualification timelines freezing out new entrants. Major infrastructure contractors anchor supply agreements through North American manufacturing footprints.
- Mining Operators:Australian and Chilean open-pit specialists generate fastest replacement cycles and aftermarket attachment sales due to abrasive operating conditions and TGA-mandated workplace safety protocols.
- Shipbuilding Companies:Naval and commercial newbuild programs require corrosion-resistant Grade 100 assemblies with magnetic particle inspection traceability for subsea rigging applications.
- Manufacturing Plants:Asset owners unbundle inspection services from original equipment purchases, contracting independent NDT providers for periodic magnetic particle and ultrasonic testing.
- Logistics Providers:Rental fleet digitization through RFID-embedded chains enables usage-hour tracking and opens software-integrated hardware revenue streams.
Construction Firms anchor procurement volume. Mining Operators drive fastest replacement revenue growth.
Installation Type:
Fixed infrastructure commitments contrast with mobile systems where rental and short-term deployment models predominate.
- Fixed Lifting Points:Permanent anchor installations in heavy manufacturing and process industries with integrated load monitoring systems. German industrial corridors specify fixed points with KBA-inspected certification for heavy transport fleet maintenance.
- Overhead Cranes:Bridge and gantry configurations in steel fabrication and assembly plants require Grade 100 master links for capacity optimization. OSHA mandates govern US installations with quarterly documented inspections.
- Portable Hoist Systems:Modular configurations for construction sites and maintenance operations where rapid deployment overrides permanent infrastructure investment.
- Gantry Cranes:Rail-mounted and rubber-tired variants for shipyard and heavy transport applications with span-adjustable lifting geometries.
- Mobile Lifting Devices:Telescopic boom and crawler configurations for wind turbine installation and decommissioning projects in the North Sea and Taiwan Strait.
Fixed Lifting Points and Overhead Cranes together dominate installed base. Mobile Lifting Devices gain share fastest in offshore wind deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for hoist sling chains assemblies clusters in mining-intensive economies and heavy-transport corridors where regulatory inspection mandates compress replacement cycles. Procurement patterns diverge sharply between resource-extraction regions with abrasive operating conditions and manufacturing belts governed by workplace safety protocols.
United States
Gulf Coast petrochemical clusters and maritime ports drive Grade 100 procurement for subsea decommissioning projects. OSHA quarterly sling inspection mandates force documented replacement schedules across construction and offshore sectors. Houston and New Orleans anchor the heaviest concentration of corrosion-resistant alloy chain demand.
Germany
Ruhr industrial corridor manufacturers specify Grade 80 configurations for general lifting below 50 tons where weight savings do not justify premium alloys. KBA road safety protocols mandate frequent sling chain replacement for heavy transport fleets with supplier-provided batch certificates. Dortmund and Essen concentrate procurement for automotive and steel fabrication applications.
China
MIIT directives on industrial equipment certification redirect procurement toward domestically certified Grade 100 chain suppliers. SAMR enforces GB standards compliance that adds import delays for uncertified foreign suppliers. Yangtze River Delta infrastructure contractors anchor volume for precast segment erection in metro rail and freight corridor projects.
Australia
Open-pit copper operations in Western Australia and Queensland generate 18-24 month replacement intervals versus 5-7 years in general industry. TGA-mandated workplace safety protocols compel mining operators to expand alloy chain assembly procurement with full traceability documentation. Perth and Mount Isa concentrate demand for abrasive-environment lifting configurations.
India
Dedicated Freight Corridor and metro rail projects require Grade 80 and Grade 100 assemblies for precast segment erection across multiple states. BIS certification standards govern domestic procurement while infrastructure build-out accelerates import demand for heat-treated chains. Mumbai and Delhi-NCR anchor the steepest expansion trajectory in replacement revenue.
Hoist Sling Chains Assemblies Market Key Industry Players
Multi-source procurement dominates the current landscape as construction firms and mining operators abandon sole-source contracts for qualified vendor panels. The vendor base separates into integrated manufacturers with captive heat-treatment capabilities and specialized alloy forges serving subsea and corrosive environments. Three archetypes define positioning: North American infrastructure anchors, European precision-forging specialists, and Asian scale producers. M&A activity and geographic expansion represent the dominant competitive vectors as firms secure dual-source qualification status with major contractors.
Among integrated manufacturers with captive furnace control, Columbus McKinnon Corporation and Gunnebo Industries exemplify the premium-tier archetype through vertically controlled production footprints. RUD Group occupies a specialist position within the alloy-forging segment. These three entities represent distinct strategic postures: North American manufacturing anchorage, European heat-treatment consistency, and subsea application expertise respectively.
| Leading Market Players |
|---|
| Columbus McKinnon Corporation |
| RUD Group |
| Gunnebo Industries |
| Pewag Group |
| The Crosby Group LLC |
| Peerless Industrial Group |
| KITO Corporation |
| Apex Tool Group LLC |
| J.D. Theile GmbH & Co. KG |
| Others |
Cost & Logistics Intelligence
Nickel and chromium spot price indices on the London Metal Exchange cascade directly into alloy steel chain manufacturing costs, compressing margins on fixed-price infrastructure contracts while creating three distinct pricing tiers based on heat-treatment certification levels and batch traceability documentation.
Pricing Analysis
Volume concentrates in commodity Grade 80 configurations where per-unit margins thin, while Grade 100 and specialty alloy chains capture premium positioning through strength-to-weight advantages and REACH-mandated material disclosure. Price differentiation rests on certification grade and captive heat-treatment capabilities, with magnetic particle inspection documentation commanding substantial premiums. Cost compression in standard Grade 80 tiers is intensifying because of synthetic sling substitution below ten-ton thresholds. Mining operators under TGA protocols show lowest price sensitivity due to safety-critical replacement mandates, while general construction firms exhibit highest sensitivity to unit economics.
Supply Chain Analysis
Container freight rates from Asian manufacturing hubs to North Sea offshore wind sites and Australian mining corridors directly input into landed cost calculations for Grade 100 assemblies. Production concentrates in Germany, China, and the United States, with Ruhr corridor forges and Yangtze River Delta mills anchoring European and Asian supply respectively. Raw material feeds from nickel mines in Indonesia, chromium from South Africa, and domestic alloy scrap recycling operations. Single-source vulnerability around magnetic particle inspection technician certification creates bottleneck risk. Distribution runs through OEM direct contracts for major infrastructure projects and rental fleet operators for construction mobility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as players pursue captive heat-treatment furnace control to guarantee Grade 100 consistency and accelerate dual-source qualification timelines with major contractors.
For Market Incumbents: Extend heat-treatment capacity in Germany's Ruhr corridor and Australia's Perth basin to defend against emerging Asian scale producers. Secure parallel supplier validation status with US infrastructure contractors before tender windows compress. Reinforce batch traceability systems to meet REACH SCIP database obligations. For New Entrants and Emerging Players: OSHA quarterly inspection mandates in the United States open a window for certified inspection service bundling alongside chain supply. Target RFID-embedded chain digitization for logistics providers seeking predictive replacement software. Penetrate Indian Dedicated Freight Corridor projects through BIS-certified Grade 80 volume plays. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap European forges with captive furnace control and existing KBA inspection relationships. Long-term viability hinges on regulatory compliance automation rather than commodity volume. Watch magnetic particle inspection technician wage inflation as the inflection signal for automation investment urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Heat-Treatment Capacity Expansion | Guarantees Grade 100 consistency for North Sea offshore wind contractors under REACH protocols. |
| RFID-Enabled Chain Digitization | Opens predictive replacement software revenue with logistics providers and mining operators. |
| Dual-Source Qualification Acceleration | Reduces 18-month contractor validation timelines through pre-certified manufacturing footprints. |
| Magnetic Particle Inspection Automation | Addresses NDT technician shortages constraining testing throughput in Australian mining clusters. |
| GB Standards Certification Investment | Unlocks SAMR-compliant market access for Yangtze River Delta infrastructure procurement. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with maintenance directors at Australian mining operations, OEM procurement teams in Germany's automotive sector, aftermarket service heads at US rental fleet operators, and plant engineers at Indian infrastructure contractors. Bottom-up volume estimates from grade-level shipment data triangulated against top-down infrastructure investment projections from national development authorities.
Granularity-level modeling disaggregated demand across product grade, application environment, end-user scale, and installation type, with separate treatment of replacement cycle velocity in abrasive versus controlled conditions. CAGRs derived from regression analysis of historical procurement patterns against regulatory mandate implementation timelines. Forecast inputs included OSHA inspection compliance rates, TGA workplace safety protocol adoption curves, and offshore wind installation capacity buildouts.
The model assumes a particular technology adoption path for RFID-embedded chain traceability; alternative pathways for synthetic sling substitution in below-ten-ton lifting would alter the outlook. Forecasts reflect assumptions about nickel price stability and inspection technician availability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Pipe Jacking Machines Market
Material Handling Equipment
Robotic Palletizers Market
Material Handling Equipment
Hose Pipe Market
Material Handling Equipment
Bulk Material Handling Products and Technologies Market
Material Handling Equipment
Stacker Crane Market
Material Handling Equipment
Industrial Hoists Market
Material Handling Equipment
Europe Forklift Truck Market
Material Handling Equipment
Decoiler Machine Market
Material Handling Equipment
Bale Clamp Intensive Market
Material Handling Equipment
Dump Tubs Market
Material Handling Equipment
Cherry Picker Forklift Market
Material Handling Equipment
Hi Lift Jack Market
Material Handling Equipment
Telescopic Crane Market
Material Handling Equipment
High Pressure Grease Hose Market
Material Handling Equipment
Hydraulic Hose and Fittings Market
Material Handling Equipment
Precision Ballscrews Market