
 India Crane Market | 2026-2036
India Crane Market Size, Share, and Industry Trends Forecast 2026-2036
India Crane Market Outlook
The Bureau of Indian Standards (BIS) certification mandate for lifting equipment is hardening compliance requirements across domestic manufacturing. SANY Group leverages its crawler crane specialization to anchor large infrastructure projects in western India. Escorts Ltd competes through its truck crane portfolio, while Action Construction Equipment Limited dominates the sub-20-ton mobile crane segment with localized production.
An India crane is a powered lifting machine incorporating steel-boom structures, wire rope hoists, and load-moment indicators, engineered to vertically transport materials and personnel across construction sites, factories, and ports. Tower cranes command the highest deployment volumes in urban high-rise construction, while crawler cranes capture premium margins in wind energy installation. Hydraulic technology leads the installed base, though electric drives are gaining share in manufacturing end-use where emission norms tighten.
BIS standards, the Construction Equipment Manufacturers Association code, and state-level factory inspectorate rules collectively shape crane certification, operator licensing, and site safety protocols. The central bank's infrastructure lending norms and the PLI scheme for construction equipment further steer capital allocation toward domestic assembly capacity. Stakeholders must monitor state-level building codes and renewable energy tender designs to anticipate capacity mix shifts.
Market Dynamics
Metro rail construction in Mumbai and Bengaluru is concentrating tower crane demand in urban corridors, while BIS certification mandates are compressing the supplier base by disqualifying non-compliant equipment. This dual pressure of infrastructure acceleration and regulatory hardening defines current market mechanics.
Growth Catalysts
- Industrial Corridor Investments:Dedicated freight corridors and manufacturing zones in Maharashtra and Gujarat are sustaining crawler crane deployment for heavy foundation work.
- PLI Scheme for Construction Equipment:The central government's production-linked incentive scheme is steering capital toward domestic assembly capacity, reducing import dependency for critical crane subsystems.
- Wind Energy Installation:Renewable energy tenders specifying taller turbine hubs are pulling specialized high-capacity crawler cranes into western and southern states.
Market Restraints
- Steel Price Volatility:Fluctuations in domestic hot-rolled coil prices directly compress crane manufacturer margins, particularly for tower crane fabricators with fixed-price construction contracts.
- BIS Compliance Costs:The Bureau of Indian Standards certification timeline and testing fees create a structural barrier for smaller fabricators seeking to enter the formal market.
- Used Equipment Imports:Influx of depreciated Japanese and European crawler cranes through secondary channels undercuts new domestic sales in price-sensitive project segments.
Strategic Opportunities
- Electric Drive Conversion:Manufacturing end-use facilities in Tamil Nadu and Karnataka are specifying electric-hybrid cranes to meet state-level emission enforcement, creating first-mover advantage for domestic assemblers.
- Rental Fleet Expansion:Project developers are shifting from ownership to operational lease models, opening channel innovation for fleet operators with maintenance capabilities.
- Smart City Vertical Construction:Urban renewal missions in tier-2 cities are generating demand for compact tower crane configurations suited to constrained site footprints.
Industry Challenges
- Certified Operator Scarcity:State factory inspectorate licensing backlogs and inadequate training infrastructure constrain crane utilization rates even when equipment is available.
- Load Moment Indicator Integration:Retrofitting legacy crane fleets with anti-collision and overload systems required by revised BIS safety codes demands technical execution without standardized retrofit protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Crane Market |
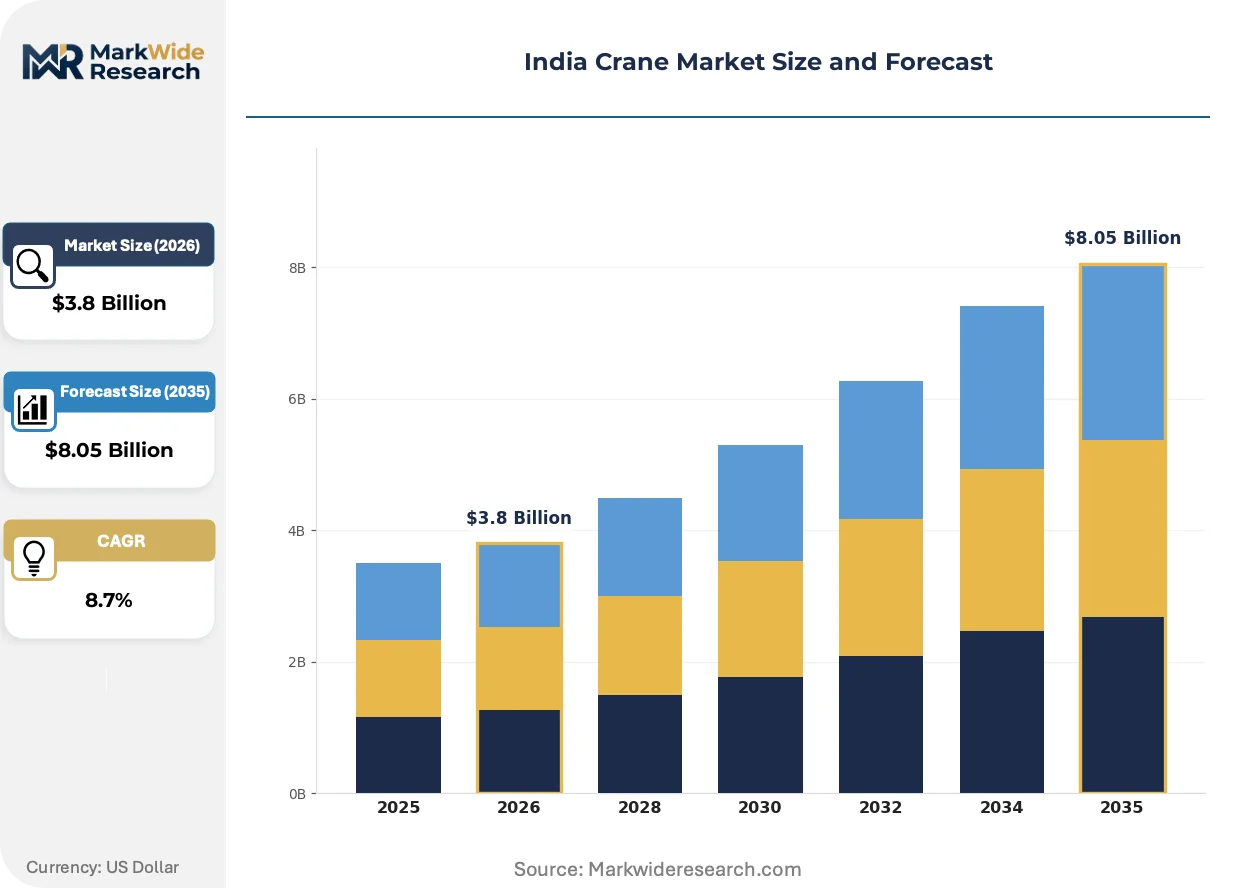
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Truck Crane, Tower Crane, Overhead Crane, Crawler Crane End User: Construction, Manufacturing, Shipping, Mining Technology: Hydraulic, Electric, Pneumatic, Manual Capacity: Below 10 Tons, 10-20 Tons, 20-30 Tons, Above 30 Tons |
| Companies Covered | SANY Group, Escorts Ltd, Action Construction Equipment Limited, Palfinger India, Tata Hitachi Construction Machinery, Liebherr Group, Konecranes, XCMG India, Kobelco Construction Equipment India, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Crane Market Strategic Shifts
Telematics integration and electrification are compressing the traditional divide between equipment manufacturing and fleet management services. These shifts are redrawing competitive boundaries around data capabilities rather than mechanical specifications alone.
Telematics platforms are unifying crane operational data with project management systems, enabling real-time load tracking and predictive maintenance scheduling. Large infrastructure contractors in Gujarat and Maharashtra are mandating connected equipment in tender specifications. This unifying architecture is compressing after-sales service into continuous remote monitoring contracts, displacing traditional breakdown-repair revenue models.
BIS has tightened certification protocols for lifting equipment under revised safety codes, extending compliance requirements to imported used cranes. The Construction Equipment Manufacturers Association is coordinating with state factory inspectorates to harmonize inspection intervals. Tower crane deployments in urban Maharashtra face the steepest compliance burden, driving manufacturers toward modular designs that simplify field certification.
Rental penetration is accelerating as project developers prioritize capital efficiency over equipment ownership. Fleet operators with integrated maintenance and operator provisioning are capturing share from traditional distributors in western India. This shift is most visible in Mumbai metro construction, where contractors specify full-service crane packages rather than bare equipment leases.
India Crane Market Segmentation
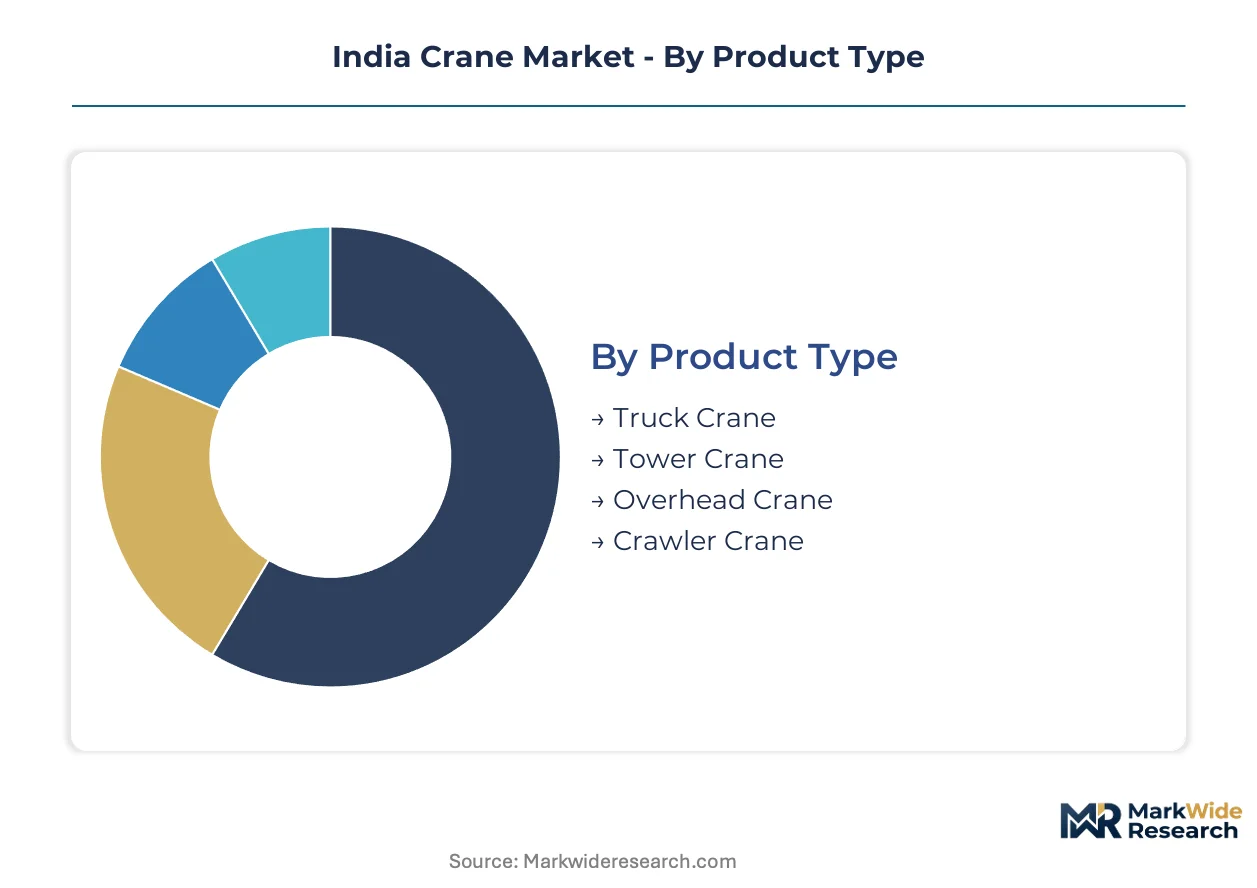
Crane procurement decisions in India diverge sharply across project scales and regulatory environments. Equipment replacement cycles vary from 8 years in high-utilization construction fleets to 15 years in intermittent manufacturing applications, creating distinct upgrade windows for each segment category.
Product Type:
Replacement urgency concentrates in urban infrastructure fleets where BIS certification deadlines are forcing premature retirements of non-compliant legacy equipment.
- Tower Crane:Stationary vertical-lifting systems with lattice or telescopic masts engineered for high-rise construction. Metro rail projects in Mumbai and Bengaluru are pulling tower crane volumes upward as contractors deploy luffing-jib configurations for constrained urban sites.
- Crawler Crane:Tracked undercarriage systems delivering superior load distribution for heavy foundation work. Wind energy installation tenders in Gujarat and Maharashtra specify crawler cranes for turbine hub heights exceeding 120 meters, anchoring premium demand in western states.
- Truck Crane:Road-mobile telescopic boom systems mounted on commercial chassis. Escorts Ltd dominates this segment through localized production serving highway and bridge contractors across the Golden Quadrilateral corridor.
- Overhead Crane:Bridge-mounted systems traversing fixed runways in industrial facilities. Steel plants in Odisha and Jharkhand sustain overhead crane replacement cycles tied to blast furnace refurbishment schedules.
Tower Crane sits at the top of the volume ranking, with Crawler Crane climbing the fastest.
End User:
Capital allocation patterns separate ownership-intensive sectors from emerging rental penetration zones.
- Construction:Primary demand anchor encompassing residential, commercial, and infrastructure verticals. Project developers in Maharashtra and Gujarat are shifting from equipment ownership to operational lease models, compressing traditional distributor margins.
- Manufacturing:Factory-integrated lifting systems serving automotive and process industries. Tamil Nadu and Karnataka facilities are specifying electric-hybrid cranes to comply with state-level emission enforcement.
- Shipping:Port cargo handling equipment including ship-to-shore and yard cranes. Jawaharlal Nehru Port Trust and Mundra Port expansions are sustaining mobile harbor crane procurement.
- Mining:Heavy-lift systems for ore extraction and processing operations. Iron ore belt operations in Chhattisgarh drive crawler crane demand for shovel maintenance and crusher relocation.
Construction commands absolute volume leadership, while Manufacturing expands most quickly on electrification mandates.
Technology:
Technology selection tracks energy cost differentials and maintenance infrastructure availability across state boundaries.
- Hydraulic:Fluid-power actuation systems dominating the installed base through superior power density. Construction contractors across tier-2 cities prefer hydraulic systems for field serviceability where electric infrastructure is sparse.
- Electric:Motor-driven systems gaining share in manufacturing end-use where grid stability supports continuous operation. Karnataka and Tamil Nadu state policies are accelerating electric crane adoption through industrial tariff incentives.
- Pneumatic:Compressed-air systems serving explosion-sensitive environments. Fertilizer and chemical plants in Gujarat deploy pneumatic cranes for hazardous zone compliance.
- Manual:Human-powered systems for low-capacity intermittent lifting. Small fabrication workshops in Punjab and Haryana sustain manual crane demand for cost-sensitive applications.
Hydraulic systems retain volume dominance, with Electric technology gaining share fastest on emission compliance pressure.
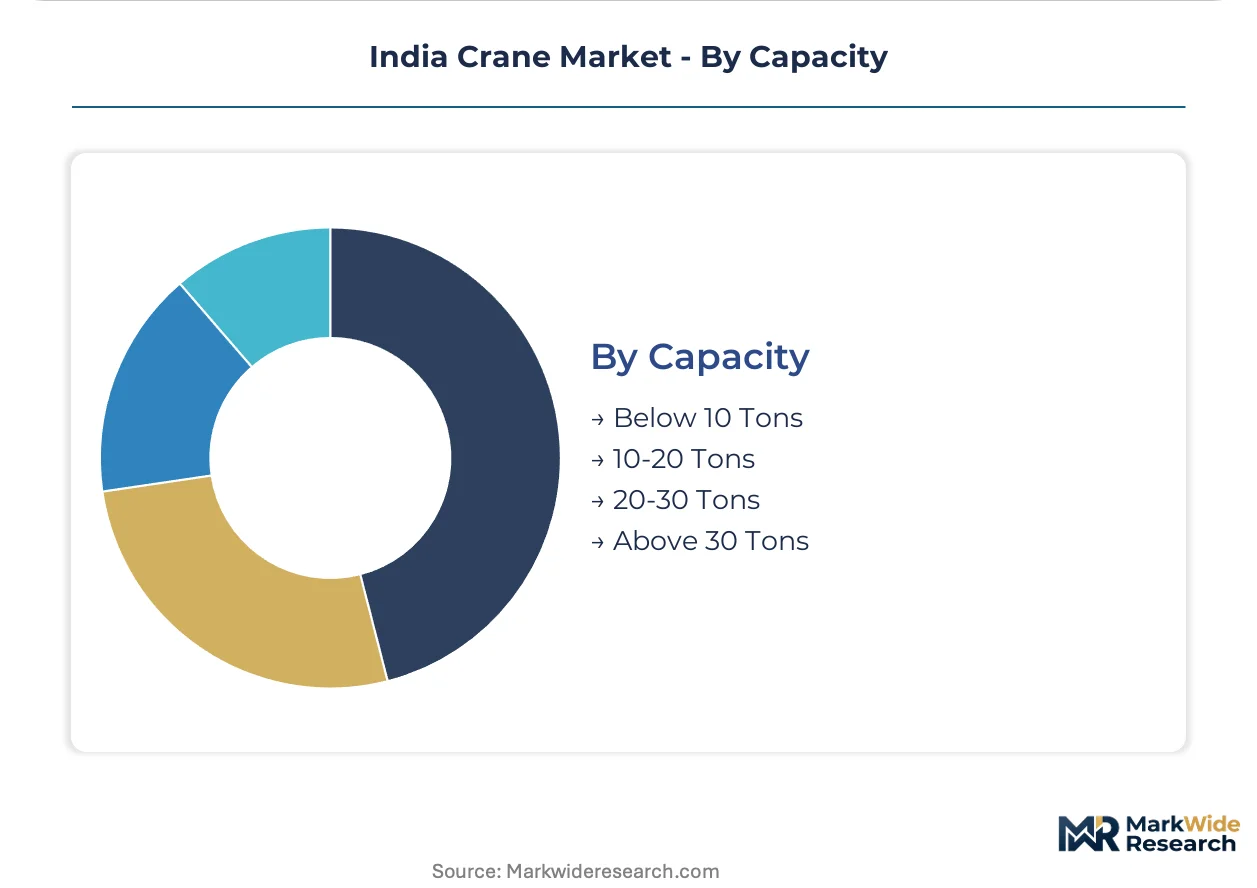
Capacity:
Capacity tier distribution mirrors project scale concentration and financing availability across state industrial corridors.
- Below 10 Tons:Compact mobile systems serving maintenance and small-scale construction. Action Construction Equipment Limited anchors this segment through sub-20-ton mobile crane production for tier-2 city contractors.
- 10-20 Tons:Mid-range systems bridging utility and commercial applications. Warehouse construction in Delhi-NCR and Hyderabad sustains steady demand for this capacity band.
- 20-30 Tons:Heavy-utility systems for industrial and infrastructure deployment. Dedicated freight corridor construction in Uttar Pradesh and Bihar pulls 20-30 ton crawler crane volumes.
- Above 30 Tons:High-capacity specialized systems for wind energy and heavy industrial projects. SANY Group leverages crawler crane specialization to capture premium margins in western India renewable energy installation.
Below 10 Tons sits at the top of the volume ranking, with Above 30 Tons climbing the fastest on wind energy tender specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's crane industry traces its modern foundations to post-independence industrialization drives in the 1950s, when state-owned steel plants and dam projects established domestic lifting equipment demand. Maharashtra and Gujarat subsequently emerged as the twin anchors of crane deployment, sustained by port modernization and chemical corridor investments. Today, state-level infrastructure spending patterns and BIS regulatory enforcement create distinct regional demand cycles across India's industrial geography.
Maharashtra
Mumbai metro construction and the Mumbai-Ahmedabad high-speed rail corridor are concentrating tower crane demand in the Mumbai-Pune industrial belt. The state's factory inspectorate maintains stringent load-moment indicator compliance timelines, accelerating fleet replacement cycles. Pune's automotive manufacturing cluster is specifying electric-hybrid overhead cranes to meet Maharashtra Pollution Control Board emission directives for industrial zones.
Gujarat
Mundra Port and Dahej Petrochemical Complex expansions are sustaining crawler crane deployment for heavy foundation and wind turbine installation work. The Gujarat Maritime Board mandates BIS-certified lifting equipment for all port cargo operations, disqualifying non-compliant used imports. The Sanand-Vithalapur industrial corridor is attracting crane rental fleet operators serving the Tata Motors and Suzuki manufacturing facilities.
Karnataka
Bengaluru metro Phase 2 construction and the upcoming suburban rail project are pulling compact tower crane volumes for constrained urban sites. The Karnataka State Pollution Control Board's industrial emission norms are accelerating electric crane adoption in the Peenya and Bommasandra manufacturing belts. Mysuru's emerging aerospace cluster is generating specialized overhead crane demand for precision assembly operations.
Tamil Nadu
Chennai's port modernization and the Ennore-Kattupalli industrial corridor are driving mobile harbor crane procurement. The Tamil Nadu Energy Development Agency's renewable energy tenders specifying 140-meter hub heights are pulling high-capacity crawler cranes to the Tirunelveli and Coimbatore wind zones. Sriperumbudur's electronics manufacturing cluster is specifying clean-room overhead cranes for semiconductor assembly lines.
Telangana
Hyderabad metro expansion and the Pharma City project near Mucherla are generating tower crane demand for vertical construction and process facility installation. The Telangana State Industrial Infrastructure Corporation's integrated manufacturing zones mandate BIS-compliant lifting equipment for plot allotments. The Genome Valley life sciences cluster is deploying specialized cranes for bioreactor installation and maintenance operations.
India Crane Market Competitive Environment
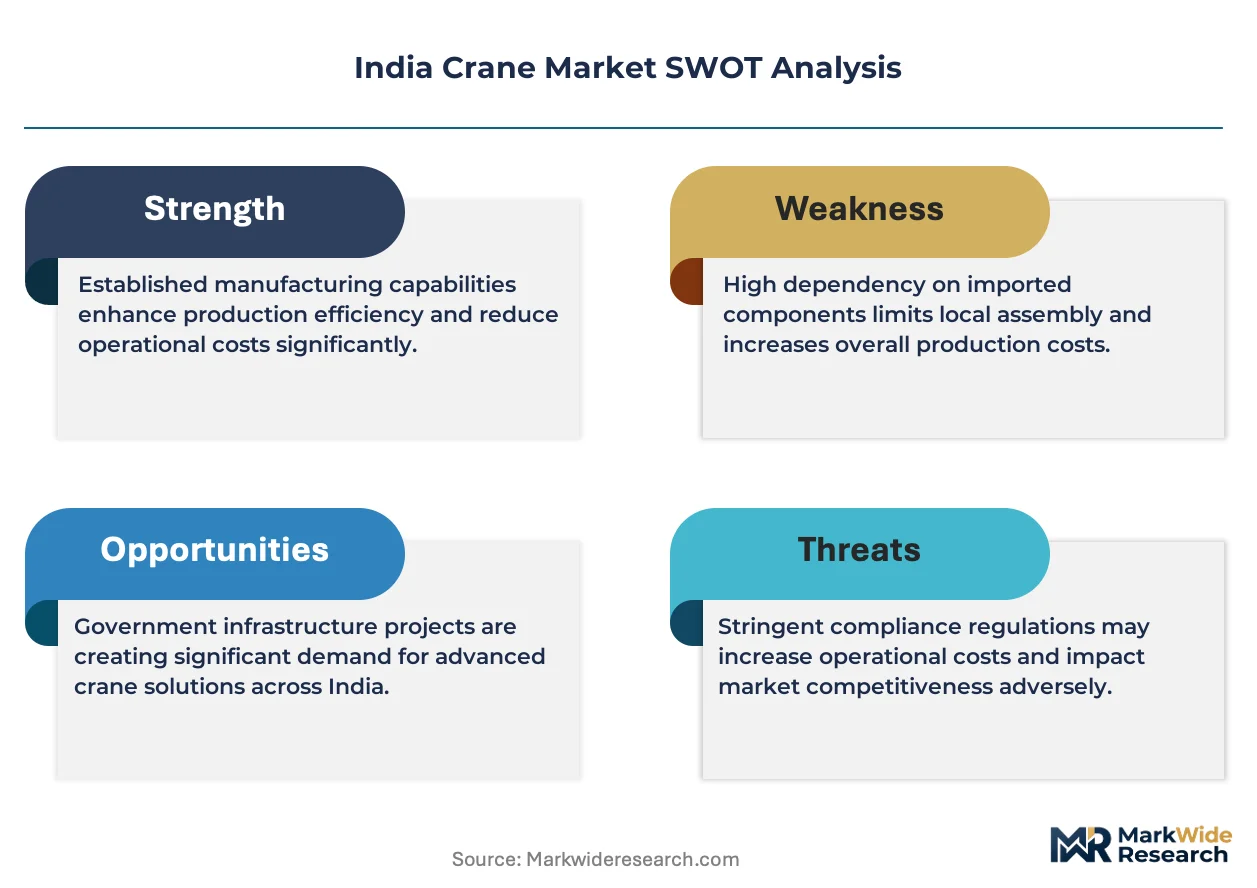
Capital-heavy domestic fabricators compete with asset-light multinational assemblers across India's crane market structure. The supplier base concentrates around three strategic tiers: integrated manufacturers with captive component production, licensed assemblers importing critical subsystems, and pure-play rental fleet operators. Consolidation pressure is intensifying as BIS certification timelines and testing costs compress margins for smaller fabricators. Dominant competitive moves include backward integration into boom fabrication and steel processing, alongside strategic partnerships for electric drive technology licensing.
Among China-based heavy equipment specialists, SANY Group and XCMG India exemplify the integrated manufacturing archetype with substantial crawler crane deployment in western India renewable energy projects. Escorts Ltd anchors the domestic truck crane segment through localized production serving highway contractors. Action Construction Equipment Limited occupies a distinct position in the sub-20-ton mobile crane tier, while Liebherr Group and Konecranes represent European engineering-intensive positioning in premium overhead and port crane categories. Tata Hitachi Construction Machinery and Kobelco Construction Equipment India illustrate Japanese-Indian joint venture structures combining technology transfer with regional assembly presence.
| Leading Market Players |
|---|
| SANY Group |
| Escorts Ltd |
| Action Construction Equipment Limited |
| Palfinger India |
| Tata Hitachi Construction Machinery |
| Liebherr Group |
| Konecranes |
| XCMG India |
| Kobelco Construction Equipment India |
| Others |
Value Chain & Pricing Dynamics
Wind energy EPC contractors in Gujarat and Maharashtra anchor crane procurement volumes, compressing supplier margins through consolidated tender specifications and long-term service bundling demands. This buyer concentration forces manufacturers toward project-based pricing with captive maintenance contracts rather than discrete equipment sales.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates BIS-certified crawler cranes from non-compliant used imports and bare rental units. Price differentiation hinges on certification grade and after-sales service bundling, with factory-inspectorate compliance timelines adding 15-20% cost premiums to premium tiers. Cost compression in the standard tier is intensifying because steel price volatility and BIS testing fees squeeze fabricator margins. Small tier-2 contractors exhibit highest price sensitivity, while wind energy developers prioritize uptime guarantees over acquisition cost.
Supply Chain Analysis
Steel-boom fabrication rests on hot-rolled coil supply from domestic mills in Odisha and Jharkhand, supplemented by specialized wire rope imports from Germany and South Korea. Critical subsystems including load-moment indicators and electric drive motors draw from Chinese and Japanese component suppliers. Single-source vulnerability concentrates in high-capacity crawler crane undercarriage assemblies, where limited domestic forging capacity creates import dependency. Distribution runs through manufacturer-direct sales for large infrastructure projects and rental fleet operators serving fragmented construction contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in India's crane market stems from BIS certification barriers eliminating low-cost used imports and creating premium-tier pricing power for compliant domestic fabricators.
For Market Incumbents: Acquire rental fleet operators with maintenance capabilities to capture recurring revenue streams as project developers shift from ownership to operational lease models. Escalate backward integration into boom steel processing to defend against hot-rolled coil price volatility and compress lead times for BIS certification testing. Channel control through captive service networks anchors customer retention against emerging Chinese assemblers. For New Entrants and Emerging Players: Launch via electric-hybrid crane specialization targeting Tamil Nadu and Karnataka manufacturing facilities facing state-level emission enforcement. White-space concentration sits in compact tower crane configurations for tier-2 smart city vertical construction, where constrained site footprints disqualify standard luffing-jib designs. Telematics-enabled fleet management partnerships with infrastructure contractors provide differentiated entry positioning against established distributors. For Investors and Strategic Acquirers: Domestic construction equipment conglomerates are the most active acquirer in this space, consolidating sub-20-ton mobile crane fabricators to achieve scale economies in BIS compliance testing. Long-term viability centers on rental penetration acceleration and electrification transition timing across state industrial corridors. Monitor Karnataka and Tamil Nadu state pollution control board enforcement intensity as the inflection signal for electric crane adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Processing | Captive boom fabrication reduces BIS certification lead times and insulates margins from coil price swings. |
| Electric Drive Technology Licensing | Karnataka and Tamil Nadu emission norms accelerate demand for manufacturing-integrated electric-hybrid systems. |
| Rental Fleet Acquisition | Operational lease shift in Maharashtra and Gujarat construction projects transforms revenue from transactional to recurring. |
| Telematics Platform Deployment | Real-time load tracking meets Gujarat infrastructure contractor tender specifications for connected equipment. |
| BIS Certification Fast-Track Investment | Compressed testing timelines capture replacement demand from non-compliant legacy crane retirements in urban corridors. |
Study Parameters
Coverage spans Maharashtra, Gujarat, Karnataka, Tamil Nadu, and Telangana, with primary inputs from each state's industrial corridor. The approach combines interviews with maintenance directors at steel plants, procurement leads at wind energy EPC contractors, OEM crane manufacturer sales heads, and aftermarket service managers with secondary validation through BIS certification databases, Construction Equipment Manufacturers Association technical circulars, state factory inspectorate compliance schedules, and customs import records for used crane shipments. Bottom-up equipment deployment tracking and top-down infrastructure spending analysis triangulate market sizing.
Granularity-level modeling disaggregates volume and value across product type, end-use vertical, technology architecture, and capacity tier, with additional dimensioning by state-level regulatory enforcement intensity. CAGRs derive from regression analysis of historical deployment patterns against infrastructure tender pipelines and manufacturing capacity expansion schedules. Forecast inputs incorporate PLI scheme disbursement trajectories for construction equipment and state renewable energy tender specifications for hub height requirements.
Several conditions sit outside the modeled scope, including abrupt steel price shocks exceeding historical volatility bands, unscheduled BIS certification protocol revisions, and geopolitical disruptions to Chinese component supply chains. Forecasts reflect assumptions about continued state-level emission enforcement and infrastructure lending norm stability. A small set of named triggers warrants ongoing watch: Maharashtra Pollution Control Board electric crane mandates, Gujarat Maritime Board port equipment compliance deadlines, and central bank infrastructure credit allocation shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Asia-Pacific Heavy Construction Equipment Market
Construction Equipment
Global Asphalt Crushers Market
Construction Equipment
India Construction Equipment Rental Market
Construction Equipment
Escalator Cleaning Machine Market
Construction Equipment
Hydraulic Shearing Machine Market
Construction Equipment
3-Wheel Sit-Down Counterbalance Forklift Market
Construction Equipment
Excavator Wheels Market
Construction Equipment
Multi Attachment Loaders Market
Construction Equipment
Street Washer Machine Market
Construction Equipment
Global Hydraulic Hammer Market
Construction Equipment
Middle East Flexible Concrete Vibrator Market
Construction Equipment
Tray Dryers Market
Construction Equipment
Backhoe Loaders Market
Construction Equipment
Backhoes Market
Construction Equipment
Crane Pumps Market
Construction Equipment
Gear Grinding Machine Market