
 Outdoor Sound Barrier Market | 2026-2036
Outdoor Sound Barrier Market Size, Share, and Industry Trends Forecast 2026-2036
Outdoor Sound Barrier Market Analysis
The EU Green Deal's noise-reduction mandates is hardening specifications for low-carbon acoustic materials across European infrastructure tenders. Saint-Gobain leverages its mineral wool expertise to anchor supply relationships with French and German rail operators. Rockwool International sustains competitive positioning through backward integration into basalt sourcing, while Owens Corning specializes in composite barrier systems for North American highway applications.
An outdoor sound barrier is an engineered noise-attenuation structure, typically constructed from concrete, metal, PVC, or composite assemblies with surface densities of 10-25 kg/m² and sound reduction indices exceeding 25 dB, designed to intercept and absorb acoustic energy from transportation corridors, industrial facilities, and construction sites. Concrete dominates transportation and highway installations due to structural longevity and fire resistance, while PVC and composite variants capture retrofit and embedded applications where weight constraints govern specification. Metal barriers compete in railway corridors demanding electromagnetic compatibility and vandal resistance, with municipalities and contractors driving procurement through design-build contracts that bundle installation with long-term acoustic performance guarantees.
The US Federal Highway Administration's noise standards, the EU's Environmental Noise Directive, and China's GB/T acoustic barrier standards collectively shape product certification, material recyclability requirements, and cross-border market access for manufacturers. EPA and EMA-aligned testing protocols for outdoor sound barriers are diverging on end-of-life criteria, forcing suppliers to maintain parallel certification tracks. Stakeholders must monitor how emerging carbon-border adjustments and green public procurement rules will restructure competitive advantage between regional and multinational suppliers.
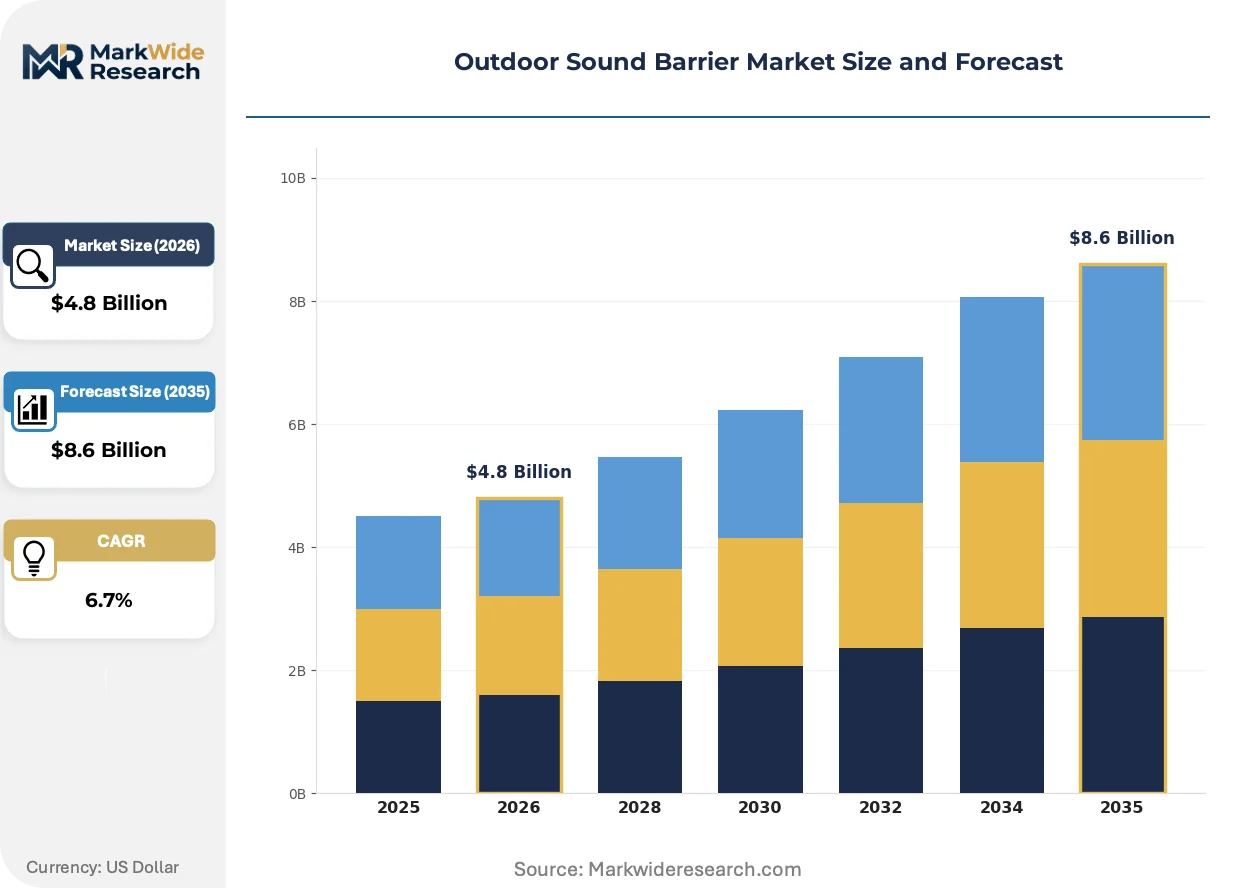
Market Dynamics
EU Green Deal noise-reduction mandates are hardening specifications for low-carbon acoustic materials across European infrastructure tenders. This regulatory pressure is accelerating material substitution toward recycled-content products while compressing certification timelines for suppliers.
Growth Catalysts
- EU Environmental Noise Directive:Mandates systematic noise mapping and action planning in urban agglomerations above 100,000 inhabitants, forcing municipal procurement of certified barrier systems.
- Basalt fiber composites:Railway operators in Germany and France specify these lightweight, fire-resistant materials for elevated corridor installations where structural load limits constrain concrete deployment.
- Urban corridor densification:Highway agencies across China, India, and the United States expand procurement of absorptive barrier systems to mitigate traffic noise in residential-adjacent rights-of-way.
Market Restraints
- Petroleum-based resin volatility:Composite barrier manufacturers face margin compression from epoxy and polyester price swings tied to crude oil benchmarks.
- Basalt feedstock concentration:Premium volcanic rock deposits cluster in specific volcanic regions, creating geographic supply vulnerability for mineral wool producers.
- Concrete's embodied carbon:Portland cement's high carbon intensity exposes suppliers to carbon-border adjustment risks under emerging EU CBAM scope expansion.
Strategic Opportunities
- India's Bharatmala corridor program:National highway expansion creates demand for cost-optimized absorptive barriers in tier-2 and tier-3 urban corridors.
- Modular retrofit kits:PVC and composite panel systems capture embedded-application growth where existing infrastructure cannot support structural concrete loads.
- Green public procurement rules:Recycled-content mandates in French and German tenders favor suppliers with verified circular material flows and EPD-certified products.
Industry Challenges
- Acoustic engineer scarcity:Specialized expertise in finite-element noise modeling and site-specific barrier design limits project execution capacity for design-build contractors.
- Parallel certification tracks:Diverging EPA and EMA-aligned testing protocols for end-of-life criteria force manufacturers to maintain redundant laboratory relationships.
- Legacy steel barrier electromagnetic compatibility:Railway electrification projects require expensive retrofitting of existing metal installations to prevent signal interference.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outdoor Sound Barrier Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PVC, Concrete, Wood, Metal Application: Transportation, Highway, Railway, Industrial End User: Municipalities, Contractors, Developers, Homeowners Installation Method: Pre-fabricated, Custom-built, Embedded, Retrofitted |
| Companies Covered | Saint-Gobain, IAC Acoustics, Durisol, Echo Barrier, Rockwool International, Knauf Insulation, Owens Corning, Kinetics Noise Control, Fort Miller Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outdoor Sound Barrier Market Emerging Trajectories
Material science advances and procurement model evolution are restructuring competitive advantage in outdoor sound barrier supply. Three developments warrant particular attention from stakeholders monitoring specification trends and contract structures.
Photocatalytic surface coatings are integrating titanium dioxide layers that degrade airborne pollutants when activated by UV radiation. Dutch and Belgian highway authorities now specify these self-cleaning finishes for urban tunnel portals and high-visibility installations. The technology is integrating air-quality co-benefits into barrier procurement criteria, compressing pure acoustic-performance bidding.
REACH restrictions on persistent organic pollutants are tightening flame-retardant chemistries in polymer-based barriers. Manufacturers reformulate PVC and composite formulations to exclude halogenated compounds while maintaining Class A fire ratings. German KBA rail certification protocols now require third-party verification of non-halogenated systems, creating compliance differentiation between prepared and unprepared suppliers.
Design-build-operate contracts are displacing traditional lump-sum procurement in North American highway projects. State DOTs bundle 20-year acoustic performance guarantees with installation, transferring operational risk to contractors. Texas and California corridor projects exemplify this shift, with bidders pricing long-term maintenance reserves into upfront quotes and selecting materials for durability rather than first cost.
Outdoor Sound Barrier Market Segmentation
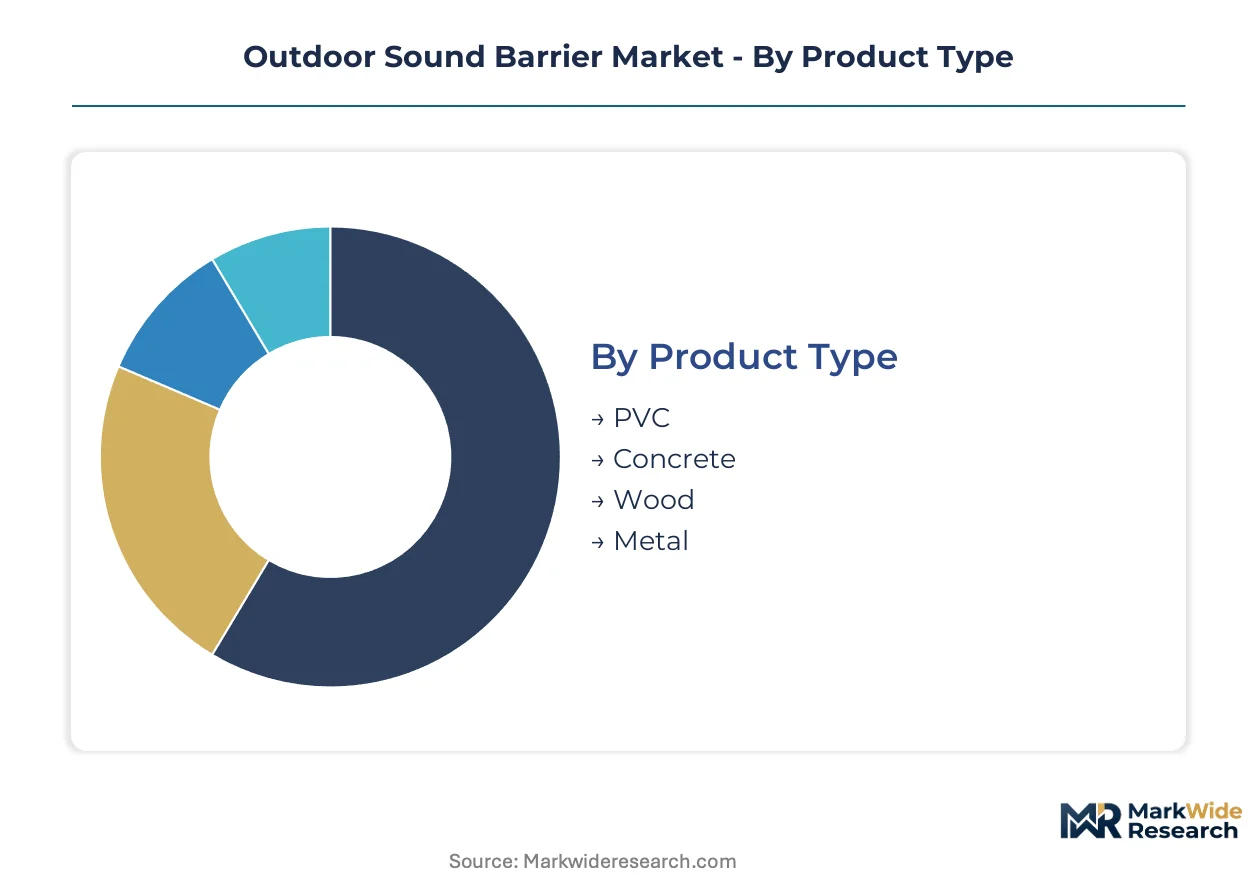
Sound barrier procurement diverges sharply across material chemistry, installation physics, and contracting structures. Specification choices cascade through acoustic performance guarantees, structural load requirements, and end-of-life compliance obligations that reshape supplier competitive advantage.
Product Type:
Customization intensity varies from commodity concrete pours to engineered composite formulations with site-specific acoustic tuning.
- Concrete:Portland cement-based systems with surface densities of 10-25 kg/m² deliver structural longevity exceeding 50 years in highway installations. German and French transportation agencies specify precast concrete for fire-rated corridors where structural integrity governs procurement above first cost.
- PVC:Polyvinyl chloride panels with integrated absorptive cavities capture retrofit applications where weight constraints prohibit masonry. Indian highway expansion under the Bharatmala program sources PVC systems for tier-2 urban corridors with limited foundation capacity.
- Metal:Galvanized steel and aluminum assemblies serve railway electrification projects demanding electromagnetic compatibility.
- Wood:Timber-based barriers with pressure-treated durability ratings satisfy aesthetic mandates in residential-adjacent installations.
Leading the category by volume: Concrete. Growing fastest: PVC.
Application:
End-use physics dictate material selection through acoustic frequency profiles, fire exposure risk, and structural load constraints.
- Transportation:Multi-modal corridor barriers attenuate road, rail, and airport noise through composite assemblies tuned to 100-5000 Hz frequency ranges. US Federal Highway Administration noise standards mandate minimum 25 dB reduction indices for federal-aid projects.
- Highway:Ground-level installations dominate procurement volume with absorptive-facing designs that mitigate tire-pavement noise reflection. China's GB/T acoustic barrier standards shape certification requirements for urban expressway tenders.
- Railway:Elevated corridor systems face stringent electromagnetic compatibility and fire-resistance specifications under German KBA protocols.
- Industrial:Manufacturing facility enclosures manage occupational noise exposure while containing process emissions within property boundaries.
Highway commands installed base. Railway installations are expanding most quickly.
End User:
Contracting sophistication separates municipal design-build tenders from developer-driven specification minimums.
- Municipalities:City and state agencies bundle 20-year acoustic performance guarantees with installation contracts, transferring operational risk to contractors. Texas and California DOT corridor projects exemplify this procurement evolution.
- Contractors:Design-build firms maintain parallel certification tracks for EPA and EMA-aligned testing protocols, pricing compliance redundancy into bids.
- Developers:Private infrastructure projects prioritize first-cost optimization over lifecycle durability in emerging market corridors.
- Homeowners:Residential retrofit demand concentrates in noise-impacted properties adjacent to transportation rights-of-way.
Municipalities drive specification standards. Contractors capture margin through risk-bearing contract structures.
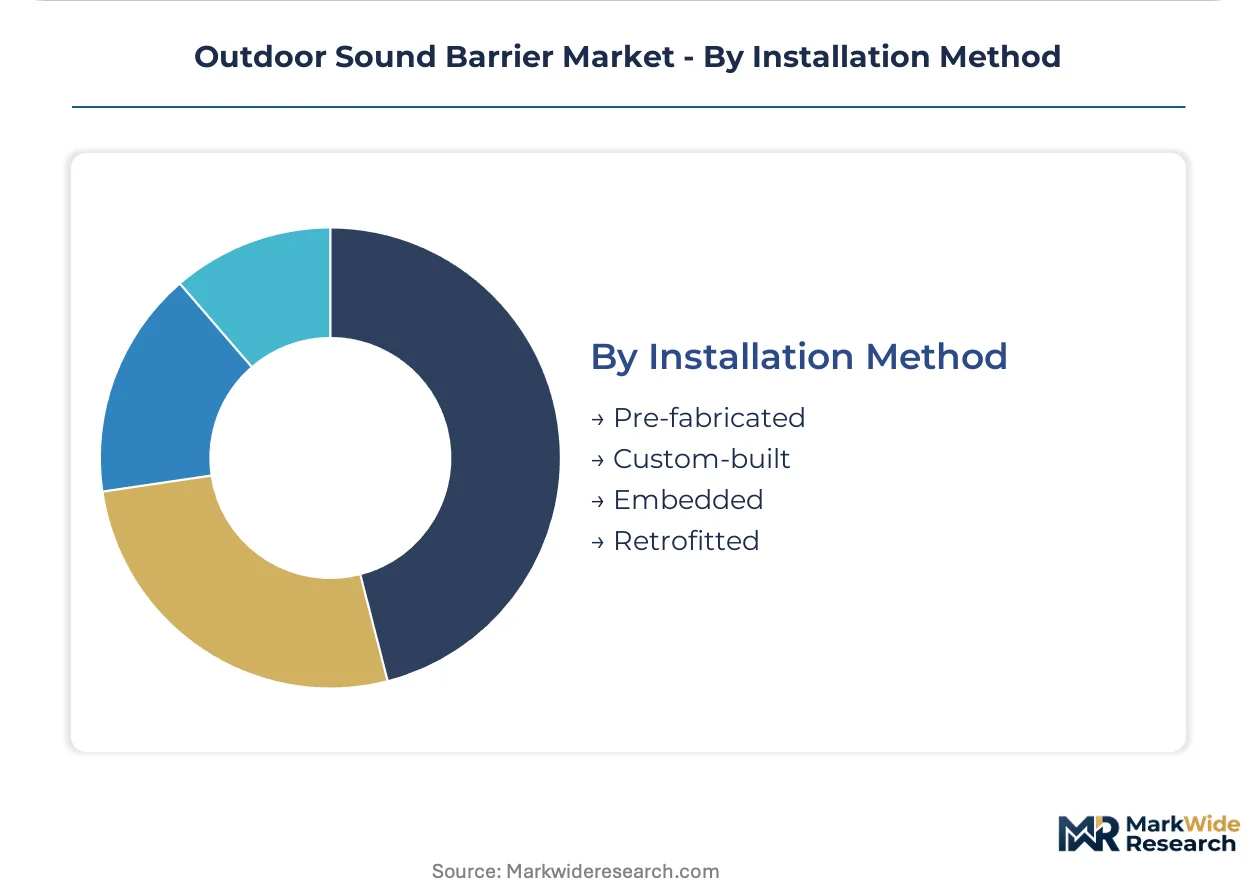
Installation Method:
Site constraints and existing infrastructure condition determine fabrication approach and structural integration depth.
- Pre-fabricated:Factory-cast concrete panels and composite modules accelerate installation timelines for greenfield highway projects. Standardized dimensions enable quality control but limit acoustic customization.
- Custom-built:Cast-in-place concrete and site-fabricated metal systems accommodate non-standard geometries and foundation conditions in constrained urban corridors.
- Embedded:PVC and lightweight composite panels integrate into existing structures where structural loads prohibit independent foundations.
- Retrofitted:Surface-mounted absorptive treatments upgrade legacy barrier acoustic performance without structural replacement.
Pre-fabricated systems dominate new construction. Retrofitted solutions are gaining share fastest in mature infrastructure markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rhineland corridor cities anchor European procurement volume, with Dutch and Belgian highway authorities pioneering photocatalytic barrier specifications for urban tunnel portals.
United States
Texas and California DOT corridor projects drive design-build-operate contract adoption, bundling 20-year acoustic performance guarantees with installation. EPA noise standards and FHWA federal-aid requirements shape certification protocols. Houston and Los Angeles metro areas concentrate retrofit demand for absorptive-facing systems along residential-adjacent rights-of-way.
Germany
Railway operators specify basalt fiber composites for elevated corridor installations where structural load limits constrain concrete deployment. KBA rail certification protocols mandate third-party verification of non-halogenated flame-retardant systems. The Rhine-Ruhr and Stuttgart regions concentrate manufacturing capacity for mineral wool and precast concrete barrier systems.
China
Urban expressway expansion across tier-2 and tier-3 cities generates demand for cost-optimized absorptive barriers under GB/T acoustic barrier standards. The country's national environmental regulator enforces noise-reduction mandates in urban agglomerations. Yangtze River Delta corridor projects exemplify specification tightening for recycled-content materials.
India
The Bharatmala national highway program creates procurement volume for PVC and lightweight composite systems in foundation-constrained corridors. Central public works specifications increasingly reference acoustic performance minimums. Maharashtra and Gujarat infrastructure clusters concentrate domestic fabrication capacity for polymer-based barrier panels.
France
Rail operators anchor supply relationships with mineral wool specialists for fire-rated corridor installations. Green public procurement rules harden recycled-content mandates in national infrastructure tenders. The Paris-Saclay and Lyon corridor regions concentrate design-build contractor expertise for complex urban acoustic remediation.
Outdoor Sound Barrier Market Vendor Landscape
The competitive structure tilts toward material-specialist incumbents with backward integration into mineral feedstocks. Tier-one suppliers maintain captive basalt sourcing and precast concrete manufacturing, while tier-two fabricators compete on modular PVC and composite retrofit kits. Strategic moves concentrate on geographic expansion through design-build joint ventures and portfolio diversification into photocatalytic surface treatments.
Among European material specialists, Saint-Gobain and Rockwool International occupy positions anchored by mineral wool expertise and volcanic rock supply control. Owens Corning represents the North American composite systems archetype. These three exemplify how regional regulatory alignment—EU Green Deal mandates versus FHWA performance standards—shapes competitive positioning without requiring identical capability portfolios.
| Leading Market Players |
|---|
| Saint-Gobain |
| IAC Acoustics |
| Durisol |
| Echo Barrier |
| Rockwool International |
| Knauf Insulation |
| Owens Corning |
| Kinetics Noise Control |
| Fort Miller Group |
| Others |
Supply Flow & Price Mechanics
Backward integration into basalt sourcing anchors competitive positioning for mineral wool specialists while compressing margin exposure for composite manufacturers tethered to petroleum-based resin markets. This supply architecture concentrates pricing power with volcanic rock deposit holders in Germany and France, leaving PVC fabricators vulnerable to crude oil benchmark volatility.
Pricing Analysis
Acoustic performance guarantees anchor value-based pricing for design-build contractors bundling 20-year operational commitments. Three-tier pricing structure across premium, standard, and economy levels separates EPD-certified recycled-content systems from commodity concrete pours and foundation-constrained PVC retrofit kits. Cost compression in composite tiers is intensifying because epoxy and polyester feedstock volatility erodes fixed-quote margins. Municipal procurement teams exhibit lowest price sensitivity given risk-transfer contract structures, while tier-3 highway developers in India drive aggressive first-cost negotiation.
Supply Chain Analysis
Basalt feedstock rests on volcanic deposits concentrated in Germany, France, and select Mediterranean formations. Mineral wool production draws from these captive rock sources, while composite panel manufacturing sources epoxy resins and glass fiber from petrochemical complexes in China and the United States. Single-source vulnerability in premium volcanic rock clusters exposes European mineral wool producers to geographic concentration risk. Distribution runs through design-build contractors capturing specification influence in North American and European infrastructure tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The outdoor sound barrier market functions as a cost-of-compliance story where EU Green Deal mandates and KBA rail certification protocols erect barrier-to-entry moats favoring EPD-certified suppliers with verified circular material flows.
For Market Incumbents: Cement supply relationships with French and German rail operators through mineral wool expertise and captive basalt sourcing. Expand photocatalytic surface treatment capabilities to capture Dutch and Belgian tunnel portal specifications. Basalt deposit concentration and REACH flame-retardant reformulation timelines compress competitive response windows for unprepared rivals.
For New Entrants and Emerging Players: Direct-to-contractor digital specification platforms offer low-friction entry into modular retrofit kit segments where embedded-application growth outpaces greenfield concrete deployment. Target India's Bharatmala corridor program for PVC and lightweight composite penetration in foundation-constrained tier-2 urban markets. Lead with cost-optimized absorptive barrier systems priced below European EPD-certified tiers.
For Investors and Strategic Acquirers: Exit pathways concentrate in design-build joint ventures and strategic acquisitions by construction conglomerates seeking acoustic engineering capabilities. Long-term viability hinges on carbon-border adjustment preparedness and recycled-content verification infrastructure. Watch EU CBAM scope expansion into construction materials as the inflection signal for portfolio rebalancing toward low-carbon mineral wool assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Basalt Sourcing | Captive volcanic rock supply secures cost position for German and French rail corridor contracts. |
| Photocatalytic Surface Treatment Development | Titanium dioxide coating capabilities unlock Dutch and Belgian urban tunnel portal specifications. |
| EPD Certification Investment | Environmental product declaration verification enables bidding under French and German green procurement rules. |
| Design-Build Joint Venture Formation | Local contractor partnerships accelerate access to Texas and California DOT bundled performance contracts. |
| Modular Retrofit Kit Expansion | Lightweight PVC and composite systems capture embedded-application growth in foundation-constrained corridors. |
Methodological Framework
Document review covered EU Environmental Noise Directive implementation reports, FHWA noise standard technical advisories, and KBA rail certification protocols, complemented by interviews with highway agency procurement officers, acoustic engineering consultants, design-build contractors, and mineral wool plant managers. Secondary validation drew from customs trade data, SEC filings of listed building materials suppliers, and infrastructure tender databases. Bottom-up project pipeline analysis and top-down materials consumption estimates were triangulated to establish market sizing.
Historical contract award patterns were cross-referenced against panel input from transportation agency planners and barrier system specifiers. Segmentation modeling covered material chemistry, installation physics, application frequency profiles, and regional regulatory clusters. CAGRs were derived from weighted average of project pipeline visibility and materials demand trajectories across the analysis window. Basalt fiber composite adoption curves and recycled-content mandate enforcement timelines served as industry-specific forecast inputs.
The model holds under steady regulatory enforcement of EU Green Deal mandates and FHWA federal-aid requirements; deviation in carbon-border adjustment scope expansion or REACH flame-retardant restriction timing would shift competitive advantage between mineral wool and polymer-based suppliers. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Engineering
Gas Scrubber Market
Environmental Engineering
Dust Control Systems Market
Environmental Engineering
Fume Hoods Market
Environmental Engineering
Aerobic Treatment Units Market
Environmental Engineering
Global Rainwater Harvesting System Market
Environmental Engineering
Rainwater Harvesting Market
Environmental Engineering
Tunnel Ventilation and Environmental Monitoring Systems Market
Environmental Engineering
Outdoor Noise Barrier Market
Environmental Engineering
Global Built and Natural Environment Consulting Market
Environmental Engineering
Wet Scrubber Market
Environmental Engineering
Secondary Water and Wastewater Treatment Equipment Market
Environmental Engineering
North America Rainwater Harvesting Market
Environmental Engineering
Septic Tanks Market
Environmental Engineering
Silt Curtain Market