
 Sweden Construction Equipment Market | 2026-2036
Sweden Construction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Construction Equipment Market Insights
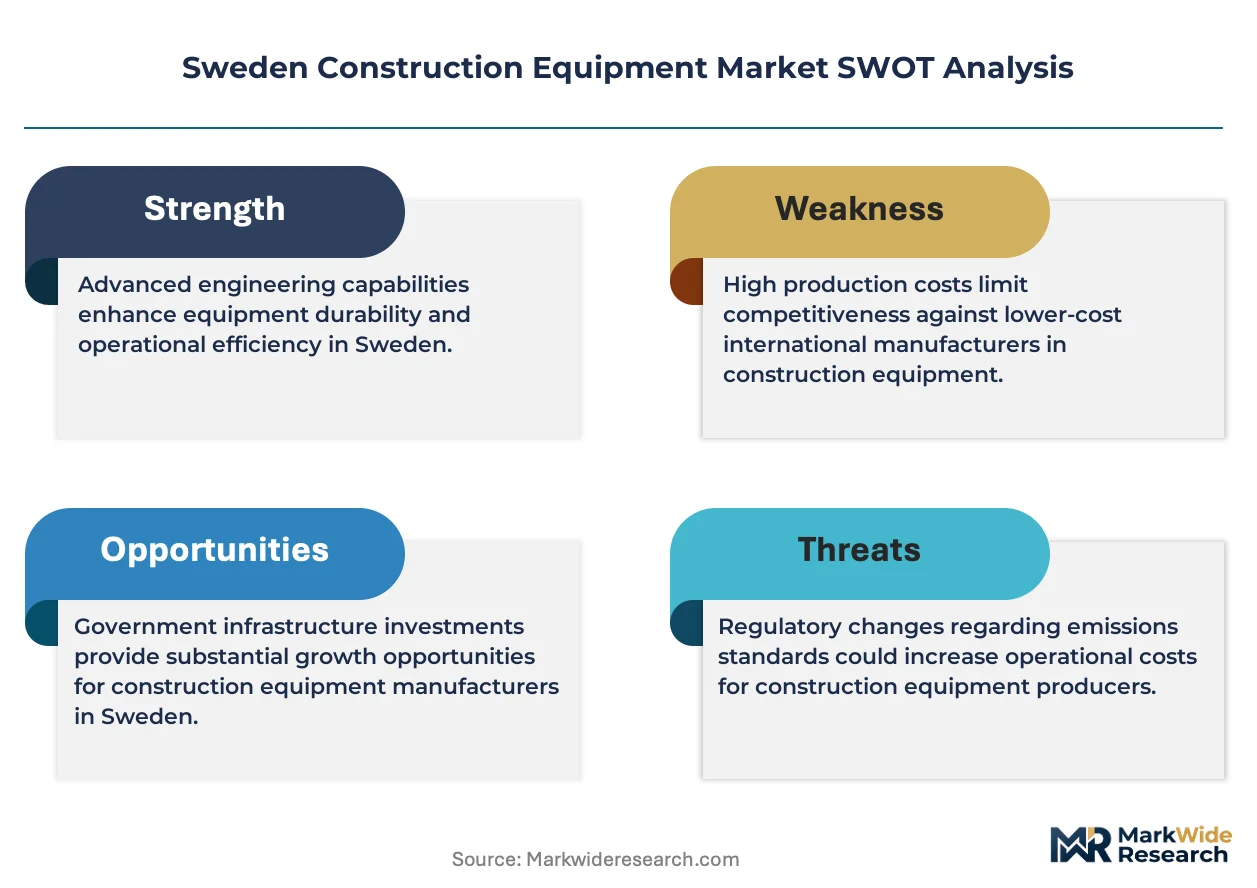
A widening capability gap in battery-electric drivetrain integration is rotating competitive advantage toward OEMs with captive R&D in electromobility. Volvo Construction Equipment leverages its Gothenburg engineering base to sustain prototype-to-production cycles for mid-size excavators. Caterpillar competes through aftermarket parts density and dealer coverage across Norrland mining zones. Liebherr anchors crane demand in Stockholm's high-rise residential segment through specialized lattice-boom configurations.
Construction equipment encompasses earthmoving, lifting, and material-handling machinery engineered to hydraulic pressure ratings exceeding 350 bar and designed for repetitive load cycles in civil engineering and resource extraction. Excavators dominate replacement demand as contractors phase out Tier 3 diesel units ahead of municipal tender requirements. Electric technology is capturing the fastest equipment financing allocations, though diesel variants still occupy the bulk of rental fleet hours in remote county projects. Telematics integration is deepening across loaders deployed in commercial site logistics, generating usage-data revenue streams for fleet managers.
The Swedish Transport Administration imposes progressive emissions thresholds on infrastructure tenders, while the Swedish Work Environment Authority enforces operator cabin ergonomics and noise exposure limits that shape product certification requirements. The EU F-Gas Regulation and national carbon-reduction commitments are compressing the residual value horizon for conventional diesel equipment. Stakeholders must calibrate fleet turnover timing against the uncertain pace of charging infrastructure rollout at dispersed construction sites.
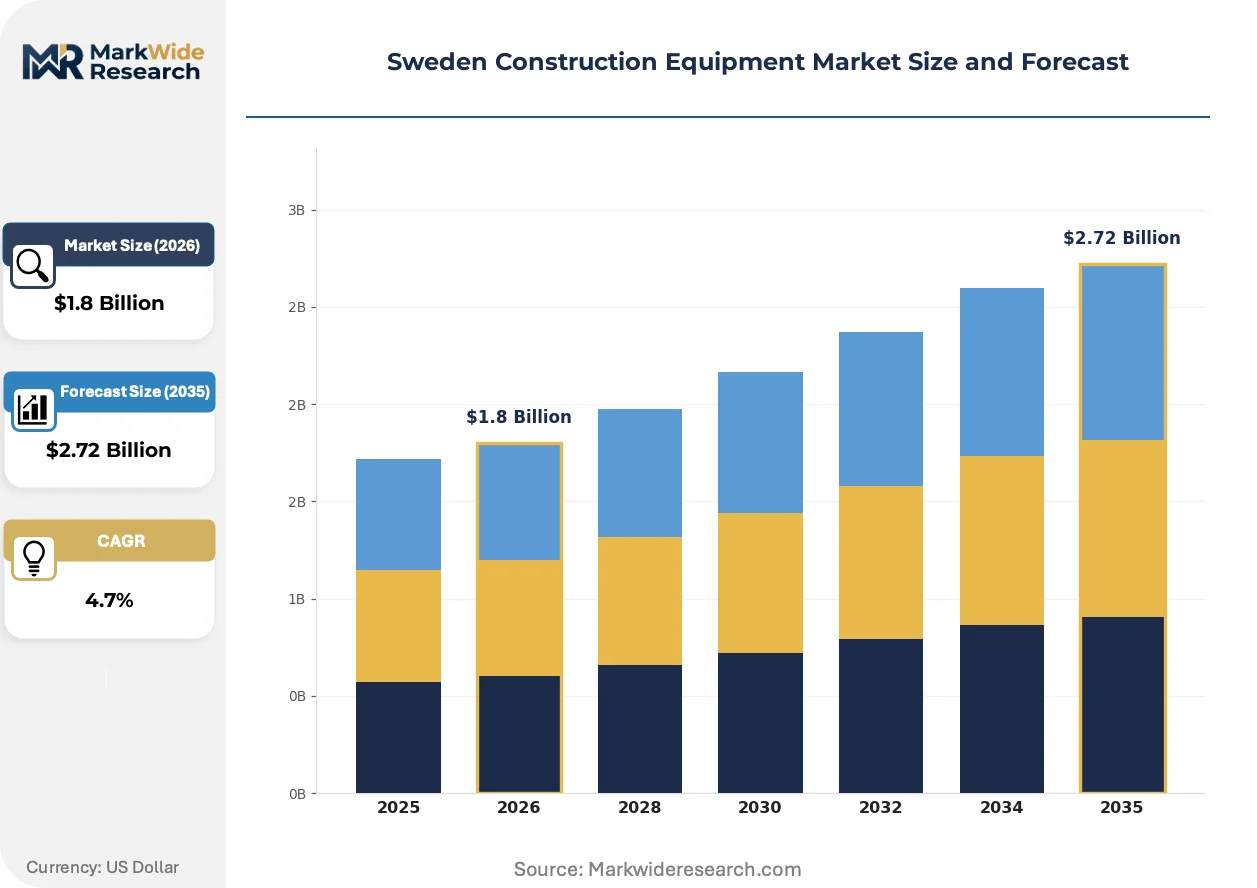
Market Dynamics
The Swedish Transport Administration's emissions benchmarks for public infrastructure contracts are compressing fleet turnover timelines and redirecting capital allocation toward electrified platforms across Greater Stockholm and Gothenburg corridors.
Growth Catalysts
- EU F-Gas Regulation:Phase-down mandates for fluorinated greenhouse gases in mobile machinery are accelerating replacement demand for climate-controlled operator cabins and HVAC systems in earthmoving equipment.
- Railway corridor densification:The Stockholm-Gothenburg high-capacity rail expansion is extending equipment utilization hours for tunnel-boring and track-laying machinery through multi-year project visibility.
- Battery-electric drivetrains:Advancements in 400-volt architectures and thermal management are enabling 8-hour operational cycles for mid-size excavators in urban demolition and foundation work.
Market Restraints
- Lithium-ion cell supply concentration:Dependence on East Asian cathode and cell manufacturing creates input cost volatility and extended lead times for battery pack assembly in Nordic assembly plants.
- Charging infrastructure dispersion:The Swedish Transport Administration's public works sites in Norrland counties lack grid capacity for high-power charging, constraining electric machine deployment to tethered or battery-swap configurations.
- Residual value compression:The EU Green Deal's carbon-border adjustments and national fossil-fuel phase-out commitments are eroding secondary market liquidity for Tier 3 diesel units ahead of physical obsolescence.
Strategic Opportunities
- Telematics-enabled usage billing:Construction fleet managers in Stockholm's commercial site logistics segment are adopting hour-based subscription models for wheel loaders, creating recurring revenue streams independent of unit sales.
- Gothenburg electrification cluster:Proximity to automotive battery R&D facilities and port hydrogen infrastructure positions western Sweden as a testbed for fuel-cell range extenders in heavy crawler cranes.
- Swedish Work Environment Authority ergonomic mandates:Operator cabin vibration and noise exposure limits are creating premium pricing power for OEMs with active suspension seats and electric-hydraulic hybrid actuation.
Industry Challenges
- High-voltage technician scarcity:The transition to 800-volt battery architectures requires certified electricians for field service, and Swedish vocational programs are not yet producing sufficient qualified personnel for dispersed construction sites.
- CE marking timeline compression:The EU Machinery Directive's revised conformity assessment procedures for autonomous safety systems are extending prototype-to-homologation cycles for semi-automated excavators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Construction Equipment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Loaders, Cranes, Bulldozers Application: Residential, Commercial, Infrastructure, Industrial End User: Contractors, Builders, Government, Mining Technology: Telematics, Autonomous, Electric, Diesel |
| Companies Covered | Volvo Construction Equipment, Caterpillar, Komatsu, Liebherr, Sandvik AB, JCB, Hitachi Construction Machinery, Kobelco, Husqvarna Construction, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Construction Equipment Market Trends and Innovations
Electrification, digitalization, and circularity mandates are restructuring equipment procurement criteria across Swedish infrastructure and urban development verticals.
Battery-electric drivetrain development is bifurcating the product roadmap for mid-size excavators and wheel loaders. Municipal contractors in Stockholm County are specifying zero-emission machines for inner-city demolition and utility trenching, while remote county projects retain diesel-hybrid configurations due to charging infrastructure gaps. This technical divergence is forcing OEMs to maintain parallel engineering streams and dual manufacturing footprints for the same equipment categories.
The Swedish Transport Administration's progressive emissions thresholds for infrastructure tenders are tightening procurement specifications on a project-by-project basis. Contractors bidding on railway and tunnel works must now document lifecycle carbon intensity for equipment fleets, with electric or renewable-diesel platforms receiving tender preference points. Earthmoving contractors are responding by accelerating lease-to-own transitions for battery-electric units ahead of residual value uncertainty.
Equipment-as-a-service contracting is displacing outright purchase in commercial construction site logistics. Fleet managers for Stockholm's high-rise residential developers are unbundling maintenance, telematics, and uptime guarantees into fixed monthly fees, transferring residual value risk to OEM captive finance arms. This financing model is most visible in wheel loader and material-handling equipment categories where utilization data enables precise hourly rate calibration.
Sweden Construction Equipment Market Segmentation
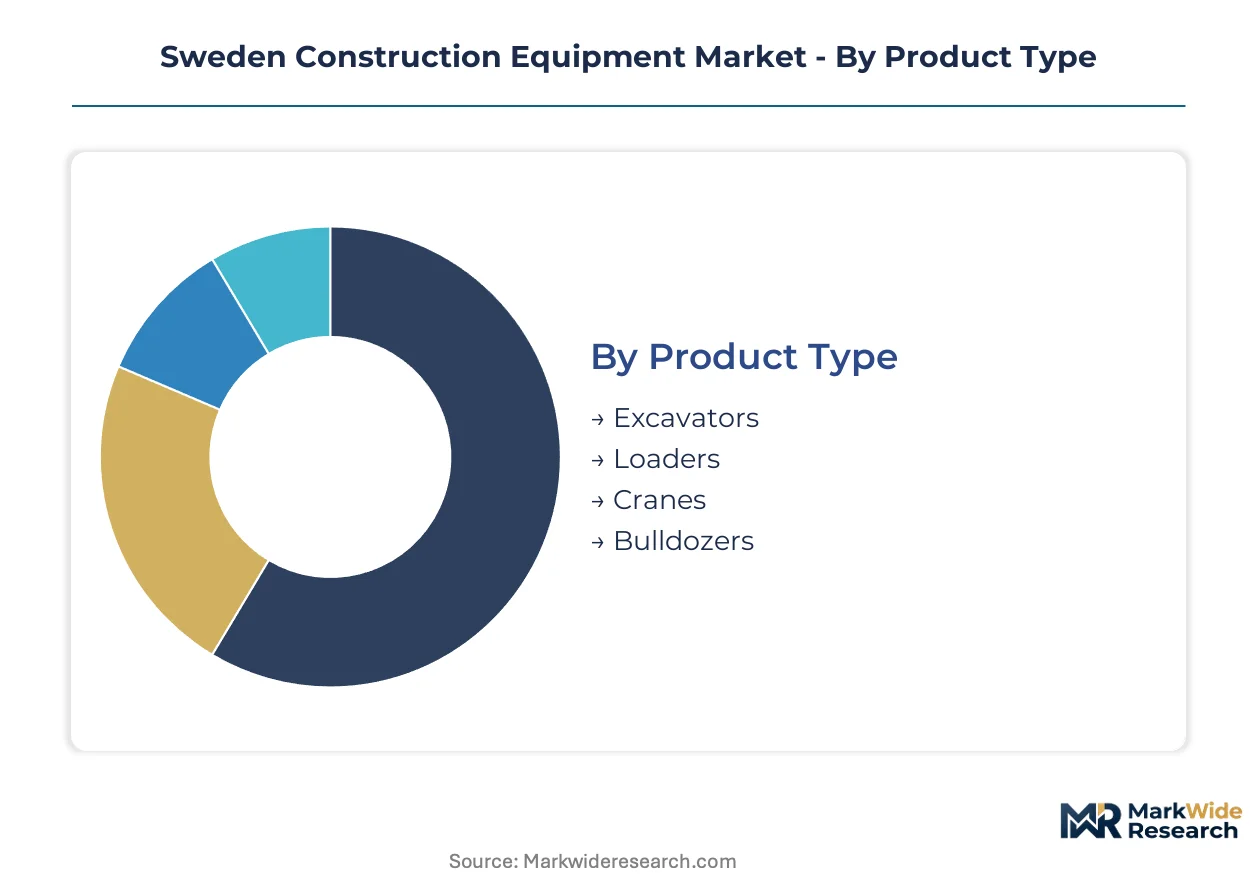
Equipment segmentation in Sweden follows divergent procurement channels: municipal tenders favor electrified platforms with documented carbon intensity, while private contractors optimize fleet utilization through rental intermediaries. Channel mix varies sharply across product categories and geographies.
Product Type:
Channel concentration differs by machine class: excavators and loaders flow heavily through rental fleets serving Stockholm's urban densification projects, while cranes and bulldozers see more direct OEM sales to specialized contractors.
- Excavators:Mid-size units with 400-volt battery architectures dominate municipal procurement in Greater Stockholm, where the Swedish Transport Administration's emissions benchmarks require zero-emission documentation for inner-city demolition and utility trenching. Tier 3 diesel phase-out compresses replacement cycles ahead of physical obsolescence.
- Loaders:Wheel loaders in commercial site logistics generate telematics-enabled usage data that supports hour-based subscription billing models, transferring residual value risk to OEM captive finance arms. Fleet managers in Stockholm's high-rise residential segment drive this contracting shift.
- Cranes:Lattice-boom configurations anchor demand in Stockholm's vertical residential construction, with specialized units commanding premium positioning through Liebherr's engineering concentration.
- Bulldozers:Heavy crawler units retain diesel-hybrid dominance in Norrland mining zones where Caterpillar's aftermarket parts density sustains competitive positioning.
By volume, excavators lead. By growth pace, electric loaders are expanding most quickly through equipment-as-a-service contracting.
Application:
Cost tier stratification separates premium electrified platforms for municipal infrastructure from standard diesel configurations for remote industrial sites.
- Infrastructure:Railway and tunnel projects across Stockholm-Gothenburg corridors extend equipment utilization hours through multi-year visibility, with the Swedish Transport Administration imposing progressive emissions thresholds that compress fleet turnover timelines.
- Commercial:High-rise residential development in Greater Stockholm concentrates wheel loader and material-handling demand, where telematics integration enables precise hourly rate calibration for subscription financing.
- Residential:Urban densification drives compact excavator deployment for foundation work and utility installation in Stockholm County municipalities.
- Industrial:Mining and resource extraction in Norrland counties retain diesel-hybrid configurations due to charging infrastructure gaps, constraining electric machine deployment to tethered or battery-swap setups.
By revenue concentration, infrastructure leads. By contract value growth, commercial applications are climbing the fastest.
End User:
Customer type determines procurement modality: government entities mandate lifecycle carbon documentation, while mining operators prioritize uptime guarantees over capital efficiency.
- Government:The Swedish Transport Administration and municipal authorities impose emissions documentation requirements that redirect procurement toward electrified platforms, with tender preference points awarded for renewable-diesel or battery-electric fleets.
- Contractors:Earthmoving specialists accelerate lease-to-own transitions for battery-electric units to align with municipal tender specifications, absorbing residual value uncertainty.
- Builders:Commercial site logistics fleet managers unbundle maintenance and uptime guarantees into fixed monthly fees, creating recurring revenue streams independent of unit sales.
- Mining:Norrland extraction operations retain diesel-dominant fleets where Caterpillar's dealer coverage and parts density sustain operational continuity across dispersed sites.
By fleet size, contractors lead. By specification stringency, government end users are gaining share fastest through tender design.
Technology:
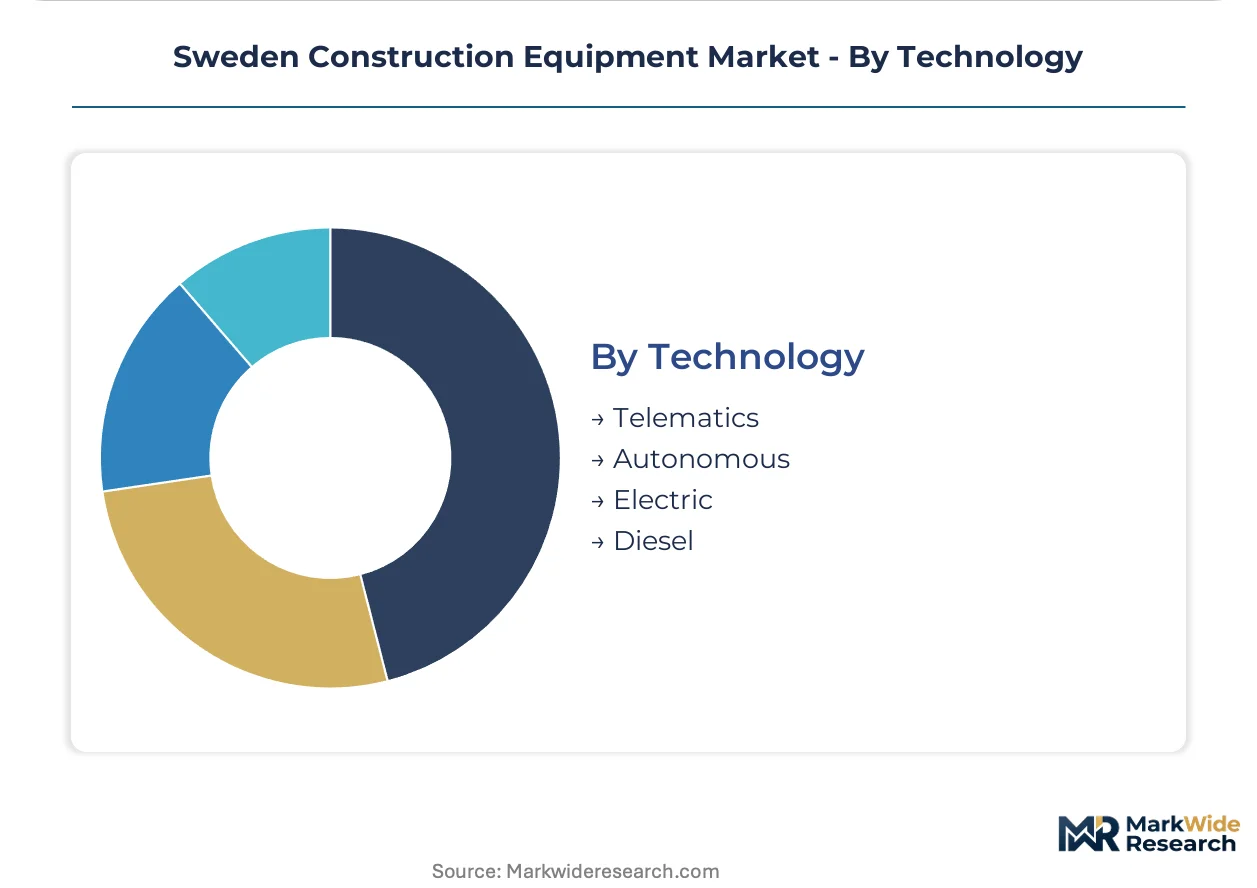
Maturity stage bifurcates the landscape: telematics and diesel represent installed-base dominance, while electric and autonomous platforms capture disproportionate R&D allocation.
- Electric:400-volt architectures and thermal management enable 8-hour operational cycles for mid-size excavators, with Gothenburg's automotive battery R&D cluster supporting prototype-to-production acceleration for Volvo Construction Equipment.
- Telematics:Usage-data revenue streams deepen across wheel loaders deployed in commercial site logistics, enabling precise hourly rate calibration for fleet managers.
- Diesel:Tier 3 units face residual value compression from EU Green Deal carbon-border adjustments and national fossil-fuel phase-out commitments, eroding secondary market liquidity ahead of physical obsolescence.
- Autonomous:Semi-automated excavators encounter extended prototype-to-homologation cycles from revised EU Machinery Directive conformity assessment procedures for safety systems.
By installed base, diesel leads. By financing allocation, electric technology is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Greater Stockholm exhibit acute price sensitivity to residual value risk from emissions regulation, while Norrland mining operators prioritize uptime guarantees over capital efficiency, creating a demand-elasticity divide that shapes regional procurement patterns.
Greater Stockholm
Urban densification and transit corridor upgrades concentrate equipment demand in tunnel-boring and foundation work segments. The Swedish Transport Administration imposes progressive emissions thresholds on infrastructure tenders, redirecting procurement toward electrified platforms. The Stockholm-Gothenburg high-capacity rail expansion extends multi-year project visibility for specialized machinery fleets.
Västra Götaland
Gothenburg's automotive battery R&D cluster accelerates prototype-to-production cycles for mid-size excavators with 400-volt architectures. The Swedish Work Environment Authority enforces operator cabin ergonomics limits that shape product certification requirements for regional OEM engineering bases. Port hydrogen infrastructure positions the region as a testbed for fuel-cell range extenders in heavy crawler cranes.
Norrland Mining Zones
Resource extraction operations retain diesel-hybrid dominance due to charging infrastructure gaps across dispersed sites. National fossil-fuel phase-out commitments compress residual value horizons for conventional equipment ahead of physical obsolescence. Caterpillar's aftermarket parts density sustains competitive positioning through dealer coverage networks.
Skåne County
Commercial site logistics in Malmö's high-rise residential segment drives telematics-enabled usage billing for wheel loaders. EU F-Gas Regulation phase-down mandates accelerate replacement demand for climate-controlled operator cabins. Equipment-as-a-service contracting transfers residual value risk to OEM captive finance arms through fixed monthly fee structures.
Sweden Construction Equipment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with electromobility R&D concentration defining premium positioning while aftermarket density sustains volume tiers. The market structures around three strategic archetypes: integrated OEMs with captive battery engineering, rental fleet intermediaries with telematics platforms, and specialized component suppliers for hydraulic systems. Consolidation pressure concentrates among mid-tier fabricators lacking vertical control over electric drivetrain sourcing. Geographic expansion and strategic partnerships represent the dominant competitive moves as players seek charging infrastructure alignment.
Among Sweden-based integrated manufacturers, Volvo Construction Equipment leverages its Gothenburg engineering concentration to anchor the electromobility tier. Caterpillar occupies a position exemplifying aftermarket-driven competitive defense through parts density networks. Liebherr represents specialized crane engineering concentration for vertical residential construction applications.
| Leading Market Players |
|---|
| Volvo Construction Equipment |
| Caterpillar |
| Komatsu |
| Liebherr |
| Sandvik AB |
| JCB |
| Hitachi Construction Machinery |
| Kobelco |
| Husqvarna Construction |
| Others |
Pricing and Supply Chain Analysis
Twelve-to-sixteen-week battery pack lead times from East Asian cathode suppliers are compressing OEM working capital cycles and amplifying pricing power for integrated manufacturers with captive cell engineering in western Sweden. This inventory pressure concentrates margin defense around aftermarket service density and telematics-enabled usage contracts that extend revenue recognition horizons.
Pricing Analysis
Aftermarket parts and service contracts generate lifetime value multiples exceeding original equipment margins, with three-tier pricing structure across premium electrified platforms, standard diesel-hybrid configurations, and economy rental fleet tiers. Price differentiation rests on CE marking tier for autonomous safety systems and Volvo Construction Equipment's Gothenburg engineering concentration for battery-thermal management. Cost compression in diesel residual values is intensifying because EU Green Deal carbon-border adjustments erode secondary market liquidity. Municipal contractors in Greater Stockholm exhibit acute price sensitivity to residual value risk, while Norrland mining operators prioritize uptime guarantees over capital efficiency.
Supply Chain Analysis
Container availability constraints on the Asia-North Europe trade lane are elevating inbound logistics costs for lithium-ion cells and power electronics modules. Manufacturing concentration draws from China, South Korea, and Japan for cathode materials, cell assembly, and semiconductor components. Raw material dependencies center on lithium carbonate, nickel sulfate, and rare-earth permanent magnets for electric drivetrains. Single-source vulnerability in 800-volt inverter supply creates fleet delivery risk for mid-size excavator programs. Distribution runs through rental fleet intermediaries in Stockholm County and direct OEM sales to specialized contractors in vertical residential construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Sweden Construction Equipment Market functions as a regulatory-moat story where Swedish Transport Administration emissions benchmarks create switching costs that entrench early electrification adopters against latecomers facing compressed residual value horizons.
For Market Incumbents: Secure captive battery engineering capacity in the Gothenburg automotive cluster to defend against emerging Chinese OEM entrants with cost-optimized electric platforms. Deepen telematics integration for hour-based subscription billing that transfers residual value risk to fleet managers. Prioritize certification investment for EU Machinery Directive autonomous safety systems to extend prototype-to-homologation cycle advantages. For New Entrants and Emerging Players: Differentiate on battery-swap infrastructure deployment for Norrland mining zones where grid capacity constraints block conventional charging. Target the Skåne County commercial site logistics segment with equipment-as-a-service contracting that unbundles maintenance and uptime guarantees. Pursue go-to-market partnerships with Stockholm rental fleet intermediaries seeking electrified platform diversification. For Investors and Strategic Acquirers: Carve-out targets emerge from mid-tier hydraulic component fabricators lacking vertical control over electric drivetrain sourcing. Long-term viability favors integrated OEMs with captive R&D in 400-volt architectures and aftermarket parts density networks. Monitor Swedish Work Environment Authority ergonomic mandate enforcement as an inflection signal for premium cabin configuration demand.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell allocation from East Asian manufacturers for Gothenburg assembly plants. |
| Telematics Platform Integration | Enables hour-based subscription billing for wheel loaders in Stockholm commercial logistics. |
| Backward Integration into Thermal Management | Captures battery pack engineering margin for 8-hour operational cycle excavators. |
| Charging Infrastructure Partnership | Addresses grid capacity gaps constraining electric deployment in Norrland mining zones. |
| CE Marking Pathway Acceleration | Compresses prototype-to-homologation cycles for semi-automated excavator safety systems. |
Research Methodology
Desk research of EU regulatory filings, Swedish Transport Administration tender documentation, and OEM technical disclosures preceded structured interviews with fleet procurement managers, aftermarket service directors, and municipal contracting officers. Primary fieldwork captured utilization patterns across Greater Stockholm rental fleets and Norrland mining operations. Secondary validation drew from customs trade data, SEC 10-K equipment segment disclosures, and Swedish Work Environment Authority certification records. Bottom-up equipment unit economics triangulated against top-down infrastructure investment forecasts.
Variance decomposition across product type, application, end user, and technology dimensions shaped the analytical framework over the projection horizon. Segmentation modeling captured excavator, loader, crane, and bulldozer categories with electric, diesel, telematics, and autonomous technology tiers. CAGRs derived from equipment replacement cycle compression rates and municipal tender specification trajectories. Forecast inputs incorporated railway corridor project visibility and battery-electric drivetrain adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained Swedish Transport Administration emissions enforcement or accelerated EU F-Gas Regulation phase-down timelines would require recalibration. Forecasts reflect documented assumptions regarding charging infrastructure rollout pace and lithium-ion cell supply concentration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Commercial Sanitizing Equipment Market
Construction Equipment
Global Dragline Excavator Market
Construction Equipment
Stud Welding Guns Market
Construction Equipment
Compact Excavator Market
Construction Equipment
Construction Wearable Technology Market
Construction Equipment
Electric and Hybrid Construction Equipment Market
Construction Equipment
Canada Construction Equipment Market
Construction Equipment
Construction Pump Market
Construction Equipment
Europe Construction Equipment Rental Market
Construction Equipment
Hexagonal Wire Netting Machine Market
Construction Equipment
Global Hydraulic Hammer Market
Construction Equipment
Street Cleaning Machine Market
Construction Equipment
Global Desktop CNC Machines Market
Construction Equipment
Mobile Crushers and Screeners Market
Construction Equipment
Water Sprinkler Market
Construction Equipment
Garage Equipment Market