
 Asia-Pacific Heavy Construction Equipment Market | 2026-2036
Asia-Pacific Heavy Construction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Heavy Construction Equipment Market Analysis
The Asia-Pacific heavy construction equipment sector is pivoting along a widening gap between premium electrified machines and conventional diesel units serving price-sensitive contractors. Sany Heavy Industry leverages its integrated battery supply chain to dominate electric excavator shipments within China. Komatsu sustains technology leadership through its autonomous haulage systems deployed across Australian iron ore operations. Caterpillar anchors premium positioning through global service networks that extend equipment lifecycle value for mining clients.
Heavy construction equipment encompasses earth-moving, material-handling, and compaction machinery engineered to operating weights exceeding 12 metric tons, typically powered by diesel engines rated above 130 kW for excavation and grading operations in commercial and civil engineering environments. Excavators command the largest equipment-type share due to versatility across trenching, demolition, and material-loading workflows. The electric fuel-type segment attracts capital as battery energy density improvements enable eight-hour shift compatibility for urban deployment configurations. Diesel retains dominance in off-road mining applications where refueling infrastructure and torque requirements resist near-term substitution.
China's MIIT enforces GB standards on non-road mobile machinery emissions, compelling manufacturers to redesign engine combustion architectures or accelerate electrification roadmaps. Australia's national regulator mandates autonomous vehicle protocols for open-pit mining sites, shaping product development priorities for Hitachi Construction Machinery and HD Hyundai Construction Equipment. India's BIS certification requirements for construction equipment imports create compliance barriers that favor localized assembly by XCMG Group and domestic producers. Stakeholders must weigh carbon-border adjustment exposure against regional subsidy eligibility when configuring regional manufacturing footprints and powertrain portfolios.
Market Dynamics
The Asia-Pacific heavy construction equipment market is compressing around a bifurcation between electrified urban machinery and diesel-powered mining fleets, with battery energy density gains and Australia's autonomous mining mandates forcing parallel product development tracks.
Growth Catalysts
- India's PLI scheme for manufacturing:Production-linked incentives for capital goods assembly are drawing XCMG Group and domestic producers to establish localized supply chains serving the Delhi-Mumbai infrastructure corridor.
- Autonomous haulage protocols:Australia's national regulator mandates autonomous vehicle standards for open-pit mining sites, accelerating fleet replacement cycles among iron ore contractors.
- Dual carbon goals:China's MIIT enforcement of GB emissions standards on non-road mobile machinery compels engine redesign or electrification pivots across domestic OEM portfolios.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack cost volatility and cathode material sourcing bottlenecks from concentrated Asian suppliers constrain electric excavator pricing flexibility.
- Refueling infrastructure gap:Remote mining sites in Indonesia and Western Australia lack grid connectivity or hydrogen distribution, locking diesel dominance for 300-ton-class haul trucks.
- BIS certification timelines:India's import certification requirements for construction equipment create 6-12 month compliance delays that disadvantage non-localized suppliers.
Strategic Opportunities
- Vietnam's infrastructure buildout:Underpenetrated demand for mid-size excavators exists in Vietnamese port and highway projects outside Ho Chi Minh City and Hanoi corridors.
- Battery-as-a-service models:Swappable powerpack leasing for urban electric fleets addresses range anxiety without capital burden on small contractors.
- Telematics-ERP convergence:Integration of equipment IoT data with project management software creates subscription revenue streams beyond hardware margins.
Industry Challenges
- Autonomous systems integration:Mining contractors face 18-24 month workforce retraining cycles to operate and maintain sensor-fusion haulage fleets.
- Legacy fleet interoperability:Mixed diesel-electric jobsites require dual maintenance capabilities and incompatible parts inventories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Heavy Construction Equipment Market |
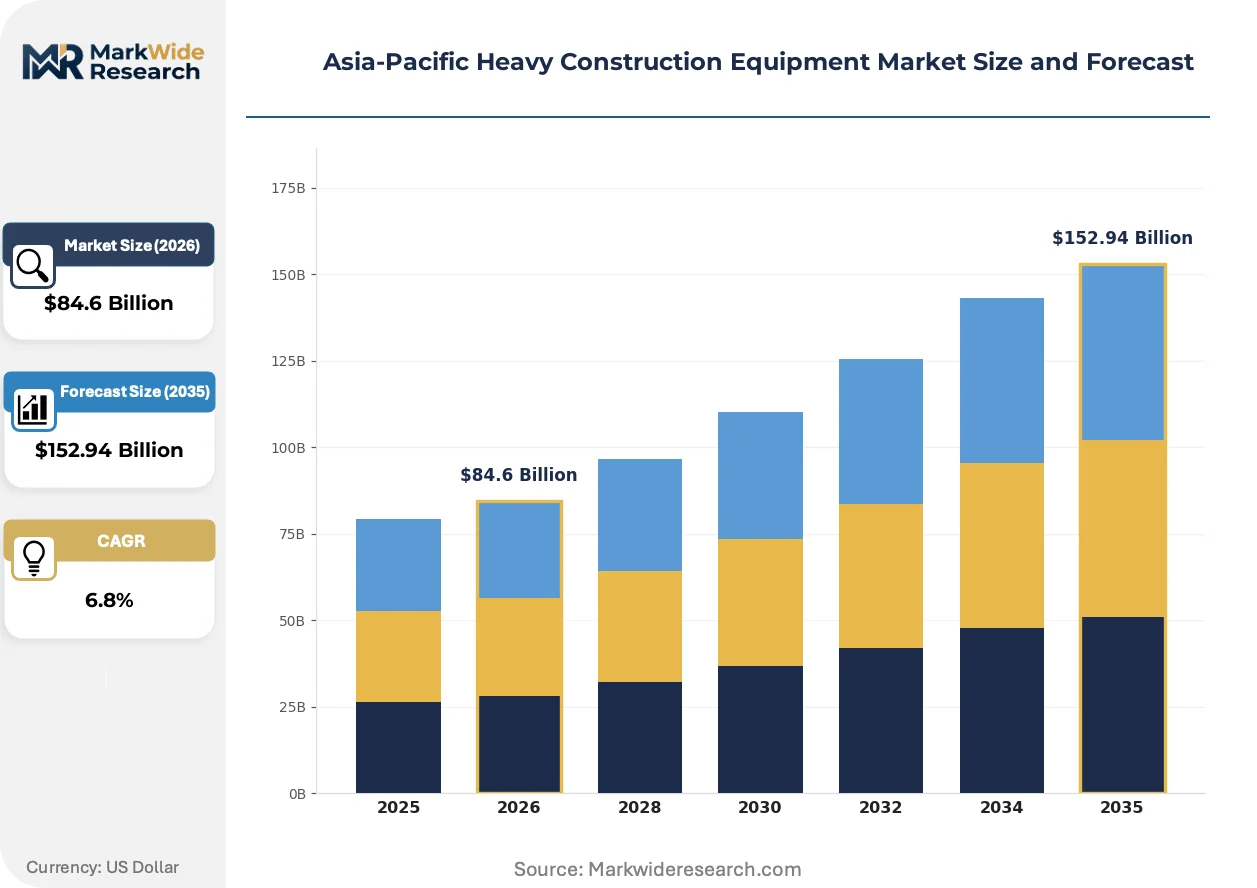
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $152.94 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Excavators, Bulldozers, Loaders, Graders End User: Contractors, Government, Mining, Infrastructure Fuel Type: Diesel, Electric, Hybrid, Gas Deployment: On-Road, Off-Road, Remote, Urban |
| Companies Covered | Volvo Construction Equipment, Sany Heavy Industry, Caterpillar, HD Hyundai Construction Equipment, XCMG Group, Komatsu, Develon, JCB, Hitachi Construction Machinery, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Heavy Construction Equipment Market Emerging Trajectories
Electrification, autonomy, and data monetization are rewriting competitive advantage in Asia-Pacific heavy equipment, compressing the traditional hardware-centric business model toward service-integrated offerings.
Solid-state battery prototypes are rewriting range and charging constraints for electric excavators. Urban contractors in Japan and South Korea are piloting 300 kWh-class machines for eight-hour shift compatibility. The technology is rewriting total cost of ownership calculations by eliminating mid-shift charging downtime and reducing maintenance intervals.
China's MIIT GB36886 emissions standard for non-road diesel machinery is forcing engine architecture redesigns or accelerated electrification roadmaps. Domestic manufacturers face compliance deadlines that favor clean-sheet electric platforms over incremental combustion improvements. The regulation is rewriting product portfolios, with electric excavator SKUs expanding fastest in 20-35 ton classes serving municipal construction.
Equipment utilization data is becoming a standalone revenue stream as contractors demand outcome-based fleet management. Komatsu's KOMTRAX and comparable telematics platforms are displacing traditional time-and-materials rental contracts. Mining operators in Australia's Pilbara region are negotiating availability-guaranteed agreements where suppliers bear downtime risk, compressing pricing transparency and locking in multi-year service relationships.
Asia-Pacific Heavy Construction Equipment Market Segmentation
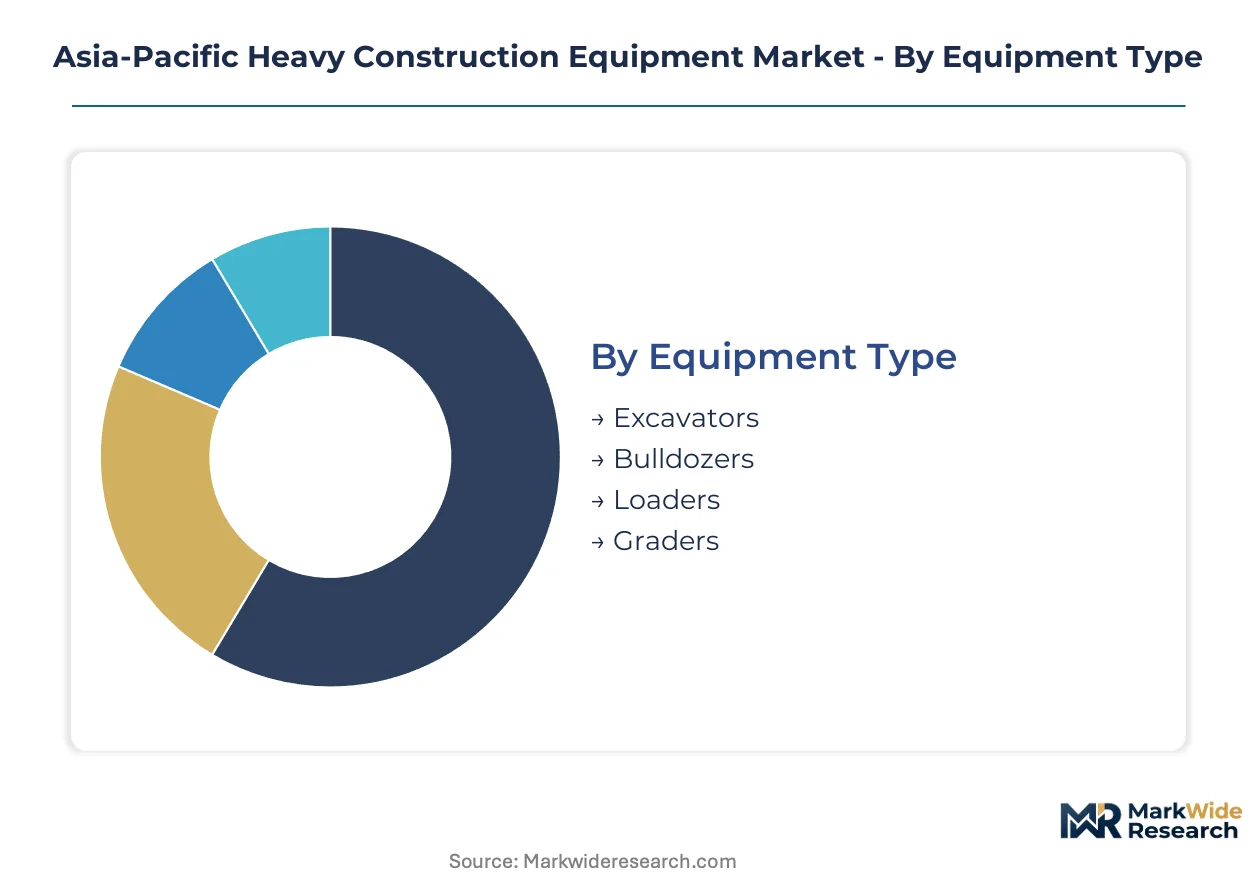
Segmentation in Asia-Pacific heavy construction equipment reveals how procurement patterns split between mining-scale diesel deployments and municipal electrification mandates. Equipment specifications, fuel compliance, and site accessibility requirements create distinct supplier-customer pairings across the region.
Equipment Type:
Supply concentration in hydraulic system manufacturing tilts competitive advantage toward integrated producers with in-house pump and valve capabilities.
- Excavators:Hydraulic machines with operating weights from 20 to 90 metric tons dominate fleet compositions. Australia's Pilbara iron ore contractors specify autonomous-compatible models for haul truck loading operations.
- Loaders:Articulated wheel loaders with bucket capacities exceeding 5 cubic meters serve aggregate handling and port material movement. India's Delhi-Mumbai corridor infrastructure projects sustain demand for 30-50 ton class units.
- Bulldozers:Tracked dozers rated above 250 kW handle bulk earthworks and mine site preparation.
- Graders:Motor graders with 12-14 foot moldboards deliver precision grading for highway and airport runway construction.
Excavators absorb the bulk of installed capacity; loaders are expanding most quickly.
End User:
Customer procurement scale determines whether manufacturers prioritize unit economics or lifecycle service contracts.
- Contractors:Private construction firms operating on fixed-price contracts prioritize equipment availability and resale value. Indonesia's mining contractors favor rental-with-maintenance agreements to manage fleet utilization risk.
- Mining:Resource extraction operators demand 24/7 availability guarantees and autonomous compatibility. Australia's open-pit iron ore sector mandates compliance with national autonomous vehicle protocols.
- Government:Public works agencies specify domestic content requirements and BIS certification for imported equipment.
- Infrastructure:Dedicated project entities for expressway and rail construction deploy dedicated fleets for multi-year construction windows.
Mining commands premium pricing power; contractors represent the largest unit volume channel.
Fuel Type:
Powertrain selection tracks the divergence between grid-connected urban job sites and remote diesel-dependent operations.
- Diesel:Compression-ignition engines above 130 kW retain dominance in off-road mining where refueling infrastructure exists and torque demands exceed electric motor capabilities.
- Electric:Battery-powered excavators with 300 kWh packs achieve eight-hour shift compatibility in Japanese and South Korean urban construction. China's MIIT GB emissions enforcement accelerates domestic OEM electrification roadmaps.
- Hybrid:Diesel-electric architectures reduce fuel consumption through regenerative braking and engine downsizing.
- Gas:Compressed natural gas conversions serve select municipal fleets with fixed-base refueling.
Diesel retains the majority of installed base; electric powertrains are climbing the fastest.
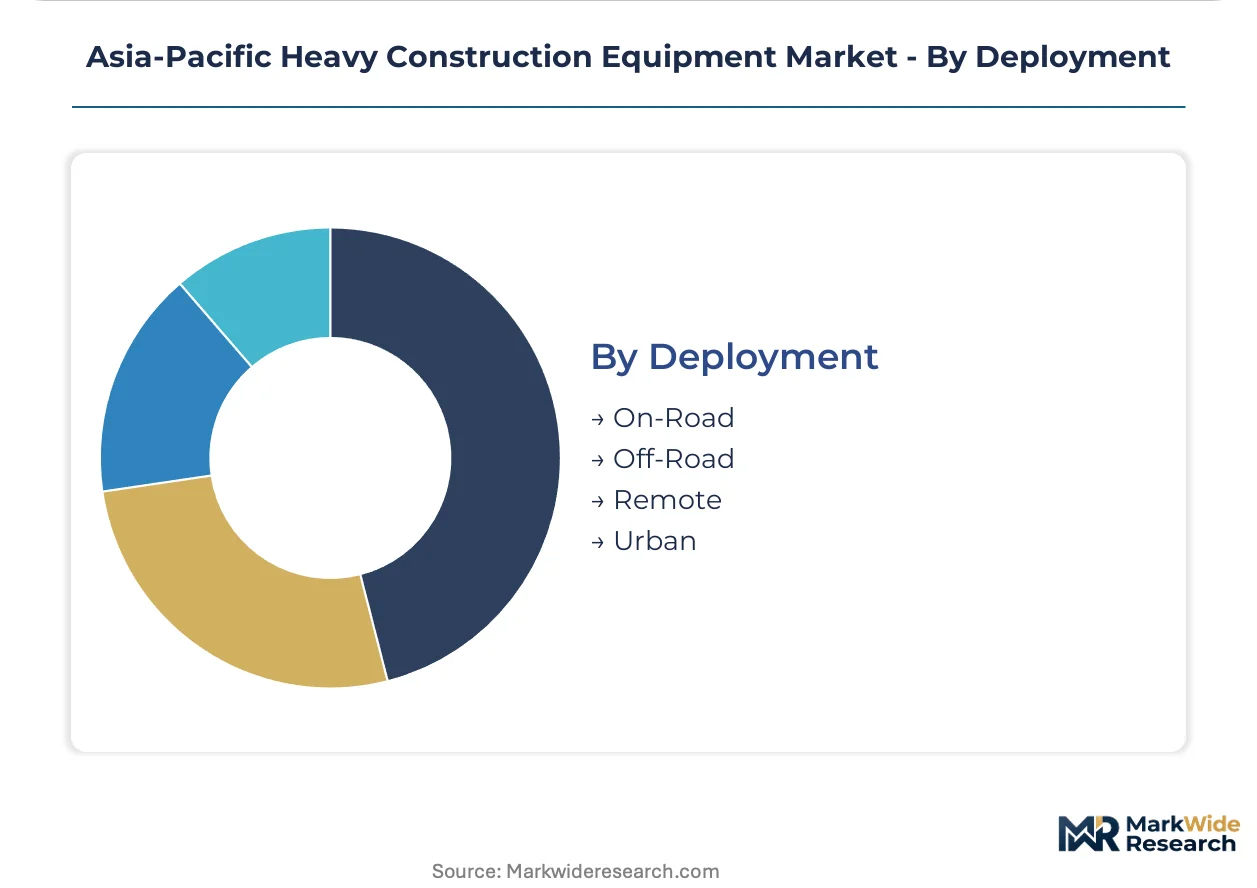
Deployment:
Site accessibility constraints dictate equipment mobility specifications and telematics integration depth.
- Off-Road:Purpose-built machines with reinforced undercarriages and high ground clearance operate on unimproved mine haul roads and construction sites.
- Urban:Compact-radius excavators and low-noise equipment serve dense Japanese and South Korean metropolitan construction with strict emissions and sound ordinances.
- Remote:Satellite-connected telematics and extended maintenance intervals address grid-disconnected operations in Western Australia and Indonesian archipelago projects.
- On-Road:Highway-legal mobile cranes and truck-mounted equipment move between dispersed job sites under their own power.
Off-Road deployment absorbs the bulk of heavy equipment value; urban configurations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Delhi-Mumbai Industrial Corridor anchors fleet deployment intensity across Asia-Pacific heavy construction equipment procurement, with sustained expressway and rail construction driving multi-year equipment orders.
China
Domestic OEMs accelerate electrification roadmaps as MIIT enforces GB36886 emissions standards on non-road mobile machinery. The dual carbon goals compel engine architecture redesigns or clean-sheet electric platforms. Yangtze River Delta manufacturers expand 20-35 ton electric excavator SKUs for municipal construction.
India
The PLI scheme for capital goods assembly draws XCMG Group and domestic producers to localized supply chains. BIS certification requirements for imported equipment create compliance barriers favoring regional assembly. The Delhi-Mumbai infrastructure corridor sustains demand for 30-50 ton class wheel loaders.
Australia
Iron ore contractors in the Pilbara region mandate autonomous-compatible excavators for haul truck loading operations. The national regulator enforces autonomous vehicle protocols for open-pit mining sites. Western Australian mining operations negotiate availability-guaranteed agreements with equipment suppliers.
Indonesia
Mining contractors favor rental-with-maintenance agreements to manage fleet utilization risk across archipelago projects. Remote site operations lack grid connectivity for electric alternatives. Kalimantan and Papua mining concessions sustain diesel dominance for 300-ton-class haul trucks.
Japan
Urban contractors pilot 300 kWh-class electric excavators for eight-hour shift compatibility in dense metropolitan construction. METI emissions ordinances and strict sound regulations compress diesel deployment windows. Tokyo and Osaka metropolitan areas drive compact-radius equipment specifications.
Asia-Pacific Heavy Construction Equipment Market Vendor Landscape
Premium-margin players sit above commodity-margin players across electrification capability and autonomous systems integration. The vendor base clusters around three strategic archetypes: integrated battery supply chain operators, autonomous haulage technology leaders, and global service network anchors. Capacity expansion and strategic partnerships dominate competitive moves as manufacturers localize assembly to capture PLI scheme benefits and BIS certification advantages.
Within the integrated supply chain tier, Sany Heavy Industry and XCMG Group occupy positions shaped by captive battery production and domestic market scale. Komatsu and Caterpillar anchor the premium service tier through multi-year availability agreements and lifecycle value contracts. HD Hyundai Construction Equipment represents the autonomous systems specialist archetype with regulatory compliance focus for Australian mining protocols.
| Leading Market Players |
|---|
| Volvo Construction Equipment |
| Sany Heavy Industry |
| Caterpillar |
| HD Hyundai Construction Equipment |
| XCMG Group |
| Komatsu |
| Develon |
| JCB |
| Hitachi Construction Machinery |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed producers across China and state-supported mining contractors in Australia anchor procurement patterns that compress supplier margins while sustaining premium pricing for electrified fleets. China's MIIT emissions enforcement and Australia's autonomous haulage mandates create divergent cost structures that manufacturers must reconcile through regional pricing stratification.
Pricing Analysis
Availability-guaranteed contracts with throughput-linked penalties dominate Australian iron ore procurement, shifting price anchors from unit cost to uptime performance. Tiered pricing separates autonomous-compatible excavators from conventional diesel units, with battery-electric machines commanding premiums justified by eight-hour shift compatibility. Cost compression in mid-size excavators intensifies as domestic Chinese OEMs expand 20-35 ton electric SKUs. Small contractors in Vietnam and Indonesia exhibit highest price sensitivity, favoring rental-with-maintenance agreements over capital purchases.
Supply Chain Analysis
Dual-sourcing requirements for lithium-ion cathode materials compel battery pack assemblers to qualify suppliers across China, South Korea, and Japan simultaneously. Hydraulic system manufacturing draws from integrated pump and valve production concentrated in Germany, Japan, and China. Single-source vulnerability in high-grade steel forgings for excavator booms exposes OEMs to commodity price volatility. Distribution runs through manufacturer-owned service networks for mining clients and independent dealers serving municipal contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in battery cell capacity prop pricing power for electrified equipment, with cathode material bottlenecks extending lead times for 300 kWh-class machines beyond standard procurement cycles.
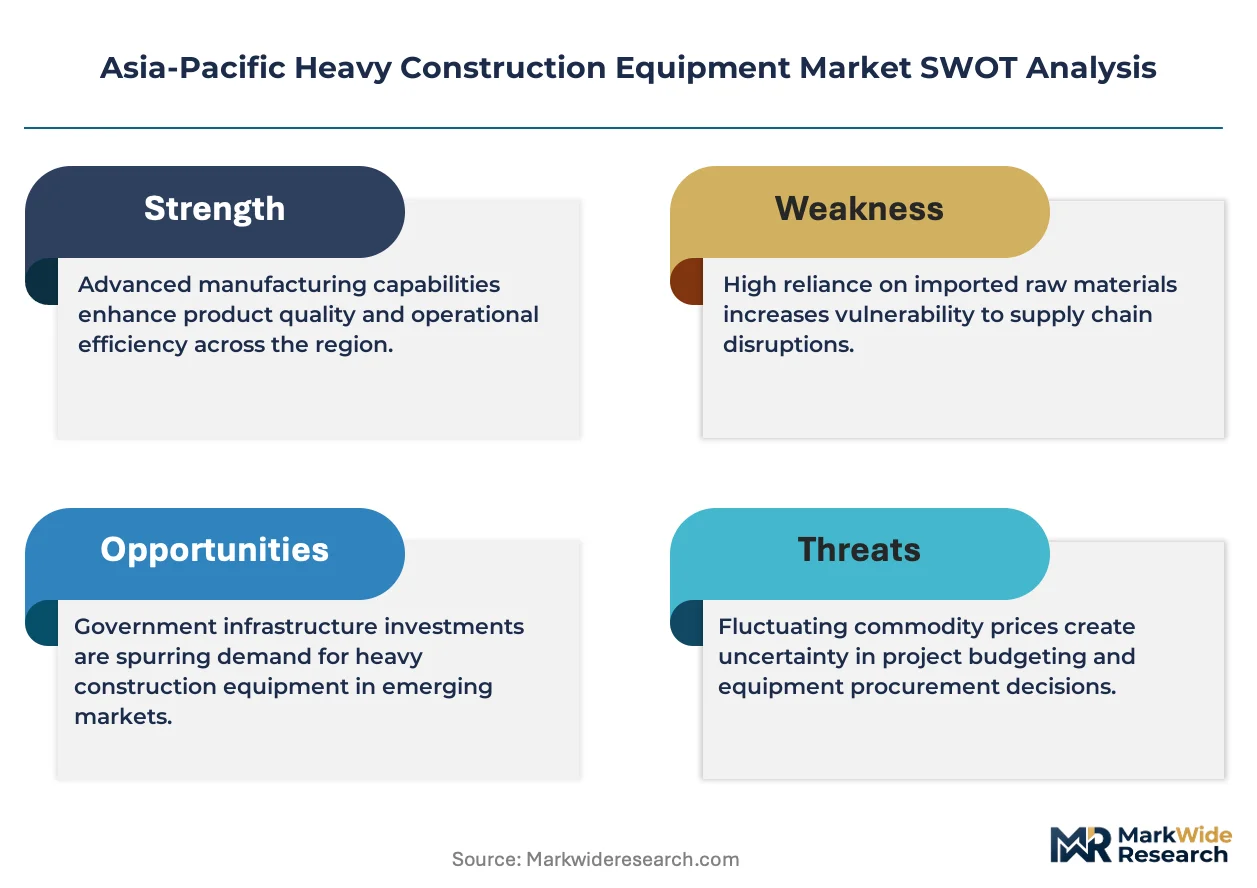
For Market Incumbents: Extend autonomous systems integration beyond Australian mining protocols into Indonesian archipelago operations where workforce retraining cycles create switching costs. Consolidate aftermarket parts distribution through regional hub investments in India to capture PLI scheme localization benefits and neutralize BIS certification delays threatening import-dependent competitors. For New Entrants and Emerging Players: Vietnamese port authorities represent an underserved buyer archetype with underpenetrated demand for mid-size excavators outside Ho Chi Minh City and Hanoi corridors. Battery-as-a-service leasing models for urban electric fleets address contractor capital constraints without requiring manufacturing scale. Partner with established hydraulic component suppliers to bypass integrated pump and valve development timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor autonomous technology specialists with Australian regulatory compliance credentials during mining capex contraction phases. Long-term viability hinges on service-revenue attachment rates exceeding hardware margins across five-to-ten year holding periods. Monitor MIIT enforcement intensity on GB36886 emissions deadlines as inflection indicator for electric platform investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Production | Captive cathode supply insulates Sany Heavy Industry from lithium-ion pricing volatility. |
| Autonomous Haulage Protocol Certification | Komatsu's compliance with Australian national standards locks in Pilbara iron ore replacement cycles. |
| Localized Assembly for PLI Scheme Access | XCMG Group's India manufacturing qualifies for production-linked incentives serving Delhi-Mumbai corridor demand. |
| Telematics-ERP Platform Convergence | KOMTRAX integration with project management software displaces time-and-materials rental contracts. |
| Solid-State Battery Prototype Deployment | 300 kWh-class machines in Japanese urban construction eliminate mid-shift charging downtime. |
Methodological Framework
Multi-period observation of fleet replacement cycles, emissions compliance deadlines, and battery energy density improvements anchored the trend analysis, supplemented by interviews with mining procurement directors, municipal contractor fleet managers, OEM platform engineers, and aftermarket service heads. Secondary validation drew from MIIT regulatory filings, Australian autonomous vehicle protocol documentation, Indian BIS certification records, and customs trade data for heavy equipment imports. Bottom-up equipment shipment tallies and top-down construction expenditure estimates were triangulated to reconcile volume figures.
Segment-weighting across equipment type, fuel architecture, deployment configuration, and end-user procurement scale determined value distribution. CAGRs were derived from regression analysis of historical shipment data against infrastructure investment flows and mining commodity price cycles. The projection horizon incorporates battery cost curves, autonomous technology adoption thresholds, and regional emissions enforcement trajectories as industry-specific forecast inputs.
Revisions become necessary when GB standards enforcement intensity deviates from announced timelines, autonomous vehicle protocol adoption accelerates beyond mining sector pilots, or battery cell supply concentration shifts through new cathode material sourcing routes. Deviation in any of these triggers would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Shield Machines Market
Construction Equipment
Electric Excavators Market
Construction Equipment
Core Drill Automatic Feeding Machine Market
Construction Equipment
Heavy Construction Equipment Market
Construction Equipment
Welding Equipment and Consumables Market
Construction Equipment
Water Sprinkler Market
Construction Equipment
LAMEA Stud Welding Machine Market
Construction Equipment
Compact Power Equipment Rental Market
Construction Equipment
Trash Rack Cleaning Machine Market
Construction Equipment
All-Terrain Crane Market
Construction Equipment
Earthmoving Equipment Market
Construction Equipment
Global Tablet Press Machine Market
Construction Equipment
Hand Push Trencher Market
Construction Equipment
Autonomous Construction Equipment Market
Construction Equipment
Field Marking Equipment Market
Construction Equipment
Global Construction Dumper Market