
 Cement and Mortar Testing Equipment Market | 2026-2036
Cement and Mortar Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Cement and Mortar Testing Equipment Market Analysis
Geopolymer binders is realigning equipment specifications as manufacturers recalibrate compression testing protocols for lower-carbon formulations. Humboldt Manufacturing Company leverages its North American distribution network to anchor regional service capabilities. ZwickRoell GmbH & Co. KG differentiates through precision automation in digital testing equipment, while Controls Group specializes in modular systems for emerging market laboratories.
Cement and mortar testing equipment encompasses mechanical and electronic apparatus designed to measure compressive strength, workability, setting time, and dimensional stability of hydraulic binders, typically operating within load frames rated from 50 kN to 5,000 kN with digital data acquisition. Compression testing machines command the largest installed base across quality control laboratories, though non-destructive testing represents the fastest-growing technology category as infrastructure owners prioritize in-situ structural assessment without core extraction. Automated systems capture expanding margin pools where construction companies seek throughput gains in batch certification workflows.
ASTM International governs test method standards for compressive strength evaluation in the United States, while the European Committee for Standardization maintains EN 196 for cement characterization across EU member states. China's SAMR enforces GB standards for building materials certification, creating parallel compliance pathways that equipment vendors must navigate. Stakeholders should monitor regulatory convergence between carbon-accounting frameworks and mechanical test protocols, as embodied-carbon disclosure requirements begin to penetrate construction procurement rules.
Market Dynamics
Geopolymer binders are forcing recalibration of compression testing protocols as laboratories confront lower-carbon formulations with variable curing kinetics and non-standard strength development curves.
Growth Catalysts
- ASTM C109 compliance mandates:North American laboratories face compulsory upgrades from manual to automated compression frames, driving replacement cycles across quality control facilities.
- China's megaproject pipeline:Domestic quality assurance spending accelerates as infrastructure investment concentrates in high-speed rail and hydropower corridors.
- Non-destructive testing adoption:Bridge and tunnel owners prioritize in-situ structural assessment without core extraction, expanding ultrasonic and rebound hammer deployments.
Market Restraints
- Load frame steel input volatility:Precision-machined frame components face cost pressure from specialty alloy supply concentration in East Asian foundries.
- Calibration certification backlogs:ISO/IEC 17025 accreditation timelines stretch 8-14 months in saturated European metrology markets.
- Portable field tester substitution:Lightweight digital rebound hammers capture routine screening work previously assigned to laboratory compression machines.
Strategic Opportunities
- India's laboratory buildout:State-level highway authority contracts create first-mover advantage for modular, climate-hardened testing systems.
- Carbon-accounting convergence:EU Green Deal procurement rules embed embodied-carbon disclosure into cement certification, creating demand for integrated testing-data platforms.
- Automation-software bundling:Laboratory information management systems paired with load frames capture recurring revenue streams from construction material certification workflows.
Industry Challenges
- Metrology technician scarcity:Specialized calibration expertise for servo-hydraulic systems concentrates in aging workforce cohorts across Germany and Japan.
- Legacy data integration friction:Decades-old manual test records resist migration to cloud-based quality management platforms without custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cement and Mortar Testing Equipment Market |
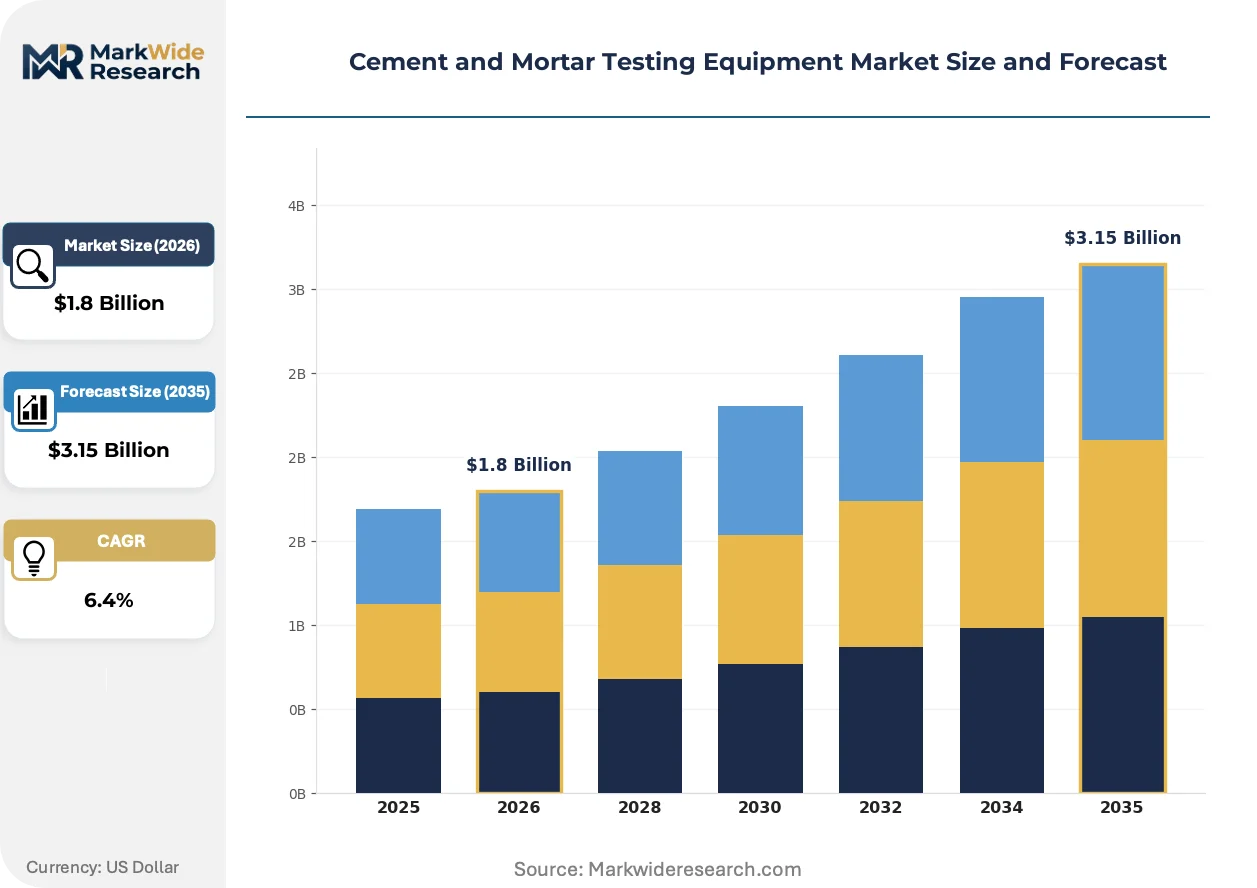
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compression Testing Machine, Concrete Testing Machine, Mortar Mixer, Slump Test Apparatus End User: Construction Companies, Quality Control Laboratories, Academic Institutions, Research Organizations Application: Material Testing, Quality Assurance, Research and Development, Compliance Testing Technology: Digital Testing Equipment, Automated Systems, Manual Testing Tools, Non-Destructive Testing |
| Companies Covered | Aimil Limited, Humboldt Manufacturing Company, ZwickRoell GmbH & Co. KG, Forney LP, Matest S.p.A., Controls Group, Qualitest International Inc., UTEST Material Testing Equipment Co Ltd., ELE International Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cement and Mortar Testing Equipment Market Emerging Trajectories
Digital automation is compressing test cycle times while embedded sensors generate granular datasets that reshape how construction firms batch-certify materials.
Machine-vision strain measurement is rewriting accuracy benchmarks in compression testing. High-resolution camera arrays track specimen deformation without mechanical extensometers. Materials testing laboratories in Germany and Japan deploy these systems to eliminate contact-point errors in brittle specimen evaluation. The technology is compressing calibration intervals and reducing operator-to-operator variance in strength determination.
REACH substance restrictions on hydraulic fluid formulations are compelling load frame manufacturers to redesign servo-hydraulic circuits. Equipment vendors reformulate seal materials and switch to biodegradable lubricants to maintain EU market access. This regulatory pressure concentrates most acutely on high-capacity frames above 2,000 kN where hydraulic systems dominate electromechanical alternatives.
Construction firms are unbundling after-sales service contracts from equipment purchases. Large batch plants now source calibration and maintenance from third-party metrology specialists rather than original manufacturers. This pattern is most visible in Australia's commercial testing sector where independent accreditation bodies capture recurring service revenue from decentralized laboratory networks.
Cement and Mortar Testing Equipment Market Segmentation
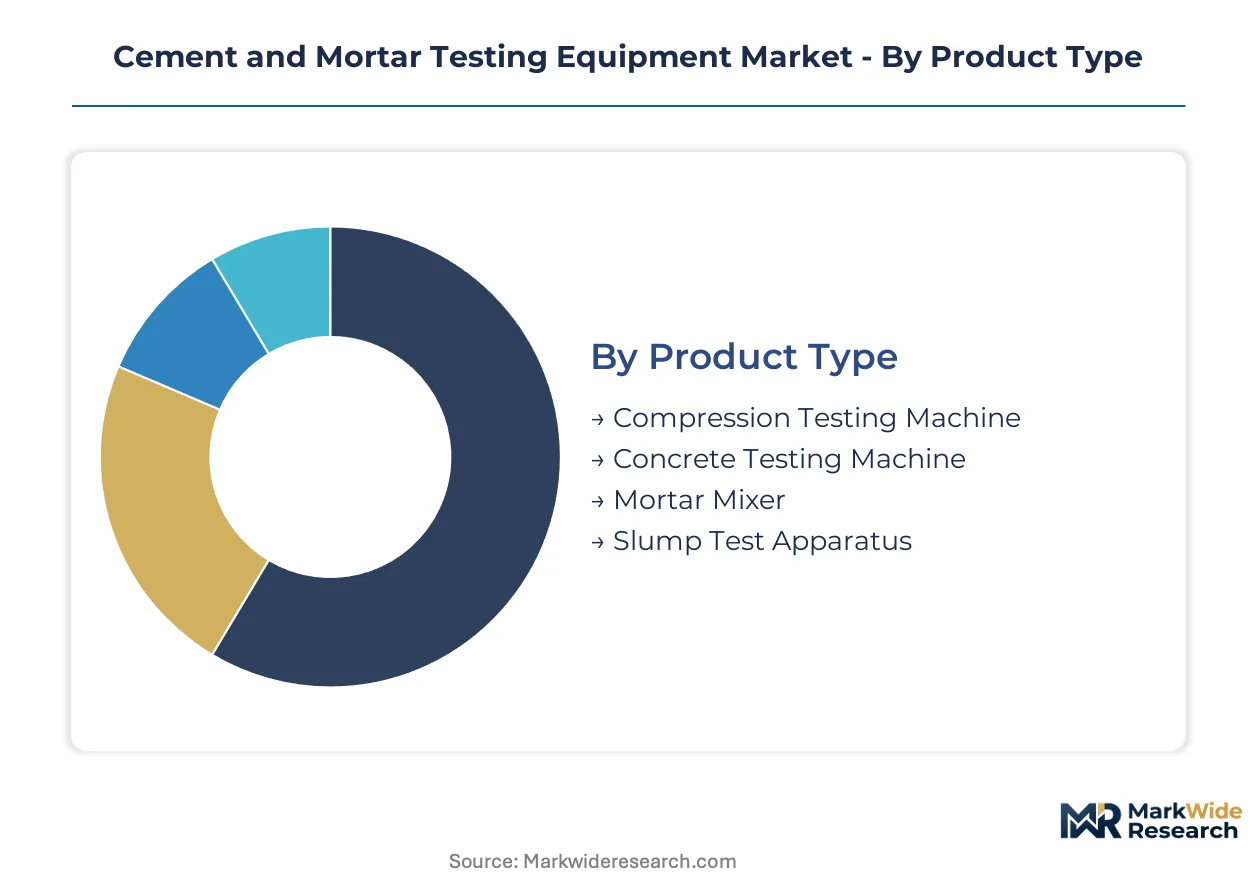
Testing equipment specifications diverge sharply across end-use contexts. Laboratory certification workflows demand precision automation, while field deployment prioritizes portability and rapid cycle times.
Product Type:
Load frame architecture and force measurement systems define performance boundaries across equipment categories.
- Compression Testing Machine:Servo-hydraulic and electromechanical frames rated 50 kN to 5,000 kN dominate quality control laboratories. China's high-speed rail megaprojects drive procurement of 3,000 kN+ capacity units for precast concrete certification.
- Concrete Testing Machine:Multi-function systems integrate flexural, split-tensile, and compression modules. Indian state highway authorities specify climate-hardened variants for remote batch plant installations.
- Mortar Mixer:Planetary mixers with programmable speed profiles ensure EN 196-1 paste consistency. Compact benchtop units serve academic materials science departments.
- Slump Test Apparatus:Standardized cone-and-rod configurations remain mandatory for field workability verification. Lightweight aluminum variants displace steel in tropical construction zones.
Compression Testing Machine leads on scale; Concrete Testing Machine leads on momentum.
End User:
Procurement authority and budget cycles create distinct purchasing patterns across customer categories.
- Construction Companies:Batch plant operators prioritize throughput automation with LIMS integration. Australian commercial testing firms now unbundle service contracts from equipment purchases.
- Quality Control Laboratories:ISO/IEC 17025 accreditation requirements drive calibration-intensive specifications. European metrology backlogs stretching 8-14 months constrain upgrade timelines.
- Academic Institutions:Materials science departments favor modular systems supporting graduate research programs. Machine-vision strain measurement systems gain traction for brittle specimen studies.
- Research Organizations:Geopolymer binder development programs demand recalibrated compression protocols. Non-standard curing kinetics require customizable load frame software.
Quality Control Laboratories anchor installed base; Research Organizations expand most quickly.
Application:
Workflow objectives determine sensor density, data granularity, and regulatory documentation requirements.
- Material Testing:Characterization of hydraulic binder properties under controlled environmental conditions. German and Japanese laboratories deploy high-resolution camera arrays for deformation tracking.
- Quality Assurance:Batch certification for commercial concrete and mortar production. ASTM C109 compliance mandates drive North American laboratory automation upgrades.
- Research and Development:Formulation screening for low-carbon cement alternatives. REACH substance restrictions on hydraulic fluids compel servo-hydraulic circuit redesigns.
- Compliance Testing:Regulatory submission documentation for building material approvals. China's SAMR enforces GB standards creating parallel certification pathways.
Quality Assurance dominates revenue concentration; Research and Development shows steepest expansion trajectory.
Technology:
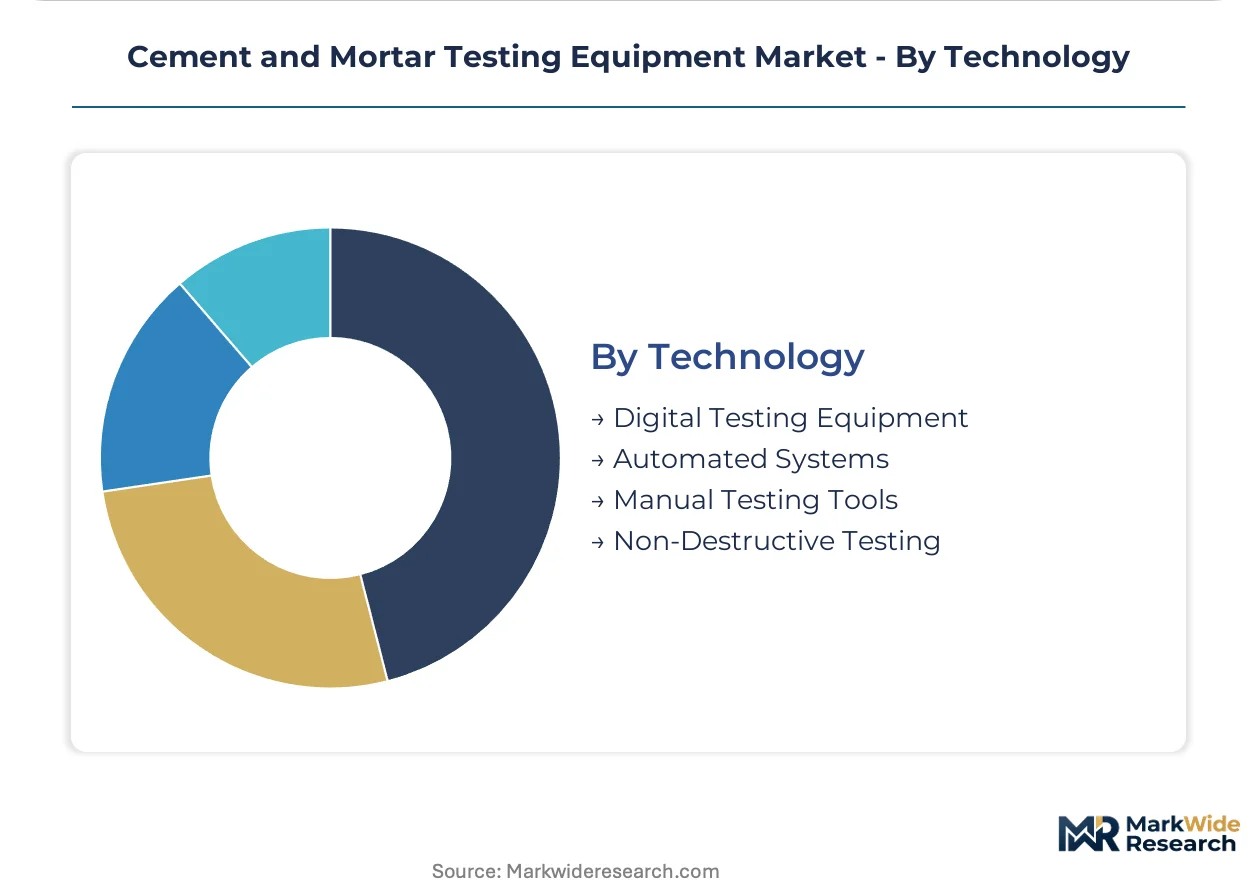
Automation depth and data architecture separate premium systems from commodity alternatives.
- Digital Testing Equipment:Embedded load cells with real-time data acquisition and cloud connectivity. ZwickRoell precision automation sets accuracy benchmarks in European markets.
- Automated Systems:Robotic specimen handling with unattended batch processing capabilities. Construction firms capture throughput gains in high-volume certification workflows.
- Manual Testing Tools:Basic mechanical apparatus for field screening and educational demonstrations. Portable rebound hammers substitute for laboratory compression in routine assessments.
- Non-Destructive Testing:Ultrasonic pulse velocity and rebound hammer techniques for in-situ structural evaluation. Bridge and tunnel owners prioritize core-extraction-free assessment protocols.
Digital Testing Equipment commands margin premiums; Non-Destructive Testing gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision engineering clusters anchor equipment manufacturing for European quality control laboratories, with Stuttgart and Munich serving as development hubs for automated compression testing systems.
United States
ASTM C109 compliance mandates drive laboratory automation upgrades across commercial testing facilities. The EPA and state-level DOT procurement rules embed quality assurance requirements into infrastructure contracts. Texas and California concentrate batch plant investments where construction firms prioritize throughput-optimized certification workflows.
China
High-speed rail and hydropower megaprojects accelerate domestic quality assurance spending on 3,000 kN+ capacity compression frames. SAMR enforces GB standards for building materials certification, creating parallel compliance pathways for equipment vendors. The Yangtze River Delta hosts manufacturing clusters supplying precision load cells to regional laboratories.
India
State highway authority contracts create procurement windows for climate-hardened testing systems in remote batch plant installations. BIS standards govern cement characterization protocols for public infrastructure projects. Gujarat and Maharashtra concentrate commercial laboratory buildouts where modular equipment specifications dominate tender requirements.
Japan
Machine-vision strain measurement systems gain traction in materials science departments evaluating brittle specimen deformation. METI funding programs support metrology infrastructure modernization for construction material certification. The Kansai region maintains specialized calibration expertise for servo-hydraulic systems facing workforce scarcity pressures.
Australia
Independent accreditation bodies capture recurring service revenue from decentralized laboratory networks unbundling maintenance contracts from equipment purchases. The country's national building code enforcement creates steady demand for field-portable non-destructive testing deployment. Queensland and Western Australia concentrate mining infrastructure projects requiring in-situ concrete assessment protocols.
Cement and Mortar Testing Equipment Market Vendor Landscape
Capacity expansion dominates the current landscape as manufacturers scale precision-machined frame production to serve infrastructure buildouts across emerging economies. The vendor base organizes around three tiers: diversified industrial conglomerates with materials testing divisions, specialized equipment fabricators focused on construction sector workflows, and regional distributors anchoring aftermarket service capabilities. Strategic archetypes include automation-first specialists capturing premium margins in laboratory certification segments, and modular system providers targeting price-sensitive public sector tenders. Geographic expansion and technology licensing represent the dominant competitive moves, with European and East Asian manufacturers establishing local assembly operations in high-growth markets.
Among precision automation specialists, ZwickRoell GmbH & Co. KG exemplifies the premium-tier archetype through its German engineering heritage and electromechanical system expertise. Humboldt Manufacturing Company occupies a position within the North American distribution-focused tier, leveraging regional service networks to anchor aftermarket revenue streams. Controls Group represents the modular-system specialist archetype, with its Italian corporate structure aligning with Mediterranean and Middle Eastern market penetration strategies. These three entities collectively illustrate how geographic origin and organizational form shape competitive positioning across compliance-driven procurement environments.
| Leading Market Players |
|---|
| Aimil Limited |
| Humboldt Manufacturing Company |
| ZwickRoell GmbH & Co. KG |
| Forney LP |
| Matest S.p.A. |
| Controls Group |
| Qualitest International Inc. |
| UTEST Material Testing Equipment Co Ltd. |
| ELE International Ltd. |
| Others |
Supply Flow & Price Mechanics
Specialty alloy steel for precision-machined load frames originates in East Asian foundries and flows through three pricing tiers before reaching quality control laboratories, with electromechanical frames commanding premium positioning over servo-hydraulic alternatives.
Pricing Analysis
Input-cost pass-through from specialty steel and precision-machined components drives pricing stratification across premium, standard, and economy tiers. Certification grade—ISO/IEC 17025 versus basic factory calibration—creates the primary price differentiation alongside after-sales service bundling. Pricing pressure stems from portable field tester substitution as lightweight digital rebound hammers displace laboratory compression machines for routine screening. Construction companies exhibit highest price sensitivity due to volume procurement cycles, while research organizations prioritize precision automation over cost minimization.
Supply Chain Analysis
Freight cost volatility from East Asian foundries to European and North American assembly plants compresses margins on high-capacity frames above 2,000 kN. Manufacturing concentrates in China, Germany, and Italy, with precision load cells sourcing from the Yangtze River Delta and Stuttgart engineering clusters. Supply chains draw from specialty alloy steel, servo-hydraulic components, and machine-vision sensor arrays. Single-source vulnerability concentrates in East Asian foundry capacity for precision-machined frame components. Distribution runs through regional distributors anchoring aftermarket service networks and direct OEM sales to megaproject contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cement and mortar testing equipment functions as a stable compounder where infrastructure modernization mandates across emerging economies generate predictable replacement cycles and compliance-driven upgrade demand.
For Market Incumbents: Extend automation-software bundling to capture recurring revenue from laboratory information management systems paired with load frames. Deepen vertical integration into precision load cell manufacturing to offset East Asian foundry concentration. Defend against portable field tester substitution by embedding cloud connectivity and real-time data acquisition as standard features. Prioritize certification investment in ISO/IEC 17025 calibration capabilities to exploit European metrology backlogs. For New Entrants and Emerging Players: Regional distributors in India's state highway authority markets offer the most penetrable channel partnership for modular, climate-hardened testing systems. Target research organization procurement for geopolymer binder development programs requiring recalibrated compression protocols. Pursue white-space in automated specimen handling for high-volume batch certification workflows. Establish go-to-market presence through third-party metrology specialists unbundling service contracts from equipment purchases in Australia's commercial testing sector. For Investors and Strategic Acquirers: Consolidation pressure builds where aging workforce cohorts concentrate specialized calibration expertise for servo-hydraulic systems in Germany and Japan. The market supports long-term viability through regulatory compliance mandates that institutionalize replacement cycles. Acquisition targets should profile as modular system specialists with established emerging market laboratory relationships. Monitor carbon-accounting convergence between EU Green Deal procurement rules and mechanical test protocols as the critical inflection signal for integrated testing-data platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| Automation-Software Bundling | LIMS integration with load frames captures recurring revenue from ASTM C109 compliance workflows. |
| Backward Integration into Load Cells | In-house production of precision sensors mitigates Yangtze River Delta supply concentration risk. |
| Climate-Hardened System Development | Modular specifications address Indian state highway authority remote batch plant requirements. |
| Machine-Vision Strain Measurement | Non-contact deformation tracking eliminates operator variance in brittle geopolymer specimen evaluation. |
| Third-Party Metrology Partnership | Independent accreditation bodies capture service revenue from Australia's unbundled laboratory networks. |
Methodological Framework
Bottom-up construction company procurement modeling reconciled against top-down equipment manufacturer production tracking forms the analytical core of this study. Primary interviews with quality control laboratory managers, construction firm procurement directors, academic materials science department heads, and aftermarket service specialists combined with secondary validation from ASTM International standards documentation, SAMR GB standards filings, BIS certification records, and SEC equipment manufacturer disclosures. Trade data from precision-machined component customs records and metrology accreditation body registries anchored supply-side triangulation.
Input-output matrices mapped compression testing machine capacity, concrete testing system specifications, mortar mixer configurations, and non-destructive testing technology adoption across end-user segments and application contexts throughout the projection horizon. Segmentation modeling captured product type, end user category, application workflow, and technology automation depth as dimensional drivers. CAGRs derived from infrastructure investment pipelines, regulatory compliance mandate timelines, and replacement cycle analysis for legacy manual systems. Forecast inputs incorporated megaproject spending trajectories, REACH substance restriction implementation schedules, and workforce demographic shifts in specialized calibration expertise.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolymer binder commercialization rates, carbon-accounting framework convergence, and East Asian specialty alloy supply disruptions. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and infrastructure procurement continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Dozer Blade Market
Construction Equipment
CNC Lathe Machine Market
Construction Equipment
Europe Excavator and Loaders Market
Construction Equipment
Global Crane Market
Construction Equipment
India Heavy Construction Equipment Rental Market
Construction Equipment
Stamping Machines Market
Construction Equipment
Wood Chipper Machines Market
Construction Equipment
Street Cleaning Machine Market
Construction Equipment
Global Wheel Aligner Equipment Market
Construction Equipment
Plasma Cutting Machine Market
Construction Equipment
Compaction Equipment Market
Construction Equipment
Drone-Based Solutions in Construction Market
Construction Equipment
Trailer Winch Market
Construction Equipment
Construction Pump Market
Construction Equipment
Global Desktop CNC Machines Market
Construction Equipment
Cold Planers Market