
 Riveting Tools Market | 2026-2036
Riveting Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Riveting Tools Market Analytics
Skilled aerospace assembly technician availability is bifurcating the Riveting Tools market between premium automated systems and cost-optimized manual alternatives. Stanley Black & Decker leverages its power tool distribution network to serve maintenance facilities across North America. GESIPA Blindniettechnik GmbH anchors European demand through specialized blind rivet technology leadership. Cherry Aerospace dominates military and commercial aviation certification requirements with legacy airframe fastening expertise.
Riveting tools are mechanical or powered devices that deform rivet bodies to create permanent mechanical joints, typically applying clamp forces between 2,000 and 10,000 pounds depending on material diameter and alloy composition. Their primary purpose is assembling sheet metal structures where welding would distort thin-gauge materials or where joint disassembly must remain impossible. Pneumatic riveters still occupy the largest installed base in heavy fabrication, though battery-operated electric units represent the fastest-expanding category as lithium-ion cell energy density improves tool portability. Smart riveting technology with force-feedback sensors and data logging is capturing margin pools in aerospace quality-critical applications where traceability mandates require digital process records.
FAA airworthiness regulations and EASA certification standards mandate traceable fastening processes in commercial aviation, directly shaping product development priorities for tool manufacturers seeking OEM qualification. OSHA workplace noise exposure limits and REACH substance restrictions on hexavalent chromium coatings are forcing design changes in pneumatic tool exhaust systems and surface treatments. Stakeholders must monitor evolving battery safety standards from IEC and UN 38.3 transport regulations as cordless electric riveters penetrate explosive atmosphere environments previously reserved for air-powered equipment.
Market Dynamics
The Riveting Tools market pivots on the tension between aerospace certification mandates requiring full process traceability and the operational pressure to reduce cycle times in high-mix, low-volume MRO environments.
Growth Catalysts
- EASA Airworthiness Directives:European aviation safety mandates are accelerating automated riveting adoption across German and French aerospace manufacturing clusters.
- Lithium-Ion Energy Density Gains:Battery chemistry improvements are extending cordless tool runtime, enabling displacement of pneumatic systems in mobile maintenance operations.
- Toulouse-Hamburg-Seattle Production Clusters:Geographic concentration of airframe assembly is creating localized demand density for specialized fastening equipment.
Market Restraints
- Lithium Carbonate Price Volatility:Battery cell input costs create margin pressure on cordless electric tool manufacturers.
- Hexavalent Chromium REACH Restrictions:European chemical regulations are forcing costly surface treatment substitutions on legacy pneumatic tool lines.
- Structural Bonding Adhesives:Advanced composite joining methods are capturing share in secondary airframe applications previously served by mechanical fastening.
Strategic Opportunities
- India Defense Aerospace Localization:The country's PLI scheme for aircraft manufacturing is opening qualification pathways for tool vendors.
- Smart Riveting Data Services:Force-feedback sensors and cloud-based process logging are creating recurring revenue streams beyond hardware sales.
- Explosive Atmosphere Certification:IEC battery safety standards are unlocking cordless tool penetration into fuel tank maintenance environments.
Industry Challenges
- Aerospace Assembly Technician Scarcity:Skilled labor shortages in Wichita and Mobile are forcing manufacturers to simplify tool interfaces and reduce training curves.
- OEM Qualification Timelines:Boeing and Airbus supplier certification cycles extend 18-24 months, freezing product iteration schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Riveting Tools Market |
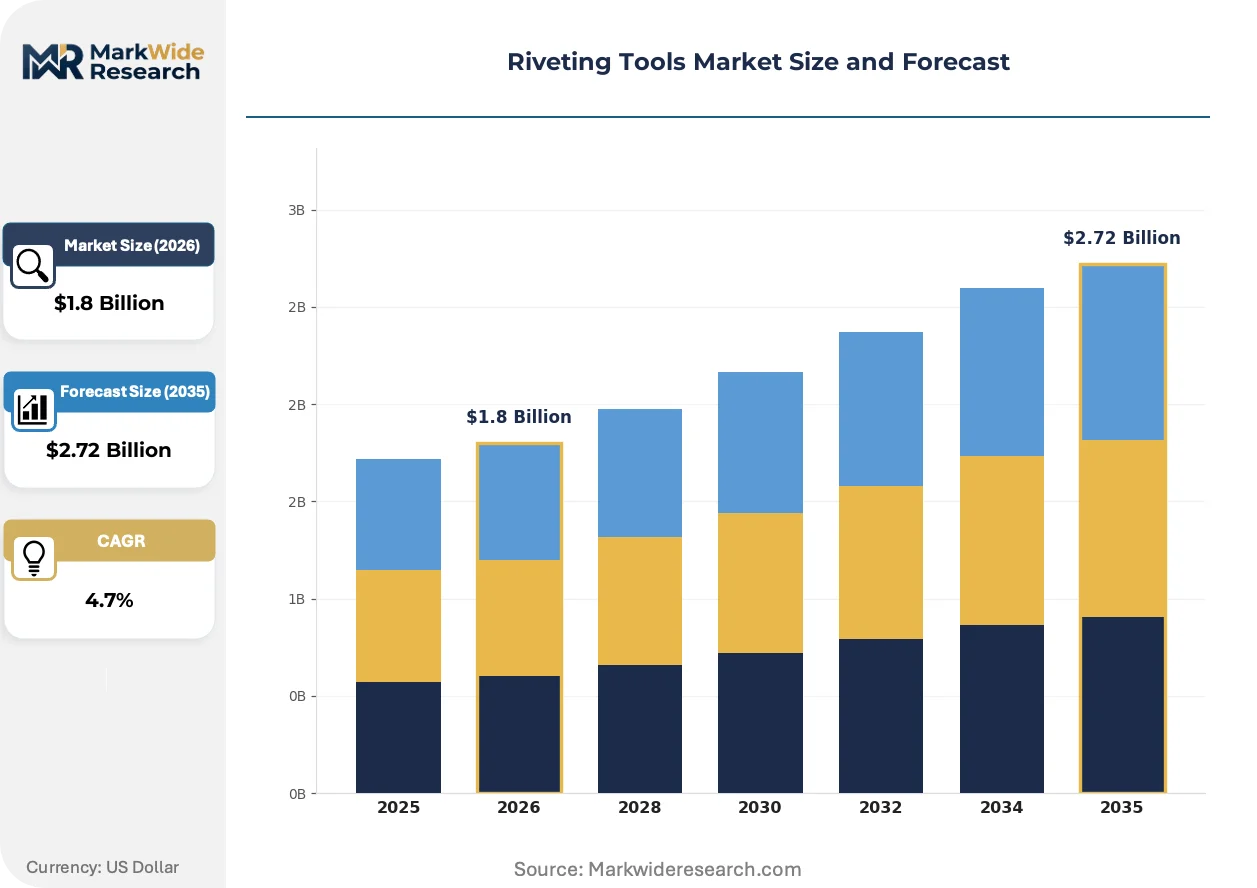
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Riveters, Pneumatic Riveters, Electric Riveters, Hydraulic Riveters Application: Aerospace Manufacturing, Automotive Assembly, Machinery Repair, Construction End User: Manufacturers, Contractors, DIY Enthusiasts, Maintenance Facilities Technology: Automatic Feeding, High-Speed Operation, Battery-Operated, Smart Riveting |
| Companies Covered | Stanley Black & Decker, GESIPA Blindniettechnik GmbH, Cherry Aerospace, Sioux Tools, Inc., Rivtec Limited, Arconic, Honsel, AVK Industrial Products, Atlas Copco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Riveting Tools Market Evolving Landscape
Digital process verification and portable power systems are rewriting competitive requirements across commercial aviation and defense maintenance segments.
Battery-operated cordless riveters are displacing pneumatic units in hangar environments where compressed air infrastructure is limited or where mobility between aircraft positions is essential. United Airlines and Japan Airlines maintenance facilities are standardizing 18V and 36V platforms to eliminate hose management and reduce trip hazards. The shift is compressing aftermarket parts revenue for legacy air tool manufacturers while expanding software-enabled service contracts.
REACH substance restrictions on hexavalent chromium coatings are forcing European tool manufacturers to redesign exhaust systems and surface treatments before 2026 compliance deadlines. The regulation is elevating compliance costs for pneumatic tool portfolios while accelerating R&D investment in ceramic and tungsten carbide alternatives. German suppliers are responding with modular tool architectures that simplify coating substitution without full platform redesign.
Maintenance facilities are unbundling tool procurement from calibration and certification services, creating standalone revenue streams for metrology providers. The disintermediation of OEM service contracts is visible across US regional airline MRO networks, where independent calibration labs are capturing recurring verification work. This pattern is fragmenting supplier relationships and compressing pricing power for integrated tool-service vendors.
Riveting Tools Market Segmentation
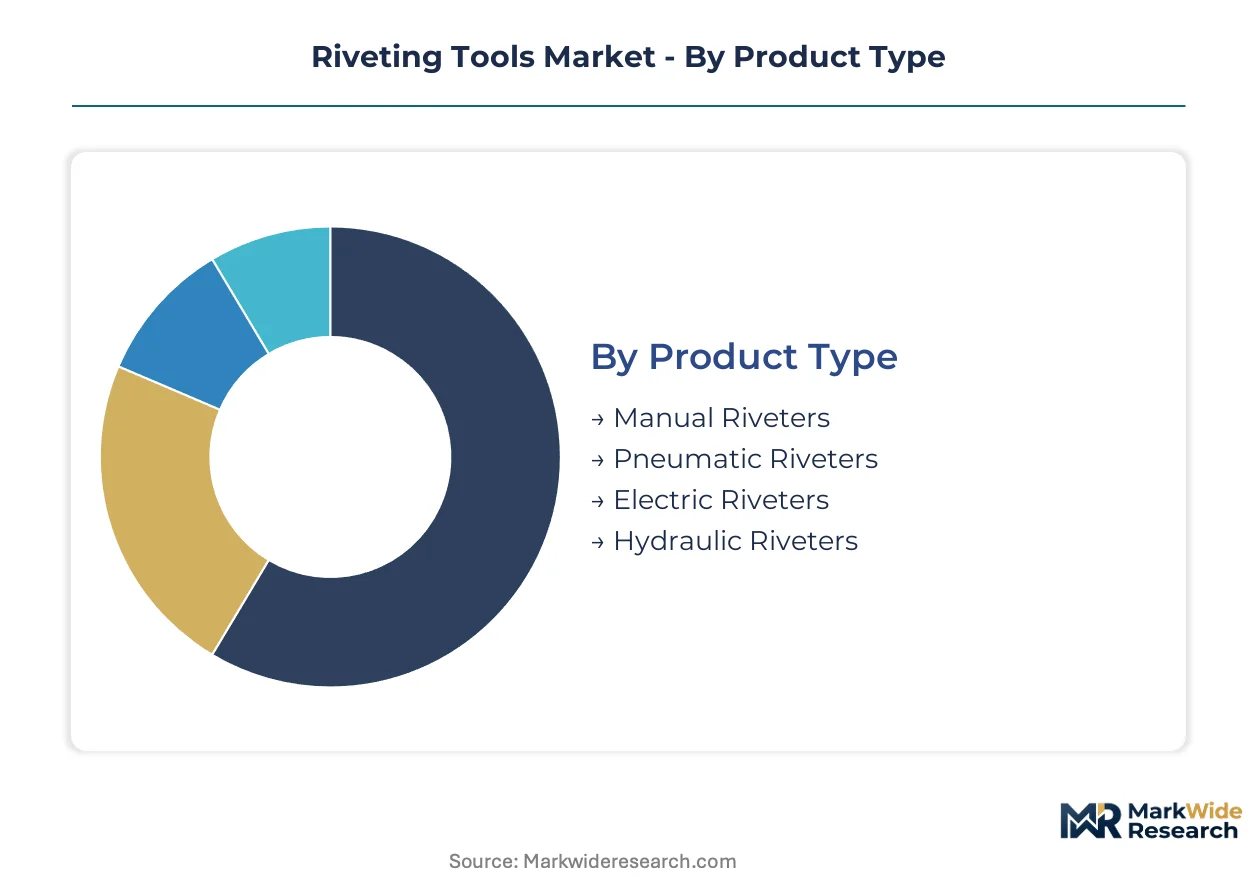
Riveting tools serve divergent performance requirements across aerospace certification environments and construction job sites. Segmentation reveals where battery substitution pressures legacy pneumatic installed bases and where smart technology commands premium positioning.
Product Type:
Pneumatic riveters face the most acute substitution threat as cordless electric platforms capture mobility-sensitive applications.
- Manual Riveters:Hand-operated lever and squeeze tools apply mechanical force through compound linkages for soft aluminum rivets up to 3/16 inch diameter. Demand persists in Wichita and Mobile MRO facilities where technician scarcity forces simplified training curves and reduced capital outlay.
- Pneumatic Riveters:Compressed-air systems deliver 2,000-10,000 pounds clamp force through piston-driven hammers, dominating heavy-gauge steel fabrication. OSHA noise exposure limits and hose management burdens are accelerating displacement in United Airlines hangar environments.
- Electric Riveters:Brushless motor systems powered by 18V and 36V lithium-ion platforms eliminate compressed air infrastructure. Japan Airlines maintenance facilities are standardizing these for inter-aircraft mobility.
- Hydraulic Riveters:Fluid-pressure systems generate extreme force for large-diameter structural rivets in shipbuilding and bridge construction. Port infrastructure projects in Hamburg sustain specialized demand.
Pneumatic riveters retain volume leadership; electric riveters hold the steepest expansion curve.
Application:
Margin structures diverge sharply between certification-mandated aerospace workflows and price-sensitive construction procurement.
- Aerospace Manufacturing:FAA and EASA traceability requirements demand force-feedback sensors and digital process logging for every fastener. Toulouse and Seattle assembly lines specify smart riveting platforms with cloud-based verification records.
- Automotive Assembly:High-volume chassis and body shop applications favor pneumatic speed over precision measurement. Battery-operated units are penetrating final trim areas where flexibility outweighs cycle time.
- Machinery Repair:Field service environments prioritize portable power and rapid bit changeover for mixed fastener populations. Independent MRO contractors drive cordless adoption here.
- Construction:Structural steel and metal roofing applications emphasize durability and dust resistance over precision. Manual and basic pneumatic tools dominate this price-compressed segment.
Aerospace manufacturing commands the highest value per unit; automotive assembly generates the largest absolute volume.
End User:
Procurement sophistication separates specification-driven manufacturers from transaction-oriented DIY purchasers.
- Manufacturers:Boeing and Airbus tier-one suppliers operate 18-24 month OEM qualification cycles that freeze supplier relationships. These buyers bundle tool procurement with calibration service contracts.
- Contractors:Construction and installation trades prioritize acquisition cost over lifecycle value, purchasing through distributor channels with limited technical support.
- DIY Enthusiasts:Consumer retail segments favor compact manual kits and entry-level cordless platforms for home metalworking projects.
- Maintenance Facilities:US regional airline MRO networks are disintermediating OEM service contracts, sourcing independent calibration verification and fragmenting supplier relationships.
Maintenance facilities are expanding fastest as a buyer category; manufacturers retain the most concentrated purchasing power.
Technology:
Intelligence layers are rewriting competitive requirements in quality-critical environments while basic automation spreads through cost-driven segments.
- Automatic Feeding:Magazine-fed systems reduce operator fatigue in high-volume repetitive applications. Automotive body shops specify these for door and panel assembly lines.
- High-Speed Operation:Rapid-cycle pneumatic mechanisms achieve sub-second rivet setting for production throughput maximization. These dominate Tier 1 supplier plants near Detroit.
- Battery-Operated:Lithium-ion chemistry improvements extend runtime beyond single-shift operations. REACH substance restrictions on hexavalent chromium are accelerating European adoption.
- Smart Riveting:Force-feedback sensors and data logging create digital process records for FAA airworthiness compliance. This technology captures margin pools in aerospace quality-critical applications.
Battery-operated platforms are climbing the fastest; smart riveting holds the premium positioning trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA airworthiness regulations anchor North American demand, while EASA directives and Japan's METI standards shape procurement across other major aerospace manufacturing bases.
United States
Boeing's 737 MAX production recovery and United Airlines' maintenance facility standardization drive cordless tool adoption. OSHA workplace noise exposure limits accelerate pneumatic displacement in Wichita and Mobile MRO networks. Seattle-Tacoma aerospace clusters concentrate smart riveting platform demand for digital process verification.
Germany
Airbus Hamburg assembly expansion and defense aerospace localization sustain premium automated system demand. REACH substance restrictions on hexavalent chromium coatings force surface treatment redesigns before 2026 deadlines. Bavarian tool manufacturers respond with modular architectures simplifying coating substitution.
France
Toulouse airframe manufacturing concentration creates localized demand density for force-feedback sensor platforms. EASA airworthiness directives mandate traceable fastening processes across Airbus supplier networks. Auvergne-Rhône-Alpes precision engineering clusters supply calibration and certification services.
Japan
Japan Airlines maintenance facilities standardize 18V and 36V battery platforms to eliminate hose management hazards. METI battery safety standards align with IEC and UN 38.3 transport regulations for explosive atmosphere penetration. Nagoya aerospace manufacturing corridors anchor regional procurement.
India
Defense aerospace localization under the PLI scheme opens qualification pathways for foreign tool vendors. DGFT import substitution policies pressure domestic manufacturing capability development. Bangalore and Hyderabad emerging aviation clusters generate initial smart riveting specification demand.
Riveting Tools Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with market structure reflecting aerospace certification barriers and maintenance facility fragmentation. Tier-one aerospace suppliers concentrate purchasing power through 18-24 month OEM qualification cycles. Three archetypes dominate: diversified industrial conglomerates with power tool distribution networks, European blind rivet technology specialists, and legacy airframe fastening certification holders. Competitive moves center on battery platform standardization and disintermediation of bundled service contracts.
Within the specialist tier, GESIPA Blindniettechnik GmbH exemplifies European blind rivet technology leadership, while Cherry Aerospace occupies a position tied to military and commercial aviation certification requirements. Stanley Black & Decker represents diversified industrial scale with maintenance facility channel access across North America.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| GESIPA Blindniettechnik GmbH |
| Cherry Aerospace |
| Sioux Tools, Inc. |
| Rivtec Limited |
| Arconic |
| Honsel |
| AVK Industrial Products |
| Atlas Copco |
| Others |
Value Network & Pricing Analysis
Scale economies in lithium-ion cell manufacturing compress cordless tool price floors while concentrating supply leverage among battery chemistry specialists in Japan and South Korea. This dynamic elevates procurement power for aerospace OEMs bundling smart riveting platforms with calibration services, forcing tier-two pneumatic vendors toward commodity positioning.
Pricing Analysis
Geographic price spreads between Toulouse aerospace clusters and US regional airline MRO networks exceed standard manufacturing premiums. Three-tier pricing structure across aerospace-certified smart systems, industrial-grade electric platforms, and manual tool alternatives dominates procurement. Price differentiation hinges on EASA traceability certification and force-feedback sensor integration. Pricing pressure stems from lithium carbonate input volatility squeezing cordless electric margins. Contractors in construction segments exhibit highest price sensitivity; Boeing tier-one suppliers show lowest.
Supply Chain Analysis
Just-in-time inventory strategies prevail among German and French aerospace manufacturers synchronizing tool delivery with airframe assembly sequences. Component sourcing concentrates in Germany, Japan, and China for precision motors, sensor arrays, and battery cells. Raw material dependencies include lithium carbonate, tungsten carbide for wear surfaces, and rare-earth magnets for brushless motors. Single-source vulnerability in battery cell supply creates structural risk. Distribution runs through authorized aerospace distributors and direct OEM procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as cordless electric platforms displace pneumatic installed bases in maintenance environments. Lithium-ion energy density improvements accelerate penetration timelines.
For Market Incumbents: Fortify certification moats by accelerating EASA and FAA qualification cycles for smart riveting platforms. Deepen backward integration into sensor manufacturing to offset margin pressure from battery cell suppliers. Counter structural bonding adhesive substitution threats by embedding force-feedback data services into long-term service contracts. For New Entrants and Emerging Players: Anchor in India defense aerospace localization under PLI scheme incentives, where DGFT import substitution creates qualification pathways absent entrenched supplier relationships. Target US regional airline MRO networks disintermediating bundled OEM service contracts. Pursue calibration and certification service bundling as primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors smart riveting specialists with aerospace certification assets and recurring software revenue components. Long-term viability over a multi-year horizon rests on data service monetization and explosive atmosphere certification expansion. Acquisition target archetype: European blind rivet technology holders with modular tool architectures. Monitor IEC battery safety standard adoption in fuel tank maintenance as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Riveting Data Service Launch | Cloud-based process logging creates recurring revenue streams beyond hardware for EASA compliance. |
| Explosive Atmosphere Certification | IEC battery safety standards unlock cordless tool penetration into fuel tank maintenance environments. |
| Backward Integration into Sensors | In-house production of force-feedback arrays reduces dependency on Japanese precision component suppliers. |
| India PLI Scheme Localization | Domestic manufacturing qualification opens defense aerospace procurement pathways under DGFT policy. |
| Calibration Service Unbundling | Independent metrology verification captures recurring revenue from US regional airline MRO fragmentation. |
Research Methodology
Initial hypotheses were tested against primary input from aerospace assembly technicians, MRO facility maintenance directors, OEM procurement managers, and calibration service providers and refined through secondary validation. Primary fieldwork encompassed facility assessments in Toulouse, Hamburg, Seattle, and Nagoya aerospace clusters. Secondary sources included FAA airworthiness directives, EASA certification databases, OSHA workplace safety filings, and REACH substance restriction compliance records. Bottom-up demand modeling triangulated against top-down industry capacity estimates.
Variance decomposition across product type, application, end user, and technology segments structured the analytical framework. Segmentation dimensions encompassed manual, pneumatic, electric, and hydraulic tool categories; aerospace, automotive, machinery repair, and construction applications; manufacturers, contractors, DIY enthusiasts, and maintenance facilities as end users; and automatic feeding, high-speed operation, battery-operated, and smart riveting technologies. CAGRs derived from installed base substitution rates and OEM qualification pipeline visibility. Forecast inputs included lithium-ion energy density improvement curves and EASA airworthiness directive implementation timelines.
Material uncertainties — lithium carbonate price volatility, REACH compliance deadline acceleration, and structural bonding adhesive penetration rates — sit outside the modeled envelope. Forecasts reflect assumptions regarding cordless tool runtime improvement and aerospace technician training curve compression. Revision becomes warranted when smart riveting platform adoption in commercial aviation crosses certification threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Shape Moulding Machines Market
Tools
Digital Levels Market
Tools
Industrial Ladder Market
Tools
Striking Tools Market
Tools
Stationary Wood Planer Market
Tools
Screwdriver Market
Tools
Nail Gun Market
Tools
Tension Tester Market
Tools
Woodworking CNC Tools Market
Tools
Wood Floor Grinding Machine Market
Tools
Construction Anchors Market
Tools
Tool Boxes Market
Tools
Crimping Tool Market
Tools
Power Press Machines Market
Tools
Portable Grinders Market
Tools
Allen Key Market