
 Portable Rebar Bending Machine Market | 2026-2036
Portable Rebar Bending Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Rebar Bending Machine Market Insights
Small-scale contractors are reorganizing portable rebar bending machine procurement patterns as infrastructure mini-contracts proliferate across developing economies. Schnell Spa leverages its Italian engineering heritage to dominate high-precision electric bending systems for European bridge projects. Thorson Industries anchors North American distribution through fabricator-direct channel control. Chiao Sheng Machinery Co., Ltd. competes on manufacturing scale across hydraulic and battery-operated lines for Asian roadworks demand.
A portable rebar bending machine is a mobile, jobsite-deployable device that cold-forms steel reinforcing bars through mechanical force application, typically achieving bend angles from zero to one hundred eighty degrees at diameters ranging from six to forty millimeters depending on power source and drive configuration. Its primary industrial purpose is to eliminate prefabrication logistics by enabling on-site custom bending for concrete reinforcement in structural, civil, and residential construction. Electric and hydraulic product types command the widest installed base due to torque reliability across heavy rebar grades, while battery-operated configurations represent the fastest-growing segment as cordless lithium-ion platforms displace generator-dependent workflows on remote tunnel projects and urban infill sites where emissions restrictions tighten.
OSHA governs operator safety and machine guarding standards for portable rebar bending equipment deployed on US construction sites, while the EU Machinery Directive and CE marking framework mandate electromagnetic compatibility and emergency-stop protocols for machines sold across European member states. India's BIS certification requirements for construction machinery create compliance thresholds that filter import competition and shape local assembly strategies. Stakeholders must monitor how evolving carbon-border adjustments and battery-recycling mandates in key manufacturing jurisdictions reshape total cost of ownership calculations across power-source categories.
Market Dynamics
Battery-operated portable rebar bending machines are fragmenting procurement hierarchies as small-scale contractors bypass rental yards and purchase direct, compressing traditional distribution tiers while India's infrastructure corridor and Southeast Asian roadworks absorb capacity expansion.
Growth Catalysts
- Servo motor integration:Precision torque control enables zero-to-one-hundred-eighty-degree bends on six-to-forty-millimeter rebar without hydraulic fluid maintenance, reducing jobsite downtime for tunnel contractors.
- India's BIS certification thresholds:Local assembly requirements filter import competition and create protected demand basins for domestic manufacturers serving bridge and highway projects.
- Southeast Asian roadworks concentration:National infrastructure budgets in Vietnam, Indonesia, and the Philippines concentrate equipment demand in transport corridors where mobility and emissions compliance outweigh capital cost sensitivity.
Market Restraints
- Lithium-ion cell cost volatility:Battery pack input expenses fluctuate with cobalt and nickel spot markets, compressing margins on cordless variants priced against established hydraulic lines.
- European CE marking electromagnetic compatibility protocols:Emergency-stop and shielding requirements add certification timeline friction for Asian exporters targeting EU bridge contractors.
- Manual rebar bending persistence:Low-wage labor pools in informal construction sectors resist mechanization where project scale falls below equipment payback thresholds.
Strategic Opportunities
- India's state-level urban infill mandates:Municipal densification policies in Maharashtra and Karnataka generate mini-contract volumes suited to battery-operated machine footprints where generator bans apply.
- Rental-to-own channel innovation:Equipment-as-service platforms bypass traditional fabricator-direct distribution, capturing contractors with cyclical project pipelines.
- OSHA operator safety standard convergence:US machine guarding requirements create specification templates that premium manufacturers export to Gulf Cooperation Council markets lacking indigenous frameworks.
Industry Challenges
- Servomotor calibration skill scarcity:Field technicians capable of diagnosing encoder drift and torque feedback loops command wage premiums that inflate service cost structures.
- Battery recycling compliance timelines:Emerging producer-responsibility mandates in manufacturing jurisdictions require reverse logistics infrastructure absent from current distribution networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Rebar Bending Machine Market |
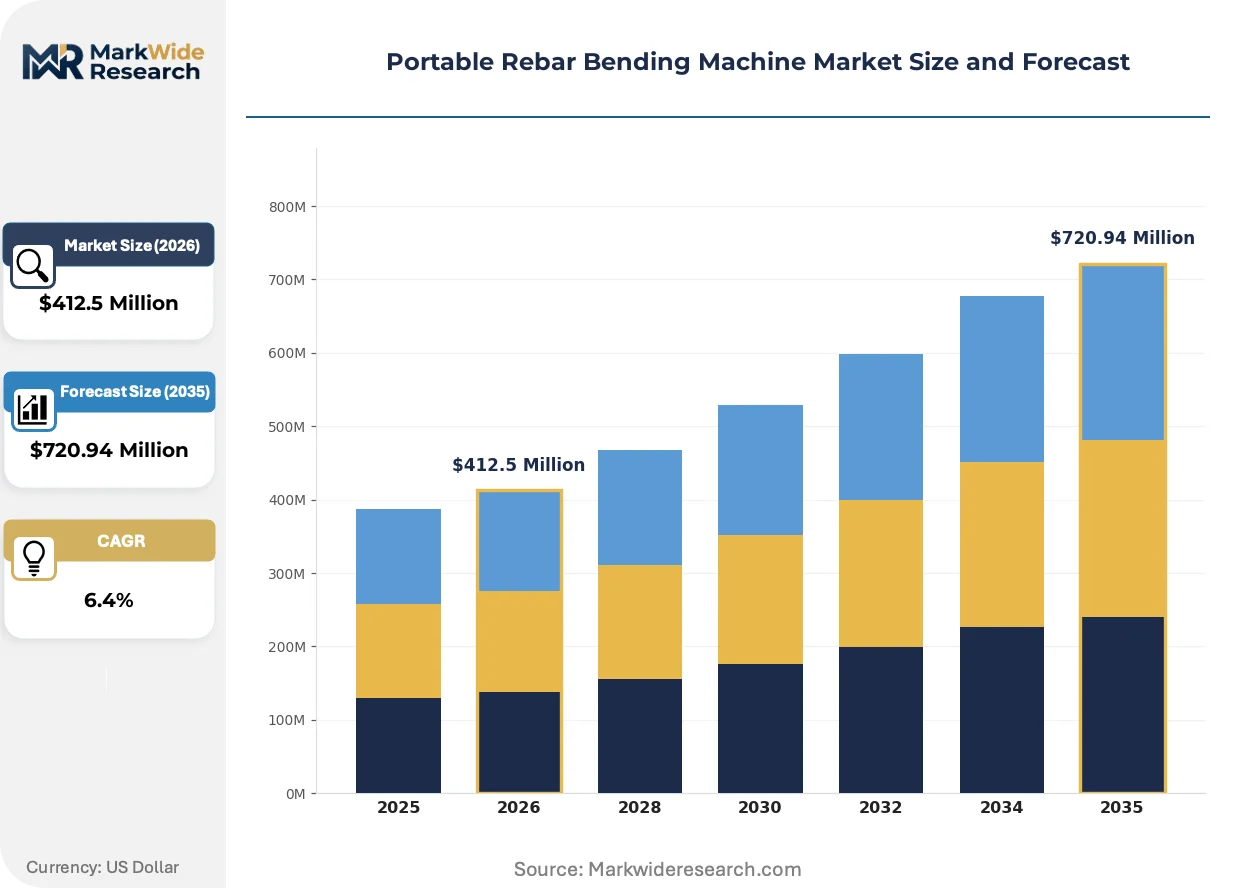
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Hydraulic, Manual, Pneumatic, Battery-operated Technology: Servo Motor, Gear Driven, Worm Gear, Chain Drive, Rack & Pinion Application: Bridge Construction, Roadworks, Tunnel Projects, Residential Construction, Commercial Projects End User: Contractors, Infrastructure Developers, Construction Consultants, Engineering Firms, Fabricators |
| Companies Covered | Schnell Spa, Thorson Industries, Chiao Sheng Machinery Co., Ltd., KRB Machinery, Eurobend, Baileigh Industrial Holdings LLC, SOCO Machinery Co., Ltd., Van Sant Enterprises, Inc., Ellsen Machinery Equipment Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Rebar Bending Machine Market Trends and Innovations
Cordless lithium-ion platforms are compressing generator-dependent workflows while regulatory emissions frameworks and contractor purchasing autonomy reshape competitive terrain across power source categories.
Servo-driven electric bending systems deliver precision torque control without hydraulic fluid contamination risks. Tunnel contractors in emissions-restricted urban cores adopt these configurations fastest. The technology is decomposing the historical hydraulic-electric duopoly by eliminating maintenance-intensive power transmission components.
The EU Machinery Directive mandates electromagnetic compatibility and emergency-stop protocols for machines sold across member states. European bridge projects now specify CE-marked equipment exclusively, filtering non-compliant imports. Asian manufacturers respond by establishing EU-based assembly nodes to bypass certification friction.
Small-scale contractors now purchase equipment direct rather than routing through rental intermediaries. Fabricator-direct channel control weakens as digital procurement platforms aggregate demand. This pattern concentrates in India's infrastructure corridor where mini-contract proliferation rewards asset ownership over rental flexibility.
Portable Rebar Bending Machine Market Segmentation
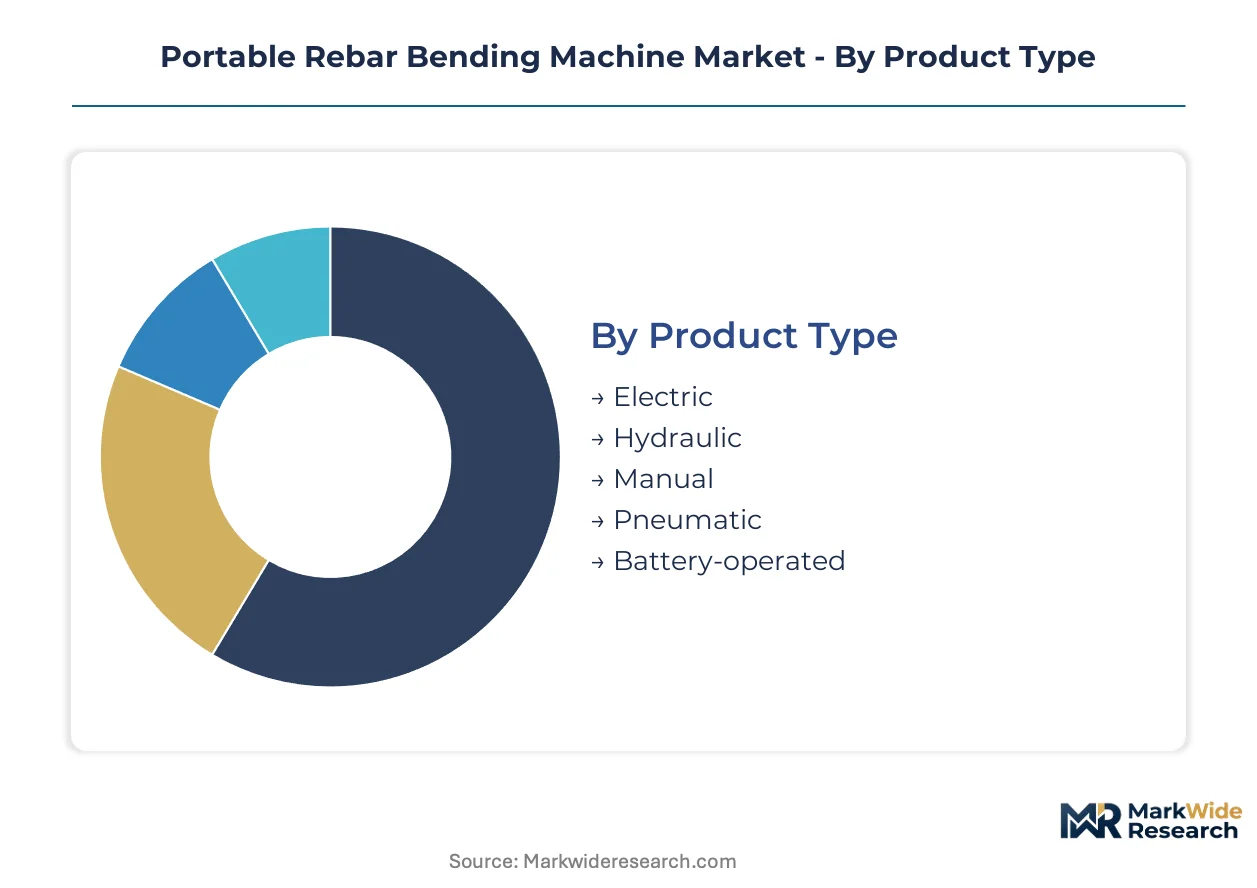
Portable rebar bending machine procurement channels fragment sharply across power-source categories. Small-scale contractors direct-buy battery-operated units while rental yards retain hydraulic and electric fleet dominance. Distribution economics and jobsite mobility requirements determine which segments bypass traditional intermediaries.
Product Type:
Channel control varies dramatically by power source. Electric and hydraulic machines flow through fabricator-direct and rental networks. Battery-operated variants increasingly ship direct to contractor fleets. Manual units penetrate informal construction sectors where capital constraints block mechanization.
- Electric:Mains-powered units deliver consistent torque for six-to-forty-millimeter rebar across bridge construction sites. Demand concentrates in European infrastructure corridors where emissions restrictions and grid reliability support electrified workflows. Schnell Spa dominates specification lists for precision electric systems in Italian and German bridge projects.
- Battery-operated:Lithium-ion platforms eliminate generator dependency for tunnel contractors working urban infill zones with emissions bans. Southeast Asian roadworks in Vietnam and Indonesia absorb capacity fastest where generator transport costs erode project margins.
- Hydraulic:Fluid-power systems maintain torque superiority for heavy-grade rebar in high-volume fabrication yards.
- Manual:Lever-operated units persist in India's informal construction sectors below mechanization payback thresholds.
- Pneumatic:Compressed-air configurations serve specialized mining and underground applications with existing compressor infrastructure.
Electric dominates installed base. Battery-operated is where expansion concentrates.
Technology:
Cost tier stratification separates precision servo systems from commodity mechanical drives. Servo motor integration commands premium pricing for zero-maintenance torque control. Gear-driven and chain-drive alternatives compete on first-cost for price-sensitive Asian roadworks procurement.
- Servo Motor:Closed-loop torque control eliminates hydraulic fluid maintenance and enables programmable bend sequences. Tunnel contractors in emissions-restricted urban cores adopt fastest where precision and reliability outweigh capital cost premiums.
- Gear Driven:Mechanical power transmission delivers cost-efficient bending for standard rebar grades. India's infrastructure corridor absorbs volume where BIS certification requirements filter import competition and protect domestic assembly operations.
- Worm Gear:Self-locking configurations prevent kickback in manual override scenarios.
- Chain Drive:Simplified maintenance appeals to remote site operators with limited technical support access.
- Rack & Pinion:Linear motion conversion serves specialized angle-forming applications in precast fabrication.
Servo motor systems capture premium specification share. Gear driven maintains volume leadership in emerging markets.
Application:
Customer type determines procurement autonomy and channel selection. Infrastructure developers centralize fleet purchasing through tender processes. Residential contractors exercise direct-buy discretion for single-project equipment deployment.
- Bridge Construction:Large-scale reinforced concrete structures demand high-precision bending for complex rebar cages. European projects specify CE-marked servo-electric systems exclusively, filtering non-compliant Asian imports through electromagnetic compatibility mandates.
- Roadworks:Linear infrastructure projects prioritize equipment mobility across dispersed work fronts. Southeast Asian national highway programs in the Philippines and Indonesia concentrate demand where battery-operated footprints suit generator-restricted corridor construction.
- Tunnel Projects:Confined underground environments with ventilation constraints favor zero-emission power sources.
- Residential Construction:Smaller-scale concrete work sustains manual and light-electric machine demand.
- Commercial Projects:Mid-rise development schedules support rental channel economics for intermittent rebar bending needs.
Bridge construction commands specification premium. Roadworks is climbing the fastest.
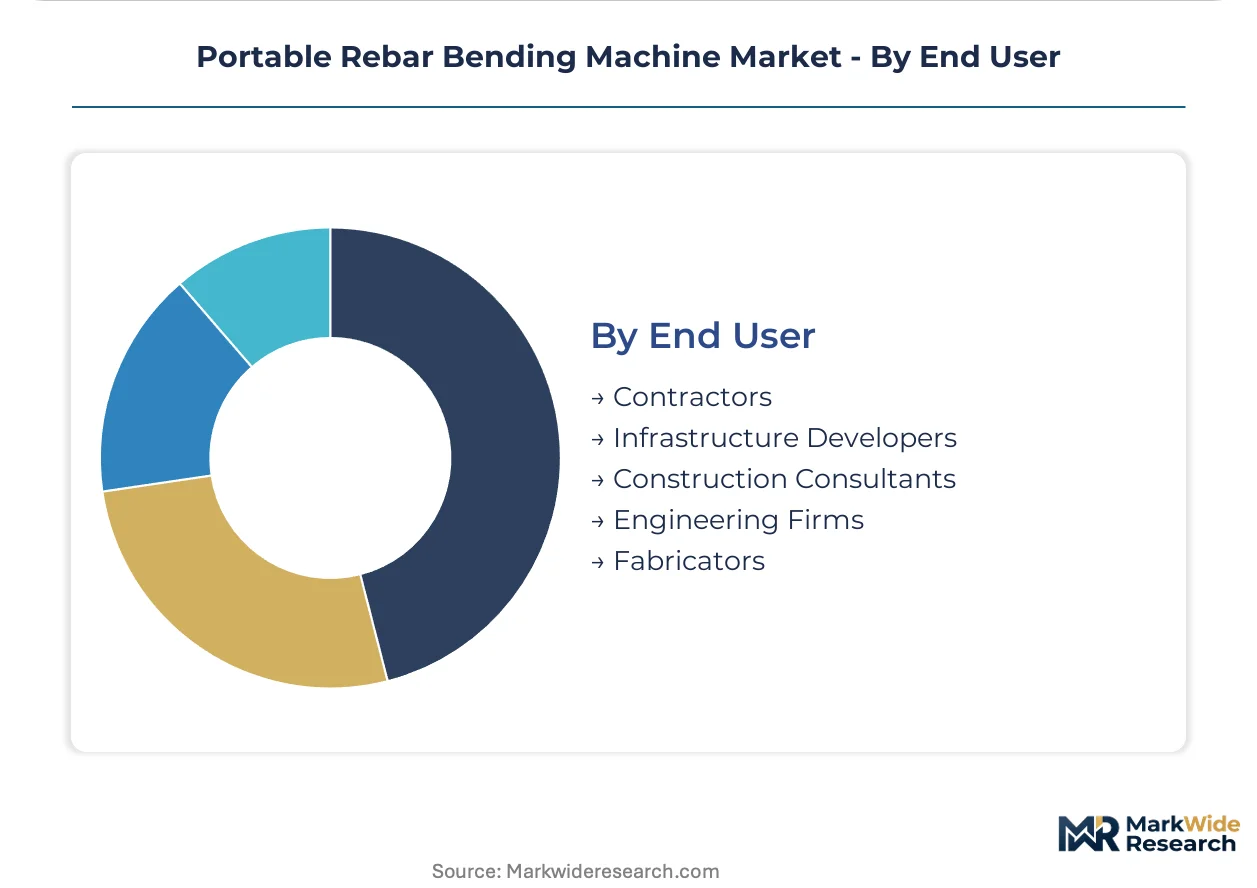
End User:
Volume concentration and margin structure diverge across buyer categories. Contractors fragment into fleet-owning and rental-dependent segments. Engineering firms influence specification but rarely take equipment title.
- Contractors:Direct equipment ownership proliferates among small-scale operators in India's infrastructure corridor. Maharashtra and Karnataka municipal densification policies generate mini-contract volumes suited to portable battery-operated footprints where generator bans apply.
- Infrastructure Developers:Centralized procurement through state-level tender processes in Vietnam and the Philippines concentrates fleet purchasing power. National budget allocations determine annual equipment absorption capacity.
- Construction Consultants:Specification influence without procurement authority shapes vendor qualification requirements.
- Engineering Firms:Design-phase involvement determines torque and precision requirements for contractor equipment selection.
- Fabricators:Off-site rebar processing yards maintain hydraulic system dominance for high-throughput production.
Contractors drive unit volume growth. Infrastructure developers concentrate capital deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Small-scale contractors concentrate equipment procurement across India's infrastructure corridor and Southeast Asian roadworks, while European bridge specifications filter import competition through electromagnetic compatibility mandates. Battery-operated variants displace generator-dependent workflows fastest in emissions-restricted urban cores.
India
Maharashtra and Karnataka municipal densification policies generate mini-contract volumes suited to portable battery-operated footprints where generator bans apply. BIS certification requirements for construction machinery create compliance thresholds that filter import competition and shape local assembly strategies. The Mumbai-Pune expressway corridor and Bangalore metro expansion concentrate contractor fleet purchasing.
Vietnam
National highway programs absorb battery-operated machine capacity where generator transport costs erode project margins on dispersed work fronts. Ministry of Transport infrastructure allocations determine annual equipment absorption through state-level tender processes. The North-South Expressway construction zone anchors procurement concentration for mobility-optimized equipment.
Germany
Bridge construction specifications mandate CE-marked servo-electric systems exclusively, filtering non-compliant Asian imports through electromagnetic compatibility protocols. The EU Machinery Directive emergency-stop and shielding requirements add certification timeline friction for exporters. The Rhine-Ruhr industrial corridor concentrates precision bending demand for reinforced concrete infrastructure.
United States
OSHA operator safety and machine guarding standards govern jobsite deployment, creating specification templates that premium manufacturers export to adjacent markets. Tunnel contractors in emissions-restricted urban cores adopt zero-emission power sources fastest. The Northeast Corridor transit expansion and Texas highway programs concentrate fleet purchasing.
Indonesia
National infrastructure budgets concentrate equipment demand in transport corridors where mobility and emissions compliance outweigh capital cost sensitivity. Ministry of Public Works and Housing allocations drive annual absorption capacity through centralized procurement. The Java toll road network and Trans-Sumatra highway anchor regional demand clusters.
Portable Rebar Bending Machine Market Competitive Landscape
Player mix skews toward mid-scale machinery specialists with Italian engineering heritage and Asian manufacturing scale. Market structure remains fragmented across hydraulic, electric, and battery-operated power-source categories, with no single archetype commanding dominant share. Strategic positioning splits between precision-engineered European specialists and volume-oriented Asian fabricators. Competitive moves concentrate on certification compliance investments and rental-to-own channel innovation.
Within the European precision-tier, Schnell Spa exemplifies Italian engineering heritage positioning for high-specification bridge projects. Thorson Industries anchors North American distribution presence through fabricator-direct channel structures. Chiao Sheng Machinery Co., Ltd. occupies the scale-driven manufacturing archetype across hydraulic and battery-operated lines for Asian roadworks demand.
| Leading Market Players |
|---|
| Schnell Spa |
| Thorson Industries |
| Chiao Sheng Machinery Co., Ltd. |
| KRB Machinery |
| Eurobend |
| Baileigh Industrial Holdings LLC |
| SOCO Machinery Co., Ltd. |
| Van Sant Enterprises, Inc. |
| Ellsen Machinery Equipment Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day lead times for servo motor controllers and lithium-ion battery packs concentrate pricing power among integrated European and East Asian manufacturers, while spot-market volatility in cobalt and nickel feeds back into cordless variant cost structures across procurement tiers.
Pricing Analysis
Servo-electric systems command forty-to-sixty percent premiums over hydraulic equivalents, while battery-operated platforms price fifteen-to-twenty-five percent above mains-powered electric units due to power electronics and cell pack costs. Three-tier pricing structure across precision servo, standard gear-driven, and economy manual levels stratifies by certification grade and torque precision. Cost compression in battery-operated tiers is intensifying because lithium-ion cell spot markets swing with cobalt supply disruptions. Small-scale contractors in India's infrastructure corridor exhibit highest price sensitivity, while European bridge developers prioritize CE-marked specification compliance over capital cost.
Supply Chain Analysis
China and Taiwan anchor controller board and servo motor production, while South Korea and Japan supply precision encoders and lithium-ion cells for cordless platforms. Manufacturing draws from steel forging in India, electronic subassemblies in East Asia, and hydraulic components from Italian specialist suppliers. Single-source vulnerability concentrates in rare-earth magnet supply for high-torque servo motors. Distribution runs through fabricator-direct channels for electric and hydraulic fleets, with battery-operated variants increasingly shipping direct to contractor fleets via digital procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service contracts and calibration support packages are expanding faster than hardware unit sales as servo motor complexity drives recurring technician dependency across contractor fleets.
For Market Incumbents: Consolidate certification infrastructure investments to defend against Asian exporters establishing EU assembly nodes for CE marking compliance. Lock in fabricator-direct channel control through exclusive service agreements that bundle calibration support with equipment leases. Battery recycling reverse logistics represents the critical capability gap where early infrastructure investment captures regulatory-compliant positioning ahead of producer-responsibility mandates. For New Entrants and Emerging Players: Field technician training and certification programs represent the service-layer gap where incumbents under-serve small-scale contractors lacking servo diagnostic capabilities. Target India's state-level urban infill corridors where BIS certification barriers filter import competition and mini-contract proliferation rewards localized support networks. Pursue rental-to-own platform partnerships that aggregate cyclical contractor demand without requiring traditional distribution tier penetration. For Investors and Strategic Acquirers: Long-term, this sits as a servitization play because hardware margins compress while recurring service revenue streams deepen customer switching costs. Acquisition candidates with captive technician networks and regional certification authority command premium positioning. Watch battery recycling compliance timeline acceleration as the inflection signal that reshapes total cost of ownership calculations and competitive moat structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Motor Production | Captive torque control supply insulates Schnell Spa and precision-tier European specialists from encoder lead-time volatility. |
| Battery Recycling Infrastructure Buildout | Reverse logistics networks satisfy emerging producer-responsibility mandates in EU and Indian manufacturing jurisdictions. |
| CE Marking Fast-Track Certification | Expedited electromagnetic compliance timelines unlock European bridge project specifications for Asian manufacturers. |
| Rental-to-Own Platform Launch | Equipment-as-service models capture small-scale contractors in Maharashtra and Karnataka with cyclical project pipelines. |
| Field Technician Certification Program | Encoder calibration expertise commands wage premiums that deepen customer dependency and service contract attach rates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade databases, BIS certification registries, and EU Machinery Directive compliance filings, combining structured interviews with equipment procurement managers at infrastructure developers, maintenance directors at fabrication yards, and aftermarket service heads at regional distributors. Bottom-up unit shipment tracking across power-source categories triangulates against top-down infrastructure budget allocation analysis.
Segmentation dimensions modeled span power source technology, drive mechanism architecture, application intensity tier, and end-user procurement autonomy across the projection horizon. CAGRs derive from regression analysis against named infrastructure project pipelines and equipment replacement cycles. Forecast inputs incorporate BIS certification timeline friction, lithium-ion cell cost curves, and municipal densification policy enforcement rates in Indian states.
Forecasts assume regulatory continuity in EU Machinery Directive electromagnetic compatibility protocols and Indian BIS construction machinery standards; material policy shifts would require re-modeling. Recalibration cycles align with material shifts in infrastructure budget allocations, battery chemistry cost trajectories, and certification compliance enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Thailand Construction Equipment Market
Construction Equipment
Philippines Construction Equipment Market
Construction Equipment
GCC Construction Machinery Market
Construction Equipment
Heavy Construction Equipment Rental Market
Construction Equipment
Cutting and Bending Machine Market
Construction Equipment
Smelting Furnace Equipment Market
Construction Equipment
China Heavy Construction Equipment Rental Market
Construction Equipment
Construction Wearable Technology Market
Construction Equipment
ASEAN Construction Equipment Rental Market
Construction Equipment
Global Hydraulic Hammer Market
Construction Equipment
Europe Stud Welding Machine Market
Construction Equipment
Construction Equipment Rental Market
Construction Equipment
Pressure Vessel Market
Construction Equipment
Asia Pacific Construction Equipment Market
Construction Equipment
Truck Mounted Knuckle Boom Cranes Market
Construction Equipment
Europe Road Marking Machine Market