
 Rubber Track Pads for Construction Machinery Market | 2026-2036
Rubber Track Pads for Construction Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Rubber Track Pads for Construction Machinery Market Insights
Asset-light leasing and pay-per-use financing is rewriting competitive dynamics for rubber track pad procurement, enabling mid-tier contractors to access premium crawler fleets without capital deployment. Bridgestone Corporation leverages its integrated rubber compounding facilities to control raw material quality from polymer sourcing to finished pad curing. McLaren Industries specializes in aftermarket replacement programs, sustaining margins through rapid-turn distribution networks that minimize equipment downtime for rental fleets.
Rubber track pads for construction machinery are elastomeric wear components, typically 20-40mm in thickness, bonded to steel or aluminum base plates through high-pressure vulcanization to absorb ground impact and protect paved surfaces from steel-track damage. Standard pads dominate volume sales for generic excavator fleets where price sensitivity governs procurement, while reinforced pads command premium positioning in mining and quarry applications where abrasion resistance extends replacement intervals. Polyurethane-coated technology leads innovation investment as contractors seek hybrid durability combining rubber flexibility with thermoplastic wear resistance.
EPA emission standards for non-road diesel engines and OSHA worksite noise regulations in the United States shape product design by mandating quieter, lower-vibration undercarriage systems that rubber pads enable. REACH chemical restrictions and CE marking requirements under EU machinery directives limit certain aromatic oil plasticizers, redirecting formulation R&D toward bio-based processing oils and halogen-free curing agents. Stakeholders must monitor how evolving carbon-border adjustment mechanisms and extended producer responsibility frameworks in Europe and North America reshape material sourcing economics and aftermarket service obligations.
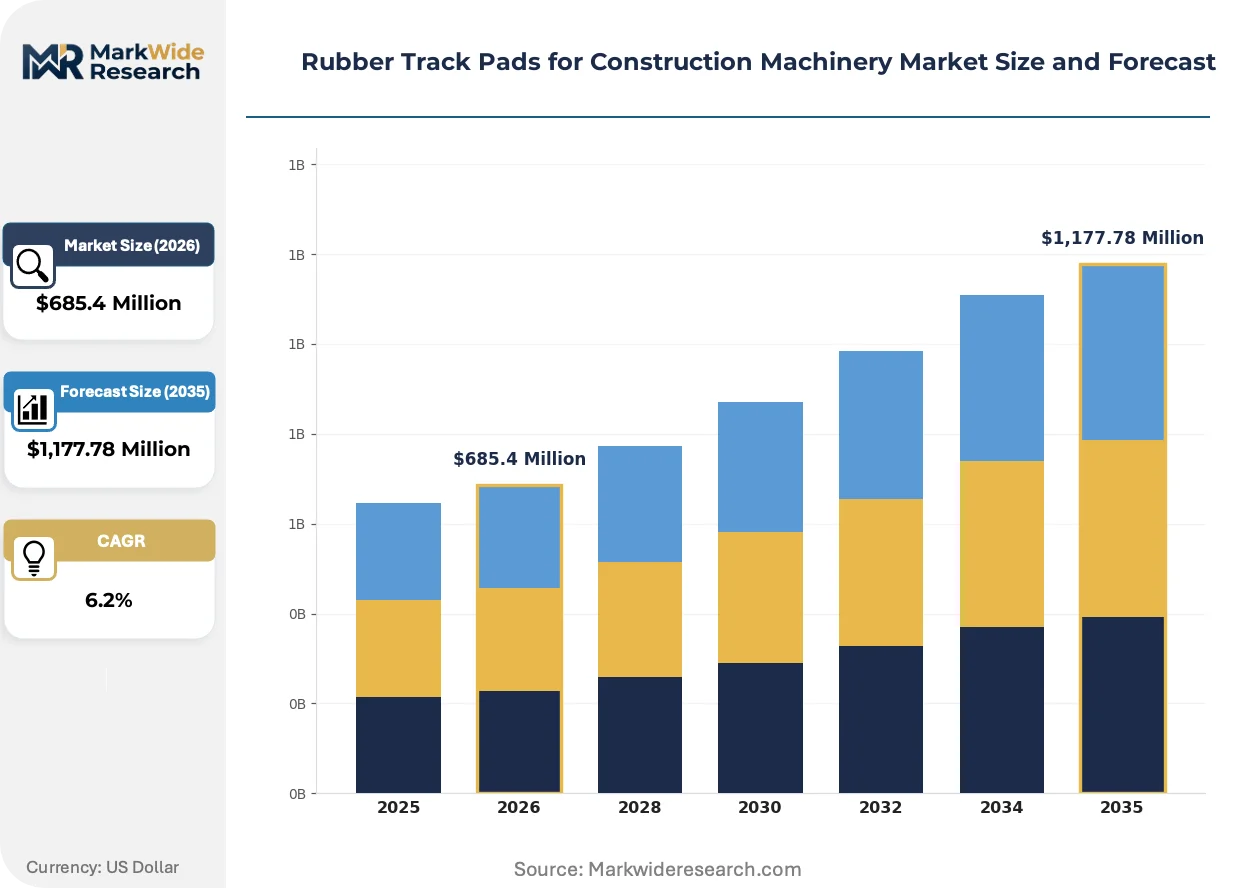
Market Dynamics
Polyurethane-coated pad technology is compressing replacement intervals while EU F-Gas Regulation and REACH compliance force reformulation investments across European manufacturing footprints. Equipment leasing companies now dominate fleet procurement decisions, shifting volume toward standardized pad specifications that reduce inventory complexity for rental yards.
Growth Catalysts
- EU Chemical Restrictions:REACH limitations on aromatic oil plasticizers redirect R&D spending toward bio-based processing oils, creating first-mover advantages for compounders with advanced formulation capabilities.
- Urban Demolition Surge:Germany, Japan, and the United States infrastructure renewal programs accelerate crawler fleet deployment for precision earthmoving in dense metropolitan corridors.
- Polyurethane Hybridization:Thermoplastic wear layers bonded to rubber substrates extend service life in quarry applications, commanding premium positioning in mining aftermarket channels.
Market Restraints
- Natural Rubber Volatility:Southeast Asian latex supply disruptions and synthetic polybutadiene price swings compress compounder margins during procurement cycles.
- Steel Track Substitution:Steel-track excavators retain cost advantage in undeveloped terrain applications where surface protection requirements remain minimal.
- CE Marking Complexity:EU machinery directive compliance timelines extend product certification periods, delaying regional launch schedules for new pad formulations.
Strategic Opportunities
- Pay-per-Use Financing:Asset-light leasing models enable mid-tier contractors to access premium crawler fleets without capital deployment, expanding addressable demand for high-durability pads.
- Carbon Border Adjustments:Emerging European carbon-border mechanisms create incentives for localized compounding facilities serving regional OEM assembly plants.
- Silicone-Treated Formulations:Lower volatile compound emission pads align with tightening EPA non-road diesel worksite standards, opening specification windows in California and Northeast corridor states.
Industry Challenges
- Vulcanization Technician Scarcity:High-pressure bonding expertise shortages constrain capacity expansion at specialized pad manufacturing facilities.
- Legacy Equipment Compatibility:Retrofit pad mounting systems require dimensional standardization across fragmented excavator undercarriage designs, complicating aftermarket inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubber Track Pads for Construction Machinery Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Pads, Customized Pads, Reinforced Pads, Eco-Friendly Pads Application: Excavators, Bulldozers, Skid Steer Loaders, Crawler Loaders, Trenchers Technology: Vulcanized Rubber, Neoprene Rubber, Polyurethane Coated, Silicone Treated, Composite Material End User Industry: Heavy Equipment Rental, Construction Contractors, Mining Operators, Infrastructure Developers, Earthmoving Services |
| Companies Covered | Bridgestone Corporation, Camso, Superior Tire & Rubber Corp., Everpads Co., Ltd., Rio Rubber Track, Inc., Global Track Warehouse, McLaren Industries, Trelleborg AB, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubber Track Pads for Construction Machinery Market Trends and Innovations
Formulation chemistry and procurement models are simultaneously transforming how rubber track pads are engineered, specified, and distributed across construction equipment networks. Three developments are restructuring competitive positioning.
Polyurethane-coated hybrid pads combine thermoplastic wear resistance with rubber impact absorption, extending replacement cycles in high-abrasion quarry environments. Mining contractors and heavy civil operators are specifying these configurations for 30-ton-plus excavator fleets. The technology is virtualizing traditional rubber-only pad categories by collapsing the performance gap between standard and reinforced product lines.
EPA emission standards for non-road diesel engines mandate quieter undercarriage systems, accelerating rubber pad adoption over steel tracks in urban utility trenching. OSHA worksite noise regulations in the United States reinforce this specification shift. Equipment leasing companies now require sub-85 decibel ground engagement systems as standard fleet configuration.
Contractors are consolidating vendor relationships toward integrated service providers offering pad supply, mounting, and disposal as bundled offerings. Independent distributors face margin compression as rental fleet operators negotiate direct compounding contracts. This consolidation is most visible in Germany and Japan where precision earthmoving standards drive specification complexity.
Rubber Track Pads for Construction Machinery Market Segmentation
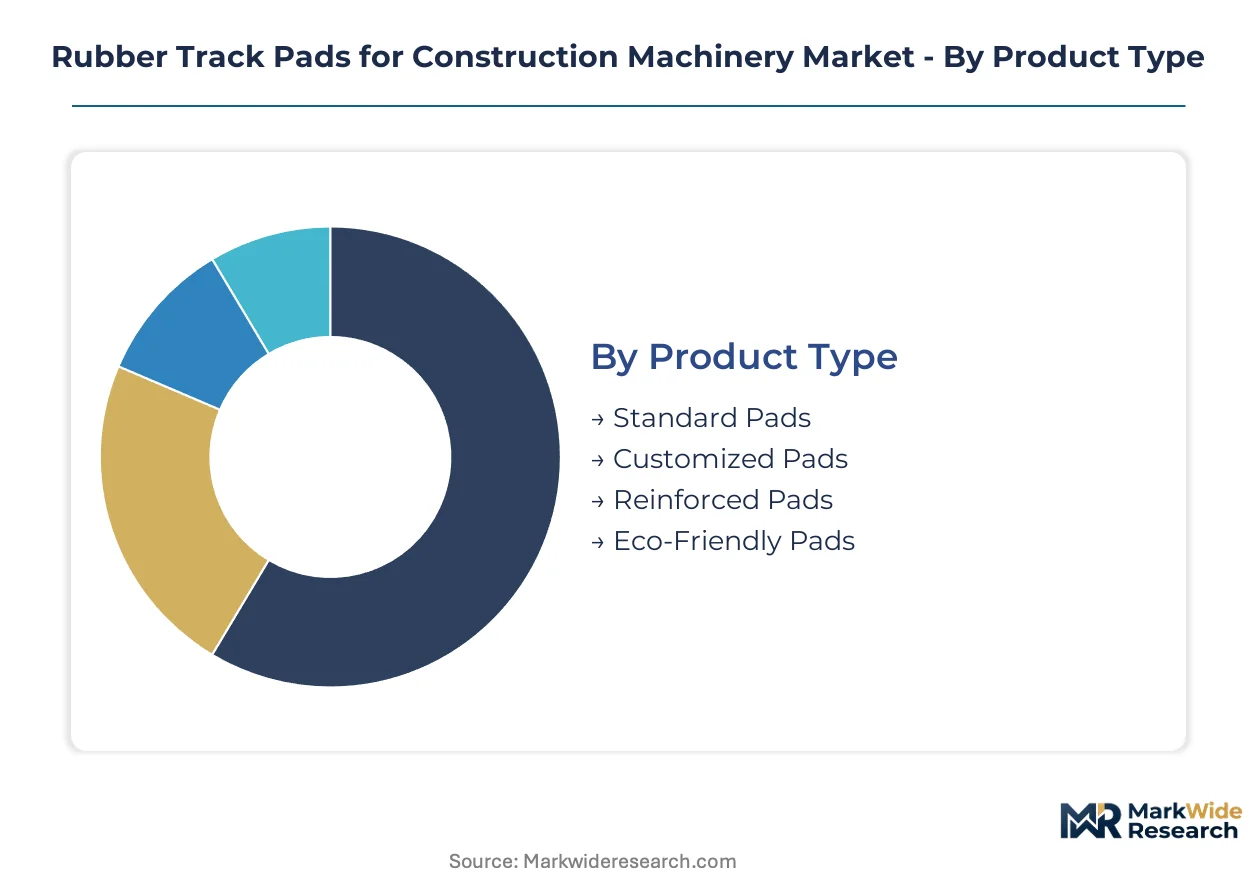
Rubber track pad procurement patterns diverge sharply across equipment types and user economics. Contractors prioritize surface protection specifications while rental fleets standardize for inventory velocity, forcing manufacturers to maintain parallel product architectures.
Product Type:
Mature specifications dominate volume procurement, though emerging formulations are capturing specification windows in regulated jurisdictions.
- Standard Pads:Generic elastomeric compounds bonded to steel base plates serve price-sensitive excavator fleets where replacement frequency governs total cost of ownership. Demand concentrates in United States rental yards and German construction corridors where fleet standardization reduces inventory complexity.
- Reinforced Pads:High-tensile fabric inserts and thicker rubber cross-sections extend service intervals in quarry and mining applications. Mining operators in Australia and Canada specify these configurations for 30-ton-plus crawler fleets where downtime costs exceed material premiums.
- Customized Pads:Dimensional modifications accommodate legacy undercarriage designs and specialized mounting systems.
- Eco-Friendly Pads:Bio-based processing oils and halogen-free curing agents address REACH aromatic oil restrictions and California Air Resources Board worksite emission standards.
Standard pads handle the majority of throughput; eco-friendly pads are expanding most quickly on specification share.
Application:
Equipment weight class and operating terrain dictate pad specification intensity across the installed base.
- Excavators:20-40 ton crawler excavators represent the highest-volume application, with urban demolition contractors in Japan and Germany specifying polyurethane-coated configurations for pavement protection. EPA non-road diesel noise regulations reinforce rubber pad specification over steel tracks in metropolitan utility corridors.
- Skid Steer Loaders:Compact footprint and frequent surface transitions drive rapid replacement cycles. United States landscaping and residential construction contractors generate concentrated demand for clip-on pad systems enabling field installation without specialized tooling.
- Bulldozers:High ground pressure and continuous operation in undeveloped terrain favor reinforced pad specifications or steel track retention.
- Crawler Loaders:Material handling applications in aggregate processing facilities require abrasion-resistant formulations.
- Trenchers:Linear excavation projects in utility infrastructure drive seasonal demand spikes aligned with municipal contracting calendars.
Excavator applications absorb the greatest pad volume; skid steer configurations show the steepest expansion trajectory in rental fleet penetration.
Technology:
Formulation chemistry separates commodity supply from premium positioning through durability and regulatory compliance attributes.
- Polyurethane Coated:Thermoplastic wear layers bonded to rubber substrates collapse the performance gap between standard and reinforced categories. Mining contractors in South Africa and Chile specify these hybrid configurations for high-abrasion environments where replacement interval extension justifies material premiums.
- Silicone Treated:Lower volatile compound emissions align with tightening OSHA worksite exposure limits and California occupational safety standards. Infrastructure developers in Northeast corridor states increasingly specify these formulations for urban tunneling and subway extension projects.
- Vulcanized Rubber:Conventional sulfur-cured compounds remain the cost baseline for generic fleet replacement.
- Neoprene Rubber:Chloroprene-based formulations offer enhanced oil resistance for contaminated site remediation equipment.
- Composite Material:Multi-layer constructions combining rubber, metal, and polymer elements address extreme load applications.
Vulcanized rubber maintains the largest installed base; polyurethane coated technology is climbing the fastest in specification share.
End User Industry:
Procurement authority concentration varies sharply between asset-heavy operators and asset-light service providers.
- Heavy Equipment Rental:Leasing companies now dominate fleet procurement decisions, standardizing pad specifications across multi-brand crawler inventories to reduce spare parts complexity. United Rentals and Ashtead Group procurement teams negotiate direct compounding contracts bypassing traditional distribution tiers.
- Construction Contractors:Mid-tier earthmoving specialists access premium crawler fleets through pay-per-use financing without capital deployment, expanding addressable demand for high-durability pad configurations.
- Mining Operators:Autonomous haulage and precision excavation requirements drive specification toward sensor-compatible pad designs with embedded wear indicators.
- Infrastructure Developers:Public-private partnership concession agreements increasingly mandate surface protection clauses favoring rubber over steel track systems.
- Earthmoving Services:Specialized grading and site preparation contractors maintain fragmented procurement patterns with high vendor switching frequency.
Rental industry procurement handles the greatest volume concentration; construction contractor demand is gaining share fastest through financing model transformation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor manufacturing concentration near synthetic rubber and polyurethane feedstock sources, with finished pad shipments flowing toward heavy equipment assembly clusters in Germany, Japan, and the United States. Regional regulatory divergence around chemical emissions and surface protection standards is fragmenting specification requirements.
United States
EPA non-road diesel emission standards and OSHA worksite noise regulations accelerate rubber pad specification over steel tracks in urban utility corridors. Infrastructure renewal programs in Texas and California drive crawler fleet deployment for precision earthmoving. The Southeast manufacturing belt hosts compounding facilities serving domestic OEM assembly plants.
Germany
REACH aromatic oil restrictions and EU F-Gas Regulation compliance timelines redirect formulation R&D toward bio-based processing oils. Bavaria and North Rhine-Westphalia concentrate precision earthmoving contractors specifying polyurethane-coated configurations for pavement protection. Stuttgart's automotive supplier network supplies vulcanization equipment to pad fabricators.
Japan
METI industrial standards and JIS certification requirements shape product quality benchmarks for export-oriented manufacturers. Tokyo and Osaka metropolitan demolition projects specify sub-85 decibel ground engagement systems. Chubu region rubber compounders leverage integrated polymer sourcing for high-pressure curing operations.
China
GB standards and MIIT equipment certification frameworks govern domestic crawler fleet specifications. Yangtze River Delta construction machinery clusters generate concentrated demand for standard pad replacements. Zhengzhou and Xuzhou equipment manufacturing hubs anchor regional distribution networks.
Australia
State-level surface protection mandates in Queensland and Western Australia favor rubber over steel tracks in environmentally sensitive mining corridors. Perth and Brisbane rental fleets standardize specifications across multi-brand inventories. Local compounding capacity remains limited, driving import dependence from Southeast Asian suppliers.
Rubber Track Pads for Construction Machinery Market Competitive Landscape
On the supply side, the industry is tiered between integrated rubber compounders with captive polymer sourcing and specialized aftermarket distributors focused on rapid-turn logistics. Three archetypes dominate: integrated chemical-industrial conglomerates controlling formulation from base polymer to finished pad, independent pad specialists leveraging regional distribution density, and equipment OEM captive suppliers bundling undercarriage components. Competitive moves center on backward integration into compounding capacity and direct contracting relationships with rental fleet operators bypassing traditional distribution tiers.
Among integrated compounders, Bridgestone Corporation and Continental AG exemplify the chemical-industrial archetype with polymer-to-pad production control. McLaren Industries occupies a position within the aftermarket specialist tier, representing rapid-turn distribution models serving rental fleet downtime minimization requirements. Trelleborg AB anchors the European formulation-technology segment, sitting within the premium hybrid-material development space.
| Leading Market Players |
|---|
| Bridgestone Corporation |
| Camso |
| Superior Tire & Rubber Corp. |
| Everpads Co., Ltd. |
| Rio Rubber Track, Inc. |
| Global Track Warehouse |
| McLaren Industries |
| Trelleborg AB |
| Continental AG |
| Others |
Pricing and Supply Chain Analysis
Shanghai-Rotterdam container freight corridors transmit synthetic rubber and polyurethane feedstock cost volatility directly into pad pricing tiers, concentrating margin pressure on compounders without captive polymer sourcing while amplifying price differentiation between integrated manufacturers and distributor-dependent suppliers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across premium, standard, and economy tiers based on certification grade and volume scale. Price differentiation stems from REACH compliance investment and after-sales service bundling. Cost compression in standard pad tiers is intensifying because rental fleet procurement consolidation squeezes distributor markups. Price sensitivity peaks among mid-tier construction contractors accessing equipment through pay-per-use financing, while mining operators demonstrate lowest sensitivity due to downtime cost prioritization.
Supply Chain Analysis
Export-control regimes limiting advanced vulcanization equipment flows to Southeast Asian manufacturing hubs tether supply concentration to Germany, Japan, and the United States where high-pressure curing expertise concentrates. Raw material dependencies center on Malaysian natural rubber latex, Saudi synthetic polybutadiene, and German polyurethane isocyanates. Single-source vulnerability characterizes specialized high-tensile fabric insert supply. Distribution runs through equipment OEM captive networks and independent aftermarket distributors serving rental fleet rapid-turn requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rubber track pad procurement is restructuring around service-attach revenue models where mounting, wear monitoring, and end-of-life disposal bundles expand faster than hardware unit sales, creating recurring income streams that compound customer lifetime value.
For Market Incumbents: Build formulation IP moats through captive R&D in bio-based processing oils and halogen-free curing agents ahead of REACH aromatic oil phase-outs. Deepen backward integration into Southeast Asian natural rubber sourcing to defend margins against latex price volatility. Consolidate regional distribution networks to counter equipment leasing company direct contracting threats.
For New Entrants and Emerging Players: Pursue white-space positioning in silicone-treated pad formulations for California and Northeast corridor states where OSHA worksite exposure limits tighten fastest. Target aftermarket retrofit systems for legacy excavator fleets where dimensional standardization gaps fragment incumbent inventory management. Deploy direct-to-rental-fleet digital sales channels bypassing traditional distributor tiers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underoptimized construction equipment components divisions. Long-term viability favors compounders with integrated polymer-to-pad production control and regulatory compliance certification depth. Monitor EPA non-road diesel emission standard enforcement intensity as inflection indicator for rubber pad substitution acceleration over steel tracks.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive control over natural rubber and synthetic polybutadiene quality secures margin defense against feedstock volatility. |
| Green Formulation Certification Program | REACH-compliant bio-based processing oil pads unlock specification windows in EU infrastructure procurement. |
| Direct Rental Fleet Contracting | United Rentals and Ashtead Group procurement teams increasingly bypass distribution tiers for volume purchasing. |
| Polyurethane Hybrid Technology Licensing | Thermoplastic wear layer bonding expertise commands premium positioning in mining aftermarket channels. |
| End-of-Life Pad Recycling Infrastructure | Extended producer responsibility frameworks in Europe reshape aftermarket service obligations toward circular models. |
Research Methodology
Initial hypotheses were tested against primary input from equipment maintenance directors, OEM procurement managers, aftermarket service heads, and rental fleet operations leads and refined through secondary validation against customs trade data, SEC equipment manufacturer filings, ECHA REACH registration databases, and construction machinery production statistics. Bottom-up segment sizing triangulated with top-down macroeconomic drivers anchored volume and value estimates.
Demand-supply balance dynamics across product type, application equipment class, formulation technology, and end-user industry concentration shaped the analytical framework over the projection horizon. CAGRs were derived from replacement cycle analysis, fleet penetration modeling, and regulatory compliance timeline acceleration. Industry-specific inputs included excavator utilization rates from rental fleet telemetry and polyurethane raw material price indices from chemical feedstock markets.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by integrated rubber compounders or accelerated steel track substitution in undeveloped terrain applications would shift outcomes. Material shifts in EU carbon-border adjustment implementation timelines or Southeast Asian natural rubber supply disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Construction Wearable Technology Market
Construction Equipment
Street Washer Machine Market
Construction Equipment
Sandblast Nozzle Market
Construction Equipment
Laser Cutting Machines Market
Construction Equipment
Global Cone Crusher Market
Construction Equipment
Pressure Vessel Market
Construction Equipment
Plastic Molding Machine Market
Construction Equipment
Crane Pumps Market
Construction Equipment
Global Wheel Aligner Equipment Market
Construction Equipment
Rail Welding Equipment Market
Construction Equipment
Smelting Furnace Equipment Market
Construction Equipment
Global Submerged Arc Welding Market
Construction Equipment
Engine Driven Welders Market
Construction Equipment
Hybrid Construction Equipment Market
Construction Equipment
Wheeled Excavators Market
Construction Equipment
Brazil Construction Equipment Market