
 Global RF Power Semiconductor Market | 2026-2036
Global RF Power Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
Global RF Power Semiconductor Market Outlook
Market Context
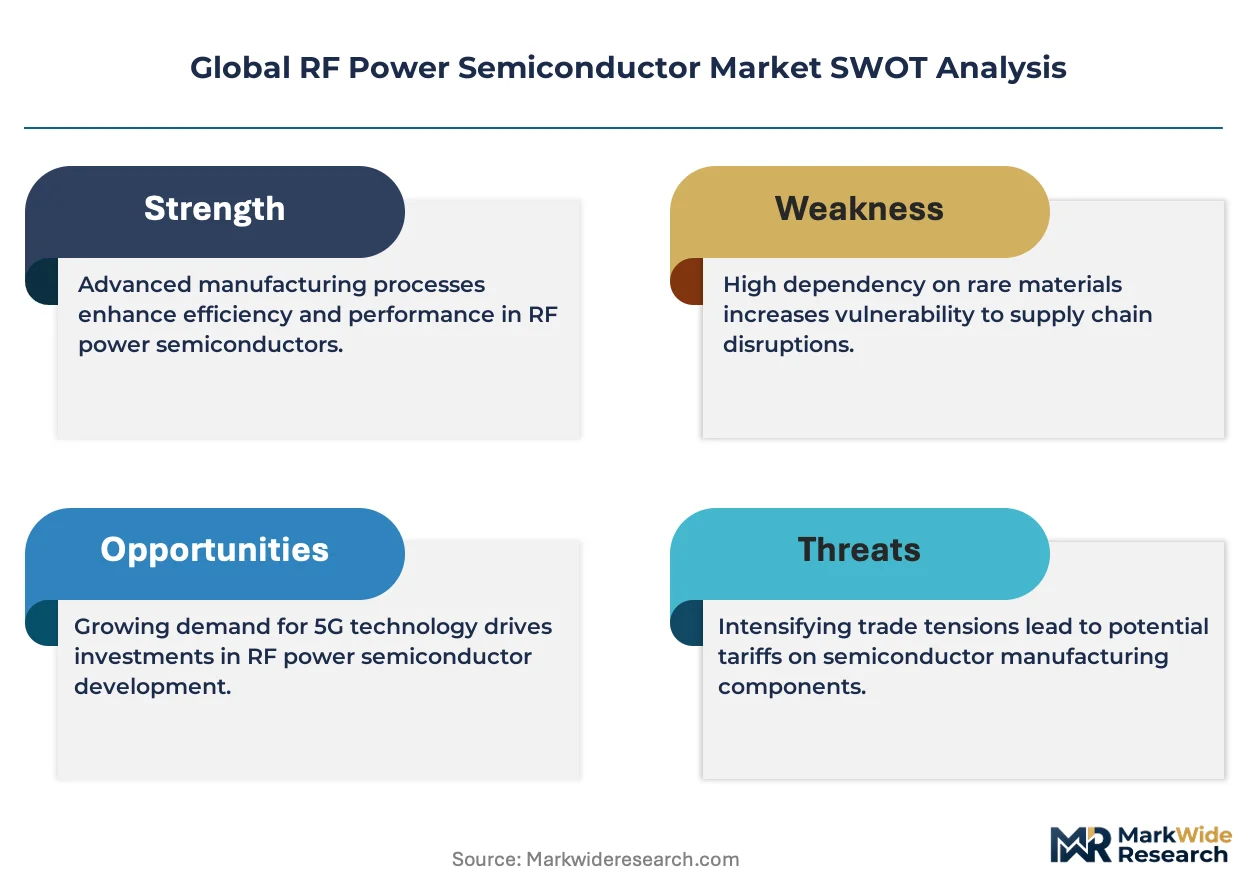
A widening capital-intensity divergence between GaN-first foundries and legacy silicon houses is reorganizing competitive tiers across the RF power semiconductor supply base. Qorvo, Inc. leverages captive GaN-on-SiC fabrication to command premium positioning in defense radar and satellite communications. Wolfspeed, Inc. anchors the upstream materials layer through vertical control of SiC substrate supply, constraining competitor expansion. NXP Semiconductors N.V. competes across LDMOS and GaN portfolios, sustaining scale in cellular infrastructure through multi-technology sourcing flexibility.
Technical Definition and Segment Structure
RF power semiconductors are discrete or integrated devices engineered to amplify radio-frequency signals above 1 MHz, with GaN HEMTs achieving power-added efficiencies exceeding 70% at frequencies up to 100 GHz through wide bandgap epitaxy on SiC or silicon substrates. These components serve as the final amplification stage in radar transmitters, cellular base stations, and broadcast systems where thermal dissipation and linearity determine system performance. GaN technology captures the fastest expansion trajectory as mobile network operators deploy massive MIMO arrays demanding higher instantaneous bandwidth per channel element. Silicon LDMOS retains cost advantages below 4 GHz in macrocell infrastructure, though margin pools are migrating toward GaN-SiC hybrids in aerospace and defense end uses. Field Effect Transistor architectures dominate research institute procurement for particle accelerator and fusion energy applications requiring pulsed operation at megawatt peaks.
Regulatory Environment
FCC spectrum allocation decisions in the United States, MIIT 5G base station certification requirements in China, and EU CE marking under the Radio Equipment Directive collectively shape product development roadmaps and market access timelines for RF power semiconductor vendors. EAR export controls on GaN epitaxy equipment constrain technology transfer to non-allied defense programs, redirecting procurement toward qualified domestic foundries in affected jurisdictions. Stakeholders must monitor evolving spectrum harmonization between the FCC and CEPT to anticipate frequency band reallocations that would obsolete incumbent amplifier designs.
Market Dynamics
The transition from silicon LDMOS to GaN-on-SiC architectures is redrawing competitive boundaries across telecommunications and defense procurement channels, concentrating margin capture among foundries with captive substrate supply.
Growth Catalysts
- 5G Massive MIMO Deployment:Mobile network operators in China, the United States, and Germany are installing high-channel-count base stations requiring GaN HEMTs for thermal efficiency at millimeter-wave frequencies.
- MIIT Certification Mandates:China's base station certification requirements under MIIT are accelerating domestic GaN foundry capacity expansion to serve state-backed carrier procurement timelines.
- Defense Radar Modernization:Active electronically scanned array upgrades across NATO and Indo-Pacific militaries are pulling high-reliability GaN-SiC amplifiers into long-term supply agreements.
Market Restraints
- SiC Substrate Bottleneck:Wolfspeed's vertical control of 6-inch and 8-inch SiC wafer supply constrains competitor expansion regardless of epitaxy capability.
- EAR Export Controls:US Commerce Department restrictions on GaN MOCVD equipment transfer to non-allied defense programs fragment global technology access.
- Silicon LDMOS Cost Floor:Mature 8-inch silicon foundry economics sustain incumbent positioning below 4 GHz in emerging market macrocell infrastructure.
Strategic Opportunities
- India Telecom Infrastructure:Reliance Jio and Bharti Airtel 5G rollouts create demand for cost-optimized GaN-on-silicon amplifiers in mid-band massive MIMO configurations.
- EU Green Deal Alignment:Base station power efficiency mandates under the EU Green Deal favor wide bandgap semiconductors in public procurement scoring.
- GaN-SiC + Digital Pre-Distortion Convergence:Integration of linearization algorithms with RF front-ends enables single-amplifier solutions across multi-band configurations.
Industry Challenges
- Compound Semiconductor Process Engineering Talent:Foundries in the United States, Germany, and Japan compete for limited pools of GaN HEMT device physicists and MOCVD operators.
- Dual-Use Export Licensing Timelines:ITAR and EAR classification reviews extend qualification cycles for defense-qualified GaN amplifiers by 12-18 months versus commercial timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global RF Power Semiconductor Market |
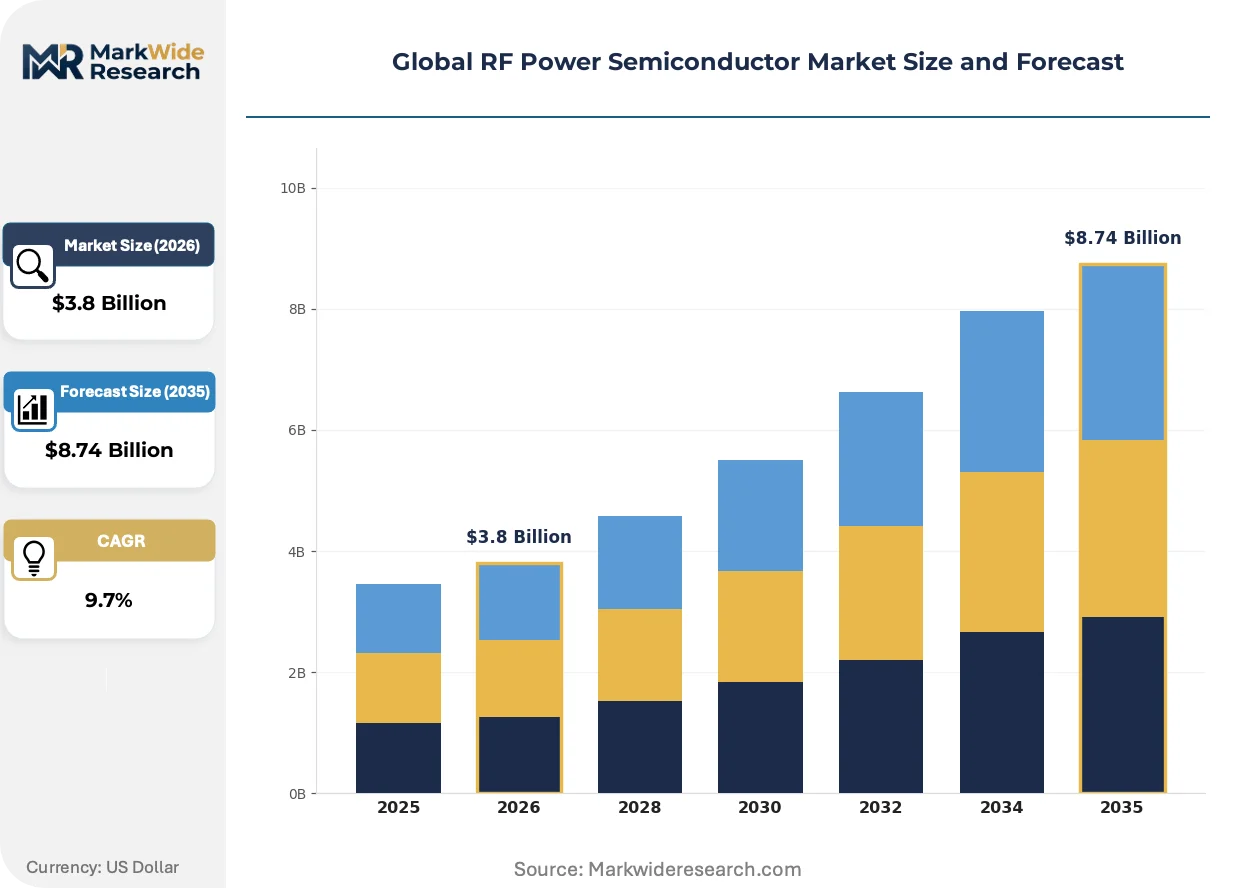
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bipolar Junction Transistor, Field Effect Transistor, GaN, LDMOS Application: Telecommunications, Industrial, Consumer Electronics, Automotive Technology: Silicon, Gallium Nitride, Silicon Carbide, Hybrid End User: Data Centers, Mobile Network Operators, Aerospace, Research Institutes |
| Companies Covered | Qorvo, Inc., NXP Semiconductors N.V., Skyworks Solutions, Inc., Infineon Technologies AG, Broadcom Inc., Qualcomm Technologies, Inc., Analog Devices, Inc., MACOM Technology Solutions Holdings, Inc., Wolfspeed, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global RF Power Semiconductor Market Strategic Shifts
GaN technology diffusion is compressing design cycles across cellular infrastructure while regulatory energy-efficiency mandates and procurement consolidation reshape supplier relationships.
GaN-on-SiC high electron mobility transistors deliver power-added efficiencies exceeding 70% at frequencies up to 100 GHz through wide bandgap epitaxy. Mobile network operators in the United States, China, and South Korea are adopting these devices for 5G massive MIMO arrays at accelerating procurement volumes. This technology is displacing legacy silicon LDMOS in high-frequency base station applications and concentrating margin pools among foundries with captive SiC substrate access.
FCC spectrum reallocation decisions in the United States and MIIT 5G base station certification requirements in China are synchronizing frequency band definitions across major economies. Equipment manufacturers must redesign amplifier chains for n77, n78, and n79 band convergence, compressing product lifecycle planning horizons. Defense contractors in affected jurisdictions are redirecting procurement toward qualified domestic foundries to circumvent EAR export control friction on GaN epitaxy equipment.
Consolidated carrier procurement through centralized 5G infrastructure tenders in China, India, and Brazil is compressing supplier margins and extending qualification requirements. Tier-1 telecommunications equipment vendors are unbundling after-sales service contracts and demanding multi-source GaN amplifier availability. This pattern is most visible in Chinese state-backed carrier procurement, where MIIT-mandated domestic content ratios privilege locally qualified foundries.
Global RF Power Semiconductor Market Segmentation
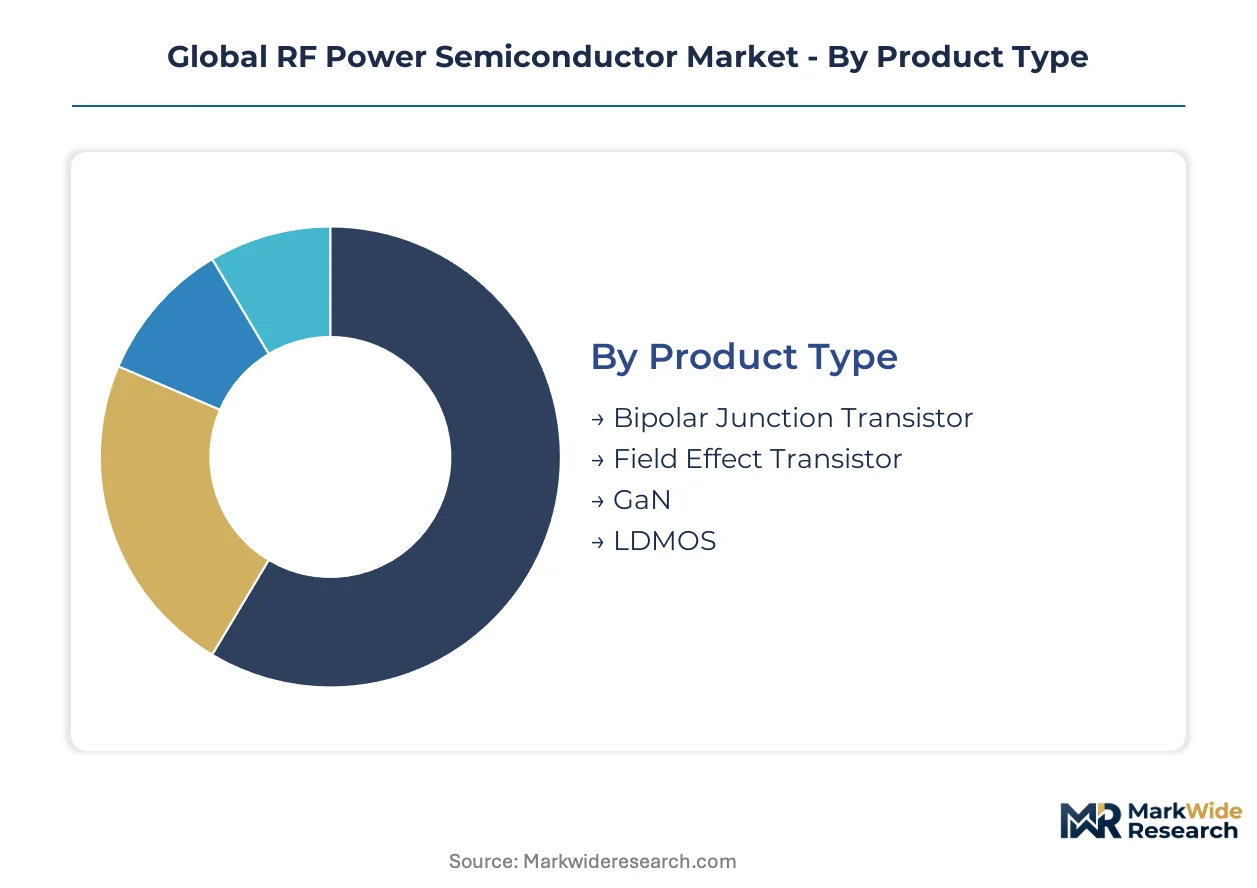
Technology substitution pressures and end-use performance requirements fragment the RF power semiconductor landscape across four intersecting dimensions. Procurement patterns diver sharply between cost-optimized cellular infrastructure and reliability-weighted defense applications.
Product Type:
GaN HEMTs and silicon LDMOS face the most acute substitution tension as mobile operators weigh thermal efficiency gains against established foundry economics.
- GaN:Wide bandgap epitaxy on SiC substrates delivers power-added efficiencies exceeding 70% at millimeter-wave frequencies. Defense radar modernization programs in the United States and Germany are pulling high-reliability GaN-SiC amplifiers into long-term supply agreements with qualified domestic foundries.
- LDMOS:Mature silicon laterally-diffused metal-oxide-semiconductor technology dominates macrocell infrastructure below 4 GHz through cost-optimized 8-inch foundry economics. Emerging market carriers in India and Brazil sustain procurement volumes despite margin compression from GaN displacement at higher frequencies.
- Field Effect Transistor:Research institutes in Japan and Germany procure specialized FET architectures for particle accelerator and fusion energy applications requiring pulsed operation at megawatt peaks.
- Bipolar Junction Transistor:Legacy silicon BJTs persist in broadcast transmitter retrofits and industrial heating equipment where frequency requirements stay below 100 MHz.
LDMOS retains volume leadership in cellular infrastructure procurement; GaN holds the steepest expansion curve as massive MIMO deployment accelerates.
Application:
Cost tier stratification separates premium defense-grade qualification from commodity telecommunications procurement.
- Telecommunications:5G massive MIMO base station deployment drives the dominant demand pool. China's MIIT certification mandates and FCC spectrum reallocations in the United States are synchronizing n77, n78, and n79 band requirements, forcing amplifier redesign cycles.
- Industrial:RF plasma generation and industrial heating systems in Germany and Japan specify robust thermal cycling tolerance. Semiconductor fabrication equipment makers source GaN-on-SiC devices for etching and deposition power supplies.
- Automotive:Vehicle-to-everything communication modules and radar sensors are emerging procurement channels. Tier-1 automotive suppliers in South Korea and Germany are qualifying GaN amplifiers for 77 GHz adaptive cruise control systems.
- Consumer Electronics:Wi-Fi 6E and Wi-Fi 7 router amplification represent a price-sensitive volume segment. Contract manufacturers in Taiwan and Vietnam assemble cost-optimized GaN-on-silicon solutions for retail networking equipment.
Telecommunications commands the largest revenue share; automotive applications are climbing the fastest as connected vehicle mandates expand.
Technology:
Supply concentration in upstream materials creates divergent margin structures across substrate choices.
- Gallium Nitride:Epitaxial growth on SiC or silicon substrates enables the highest frequency operation. Wolfspeed's captive control of 6-inch and 8-inch SiC wafer supply constrains competitor expansion regardless of device design capability.
- Silicon:Mature CMOS-compatible processes sustain cost positioning in sub-6 GHz infrastructure. Foundries in China and Taiwan offer competitive LDMOS foundry services with shorter qualification timelines than compound semiconductor alternatives.
- Silicon Carbide:Pure SiC devices serve specialized high-voltage switching applications rather than RF amplification. Power electronics crossover demand from electric vehicle inverters competes for limited substrate allocation.
- Hybrid:Multi-technology modules combining GaN HEMTs with silicon driver circuits address thermal management in dense base station configurations. NXP Semiconductors and Qorvo compete in this integration-intensive segment.
Silicon maintains installed base dominance; GaN-on-SiC combinations are gaining share fastest in defense and satellite communications procurement.
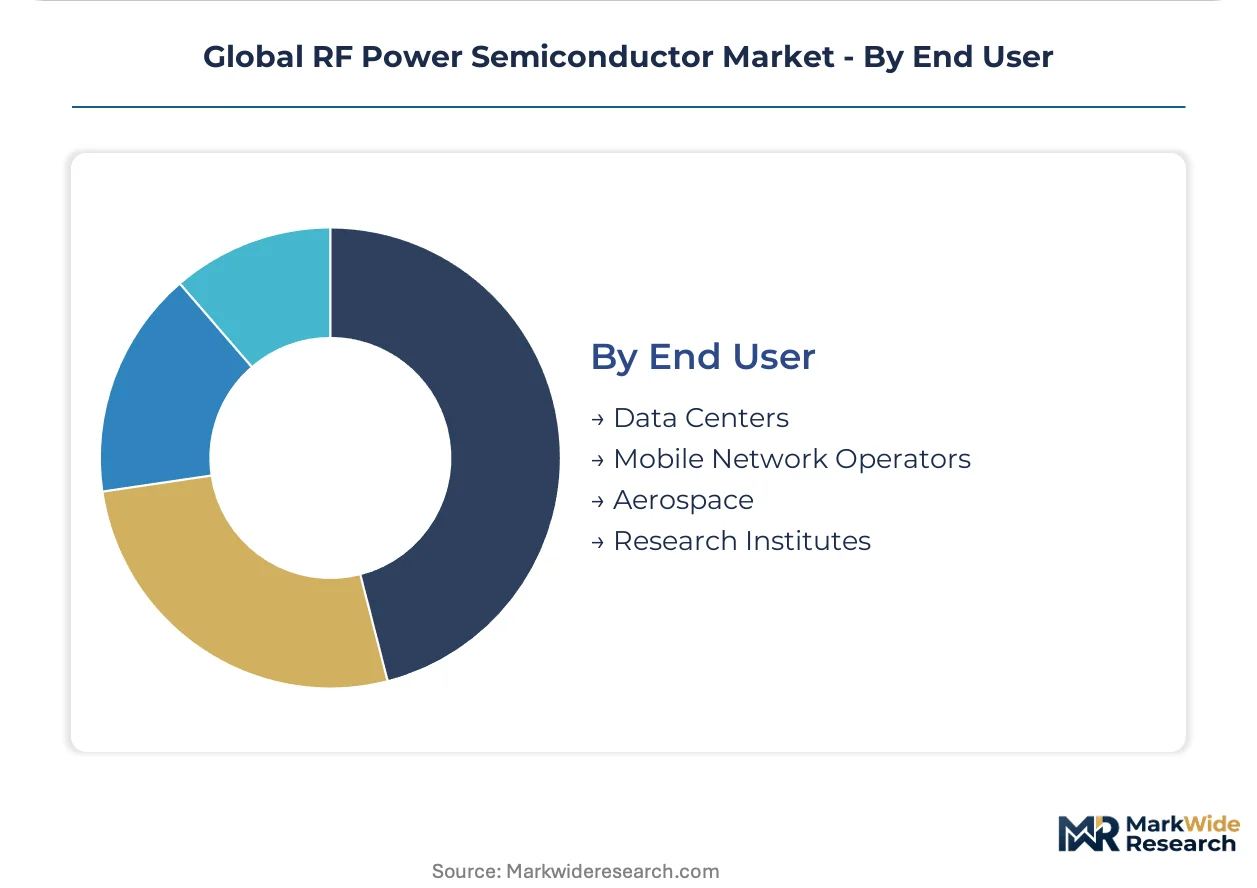
End User:
Customer type determines qualification burden, with defense and aerospace programs imposing 12-18 month ITAR and EAR review cycles.
- Mobile Network Operators:Consolidated carrier procurement through centralized 5G tenders in China, India, and Brazil compresses supplier margins. Reliance Jio and Bharti Airtel in India are driving cost-optimized GaN-on-silicon adoption for mid-band massive MIMO.
- Aerospace:Satellite communications and radar systems require hermetic packaging and radiation tolerance. NATO and Indo-Pacific militaries are redirecting procurement toward qualified domestic foundries to circumvent export control friction.
- Data Centers:Wireless fronthaul and in-building distributed antenna systems represent an emerging demand channel. Hyperscale operators in the United States are testing GaN amplifiers for energy-efficient small cell densification.
- Research Institutes:Particle physics laboratories and fusion energy programs specify custom pulsed operation at extreme power levels. CERN in Switzerland and national laboratories in the United States and Japan sustain niche procurement volumes.
Mobile network operators anchor volume demand; aerospace end users deliver the steepest margin expansion as defense budgets prioritize electronic warfare modernization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Indian and Brazilian carriers prioritize cost-optimized silicon LDMOS for sub-6 GHz macrocells, while United States and German defense programs absorb GaN-on-SiC premiums for radar modernization without volume elasticity.
United States
Defense radar modernization and FCC spectrum reallocation for 5G mid-band drive procurement volumes. FCC decisions on n77 and n78 band licensing synchronize equipment qualification timelines with carrier deployment schedules. The Boston-Washington corridor anchors GaN HEMT design activity, with defense contractors redirecting sourcing toward qualified domestic foundries under EAR compliance protocols.
China
MIIT-mandated 5G base station certification accelerates domestic GaN foundry capacity expansion for state-backed carrier procurement. MIIT technical requirements for massive MIMO arrays privilege locally qualified suppliers with domestic content ratios. The Yangtze River Delta concentrates epitaxy equipment installation, with Shanghai and Suzhou clusters scaling 6-inch GaN-on-SiC production for telecommunications infrastructure.
Germany
Industrial RF plasma systems and automotive radar qualification sustain dual-use demand for wide bandgap devices. EU CE marking under the Radio Equipment Directive shapes product development roadmaps for base station exports. Bavaria hosts precision manufacturing clusters around Munich, where semiconductor fabrication equipment makers source GaN amplifiers for etching power supplies.
India
Reliance Jio and Bharti Airtel 5G rollouts create volume demand for cost-optimized GaN-on-silicon amplifiers in mid-band configurations. TRAI spectrum auction structures influence carrier capital allocation toward massive MIMO densification. Karnataka's Bangalore cluster attracts contract assembly for networking equipment, with domestic value-add requirements under PLI scheme incentives reshaping supplier selection.
South Korea
Connected vehicle mandates and Wi-Fi 7 router manufacturing pull GaN amplifiers into consumer electronics supply chains. MFDS automotive certification timelines for 77 GHz radar modules synchronize tier-1 supplier qualification cycles. Seoul Capital Area foundries specialize in GaN-on-silicon integration for price-sensitive retail networking equipment exported to Vietnam and Taiwan assembly partners.
Global RF Power Semiconductor Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the RF power semiconductor supply base. GaN-first foundries with captive SiC substrate access command premium positioning in defense and satellite communications, while legacy silicon houses sustain scale through multi-technology sourcing flexibility. Three archetypes dominate: vertically integrated compound semiconductor specialists, diversified multi-technology portfolio vendors, and captive substrate suppliers constraining competitor expansion. Competitive moves concentrate on foundry capacity expansion and strategic partnerships for digital pre-distortion algorithm integration.
Among compound semiconductor specialists, Qorvo, Inc. and Wolfspeed, Inc. exemplify divergent upstream strategies—one emphasizing device design integration, the other anchoring materials supply. NXP Semiconductors N.V. occupies a position spanning LDMOS and GaN portfolios, representing the diversified archetype competing through multi-source qualification flexibility. These three companies illustrate how substrate control, technology breadth, and application focus segment competitive positioning across telecommunications and defense procurement channels.
| Leading Market Players |
|---|
| Qorvo, Inc. |
| NXP Semiconductors N.V. |
| Skyworks Solutions, Inc. |
| Infineon Technologies AG |
| Broadcom Inc. |
| Qualcomm Technologies, Inc. |
| Analog Devices, Inc. |
| MACOM Technology Solutions Holdings, Inc. |
| Wolfspeed, Inc. |
| Others |
Value Chain & Pricing Dynamics
6-inch SiC wafer utilization rates at Wolfspeed's Durham facility shape both supply availability and price floors across defense and telecommunications procurement tiers, compressing margins for GaN-on-SiC amplifiers when capacity tightens while silicon LDMOS foundries in Taiwan and China exploit 8-inch depreciation curves to defend sub-4 GHz positioning.
Pricing Analysis
After-sales service contracts and multi-year maintenance agreements drive lifetime value capture for qualified GaN-SiC suppliers serving NATO radar programs. Three-tier pricing structure across ITAR-qualified defense-grade, MIIT-certified telecommunications-grade, and unqualified commercial-grade tiers separates procurement channels. Cost compression in mid-band massive MIMO amplifiers intensifies because Reliance Jio and Bharti Airtel bundle installation and 10-year service into fixed-price tenders. Mobile network operators in India and Brazil exhibit highest price sensitivity; United States defense contractors absorb premiums for hermetic packaging and radiation tolerance without volume elasticity.
Supply Chain Analysis
Inventory buffers for SiC substrates and GaN epitaxy equipment extend qualification timelines by 12-18 months regardless of device design capability. Upstream concentration centers on Wolfspeed's United States SiC ingot production, Sumitomo Electric's Japan substrate polishing, and China's MIIT-backed Yangtze River Delta foundry clusters for domestic carrier procurement. Raw material dependencies encompass high-purity gallium metal, 6-inch and 8-inch SiC wafers, and MOCVD reactor components subject to EAR export controls. Single-source vulnerability concentrates in Wolfspeed's captive 8-inch SiC supply, constraining competitor expansion. Distribution runs through tier-1 telecommunications equipment vendors including Ericsson, Nokia, and Huawei, which unbundle amplifier procurement from system integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense as GaN-on-silicon architectures threaten to displace GaN-on-SiC in cost-optimized mid-band massive MIMO configurations, forcing incumbents to anchor premium positioning through substrate control and qualification barriers.
For Market Incumbents: Compound captive SiC substrate access with ITAR qualification investments to defend margin pools in defense radar and satellite communications. Prioritize backward integration into 8-inch SiC ingot production or long-term offtake agreements with Wolfspeed to circumvent supply constraints. Expand GaN-on-silicon foundry partnerships in South Korea and Taiwan to capture Reliance Jio and Bharti Airtel procurement without diluting GaN-on-SiC premium tiers.
For New Entrants and Emerging Players: Differentiate on GaN-on-silicon cost optimization for India's mid-band massive MIMO tenders, where domestic content requirements under PLI scheme incentives privilege local assembly partners. Target Brazil's centralized 5G infrastructure auctions through partnerships with tier-1 vendor approved supplier lists. Pursue research institute procurement for particle accelerator and fusion energy applications, where custom pulsed FET specifications sustain niche margin structures outside telecommunications commodity pressures.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compound semiconductor foundries with multi-year defense supply agreements and MIIT-certified telecommunications qualifications. Long-term viability hinges on substrate access and export control compliance rather than device design alone. Acquisition target archetype: mid-cap GaN epitaxy specialists with existing ITAR facilities and underutilized 6-inch SiC capacity. Monitor EAR enforcement intensity as inflection indicator for domestic foundry valuation premiums in affected jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| SiC Substrate Capacity Expansion | Wolfspeed's 8-inch Durham expansion constrains competitor GaN-SiC amplifier output regardless of epitaxy capability. |
| MIIT Certification Investment | Domestic content ratios in China's state-backed carrier procurement privilege locally qualified foundry partnerships. |
| GaN-on-Silicon Foundry Partnership | Cost-optimized amplifiers for India's Reliance Jio and Bharti Airtel tenders capture volume without SiC supply dependence. |
| ITAR Qualification Maintenance | Defense radar modernization programs require 12-18 month classification reviews that sustain incumbent positioning. |
| Digital Pre-Distortion Integration | Linearization algorithm convergence with RF front-ends enables single-amplifier multi-band solutions reducing bill-of-materials. |
Study Parameters
Desk research of SEC 10-K filings, FCC spectrum allocation dockets, MIIT certification databases, and customs trade data preceded structured interviews with GaN HEMT device physicists, MOCVD operations managers, defense contractor procurement leads, and mobile network operator infrastructure planners. Primary fieldwork validated secondary estimates through bottom-up triangulation against foundry capacity utilization disclosures and top-down reconciliation with carrier capex deployment schedules.
Variance decomposition across technology substitution rates, substrate supply constraints, and regulatory certification timelines shaped analytical framework construction across the projection horizon. Segmentation dimensions modeled encompass product type, application, substrate technology, and end-user qualification tier. CAGRs derived from installed base replacement cycles, massive MIMO channel count expansion, and defense modernization program commitments. Industry-specific forecast inputs include Wolfspeed SiC wafer supply expansion schedules and MIIT 5G base station certification throughput rates.
The analysis sits within stated boundaries; outcomes outside sustained EAR enforcement, MIIT domestic content ratio maintenance, or Wolfspeed 8-inch yield achievement would require recalibration. Forecasts reflect documented assumptions regarding carrier deployment timelines and defense budget authorization patterns. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Multilayer Coupled Inductor Market
RF Components
Analog Phase Shifter Market
RF Components
RF Isolator Market
RF Components
Smartphone RF Power Amplifier Market
RF Components
Digital Radio Frequency Memory Market
RF Components
China Small Signal Transistor Market
RF Components
Dielectric Resonator Market
RF Components
Radio Frequency Filters Market
RF Components
Digital Phase Shifter Market
RF Components
RF Passive Component Market
RF Components
Z-Wave Products Market
RF Components
LTCC Power Dividers Market
RF Components
Phase Shifters Market
RF Components
Stand-Alone Radio Receivers Market
RF Components
High-Frequency RF Evaluation Board Market
RF Components
Radio Frequency Front End Market