
 RF Passive Component Market | 2026-2036
RF Passive Component Market Size, Share, and Industry Trends Forecast 2026-2036
RF Passive Component Market Insights
Modular filter-capacitor-resistor bundles is hardening as the dominant procurement format for 5G base station OEMs, compressing vendor lists and raising qualification barriers. Murata Manufacturing leverages its ceramic material science leadership to dominate high-frequency multilayer capacitor supply. TDK Corporation anchors European automotive radar programs through thick-film inductor specialization. Vishay Intertechnology competes across wirewound and thin-film resistor lines with broad distributor coverage.
RF passive components are non-amplifying circuit elements—resistors, capacitors, inductors, and filters—that manage impedance matching, signal filtering, and power distribution at frequencies from megahertz to millimeter-wave bands, typically manufactured through thin-film sputtering, thick-film screen printing, or ceramic co-firing processes with critical tolerances below one percent. Capacitor segments lead absolute revenue contribution due to volumetric efficiency demands in smartphone RF front-end modules, while filter categories register the steepest growth trajectory driven by carrier aggregation complexity in 5G and Wi-Fi 7 architectures. Ceramic technology occupies the largest installed manufacturing base, though thin-film processes capture premium margin pools in aerospace and defense applications where temperature stability and precision matter most.
FCC Part 15 emissions rules, ETSI EN 301 489 standards, and RoHS substance restrictions collectively dictate material selection, shielding performance, and market access qualification timelines for RF passive suppliers. REACH chemical registration requirements in Europe and China's GB standard certification further fragment compliance burdens across major demand centers. Stakeholders must monitor evolving millimeter-wave spectrum allocations and corresponding test specification changes to align R&D roadmaps with buyer qualification cycles.
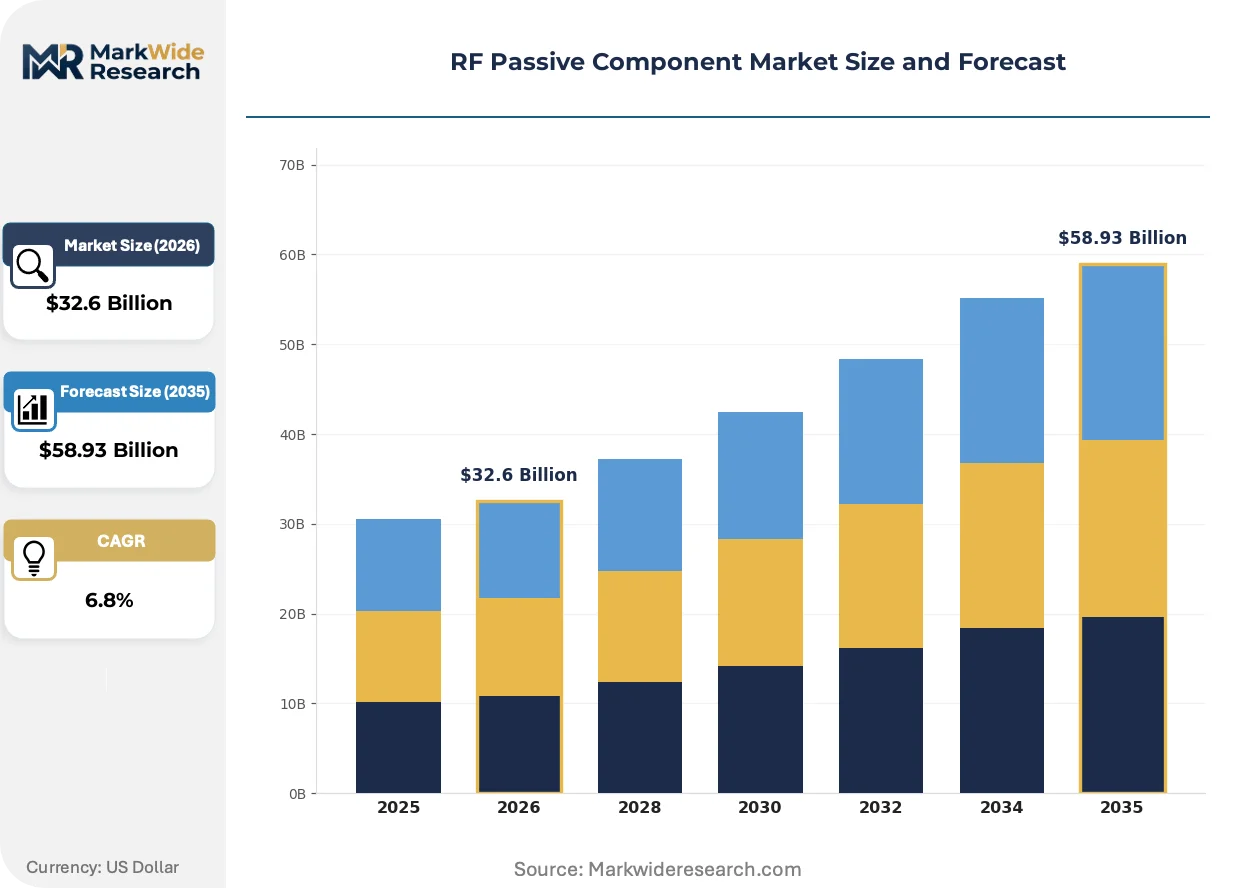
Market Dynamics
Base station densification for 5G mid-band and millimeter-wave deployments is compressing component qualification timelines while elevating electromagnetic compatibility thresholds, forcing suppliers to recalibrate material science roadmaps around ceramic co-firing and thin-film precision.
Growth Catalysts
- FCC Part 15 Emissions Mandates:Tighter spurious emission limits in the United States are accelerating replacement cycles for legacy ferrite-based filters with low-loss ceramic alternatives.
- Automotive Radar Proliferation:77-81 GHz frequency allocations for collision-avoidance systems in Germany and Japan are expanding thick-film inductor procurement volumes.
- Carrier Aggregation Complexity:Wi-Fi 7 and 5G-Advanced architectures require multiband filter arrays that single-package ceramic solutions address more efficiently than discrete alternatives.
Market Restraints
- Palladium and Silver Price Volatility:Thick-film resistor and capacitor electrode formulations depend on precious metal feedstocks subject to commodity exchange fluctuations.
- MLCC Concentration in East Asia:Multilayer ceramic capacitor manufacturing clusters heavily in Japan, South Korea, and China, creating single-source exposure for European and North American OEMs.
- Temperature Coefficient Limitations:Standard X7R and Y5V dielectrics exhibit capacitance drift under thermal stress that disqualifies them from aerospace signal-path applications.
Strategic Opportunities
- India Telecom Infrastructure Buildout:TRAI spectrum auctions and BharatNet rural connectivity targets are opening procurement channels for cost-optimized filter-capacitor bundles.
- RoHS Exemption Expiration:European lead-free soldering mandates are creating replacement demand for high-temperature stable ceramic formulations in industrial equipment.
- Antenna-in-Package Convergence:Integration of filter, switch, and antenna functions into single modules is consolidating vendor relationships around full RF front-end capability.
Industry Challenges
- Millimeter-Wave Test Engineering Scarcity:Vector network analysis and probe station operation above 40 GHz require specialized technician training that outpaces workforce development.
- ETSI EN 301 489 Certification Timelines:European electromagnetic compatibility approval cycles extend 14-22 weeks, delaying product launches for non-EU suppliers.
- Legacy Thick-Film Process Retention:Foundry equipment for older screen-printed resistor lines requires maintenance expertise that retiring workforces possess in diminishing numbers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RF Passive Component Market |
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $58.93 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Resistors, Capacitors, Inductors, Filters Technology: Thin Film, Thick Film, Wirewound, Ceramic Application: Telecommunications, Consumer Electronics, Automotive, Aerospace End User: OEMs, Component Distributors, Retailers, Research Institutions |
| Companies Covered | Murata Manufacturing, KYOCERA AVX, TDK Corporation, Vishay Intertechnology, Skyworks Solutions, Qorvo, Taiyo Yuden, Knowles Corporation, Walsin Technology Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RF Passive Component Market Trends and Innovations
Material science advances and regulatory harmonization pressures are compressing the technology refresh cycle for RF passive components, with ceramic precision and electromagnetic shielding emerging as the decisive performance axes.
Thin-film sputtered tantalum nitride resistors is consolidating position in test-and-measurement and aerospace applications where temperature coefficients below 25 ppm/°C are mandatory. Defense contractors and satellite manufacturers in the United States and France are specifying these devices for phased-array radar signal conditioning. The technology is consolidating vendor tiers by disqualifying thick-film alternatives from high-reliability procurement lists.
REACH chemical registration requirements in Europe are restricting hexavalent chromium use in surface finishes and nickel content in electrode materials for RF components sold into automotive and medical devices. ECHA substance-of-very-high-concern listings are forcing reformulation of termination platings across capacitor and inductor product lines. German automotive suppliers are responding fastest, with several Tier-1 firms mandating full material disclosure down to smelter-level sourcing.
Modular procurement of pre-matched filter-LNA-switch assemblies is displacing discrete component purchasing among 5G infrastructure OEMs in South Korea and the United States. This bundling compresses supplier lists from dozens of specialized passive vendors to a handful of integrated module providers. The shift is most visible in massive MIMO antenna shipments, where RF front-end integration density directly correlates with base station cabinet size reduction targets.
RF Passive Component Market Segmentation
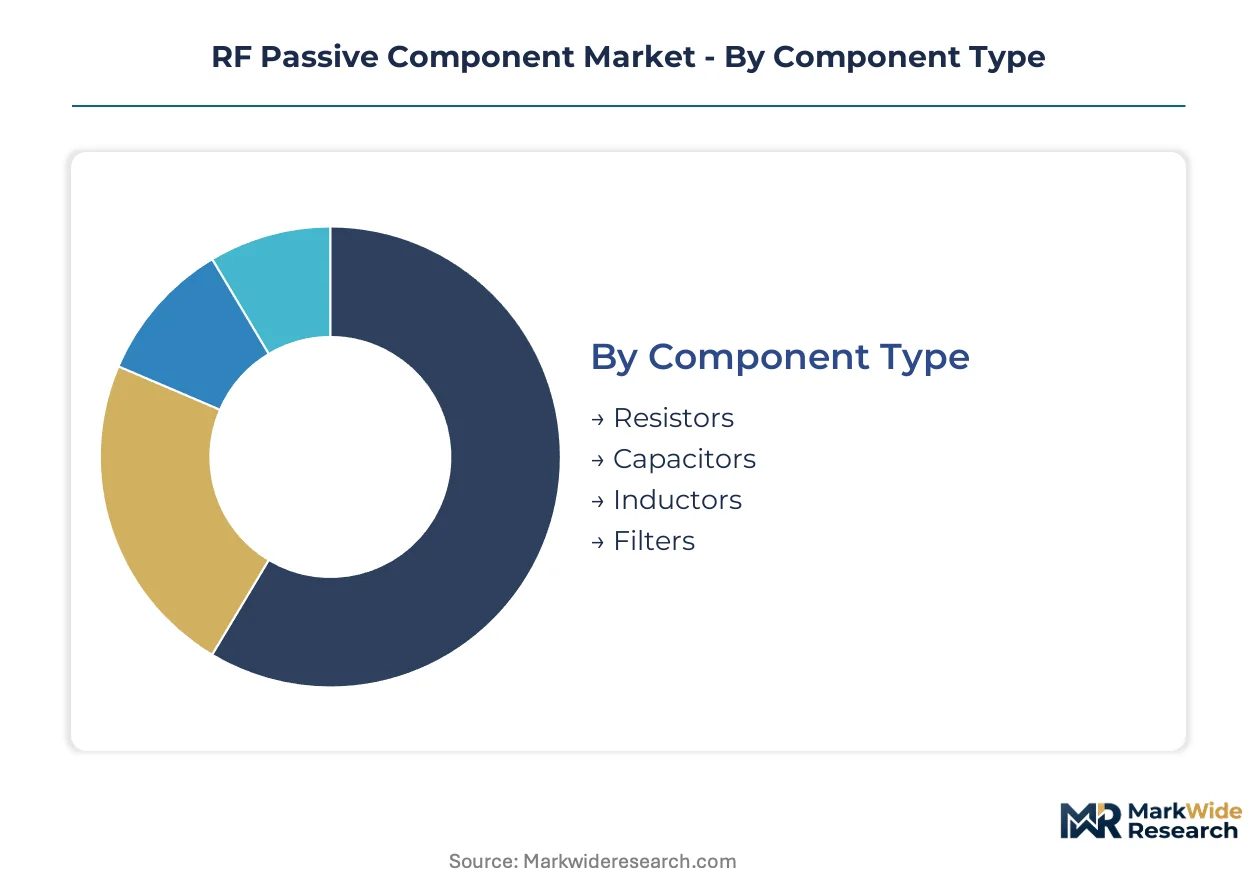
RF passive component procurement splits sharply between discrete catalog sales and integrated module supply, with bundling economics reshaping how each segment captures value across frequency bands and reliability tiers.
Component Type:
Standalone discretes dominate low-complexity replacement markets while multicomponent assemblies capture design-win economics in 5G infrastructure.
- Resistors:Wirewound and thin-film constructions manage precision current limiting in test equipment and satellite signal chains. Thick-film chip resistors supply high-volume automotive electronics from German Tier-1 module suppliers facing REACH termination plating mandates.
- Capacitors:Multilayer ceramic formulations achieve volumetric efficiency below 0402 case sizes for smartphone RF front-end integration. X7R and C0G dielectrics from Japanese manufacturers supply carrier aggregation filters in South Korean base station programs where temperature stability requirements exclude standard formulations.
- Inductors:Ferrite-core and air-core variants address impedance matching across sub-6 GHz and millimeter-wave bands.
- Filters:Surface acoustic wave and bulk acoustic wave devices enable band-selective signal routing.
Capacitors lead volumes today; filters are gaining share fastest.
Technology:
Process selection tracks precision requirements and thermal operating windows, with automotive and aerospace specifications diverging from consumer-grade tolerance bands.
- Thin Film:Sputtered metal layers on ceramic substrates deliver temperature coefficients below 25 ppm/°C for aerospace phased-array radar and precision test instrumentation. US defense contractors specify tantalum nitride resistor networks for satellite signal conditioning where thick-film drift disqualifies alternatives.
- Thick Film:Screen-printed resistive and dielectric pastes on alumina substrates balance cost and performance for automotive sensor modules. German automotive radar programs source thick-film inductors for 77-81 GHz collision-avoidance systems from European foundries with established KBA component qualification.
- Wirewound:Precision-wound copper or nickel-chrome on ceramic cores handles high-power dissipation.
- Ceramic:Co-fired multilayer structures dominate high-frequency capacitor and filter manufacturing.
Ceramic occupies the largest installed base; thin film captures the steepest margin expansion.
Application:
End-use concentration determines qualification burden and procurement format, with infrastructure OEMs consolidating vendor relationships faster than consumer electronics buyers.
- Telecommunications:5G base station densification drives multiband filter-capacitor bundle procurement from South Korean and US infrastructure OEMs. FCC Part 15 spurious emission mandates accelerate ceramic filter replacement of legacy ferrite designs in macro cell and small cell deployments.
- Consumer Electronics:Smartphone RF front-end modules demand 0201 and smaller case sizes for capacitors and inductors. Japanese component houses supply high-frequency multilayer ceramics to flagship handset programs where board area constraints dominate specification priorities.
- Automotive:Radar and telematics integration expands thick-film and ceramic component volumes.
- Aerospace:Satellite and defense applications specify high-reliability screening levels.
Telecommunications leads absolute procurement value; automotive is climbing the fastest.
End User:
Channel structure fragments between direct OEM contracting for high-reliability programs and distributor-mediated fulfillment for maintenance and repair operations.
- OEMs:Original equipment manufacturers in telecommunications and automotive sectors negotiate multi-year supply agreements for qualified component families. 5G infrastructure OEMs in the United States and South Korea compress supplier lists through modular filter-LNA-switch procurement that eliminates discrete passive vendors.
- Component Distributors:Arrow, Avnet, and regional specialists manage inventory and logistics for mid-volume electronics manufacturers. European industrial equipment OEMs rely on distributor stocking programs to navigate RoHS exemption transitions without line-down risk.
- Retailers:Catalog and online channels serve prototype and repair demand.
- Research Institutions:University and government laboratories source precision components for experimental RF systems.
OEMs dominate contract value; distributors handle the widest SKU breadth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RF passive component manufacturing traces its modern origins to post-war Japan, where ceramic co-firing techniques pioneered in Kyoto and Osaka established the technical foundation for multilayer capacitor production. That Japanese industrial base subsequently seeded specialized clusters across East Asia and selective capabilities in North America and Europe.
Japan
Domestic demand for smartphone RF front-end modules and automotive radar systems sustains high-volume production of multilayer ceramic capacitors and surface acoustic wave filters. METI's component technology roadmaps prioritize millimeter-wave material science for 6G pre-standardization research. Kyoto-Osaka corridor manufacturers supply precision thin-film components to domestic aerospace and defense contractors with exacting temperature coefficient specifications.
China
Base station densification for 5G mid-band and millimeter-wave deployments drives procurement of ceramic filter-capacitor bundles from state-owned telecommunications operators. MIIT GB standard certification mandates electromagnetic compatibility testing that extends qualification timelines for imported components. Shenzhen and Dongguan electronics manufacturing clusters concentrate assembly operations for consumer-grade RF passives serving domestic handset OEMs and export markets.
South Korea
Massive MIMO antenna shipments for 5G-Advanced infrastructure compress supplier lists around integrated module providers capable of filter-LNA-switch assemblies. MFDS medical device regulations indirectly shape component specifications for telehealth hardware exports. Seoul-Incheon metropolitan area hosts R&D centers where domestic telecommunications OEMs co-develop ceramic formulations with material science partners.
United States
Defense contractors and satellite manufacturers specify tantalum nitride thin-film resistor networks for phased-array radar signal conditioning where thick-film alternatives fail temperature stability requirements. FCC Part 15 spurious emission mandates accelerate replacement of legacy ferrite-based filters with low-loss ceramic designs in macro cell deployments. Greater Boston and Southern California clusters concentrate aerospace-focused precision component manufacturing.
Germany
Automotive radar programs for 77-81 GHz collision-avoidance systems source thick-film inductors from European foundries with established KBA component qualification. REACH chemical registration requirements restrict hexavalent chromium in surface finishes and nickel content in electrode materials, forcing reformulation of termination platings. Bavaria-based Tier-1 automotive suppliers mandate full material disclosure down to smelter-level sourcing for RF passives in radar and telematics modules.
RF Passive Component Market Competitive Landscape
Premium-margin players sit above commodity-margin players across precision and reliability tiers, with thin-film specialists commanding price multiples over thick-film volume producers. The vendor structure concentrates around integrated module providers capable of full RF front-end capability, while discrete component specialists face narrowing procurement channels. Three archetypes dominate: ceramic material science leaders, thick-film automotive radar specialists, and broad-line distributors with wirewound and thin-film resistor coverage. Competitive moves center on modular bundle qualification for 5G infrastructure OEMs and backward integration into ceramic powder formulation.
Among Japanese material science conglomerates, Murata Manufacturing, TDK Corporation, and Taiyo Yuden occupy positions defined by ceramic co-firing expertise and multilayer capacitor volumetric efficiency. These entities exemplify the premium-tier archetype where temperature-stable dielectric formulations and sub-0402 case size capabilities create qualification barriers. Their geographic concentration in the Kyoto-Osaka corridor reinforces supply relationships with domestic telecommunications and automotive OEMs. The competitive dynamic between these players and Korean module integrators shapes procurement consolidation trends in 5G base station programs.
| Leading Market Players |
|---|
| Murata Manufacturing |
| KYOCERA AVX |
| TDK Corporation |
| Vishay Intertechnology |
| Skyworks Solutions |
| Qorvo |
| Taiyo Yuden |
| Knowles Corporation |
| Walsin Technology Corporation |
| Others |
Pricing and Supply Chain Analysis
REACH chemical registration mandates in Europe gate qualified supply for RF passive components destined for automotive and medical device markets, simultaneously compressing vendor pools and elevating premium-tier pricing access for suppliers with full material disclosure capabilities down to smelter-level sourcing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with price differentiation resting on temperature coefficient precision and REACH compliance certification. Cost compression in standard-grade thick-film resistors is intensifying because palladium and silver electrode feedstock volatility erodes margin buffers. Automotive Tier-1 module suppliers exhibit the sharpest price sensitivity due to volume procurement leverage, while aerospace defense contractors show minimal elasticity given mission-critical reliability requirements.
Supply Chain Analysis
Single-source vulnerability sits with multilayer ceramic capacitor manufacturing clusters in Japan, South Korea, and China, creating geographic concentration risk for European and North American OEMs. Raw material dependencies draw from high-purity barium titanate ceramic powders, palladium and silver electrode pastes, and nickel-chrome resistor formulations. Tariff exposure on Chinese-sourced ceramic substrates feeds into component cost structures. Distribution runs through Arrow and Avnet for mid-volume industrial equipment manufacturers, while telecommunications infrastructure OEMs negotiate direct multi-year supply agreements with Japanese material science conglomerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where FCC Part 15 emissions mandates and ETSI EN 301 489 electromagnetic compatibility standards continuously refresh replacement demand cycles.
For Market Incumbents: Cement ceramic material science leadership through backward integration into high-purity dielectric powder formulation, defending against emerging thin-film specialists from Greater Boston aerospace clusters. Prioritize qualification investment for modular filter-LNA-switch bundles to capture 5G infrastructure OEM consolidation. Capacity addition in India addresses BharatNet rural connectivity procurement channels before domestic competitors establish KBA-equivalent qualification pathways. For New Entrants and Emerging Players: Capture cost-optimized filter-capacitor bundle opportunities in India's TRAI-spectrum-driven telecom infrastructure buildout, the most penetrable geography given incumbent concentration in East Asian supply relationships. Target industrial equipment replacement demand as European RoHS exemption expiration forces high-temperature stable ceramic procurement. Pursue co-development partnerships with Seoul-based telecommunications OEMs seeking alternative ceramic formulation suppliers for 5G-Advanced massive MIMO programs. For Investors and Strategic Acquirers: Roll-up economics work for thin-film precision specialists because temperature coefficient capabilities below 25 ppm/°C disqualify thick-film alternatives from aerospace and defense procurement lists, creating durable margin pools. Long-term viability hinges on millimeter-wave test engineering workforce development and antenna-in-package integration capabilities. Watch ECHA substance-of-very-high-concern listing velocity as the inflection indicator for forced reformulation cycles across termination plating supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Powder Formulation | Murata and TDK secure captive supply of high-purity barium titanate against feedstock volatility. |
| Modular Filter-LNA-Switch Bundle Qualification | South Korean massive MIMO OEMs compress supplier lists from dozens to integrated module providers. |
| REACH-Compliant Termination Plating Reformulation | German Tier-1 automotive suppliers mandate full material disclosure down to smelter-level sourcing. |
| Millimeter-Wave Test Engineering Workforce Development | Vector network analysis above 40 GHz requires specialized technician training that outpaces supply. |
| India Telecom Infrastructure Direct Contracting | TRAI spectrum auctions open procurement channels bypassing East Asian distributor intermediaries. |
Research Methodology
Direct dialogue with RF component procurement managers at telecommunications infrastructure OEMs, ceramic material science R&D directors, automotive Tier-1 supplier quality engineers, and distributor inventory planners grounded qualitative findings. Secondary validation drew from FCC Part 15 rulemaking dockets, ETSI EN 301 489 certification databases, ECHA REACH substance registrations, and SEC 10-K filings from Japanese component manufacturers. Bottom-up and top-down triangulation cross-checked volumetric demand assumptions against foundry capacity disclosures.
Segment-level outputs across the analysis window reflect component type, technology process, application vertical, and end-user channel structure. CAGRs were derived from installed base replacement cycles, spectrum allocation timelines, and automotive radar frequency band expansion. Industry-specific inputs included palladium spot price correlation models, MLCC case size adoption curves, and electromagnetic compatibility test specification evolution.
Millimeter-wave spectrum reallocation, precious metal commodity volatility, and REACH substance listing acceleration are the dominant revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Noise Suppression Components Market
RF Components
RF Antenna Market
RF Components
RF Components Market
RF Components
RF-Microwave for 5G Market
RF Components
Asia-Pacific Small Signal Transistor Market
RF Components
RFID Tags Market
RF Components
Radiofrequency Identification (RFID) Market
RF Components
Wireless Module Market
RF Components
FBAR Devices Market
RF Components
High Reliability Oscillators Market
RF Components
Radio Frequency Counter Market
RF Components
High-Frequency RF Evaluation Board Market
RF Components
US RFID Tags Market
RF Components
Radio Frequency Front End Module Market
RF Components
SMD Resonator Market
RF Components
RF Power Amplifiers Market