
 Digital Radio Frequency Memory Market | 2026-2036
Digital Radio Frequency Memory Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Radio Frequency Memory Market Analysis
Software-defined threat emulation is hardening as the dominant service layer in DRFM contracting, shifting procurement from hardware-only transactions to capability-as-a-service models. Lockheed Martin leverages its classified program footprint to sustain multi-year sustainment contracts across Pentagon electronic warfare divisions. Raytheon Technologies anchors its position through captive semiconductor fabrication for radio frequency components. BAE Systems differentiates via sovereign capability partnerships with UK and Australian defense ministries.
Digital Radio Frequency Memory constitutes a signal processing subsystem that digitizes incoming radio frequency signals, stores them in high-speed memory buffers, and regenerates modulated outputs with programmable delay and Doppler characteristics for electronic attack and protection missions. Modern DRFM units achieve instantaneous bandwidths exceeding 1 GHz through direct radio frequency sampling architectures, enabling precise coherent jamming against phased-array radars. The defense application segment commands the dominant revenue share given classified program volumes and sovereign security requirements, while the module form factor represents the fastest-growing category as integrators seek standardized building blocks for rapid platform adaptation. FRAM technology occupies a niche position in radiation-hardened deployments, whereas SRAM dominates latency-critical electronic warfare applications where rewrite endurance matters less than access speed.
The US Department of Defense's electromagnetic spectrum superiority strategy shapes procurement priorities, while NATO's joint electronic warfare core staff establishes interoperability standards for allied DRFM systems. The UK's Defence Science and Technology Laboratory and France's Direction Générale de l'Armement both mandate domestic source verification for critical radio frequency subsystems, constraining vendor eligibility. Stakeholders must monitor how export control recalibrations under the Wassenaar Arrangement affect technology transfer pathways for reprogrammable jamming architectures.
Market Dynamics
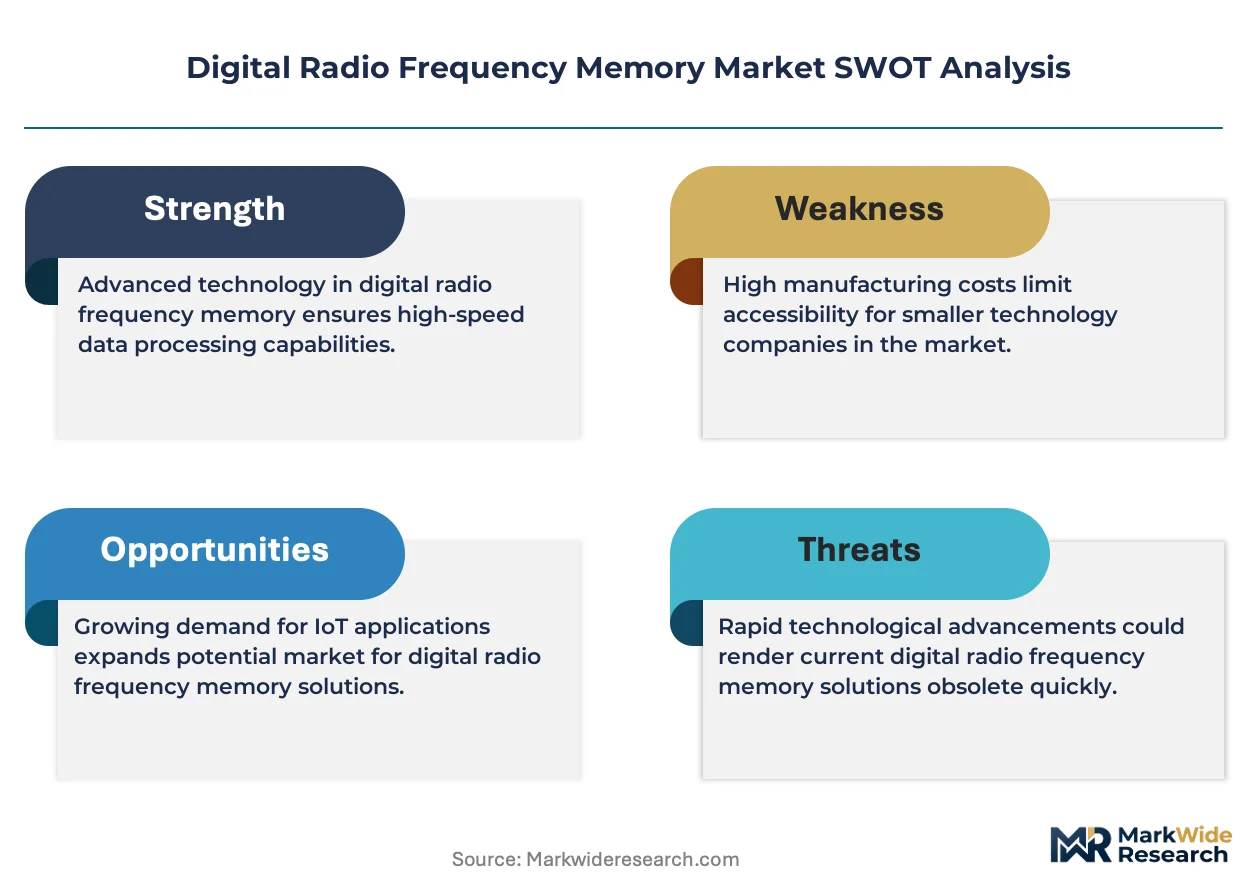
Gallium nitride semiconductor maturation is compressing development cycles for wideband DRFM architectures, while electromagnetic spectrum superiority mandates from the US Department of Defense reshape procurement specifications across allied defense industrial bases.
Growth Catalysts
- Electronic warfare training expansion:NATO joint electronic warfare core staff protocols mandate interoperable DRFM systems for allied exercises, creating standardized demand across member state procurement agencies.
- Direct RF sampling architectures:These designs eliminate analog downconversion stages, reducing latency and enabling coherent jamming against modern phased-array radars in contested electromagnetic environments.
- US electromagnetic spectrum superiority strategy:This framework prioritizes reprogrammable electronic attack capabilities, directing classified program funding toward adaptive DRFM subsystems.
Market Restraints
- Gallium nitride substrate supply concentration:US-based defense contractors depend on limited qualified foundry capacity for radiation-hardened GaN-on-SiC wafers, creating single-source vulnerability.
- Domestic source verification mandates:UK Defence Science and Technology Laboratory and France's Direction Générale de l'Armement regulations restrict vendor eligibility for critical radio frequency subsystems.
- Export control recalibration under Wassenaar Arrangement:These multilateral restrictions constrain technology transfer pathways for reprogrammable jamming architectures, lengthening sales cycles.
Strategic Opportunities
- Module form factor standardization:Platform integrators seek building-block DRFM units for rapid adaptation across unmanned aerial systems and naval platforms, opening systems integration channels.
- Australian sovereign capability partnerships:BAE Systems' established collaboration model with the Australian defense ministry demonstrates replicable pathways for other mid-tier defense industrial bases.
- Software-defined threat emulation services:Capability-as-a-service contracting models displace hardware-only transactions, creating recurring revenue streams and deeper customer lock-in.
Industry Challenges
- Cleared workforce scarcity:Electronic warfare subsystem development requires personnel with active security clearances, constraining engineering headcount expansion at prime contractors.
- SRAM radiation tolerance limitations:Latency-critical applications demand memory technologies with insufficient rewrite endurance for extended orbital or high-altitude deployments, forcing FRAM trade-offs.
- Legacy platform integration friction:Existing aircraft and shipboard electronic warfare suites operate on proprietary architectures, complicating DRFM retrofit programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Radio Frequency Memory Market |
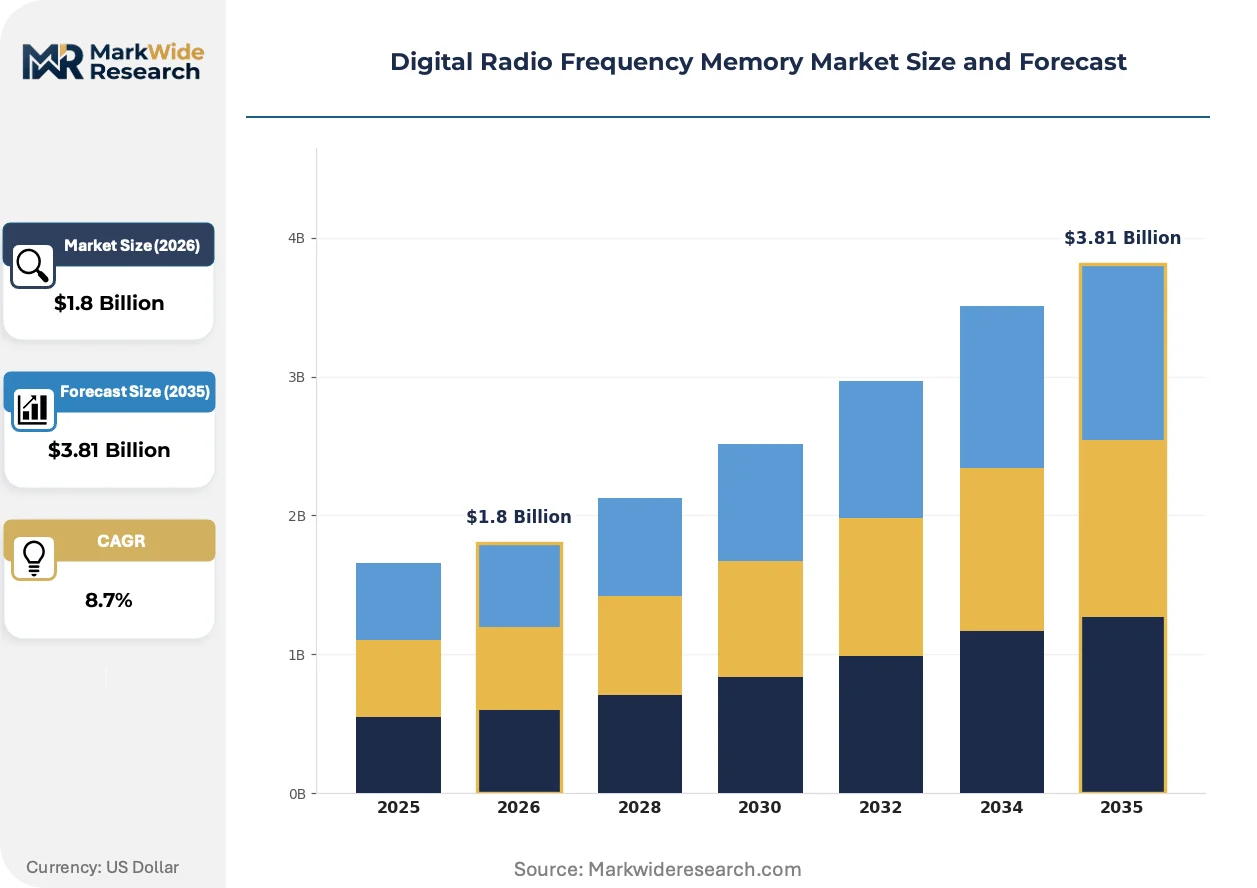
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Telecommunications, Consumer Electronics, Automotive, Defense End User: OEMs, Telecom Operators, Research Organizations, Government Agencies Technology: FRAM, MRAM, SRAM, DRAM Form Factor: Chip, Module, Board, Package |
| Companies Covered | Thales Group, Lockheed Martin Corporation, Raytheon Technologies Corporation, Rohde & Schwarz, Leonardo S.p.A., BAE Systems, Elbit Systems Ltd., L3Harris Technologies, Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Radio Frequency Memory Market Emerging Trajectories
Signal processing architectures are converging with artificial intelligence inference engines, enabling real-time threat classification and adaptive jamming waveform generation without human-in-the-loop latency.
Direct radio frequency sampling chipsets are integrating machine learning accelerators for instantaneous threat library matching. US Navy airborne electronic attack squadrons are fielding these units for reactive jamming against frequency-agile radars. This convergence is integrating cognitive electronic warfare capabilities into previously deterministic hardware platforms.
EU export control harmonization under the Wassenaar Arrangement is tightening technology transfer scrutiny for reprogrammable signal processors. Dual-use classification ambiguity creates compliance overhead for vendors serving both defense and commercial satellite markets. European prime contractors are responding by segregating product lines into defense-only and commercial variants with distinct firmware architectures.
Defense procurement agencies are consolidating electronic warfare sustainment under multi-year performance-based agreements. The Pentagon's electronic warfare divisions now prioritize availability metrics over unit acquisition costs, shifting vendor selection toward integrated logistics support capability. This pattern concentrates contract awards with primes possessing classified program infrastructure and captive semiconductor fabrication.
Digital Radio Frequency Memory Market Segmentation
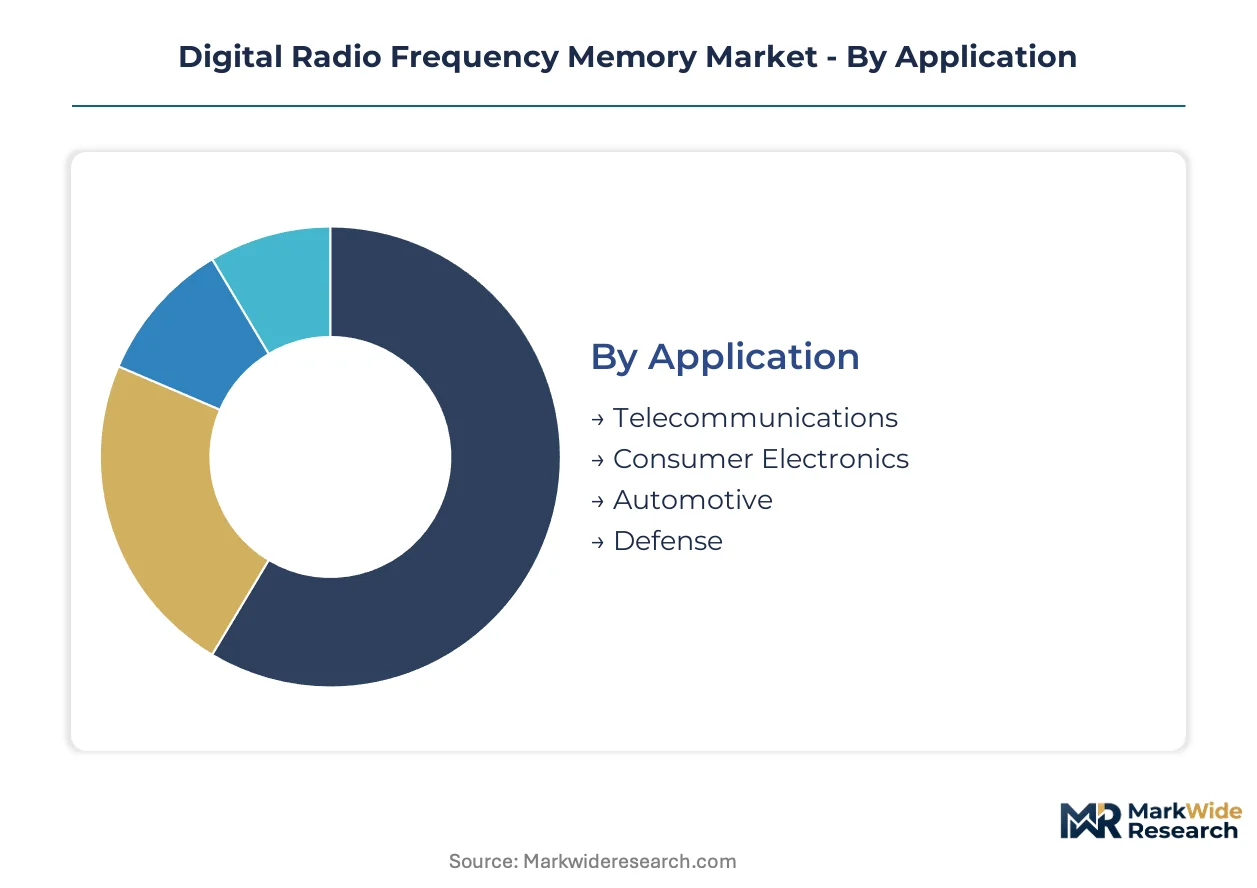
DRFM procurement patterns diverge sharply between sovereign defense programs demanding bespoke architectures and commercial integrators seeking standardized building blocks. Segmentation reveals how memory technology selection, form factor modularity, and end-user security clearance levels reshape vendor competitive positioning across distinct revenue pools.
Application:
Standardized interfaces dominate telecommunications and consumer electronics procurement, while defense applications require extensive customization for classified electromagnetic spectrum operations.
- Defense:Classified program volumes concentrate procurement around reprogrammable jamming subsystems with sovereign security requirements. Pentagon electronic warfare divisions and NATO joint electronic warfare core staff protocols mandate interoperable systems, creating multi-year sustainment contracts with primes possessing cleared infrastructure.
- Telecommunications:Base station infrastructure and spectrum monitoring equipment drive demand for wideband signal processing. Telecom operators prioritize cost-optimized modules with rapid firmware upgradeability over radiation-hardened specifications.
- Automotive:Autonomous vehicle radar testing and V2X communication validation create emerging demand for portable threat emulation units. Automotive OEMs favor compact module form factors for integration into mobile test fleets.
- Consumer Electronics:Minimal direct DRFM penetration; limited to high-end spectrum analyzer accessories and hobbyist radio equipment. Volume constraints relegate this segment to derivative chip sales through distribution channels.
Leading the category by volume: Defense. Growing fastest: Automotive.
End User:
Security clearance requirements and procurement authority levels segment this category into closed sovereign channels and open commercial markets with diverging vendor qualification barriers.
- Government Agencies:US Department of Defense electromagnetic spectrum superiority strategy directs classified program funding. Procurement concentrates through Maryland and Virginia defense industrial corridors with mandatory domestic source verification.
- OEMs:Platform integrators seek standardized DRFM building blocks for rapid adaptation across unmanned aerial systems and naval electronic warfare suites. Module form factor preference reflects pressure to reduce non-recurring engineering costs.
- Telecom Operators:Spectrum auction winners and infrastructure deployers purchase signal monitoring equipment with embedded DRFM subsystems. Procurement emphasizes interoperability certification over raw performance specifications.
- Research Organizations:University laboratories and federally funded research centers acquire development kits for algorithm validation. Wassenaar Arrangement export controls constrain international technology transfer for reprogrammable architectures.
Dominant procurement authority: Government Agencies. Expanding most quickly: OEMs.
Technology:
Memory cell architecture selection trades radiation tolerance, rewrite endurance, and access latency against mission-specific electromagnetic environment requirements.
- SRAM:Dominates latency-critical electronic warfare applications where sub-microsecond access enables coherent jamming against frequency-agile radars. Rewrite endurance limitations acceptable for terrestrial deployments with maintenance access.
- FRAM:Ferroelectric random-access memory occupies radiation-hardened orbital and high-altitude deployments where rewrite endurance exceeds SRAM capabilities. Limited qualified foundry capacity constrains supply expansion.
- MRAM:Magnetoresistive architectures emerging for non-volatile storage in power-constrained unmanned platforms. Density limitations currently restrict deployment to buffer memory roles rather than primary signal storage.
- DRAM:Cost-optimized bulk storage for training and simulation environments with benign thermal and radiation profiles. Refresh requirements introduce latency penalties unacceptable for reactive jamming missions.
Widest deployment: SRAM. Steepest expansion trajectory: MRAM.
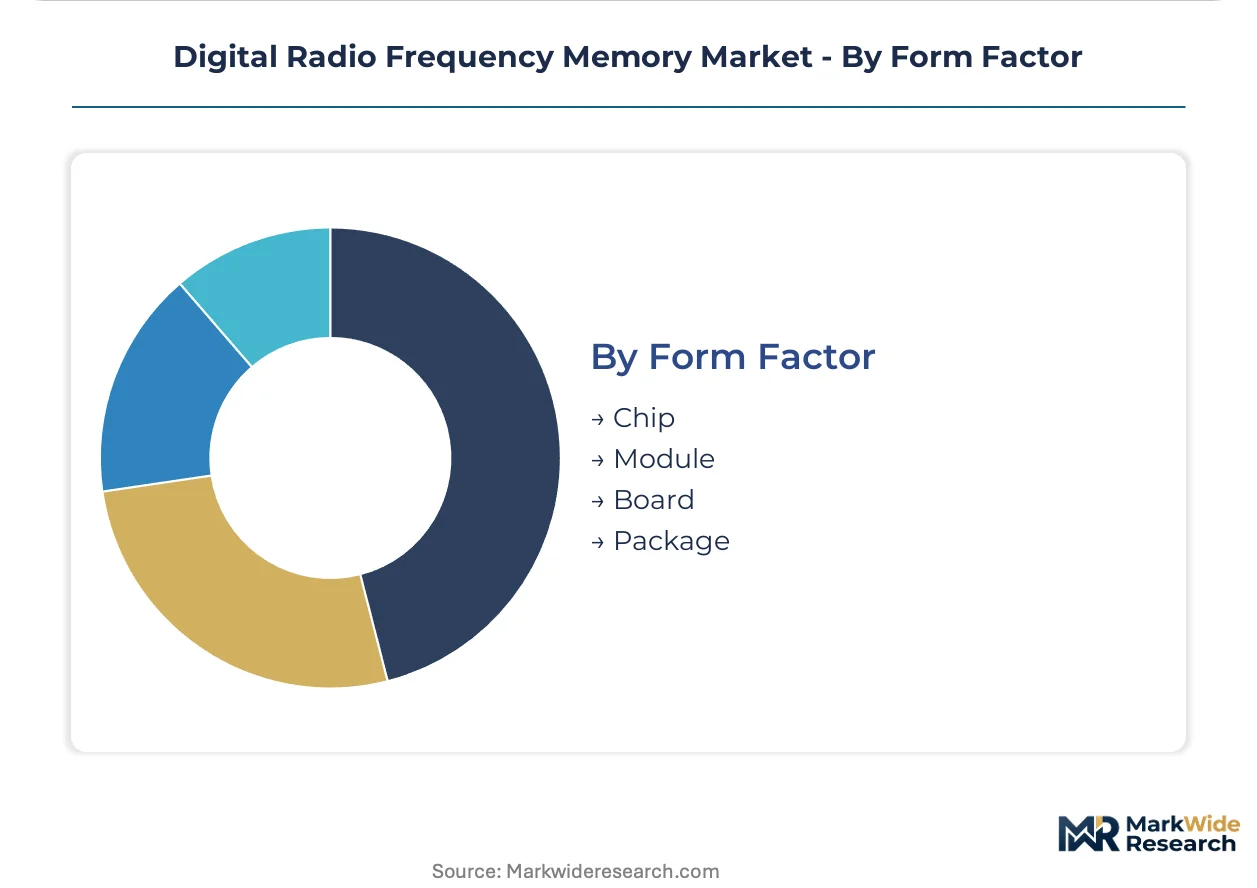
Form Factor:
Integration depth requirements segment procurement from discrete components through fully qualified subsystems, with platform retrofit constraints driving modular intermediate solutions.
- Module:Standardized building blocks enable rapid platform adaptation across unmanned aerial systems and naval electronic warfare suites. Platform integrators drive fastest category expansion through reduced non-recurring engineering.
- Chip:Bare die procurement serves captive semiconductor fabrication at primes like Raytheon Technologies and specialized radiation-hardened foundries. Volume concentrates in classified program supply chains with long qualification cycles.
- Board:Custom printed circuit board assemblies address legacy platform integration friction in existing aircraft and shipboard electronic warfare suites. Proprietary architecture mismatches sustain niche demand despite higher unit costs.
- Package:Fully integrated hermetic enclosures for orbital and submerged deployments with extreme environmental sealing requirements. Limited volume reflects concentrated demand from satellite and submarine programs.
Highest shipment volume: Module. Gaining share fastest: Chip.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement concentrates manufacturing in the United States while allied nations import subsystems or establish sovereign production partnerships. Consumption patterns diverge between NATO interoperability mandates and national security requirements driving domestic source verification.
United States
The Pentagon's electromagnetic spectrum superiority strategy directs classified program funding toward adaptive DRFM subsystems. Maryland and Virginia defense industrial corridors host prime contractor facilities with mandatory domestic source verification for critical radio frequency components. US-based contractors face single-source vulnerability for radiation-hardened GaN-on-SiC wafers from limited qualified foundry capacity.
United Kingdom
The Defence Science and Technology Laboratory mandates domestic source verification for critical radio frequency subsystems, restricting vendor eligibility. UK sovereign capability partnerships with BAE Systems demonstrate replicable pathways for classified electronic warfare programs. Procurement concentrates around interoperability requirements with NATO joint electronic warfare core staff protocols.
France
The Direction Générale de l'Armement enforces domestic source verification regulations constraining foreign vendor participation in critical subsystems. French defense procurement prioritizes sovereign electronic attack capabilities aligned with national electromagnetic spectrum superiority objectives. Industrial activity clusters around Paris-Saclay defense research corridors and Toulouse aerospace electronics manufacturing.
Germany
Rohde & Schwarz anchors domestic signal processing expertise serving both defense and telecommunications applications. German procurement agencies emphasize NATO interoperability standards while maintaining sovereign test and measurement capabilities. Industrial concentration in Bavaria and Baden-Württemberg supports precision radio frequency component manufacturing.
Australia
BAE Systems' established sovereign capability partnership model with the Australian defense ministry creates replicable pathways for mid-tier defense industrial bases. Australian procurement prioritizes interoperability with allied electronic warfare systems through standardized DRFM architectures. Industrial activity concentrates in Adelaide defense technology precincts and Canberra procurement corridors.
Digital Radio Frequency Memory Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the DRFM value chain, with captive semiconductor fabrication distinguishing primes from subsystem integrators. The vendor base stratifies between cleared infrastructure holders and commercial component suppliers. Three archetypes dominate: primes with classified program footprints, sovereign capability partners, and specialized radio frequency component fabricators. Competitive moves concentrate on multi-year sustainment contract consolidation and module form factor standardization for rapid platform adaptation.
Within the prime contractor tier, Lockheed Martin Corporation and Raytheon Technologies Corporation exemplify archetypes distinguished by cleared infrastructure scale and captive fabrication capabilities. BAE Systems occupies a position representing sovereign partnership models with UK and Australian defense ministries. These three entities anchor competitive positioning through distinct vectors: classified program access, semiconductor supply chain control, and allied government collaboration frameworks.
| Leading Market Players |
|---|
| Thales Group |
| Lockheed Martin Corporation |
| Raytheon Technologies Corporation |
| Rohde & Schwarz |
| Leonardo S.p.A. |
| BAE Systems |
| Elbit Systems Ltd. |
| L3Harris Technologies |
| Northrop Grumman Corporation |
| Others |
Supply Flow & Price Mechanics
Gallium nitride substrate costs cascade through DRFM procurement tiers, with radiation-hardened GaN-on-SiC wafer scarcity compressing margins at module integrators while concentrating pricing power among captive foundry operators serving classified Pentagon programs.
Pricing Analysis
Cost-down pressure on module form factors accelerates because platform integrators demand standardized building blocks for unmanned aerial systems and naval retrofits. Three-tier pricing structure across radiation-hardened, military-grade, and commercial variants reflects certification level and sovereign security clearance requirements. Price erosion runs through commercial telecommunications segments as telecom operators prioritize cost-optimized units with rapid firmware upgradeability. Government agencies exhibit lowest price sensitivity given classified program mandates and multi-year sustainment contracting, while automotive OEMs negotiating portable threat emulation volumes demonstrate highest sensitivity to unit economics.
Supply Chain Analysis
Refurbishment flows for legacy aircraft electronic warfare suites create secondary component markets, extending useful life of proprietary board-level assemblies against module standardization trends. Manufacturing concentrates in the United States, United Kingdom, and Germany, with GaN semiconductor fabrication anchored in Maryland-Virginia defense corridors and Toulouse aerospace electronics clusters. Raw material dependencies span silicon carbide substrates, high-speed analog-to-digital converters, and radiation-hardened memory cells. Single-source vulnerability for qualified GaN-on-SiC foundry capacity represents the dominant structural risk. Distribution runs through prime contractor classified program channels and sovereign capability partnerships with allied defense ministries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified foundry capacity for radiation-hardened GaN-on-SiC wafers constitutes the binding supply constraint, sustaining pricing premiums for cleared infrastructure holders across the analysis window.
For Market Incumbents: To counter SRAM radiation tolerance limitations in extended orbital deployments, prioritize backward integration into ferroelectric memory foundry partnerships and expand module form factor standardization for unmanned platform rapid adaptation. Lockheed Martin's multi-year sustainment contract consolidation demonstrates the defensive value of classified program infrastructure depth. For New Entrants and Emerging Players: Enter via automotive radar testing and V2X communication validation segments, where autonomous vehicle OEMs seek portable threat emulation units with minimal sovereign security clearance barriers. Target Australian sovereign capability partnership pathways as replicable models for mid-tier defense industrial base penetration, leveraging BAE Systems' established collaboration framework with Canberra procurement corridors. For Investors and Strategic Acquirers: NATO joint electronic warfare core staff protocol ratification is the leading indicator that interoperability standardization will consolidate contract awards toward primes with cleared infrastructure. Long-term viability favors asset-light designers with software-defined threat emulation service capabilities over capital-heavy hardware producers. Acquisition target archetype: specialized radio frequency component fabricators with radiation-hardened qualification pedigree. Monitor Wassenaar Arrangement export control recalibrations for reprogrammable jamming architecture licensing restrictions as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Captive GaN Semiconductor Fabrication | Raytheon Technologies' in-house production insulates against single-source foundry vulnerability in Pentagon supply chains. |
| Software-Defined Threat Emulation Services | Capability-as-a-service contracting displaces hardware transactions, creating recurring revenue with deeper customer lock-in. |
| Sovereign Capability Partnerships | BAE Systems' UK-Australian defense ministry collaborations demonstrate replicable pathways for classified program access. |
| Module Form Factor Standardization | Platform integrators reduce non-recurring engineering costs through building-block architectures for unmanned systems. |
| Direct RF Sampling Architecture Investment | Elimination of analog downconversion stages enables coherent jamming against frequency-agile phased-array radars. |
Methodological Framework
Document review covered SEC 10-K filings from prime contractors, NATO joint electronic warfare core staff protocol documentation, and Wassenaar Arrangement export control registers, complemented by interviews with Pentagon electronic warfare program officers, platform integration engineers at unmanned systems OEMs, and procurement leads at sovereign defense ministries. Secondary validation drew from Department of Defense electromagnetic spectrum superiority strategy publications, UK Defence Science and Technology Laboratory procurement guidelines, and French Direction Générale de l'Armement domestic source verification regulations. Bottom-up segment sizing triangulated against top-down defense budget allocation analysis.
Historical contract award patterns cross-referenced with panel input from cleared infrastructure holders informed the analytical framework across the projection horizon. Segmentation dimensions modeled encompass application type, end-user procurement authority level, memory cell technology architecture, and form factor integration depth. CAGRs derived from installed base expansion rates and replacement cycle analysis for legacy electronic warfare suites. Industry-specific forecast inputs included classified program funding trajectories and GaN semiconductor foundry capacity expansion timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Wassenaar Arrangement technology transfer restrictions or qualified foundry capacity disruptions. Practitioners should monitor NATO interoperability protocol implementation progress and radiation-hardened memory technology qualification milestones for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Radio Frequency Front End Market
RF Components
RF Antenna Market
RF Components
Digital Phase Shifter Market
RF Components
China Small Signal Transistor Market
RF Components
High-Volume RF Front-End Module Test Systems Market
RF Components
Small Signal Mosfets Market
RF Components
RF Semiconductor Market
RF Components
RF Transceiver Chip Market
RF Components
RF Passive Component Market
RF Components
GPS Low Noise Amplifier Market
RF Components
Analog Phase Shifter Market
RF Components
Global RF Transceiver Market
RF Components
RF Front End Module Market
RF Components
RF Over Fiber (Rfof) Market
RF Components
Americas Small Signal Transistor Market
RF Components
Tunable Capacitors Market