
 Z-Wave Products Market | 2026-2036
Z-Wave Products Market Size, Share, and Industry Trends Forecast 2026-2036
Z-Wave Products Market Outlook
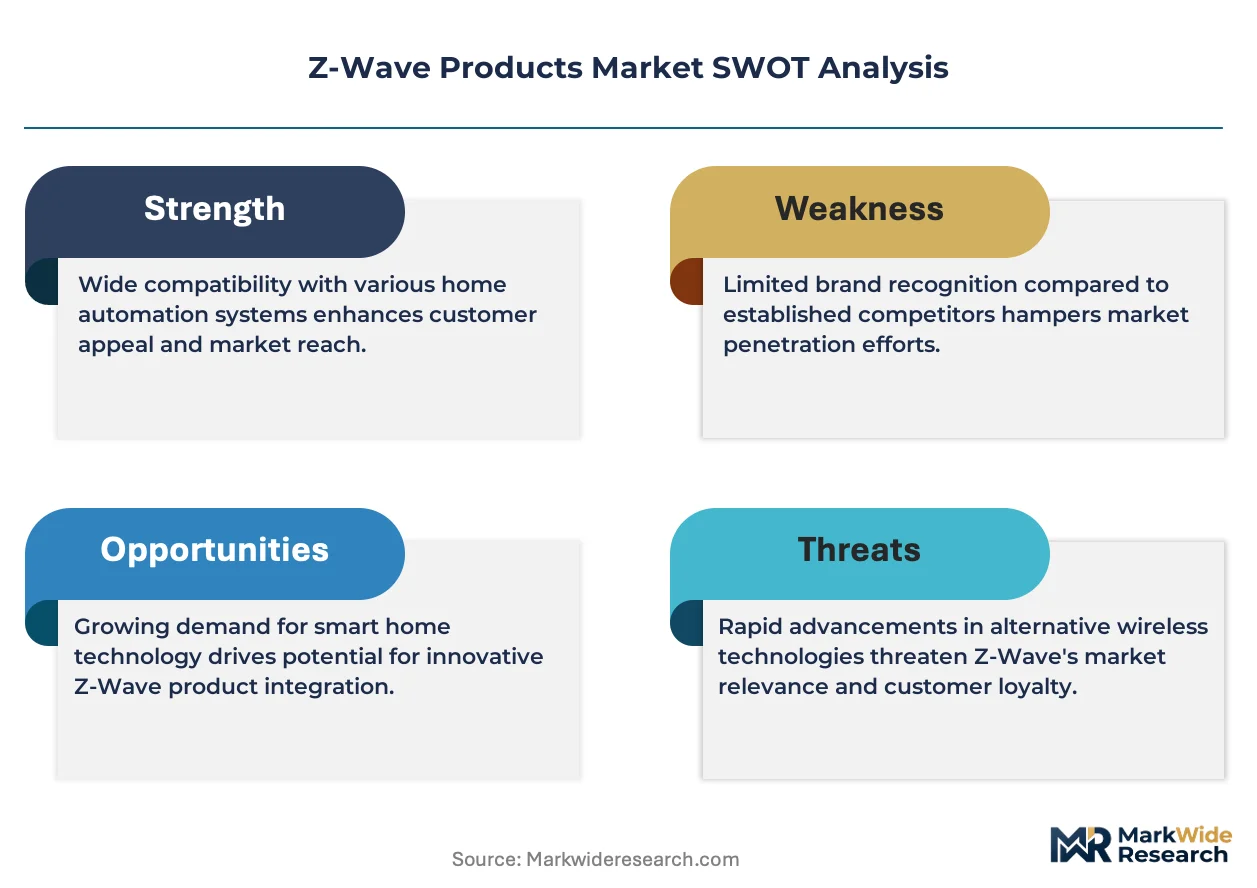
A shift from single-source chipset supply toward multi-source procurement is rebalancing vendor relationships across the Z-Wave value chain. Silicon Labs sustains its position through captive semiconductor fabrication for Z-Wave 800 series controllers. Aeotec differentiates via deep product specialization in sensors and repeaters. Assa Abloy AB anchors commercial access control integration by embedding Z-Wave modules into smart lock portfolios.
Z-Wave products are low-power wireless devices operating in sub-GHz frequency bands, typically 908.42 MHz in North America and 868.42 MHz in Europe, utilizing mesh networking topology to enable reliable device-to-device communication across residential and commercial environments. Smart lighting and security systems command the largest product type positions due to established installer channels and homeowner familiarity. Energy management applications within the application dimension are gaining structural momentum as utility demand-response programs expand rebate eligibility for connected thermostats and load controllers.
The FCC governs unlicensed spectrum allocation and emission limits for Z-Wave devices in the United States, while the EU Radio Equipment Directive mandates harmonized frequency use and interoperability testing for CE-marked products entering European markets. Z-Wave Alliance certification requirements add a voluntary but commercially decisive layer for cross-brand compatibility. Stakeholders must monitor evolving cybersecurity labeling mandates from both regulators and decide whether to front-load encryption standards ahead of compulsory deadlines.
Market Dynamics
Mesh networking protocol upgrades are compressing interoperability timelines across the Z-Wave value chain, forcing chipset vendors and device manufacturers to synchronize firmware roadmaps around the 800-series specification while navigating divergent certification cycles in North America and Europe.
Growth Catalysts
- EU Radio Equipment Directive harmonization:CE marking requirements for sub-GHz devices are streamlining cross-border product launches, reducing duplicate testing costs for manufacturers targeting multiple European member states.
- Utility demand-response program expansion:Rebate eligibility for connected thermostats and load controllers is accelerating energy management application adoption across residential new construction in Texas, Florida, and California.
- Silicon carbide controller integration:Lower power consumption profiles in next-generation Z-Wave modules are extending battery life in wireless sensors, enabling deployment in hard-to-wire locations previously served by wired alternatives.
Market Restraints
- Sub-GHz spectrum congestion:Coexistence with LoRaWAN and proprietary security systems in the 900 MHz band is introducing interference management costs for multi-protocol gateway manufacturers.
- Single-source silicon dependency:Concentrated controller fabrication capacity creates supply vulnerability during foundry allocation cycles, particularly for Z-Wave 700 and 800 series chipsets.
- Wi-Fi 6E substitution pressure:Lower-cost 2.4 GHz and 5 GHz alternatives are capturing price-sensitive smart lighting and basic sensor applications where mesh reliability is less critical.
Strategic Opportunities
- India smart city infrastructure:Bureau of Indian Standards certification pathways for sub-GHz protocols remain underdeveloped, creating first-mover advantage for vendors establishing local testing partnerships ahead of formal mandate rollout.
- Matter protocol convergence:Bridge device development combining Z-Wave mesh reliability with Matter application layer interoperability is opening retrofit opportunities in existing installed bases.
- Professional installer channel digitization:Direct-to-contractor platforms are compressing distributor margins while capturing specification influence in multi-dwelling unit and commercial access control projects.
Industry Challenges
- FCC Part 15 certification backlog:Extended equipment authorization timelines at Telecommunication Certification Bodies are delaying product launches and compressing revenue recognition windows.
- Legacy Z-Wave Plus migration complexity:Backward compatibility requirements are fragmenting firmware development resources and extending quality assurance cycles for multi-generation product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Z-Wave Products Market |
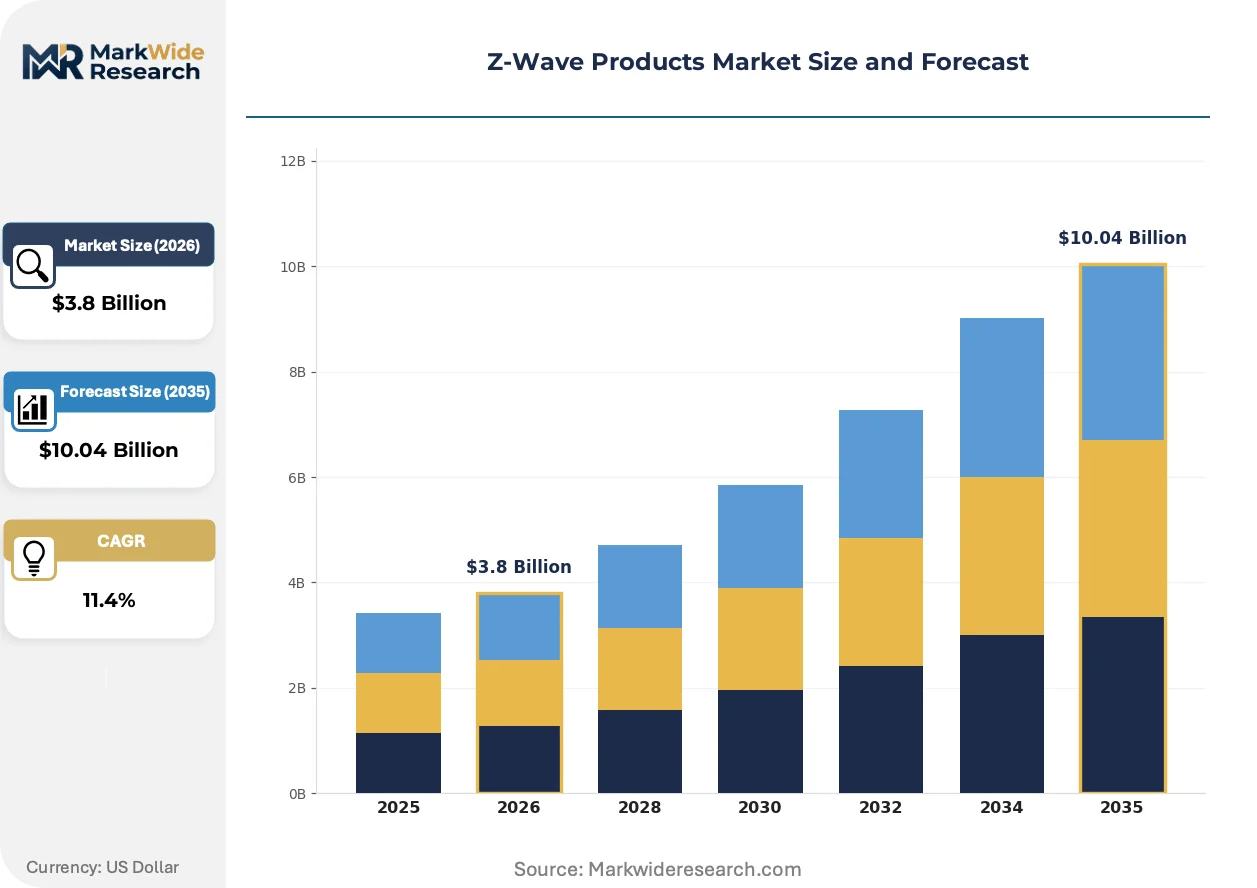
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lighting, Security Systems, Thermostats, Sensors End User: Residential Users, Commercial Facilities, Government Buildings, Hospitality Application: Home Automation, Energy Management, Security Monitoring, Healthcare Technology: Wireless Communication, Cloud-Based Solutions, Mobile Applications, Mesh Networking |
| Companies Covered | Vivint Smart Home Inc., Aeotec, Honeywell International Inc., Zooz, Jasco, Assa Abloy AB, Silicon Labs, Shelly, Allegion plc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Z-Wave Products Market Strategic Shifts
Protocol-layer unification efforts are compressing the competitive window for standalone Z-Wave offerings, forcing ecosystem participants to position mesh networking as a specialized reliability layer rather than a standalone connectivity standard.
Long Range (LR) specification extensions are consolidating signal propagation advantages for outdoor and large-structure applications. Property developers in suburban Texas and Florida markets are specifying Z-Wave LR for gate controllers and perimeter sensors where Wi-Fi coverage gaps persist. This technology is consolidating vendor R&D budgets away from repeater-dense legacy architectures toward optimized single-hop deployments.
CSRD sustainability disclosure mandates are accelerating hardware recyclability requirements for CE-marked devices. European manufacturers must now document sub-GHz radio module end-of-life processing pathways, adding compliance overhead but creating differentiation for vendors with established take-back programs. The directive is reshaping packaging and material selection decisions most acutely in sensor and thermostat product categories.
Builder-direct specification models are displacing traditional electrical distributor channels in North American new construction. National homebuilders in California and Texas are consolidating smart home package decisions at corporate procurement levels, compressing local installer autonomy. This concentration is most visible in master-planned communities where pre-installation rates for lighting and security systems now exceed traditional retrofit penetration timelines.
Z-Wave Products Market Segmentation
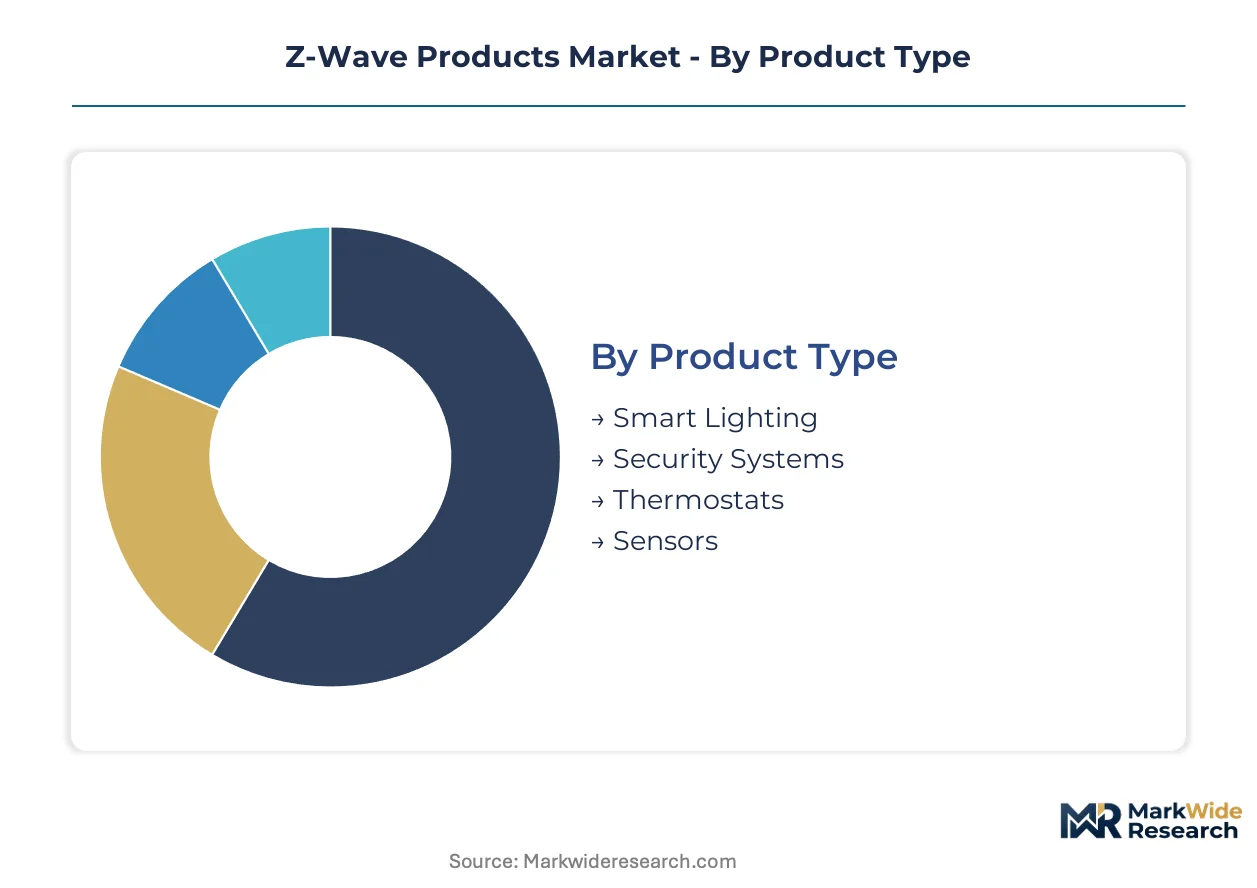
Z-Wave product segmentation reveals distinct procurement patterns across residential and commercial channels. Installer certification requirements and utility rebate eligibility create divergent specification standards that reshape volume distribution across each category.
Product Type:
Standardization dominates lighting and sensor categories where interoperability certification drives purchasing decisions, while security and climate control segments reward deeper customization for integration with legacy building systems.
- Smart Lighting:Bulb, switch, and dimmer modules utilizing 800-series controllers for sub-GHz mesh command propagation. Demand clusters in Texas and Florida new construction where builder-direct procurement mandates Z-Wave Alliance certification for whole-home package uniformity.
- Security Systems:Door and window sensors, motion detectors, and siren modules with encrypted S2 security frameworks. Commercial facilities in California specify these for insurance premium reductions tied to monitored alarm verification.
- Thermostats:Connected climate controllers with utility API integration for demand-response programs.
- Sensors:Multipurpose environmental and occupancy detection devices with extended battery life.
Most installed capacity flows through Smart Lighting. Expansion is steepest in Security Systems.
End User:
Volume concentration tilts toward residential retrofit and new construction, though commercial procurement carries higher per-project value and longer replacement cycles.
- Residential Users:Single-family homeowners and multi-dwelling unit tenants purchasing through installer channels or retail. California and Texas markets show strongest penetration where utility rebates offset hardware costs for energy management deployments.
- Commercial Facilities:Office buildings, warehouses, and retail locations requiring centralized building management integration. FCC Part 15 compliance documentation becomes a procurement gate for multi-site rollouts.
- Government Buildings:Municipal and federal facilities with cybersecurity labeling mandates.
- Hospitality:Hotels and serviced apartments prioritizing guest room automation for operational efficiency.
Residential Users absorb the majority of unit shipments. Commercial Facilities command the highest average selling prices per installation.
Application:
Application segmentation tracks functional deployment rather than device taxonomy, revealing where Z-Wave's mesh reliability outperforms alternative protocols.
- Home Automation:Integrated lighting, climate, and entertainment control through unified hubs. Builder specifications in Florida master-planned communities standardize these systems during rough-in construction phases.
- Energy Management:Load controllers and connected thermostats participating in utility demand-response programs. Texas grid operators expand rebate eligibility fastest, concentrating manufacturer R&D on Texas-specific utility API integrations.
- Security Monitoring:Intrusion detection and access logging with professional central station connectivity.
- Healthcare:Remote patient monitoring and assisted living safety systems with fall detection.
Home Automation represents the largest installed base. Energy Management is climbing the fastest as utility programs mature.
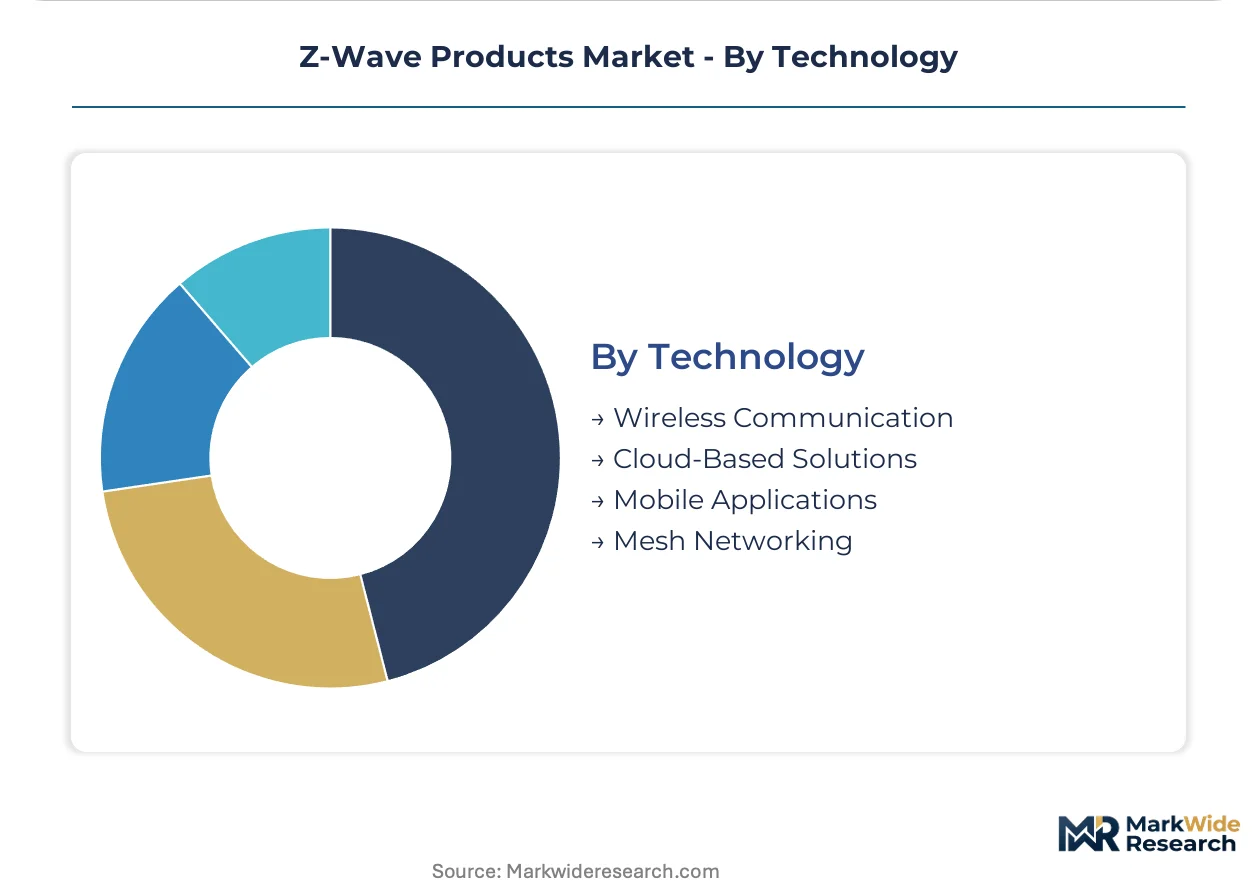
Technology:
Technology segmentation distinguishes connectivity architecture from user interface layers, exposing where silicon and software investments concentrate.
- Wireless Communication:Sub-GHz radio modules operating at 908.42 MHz in the United States and 868.42 MHz in Europe. Silicon Labs maintains captive fabrication for 800-series controllers, creating supply concentration risk during foundry allocation cycles.
- Cloud-Based Solutions:Remote command processing and firmware update infrastructure hosted on third-party servers. EU GDPR compliance requirements add data residency overhead for European deployments.
- Mobile Applications:Smartphone and tablet interfaces for device commissioning and status monitoring.
- Mesh Networking:Self-healing multi-hop topology enabling extended range without infrastructure dependence.
Wireless Communication anchors hardware revenue. Cloud-Based Solutions are gaining share fastest as subscription models displace one-time license sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting Z-Wave manufacturing investment toward jurisdictions with streamlined sub-GHz certification pathways, as the cost differential between FCC Part 15 compliance in the United States and CE marking in Europe reshapes production location decisions.
United States
New construction markets in Texas and Florida are driving smart home pre-installation demand, with master-planned communities standardizing Z-Wave lighting and security packages during rough-in phases. FCC Part 15 rules govern unlicensed spectrum allocation and emission limits, tightening certification timelines at Telecommunication Certification Bodies. California's utility rebate programs for connected thermostats are concentrating energy management deployments in the state's residential retrofit channel.
Germany
Industrial building automation and commercial access control applications are absorbing Z-Wave modules for insurance-compliant security installations. The EU Radio Equipment Directive mandates harmonized frequency use and interoperability testing for CE-marked products, with CSRD sustainability disclosure requirements now forcing hardware recyclability documentation. Manufacturing clusters in Bavaria and Baden-Württemberg are developing take-back programs for sub-GHz radio module end-of-life processing.
United Kingdom
Professional installer networks in London and the Southeast are specifying Z-Wave LR for large-structure deployments where Wi-Fi coverage gaps persist. Post-Brexit regulatory divergence from EU CE marking is creating dual certification overhead for manufacturers, though UKCA alignment remains partially harmonized with Radio Equipment Directive standards. Insurance premium reductions for monitored alarm verification are accelerating commercial security sensor adoption in urban office stock.
India
Bureau of Indian Standards certification pathways for sub-GHz protocols remain underdeveloped, creating first-mover positioning for vendors establishing local testing partnerships ahead of formal mandate rollout. Smart city infrastructure projects in Maharashtra and Karnataka are evaluating mesh networking for municipal lighting and perimeter control applications. The country's national telecom regulator is drafting spectrum allocation frameworks that will determine Z-Wave frequency availability.
Japan
Assisted living and healthcare monitoring applications are deploying Z-Wave sensors for fall detection and remote patient safety systems. METI standards for radio equipment interoperability are adding certification layers beyond baseline technical compliance. Manufacturing and R&D activity concentrates in the Kanto region around Tokyo, where semiconductor fabricators are evaluating sub-GHz controller production for regional supply security.
Z-Wave Products Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue Matter protocol bridge development and professional installer channel digitization. The vendor base stratifies across captive semiconductor fabricators, deep-product specialists, and commercial access control integrators. Three archetypes dominate: silicon suppliers controlling controller supply, sensor manufacturers extending battery-life performance, and lock manufacturers embedding modules for insurance-compliant security. Competitive moves concentrate on multi-source procurement rebalancing and firmware roadmap synchronization around 800-series specifications.
Within the semiconductor supply tier, Silicon Labs exemplifies captive fabrication strategy for Z-Wave 800-series controllers. Aeotec occupies a specialist position in sensor and repeater product categories. Assa Abloy AB anchors commercial access control integration through smart lock portfolio embedding. These three represent distinct competitive vectors—supply security, product depth, and vertical application integration—that structure rivalry across the value chain.
| Leading Market Players |
|---|
| Vivint Smart Home Inc. |
| Aeotec |
| Honeywell International Inc. |
| Zooz |
| Jasco |
| Assa Abloy AB |
| Silicon Labs |
| Shelly |
| Allegion plc. |
| Others |
Value Chain & Pricing Dynamics
Silicon wafer pricing volatility cascades through Z-Wave controller fabrication, compressing margins for 800-series chipset vendors while amplifying cost differentials between premium-certified and economy-tier device modules. FCC Part 15 certification fees and EU Radio Equipment Directive testing costs accumulate disproportionately at lower volume tiers, forcing smaller manufacturers toward private-label arrangements with silicon-integrated module suppliers.
Pricing Analysis
Input-cost pass-through from captive semiconductor fabrication concentrates pricing power with Silicon Labs, though Aeotec and Jasco offset controller premiums through volume scale in sensor and lighting categories. Three-tier pricing structure across premium-certified, standard-interoperable, and economy-private-label levels segments buyer archetypes, with builder-direct procurement in Texas and Florida squeezing standard-tier margins most acutely. Pricing pressure stems from Wi-Fi 6E substitution in basic lighting applications, where mesh reliability commands diminishing premiums. Residential retrofit buyers exhibit highest price sensitivity; commercial access control integrators absorb certification premiums for insurance-compliant security deployments.
Supply Chain Analysis
Single-source vulnerability sits with Silicon Labs' captive Austin fabrication for Z-Wave 800-series controllers, exposing the value chain to foundry allocation cycles during semiconductor demand surges. Geographic supply concentration centers on United States controller production, Chinese PCB assembly, and Malaysian sensor packaging. Raw material dependencies encompass silicon carbide substrates, sub-GHz RF components, and lithium-ion battery cells for wireless endpoints. Tariff exposure on Chinese-assembled modules creates margin compression for North American device vendors. Distribution runs through professional installer channels in new construction markets, with builder-direct procurement displacing traditional electrical distributor networks in California and Texas master-planned communities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Z-Wave Products Market represents a late-cycle quality story where builder-direct procurement and Matter protocol convergence reward premium-certified, multi-protocol-ready device portfolios. Demand is shifting toward 800-series Long Range specifications in suburban gate control and perimeter sensor applications.
For Market Incumbents: Anticipate Wi-Fi 6E encroachment in basic lighting by deepening 800-series firmware differentiation and securing exclusive builder-direct procurement contracts in Florida and Texas master-planned communities. Prioritize backward compatibility investment to reduce multi-generation quality assurance overhead. Certification pre-positioning ahead of compulsory EU cybersecurity labeling mandates protects margin structure against compliance-cost inflation. For New Entrants and Emerging Players: Matter protocol bridge development offers technology-first wedge positioning for retrofit opportunities in existing Z-Wave installed bases, particularly where consumers resist full ecosystem replacement. White-space targets include India Bureau of Indian Standards pre-certification partnerships ahead of formal sub-GHz mandate rollout, and professional installer channel digitization platforms capturing specification influence in multi-dwelling unit projects. Go-to-market execution should anchor on direct-to-contractor sales compression of distributor margins. For Investors and Strategic Acquirers: Asymmetric upside sits with sensor specialists extending battery-life performance through silicon carbide controller integration, and commercial access control integrators embedding Z-Wave modules for insurance-premium-reduction eligibility. Long-term viability favors vendors with demonstrated 800-series firmware synchronization and established take-back programs for CSRD-compliant hardware recyclability. The signal to watch is FCC Telecommunication Certification Body backlog resolution velocity, which gates revenue recognition windows for new product launches.| Strategic Initiative | Industry Significance |
|---|---|
| 800-Series Firmware Synchronization | Aligns chipset vendors and device manufacturers around unified certification timelines for North America and Europe. |
| Matter Protocol Bridge Development | Captures retrofit demand in existing installed bases without requiring full ecosystem replacement by consumers. |
| Builder-Direct Procurement Consolidation | Secures specification influence in Texas and Florida new construction where pre-installation rates exceed retrofit penetration. |
| CSRD-Compliant Take-Back Programs | Differentiates European vendors through documented sub-GHz radio module end-of-life processing pathways. |
| India BIS Pre-Certification Partnerships | Establishes first-mover positioning ahead of formal sub-GHz mandate rollout in Maharashtra and Karnataka smart city projects. |
Study Parameters
Bottom-up residential and commercial end-use modeling reconciled against top-down semiconductor supply-side tracking forms the analytical core of this study. Primary interviews with smart home platform engineers, professional installer network managers, utility demand-response program administrators, and FCC Telecommunication Certification Body officials combined with secondary validation from FCC equipment authorization databases, EU Radio Equipment Directive harmonized standards publications, Z-Wave Alliance certification registries, and builder-direct procurement disclosures from publicly traded homebuilders. Triangulation across these sources anchors volume estimates in observed channel flow rather than manufacturer shipment claims.
Historical trendline analysis of Z-Wave Alliance certification volumes, utility rebate program participation rates, and new construction smart home pre-installation penetration informed the projection framework. Segmentation dimensions modeled encompass product type, end-user category, application function, and technology architecture, with regional regulatory cluster differentiation for FCC Part 15, EU Radio Equipment Directive, and emerging India Bureau of Indian Standards pathways. CAGRs derive from fitted trend extrapolation adjusted for protocol migration dynamics and substitute technology substitution pressure. Forecast inputs include silicon foundry capacity allocation cycles, builder procurement consolidation velocity, and Matter protocol adoption curves in existing installed bases.
The model holds under stable regulatory harmonization timelines and continued utility demand-response program expansion; deviation in FCC certification backlog duration, sub-GHz spectrum reallocation decisions, or Wi-Fi 6E cost compression would shift volume trajectories. Forecasts reflect assumptions about 800-series migration velocity and Matter bridge deployment pace that material evidence may revise. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Harness-Level EMI and Shielding Component Systems Market
RF Components
433MHz Active RFID Reader Market
RF Components
RF Switches Market
RF Components
Global RF Transceiver Market
RF Components
RF Microwave MLCC Market
RF Components
RF Power Dividers Market
RF Components
Multilayer Coupled Inductor Market
RF Components
Global Inductors Market
RF Components
Multi-Mode Receiver Market
RF Components
RF Gan Market
RF Components
Japan Small Signal Transistor Market
RF Components
5G Driver Amplifier Market
RF Components
Dielectric Resonator Market
RF Components
Microwave Devices Market
RF Components
RF Tester Market
RF Components
RF Acoustic Wave Filters Market