
 Multilayer Coupled Inductor Market | 2026-2036
Multilayer Coupled Inductor Market Size, Share, and Industry Trends Forecast 2026-2036
Multilayer Coupled Inductor Market Analytics
Multi-source procurement from Asian ceramic substrate suppliers is broadening as Western automotive Tier 1s derisk magnetic component supply chains. TDK Corporation leverages captive ferrite powder production to anchor its position in high-frequency power inductors. Murata Manufacturing Co., Ltd. sustains R&D intensity across thin-film multilayer processes for 5G base station modules. Vishay Intertechnology, Inc. competes through broad catalog breadth across industrial temperature grades.
A multilayer coupled inductor consists of two or more magnetically coupled coils fabricated through sequential lamination of ferrite or ceramic layers with printed silver-palladium windings, typically achieving inductance values from 0.1 µH to 100 µH with coupling coefficients exceeding 0.95 for tight magnetic integration. These components serve primarily to manage electromagnetic interference, enable compact DC-DC converter designs, and maintain signal integrity in densely packed printed circuit boards where discrete magnetics would exceed spatial constraints. Power inductors within the product type category dominate current revenue owing to their indispensability in voltage regulator modules for servers and GPUs, while integrated inductors are gaining share fastest as system-in-package architectures displace discrete magnetics in smartphone and wearable designs. The technology dimension shows multilayer fabrication overtaking wire-wound methods in units shipped below 10 A current ratings, though ceramic multilayer variants still trail film-based alternatives in high-Q RF signal paths.
The US FCC emissions compliance framework and EPA hazardous substance restrictions shape material selection and shielding requirements for inductors deployed in telecommunications infrastructure and automotive electronics. Japan's METI energy efficiency standards for industrial equipment and China's GB/T electromagnetic compatibility mandates collectively push manufacturers toward low-loss ferrite formulations and improved thermal characterization. South Korea's MFDS does not directly regulate passive magnetics, but the country's national standards body aligns component reliability testing with IEC specifications for automotive qualification. Stakeholders must monitor how impending EU RoHS amendments and REACH substance restrictions will affect nickel-zinc ferrite chemistries and alternative core material qualification timelines.
Market Dynamics
Automotive electrification is compressing development cycles for magnetic components as OEMs demand higher power density in electric drivetrain modules and ADAS power management systems. This structural force is reshaping supplier qualification timelines and material specifications across the component ecosystem.
Growth Catalysts
- China's dual carbon goals:GB standards for electronic component efficiency are tightening energy-loss thresholds and accelerating replacement cycles in industrial equipment.
- Electric vehicle power electronics:Tight magnetic integration in DC-DC converters and onboard chargers is expanding unit volumes for multilayer coupled architectures.
- 5G infrastructure deployment:Base station manufacturers are specifying thin-film multilayer inductors to achieve compact filtering in densely packed RF front-end modules.
Market Restraints
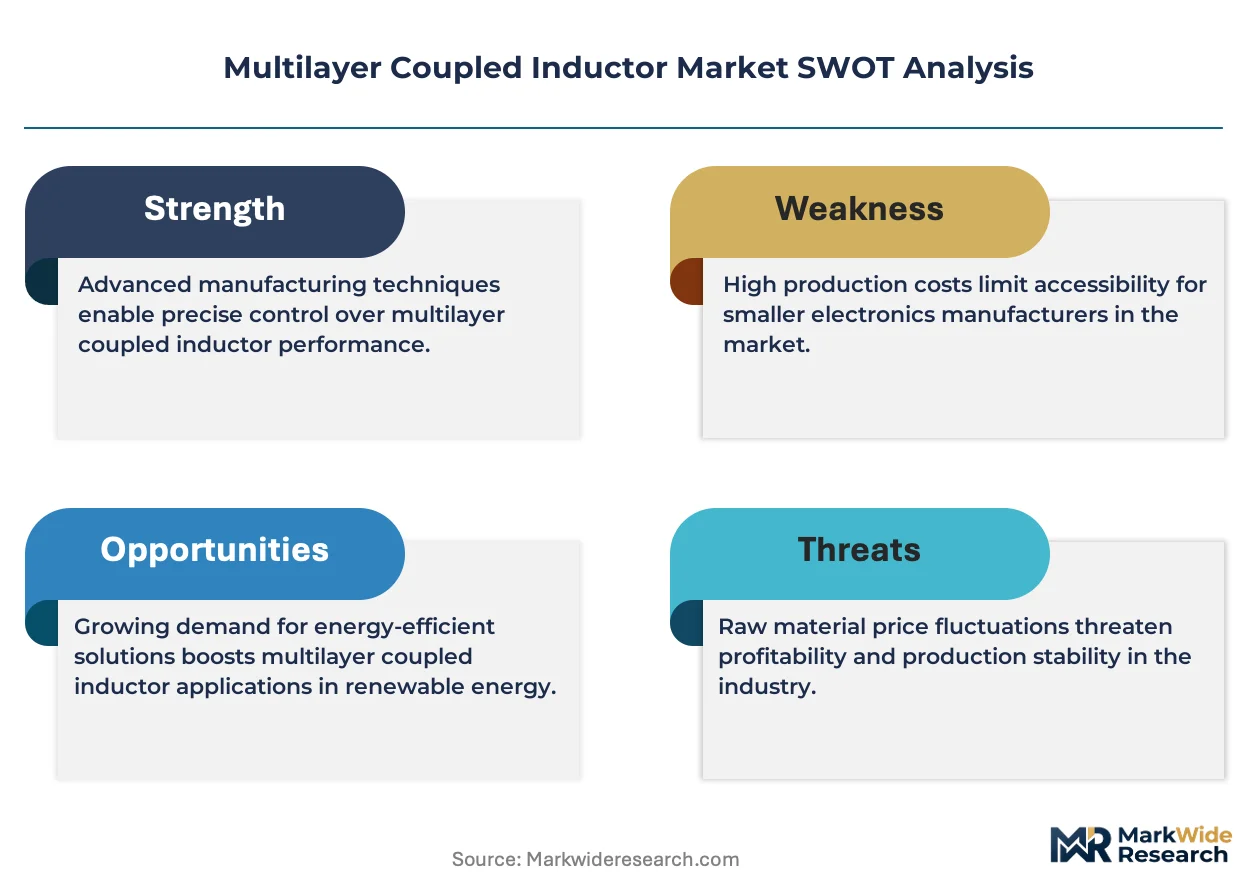
- Silver-palladium conductor costs:Precious metal price volatility in printed windings compresses gross margins for high-frequency power inductor variants.
- Ferrite powder supply concentration:Captive production capabilities cluster among Japanese and Chinese ceramic substrate suppliers, creating single-source exposure for Western Tier 1s.
- Wire-wound legacy dominance:Current ratings above 10 A still favor traditional winding methods, limiting multilayer penetration in heavy industrial motor drives.
Strategic Opportunities
- System-in-package architectures:Smartphone and wearable OEMs are displacing discrete magnetics with integrated inductor designs that reduce PCB footprint.
- South Korean automotive electronics:MFDS-aligned IEC qualification pathways for automotive-grade components create a regulatory on-ramp for premium inductor suppliers.
- EU RoHS amendment preparation:Nickel-zinc ferrite chemistry qualification ahead of REACH substance restrictions offers first-mover positioning for alternative core materials.
Industry Challenges
- Thermal characterization expertise:Characterizing low-loss ferrite formulations under automotive temperature grades requires specialized simulation talent that remains scarce outside East Asian R&D clusters.
- Multi-source qualification timelines:Western Tier 1s face 18-24 month validation cycles when derisking supply chains away from concentrated Japanese ferrite suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multilayer Coupled Inductor Market |
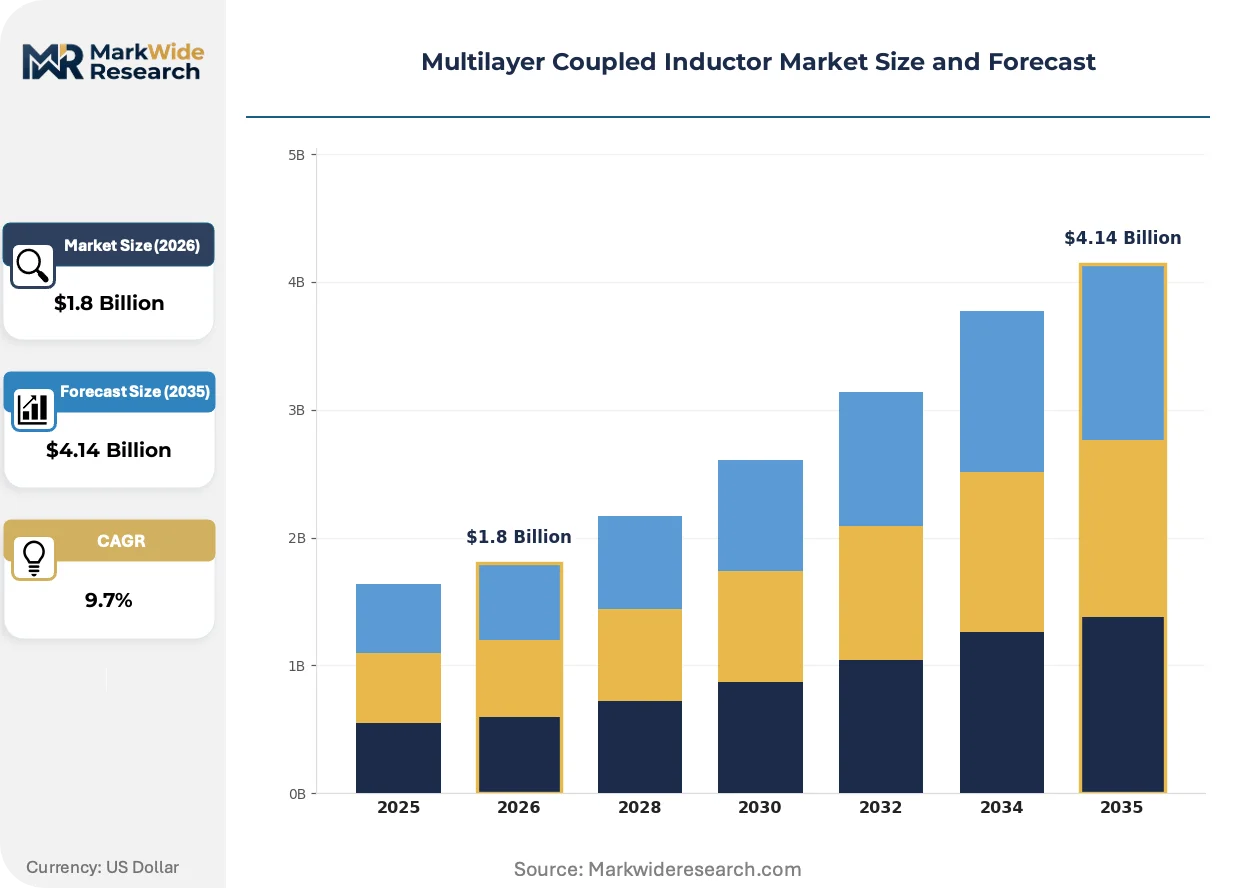
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Inductor, Signal Inductor, Common Mode Choke, Integrated Inductor Application: Telecommunications, Consumer Electronics, Automotive Electronics, Industrial Automation End User: OEMs, Electronics Manufacturers, Automotive Suppliers, Industrial Equipment Providers Technology: Wire-Wound, Ceramic, Film, Multilayer |
| Companies Covered | TDK Corporation, Murata Manufacturing Co., Ltd., Taiyo Yuden Co., Ltd., Vishay Intertechnology, Inc., Pulse Electronics Corporation, Wurth Elektronik GmbH & Co. KG, Coilcraft Inc., Delta Electronics Inc., Sumida Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multilayer Coupled Inductor Market Evolving Landscape
Thin-film lamination processes are compressing form factors while regulatory pressure on hazardous substances is forcing material chemistry transitions. These parallel developments are redefining competitive differentiation in magnetic component supply.
Automated laser-trimmed ferrite deposition is automating precision control over layer thickness in multilayer fabrication. Automotive DC-DC converter suppliers in Germany and Japan are adopting this process at pilot scale. The technology is automating yield improvement in sub-1 µH inductance values where manual trimming previously dominated.
REACH substance restrictions on nickel compounds are compelling core material reformulations across European supply chains. ECHA's candidate list expansion is accelerating qualification of manganese-zinc alternatives with comparable permeability. High-Q RF signal path applications in telecommunications infrastructure face the steepest reformulation timelines.
Consolidated vendor-managed inventory programs are displacing spot-market purchasing for high-volume automotive programs. Tier 1 power module suppliers in Michigan and Bavaria are locking annual volumes through framework agreements with Japanese ceramic substrate partners. This concentration is most visible in electric drivetrain programs where traceability requirements exceed discrete component norms.
Multilayer Coupled Inductor Market Segmentation
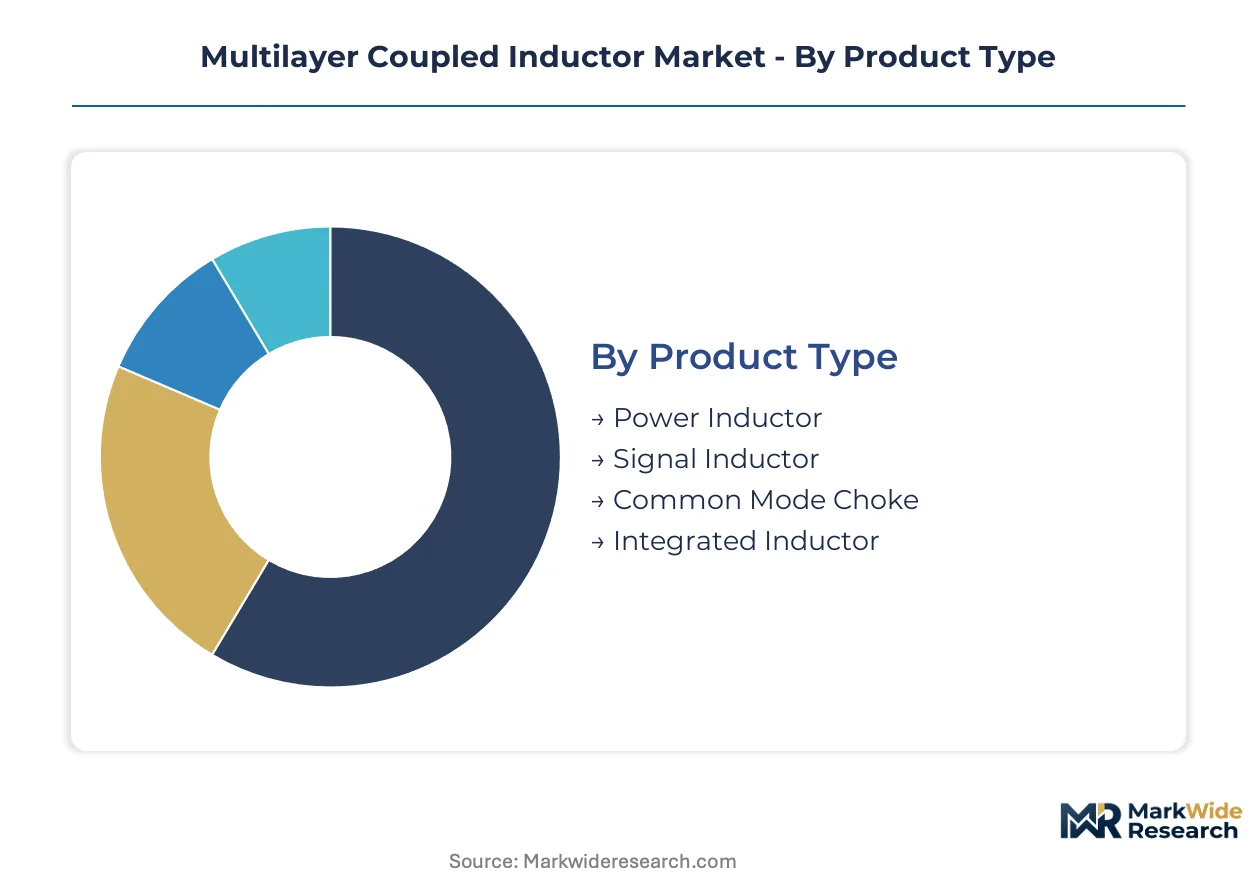
Multilayer coupled inductor procurement decisions hinge on current-handling requirements, thermal constraints, and magnetic integration density. Component selection varies sharply across DC-DC converter architectures, RF front-end modules, and EMI suppression circuits where spatial and electrical specifications diverge.
Product Type:
Buyers prioritize current saturation characteristics and core loss profiles when specifying inductor architectures for power conversion versus signal conditioning applications.
- Power Inductor:Ferrite or iron-powder cores wound with silver-palladium or copper conductors handle load currents from 1 A to 50 A in voltage regulator modules. Server and GPU power stages in Taiwan and Korea drive procurement volumes for sub-10 µH values with tight DCR specifications.
- Integrated Inductor:Thin-film multilayer fabrication embeds magnetics within system-in-package substrates, eliminating discrete component placement. Smartphone OEMs in Shenzhen and Seoul specify these for camera module power delivery where PCB area measures under 4 mm².
- Signal Inductor:High-Q ceramic formulations serve RF impedance matching in 5G base station transceivers.
- Common Mode Choke:Bifilar-wound or multilayer balanced windings suppress conducted EMI in USB-C and HDMI interface cables.
Volume sits with Power Inductor; growth tilts toward Integrated Inductor.
Application:
End-equipment thermal cycling requirements and electromagnetic compliance standards dictate material grade and qualification pathway selection.
- Automotive Electronics:AEC-Q200 qualified components withstand −40°C to 150°C operation in electric drivetrain DC-DC converters and ADAS camera power rails. German and Japanese Tier 1s mandate PPAP documentation and traceable ferrite powder lots for onboard charger modules.
- Telecommunications:Base station OEMs specify tight inductance tolerance (±2%) and high self-resonant frequency for massive MIMO beamforming circuits. Huawei, Ericsson, and Nokia suppliers in Finland and China prioritize ceramic multilayer formats for 3.5 GHz and 28 GHz sub-6 and mmWave deployments.
- Consumer Electronics:Wearable and TWS earbud designs drive demand for 0603 and 0402 case sizes with sub-1 µH values.
- Industrial Automation:Motor drive inverters and PLC power supplies favor wire-wound construction for 10 A+ current handling.
Revenue concentrates in Automotive Electronics; steepest expansion trajectory appears in Telecommunications.
End User:
Procurement scale and supplier qualification intensity separate high-volume electronics manufacturers from specialized industrial equipment providers.
- OEMs:Apple, Samsung, and Dell negotiate direct allocation agreements with Murata and TDK for multilayer inductor die banks, securing capacity 12-18 months ahead of product ramps.
- Electronics Manufacturers:Foxconn, Jabil, and Flex operate vendor-managed inventory programs that buffer OEMs against lead time volatility.
- Automotive Suppliers:Bosch, Denso, and Continental enforce IATF 16949 traceability and zero-defect PPAP thresholds.
- Industrial Equipment Providers:Siemens, ABB, and Rockwell Automation specify extended temperature grades with 20-year operational life guarantees.
Unit volume flows through Electronics Manufacturers; margin capture favors direct OEM relationships.
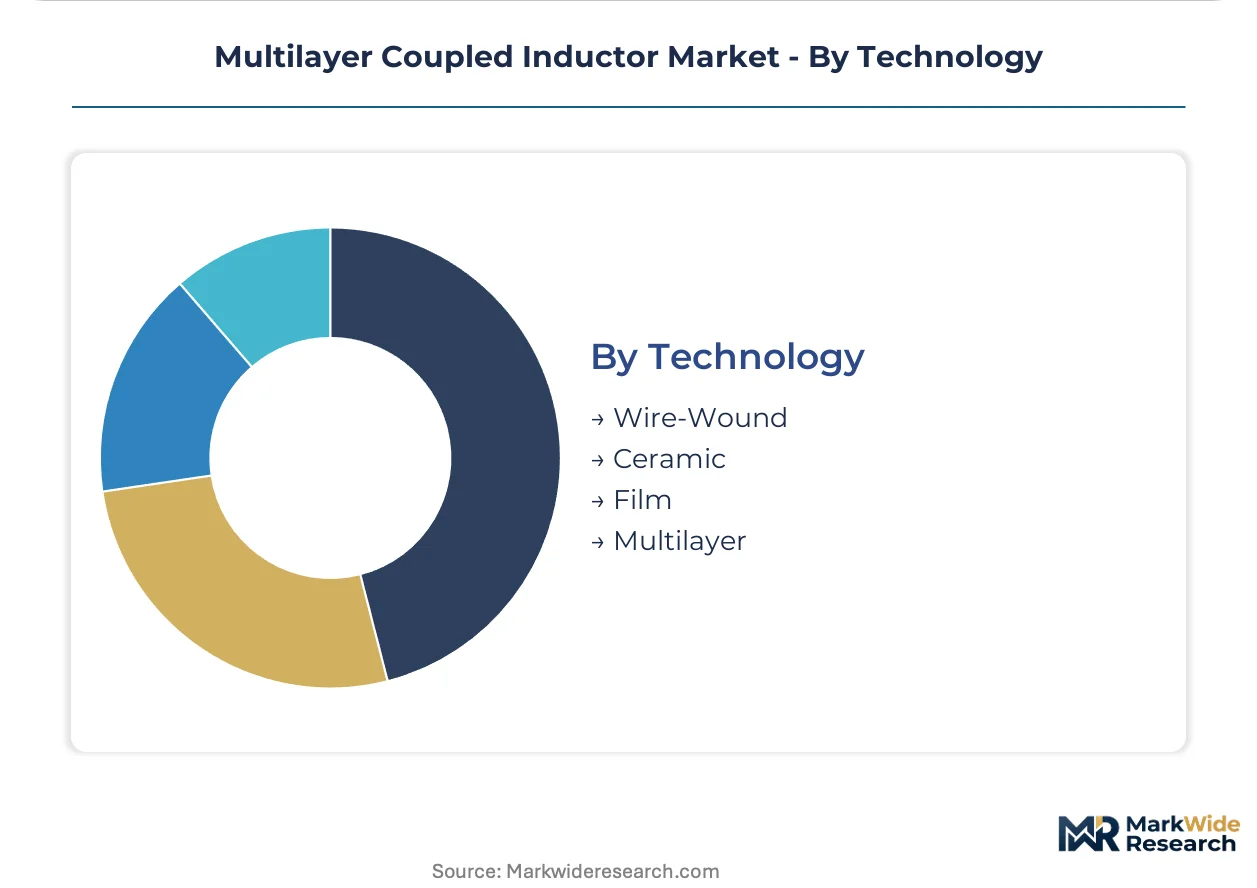
Technology:
Manufacturing process selection trades off current capacity, Q-factor, and unit cost against application-specific electrical constraints.
- Multilayer:Sequential lamination of ferrite tapes with screen-printed windings achieves sub-mm³ form factors and self-shielding geometries. This dominates sub-10 A applications in smartphones, wearables, and IoT sensors where automated SMT placement demands tape-and-reel packaging.
- Wire-Wound:Toroidal or drum-core constructions with enamelled copper wire sustain high saturation currents and low core losses. Industrial motor drives and automotive DC-DC stages above 10 A retain this method despite larger footprints.
- Ceramic:Low-temperature co-fired ferrite (LTCC) processes enable embedded passives in high-density substrates.
- Film:Sputtered or plated magnetic films on silicon or glass carriers serve RF applications requiring Q-factors above 50.
Shipment volume favors Multilayer; Wire-Wound retains revenue concentration in heavy-current segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian manufacturing clusters in Japan, South Korea, and coastal China concentrate multilayer coupled inductor fabrication. Automotive electronics OEMs in Germany and the United States are accelerating qualification of alternative suppliers to reduce single-source exposure.
China
Electric vehicle power electronics and 5G base station deployments drive procurement volumes for multilayer coupled inductors. GB standards for electronic component efficiency under the dual carbon goals tighten energy-loss thresholds and accelerate replacement cycles. Manufacturing concentrates in the Yangtze River Delta and Pearl River Delta, where ceramic substrate suppliers serve domestic automotive Tier 1s.
Japan
METI energy efficiency standards for industrial equipment push manufacturers toward low-loss ferrite formulations. Automotive DC-DC converter suppliers in Nagoya and Tokyo enforce PPAP documentation and traceable ferrite powder lots for electric drivetrain modules. TDK Corporation anchors captive ferrite production in this cluster.
South Korea
Smartphone OEMs in Seoul specify integrated inductor designs for camera module power delivery where PCB area measures under 4 mm². MFDS-aligned IEC qualification pathways create regulatory on-ramps for automotive-grade components. Manufacturing concentrates in the Seoul Capital Area and Busan-Ulsan corridor.
Germany
Tier 1 power module suppliers in Bavaria and Baden-Württemberg lock annual volumes through framework agreements with Japanese ceramic substrate partners. ECHA REACH substance restrictions on nickel compounds compel core material reformulations across European supply chains. Automated laser-trimmed ferrite deposition is scaling at pilot facilities near Munich.
United States
FCC emissions compliance and EPA hazardous substance restrictions shape material selection for telecommunications infrastructure. Server and GPU power stages drive procurement for sub-10 µH values with tight DCR specifications. Electronics manufacturers in Michigan and Texas operate vendor-managed inventory programs that buffer OEMs against lead time volatility.
Multilayer Coupled Inductor Market Competitive Landscape
Capacity expansion dominates the current landscape as suppliers add multilayer fabrication lines to capture automotive electrification demand. The vendor base clusters around three tiers: integrated Japanese conglomerates with captive material production, specialized European component houses with automotive qualification depth, and Asian contract manufacturers scaling thin-film processes. Strategic archetypes include ferrite powder self-suppliers, thin-film process specialists, and broad-catalog industrial distributors. M&A activity and strategic partnerships concentrate on securing ceramic substrate supply and expanding RF signal path capabilities.
Among Japanese fabricators, TDK Corporation and Murata Manufacturing Co., Ltd. exemplify the integrated archetype with upstream control over ferrite powder production. Vishay Intertechnology, Inc. represents the broad-catalog positioning across industrial temperature grades. These three anchors illustrate how competitive differentiation flows from material science depth, process specialization, or portfolio breadth rather than scale alone.
| Leading Market Players |
|---|
| TDK Corporation |
| Murata Manufacturing Co., Ltd. |
| Taiyo Yuden Co., Ltd. |
| Vishay Intertechnology, Inc. |
| Pulse Electronics Corporation |
| Wurth Elektronik GmbH & Co. KG |
| Coilcraft Inc. |
| Delta Electronics Inc. |
| Sumida Corporation |
| Others |
Value Network & Pricing Analysis
AEC-Q200 certification tiers bifurcate procurement economics across automotive-grade and commercial-grade segments, concentrating margin capture with Japanese ferrite powder suppliers while compressing returns for undifferentiated multilayer fabricators serving consumer electronics.
Pricing Analysis
High-volume power inductor contracts for server voltage regulator modules run on per-unit transactional pricing with annual volume rebates, while automotive DC-DC converter programs lock long-term offtake agreements with indexed precious metal adjustments. Price differentiation hinges on AEC-Q200 qualification tier and captive ferrite powder production, with automotive buyers least sensitive to unit cost given traceability mandates. Cost compression in consumer-grade integrated inductors intensifies as Shenzhen smartphone OEMs consolidate die bank allocations toward Murata and TDK.
Supply Chain Analysis
Specialized thermal characterization engineers cluster in Nagoya, Seoul, and Suzhou, constraining Western Tier 1s from replicating automotive-grade validation capabilities outside East Asian R&D hubs. Ferrite powder supply concentrates in Japan and China, with silver-palladium conductor sourcing tethered to South Korean precious metal refiners. Single-source vulnerability runs through Japanese ceramic substrate partners qualified under IATF 16949. Distribution runs through vendor-managed inventory programs operated by Foxconn, Jabil, and Flex for high-volume electronics manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multilayer fabrication processes are displacing wire-wound construction below 10 A current ratings, creating asymmetric exposure for legacy magnetic component suppliers dependent on drum-core manufacturing.
For Market Incumbents: Acquire thin-film process specialists with existing 5G base station qualifications to preempt RF signal path consolidation. TDK Corporation and Murata Manufacturing should deepen upstream control over low-loss ferrite formulations before REACH substance restrictions accelerate manganese-zinc chemistry transitions. Capacity addition in South Korea's Seoul Capital Area captures MFDS-aligned automotive qualification pathways. For New Entrants and Emerging Players: Mid-tier industrial automation OEMs in Germany and the United States represent underserved buyers seeking AEC-Q200-adjacent reliability without full automotive PPAP overhead. European REACH compliance services for nickel-zinc ferrite reformulation offer a services-led entry point before alternative core material qualification timelines compress. Partner with ECHA-registered testing laboratories to accelerate chemistry validation. For Investors and Strategic Acquirers: Re-rating potential sits with European component houses possessing automotive qualification depth given impending EU RoHS amendments and stranded wire-wound asset risk. Long-term viability over the next decade favors suppliers with backward integration into ferrite powder production and thin-film multilayer capabilities. Watch ECHA candidate list expansion velocity as inflection indicator for core material substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Thin-Film Process Scale-Up | Murata's lamination expertise enables sub-mm³ form factors for smartphone camera modules. |
| Automotive Qualification Pathway Investment | MFDS-IEC alignment in South Korea opens premium inductor supply to German Tier 1s. |
| Ferrite Powder Backward Integration | TDK's captive production insulates margins from silver-palladium conductor volatility. |
| REACH-Compliant Chemistry Qualification | Manganese-zinc alternatives ahead of ECHA restrictions secure European automotive programs. |
| Vendor-Managed Inventory Expansion | Framework agreements with Japanese substrate partners lock capacity for electric drivetrain ramps. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with magnetic component procurement managers at automotive Tier 1s, ferrite powder plant engineers in Japan, RF front-end module designers at 5G base station OEMs, and thermal characterization specialists at multilayer fabrication facilities. SEC 10-K disclosures, METI energy efficiency standard documentation, ECHA REACH candidate list updates, and GB/T electromagnetic compatibility filings provided demand-side validation. Bottom-up unit shipment estimates triangulated against top-down value projections across the analysis window.
Product type, application, and technology dimensions were modeled at the SKU level for power inductor, integrated inductor, signal inductor, and common mode choke categories. Current saturation characteristics, core loss profiles, and coupling coefficients informed unit economics. CAGRs derived from regression analysis of historical procurement volumes correlated with electric vehicle production forecasts and 5G infrastructure deployment schedules. Silver-palladium price indices and ferrite powder capacity utilization rates fed input cost sensitivity scenarios.
Revisions become necessary when ECHA substance restriction timelines accelerate, Chinese GB standards tighten energy-loss thresholds beyond current low-loss ferrite capabilities, or automotive OEMs compress supplier qualification cycles below 18 months. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
RF Antenna Market
RF Components
UHF RFID Inlays Market
RF Components
Stand-Alone Radio Receivers Market
RF Components
Radio Frequency (RF) Signal Generators Market
RF Components
Digital Radio Frequency Market
RF Components
Global RF and Microwave Power Transistors Market
RF Components
Tunable Capacitors Market
RF Components
LTCC Power Dividers Market
RF Components
Radiofrequency Identification (RFID) Market
RF Components
Global RF Power Semiconductor Market
RF Components
Digital Radio Frequency Memory Market
RF Components
RF Semiconductor Market
RF Components
Gaas RF Switch Market
RF Components
Flat Panel Antenna Market
RF Components
RF Power Dividers Market
RF Components
Ultra-Wideband (UWB) Market