
 LTCC Power Dividers Market | 2026-2036
LTCC Power Dividers Market Size, Share, and Industry Trends Forecast 2026-2036
LTCC Power Dividers Market Insights
Distributor networks for ceramic RF components is fragmenting as direct OEM engagements replace traditional electronics wholesalers. TDK leverages its vertically integrated ferrite and ceramic operations to control substrate quality from powder to fired component. Mini-Circuits competes through catalog breadth and rapid turnaround on custom splitter designs. Murata Manufacturing Co., Ltd. anchors high-volume production for consumer-facing wireless infrastructure with automated LTCC lines.
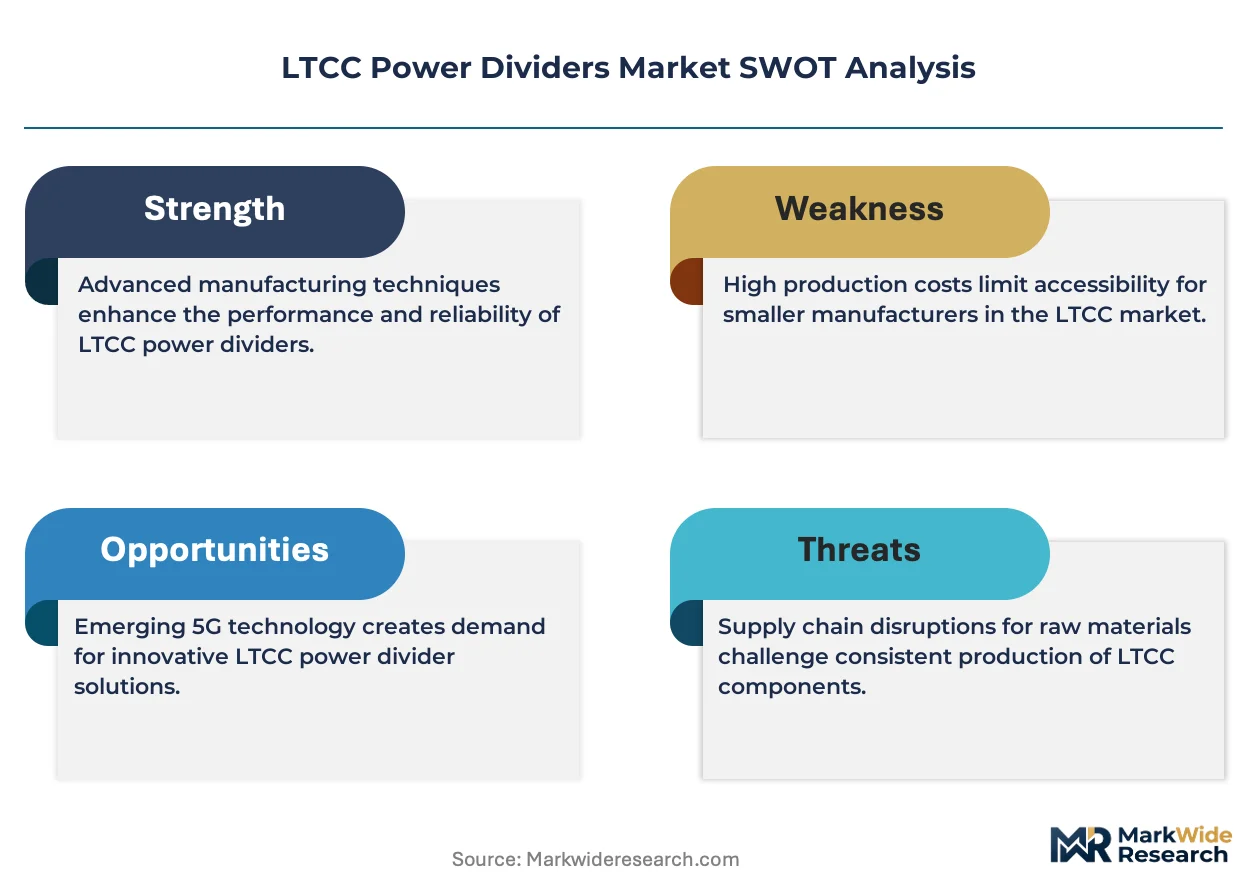
LTCC power dividers are multilayer ceramic devices fabricated by co-firing glass-ceramic tapes with printed metal conductors below 1000°C, achieving dielectric constants of 5-8 and insertion losses under 0.3 dB through X-band. These components split input RF signals into multiple phase-matched outputs for radar front-ends and satellite payload electronics. Wilkinson power divider configurations dominate military applications where isolation between output ports prevents cascade failures, while hybrid couplers capture expanding share in 5G massive MIMO arrays. Thin film technology segments serve test and measurement equipment requiring tighter amplitude balance than standard LTCC tolerances permit.
FCC Part 15 emissions rules and ITAR export controls shape product qualification timelines for US defense applications, while ESA ECSS-Q-ST-60-05C standards govern space-grade divider reliability in European satellite programs. Japan's METI promotes domestic sourcing of advanced ceramics through supply chain resilience directives. Stakeholders must monitor convergence between commercial 5G and military radar frequency allocations, as spectrum overlap forces simultaneous compliance with civilian interoperability and hardened environmental specifications.
Market Dynamics
Defense procurement cycles for phased array radar systems are compressing lead times for LTCC power dividers while silver-palladium paste specifications tighten under evolving material compliance frameworks. This dual pressure is restructuring supplier qualification protocols and accelerating vertical consolidation across ceramic substrate value chains.
Growth Catalysts
- Phased Array Radar Modernization:Defense agencies in the United States are expanding procurement of compact RF components for next-generation radar front-ends, creating sustained demand for Wilkinson configurations with port isolation exceeding 20 dB.
- REACH Material Compliance:European ECHA restrictions on hazardous substances are forcing paste reformulation toward lead-free glass-ceramic systems, which inadvertently improves thermal cycling performance for space-grade applications.
- Satellite Constellation Deployment:Low Earth orbit communications programs in Japan are consuming high-reliability dividers qualified to JAXA standards, with domestic ceramic substrate makers anchoring supply security through METI-directed resilience initiatives.
Market Restraints
- Precious Metal Cost Volatility:Silver-palladium conductor pastes represent 35-45% of raw material costs, with London Bullion Market Association pricing fluctuations directly compressing gross margins for multilayer fabricators.
- Japan-Centered Substrate Concentration:Over 60% of high-grade alumina and glass-ceramic tape supply originates from Japanese powder processors, creating geographic single-point vulnerability for non-domestic divider manufacturers.
- Thin Film Substitution Ceiling:Test and measurement equipment above 40 GHz increasingly specifies thin film on alumina substrates, capping LTCC addressable market in precision instrumentation segments.
Strategic Opportunities
- India Defense Indigenization:The country's PLI scheme for electronic components and DRDO import substitution lists are opening qualification pathways for non-traditional LTCC suppliers in radar and electronic warfare programs.
- 5G Massive MIMO Hybrid Couplers:Base station OEMs are specifying hybrid coupler architectures over Wilkinson designs for beamforming arrays, creating volume opportunities in commercial wireless infrastructure previously dominated by military-specification products.
- Direct OEM Engagement Models:Catalog distributors are losing share to factory-direct relationships as RF subsystem houses consolidate vendor bases and negotiate multi-year supply agreements with dedicated capacity allocation.
Industry Challenges
- Co-Firing Process Expertise Gap:Qualified tape casting and via fill technicians are concentrated at Japanese and Korean manufacturers, constraining capacity expansion at newer fabrication facilities in Southeast Asia.
- ITAR-FCC Convergence Complexity:Dual-use products must simultaneously satisfy United States ITAR export controls and FCC Part 15 unintentional radiator limits, extending qualification timelines by 8-14 months for cross-border defense contracts.
- Silver Migration Under Bias:Electrochemical migration in fine-line silver conductors under DC bias conditions remains an unaddressed failure mode for long-duration geostationary satellite missions, requiring redundant design margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LTCC Power Dividers Market |
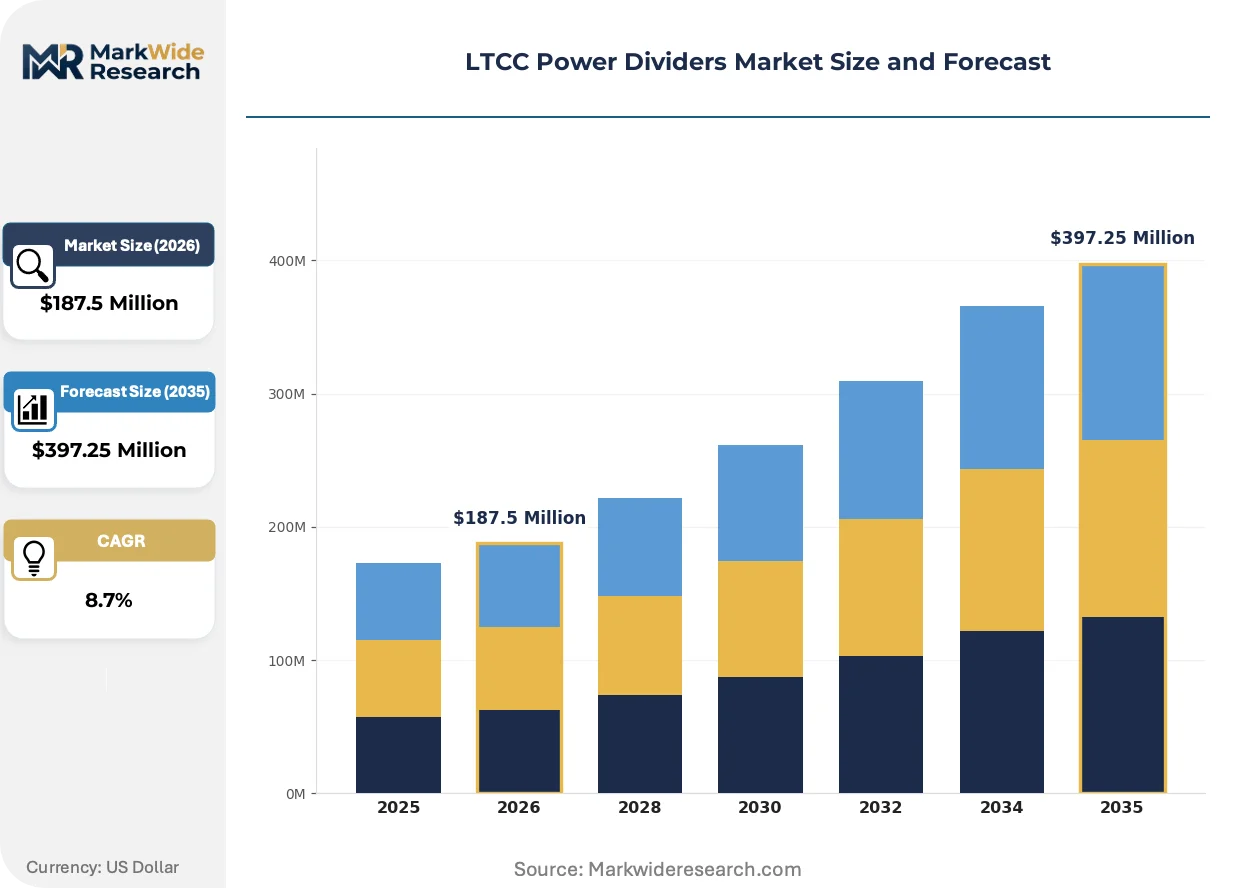
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $397.25 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3 dB Power Divider, Wilkinson Power Divider, Resistive Power Divider, Hybrid Coupler, Branch Line Coupler Technology: Low Temperature Co-fired Ceramic, High Temperature Co-fired Ceramic, Multilayer Ceramic, Thin Film, Thick Film Application: Radar Systems, Satellite Communications, Wireless Infrastructure, Test & Measurement, Radar Altimeters, Aerospace Telemetry End User: Telecommunication Equipment Manufacturers, Defense Agencies, Space Research Organizations, Electronics OEMs |
| Companies Covered | TDK, Mini-Circuits, Electro-Photonics, BDStar (Glead), Murata Manufacturing Co., Ltd., Kyocera Corporation, Taiyo Yuden Co., Ltd., Hitachi Metals Ltd., NGK Spark Plug Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LTCC Power Dividers Market Trends and Innovations
Material science advances and procurement model restructuring are converging to redefine competitive positioning in ceramic RF components. Fabrication processes, regulatory compliance frameworks, and buyer-seller relationships are all undergoing simultaneous transformation.
Low-temperature co-fired ceramic with embedded passive components is collapsing the discrete component count in RF front-end modules. Satellite payload manufacturers in Japan and the United States are adopting these integrated substrates for 20-40% reduction in assembly labor. This integration is collapsing the addressable market for standalone chip resistors and capacitors in divider-adjacent circuitry.
REACH Annex XIV authorization requirements for lead and cadmium compounds are forcing paste suppliers to certify alternative glass frit compositions by 2026. European space agencies under ESA ECSS-Q-ST-60-05C are accepting these reformulated materials only with accelerated thermal cycling data. Space-grade divider manufacturers are responding by dual-qualifying legacy and lead-free pastes to maintain program eligibility across defense and commercial satellite contracts.
Consolidated procurement by prime defense contractors is displacing fragmented distributor purchasing for LTCC power dividers. Raytheon, Northrop Grumman, and Lockheed Martin are mandating direct supplier audits and captive inventory programs for critical RF components. This concentration is most visible in United States Navy and Air Force radar programs, where sole-source agreements now cover 70-80% of ceramic divider volume.
LTCC Power Dividers Market Segmentation
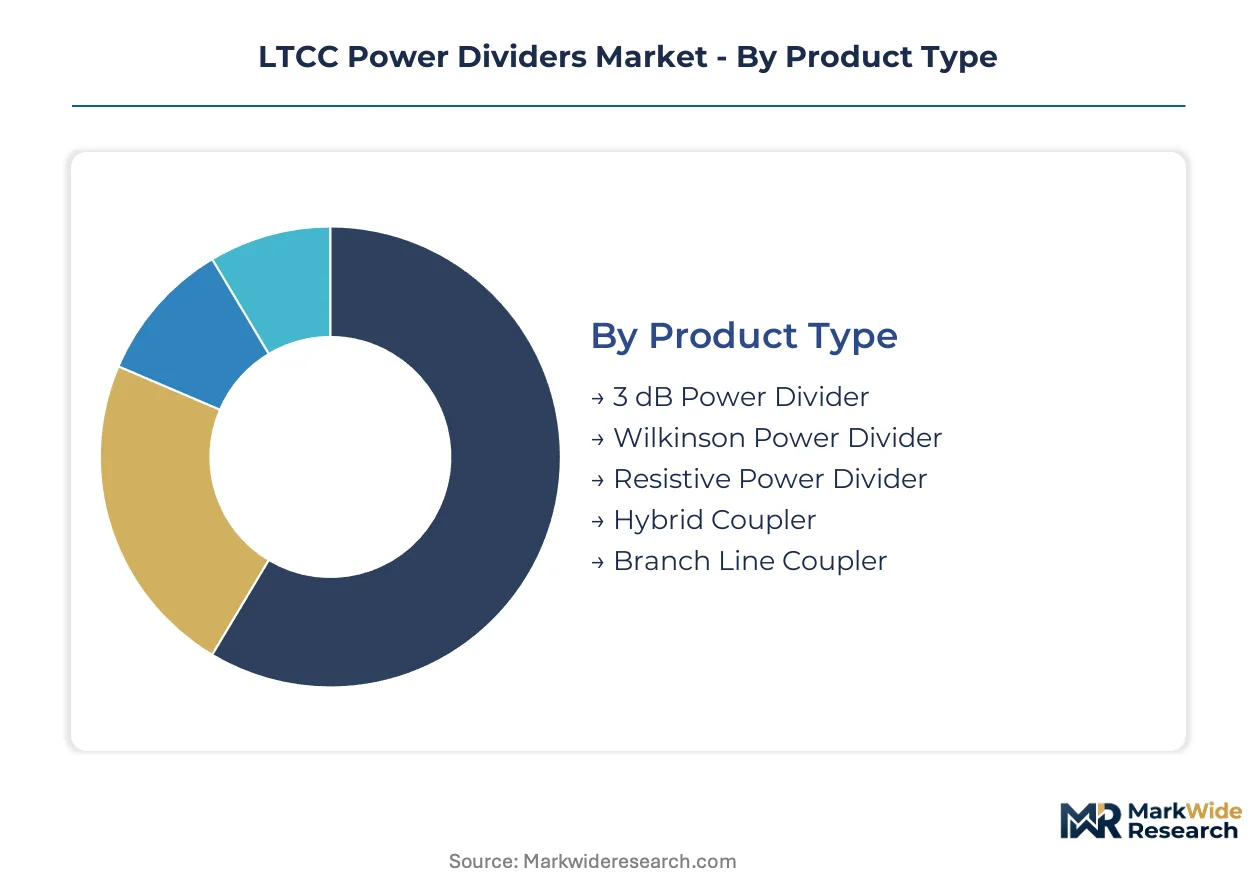
LTCC power dividers serve distinct performance requirements across military radar, satellite payloads, and commercial wireless infrastructure. Segmentation reveals how fabrication technology, circuit topology, and end-use specifications create divergent procurement patterns and margin structures.
Product Type:
Mature Wilkinson configurations dominate mission-critical applications while hybrid couplers emerge as the fastest-expanding topology for 5G beamforming arrays.
- Wilkinson Power Divider:Quarter-wave transmission line sections with isolation resistors deliver 20 dB+ port isolation for phased array radar front-ends. United States Navy and Air Force radar programs specify this configuration exclusively, with Raytheon and Northrop Grumman mandating direct supplier audits and captive inventory programs.
- Hybrid Coupler:Quadrature phase-splitting networks achieve 90-degree output phase relationships essential for massive MIMO beamforming. Base station OEMs in South Korea and Japan are specifying hybrid architectures over Wilkinson designs, creating volume opportunities in commercial wireless infrastructure previously reserved for military-specification products.
- 3 dB Power Divider:Equal-amplitude splitting networks serve general-purpose RF distribution in test equipment and lower-tier wireless infrastructure.
- Resistive Power Divider:Broadband resistive networks sacrifice efficiency for flat frequency response across multi-octave instrumentation applications.
- Branch Line Coupler:Quadrature hybrids fabricated in planar LTCC formats address compact quadrature downconverter modules in satellite receivers.
Wilkinson Power Divider retains volume leadership; Hybrid Coupler holds the steepest expansion curve.
Technology:
Cost tier separation runs from premium thin-film precision to economy thick-film consumer volumes, with co-fired ceramics occupying the technical middle ground.
- Low Temperature Co-fired Ceramic:Glass-ceramic tapes co-fired below 1000°C with silver-palladium conductors achieve dielectric constants of 5-8 and insertion losses under 0.3 dB through X-band. Defense procurement cycles for phased array radar systems are compressing lead times while silver-palladium paste specifications tighten under evolving REACH material compliance frameworks.
- Thin Film:Photolithographically patterned metal on polished alumina substrates delivers sub-micron line resolution for test and measurement equipment above 40 GHz. This precision comes at 3-5x the unit cost of LTCC, capping addressable market in precision instrumentation segments where amplitude balance tolerances exceed standard ceramic capabilities.
- High Temperature Co-fired Ceramic:Alumina-based systems fired above 1500°C with refractory metal conductors serve legacy aerospace programs with established qualification heritage.
- Multilayer Ceramic:Embedded passive integration collapses discrete component counts in RF front-end modules, with satellite payload manufacturers in Japan achieving 20-40% assembly labor reduction.
- Thick Film:Screen-printed conductors on ceramic substrates address cost-sensitive consumer wireless peripherals with relaxed electrical specifications.
Low Temperature Co-fired Ceramic commands the dominant revenue share; Thin Film claims the premium pricing tier with steepest expansion in instrumentation.
Application:
Customer type concentration separates defense-primed radar programs from commercial wireless infrastructure rollouts, with satellite communications bridging both procurement modes.
- Radar Systems:Phased array antenna architectures require hundreds to thousands of phase-matched dividers per aperture. United States defense agencies are expanding procurement of compact RF components for next-generation radar front-ends, creating sustained demand for Wilkinson configurations with port isolation exceeding 20 dB.
- Satellite Communications:Low Earth orbit constellation programs in Japan consume high-reliability dividers qualified to JAXA standards. Domestic ceramic substrate makers anchor supply security through METI-directed resilience initiatives, with over 60% of high-grade alumina and glass-ceramic tape supply originating from Japanese powder processors.
- Wireless Infrastructure:5G massive MIMO base stations deploy hybrid couplers for beamforming arrays, with volume procurement consolidating around direct OEM engagements rather than traditional electronics distributors.
- Test & Measurement:Precision instrumentation above 40 GHz increasingly specifies thin film on alumina substrates, capping LTCC penetration in this frequency range.
- Radar Altimeters:Compact LTCC dividers serve commercial aviation and unmanned aerial vehicle terrain-following radar with moderate reliability requirements.
- Aerospace Telemetry:Launch vehicle and spacecraft data transmission systems utilize hermetic ceramic packaging for environmental hardening.
Radar Systems maintains procurement volume leadership; Satellite Communications exhibits the most rapid demand acceleration.
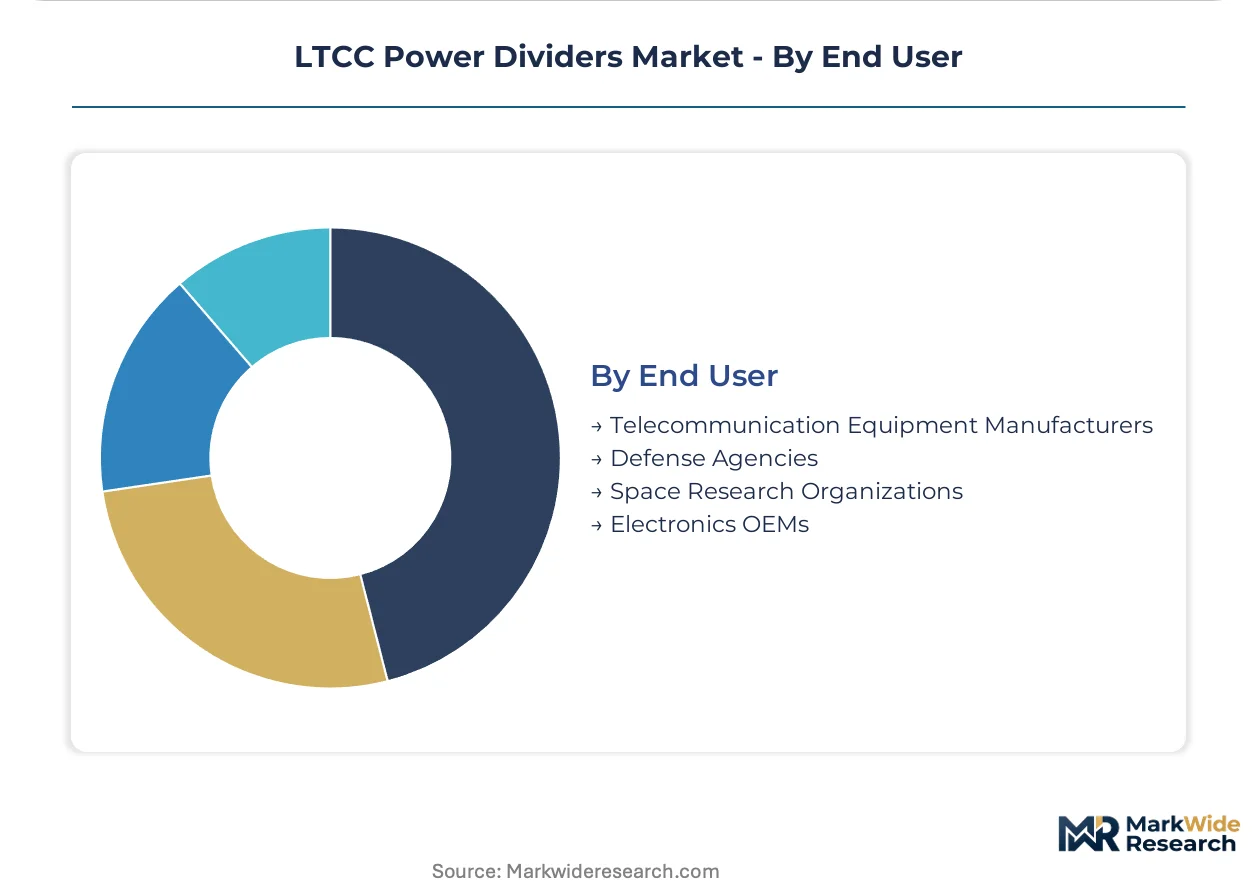
End User:
Supply concentration distinguishes captive defense supply chains from fragmented commercial electronics procurement, with space research organizations imposing the most stringent qualification protocols.
- Defense Agencies:United States Department of Defense programs operate under ITAR export controls and FCC Part 15 emissions rules, extending qualification timelines by 8-14 months for cross-border contracts. Sole-source agreements now cover 70-80% of ceramic divider volume in Navy and Air Force radar programs.
- Space Research Organizations:ESA ECSS-Q-ST-60-05C standards govern space-grade divider reliability in European satellite programs, with accelerated thermal cycling data required for lead-free paste acceptance. Electrochemical migration in fine-line silver conductors under DC bias remains an unaddressed failure mode for long-duration geostationary missions.
- Telecommunication Equipment Manufacturers:Ericsson, Nokia, and Samsung base station divisions are consolidating vendor bases and negotiating multi-year supply agreements with dedicated capacity allocation, displacing traditional catalog distributors.
- Electronics OEMs:Diversified RF subsystem houses source standard catalog configurations through remaining distributor channels for non-critical applications.
Defense Agencies dominate absolute procurement value; Space Research Organizations impose the most demanding technical qualification barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pacific submarine cable systems linking Japan to continental Asia and North America underwrite the country's central role in satellite communications supply chains. Defense procurement corridors along the US East Coast and ceramic processing clusters in Bavaria create distinct demand geographies for multilayer RF components.
United States
Phased array radar modernization programs at Raytheon and Northrop Grumman drive procurement of Wilkinson configurations with 20 dB+ port isolation. ITAR export controls and FCC Part 15 emissions rules extend qualification timelines by 8-14 months for cross-border defense contracts. The Boston-Washington corridor concentrates prime contractor engineering and sole-source agreements covering 70-80% of Navy and Air Force ceramic divider volume.
Japan
Low Earth orbit constellation programs consume high-reliability dividers qualified to JAXA standards for satellite payload integration. METI-directed supply chain resilience initiatives anchor domestic sourcing of advanced ceramics through powder processor subsidies. Kanto region substrate makers control over 60% of high-grade alumina and glass-ceramic tape supply, creating geographic concentration for non-domestic manufacturers.
Germany
ESA ECSS-Q-ST-60-05C standards govern space-grade divider reliability in European satellite programs with accelerated thermal cycling requirements for lead-free paste acceptance. REACH Annex XIV authorization deadlines for 2026 force paste suppliers to certify alternative glass frit compositions. Bavarian precision ceramics clusters dual-qualify legacy and reformulated materials to maintain program eligibility across defense and commercial contracts.
South Korea
5G massive MIMO base station OEMs specify hybrid coupler architectures over Wilkinson designs for beamforming arrays. Samsung base station divisions consolidate vendor bases and negotiate multi-year supply agreements with dedicated capacity allocation. Seoul-Incheon electronics manufacturing corridors displace traditional catalog distributors with factory-direct procurement models.
India
DRDO import substitution lists and PLI scheme incentives for electronic components open qualification pathways for non-traditional LTCC suppliers in radar programs. Defense indigenization mandates compress vendor approval cycles for domestic ceramic fabricators. Bangalore-Hyderabad aerospace corridors anchor emerging production capacity for electronic warfare subsystem integration.
LTCC Power Dividers Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated ceramic specialists and catalog distributors losing share to direct OEM engagements. Three strategic archetypes dominate: Japanese powder-to-component integrators controlling substrate quality from raw material sourcing; Korean and Taiwanese scale producers serving consumer wireless infrastructure; and North American catalog houses competing through custom design turnaround speed. Competitive moves concentrate on captive inventory programs for defense primes and multi-year capacity allocation agreements with telecommunications equipment manufacturers.
Among Japanese fabricators, TDK exemplifies the vertically integrated archetype through captive ferrite and ceramic operations, while Murata Manufacturing Co., Ltd. anchors high-volume automated production for consumer-facing wireless infrastructure. Mini-Circuits occupies a position within the North American catalog distributor tier, representing the rapid-custom-design competitive vector against integrated manufacturing specialists.
| Leading Market Players |
|---|
| TDK |
| Mini-Circuits |
| Electro-Photonics |
| BDStar (Glead) |
| Murata Manufacturing Co., Ltd. |
| Kyocera Corporation |
| Taiyo Yuden Co., Ltd. |
| Hitachi Metals Ltd. |
| NGK Spark Plug Ltd. |
| Others |
Pricing and Supply Chain Analysis
Kanto region substrate makers anchor global supply capacity for glass-ceramic tapes, and their production discipline translates directly into pricing power over non-integrated divider fabricators in North America and Europe. Silver-palladium paste cost pass-through mechanisms favor vertically integrated Japanese producers while squeezing margins at catalog distributors dependent on spot metal markets.
Pricing Analysis
Volume-discount tiering separates military-qualified Wilkinson configurations from commercial hybrid couplers and economy-grade resistive dividers. Price differentiation hinges on JAXA certification grade and captive inventory program participation, with defense primes absorbing premium tiers while telecommunications OEMs drive cost compression through multi-year offtake agreements. Pricing pressure stems from London Bullion Market Association silver volatility feeding raw material cost escalation. Test equipment manufacturers exhibit highest price sensitivity as thin film alternatives capture precision instrumentation share above 40 GHz.
Supply Chain Analysis
Upstream feedstock concentration rests on Japanese powder processors controlling high-grade alumina and glass-ceramic tape supply, with Korean and Taiwanese fabricators drawing from these same sources. Raw material dependencies center on silver-palladium conductor pastes, proprietary glass frit formulations, and precision tape casting equipment. Single-source vulnerability concentrates in Kanto region ceramic substrate production, where METI-directed resilience initiatives have not yet diversified geographic footprint. Distribution runs through direct OEM engagements displacing traditional electronics wholesalers, with Raytheon and Samsung mandating factory-direct procurement and captive inventory programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a service-attach opportunity because qualification support and thermal cycling test data packages generate recurring revenue streams expanding faster than standalone component hardware sales.
For Market Incumbents: Build captive powder-to-component moats through backward integration into ferrite and ceramic substrate production. TDK's model of controlling substrate quality from raw material sourcing sets the defensive standard. Acquire tape casting and via fill technician expertise pools in Japan and Korea before competitors consolidate this scarce capability. Thin film substitution above 40 GHz threatens standard LTCC positioning in precision instrumentation, requiring dual-technology qualification investments. For New Entrants and Emerging Players: Establish a beachhead in India's DRDO import substitution programs where PLI scheme incentives compress vendor approval cycles for domestic ceramic fabricators. Target Bangalore-Hyderabad aerospace corridors for electronic warfare subsystem integration partnerships before prime contractor consolidation closes qualification pathways. Lead with accelerated custom design turnaround against Mini-Circuits catalog model, emphasizing hybrid coupler architectures for 5G massive MIMO base station procurement. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because defense procurement concentration and REACH material compliance barriers favor scaled specialists over fragmented distributors. Target vertically integrated mid-cap ceramic fabricators with existing JAXA or ESA ECSS-Q-ST-60-05C qualification heritage. Watch silver-palladium paste reformulation timelines as inflection indicator—lead-free glass-ceramic systems achieving accelerated thermal cycling acceptance will separate qualified suppliers from stranded legacy inventory.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Inventory Program | Raytheon sole-source agreements now cover majority of Navy ceramic divider volume. |
| Paste Reformulation Certification | REACH Annex XIV authorization deadlines force dual-qualification of lead-free materials. |
| Direct OEM Engagement Model | Samsung base station divisions displace catalog distributors with factory-direct procurement. |
| Technician Expertise Acquisition | Qualified tape casting specialists concentrate at Japanese and Korean manufacturers. |
| Hybrid Coupler Architecture Pivot | 5G massive MIMO beamforming arrays specify quadrature phase-splitting over Wilkinson designs. |
Research Methodology
A spread of perspectives from RF subsystem procurement managers, ceramic fabrication engineers, defense program qualification leads, and satellite payload integration specialists converged on the working assumptions. Primary fieldwork combined structured interviews with tape casting technicians and paste formulation chemists alongside secondary validation through JAXA technical standards, ESA ECSS-Q-ST-60-05C reliability protocols, and METI supply chain resilience directives. Customs data on silver-palladium paste imports, SEC filings from prime defense contractors, and telecommunications equipment manufacturer capex disclosures anchored bottom-up and top-down triangulation.
Demand-supply-balance framing across the analysis window modeled volume and value outputs through segmentation across circuit topology, fabrication technology, end-use application, and customer procurement mode. CAGRs derived from phased array radar modernization program announcements, low Earth orbit constellation deployment schedules, and 5G base station rollout trajectories. Forecast inputs incorporated silver price volatility scenarios, ITAR-FCC qualification timeline distributions, and hybrid coupler substitution elasticities in commercial wireless infrastructure.
Sensitivities concentrate around silver-palladium London Bullion Market Association price spikes, REACH Annex XIV authorization delays, and Japanese substrate export restriction scenarios. Forecasts reflect documented assumptions on defense procurement cycle compression and satellite constellation deployment pacing. Cross-checking against ESA and JAXA published qualification statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Coaxial Connectors (RF) Market
RF Components
Harness-Level EMI and Shielding Component Systems Market
RF Components
RF Power Detector Market
RF Components
RFID Tags Market
RF Components
Global RF Power Semiconductor Market
RF Components
Radio Frequency Components Market
RF Components
Global RF Transceiver Market
RF Components
RF Passive Component Market
RF Components
RF Front End Module Market
RF Components
Asia-Pacific Small Signal Transistor Market
RF Components
UHF RFID Inlays Market
RF Components
RF Interconnect Market
RF Components
433MHz Active RFID Reader Market
RF Components
RF Mixers Market
RF Components
Low Noise Amplifier Market
RF Components
RFID Antenna Market