
 High-Frequency RF Evaluation Board Market | 2026-2036
High-Frequency RF Evaluation Board Market Size, Share, and Industry Trends Forecast 2026-2036
High-Frequency RF Evaluation Board Market Insights
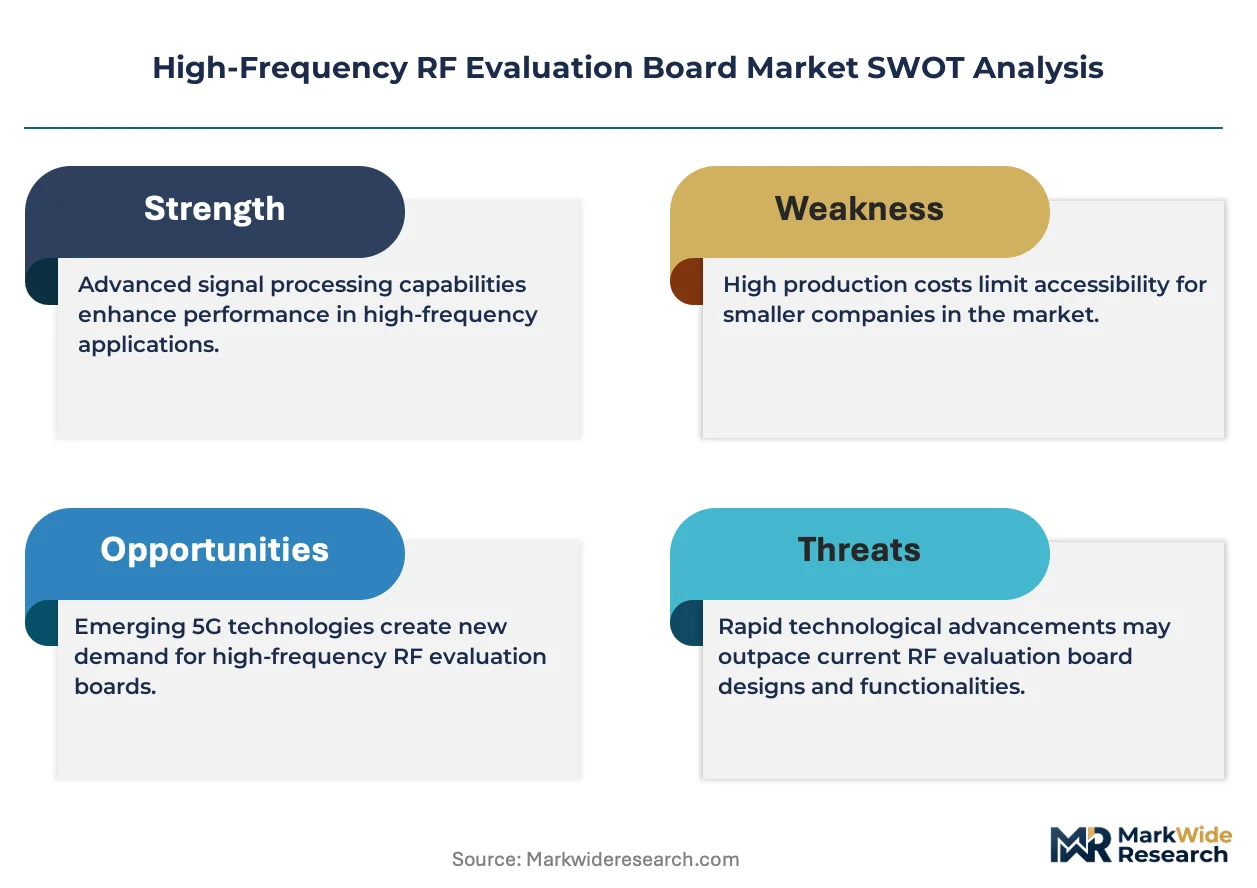
IEC 61000-4-3 electromagnetic immunity qualification is bifurcating the supplier landscape into certified tier-one vendors and uncertified challengers. Texas Instruments leverages its vertically integrated fabs to sustain pricing power on GaAs-based reference designs. Qorvo anchors its position through deep partnerships with 5G baseband chipset makers, while STMicroelectronics competes aggressively on CMOS RF front-end evaluation kits for cost-sensitive satellite ground stations.
High-frequency RF evaluation boards are test and measurement platforms engineered to characterize radio frequency integrated circuits and modules across gigahertz-scale bandwidths, typically employing Rogers RO4350B or Taconic TLY-5 substrates with controlled dielectric constants below 3.7 to preserve signal integrity through 40 GHz. Their primary purpose is to de-risk front-end designs before mass production by providing calibrated reference environments for S-parameter extraction and spurious emission profiling. Wideband evaluation boards now command the dominant share of unit volume as multi-protocol testing displaces single-band legacy workflows, while GaAs technology retains the highest margin pool due to its irreplaceable performance in defense-grade power amplifier validation. RF MEMS segments remain niche but are accelerating fastest as tunable filter architectures penetrate software-defined radio test benches.
FCC Part 15 rules constrain unintentional radiator emissions from evaluation hardware, forcing board designers to integrate shielding cans and filtered power entry modules that add bill-of-materials cost. ETSI EN 301 489 in Europe and the EU Radio Equipment Directive impose parallel conformity burdens that fragment SKU strategies for vendors serving both markets. Defense procurement regulations through the U.S. Department of Commerce Bureau of Industry and Security further restrict GaN-on-SiC evaluation platform exports, tightening supply to allied nations. Stakeholders must monitor how 3GPP's progression toward sub-terahertz spectrum definitions reshapes reference board bandwidth requirements before committing to fixed hardware architectures.
Market Dynamics
Defense procurement cycles are compressing validation timelines for millimeter-wave reference platforms, while FCC spectrum reallocations force simultaneous multi-band testing that strains legacy single-protocol board architectures.
Growth Catalysts
- 3GPP Release 17 mandates:Sub-terahertz definitions are accelerating reference board refresh rates for 5G-Advanced baseband validation, pulling demand toward wideband-capable substrates.
- GaN-on-SiC adoption in radar:Pentagon procurement offices are specifying these power amplifiers for next-generation electronic warfare, creating captive demand for specialized thermal-management evaluation kits.
- Munich engineering cluster density:Rohde & Schwarz and Infineon co-location is generating knowledge spillovers that shorten design-to-test cycles for European defense contractors.
Market Restraints
- Rogers RO4350B supply concentration:Three North American laminate mills control high-frequency substrate supply, exposing board fabricators to allocation risk during defense procurement surges.
- IEC 61000-4-3 certification cost:Electromagnetic immunity qualification requires anechoic chamber testing that adds six-figure fixed costs, excluding uncertified challengers from tier-one defense contracts.
- GaAs foundry scarcity:Legacy gallium arsenide capacity is concentrating in East Asian merchant foundries, constraining reference design availability for classified programs with domestic-source mandates.
Strategic Opportunities
- RF MEMS tunable filters:Software-defined radio test benches in Germany and France are adopting micro-electromechanical architectures that demand new characterization platforms with sub-millisecond switching validation.
- Satellite ground station commoditization:CMOS RF front-end evaluation kits for low-earth-orbit terminal manufacturers represent an underpenetrated volume segment outside traditional defense procurement channels.
- EU Radio Equipment Directive harmonization:Converged certification pathways between member states are reducing SKU fragmentation for vendors serving both German automotive radar and French aerospace test houses.
Industry Challenges
- Millimeter-wave calibration expertise:Vector network analyzer operation above 40 GHz requires specialized technicians that RF engineering programs in the United States and Germany are not producing at replacement rates.
- Shielding integration complexity:FCC Part 15 compliance demands co-design of filtered power entry modules with substrate stackups, extending layout cycles without automated electromagnetic simulation workflows.
- Export control navigation:Bureau of Industry and Security restrictions on GaN-on-SiC platform shipments force dual supply chain maintenance for allied nation programs versus domestic-only configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Frequency RF Evaluation Board Market |
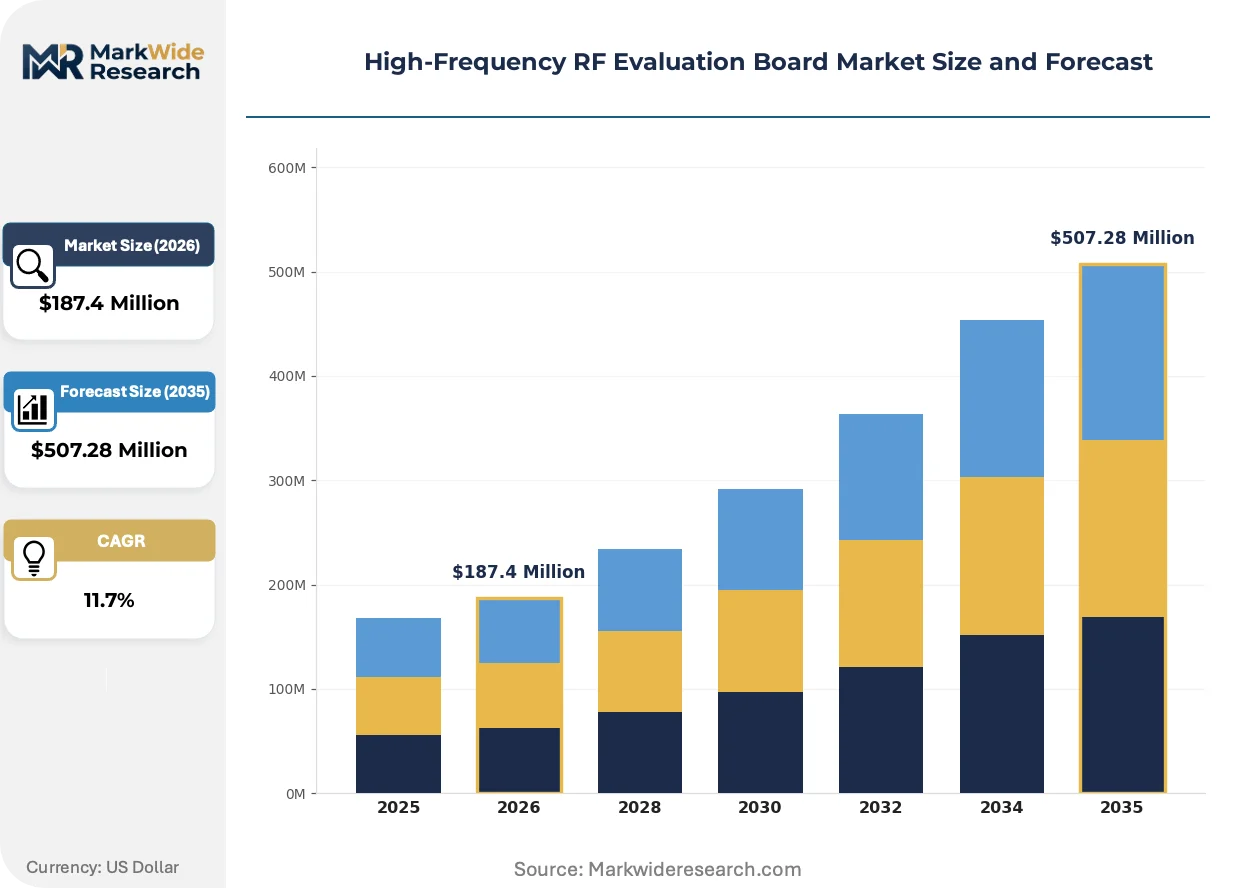
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Band, Dual Band, Multi Band, Wideband Technology: SiGe, GaAs, CMOS, RF MEMS, LDMOS Application: 5G Communication, Radar Systems, Satellite Communication, Aerospace, Defense End User: Telecommunication Manufacturers, Aerospace Contractors, Defense Agencies, Satellite Operators |
| Companies Covered | Texas Instruments, Qorvo, STMicroelectronics, Renesas Electronics Corporation, Akoustis Technologies, pSemi, CML Microcircuits, Ampleon, MACOM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Frequency RF Evaluation Board Market Trends and Innovations
Substrate architectures and validation protocols are converging around multi-octave bandwidth requirements that obsolete narrowband legacy workflows.
Organic laminate formulations with ceramic fillers are miniaturizing passive component footprints while preserving dielectric stability through 67 GHz. Defense prime contractors in the United States are qualifying these materials for conformal radar test fixtures that must fit compact anechoic chambers. The shift is miniaturizing board geometries without sacrificing S-parameter accuracy, compressing fixture costs for high-volume production validation.
ETSI EN 301 489 electromagnetic compatibility frameworks are tightening spurious emission limits for evaluation hardware sold into European Union member states. Board designers must now integrate ferrite-loaded shielding cans and segmented ground planes that add measurable bill-of-materials weight. Satellite ground station manufacturers in France and Germany are absorbing these costs fastest, treating pre-certified reference platforms as procurement differentiators.
Defense procurement offices are consolidating validation contracts under multi-year framework agreements that bundle evaluation board supply with calibration services. Traditional spot-purchase distributors are losing share to direct manufacturer relationships with embedded field application engineering. This concentration is most visible in North America, where Pentagon test range operators now specify single-source accountability for measurement traceability chains.
High-Frequency RF Evaluation Board Market Segmentation
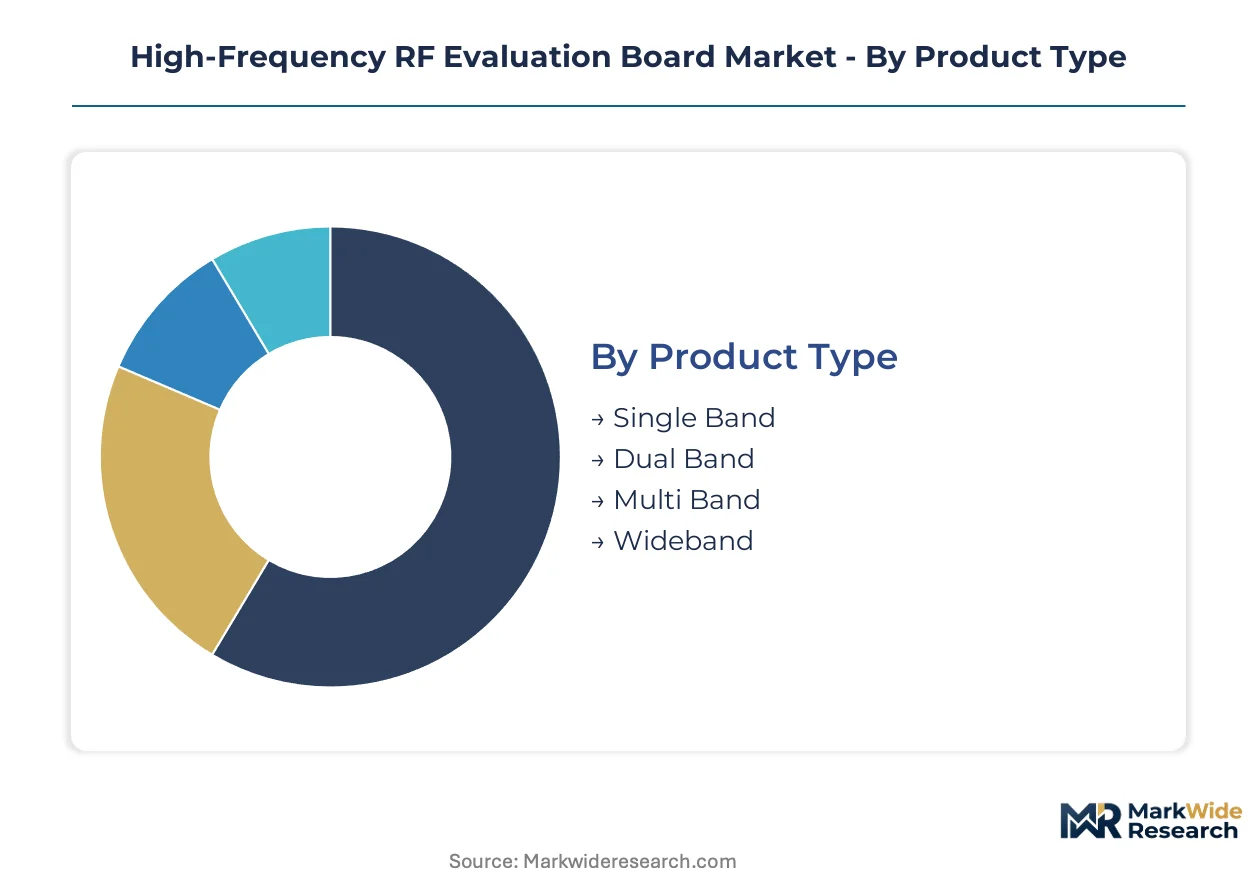
Segmentation in high-frequency RF evaluation boards reveals distinct procurement patterns across defense, commercial, and export-controlled channels. Each dimension—product architecture, semiconductor technology, application vertical, and end-user category—carries unique regulatory and supply chain constraints that shape vendor strategies.
Product Type:
Domestic defense procurement in the United States favors wideband architectures for multi-spectrum radar validation, while export-restricted programs still specify single-band legacy boards to limit technology transfer risk. European telecommunications manufacturers import multi-band platforms for 3GPP Release 17 baseband testing, compressing design cycles through reusable hardware.
- Wideband:These platforms span multiple octaves with Rogers RO4350B or Taconic TLY-5 substrates, enabling S-parameter extraction across 6-40 GHz without fixture swaps. Pentagon test range operators specify these for electronic warfare validation, though IEC 61000-4-3 certification requirements restrict qualified suppliers to a handful of tier-one vendors.
- Multi Band:Architectures supporting discrete protocol blocks—5G NR, Wi-Fi 6E, and satellite bands—are concentrating demand in Germany's Munich engineering cluster, where Rohde & Schwarz co-location with Infineon accelerates design-to-test cycles for automotive radar manufacturers.
- Dual Band:Compact footprints suit cost-sensitive satellite ground station manufacturers in France and commercial 5G small cell developers.
- Single Band:Legacy narrowband designs persist in classified programs with domestic-source mandates and restricted export classifications.
Wideband holds the largest share; momentum sits with multi-band platforms as protocol consolidation accelerates.
Technology:
Margin structures diverge sharply across semiconductor processes, with GaAs commanding premium pricing for defense-grade power amplifier validation while CMOS gains volume in commoditized satellite terminals.
- GaAs:Irreplaceable for high-linearity power amplifier characterization through 40 GHz, these reference designs rely on legacy foundry capacity concentrated in East Asia. Bureau of Industry and Security export controls on GaN-on-SiC platforms indirectly strengthen GaAs demand for allied nation programs.
- RF MEMS:Micro-electromechanical tunable filters are expanding most quickly in software-defined radio test benches across Germany and France, requiring sub-millisecond switching validation that legacy solid-state architectures cannot provide.
- CMOS:STMicroelectronics competes aggressively on cost-sensitive satellite ground station evaluation kits for low-earth-orbit terminal manufacturers.
- SiGe:Silicon-germanium BiCMOS suits millimeter-wave transceiver validation below 30 GHz for commercial 5G infrastructure.
- LDMOS:Lateral diffused metal-oxide-semiconductor dominates UHF and L-band radar characterization for ground-based early warning systems.
GaAs retains the highest margin pool; RF MEMS is climbing the fastest as tunable architectures penetrate defense and commercial test benches.
Application:
Defense procurement cycles compress validation timelines for millimeter-wave reference platforms, while FCC spectrum reallocations force simultaneous multi-band testing that strains legacy single-protocol board architectures.
- Radar Systems:Next-generation electronic warfare programs specify GaN-on-SiC power amplifiers with specialized thermal-management evaluation kits. Pentagon procurement offices bundle these under multi-year framework agreements that consolidate supplier relationships.
- 5G Communication:Sub-terahertz definitions in 3GPP Release 17 are accelerating reference board refresh rates for baseband validation, pulling substrate demand toward wideband-capable formulations.
- Defense:Broader than radar alone, this segment encompasses signals intelligence and electronic countermeasure test fixtures with stringent measurement traceability requirements.
- Satellite Communication:Low-earth-orbit constellation deployments are commoditizing CMOS RF front-end evaluation kits outside traditional defense channels.
- Aerospace:Conformal test fixtures for compact anechoic chambers demand organic laminate formulations with ceramic fillers qualified by United States defense prime contractors.
Radar systems command the dominant procurement value; 5G communication is gaining share fastest as Release 17 mandates propagate through equipment manufacturer roadmaps.
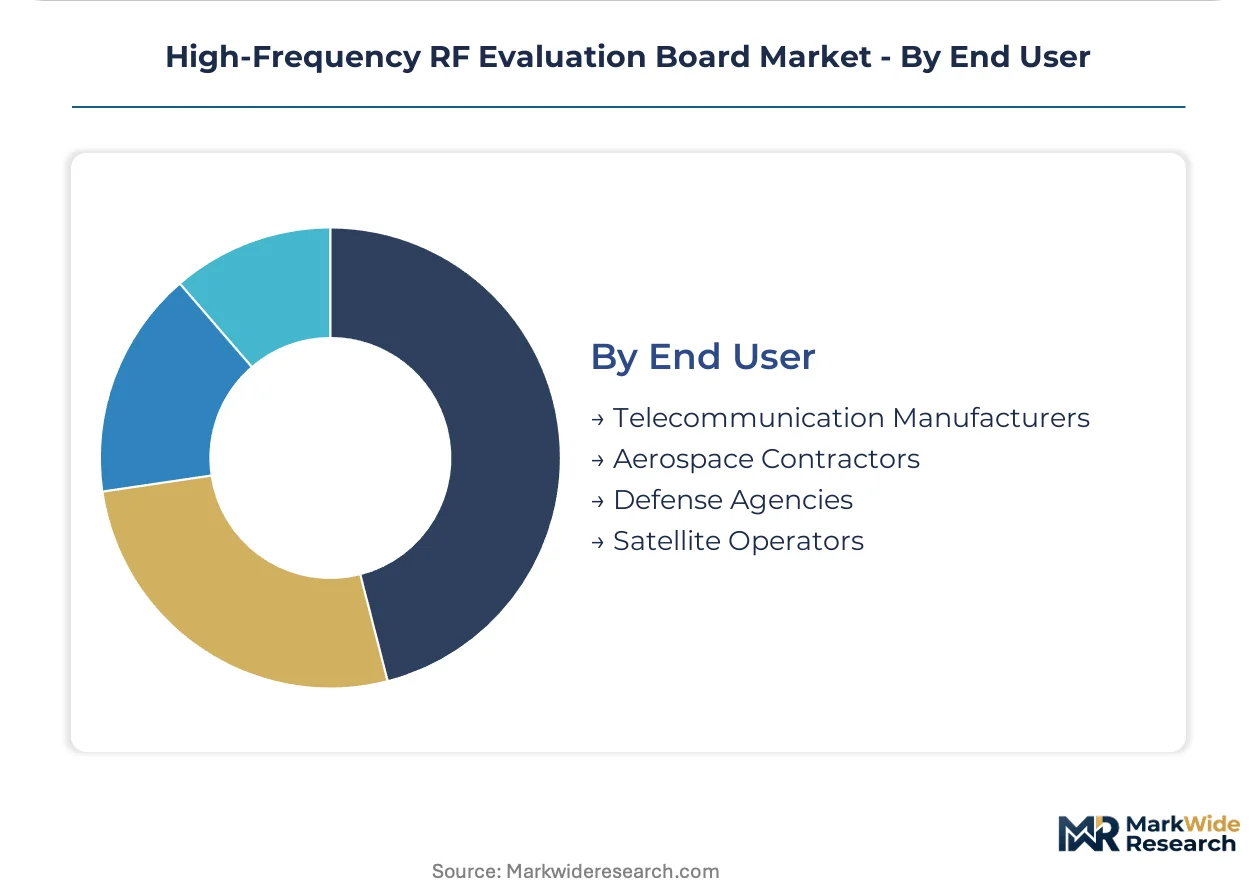
End User:
Procurement concentration varies by institutional buyer type, with defense agencies specifying single-source accountability for measurement traceability while commercial manufacturers prioritize cost and availability.
- Defense Agencies:United States Department of Commerce Bureau of Industry and Security regulations restrict GaN-on-SiC platform exports, tightening supply to allied nations and forcing dual supply chain maintenance for vendors.
- Telecommunication Manufacturers:European baseband chipset makers source multi-band reference boards through direct manufacturer relationships, bypassing traditional spot-purchase distributors.
- Aerospace Contractors:French and German test houses absorb ETSI EN 301 489 compliance costs fastest, treating pre-certified reference platforms as procurement differentiators.
- Satellite Operators:Ground station manufacturers represent an underpenetrated volume segment with distinct price sensitivity compared to defense procurement channels.
Defense agencies hold the largest share; satellite operators present the steepest expansion trajectory as low-earth-orbit terminal production scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement offices in the United States concentrate the largest procurement value for millimeter-wave reference platforms, while Germany's engineering cluster and China's substrate manufacturing base anchor complementary supply chain nodes. Telecommunication manufacturers in France and Japan complete the geographic spread with distinct regulatory and demand profiles.
United States
Pentagon test range operators specify wideband evaluation boards for electronic warfare validation under compressed procurement timelines. FCC Part 15 rules constrain unintentional radiator emissions, forcing shielding integration that extends design cycles. Defense prime contractors in California and Massachusetts qualify organic laminate formulations with ceramic fillers for conformal radar test fixtures.
Germany
Automotive radar manufacturers and aerospace test houses drive multi-band platform demand around Munich's engineering cluster. ETSI EN 301 489 electromagnetic compatibility frameworks tighten spurious emission limits, accelerating pre-certified reference platform adoption. Rohde & Schwarz co-location with Infineon generates knowledge spillovers that shorten design-to-test cycles for European defense contractors.
China
Domestic 5G infrastructure deployment sustains volume demand for CMOS RF front-end evaluation kits. MIIT spectrum policies and GB standards for radio equipment shape substrate qualification requirements. Pearl River Delta fabricators concentrate Rogers RO4350B laminate processing capacity for regional board manufacturers serving commercial telecommunications.
France
Satellite ground station manufacturers absorb ETSI compliance costs fastest, treating pre-certified reference platforms as procurement differentiators. ANSM and national regulators enforce parallel conformity burdens that influence SKU strategies for vendors serving both French and German markets. Aerospace test houses in Toulouse and Paris anchor demand for compact anechoic chamber fixtures.
Japan
METI industrial policy supports millimeter-wave test equipment development for 5G-Advanced and sub-terahertz research. JIS standards for high-frequency materials intersect with domestic semiconductor equipment manufacturer requirements. Kanto region electronics clusters concentrate vector network analyzer calibration expertise that supports reference board validation workflows.
High-Frequency RF Evaluation Board Market Competitive Landscape
Player mix skews toward vertically integrated semiconductor manufacturers with captive substrate sourcing and specialized RF engineering houses with deep test equipment partnerships. Tier-one vendors with IEC 61000-4-3 certification dominate defense procurement channels, while uncertified challengers compete on price for commercial telecommunications. Two strategic archetypes prevail: integrated device manufacturers leveraging in-house fab capacity for GaAs reference designs, and fabless specialists partnering with foundries for RF MEMS tunable filter platforms. Competitive moves concentrate on multi-year framework agreements bundling hardware with calibration services, and direct manufacturer relationships displacing traditional distribution.
Within the integrated device manufacturer tier, Texas Instruments and STMicroelectronics exemplify divergent technology positioning—one anchored in vertically integrated GaAs fabrication, the other competing aggressively on CMOS cost structures for satellite ground station applications. Qorvo occupies a position between these poles, representing the partnership-driven archetype through deep relationships with 5G baseband chipset makers that secure reference design socket wins. These three companies collectively illustrate how semiconductor process choices and channel strategies bifurcate competitive positioning across defense and commercial end markets.
| Leading Market Players |
|---|
| Texas Instruments |
| Qorvo |
| STMicroelectronics |
| Renesas Electronics Corporation |
| Akoustis Technologies |
| pSemi |
| CML Microcircuits |
| Ampleon |
| MACOM |
| Others |
Pricing and Supply Chain Analysis
Organic laminate formulations with ceramic fillers are displacing legacy Rogers RO4350B substrates in high-frequency applications, simultaneously shifting procurement gravity toward Pearl River Delta fabricators and compressing per-unit material costs for wideband evaluation platforms. This substitution dynamic reshapes margin structures across defense and commercial channels as board manufacturers recalibrate stackup economics.
Pricing Analysis
Multi-year framework agreements with Pentagon test range operators typically embed cost-plus contract patterns indexed to Rogers Corporation laminate pricing schedules. Three-tier pricing structure across IEC 61000-4-3 certified premium boards, uncertified commercial-grade alternatives, and economy CMOS kits for satellite terminals reflects certification investment recovery timelines. Cost compression in the economy tier intensifies because STMicroelectronics and Chinese CMOS specialists compete aggressively on volume. Satellite ground station manufacturers exhibit highest price sensitivity, while defense agencies prioritize measurement traceability over unit cost.
Supply Chain Analysis
Inbound logistics costs for Rogers RO4350B laminates spiked during Pacific trade lane congestion, exposing board fabricators to allocation risk when defense procurement surges collide with container availability constraints. High-frequency substrate supply draws from three North American laminate mills, East Asian GaAs foundries, and Pearl River Delta processing capacity. Single-source vulnerability concentrates in legacy gallium arsenide wafer production, where merchant foundry consolidation in Taiwan and South Korea constrains reference design availability. Distribution runs through direct manufacturer relationships with embedded field application engineering, displacing traditional spot-purchase distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from RF MEMS tunable filter architectures that threaten GaAs dominance in software-defined radio test benches, requiring defensive positioning around certification moats and captive substrate relationships.
For Market Incumbents: Fortify IEC 61000-4-3 certification barriers through anechoic chamber investment, locking out uncertified challengers from tier-one defense contracts. Deepen backward integration into Rogers RO4350B laminate supply through multi-year offtake agreements with North American mills, insulating procurement against allocation shocks during Pentagon validation surges.
For New Entrants and Emerging Players: EU Radio Equipment Directive harmonization fast-tracks market access across German automotive radar and French aerospace test houses without duplicate conformity investments. Target satellite ground station manufacturers in France with pre-certified CMOS evaluation kits, exploiting price sensitivity outside defense procurement channels. Lead with direct technical sales teams rather than distributor relationships to accelerate socket wins.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors RF MEMS specialists with sub-millisecond switching validation capabilities over legacy GaAs incumbents. Long-term viability hinges on exposure to 3GPP Release 17 refresh cycles and sub-terahertz reference board demand. Monitor Bureau of Industry and Security export control rulings on GaN-on-SiC platforms as inflection indicator for allied nation program access and dual supply chain requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| IEC 61000-4-3 Certification Investment | Anechoic chamber qualification excludes uncertified challengers from Pentagon electronic warfare contracts. |
| Multi-Year Framework Agreement | Defense procurement consolidation bundles evaluation board supply with calibration services under single-source accountability. |
| RF MEMS Platform Development | Sub-millisecond switching validation captures software-defined radio test bench demand in Germany and France. |
| Rogers RO4350B Supply Agreement | Captive laminate sourcing from North American mills mitigates allocation risk during procurement surges. |
| Direct Manufacturer Relationship | Embedded field application engineering displaces traditional distribution for telecommunication manufacturers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with Pentagon test range operators, Rohde & Schwarz application engineers, Infineon RF design leads, satellite ground station procurement managers, and vector network analyzer calibration technicians. Secondary validation drew from FCC Part 15 filings, ETSI EN 301 489 conformity databases, Bureau of Industry and Security export control rulings, and 3GPP Release 17 specification documents. Bottom-up segment sizing triangulated against top-down defense procurement budget analysis.
Across the analysis window, the forecast framework modeled product type segmentation across wideband, multi-band, dual-band, and single-band architectures; technology trajectories spanning GaAs, RF MEMS, CMOS, SiGe, and LDMOS; and application verticals including radar systems, 5G communication, defense, satellite communication, and aerospace. CAGRs derived from S-curve adoption modeling for sub-terahertz reference boards and procurement cycle compression effects from Pentagon validation timelines. Industry-specific inputs included 3GPP spectrum definition progression and GaN-on-SiC thermal management kit demand.
Decision-makers should treat outputs as directional under assumptions of sustained defense procurement acceleration and stable Rogers laminate supply; material deviation would warrant model refresh. Specific risks include Bureau of Industry and Security export control expansion, IEC 61000-4-3 certification backlog, and RF MEMS foundry capacity constraints. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
5G Gain Block Amplifier Market
RF Components
CATV RF Amplifiers Market
RF Components
RF Mixers Market
RF Components
High Reliability Oscillators Market
RF Components
GPS Low Noise Amplifier Market
RF Components
Radio Frequency Counter Market
RF Components
RF Microwave MLCC Market
RF Components
RF Tunable Filters Market
RF Components
5G Millimeter Wave RF Transceiver Market
RF Components
US RFID Tags Market
RF Components
High-Power Microwave Source Market
RF Components
Wi-Fi Module Market
RF Components
Radio Frequency Front End Module Market
RF Components
RF Spectrum Analyzer Market
RF Components
UHF RFID Inlays Market
RF Components
Global RF and Microwave Power Transistors Market