
 Analog Phase Shifter Market | 2026-2036
Analog Phase Shifter Market Size, Share, and Industry Trends Forecast 2026-2036
Analog Phase Shifter Market Analysis
Buyer concentration among defense prime contractors is shifting as the Pentagon consolidates supplier lists for next-generation radar programs. Analog Devices leverages its integrated circuit portfolio to capture design wins in electronically scanned arrays. Qorvo anchors its position through gallium nitride process leadership for high-frequency phase shifting modules. Mini-Circuits competes on manufacturing scale, sustaining cost advantages in standard catalog offerings for test equipment OEMs.
An analog phase shifter is a passive or active RF component that introduces a controlled, continuous phase delay to an electromagnetic signal without digital quantization, typically operating across microwave and millimeter-wave bands from hundreds of megahertz to over 100 GHz using varactor diodes, PIN diodes, or transmission-line networks. It serves primarily to steer antenna beam patterns in phased arrays and synchronize signal paths in radar and communication systems. RF Phase Shifters dominate procurement volumes in defense applications where insertion loss and power handling govern selection, while MEMS technology leads in telecommunications infrastructure seeking lower power consumption. Integrated Circuits represent the fastest-growing category as system architects push phase control into monolithic beamformer chips.
The US Department of Defense drives demand through MIL-STD-883 screening requirements and ITAR export controls that limit supplier eligibility to domestic-qualified manufacturers. FCC spectrum allocation rulings for 5G and future 6G bands shape frequency planning for commercial phase shifter designs. EU RoHS and REACH compliance requirements constrain material choices for European telecommunications deployments. Stakeholders must monitor gallium nitride supply chain concentration and defense budget authorization cycles to calibrate capacity investments.
Market Dynamics
Gallium nitride semiconductor technology is compressing insertion loss benchmarks while Pentagon procurement consolidation is narrowing the qualified supplier base for next-generation phased array radar programs.
Growth Catalysts
- Defense Procurement Consolidation:Pentagon-directed electronic warfare modernization programs are concentrating design wins among domestic-qualified manufacturers meeting MIL-STD-883 screening requirements.
- ITAR Export Controls:US International Traffic in Arms Regulations limit supplier eligibility to domestic-qualified manufacturers, protecting incumbent positions from foreign competition.
- Gallium Nitride Process Maturation:GaN semiconductor technology is displacing legacy silicon-based designs in high-power RF applications, enabling higher frequency operation with improved thermal performance.
Market Restraints
- Substrate Supply Concentration:Gallium nitride substrate manufacturing concentrates among a handful of specialized foundries, creating single-source vulnerability for high-frequency module production.
- ITAR Compliance Friction:US export control classification requirements impose documentation burdens and licensing delays that constrain commercial diversification opportunities for defense-qualified suppliers.
- Silicon Carbide Substitution:SiC-based RF components offer competitive power handling at lower cost points for sub-6 GHz applications, pressuring analog phase shifter pricing in telecommunications infrastructure.
Strategic Opportunities
- 6G Spectrum Allocation:FCC rulings on millimeter-wave bands above 100 GHz are opening frequency planning horizons for next-generation telecommunications beamforming architectures.
- Monolithic Integration:Convergence of phase control functions with low-noise amplifiers and power amplifiers onto single-die beamformer chips is collapsing board area requirements for active electronically scanned arrays.
- EU Green Deal Compliance:RoHS and REACH material restrictions are creating certification barriers that favor established suppliers with documented supply chain traceability for European telecommunications deployments.
Industry Challenges
- GaN Process Engineering Talent Scarcity:Compound semiconductor fabrication expertise concentrates among a limited pool of engineers with experience in high-electron-mobility transistor design.
- MIL-STD-883 Qualification Timelines:Extended screening protocols for defense-grade components delay revenue recognition and tie up working capital for 18-24 month qualification cycles.
- Legacy System Integration Complexity:Backward compatibility requirements with existing radar architectures constrain architectural freedom and prolong design cycles for upgraded platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Analog Phase Shifter Market |
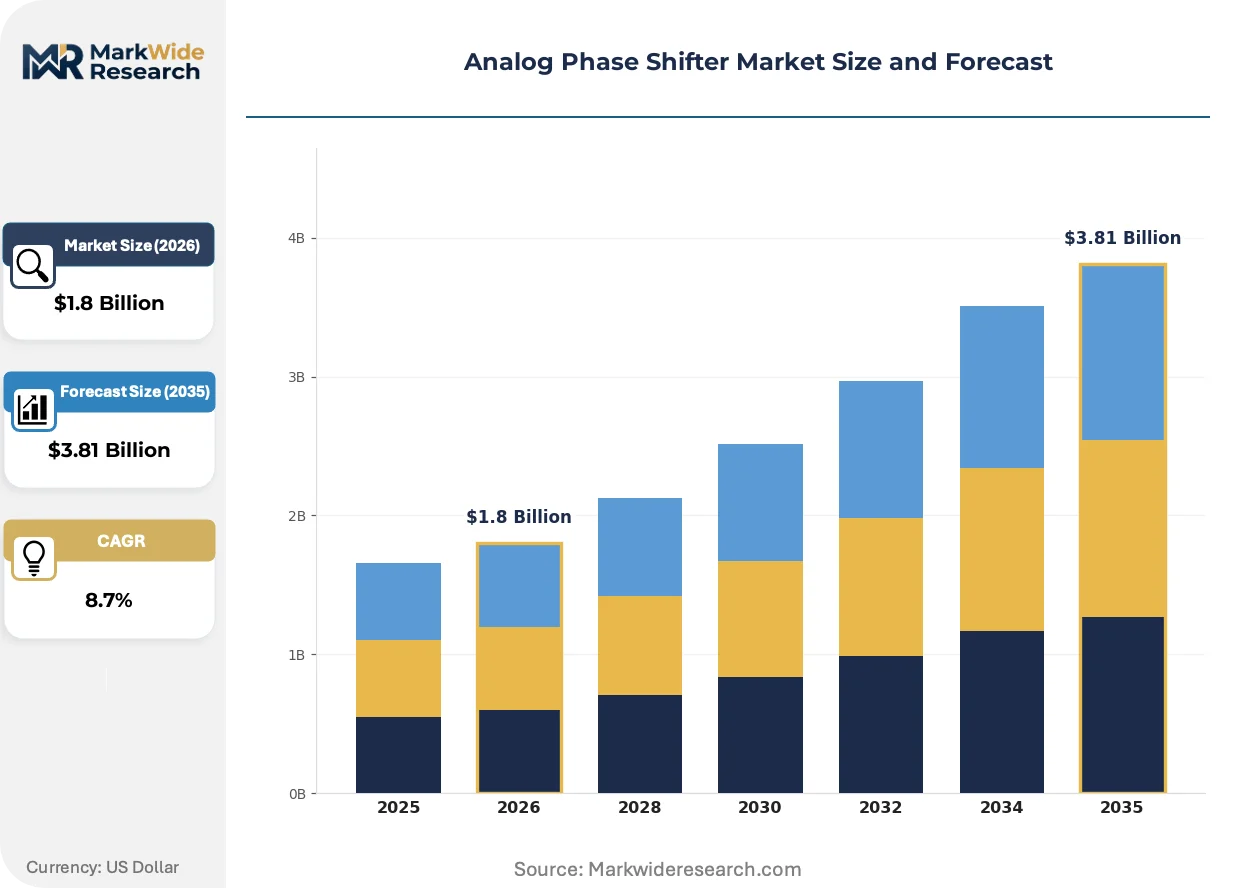
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Phase Shifters, RF Phase Shifters, Calibration Devices, Integrated Circuits Technology: MEMS, Liquid Crystal, Ferrite, Microstrip End User: Telecommunications, Aerospace, Defense, Test & Measurement Application: Signal Processing, Antenna Systems, Wireless Communication, Radar Systems |
| Companies Covered | Mini-Circuits, SAGE Millimeter, Analog Devices, Qorvo, Qotana Technologies, Cobham, Pulsar Microwave Corporation, NXP Semiconductors, Crane Aerospace & Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analog Phase Shifter Market Emerging Trajectories
Beamformer chip integration is collapsing discrete component counts while regulatory pressure on material content and spectrum efficiency is reshaping design priorities across defense and commercial applications.
Silicon-germanium BiCMOS processes are integrating phase shifting, amplification, and digital control functions onto monolithic die for sub-6 GHz 5G massive MIMO infrastructure. Telecommunications OEMs are adopting these integrated beamformers at accelerated pace to reduce antenna element count and calibration complexity. This technology is integrating RF and digital control functions that previously required separate assemblies, compressing bill-of-materials costs and assembly labor content for base station manufacturers.
REACH substance restrictions are constraining cadmium, lead, and hexavalent chromium usage in European telecommunications phase shifter production. Manufacturers are reformulating plating chemistries and substrate metallizations to maintain CE marking eligibility for network infrastructure deployments. Commercial catalog suppliers serving European markets are absorbing compliance costs through supplier qualification programs and material substitution engineering.
Defense prime contractors are consolidating supplier lists for next-generation radar programs, compressing qualification timelines and demanding earlier design involvement from component vendors. This concentration is displacing catalog distribution models with direct engineering partnerships and co-development agreements. The United States exhibits the most pronounced shift, with Pentagon program offices mandating single-source accountability for phased array subsystems.
Analog Phase Shifter Market Segmentation
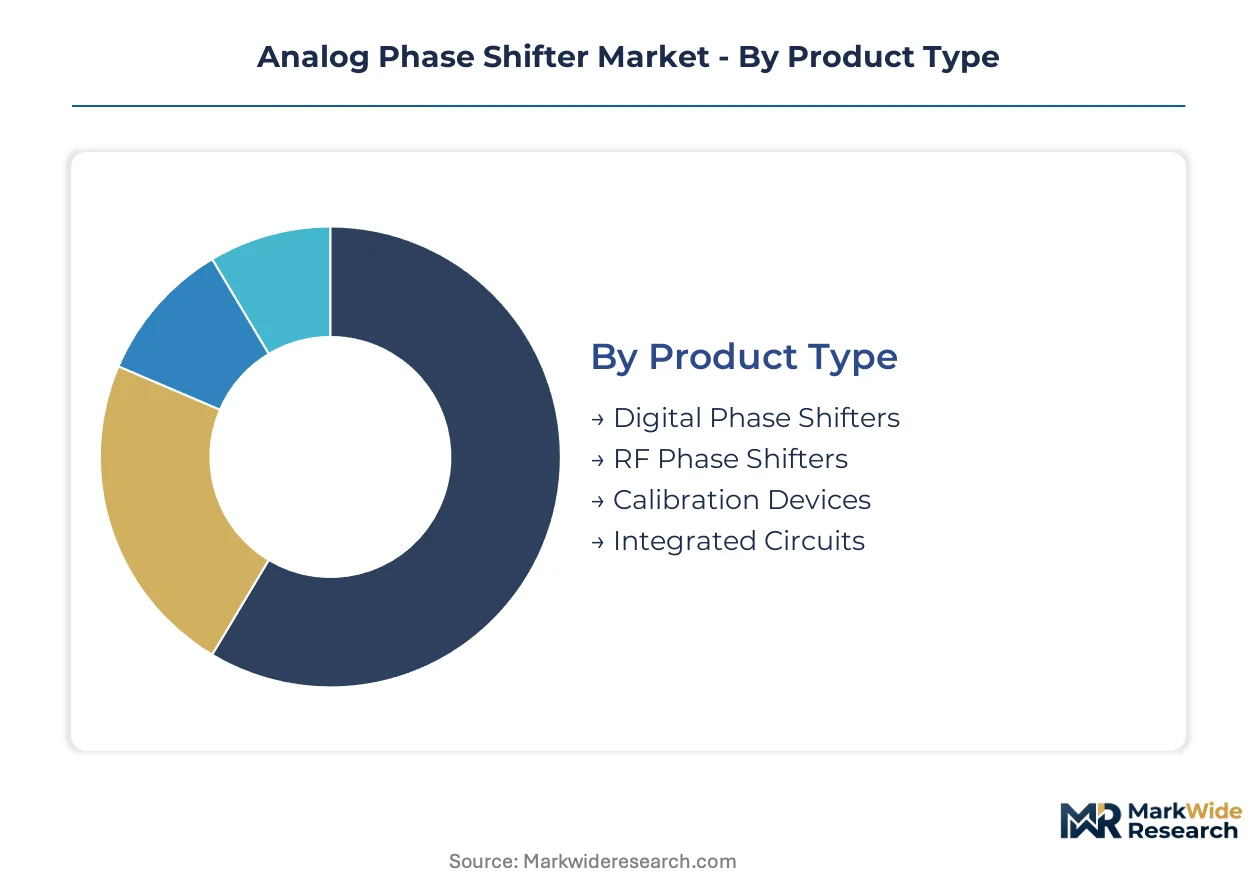
Analog phase shifter procurement patterns diverge sharply between defense-qualified suppliers and commercial catalog vendors, with technology selection and screening requirements creating distinct competitive arenas across product categories.
Product Type:
Defense procurement officers prioritize insertion loss specifications and power handling thresholds over unit economics, driving supplier consolidation toward MIL-STD-883 qualified manufacturers.
- RF Phase Shifters:Passive and active microwave components using varactor diodes or PIN diodes to introduce controlled phase delay across hundreds of megahertz to over 100 GHz. Pentagon-directed electronic warfare modernization programs concentrate procurement volumes here, with gallium nitride process technology displacing legacy silicon designs for thermal performance.
- Integrated Circuits:Monolithic beamformer chips converging phase control with amplification functions onto single-die architectures. System architects across United States defense programs and 5G infrastructure OEMs are collapsing board area requirements through this technology, which is expanding most quickly as silicon-germanium BiCMOS processes mature.
- Digital Phase Shifters:Quantized phase control devices with discrete step resolution for software-defined radio applications.
- Calibration Devices:Precision reference modules ensuring phase coherence across distributed antenna arrays in test environments.
Volume sits with RF Phase Shifters; growth tilts toward Integrated Circuits.
Technology:
Material constraints from EU RoHS and REACH compliance are reshaping process selection for suppliers serving European telecommunications infrastructure.
- MEMS:Microelectromechanical systems employing electrostatic actuation to vary transmission-line geometry with near-zero static power draw. Telecommunications infrastructure seeking lower power consumption drives demand concentration here, particularly for 5G massive MIMO base station deployments.
- Gallium Nitride:Wide-bandgap semiconductor technology enabling high-electron-mobility transistor designs with superior power density and thermal conductivity. Pentagon radar programs and electronic warfare systems anchor procurement, though substrate supply concentration among specialized foundries creates vulnerability.
- Liquid Crystal:Electrically tunable dielectric materials for low-loss phase control at millimeter-wave frequencies.
- Ferrite:Magnetic ceramic compounds providing non-reciprocal phase shifting for high-power radar applications.
- Microstrip:Printed circuit transmission-line structures with distributed varactor loading for cost-sensitive commercial applications.
Revenue concentrates in MEMS for commercial volume; technology leadership resides with gallium nitride for defense performance tiers.
End User:
ITAR export controls partition the supplier base, with domestic-qualified manufacturers capturing defense revenue while commercial vendors compete on manufacturing scale.
- Defense:Phased array radar and electronic warfare systems requiring MIL-STD-883 screening and ITAR compliance. The United States exhibits pronounced demand concentration around Pentagon program offices mandating single-source accountability for subsystem procurement.
- Telecommunications:5G and emerging 6G infrastructure seeking beamforming architectures for spectrum efficiency. FCC rulings on millimeter-wave bands above 100 GHz are opening frequency planning horizons for this segment, which is gaining share fastest as base station OEMs adopt integrated beamformers.
- Aerospace:Satellite communication and airborne radar platforms demanding radiation-hardened components.
- Test & Measurement:Calibration and characterization equipment for RF component verification.
Procurement value concentrates in Defense; commercial expansion tilts toward Telecommunications.
Application:
System architecture decisions—discrete versus monolithic integration—determine component selection across radar and communication platforms.
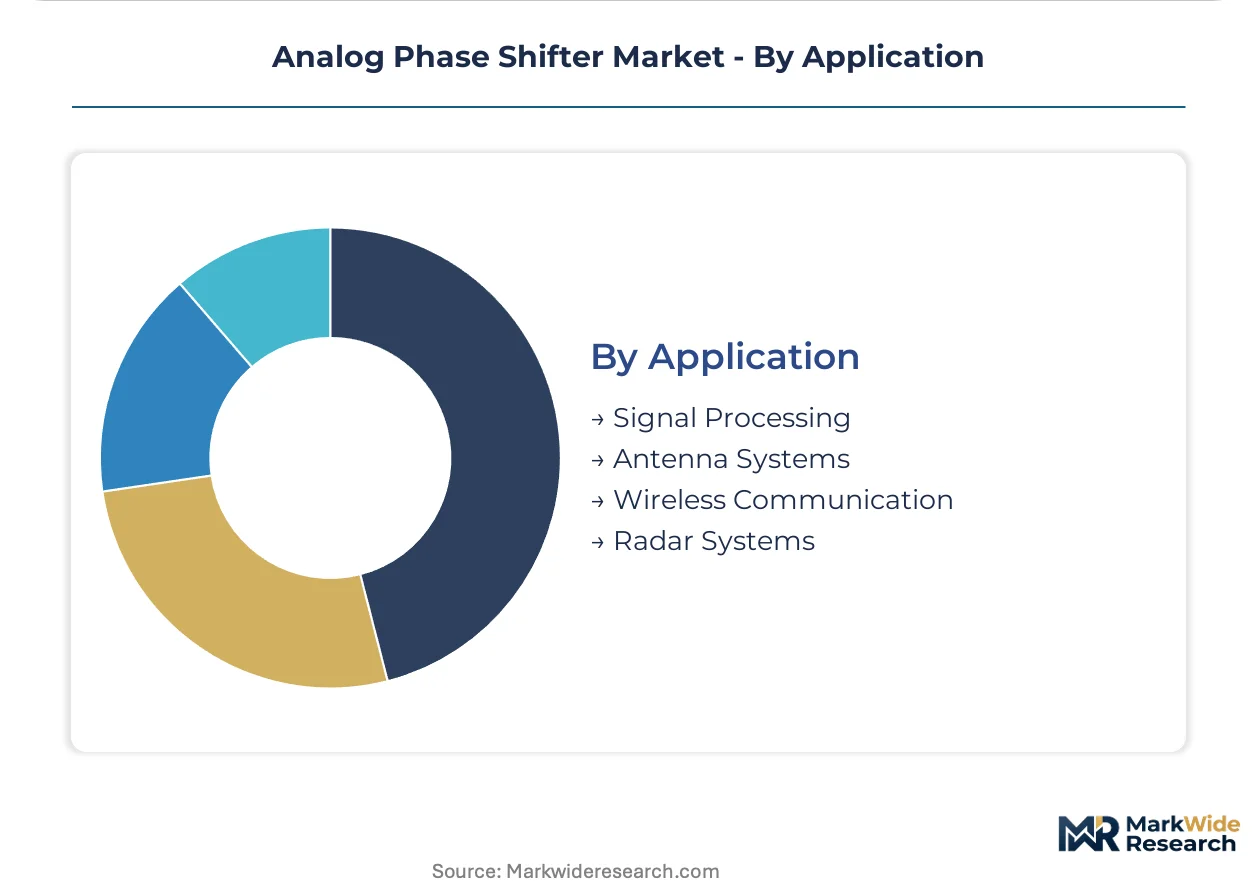
- Radar Systems:Active electronically scanned arrays requiring precise phase synchronization across hundreds of radiating elements. NATO member states are expanding phased array radar deployments, with prime contractors consolidating supplier lists and compressing qualification timelines.
- Antenna Systems:Beam steering and null-forming networks for terrestrial and satellite communication links.
- Signal Processing:Delay-line equalization and interference cancellation in wideband receivers.
- Wireless Communication:Massive MIMO beamforming for cellular infrastructure and backhaul.
Engineering resources concentrate on Radar Systems; architectural innovation tilts toward Antenna Systems integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement agencies in the United States concentrate the largest share of analog phase shifter demand through Pentagon-directed electronic warfare modernization programs. NATO member states are expanding phased array radar deployments, while telecommunications infrastructure buildouts in Asia-Pacific create secondary demand centers for commercial beamforming components.
United States
Pentagon program offices mandate single-source accountability for phased array subsystems, compressing supplier qualification timelines for defense-qualified manufacturers. FCC spectrum allocation rulings for 5G and future 6G bands shape frequency planning for commercial designs. The Greater Boston and Washington DC metropolitan clusters host concentrated defense electronics engineering talent pools.
Germany
Industrial electronics manufacturers anchor demand for precision RF components in automotive radar and test equipment applications. EU RoHS and REACH compliance requirements constrain material choices for telecommunications deployments. The Munich-Stuttgart corridor concentrates semiconductor packaging and RF module assembly operations serving European defense primes.
China
Domestic 5G base station OEMs drive procurement volumes for integrated beamformer chips in massive MIMO infrastructure. MIIT spectrum policies and GB standards govern millimeter-wave frequency planning for telecommunications equipment. The Yangtze River Delta manufacturing belt hosts concentrated substrate fabrication and RF component assembly capacity.
South Korea
Telecommunications infrastructure OEMs seek lower power consumption phase shifters for 5G massive MIMO deployments. MFDS and national spectrum regulators coordinate frequency allocation for next-generation cellular networks. The Seoul Capital Area anchors RF semiconductor design centers serving domestic and export markets.
Japan
Satellite communication and airborne radar platforms demand radiation-hardened components from specialized suppliers. METI industrial policy supports compound semiconductor fabrication for defense and space applications. The Nagoya-Chubu region maintains precision manufacturing clusters for high-frequency electronic components.
Analog Phase Shifter Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue monolithic integration and compound semiconductor process leadership. The supplier base concentrates among MIL-STD-883 qualified manufacturers for defense applications, while commercial catalog vendors compete on manufacturing scale and cost structure. Three archetypes dominate: integrated circuit portfolio holders, gallium nitride process specialists, and high-volume catalog distributors. Competitive moves center on supplier list consolidation by defense primes and strategic partnerships for beamformer chip co-development.
Within the integrated circuit tier, Analog Devices exemplifies portfolio breadth across RF signal chains. Qorvo occupies a position representing gallium nitride process leadership for high-frequency modules. Mini-Circuits anchors the catalog distribution archetype, sustaining manufacturing scale advantages for test equipment OEMs. These three entities collectively illustrate the competitive segmentation between defense-qualified precision suppliers and commercial-scale fabricators.
| Leading Market Players |
|---|
| Mini-Circuits |
| SAGE Millimeter |
| Analog Devices |
| Qorvo |
| Qotana Technologies |
| Cobham |
| Pulsar Microwave Corporation |
| NXP Semiconductors |
| Crane Aerospace & Electronics |
| Others |
Supply Flow & Price Mechanics
Pentagon program offices mandating single-source accountability for phased array subsystems have compressed procurement timelines toward contract-based long-term offtake agreements with MIL-STD-883 qualified manufacturers. This buyer concentration enables premium pricing tiers for defense-qualified suppliers while commercial catalog vendors absorb margin compression through volume scale.
Pricing Analysis
Defense procurement volumes anchor premium margins while commercial telecommunications infrastructure drives cost-down pressure. Three-tier pricing structure across MIL-qualified defense, industrial-grade commercial, and standard catalog offerings separates Analog Devices and Qorvo from Mini-Circuits on certification tier and thermal performance. Pricing pressure stems from silicon carbide substitution in sub-6 GHz telecommunications applications. Test equipment OEMs exhibit highest price sensitivity; Pentagon electronic warfare programs demonstrate lowest sensitivity due to ITAR-constrained supplier pools.
Supply Chain Analysis
Compound semiconductor fabrication expertise concentrates in the United States, Japan, and Germany, where high-electron-mobility transistor design talent scarcity constrains capacity expansion. Gallium nitride substrate supply draws from specialized foundries in the United States and Japan, with silicon-germanium BiCMOS wafer sourcing anchored in Taiwan and South Korea. Single-source vulnerability in GaN epitaxial wafer supply creates chokepoint exposure for high-frequency module production. Distribution runs through authorized distributors for defense-qualified components and direct OEM relationships for integrated beamformer chips.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Analog phase shifter procurement consolidation by defense primes is eliminating catalog distribution models, forcing weaker commercial vendors toward exit or acquisition as Pentagon-directed electronic warfare modernization programs concentrate design wins among domestic-qualified manufacturers.
For Market Incumbents: Anchor defense program office relationships through early-stage co-development agreements for next-generation radar architectures. Deepen gallium nitride process leadership through captive supply of epitaxial wafers to offset substrate concentration risk. Prioritize MIL-STD-883 qualification pipeline investment to compress 18-24 month screening timelines. For New Entrants and Emerging Players: Direct-to-defense-prime engineering partnerships bypass catalog distribution barriers that incumbent distributors dominate. Target telecommunications infrastructure OEMs in South Korea and Japan seeking lower power consumption MEMS phase shifters for 5G massive MIMO deployments. Pursue silicon-germanium BiCMOS beamformer chip co-development with base station manufacturers as the most penetrable entry vector. For Investors and Strategic Acquirers: The window for entry favors compound semiconductor process specialists with existing gallium nitride fabrication capability. Long-term viability hinges on defense program continuity through budget authorization cycles and telecommunications infrastructure refresh rates. Watch FCC spectrum allocation rulings for millimeter-wave bands above 100 GHz as the signal indicating telecommunications beamforming demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Process Leadership Investment | Captures Pentagon radar program design wins against silicon-based substitutes. |
| Monolithic Beamformer Integration | Collapses board area requirements for active electronically scanned arrays. |
| MIL-STD-883 Qualification Acceleration | Compresses 18-24 month screening cycles to match prime contractor timelines. |
| European REACH Compliance Certification | Maintains CE marking eligibility for telecommunications infrastructure OEMs. |
| Defense Prime Co-Development Partnership | Displaces catalog distribution models with direct engineering accountability. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with RF component procurement officers, phased array radar system architects, gallium nitride foundry operations managers, and telecommunications infrastructure OEM supply chain directors. SEC 10-K disclosures, Pentagon budget justification documents, FCC equipment authorization databases, and EU RoHS compliance registries provided validation layers. Bottom-up segment sizing triangulated against top-down defense expenditure and telecommunications capex aggregates.
Granularity-level modeling deployed product type, technology, end user, and application dimensions at the country level across the analysis window. RF phase shifter insertion loss specifications, power handling thresholds, and monolithic integration roadmaps informed segment-level CAGRs. Defense procurement consolidation timelines and FCC spectrum allocation rulings for 5G and 6G bands shaped regional demand trajectories.
The model holds under steady defense budget authorization and gallium nitride substrate supply continuity; deviation in Pentagon program cancellation rates or foundry disruption would shift volume and value outputs. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Latin America RFID Tags Market
RF Components
Digital Radio Frequency Market
RF Components
Smart Antenna Market
RF Components
Global Ceramic Dielectric Filters Market
RF Components
Flat Antenna Market
RF Components
Wi-Fi Module Market
RF Components
Japan Small Signal Transistor Market
RF Components
RF Over Fiber (Rfof) Market
RF Components
Radiofrequency Identification (RFID) Market
RF Components
RF Power Detector Market
RF Components
Phase Shifters Market
RF Components
RF Microwave MLCC Market
RF Components
High-Power Microwave Source Market
RF Components
EMI Microwave Absorber Market
RF Components
Microwave Devices Market
RF Components
RF-Microwave for 5G Market