
 Dielectric Resonator Market | 2026-2036
Dielectric Resonator Market Size, Share, and Industry Trends Forecast 2026-2036
Dielectric Resonator Market Outlook
Defense prime contractors is collapsing as the fastest-expanding buyer archetype for high-Q dielectric resonators, displacing legacy consumer electronics procurement patterns. Murata Manufacturing leverages captive ceramic powder synthesis to dominate premium resonator supply for millimeter-wave arrays. KYOCERA AVX Corporation anchors North American defense contracts through ITAR-compliant manufacturing cells in California. Exxelia specializes in space-qualified resonators, sustaining margins via ESA-certified heritage designs for satellite payloads.
A dielectric resonator is a ceramic or crystalline component that stores electromagnetic energy at microwave frequencies through standing-wave resonance, typically fabricated from barium titanate, alumina, or proprietary perovskite compositions with dielectric constants ranging from 20 to 100 and Q-factors exceeding 10,000. These devices serve as frequency-selective elements in filters, oscillators, and antenna feeds for RF systems requiring thermal stability and miniaturization. Standard resonators occupy mature volume tiers in cellular infrastructure, while tunable resonators capture expanding share in software-defined radio architectures. Composite resonators concentrate margin pools where aerospace buyers demand multi-octave performance. Microwave technology leads unit shipments across wireless communication applications, though photonic technology segments are gaining traction in radar signal processing chains.
FCC Part 15 emissions standards shape resonator insertion loss specifications for US telecommunications equipment, while REACH compliance constrains lead-based glaze formulations in European-sourced ceramics. China's GB standards for microwave components enforce domestic testing protocols that condition market access for foreign suppliers. India's WPC frequency allocation rules determine resonator center-frequency bands permitted for commercial 5G deployment. Stakeholders must monitor evolving quantum technology roadmaps, as cryogenic resonator requirements for quantum computing readout circuits could redirect R&D funding from conventional microwave designs.
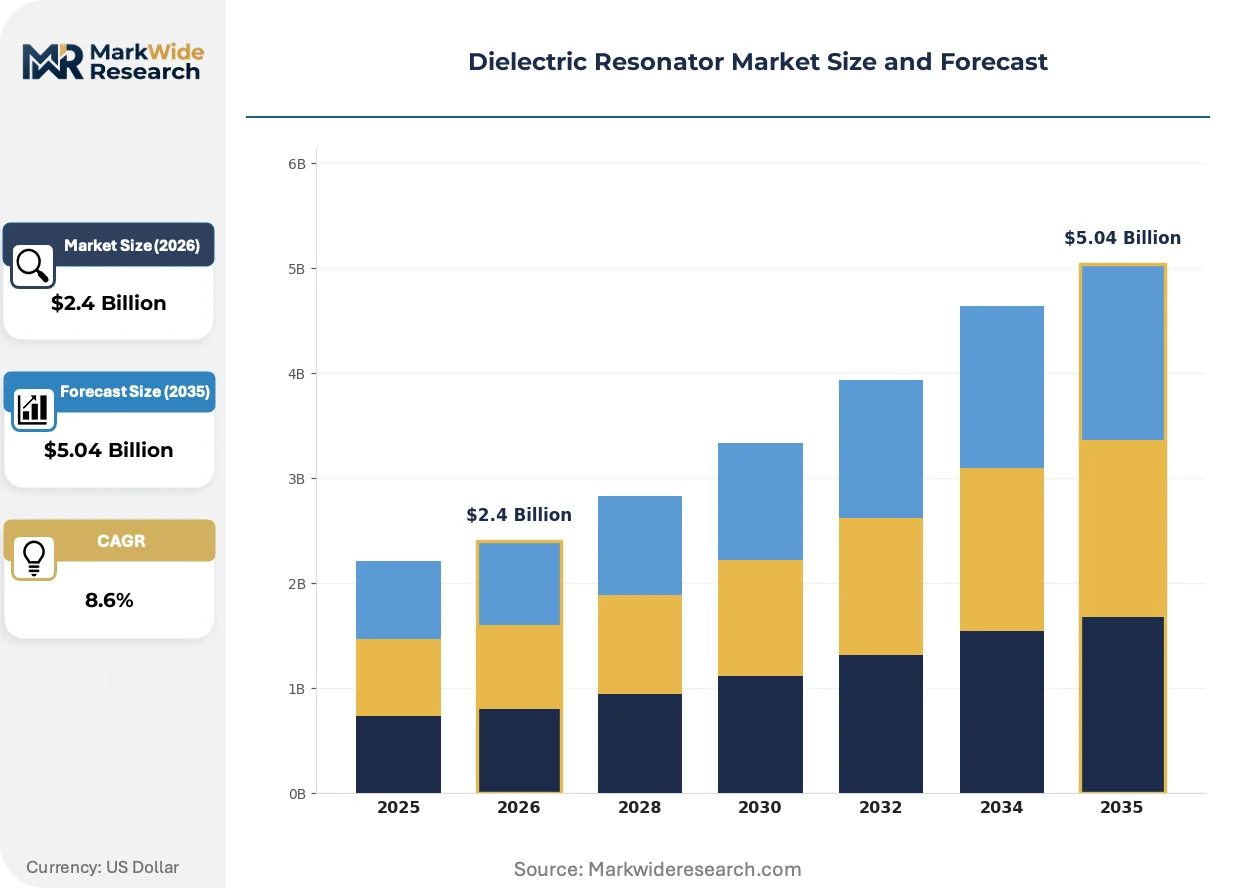
Market Dynamics
Defense procurement of high-Q dielectric resonators is accelerating faster than legacy consumer electronics demand, compressing supplier qualification timelines and reshaping capacity allocation across ceramic fabrication facilities.
Growth Catalysts
- 5G Base Station Deployment:Telecommunications infrastructure providers in South Korea are expanding procurement of microwave-grade resonators for millimeter-wave filter arrays. This demand concentrates manufacturing investment around the Suwon-Pyeongtaek corridor.
- REACH Compliance Adaptation:European ceramic formulators are reformulating lead-free glaze chemistries to satisfy ECHA substance restrictions. Qualified suppliers capture premium positioning in EU-sourced defense contracts.
- Quantum Readout Circuit Development:Cryogenic resonator specifications for superconducting qubit interfaces are redirecting R&D funding toward ultra-low-loss perovskite compositions. National quantum initiatives in multiple jurisdictions accelerate materials qualification.
Market Restraints
- Barium Titanate Supply Concentration:High-purity precursor synthesis capacity clusters in East Asian chemical processing hubs. Western resonator fabricators face input cost volatility and extended lead times for microwave-grade powders.
- ITAR Compliance Burden:US defense contracts require captive manufacturing cells with personnel screening and facility certification. Non-compliant suppliers forfeit access to prime contractor supply chains regardless of technical performance.
- Alumina Substitution Pressure:Synthetic sapphire resonators in select radar applications offer superior thermal shock resistance. Ceramic alternatives must demonstrate cost-performance parity to retain socket position.
Strategic Opportunities
- Software-Defined Radio Architectures:Tunable resonator designs enable frequency-agile military communications without hardware swaps. Integration with GaN power amplifiers creates system-level value capture for component suppliers.
- India WPC Frequency Liberalization:Revised spectrum allocation rules for commercial 5G deployment expand addressable bands for resonator manufacturers. Domestic production incentives under PLI schemes attract foreign joint ventures.
- Satellite Constellation Proliferation:ESA-certified heritage designs for space-qualified resonators command margin premiums. Exxelia's established qualification pathways create defensive moats against new entrants.
Industry Challenges
- Cryogenic Materials Engineering Talent Scarcity:Quantum computing resonator development requires physicists with superconducting circuit fabrication experience. Compensation inflation in this specialization strains mid-tier supplier R&D budgets.
- Dual-Use Export Control Navigation:Resonators meeting military Q-factor specifications trigger US State Department licensing requirements. Classification ambiguity delays commercial samples to civilian telecommunications developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dielectric Resonator Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.04 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Resonators, Tunable Resonators, Composite Resonators, Custom Resonators Application: Wireless Communication, Radar Systems, Satellite Communication, Signal Processing End User: Telecommunications, Aerospace, Defense, Consumer Electronics Technology: Microwave Technology, Optical Technology, Photonic Technology, Quantum Technology |
| Companies Covered | Murata Manufacturing, KYOCERA AVX Corporation, Exxelia, PARTRON, Tatfook, Maruwa, Token Electronics, MCV-Microwave, AVX Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dielectric Resonator Market Strategic Shifts
Dielectric resonator technology is bifurcating between established microwave applications and emerging quantum computing interfaces, with materials science investment tracking defense and quantum roadmaps more closely than consumer electronics cycles.
Perovskite-derived ceramic compositions with dielectric constants exceeding 80 are miniaturizing filter footprints for Ka-band satellite terminals. SpaceX and Amazon's Project Kuiper procurement teams specify these materials for phased-array feeds where volume constraints dominate thermal performance trade-offs. The technology is miniaturizing ground terminal dimensions while preserving insertion loss specifications that earlier alumina-based designs could not achieve at comparable scale.
China's GB standards for microwave components now mandate domestic electromagnetic compatibility testing protocols that foreign suppliers must replicate in-country. MIIT certification delays for imported resonators extend market entry timelines by six to twelve months relative to domestic competitors. European and Japanese manufacturers are responding through joint venture structures with licensed Chinese fabricators rather than direct export.
Defense prime contractors are consolidating resonator procurement under multi-year platform contracts that bundle filter, oscillator, and antenna feed requirements. This displaces the spot-market purchasing patterns that previously characterized commercial telecommunications procurement. The shift is most visible in North America, where Lockheed Martin and Raytheon negotiate directly with Murata and KYOCERA AVX for captive capacity allocation across fighter and missile programs.
Dielectric Resonator Market Segmentation
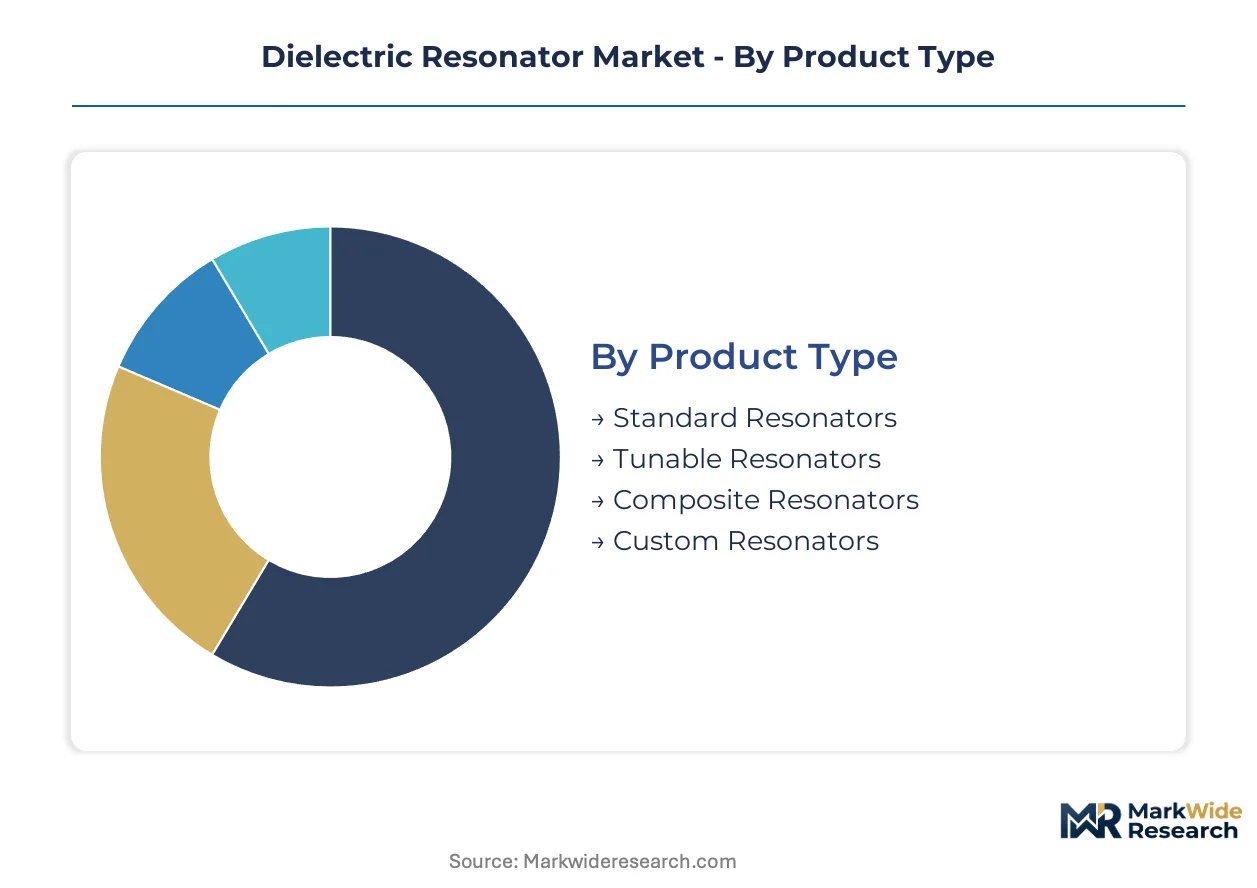
Dielectric resonator procurement patterns diverge sharply across product architectures, with defense contracts favoring custom specifications while telecommunications gravitates toward standardized volumes. Regulatory frameworks compound these splits—REACH compliance reshapes European ceramic formulations, while ITAR restrictions partition US defense supply chains from commercial channels.
Product Type:
REACH substance restrictions and FCC Part 15 emissions standards create divergent qualification burdens across resonator architectures, with European-sourced ceramics requiring lead-free glaze reformulation and US telecommunications components facing insertion loss verification.
- Standard Resonators:Fixed-frequency designs fabricated from barium titanate or alumina compositions serve cellular infrastructure with dielectric constants between 20 and 50. Procurement concentrates with South Korean telecommunications equipment manufacturers around the Suwon-Pyeongtaek manufacturing corridor, driven by 5G base station filter deployment timelines.
- Tunable Resonators:Frequency-agile architectures integrate with GaN power amplifiers for software-defined radio systems. Defense prime contractors in North America are consolidating multi-year platform contracts for these devices, displacing spot-market purchasing patterns that previously dominated commercial procurement.
- Composite Resonators:Multi-material stacks address aerospace multi-octave performance requirements.
- Custom Resonators:Application-specific geometries dominate space-qualified satellite payloads with ESA-certified heritage designs.
Standard resonators handle the majority of throughput; tunable resonators are climbing the fastest on share.
Application:
End-use concentration in millimeter-wave arrays and quantum readout circuits is reallocating manufacturing capacity away from legacy consumer electronics sockets.
- Wireless Communication:5G infrastructure deployment drives microwave-grade resonator demand for base station filter arrays. South Korea's telecommunications providers anchor procurement volumes, with manufacturing investment clustering around domestic RF component corridors to satisfy accelerated deployment schedules.
- Radar Systems:Synthetic sapphire alternatives threaten ceramic socket position in thermal shock-critical applications. Defense procurement specifications favor alumina-derived compositions where cost-performance parity can be demonstrated against crystalline competitors.
- Satellite Communication:Ka-band terminal miniaturization favors perovskite compositions with dielectric constants exceeding 80.
- Signal Processing:Photonic technology segments gain traction in advanced radar signal chains.
Wireless communication absorbs the dominant production share; satellite communication shows the steepest expansion trajectory.
End User:
Customer-type segmentation reveals a collapse in consumer electronics procurement relative to defense and aerospace qualification pathways.
- Telecommunications:Infrastructure providers specify microwave-grade resonators for millimeter-wave filter deployment. China's GB standards enforcement through MIIT certification delays conditions market access, favoring domestic fabricators or joint-venture structures over direct import.
- Aerospace:Space-qualified resonators command margin premiums through ESA-certified heritage designs. Exxelia's established qualification pathways create defensive positioning for satellite constellation proliferation contracts.
- Defense:ITAR-compliant manufacturing cells in California anchor North American prime contractor supply chains.
- Consumer Electronics:Legacy volume tiers face compression as procurement reallocates to higher-specification segments.
Telecommunications maintains volume leadership; defense procurement is expanding most quickly.
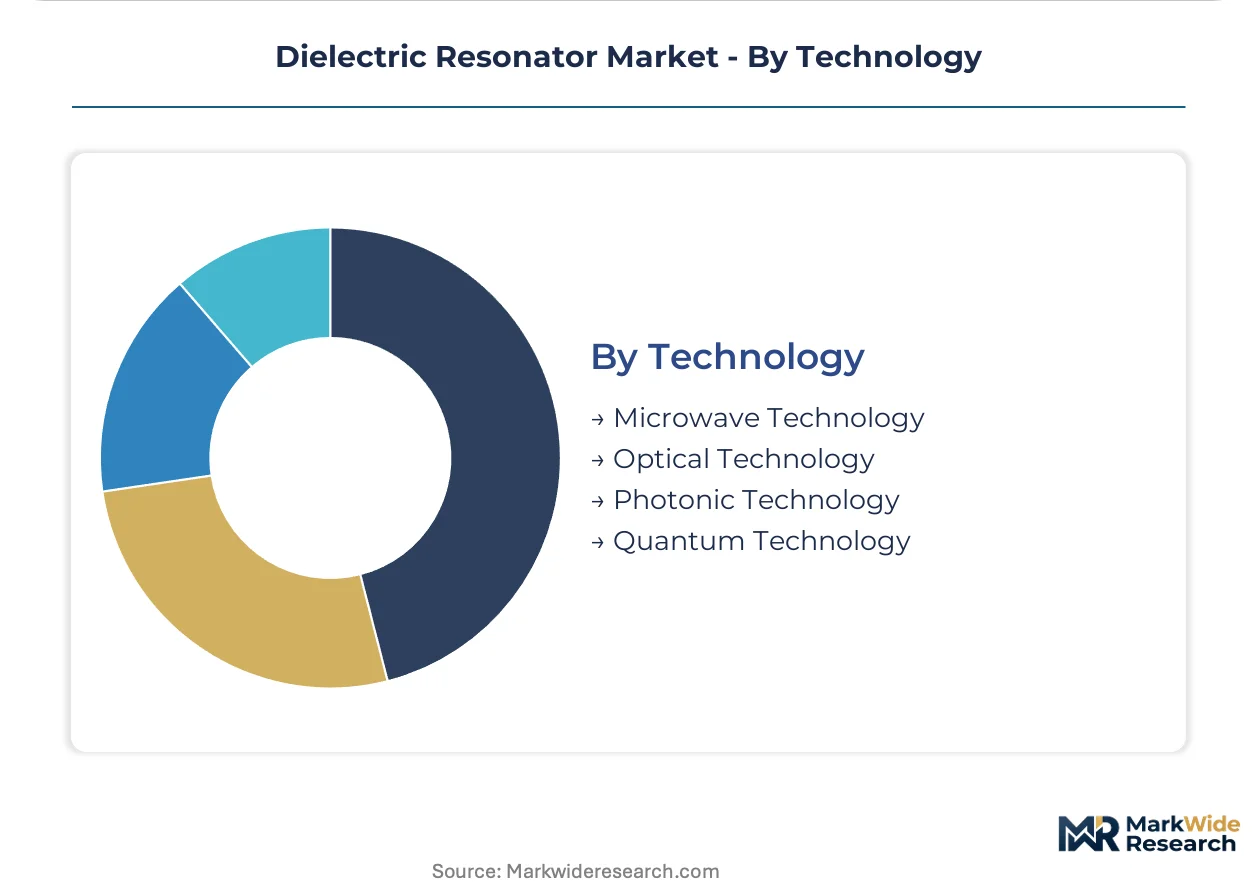
Technology:
Materials science investment tracks cryogenic and quantum roadmaps more closely than established microwave cycles, bifurcating R&D allocation.
- Microwave Technology:Standing-wave resonance architectures dominate unit shipments across wireless communication applications. Barium titanate supply concentration in East Asian chemical processing hubs creates input cost volatility for Western fabricators dependent on high-purity precursor synthesis.
- Photonic Technology:Radar signal processing chains increasingly specify these segments for advanced detection architectures. Integration with optical subsystems creates system-level value capture opportunities for component suppliers with multi-technology fabrication capabilities.
- Optical Technology:Specialized niches in precision instrumentation leverage low-loss crystalline substrates.
- Quantum Technology:Cryogenic resonator specifications for superconducting qubit interfaces redirect funding toward ultra-low-loss perovskite compositions.
Microwave technology retains dominant unit position; quantum technology is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese ceramic powder exports supply South Korean filter manufacturers, while Chinese domestic certification protocols redirect foreign supply toward joint-venture structures rather than direct import channels.
United States
Defense prime contractors consolidate multi-year platform contracts for millimeter-wave filter arrays. FCC Part 15 emissions standards enforce insertion loss verification for telecommunications equipment. ITAR-compliant manufacturing cells in California anchor North American supply chains for fighter and missile programs.
China
Domestic telecommunications infrastructure providers accelerate procurement of microwave-grade resonators for 5G base station deployment. MIIT certification through GB standards mandates in-country electromagnetic compatibility testing. The Yangtze River Delta hosts licensed joint-venture fabricators serving foreign manufacturers seeking market access.
South Korea
Telecommunications equipment manufacturers drive concentrated demand for millimeter-wave filter components. The country's spectrum regulator shapes commercial 5G deployment bands permitted for resonator center frequencies. Manufacturing investment clusters around the Suwon-Pyeongtaek RF component corridor to satisfy accelerated infrastructure timelines.
Germany
Aerospace buyers specify multi-octave performance requirements for satellite payload applications. ECHA REACH substance restrictions compel lead-free glaze reformulation in European-sourced ceramics. Bavaria-based formulators capture premium positioning in EU defense contracts through qualified material pathways.
Japan
Precursor chemical synthesis for barium titanate compositions concentrates in domestic processing hubs. METI industrial standards coordinate microwave component specifications across telecommunications and defense applications. Ceramic powder suppliers in the Nagoya industrial zone export high-purity formulations to resonator fabricators across Asia-Pacific.
Dielectric Resonator Market Competitive Environment
Listed leaders compete with private specialists across defense qualification pathways, creating tiered supply structures where ITAR compliance and ESA heritage certification separate premium sockets from commercial volume tiers. The vendor base concentrates around captive ceramic synthesis capabilities and multi-year platform contracting relationships. Three archetypes dominate: integrated material-to-component fabricators, defense-specialized qualification holders, and telecommunications-focused volume suppliers. Competitive moves center on backward integration into precursor chemical production and strategic partnerships with GaN amplifier manufacturers for software-defined radio system integration.
Among Japanese fabricators, Murata Manufacturing exemplifies the integrated material-to-component archetype through captive ceramic powder synthesis. KYOCERA AVX Corporation occupies a position bridging commercial telecommunications and ITAR-compliant defense supply chains. Exxelia represents the heritage-qualified specialist tier, anchoring ESA-certified pathways for space payload applications.
| Leading Market Players |
|---|
| Murata Manufacturing |
| KYOCERA AVX Corporation |
| Exxelia |
| PARTRON |
| Tatfook |
| Maruwa |
| Token Electronics |
| MCV-Microwave |
| AVX Corporation |
| Others |
Value Chain & Pricing Dynamics
Twelve-week lead times for microwave-grade barium titanate powders concentrate pricing power with Japanese precursor suppliers, while defense contractors absorb premium markups through multi-year platform contracts that lock capacity ahead of spot-market volatility.
Pricing Analysis
Millimeter-wave resonators for Ka-band satellite terminals command 40-60% premiums over legacy L-band designs, while quantum-grade cryogenic specifications widen the gap further through materials purity thresholds. Three-tier pricing structure across ITAR-certified defense, ESA-qualified space, and commercial telecommunications tiers separates buyers by qualification burden rather than unit volume alone. Cost compression in standard cellular infrastructure resonators stems from South Korean equipment manufacturers consolidating procurement under annual framework agreements. Telecommunications infrastructure providers exhibit highest price sensitivity, whereas aerospace prime contractors prioritize heritage certification over unit cost.
Supply Chain Analysis
Japan and China anchor high-purity barium titanate precursor synthesis, with South Korean chemical processors dependent on imported feedstock for resonator fabrication. Ceramic powder supply draws from Nagoya industrial zone exporters, Yangtze River Delta domestic producers, and licensed joint-venture structures circumventing MIIT certification delays. Single-source vulnerability concentrates in ITAR-compliant manufacturing cells, where personnel screening and facility certification create non-replicable capacity. Distribution runs through defense prime contractor direct procurement, telecommunications equipment OEM consolidated buying, and satellite constellation developer heritage-qualified supplier lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect around software-defined radio architectures, where resonator-amplifier interoperability creates system-level value capture opportunities beyond component-level supply.
For Market Incumbents: Compound captive ceramic synthesis advantages through backward integration into perovskite precursor production, defending against synthetic sapphire substitution in radar thermal-shock applications. Expand ITAR-compliant California manufacturing cells to capture Lockheed Martin and Raytheon multi-year platform contract consolidation. For New Entrants and Emerging Players: Lead with tunable resonator designs for India's WPC-liberalized 5G bands, exploiting PLI scheme production incentives and underpenetrated domestic fabrication capacity. Target joint-venture structures with licensed Chinese fabricators as the fastest path through MIIT GB standards certification. For Investors and Strategic Acquirers: Carve-out targets emerge from defense prime contractor captive component divisions, where ESA heritage certification and cryogenic materials engineering talent create defensible moats. Watch quantum computing roadmaps for superconducting qubit interface specifications as the inflection signal redirecting R&D funding from conventional microwave designs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Synthesis | Murata Manufacturing's captive ceramic powder production anchors premium resonator margins against barium titanate supply volatility. |
| ITAR Manufacturing Cell Certification | KYOCERA AVX Corporation's California facilities secure North American defense contracts through personnel-screened captive capacity. |
| ESA Heritage Design Qualification | Exxelia's established satellite payload pathways command margin premiums for SpaceX and Amazon Project Kuiper procurement teams. |
| Joint Venture Licensing for China Access | European and Japanese manufacturers bypass MIIT certification delays through Yangtze River Delta licensed fabricator partnerships. |
| GaN Amplifier System Integration | Tunable resonator suppliers capture software-defined radio value through frequency-agile military communications bundling. |
Study Parameters
A spread of perspectives from RF component procurement managers, defense prime contractor supply chain directors, ceramic materials R&D leads, and satellite payload systems engineers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through FCC Part 15 filings, ECHA REACH substance restriction updates, MIIT GB standards documentation, and customs trade data for barium titanate precursor flows. Bottom-up resonator shipment estimates triangulated against top-down telecommunications infrastructure capex allocations across the analysis window.
Segmentation dimensions modeled include resonator architecture type, application end-use, end-user industry category, and technology platform across the projection horizon. CAGRs derived from curve-fitting historical procurement patterns against disclosed 5G base station deployment schedules, satellite constellation launch manifests, and national quantum initiative funding trajectories. Forecast inputs incorporated South Korean spectrum regulator band allocations, ESA satellite payload qualification timelines, and cryogenic materials engineering compensation inflation indices.
Forecasts assume regulatory continuity in FCC emissions standards, ECHA REACH substance restrictions, and MIIT GB certification protocols; material policy shifts would require re-modeling. Specific risks include barium titanate export restriction escalation, ITAR compliance burden expansion, and quantum computing roadmap acceleration diverting R&D funding. Recalibration cycles align with material shifts in defense procurement consolidation patterns, telecommunications infrastructure deployment cadence, and satellite constellation launch rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
RF Tester Market
RF Components
High Power RF Amplifier Module Market
RF Components
Microwave Devices Market
RF Components
RF Switches Market
RF Components
US RFID Tags Market
RF Components
Toroid Inductor Market
RF Components
RFID Antenna Market
RF Components
RF Duplexer Market
RF Components
RF Transceiver Chip Market
RF Components
Smartphone RF Power Amplifier Market
RF Components
High Reliability Oscillators Market
RF Components
High-Power Microwave Source Market
RF Components
Digital Radio Frequency Market
RF Components
Global Inductors Market
RF Components
Global Ceramic Dielectric Filters Market
RF Components
Radio Frequency Front End Module Market