
 Digital Phase Shifter Market | 2026-2036
Digital Phase Shifter Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Phase Shifter Market Analysis
Software-defined calibration and remote firmware update services is decoupling hardware sales from long-term revenue streams in the digital phase shifter value chain. MACOM Technology Solutions leverages its compound semiconductor foundry to anchor high-frequency product lines for defense prime contractors. Texas Instruments Incorporated sustains broad portfolio breadth across industrial and automotive radar segments through integrated DSP-plus-phase-shifter silicon. Analog Devices, Inc. competes on converter-density leadership, pairing precision data converters with phase control in single packages for beamforming architectures.
A digital phase shifter is a solid-state device that imposes a precisely controlled phase delay on an RF signal, typically employing PIN diodes, FET switches, or MEMS elements to achieve 360-degree coverage with resolution steps of 5.625 degrees or finer for phased array steering. Its primary commercial purpose is enabling electronic beam steering without mechanical gimbals, reducing latency and maintenance burden in radar, 5G base stations, and satellite communications terminals. Integrated Circuits now capture the dominant margin pool as system-in-package integration replaces discrete module assemblies in volume applications. Digital Signal Processing technology is displacing analog-only architectures in telecommunications infrastructure, where baseband-to-RF digitization simplifies calibration and enables real-time adaptive beamforming algorithms.
FCC spectrum allocation rulings and EU Radio Equipment Directive compliance requirements shape product certification pathways for millimeter-wave phase shifter modules entering North American and European markets. Military procurement through the US Defense Logistics Agency and alignment with MIL-STD-883 testing protocols gate access to aerospace and defense revenue pools. Stakeholders must monitor gallium nitride-on-silicon process yields and foundry capacity commitments as these determine which suppliers can meet cost targets for commercial 5G massive MIMO deployment at scale.
Market Dynamics
Gallium nitride foundry capacity allocation is compressing supplier lead times for millimeter-wave phase shifter modules while NATO radar modernization programs concentrate demand among defense prime contractors with captive compound semiconductor access.
Growth Catalysts
- EU Radio Equipment Directive:Compliance mandates for millimeter-wave modules accelerate certification investment by European telecommunications equipment vendors seeking 5G massive MIMO deployment approvals.
- Electronically scanned arrays:Military radar procurement across NATO members is driving PIN diode and FET switch phase shifter volumes for next-generation airborne and naval platforms.
- Gallium nitride-on-silicon:Process yield improvements at compound semiconductor foundries are extending operating frequencies into Ka-band and E-band for satellite communications terminals.
Market Restraints
- Foundry concentration:Taiwan-based compound semiconductor fabrication accounts for the majority of GaN-on-SiC wafer supply, creating geographic single-point vulnerability for defense-qualified phase shifter production.
- Gold wire bonding costs:Precious metal input volatility affects final module pricing for hermetic packaging in aerospace applications requiring MIL-STD-883 qualification.
- MEMS reliability limitations:Microelectromechanical phase shifters face cycle-life constraints in high-shock military environments, restricting adoption in munitions guidance systems.
Strategic Opportunities
- Software-defined radio unification:Cognitive electronic warfare platforms in the United States are converging beamforming and signal processing functions, opening single-package phase-shifter-plus-DSP integration opportunities.
- Automotive radar tiering:4D imaging radar adoption by German and Japanese vehicle manufacturers is creating demand for 77-81 GHz phase shifter arrays with sub-degree resolution.
- FCC millimeter-wave allocation:Spectrum rulings for fixed wireless access in the United States are licensing new frequency blocks requiring native mmWave phase shifter designs for CPE and base station equipment.
Industry Challenges
- Calibration engineer scarcity:Phase array test and alignment expertise concentrates among defense contractors, limiting commercial 5G infrastructure vendors' ability to scale beamforming system production.
- Legacy analog integration:Hybrid architectures combining digital phase shifters with existing analog beamforming networks require custom firmware development, extending program timelines for satellite ground terminal retrofits.
- Environmental qualification backlog:MIL-STD-883 test facility capacity constraints delay aerospace product introductions by 8-14 months for suppliers without captive qualification laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Phase Shifter Market |
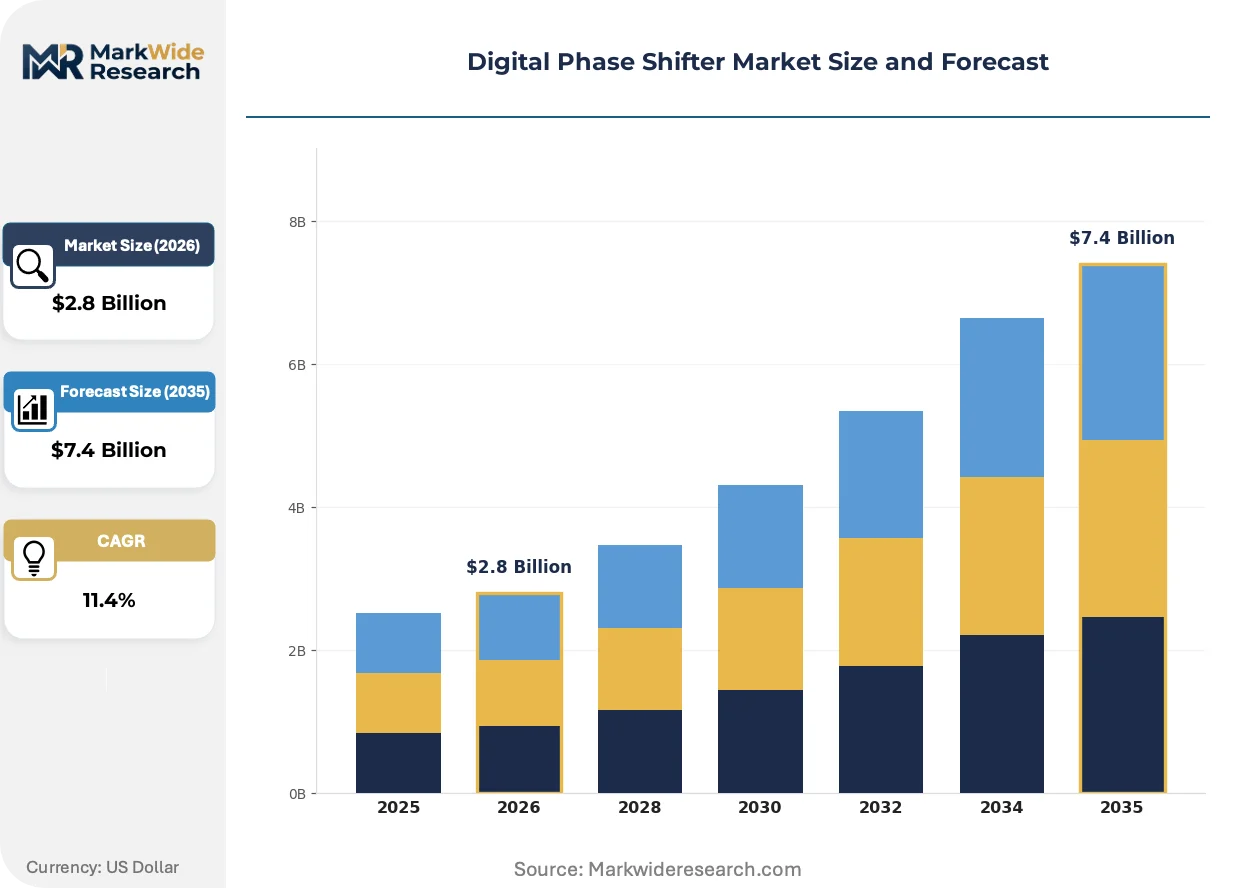
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vector Modulators, Integrated Circuits, RF Components, Control Systems Technology: Analog Signal Processing, Digital Signal Processing, Optical Techniques, Hybrid Systems End User: Telecommunications, Aerospace, Military, Automotive Application: Beamforming, Signal Conditioning, Data Communication, Electronic Warfare |
| Companies Covered | MACOM Technology Solutions, Texas Instruments Incorporated, Analog Devices, Inc., Mercury Systems, Inc., NXP Semiconductors N.V., Qorvo, Inc., pSemi Corporation, Planar Monolithics Industries, Inc., Keysight Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Phase Shifter Market Emerging Trajectories
System-in-package integration is collapsing the traditional boundary between discrete phase control elements and baseband processing, while regulatory pressure on spectrum efficiency accelerates native digital beamforming adoption.
Silicon-germanium BiCMOS phase shifter cores are modularizing RF front-end architectures for sub-6 GHz massive MIMO radios. Base station OEMs in South Korea and the United States are adopting these integrated designs to reduce bill-of-materials complexity. The technology is modularizing supplier relationships, enabling fabless semiconductor firms to capture margin previously held by discrete module assemblers.
REACH substance restrictions on lead-based solders and hexavalent chromium coatings are forcing packaging redesigns for European market access. Phase shifter module suppliers must qualify alternative metallization and underfill materials without degrading hermeticity or thermal performance. Aerospace and defense product lines face the steepest compliance cost escalation due to dual-use export classification requirements.
Defense procurement through the US Defense Logistics Agency is consolidating vendor qualification lists, compressing the effective supply base for military-grade phase shifters. Prime contractors are responding by awarding multi-year sole-source agreements to compound semiconductor foundries with existing MIL-PRF-38534 certification. This concentration is most visible in electronically scanned array programs for fighter aircraft and naval surface combatants, where security-cleared manufacturing lines constitute a de facto barrier to new entrants.
Digital Phase Shifter Market Segmentation
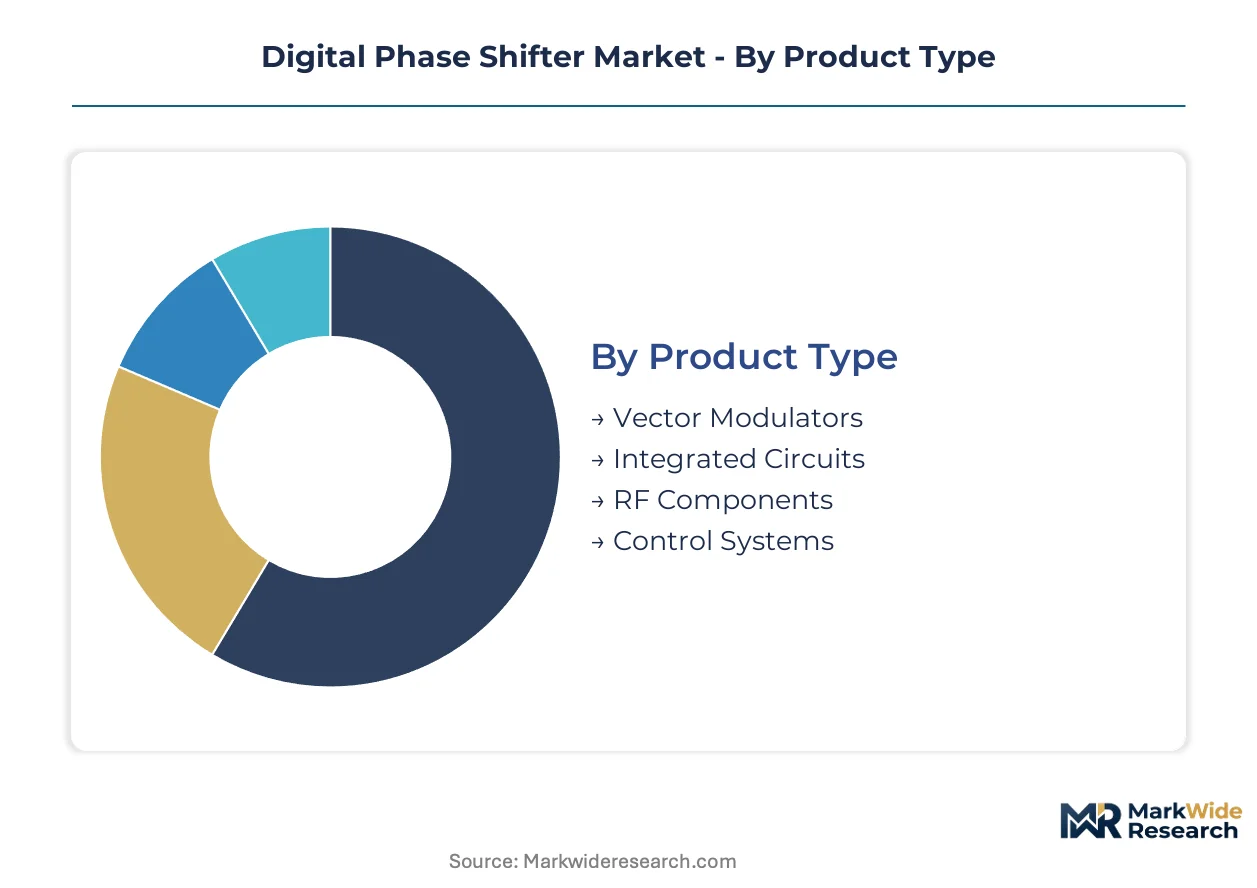
Digital phase shifter procurement patterns diverge sharply across certification regimes. MIL-STD-883 qualification gates defense revenue pools, while FCC Part 15 and EU Radio Equipment Directive compliance shape commercial 5G and automotive supplier selection.
Product Type:
MIL-STD-883 testing protocols and REACH substance restrictions on lead-based solders impose divergent compliance burdens across product categories, with aerospace modules facing the steepest qualification cost escalation.
- Integrated Circuits:System-in-package designs collapse discrete phase control and baseband processing into single silicon. South Korean and United States base station OEMs adopt these for sub-6 GHz massive MIMO radios to reduce bill-of-materials complexity. FCC spectrum allocation rulings for fixed wireless access are accelerating native mmWave IC designs for customer premises equipment.
- Vector Modulators:These devices impose amplitude and phase control simultaneously through quadrature modulation architectures. NATO radar modernization programs concentrate demand among defense prime contractors with captive compound semiconductor foundry access. EU Radio Equipment Directive compliance mandates are accelerating certification investment by European telecommunications vendors.
- RF Components:Discrete PIN diode and FET switch assemblies for legacy platform retrofits.
- Control Systems:Software-defined calibration modules enabling remote firmware updates and real-time adaptive beamforming.
Leading the category by volume: Integrated Circuits. Growing fastest: Vector Modulators.
Technology:
Cost tiering separates legacy analog architectures from premium native digital designs, with hybrid systems occupying an intermediate pricing band requiring custom firmware development.
- Digital Signal Processing:Native digitization from baseband to RF enables real-time adaptive beamforming algorithms. United States Department of Defense prioritization of software-defined radio and cognitive electronic warfare platforms is converging beamforming and signal processing functions. DSP-based architectures simplify calibration compared to analog-only alternatives.
- Analog Signal Processing:Conventional PIN diode and FET switch implementations dominate legacy military radar retrofits where program offices specify proven reliability records. Gold wire bonding costs and precious metal input volatility affect final module pricing for hermetic packaging in aerospace applications.
- Hybrid Systems:Combining digital phase shifters with existing analog beamforming networks extends program timelines for satellite ground terminal retrofits.
- Optical Techniques:Photonic phase control for specialized satellite communications and electronic warfare applications requiring immunity to electromagnetic interference.
Highest margin concentration: Digital Signal Processing. Steepest volume decline: Analog Signal Processing.
End User:
Application maturity varies dramatically, with telecommunications infrastructure representing established volume demand while automotive radar tiering creates emerging specification requirements.
- Telecommunications:5G massive MIMO deployment drives volume demand for millimeter-wave phase shifter modules. South Korean and United States base station OEMs are adopting silicon-germanium BiCMOS integrated designs. REACH substance restrictions on hexavalent chromium coatings are forcing packaging redesigns for European market access.
- Military:Electronically scanned array programs for fighter aircraft and naval surface combatants consolidate procurement through the US Defense Logistics Agency. Security-cleared manufacturing lines constitute a de facto barrier to new entrants. Taiwan-based compound semiconductor fabrication concentration creates geographic single-point vulnerability for defense-qualified production.
- Aerospace:Satellite communications terminals requiring Ka-band and E-band operation.
- Automotive:4D imaging radar adoption by German and Japanese vehicle manufacturers creates demand for 77-81 GHz arrays with sub-degree resolution.
Deepest supply concentration: Military. Expanding most quickly: Automotive.
Application:
Customer type differentiation separates defense prime contractors with captive qualification laboratories from commercial infrastructure vendors facing calibration engineer scarcity.
- Beamforming:Electronic steering without mechanical gimbals reduces latency and maintenance burden across radar, 5G base stations, and satellite terminals. Gallium nitride-on-silicon process yield improvements at compound semiconductor foundries are extending operating frequencies into millimeter-wave bands. MIL-STD-883 test facility capacity constraints delay aerospace product introductions by 8-14 months for suppliers without captive laboratories.
- Electronic Warfare:Cognitive electronic warfare platforms in the United States are converging beamforming and signal processing functions, opening single-package phase-shifter-plus-DSP integration opportunities. Security classification requirements limit vendor participation.
- Signal Conditioning:Precision phase alignment for test and measurement instrumentation.
- Data Communication:Modulation and demodulation functions in high-throughput backhaul links.
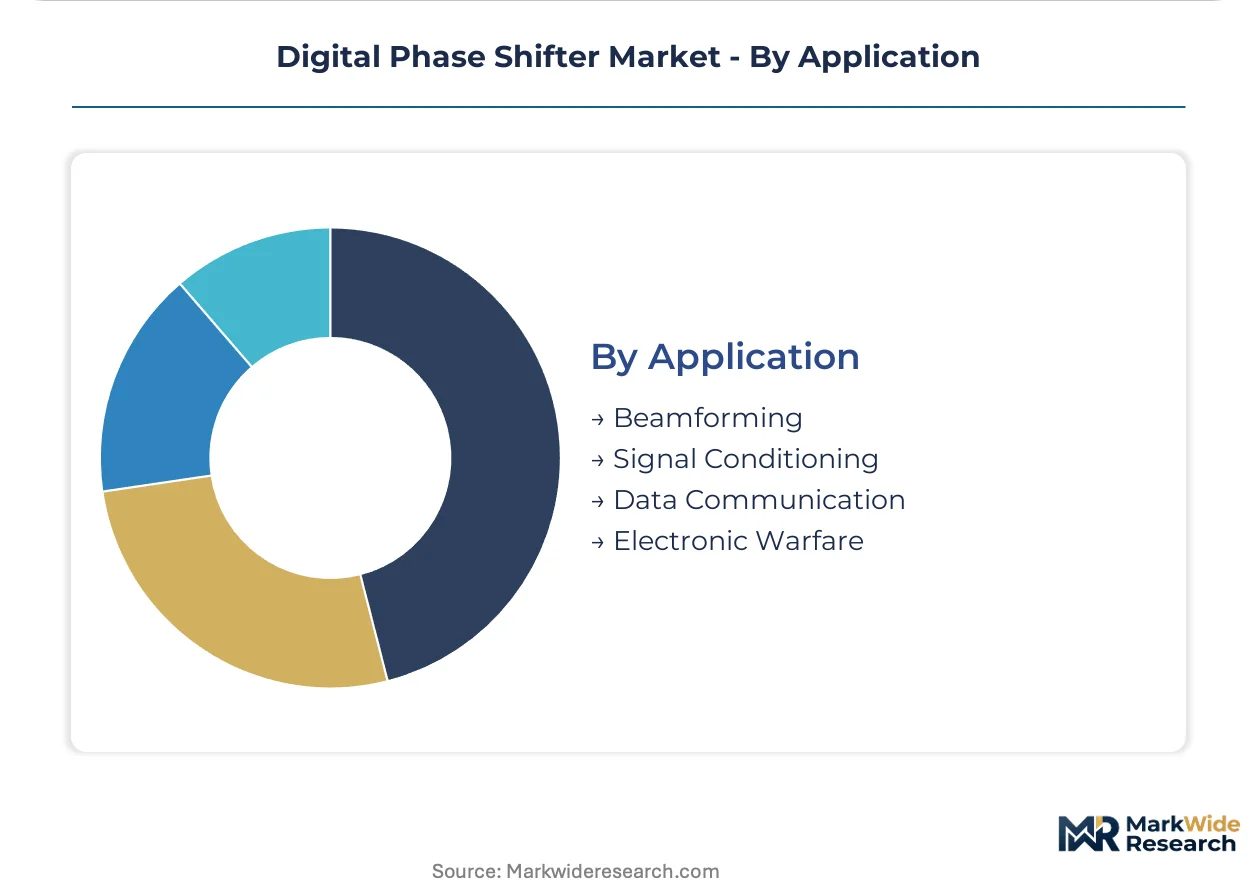
Revenue concentration: Beamforming. Gaining share fastest: Electronic Warfare.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compound semiconductor fabrication concentrates in Taiwan and the United States, while consumption splits between NATO defense procurement and East Asian telecommunications infrastructure deployment.
United States
The Department of Defense prioritizes software-defined radio and cognitive electronic warfare platforms, concentrating demand among defense prime contractors with captive qualification laboratories. FCC spectrum allocation rulings for fixed wireless access license new millimeter-wave frequency blocks requiring native designs. The Boston-Cambridge corridor hosts beamforming algorithm development clusters serving both military and commercial 5G applications.
Germany
German and Japanese vehicle manufacturers drive 4D imaging radar adoption, creating specification requirements for 77-81 GHz arrays with sub-degree resolution. EU Radio Equipment Directive compliance mandates accelerate certification investment by European telecommunications equipment vendors. The Stuttgart-Karlsruhe region anchors automotive radar tiering development for premium vehicle platforms.
South Korea
Base station OEMs adopt silicon-germanium BiCMOS integrated designs to reduce bill-of-materials complexity in sub-6 GHz massive MIMO radios. The country's national telecommunications regulator shapes spectrum efficiency requirements for millimeter-wave deployment. Seoul Capital Area concentration enables rapid prototyping partnerships between semiconductor foundries and telecommunications equipment vendors.
Japan
METI industrial policy supports compound semiconductor process yield improvements extending operating frequencies into Ka-band and E-band for satellite communications terminals. Domestic radar modernization programs concentrate procurement among established defense electronics suppliers. The Nagoya-Tokyo corridor maintains precision manufacturing capabilities for hermetic packaging in aerospace applications.
Taiwan
Compound semiconductor foundries supply the majority of GaN-on-SiC wafer production for millimeter-wave phase shifter modules, creating geographic single-point vulnerability for defense-qualified output. Foundry capacity allocation compresses supplier lead times across NATO radar programs. Hsinchu Science Park anchors gallium nitride-on-silicon process development serving both commercial 5G and aerospace demand pools.
Digital Phase Shifter Market Vendor Landscape
Top-tier vendors anchor defense-qualified compound semiconductor production, while mid-tier fabless specialists capture commercial 5G infrastructure margin through system-in-package integration. The vendor base stratifies across three archetypes: captive foundry operators with MIL-PRF-38534 certification, diversified semiconductor conglomerates with broad portfolio breadth, and RF component specialists focused on discrete module assemblies. Dominant competitive moves include multi-year sole-source agreements between prime contractors and security-cleared manufacturing lines, plus backward integration into gallium nitride foundry capacity.
Within the defense-qualified tier, MACOM Technology Solutions and Mercury Systems, Inc. exemplify compound semiconductor foundry anchoring for high-frequency product lines. Texas Instruments Incorporated occupies a position representing diversified portfolio breadth across industrial and automotive radar segments. These three entities illustrate how supplier selection concentrates among vendors with existing security clearances and captive qualification laboratories for electronically scanned array programs.
| Leading Market Players |
|---|
| MACOM Technology Solutions |
| Texas Instruments Incorporated |
| Analog Devices, Inc. |
| Mercury Systems, Inc. |
| NXP Semiconductors N.V. |
| Qorvo, Inc. |
| pSemi Corporation |
| Planar Monolithics Industries, Inc. |
| Keysight Technologies, Inc. |
| Others |
Supply Flow & Price Mechanics
Defense prime contractors with captive compound semiconductor foundries command premium pricing power through MIL-PRF-38534 certification scarcity, while commercial 5G infrastructure vendors face commoditization pressure from silicon-germanium BiCMOS integration.
Pricing Analysis
Margin tightening in aerospace-grade modules reflects gold wire bonding cost volatility and precious metal input exposure. Three-tier pricing structure across MIL-STD-883 qualified, industrial-grade, and commercial-off-the-shelf levels separates defense procurement from automotive radar tiering. Cost-down pressure on sub-6 GHz massive MIMO radios accelerates because South Korean base station OEMs consolidate supplier lists. Telecommunications infrastructure vendors exhibit highest price sensitivity; military programs with sole-source agreements show lowest.
Supply Chain Analysis
Dual-sourcing mandates from NATO radar program offices force defense prime contractors to qualify secondary gallium nitride foundries beyond Taiwan. Supply concentrates in Taiwan, the United States, and Japan for GaN-on-SiC wafer fabrication. Raw material dependencies span high-purity gallium substrates, silicon carbide wafers, and gold bonding wire. Single-source vulnerability concentrates in Taiwan-based compound semiconductor capacity. Distribution runs through defense logistics agency procurement channels and direct OEM contracts for commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital phase shifter market rewards backward integration into gallium nitride foundry capacity as the decisive upstream lever, with defense contractors securing multi-year sole-source agreements and commercial players racing for silicon-germanium BiCMOS process access.
For Market Incumbents: Lock in gallium nitride-on-silicon process yields through captive foundry investments or multi-year capacity reservations at Taiwan-based suppliers. Secure MIL-STD-883 test facility capacity to circumvent 8-14 month qualification backlogs threatening aerospace product introductions. Defend against fabless semiconductor firms by accelerating system-in-package integration roadmaps that collapse discrete module margins. For New Entrants and Emerging Players: Enter via automotive radar tiering for 4D imaging systems at 77-81 GHz, where German and Japanese vehicle manufacturers seek sub-degree resolution alternatives to established suppliers. Target software-defined calibration modules enabling remote firmware updates, decoupling hardware sales from recurring revenue streams. Pursue fabless silicon-germanium BiCMOS designs for sub-6 GHz massive MIMO radios to bypass gallium nitride foundry bottlenecks. For Investors and Strategic Acquirers: The window for entry favors compound semiconductor foundries with existing MIL-PRF-38534 certification and security-cleared manufacturing lines. Long-term viability hinges on dual-use technology positioning spanning defense and commercial telecommunications demand pools. Watch gallium nitride-on-silicon process yield improvements at Taiwan foundries as the inflection signal determining which suppliers can meet cost targets for commercial 5G deployment at scale.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into GaN Foundry Capacity | Captive supply of millimeter-wave wafers secures defense procurement eligibility under MIL-PRF-38534. |
| System-in-Package Integration | Collapsing phase control and baseband processing displaces discrete module assemblers in 5G radios. |
| MIL-STD-883 Test Facility Expansion | Captive qualification laboratories circumvent 8-14 month environmental testing backlogs for aerospace. |
| Silicon-Germanium BiCMOS Modularization | Sub-6 GHz massive MIMO adoption by South Korean OEMs reduces bill-of-materials complexity. |
| Software-Defined Calibration Services | Remote firmware update capabilities decouple hardware sales from recurring revenue streams. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with defense procurement officers at prime contractors, compound semiconductor foundry operations directors, telecommunications equipment vendor supply chain managers, and automotive radar platform engineers informed demand-side validation. FCC spectrum allocation rulings, EU Radio Equipment Directive compliance databases, and US Defense Logistics Agency contract awards supplemented bottom-up modeling. Top-down triangulation cross-checked against gallium nitride wafer production estimates and phased array radar program announcements.
Reconciliation of shipment data, foundry capacity utilization, and procurement contract values established the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology architecture, end-user vertical, and application function. CAGRs derived from curve-fitting historical defense procurement cycles and telecommunications infrastructure deployment waves. Industry-specific forecast inputs incorporated gallium nitride-on-silicon process yield trajectories and REACH substance restriction compliance cost escalations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Taiwan semiconductor fabrication disruption scenarios. Deviation in NATO radar modernization program funding levels or FCC millimeter-wave spectrum reallocation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
High Reliability Oscillators Market
RF Components
Radio Frequency Front End Market
RF Components
Asia-Pacific Small Signal Transistor Market
RF Components
Global Gan RF Devices Market
RF Components
High-Frequency RF Evaluation Board Market
RF Components
Multiband Booster Market
RF Components
Flat Antenna Market
RF Components
EMI Microwave Absorber Market
RF Components
RF Antenna Market
RF Components
RF Components Market
RF Components
Smart Antenna Market
RF Components
Coaxial Splitters Market
RF Components
High-Volume RF Front-End Module Test Systems Market
RF Components
RF-Microwave for 5G Market
RF Components
Latin America RFID Tags Market
RF Components
RF and Microwave Diodes Market