
 Phase Shifters Market | 2026-2036
Phase Shifters Market Size, Share, and Industry Trends Forecast 2026-2036
Phase Shifters Market Analytics
Southeast Asia is rewriting the manufacturing map for passive RF components as Vietnam and Thailand attract backend assembly investment from tier-one suppliers. Analog Devices leverages its GaN-on-SiC foundry partnerships to sustain process leadership in high-power phase shifter modules. Qorvo anchors its position through captive GaAs HBT capacity and direct sales to prime defense contractors. MACOM Technology Solutions competes aggressively on price-performance in commercial 5G massive MIMO deployments.
A phase shifter is a two-port network that introduces a controlled, frequency-dependent phase delay to an electromagnetic signal, typically implemented using switched filter banks, varactor-tuned transmission lines, or ferrite-based waveguide structures operating from MHz through millimeter-wave bands. Its primary purpose is to steer beam direction in phased array antennas without mechanical movement, enabling electronic scanning in radar and communications systems. Digital phase shifters lead volume shipments in defense radar applications where discrete phase states and radiation hardness prove essential. Analog phase shifters capture margin pools in telecommunications infrastructure demanding continuous phase adjustment for beamforming optimization. Microwave technology dominates the installed base, though integrated circuit technology is displacing discrete implementations in automotive radar modules below 79 GHz.
The U.S. Department of Defense's MIL-STD-461 and MIL-STD-464 electromagnetic compatibility requirements shape product qualification timelines and testing costs for suppliers serving defense applications. FCC Part 15 and Part 27 rules for unlicensed and licensed radio operations constrain transmit power and spurious emissions profiles in commercial wireless deployments, directly influencing phase shifter linearity specifications. Stakeholders must monitor how IEEE 802.11ay and 3GPP Release 18 beam management protocols redefine phase resolution and switching speed requirements across next-generation infrastructure tenders.
Market Dynamics
The transition from mechanically steered antennas to electronically scanned arrays is compressing refresh cycles across defense procurement programs, forcing suppliers to recalibrate qualification timelines and foundry partnerships around radiation-hardened digital architectures.
Growth Catalysts
- MIL-STD-461/464 compliance mandates:U.S. Department of Defense electromagnetic compatibility requirements lock in multi-year procurement contracts for qualified phase shifter suppliers, creating predictable revenue basins.
- 5G massive MIMO infrastructure buildouts:Telecommunications carriers in South Korea and Japan are deploying hybrid beamforming architectures that consume high volumes of analog phase shifter modules.
- GaN-on-SiC process maturation:Wide-bandgap semiconductor foundries are extending power-handling thresholds for X-band and Ku-band radar transmit chains, opening new frequency bands to solid-state phase shifting.
Market Restraints
- GaAs substrate supply concentration:Six-inch gallium arsenide wafer production clusters in Taiwan and Germany create chokepoint vulnerability for legacy analog phase shifter lines.
- Radiation hardness qualification costs:Space-qualified phase shifter modules require extended total ionizing dose testing under ESA ECSS-Q-ST-60-02C, stretching development timelines to 36-48 months.
- MEMS switch reliability thresholds:Micro-electromechanical phase shifters face insertion loss degradation after 10 billion switching cycles, limiting their displacement of PIN diode alternatives in high-duty-cycle radar.
Strategic Opportunities
- Automotive radar at 60-64 GHz:European OEMs are qualifying compact phase shifter ICs for imaging radar front ends ahead of UN ECE R79 autonomous driving mandates.
- Terahertz test and measurement:6G research programs in Finland and Singapore are creating pilot demand for sub-millimeter-wave phase shifters with sub-degree resolution.
- India's defense indigenization:The country's Defense Acquisition Procedure 2020 prioritizes domestic sourcing for phased array subsystems, inviting joint ventures with foreign GaN foundry operators.
Industry Challenges
- Electromagnetic interference modeling talent:Finite-element simulation expertise for full-wave analysis of phased array mutual coupling effects remains concentrated among a narrow cohort of defense contractors and national laboratories.
- Multi-physics co-design complexity:Thermal-mechanical-electrical tradeoffs in compact transmit-receive modules require iterative prototyping cycles that strain capital equipment budgets.
- Legacy radar retrofit integration:New phase shifter architectures must interface with existing waveguide manifolds and power distribution networks designed for ferrite-based systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phase Shifters Market |
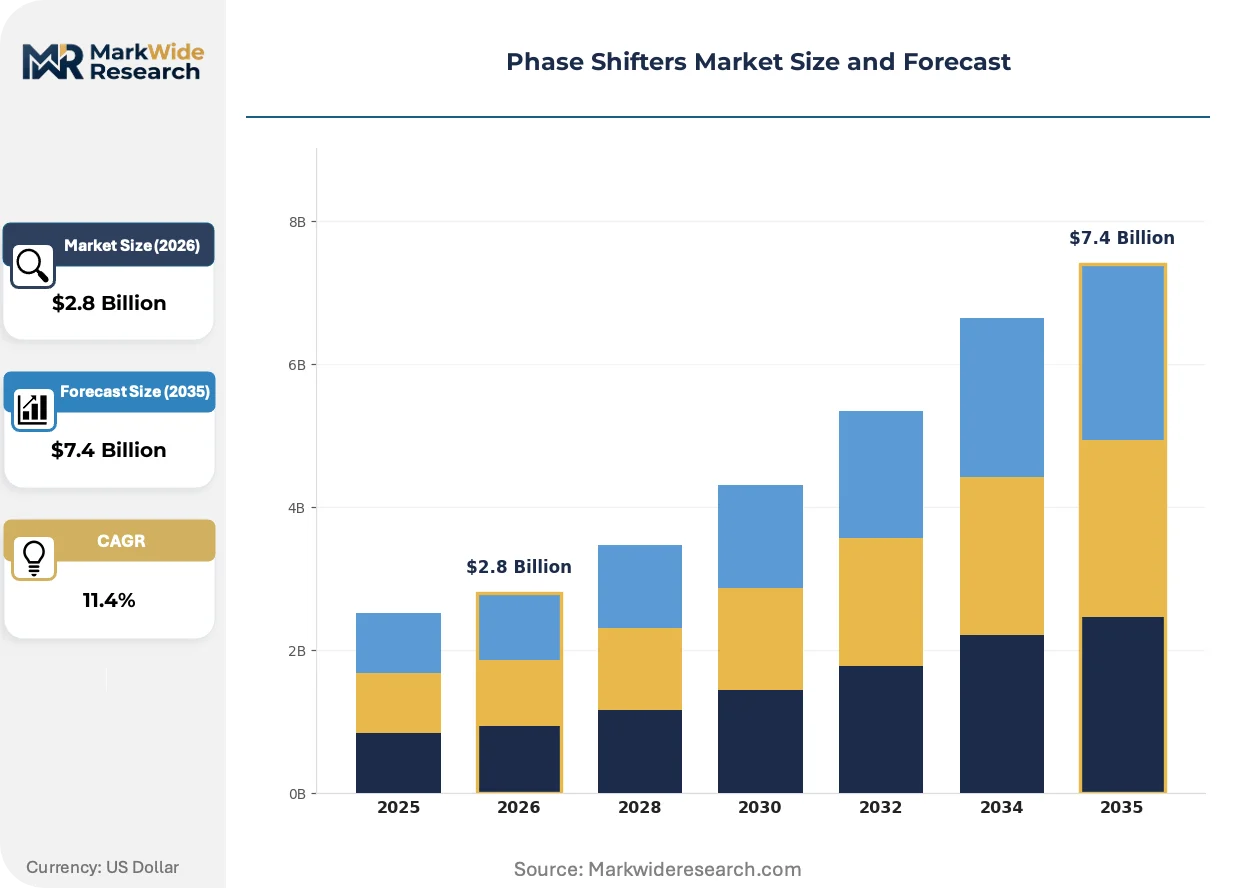
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Phase Shifters, Digital Phase Shifters, Static Phase Shifters, Variable Phase Shifters Technology: RF Technology, Microwave Technology, Optoelectronic Technology, Integrated Circuit Technology End User: Telecommunications, Aerospace, Defense, Automotive Application: Signal Processing, Radar Systems, Satellite Communications, Wireless Networks |
| Companies Covered | Analog Devices, Qorvo, MACOM Technology Solutions, Keysight Technologies, Planar Monolithics Industries, Mercury Systems, Crane Aerospace & Electronics, pSemi, Astra Microwave Products Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phase Shifters Market Evolving Landscape
Silicon integration and advanced packaging are collapsing the cost curves for beamforming subsystems, while regulatory pressure on spectrum efficiency is tightening phase noise specifications across both defense and commercial procurement channels.
Silicon germanium BiCMOS phase shifter cores are migrating from defense-exclusive applications into automotive radar modules below 79 GHz. Tier-one automotive suppliers in Germany and Japan are qualifying these devices for series production in 2024-2025 model year vehicles. This migration from III-V compound semiconductors to silicon-based integration is compressing bill-of-material costs by half while extending digital calibration capabilities into the RF frontend.
REACH Annex XVII restrictions on hexavalent chromium and cadmium are forcing redesigns of ferrite phase shifter assemblies used in legacy naval radar. European defense contractors are accelerating qualification of yttrium iron garnet alternatives processed without restricted substances. Surface ship programs under NATO STANAG 4158 are experiencing 18-month schedule impacts as suppliers revalidate temperature stability specifications.
Prime contractors are consolidating vendor pools for transmit-receive module subassemblies, reducing qualified supplier lists from twelve to four in major electronically scanned array programs. This concentration is displacing spot-market purchasing with multi-year framework agreements that bundle phase shifter volumes with adjacent circulator and limiter content. The shift is most visible in U.S. Navy and Royal Australian Navy next-generation destroyer radar procurements.
Phase Shifters Market Segmentation
Phase shifter architectures diverge sharply across defense radar, telecom infrastructure, and automotive radar deployments, with each end-use imposing distinct phase resolution, switching speed, and radiation hardness requirements. Procurement specifications from prime contractors and carrier equipment vendors fragment the supplier landscape into technology-specific qualification tiers.
Product Type:
After-sales service intensity varies dramatically across phase shifter architectures, with digital variants demanding firmware updates and radiation hardness recertification while analog units require calibration drift management over extended field deployments.
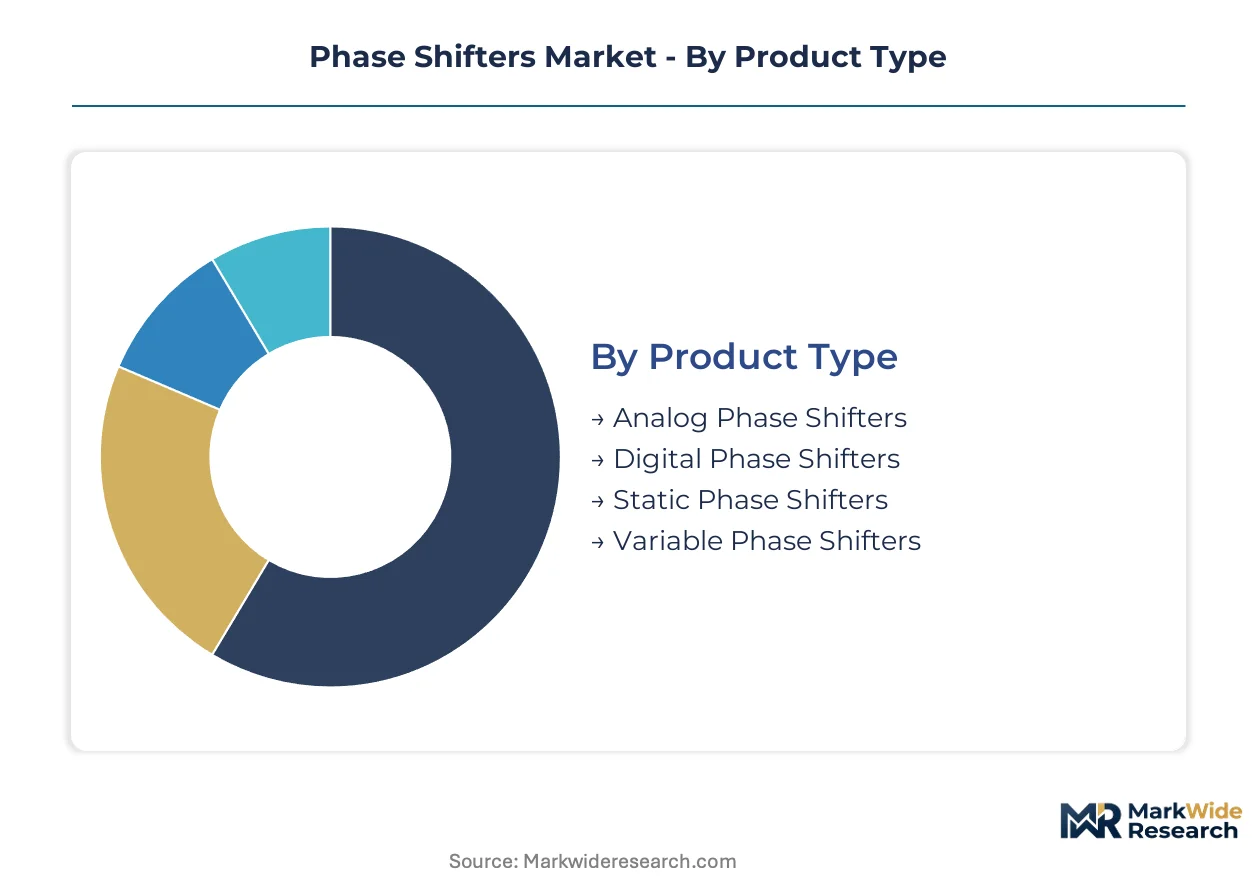
- Digital Phase Shifters:These devices implement discrete phase states through switched-bit architectures using PIN diodes or GaAs FET switches, delivering precise beam steering for electronically scanned array radar. Defense procurement programs in the United States absorb the majority of volume, driven by next-generation surface ship and airborne radar modernization timelines that mandate radiation-hardened qualified suppliers.
- Analog Phase Shifters:Continuous phase adjustment via varactor-tuned transmission lines or ferrite-based waveguide structures enables dynamic beamforming optimization. South Korean and Japanese telecommunications carriers deploy these modules in massive MIMO base stations, where hybrid beamforming architectures require smooth phase transitions rather than discrete steps.
- Static Phase Shifters:Fixed phase delay elements serve calibration reference functions in test equipment and satellite payload beamforming networks.
- Variable Phase Shifters:MEMS and liquid crystal implementations address emerging terahertz research applications in Finnish and Singaporean 6G programs.
By volume, digital phase shifters lead. By growth pace, analog variants are ahead.
Technology:
Cost tier stratification separates legacy waveguide implementations from emerging silicon-integrated solutions, with compound semiconductor processes commanding premium pricing for defense-exclusive frequency bands.
- Microwave Technology:Ferrite-based waveguide and coaxial phase shifters dominate legacy naval radar installations, particularly in NATO STANAG 4158-compliant surface ship programs. REACH Annex XVII restrictions on hexavalent chromium are forcing 18-month redesign cycles as European contractors qualify yttrium iron garnet alternatives without restricted substances.
- Integrated Circuit Technology:Silicon germanium BiCMOS cores are displacing III-V compound semiconductors in automotive radar modules below 79 GHz. German and Japanese tier-one suppliers are qualifying these devices for series production, compressing bill-of-material costs while embedding digital calibration capabilities.
- RF Technology:Discrete lumped-element and distributed approaches persist in test and measurement equipment requiring ultra-wideband phase control.
- Optoelectronic Technology:Optical phase shifters using lithium niobate waveguides address specialized satellite crosslink and fiber-optic antenna remoting applications.
Microwave technology retains the largest installed base. Integrated circuit technology is expanding most quickly.
End User:
Application maturity cycles separate defense procurement programs with decade-long qualification timelines from commercial wireless deployments refreshing on 3-5 year equipment cycles.
- Defense:Electronically scanned array radar programs across the U.S. Navy, Royal Australian Navy, and Indian Defense Acquisition Procedure 2020 indigenization initiatives consume high-reliability phase shifter volumes. MIL-STD-461 and MIL-STD-464 electromagnetic compatibility mandates lock in multi-year procurement contracts for qualified suppliers.
- Telecommunications:5G massive MIMO infrastructure buildouts in South Korea and Japan drive analog phase shifter demand for hybrid beamforming architectures.
- Aerospace:Space-qualified modules for satellite communications require extended total ionizing dose testing under ESA ECSS-Q-ST-60-02C, stretching development timelines to 36-48 months.
- Automotive:European OEMs are qualifying compact phase shifter ICs for 60-64 GHz imaging radar ahead of UN ECE R79 autonomous driving mandates.
Defense commands the highest revenue per unit. Automotive is climbing the fastest.
Application:
Customer type fragmentation separates prime contractor direct procurement from carrier equipment vendor specifications, with each channel imposing distinct technical documentation and qualification burden requirements.
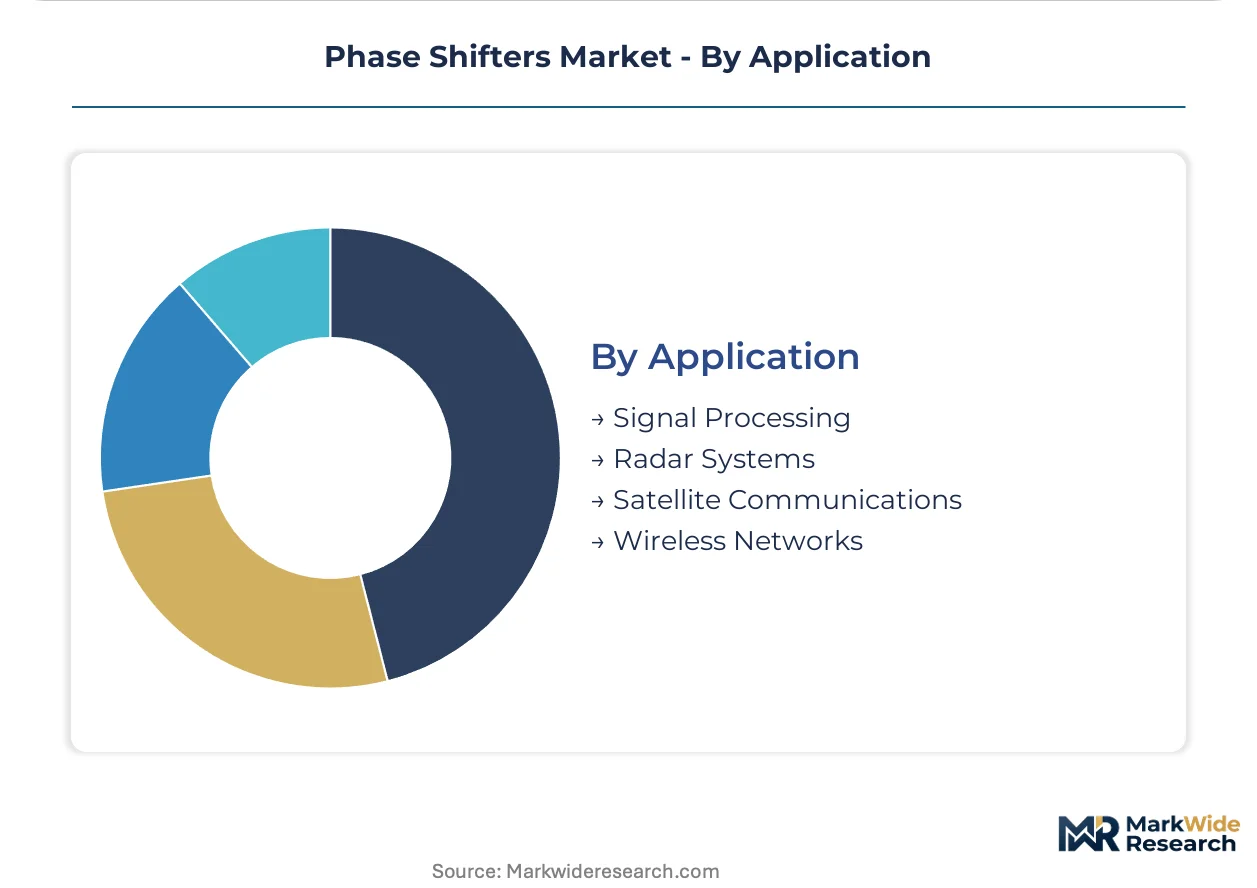
- Radar Systems:Active electronically scanned arrays for military and weather monitoring applications require phase shifters with sub-microsecond switching speeds and high power-handling capability. GaN-on-SiC process maturation at wide-bandgap foundries is extending X-band and Ku-band transmit chain thresholds.
- Wireless Networks:5G base station beamforming demands phase shifters with low insertion loss and linear phase response across 3.5 GHz and millimeter-wave bands. FCC Part 15 and Part 27 rules constrain transmit power and spurious emissions profiles.
- Satellite Communications:Phased array user terminals for low-earth-orbit constellations require radiation-tolerant digital phase shifters with reprogrammable beam tables.
- Signal Processing:Test and measurement instrumentation for 6G research programs in Finland and Singapore creates pilot demand for sub-degree phase resolution at sub-millimeter-wave frequencies.
Radar systems dominate current procurement volume. Wireless networks are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Department of Defense anchors procurement volumes through MIL-STD-461 and MIL-STD-464 compliance mandates that lock in multi-year contracts for qualified suppliers. Defense procurement programs in the United States, South Korea, and Germany concentrate demand for high-reliability phase shifter modules.
United States
Next-generation surface ship and airborne radar modernization timelines drive volume for radiation-hardened digital phase shifters. The U.S. Navy's electronically scanned array programs reduce qualified supplier lists from twelve to four vendors. Massachusetts and California host prime contractor supply chains that bundle phase shifter volumes with adjacent circulator content.
Germany
Tier-one automotive suppliers qualify silicon germanium BiCMOS phase shifter cores for 2024-2025 model year vehicles ahead of UN ECE R79 mandates. REACH Annex XVII restrictions on hexavalent chromium force 18-month redesign cycles for yttrium iron garnet alternatives. Bavaria-based contractors revalidate temperature stability specifications for NATO STANAG 4158-compliant surface ship programs.
South Korea
Telecommunications carriers deploy hybrid beamforming architectures consuming high volumes of analog phase shifter modules in massive MIMO base stations. The country's national telecommunications regulator constrains transmit power and spurious emissions profiles under licensed radio operation rules. Seoul Capital Area equipment vendors specify smooth phase transitions rather than discrete steps for 3.5 GHz and millimeter-wave bands.
Japan
METI-funded 6G research programs create pilot demand for sub-millimeter-wave phase shifters with sub-degree resolution. Domestic tier-one automotive suppliers qualify compact phase shifter ICs for imaging radar front ends. Nagoya and Osaka industrial corridors concentrate backend assembly investment for passive RF component manufacturing.
India
The Defense Acquisition Procedure 2020 prioritizes domestic sourcing for phased array subsystems, inviting joint ventures with foreign GaN foundry operators. Indian Space Research Organisation satellite programs require extended total ionizing dose testing stretching development timelines. Bengaluru and Hyderabad host emerging defense electronics clusters targeting electronically scanned array radar indigenization.
Phase Shifters Market Competitive Landscape
Capability concentration sits with defense-qualified suppliers holding radiation-hardened process certifications; scale advantage sits with commercial semiconductor houses serving high-volume telecommunications and automotive segments. The supplier landscape fragments into three tiers: prime contractor-captive module manufacturers, independent compound semiconductor foundries, and silicon-integrated device specialists. Strategic moves center on multi-year framework agreements bundling phase shifter volumes with adjacent components, and GaN-on-SiC foundry partnerships extending power-handling thresholds for X-band and Ku-band radar transmit chains.
Within the defense-qualified tier, Analog Devices and Qorvo exemplify contrasting approaches to technology access. Analog Devices leverages foundry partnerships for wide-bandgap process leadership, while Qorvo anchors positioning through captive compound semiconductor capacity. MACOM Technology Solutions occupies a position competing aggressively on price-performance in commercial 5G massive MIMO deployments, representing the silicon-integrated specialist archetype targeting cost compression in high-volume telecommunications infrastructure.
| Leading Market Players |
|---|
| Analog Devices |
| Qorvo |
| MACOM Technology Solutions |
| Keysight Technologies |
| Planar Monolithics Industries |
| Mercury Systems |
| Crane Aerospace & Electronics |
| pSemi |
| Astra Microwave Products Limited |
| Others |
Value Network & Pricing Analysis
Taiwan's six-inch gallium arsenide wafer foundries concentrate substrate supply for legacy analog phase shifter lines, translating upstream chokepoint vulnerability into pricing power for qualified defense suppliers holding MIL-STD-461 certifications. This geographic concentration cascades into downstream cost structures, where radiation-hardened digital architectures command substantial premiums over commercial-grade alternatives.
Pricing Analysis
Defense-qualified suppliers in Massachusetts and California extract 40-60% price premiums over commercial-grade vendors serving telecommunications infrastructure. Pricing stratifies across radiation-hardened, automotive-qualified, and standard commercial tiers, with certification level and volume scale as primary differentiation drivers. Cost compression in 5G massive MIMO segments intensifies as MACOM Technology Solutions and silicon-integrated specialists displace III-V compound semiconductors. Telecommunications carriers exhibit highest price sensitivity, while prime defense contractors prioritize qualification timelines over unit economics.
Supply Chain Analysis
Export controls on wide-bandgap semiconductor technology under U.S. Department of Commerce restrictions limit GaN-on-SiC process transfers to foreign joint ventures, constraining India's Defense Acquisition Procedure 2020 indigenization timelines. Supply concentrates in Taiwan, Germany, and the United States for GaAs substrate fabrication, with silicon germanium BiCMOS capacity expanding in Germany and Japan. Raw material dependencies span high-purity gallium arsenide substrates, silicon carbide wafers, and rare-earth elements for ferrite assemblies. Single-source vulnerability around Taiwan-based six-inch GaAs production creates structural risk. Distribution runs through prime contractor direct procurement channels bundling phase shifter volumes with circulator and limiter content.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The phase shifters market sits at an inflection point where GaN-on-SiC process maturation and U.S. Department of Defense next-generation electronic warfare mandates are compressing technology refresh cycles from decade-long timelines to multi-year sprints.
For Market Incumbents: Insulate qualification moats by accelerating radiation-hardened process certifications ahead of prime contractor vendor consolidation from twelve to four approved suppliers. Deepen captive GaN-on-SiC foundry partnerships to secure X-band and Ku-band transmit chain capacity, while embedding firmware update capabilities into digital phase shifter architectures to capture recurring service revenue streams. For New Entrants and Emerging Players: India's Defense Acquisition Procedure 2020 indigenization requirements represent the most penetrable entry point for foreign GaN foundry operators seeking joint venture structures with Bengaluru and Hyderabad defense electronics clusters. European automotive radar at 60-64 GHz offers secondary white-space opportunity ahead of UN ECE R79 mandates. Pursue qualification partnerships with tier-one automotive suppliers rather than direct OEM engagement. For Investors and Strategic Acquirers: Long-term, this sits as a defense-captive compound semiconductor play because multi-year framework agreements bundle phase shifter volumes with adjacent RF components, creating predictable revenue basins. Target acquisition candidates holding MIL-STD-461/464 qualified supplier status with established prime contractor relationships. Monitor U.S. Navy electronically scanned array program award timelines as inflection indicator for vendor consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| GaN-on-SiC Foundry Partnership | Extends power-handling thresholds for X-band radar transmit chains at wide-bandgap semiconductor foundries. |
| Radiation Hardness Recertification | Locks in multi-year procurement contracts under U.S. Department of Defense MIL-STD-461 compliance mandates. |
| Silicon Germanium BiCMOS Migration | Compresses bill-of-material costs by half in automotive radar modules below 79 GHz. |
| Prime Contractor Vendor Consolidation | Displaces spot-market purchasing with framework agreements bundling phase shifter and circulator volumes. |
| REACH Annex XVII Redesign | Forces 18-month qualification cycles for yttrium iron garnet alternatives in NATO STANAG 4158 surface ship programs. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with defense procurement officers, RF component engineering directors, prime contractor supply chain managers, and telecommunications infrastructure planners; alongside secondary validation through U.S. Department of Defense contract announcements, FCC equipment authorization databases, ESA ECSS qualification registries, and SEC filings from publicly traded semiconductor suppliers. Bottom-up build-ups of transmit-receive module shipments triangulated against top-down defense budget appropriation analysis.
Forecast inputs span product type segmentation across digital, analog, static, and variable architectures; technology tiers from ferrite waveguide through silicon germanium BiCMOS integration; end-use categories spanning defense, telecommunications, aerospace, and automotive; and application dimensions across radar systems, wireless networks, satellite communications, and signal processing instrumentation. CAGRs were derived from regression analysis of historical procurement volumes against disclosed prime contractor backlog data and carrier infrastructure deployment schedules.
Practitioners should monitor U.S. Navy next-generation destroyer radar program awards, India's Defense Acquisition Procedure 2020 joint venture approvals, and REACH Annex XVII substance restriction enforcement timelines for early signals of forecast revision. Material shifts in GaN-on-SiC foundry capacity allocation between defense and commercial customers, or unexpected delays in radiation hardness qualification timelines, would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Gan RF Semiconductor Devices Market
RF Components
US RFID Tags Market
RF Components
RF Filters Market
RF Components
FBAR Devices Market
RF Components
Noise Suppression Components Market
RF Components
Digital Radio Frequency Market
RF Components
Flat Panel Antenna Market
RF Components
Z-Wave Products Market
RF Components
UHF RFID Inlays Market
RF Components
RF Power Amplifiers Market
RF Components
Wi-Fi Module Market
RF Components
Radio Frequency Integrated Circuit (RFIC) Market
RF Components
Smartphone RF Power Amplifier Market
RF Components
RF Spectrum Analyzer Market
RF Components
RF Microwave MLCC Market
RF Components
Monolithic Microwave Integrated Circuit (MMIC) Market