
 Global Respiratory and Anesthesia Disposables Market | 2026-2036
Global Respiratory and Anesthesia Disposables Market Size, Share, and Industry Trends Forecast 2026-2036
Global Respiratory and Anesthesia Disposables Market Foresight
Modular bundling of breathing circuits with filtration and sampling lines is recalibrating how purchasing departments evaluate total cost per procedure. Becton, Dickinson and Company leverages its integrated manufacturing footprint to control supply continuity for high-volume SKUs. Ambu A/S anchors its position through single-use endoscopy and anesthesia portfolios that reduce cross-contamination risk. Fisher & Paykel Healthcare differentiates via humidification technology embedded within disposable breathing sets.
Respiratory and anesthesia disposables encompass single-patient-use devices manufactured from medical-grade polymers, silicone, and filtration media through injection molding and extrusion processes, designed to establish or maintain ventilatory support and drug delivery pathways during surgical, emergency, or chronic care. Breathing circuits and face masks represent mature volume categories where procurement contracts favor scale suppliers, while laryngeal masks and nebulizer kits capture faster expansion as outpatient anesthesia and home-based inhalation therapy broaden addressable patient populations. End-user concentration among hospitals and ambulatory surgical centers creates divergent margin pools, with ASCs prioritizing lean inventory and standardized SKUs against the ICU-driven customization that hospitals require.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and sterilization validation costs for manufacturers targeting both markets. ISO 18562 biocompatibility evaluation for breathing gas pathways adds a parallel compliance layer that influences material selection and supplier qualification. Stakeholders must monitor how FDA's evolving guidance on reprocessed single-use devices and the EU Green Deal's plastics packaging mandates will alter cost structures and competitive positioning across disposable portfolios.
Market Dynamics
Hospital procurement consolidation across the United States, Germany, and China is compressing supplier margins while elevating contract minimums that favor manufacturers with captive polymer extrusion and sterilization capacity.
Growth Catalysts
- EU MDR sterilization mandates:Stricter validation requirements for single-use breathing circuits are filtering out smaller competitors and concentrating volume among accredited suppliers with in-house ethylene oxide processing.
- Ambulatory surgical centers:Rising procedural migration to outpatient settings in the United States is amplifying consumption of lean-inventory, standardized anesthesia masks and laryngeal airways.
- ISO 18562 biocompatibility evaluation:The standard's gas-pathway testing protocols are driving material upgrades to medical-grade silicone and specialized filtration media that command premium positioning.
Market Restraints
- Medical-grade polymer feedstock volatility:Polypropylene and polycarbonate price swings tied to petrochemical supply chains compress margin predictability for high-volume extrusion manufacturers.
- Sterilization capacity concentration:Ethylene oxide sterilization services cluster in the United States and Germany, creating geographic bottlenecks that extend lead times for Asia-Pacific market entrants.
- Reprocessing regulatory friction:FDA's evolving scrutiny of reprocessed single-use devices creates demand uncertainty for original equipment manufacturers competing against third-party reprocessors.
Strategic Opportunities
- Home-based respiratory therapy:Nebulizer kit and oxygen delivery disposables for chronic obstructive pulmonary disease patients in China represent underpenetrated volume outside institutional settings.
- EU Green Deal packaging mandates:Plastics reduction requirements are creating first-mover advantage for suppliers developing fiber-based or recyclable breathing circuit packaging.
- Modular filtration integration:Convergence of heat-moisture exchangers with viral filtration technology enables premium bundling that captures procedure-level economics from standalone component suppliers.
Industry Challenges
- Sterilization validation timelines:FDA 510(k) and EU MDR technical documentation cycles extend eighteen to thirty-six months, delaying revenue recognition for pipeline innovations.
- Legacy ERP integration:Hospital procurement systems require EDI connectivity and consignment inventory tracking that strains mid-tier manufacturers' IT infrastructure investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Respiratory and Anesthesia Disposables Market |
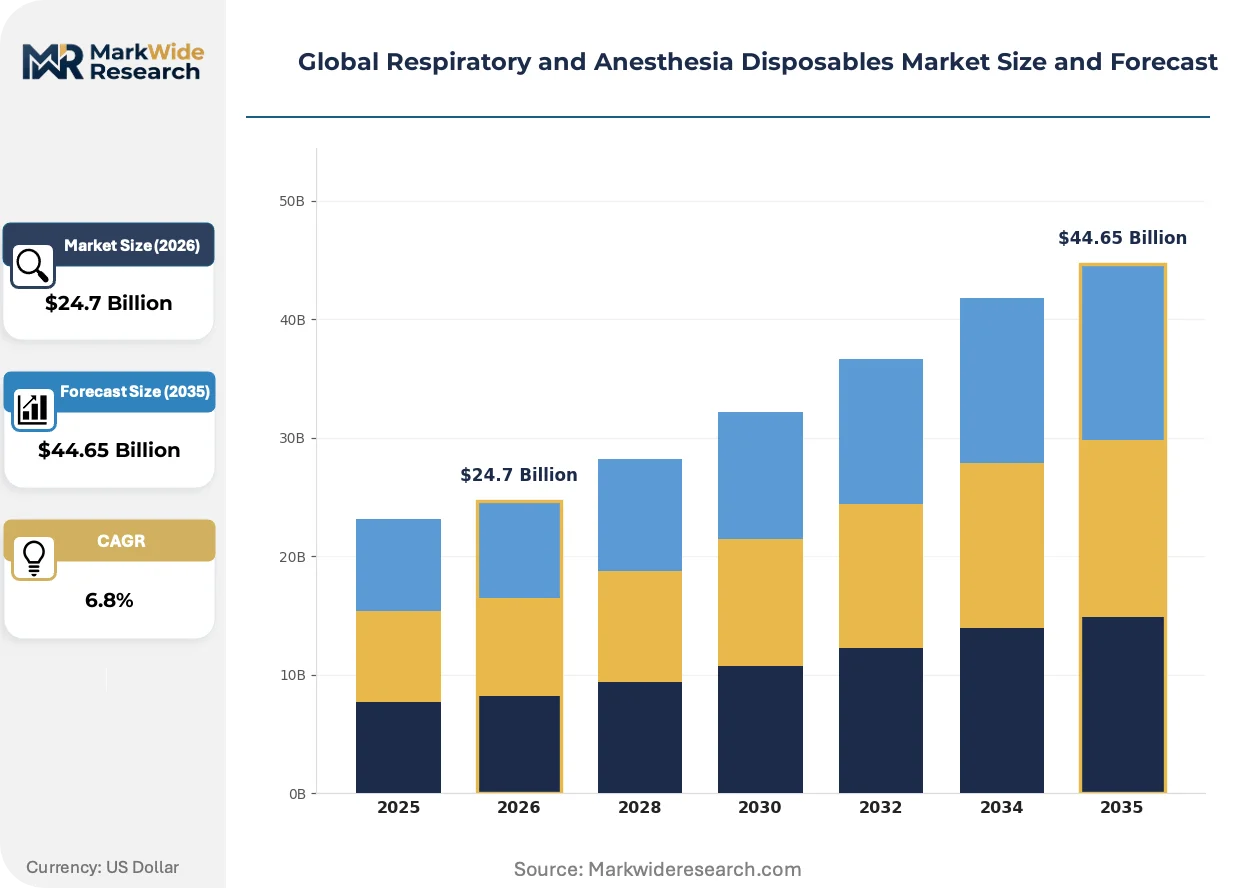
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $44.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endotracheal Tubes, Laryngeal Masks, Face Masks, Breathing Circuits, Nebulizer Kits Application: Inhalation Therapy, Surgical Anesthesia, Emergency Respiration, Intensive Care Ventilation, Sleep Apnea Management End User: Hospitals, Ambulatory Surgical Centers, Emergency Medical Services, Home Care Providers, Diagnostic Laboratories Deployment: Single-Use, Disposable, Reusable, Sterile Packaging, Non-Sterile Packaging |
| Companies Covered | Becton, Dickinson and Company, Ambu A/S, Medtronic PLC, Fisher & Paykel Healthcare, ResMed Inc., Teleflex Inc., Boston Scientific Corporation, Smiths Group plc, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Respiratory and Anesthesia Disposables Market Shifts & Advancements
Active materials science and regulatory packaging mandates are recalibrating how manufacturers design breathing circuits and filtration systems for differentiated performance and compliance positioning.
Closed-cell silicone foam is converging with anatomical molding technology to produce laryngeal masks that seal at lower cuff pressures. Ambulatory surgical centers in Germany are adopting these devices to reduce post-operative throat trauma complaints. The technology is converging with single-use economics to displace reusable metal laryngoscope blades in outpatient anesthesia workflows.
EU MDR technical documentation requirements are forcing manufacturers to rebuild clinical evidence portfolios for legacy breathing circuit SKUs. The regulation's post-market surveillance obligations are elevating quality management system investments across mid-tier suppliers. ICU-driven customization requirements in France and Italy are most affected, with hospitals demanding batch-level traceability that legacy inventory systems cannot support.
Consignment inventory models are replacing traditional purchase orders in United States hospital networks. Anesthesia departments now expect suppliers to maintain floor-stock of circuits and masks with usage-based replenishment. This shift is most visible in integrated delivery networks across Texas and Florida, where procurement directors negotiate vendor-managed inventory clauses that transfer carrying cost to manufacturers.
Global Respiratory and Anesthesia Disposables Market Segmentation
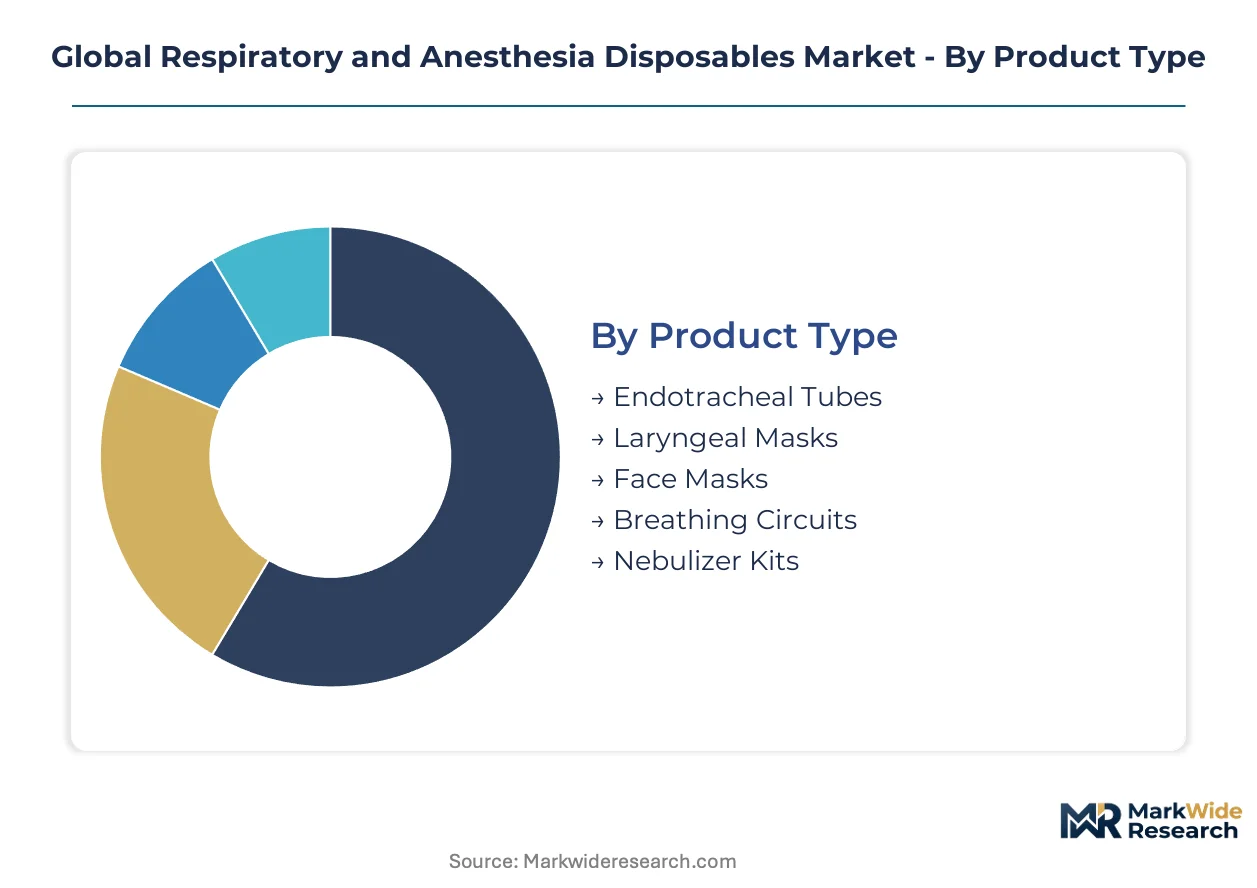
Segmentation in respiratory and anesthesia disposables reveals how procurement economics diverge across clinical settings. Product architecture and sterilization protocols create distinct margin pools that manufacturers must navigate simultaneously.
Product Type:
Standalone consumables dominate high-volume contracts, while embedded filtration systems command premium positioning in ICU workflows.
- Endotracheal Tubes:Cuffed and uncuffed configurations in polyvinyl chloride and silicone serve intubation protocols across operating theaters and emergency departments. United States hospital networks specify subglottic suction ports for ventilator-associated pneumonia prevention, tightening supplier qualification standards.
- Laryngeal Masks:Single-use supraglottic airways with integrated bite blocks and gastric access channels displace reusable alternatives in ambulatory surgical centers. Germany's outpatient anesthesia migration amplifies demand for silicone-cuff variants that seal at reduced pressures.
- Face Masks:Anatomically contoured designs in thermoplastic elastomer establish ventilation interfaces for pre-oxygenation and induction.
- Breathing Circuits:Coaxial and parallel limb configurations with heat-moisture exchanger ports form the procedural backbone of mechanical ventilation.
- Nebulizer Kits:Jet and mesh atomization chambers convert liquid bronchodilators into respirable aerosols for home and institutional use.
Breathing circuits lead volumes today; laryngeal masks are gaining share fastest.
Application:
Acute intervention settings require rapid-deployment disposables, whereas chronic management prioritizes patient compliance and cost amortization.
- Inhalation Therapy:Metered-dose inhaler spacers and nebulizer mouthpieces deliver corticosteroids and bronchodilators to asthma and COPD populations. China's expanding home respiratory care infrastructure drives kit standardization for elderly patients.
- Surgical Anesthesia:Breathing circuits with carbon dioxide sampling lines and bacterial filters support controlled ventilation during operative procedures. Ambulatory surgical centers in the United States specify lean-inventory configurations that reduce setup complexity.
- Emergency Respiration:Bag-valve-mask resuscitators and oral airways address pre-hospital airway compromise.
- Intensive Care Ventilation:Heated-wire breathing circuits with humidification chambers maintain conditioned gas delivery over prolonged mechanical support.
- Sleep Apnea Management:Nasal pillows and full-face interfaces for continuous positive airway pressure therapy address obstructive sleep disorders.
Surgical anesthesia leads volumes today; sleep apnea management is expanding most quickly.
End User:
Institutional scale determines contract structure, with consolidated health systems extracting volume discounts that strain mid-tier manufacturer margins.
- Hospitals:Integrated delivery networks in Texas and Florida negotiate consignment inventory clauses that transfer carrying costs to suppliers while demanding ICU-grade customization.
- Ambulatory Surgical Centers:Lean-staffed outpatient facilities in the United States prioritize standardized SKUs and rapid turnover disposables that minimize reprocessing overhead.
- Emergency Medical Services:Pre-hospital providers require ruggedized packaging and extended shelf-life disposables for field deployment.
- Home Care Providers:Durable medical equipment suppliers manage recurring shipments of nebulizer kits and oxygen delivery accessories to chronic respiratory patients.
- Diagnostic Laboratories:Pulmonary function testing facilities consume specialized mouthpieces and bacterial filters for spirometry protocols.
Hospitals lead volumes today; ambulatory surgical centers are climbing the fastest.
Deployment:
Sterilization assurance and packaging integrity create tiered cost structures that procurement departments evaluate against infection risk profiles.
- Single-Use:Polymer devices designated for one-patient application eliminate cross-contamination pathways and reprocessing documentation burdens.
- Disposable:Identical functional specifications to single-use variants with slightly relaxed packaging protocols for non-critical applications.
- Reusable:Metal laryngoscope blades and autoclavable breathing circuit components persist in resource-constrained settings despite FDA scrutiny of reprocessing validation.
- Sterile Packaging:Ethylene oxide or gamma-irradiated products with validated sterility assurance levels for invasive procedures.
- Non-Sterile Packaging:Cleanroom-manufactured devices for applications where terminal sterilization occurs at point of use.
Single-use leads volumes today; sterile packaging is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modern respiratory and anesthesia disposables trace their industrial origins to post-war polymer science advances in the United States and Germany, where medical-grade PVC extrusion and ethylene oxide sterilization protocols first achieved commercial scale during the 1960s hospital construction boom.
United States
Integrated delivery networks in Texas and Florida drive procurement consolidation through vendor-managed inventory clauses that transfer carrying costs to suppliers. FDA 510(k) clearance pathways shape eighteen-to-thirty-six-month product development timelines for breathing circuit innovations. Minneapolis-St. Paul anchors a cluster of anesthesia disposable manufacturers serving ambulatory surgical center chains across the Sun Belt.
Germany
Outpatient anesthesia migration amplifies demand for silicone-cuff laryngeal masks that seal at reduced pressures. EU MDR technical documentation requirements force manufacturers to rebuild clinical evidence portfolios for legacy SKUs. Baden-Württemberg hosts precision polymer extrusion facilities supplying sterile breathing circuits to university hospitals across Bavaria and North Rhine-Westphalia.
China
Expanding home respiratory care infrastructure for elderly COPD patients drives nebulizer kit standardization outside institutional settings. NMPA registration pathways for Class II medical devices compress approval timelines for domestic manufacturers. Yangtze River Delta manufacturing clusters in Jiangsu province concentrate injection molding capacity for export-grade face masks and oxygen delivery accessories.
Japan
Aging demographics expand sleep apnea management device consumption through home medical equipment channels. PMDA quality management system inspections enforce ISO 18562 biocompatibility documentation for breathing gas pathways. Osaka-based polymer compounders supply specialized filtration media to Tokyo metropolitan area ventilator manufacturers.
India
Hospital infrastructure expansion under government health insurance schemes creates procurement volume for single-use anesthesia circuits. CDSCO medical device rules harmonize with ISO standards for sterile packaging validation. Gujarat pharmaceutical manufacturing corridors attract polymer extrusion investments targeting domestic ICU disposable demand.
Global Respiratory and Anesthesia Disposables Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with captive sterilization infrastructure. Scale concentration among integrated manufacturers compresses margins for mid-tier suppliers lacking ethylene oxide processing capacity. Two strategic archetypes dominate: polymer science specialists controlling upstream extrusion and diversified health conglomerates leveraging hospital procurement relationships. Competitive moves center on modular filtration bundling and geographic footprint expansion through sterile packaging facility investments.
Among diversified health technology conglomerates, Becton, Dickinson and Company and Medtronic PLC occupy positions anchored by integrated manufacturing footprints and hospital system procurement contracts. Ambu A/S exemplifies the single-use specialization archetype, representing pure-play exposure to disposable anesthesia and respiratory portfolios. Fisher & Paykel Healthcare sits within the humidification technology tier, differentiating through embedded thermal conditioning in breathing circuit sets. These three anchors illustrate how competitive positioning diverges between scale-driven supply continuity and technology-differentiated premium positioning.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Ambu A/S |
| Medtronic PLC |
| Fisher & Paykel Healthcare |
| ResMed Inc. |
| Teleflex Inc. |
| Boston Scientific Corporation |
| Smiths Group plc |
| Koninklijke Philips N.V. |
| Others |
Supply & Pricing Matrix
Polymer extrusion specialists concentrated in Minnesota's medical device corridor create labor-cost differentials that widen spreads between premium silicone-cuff laryngeal masks and commodity polyvinyl chloride alternatives. These workforce clusters enable tiered manufacturing economics where FDA-validated sterilization capabilities command substantial price premiums over standard SKUs.
Pricing Analysis
Contract-based long-term offtake agreements dominate hospital procurement, with pricing stratifying across premium, standard, and economy tiers based on sterilization assurance levels and customization depth. Price differentiation hinges on ISO 18562 biocompatibility certification and captive ethylene oxide processing capacity. Cost compression in economy-grade breathing circuits is intensifying because of polypropylene feedstock volatility. Ambulatory surgical centers exhibit highest price sensitivity; integrated delivery networks with vendor-managed inventory clauses demonstrate lowest sensitivity due to transferred carrying costs.
Supply Chain Analysis
Freight cost exposure from sterilization services clustering in the United States and Germany extends lead times for Asia-Pacific market entrants sourcing finished goods. Manufacturing concentrates in China, Germany, and the United States, with supply chains drawing from medical-grade polypropylene, polycarbonate, and silicone resin feedstocks. Single-source vulnerability around ethylene oxide sterilization capacity creates geographic bottlenecks. Distribution runs through group purchasing organizations and direct hospital contracts with consignment inventory provisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through modular filtration bundling that captures procedure-level economics from standalone component suppliers. Premium-tier shifts toward closed-cell silicone foam laryngeal masks enable pricing power in outpatient anesthesia workflows.
For Market Incumbents: Hedge against reprocessing regulatory friction by accelerating single-use portfolio transitions ahead of FDA guidance evolution. Invest in captive ethylene oxide sterilization capacity in Germany to secure EU MDR compliance timelines. Vertical integration into medical-grade polymer compounding insulates margin structures from petrochemical volatility. For New Entrants and Emerging Players: Home care providers managing COPD populations in China's Yangtze River Delta represent the most penetrable buyer archetype for nebulizer kit standardization. Target lean-inventory ambulatory surgical centers in Texas and Florida with rapid-turnover anesthesia mask configurations. Pursue NMPA registration pathways for Class II devices to compress approval timelines against multinational competitors. For Investors and Strategic Acquirers: Diversified health technology conglomerates are the most active acquirer in this space, seeking sterilization infrastructure to complement distribution footprints. Five-to-ten-year viability favors targets with integrated polymer extrusion and validated ethylene oxide processing. Monitor FDA reprocessing guidance publication as inflection indicator for single-use demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Rebuild | Legacy SKU recertification concentrates volume among accredited suppliers with clinical evidence capabilities. |
| Modular Filtration Integration | Heat-moisture exchanger convergence with viral filtration captures premium positioning in ICU workflows. |
| Consignment Inventory Expansion | Vendor-managed inventory clauses transfer carrying costs while locking out mid-tier competitors lacking ERP integration. |
| Home Respiratory Care Infrastructure | Nebulizer kit standardization for elderly COPD patients in China opens underpenetrated volume outside hospitals. |
| Sustainable Packaging Transition | Fiber-based breathing circuit packaging addresses EU Green Deal mandates ahead of plastics reduction deadlines. |
Research Methodology
Coverage spans the United States, Germany, China, Japan, and India, with primary inputs from each market cluster combined with secondary validation. Interviews with hospital procurement managers, GPO contracts specialists, biomedical engineers, and sterilization facility operators informed demand-side dynamics. Secondary sources include FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement contract registries, and petrochemical price indices. Bottom-up SKU-level volume estimates triangulate against top-down healthcare expenditure allocations.
Granularity extends to product type, application, end user, and deployment configuration across the projection horizon. Segmentation modeling captures breathing circuit architecture, laryngeal mask cuff material, and sterilization protocol tiers. CAGRs derive from procedural volume forecasts cross-referenced with disposable consumption rates per procedure. Industry-specific inputs include ambulatory surgical center migration rates, EU MDR implementation timelines, and NMPA registration pathway efficiency.
Underlying measurement precision varies by segment; hospital procurement data carries tighter precision than home care estimates. Forecasts reflect assumptions around regulatory implementation schedules, sterilization capacity expansion, and polymer feedstock stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Medical Disposables Market
Medical Supplies
X-Ray Aprons Market
Medical Supplies
Disposable Specimen Container Market
Medical Supplies
Chlorhexidine Gluconate (CHG) Wipes Market
Medical Supplies
Disposable Hospital Gowns Market
Medical Supplies
Plasma Separation Tubes Market
Medical Supplies
Europe Surgical Glue Market
Medical Supplies
Western Europe Sterile Gloves Market
Medical Supplies
Global Contact Lens Solution Market
Medical Supplies
Global Disposable Blood Bags Market
Medical Supplies
Diagnostic Vials Market
Medical Supplies
Unit Dose Tubes Market
Medical Supplies
Anaesthesia Conduction Kits Market
Medical Supplies
Surgical and Examination Gloves Market
Medical Supplies
Ampoules and Syringes Market
Medical Supplies
Europe Medical Clothing Market