
 Ampoules and Syringes Market | 2026-2036
Ampoules and Syringes Market Size, Share, and Industry Trends Forecast 2026-2036
Ampoules and Syringes Market Analysis
Prefillable polymer syringe systems is reshaping how biologics manufacturers configure their drug-device combination products. Becton, Dickinson and Company leverages deep vertical integration across elastomer, barrel, and plunger-rod production to control supply security for high-value therapies. Gerresheimer AG anchors European glass primary packaging capacity while extending into cyclic olefin polymer alternatives for protein-sensitive formulations. Schott AG dominates borosilicate glass tubing supply through proprietary FIOLAX technology, positioning its cartridge and ampoule formats as reference standards for regulatory filings.
Ampoules and syringes constitute primary drug containment and delivery systems engineered from borosilicate glass Type I or engineered polymers with tight dimensional tolerances, lubricated plunger interfaces, and tamper-evident closure designs to ensure sterility, dosing accuracy, and chemical stability across shelf life. Pre-filled syringes now command the fastest growth trajectory as biopharma companies outsource final assembly and seek to reduce medication errors in hospital and homecare settings. Glass ampoules retain dominance in emerging market vaccination campaigns and generic injectable supply where cost sensitivity and established cold-chain infrastructure favor single-use break-open formats.
The FDA enforces stringent container closure integrity and biocompatibility standards under USP <661> and <1207>, while the EMA's MDR elevates clinical evidence requirements for device constituent parts in combination products. India's CDSCO has aligned with ISO 11040 series for pre-filled syringe quality benchmarks, tightening market access for imported devices. Stakeholders must monitor how polymer material innovations interact with evolving pharmacopeial extractables thresholds and whether regional regulator divergence on combination product pathways fragments approval strategies.
Market Dynamics
Biopharmaceutical manufacturers are consolidating their drug-device combination product strategies around pre-fillable syringe formats, creating upstream demand concentration that reshapes capacity planning across glass tubing and polymer conversion tiers.
Growth Catalysts
- Biologics Administration Shift:Complex protein therapeutics require specialized primary packaging with extractables-tested elastomer components, pulling demand toward validated pre-filled syringe systems.
- EMA MDR Compliance:The European Medical Device Regulation elevates clinical evidence requirements for device constituent parts, favoring suppliers with established technical documentation libraries.
- Homecare Injection Migration:Self-administration protocols for chronic conditions are displacing hospital-based administration, requiring patient-centric delivery formats with integrated safety features.
Market Restraints
- Borosilicate Glass Supply Concentration:FIOLAX-grade tubing production clusters in Germany and limited qualified alternative sources create vulnerability to energy cost volatility.
- Extractables Testing Burden:FDA USP <661> and <1207> container closure integrity mandates extend qualification timelines and raise analytical chemistry costs for new material introductions.
- Polymer Substitution Ceiling:Cyclic olefin polymer alternatives face adoption limits in high-value biologics where glass inertness remains the regulatory reference standard.
Strategic Opportunities
- Indian CDSCO Alignment:India's adoption of ISO 11040 quality benchmarks for pre-filled syringes creates first-mover advantage for suppliers establishing local technical service presence.
- Cell and Gene Therapy Packaging:Cryogenic storage requirements for CAR-T and viral vector products demand novel barrier systems beyond standard borosilicate specifications.
- Integrated Safety System Convergence:Passive needlestick protection mechanisms combined with connectivity-enabled adherence tracking open premium positioning in reimbursement-sensitive markets.
Industry Challenges
- Cleanroom Manufacturing Capacity:ISO 5 classified filling operations for combination products require capital-intensive facility construction with 18-24 month commissioning cycles.
- Legacy Glass-to-Polymer Validation:Established biologics face regulatory friction when switching primary packaging materials due to stability study requirements and agency consultation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ampoules and Syringes Market |
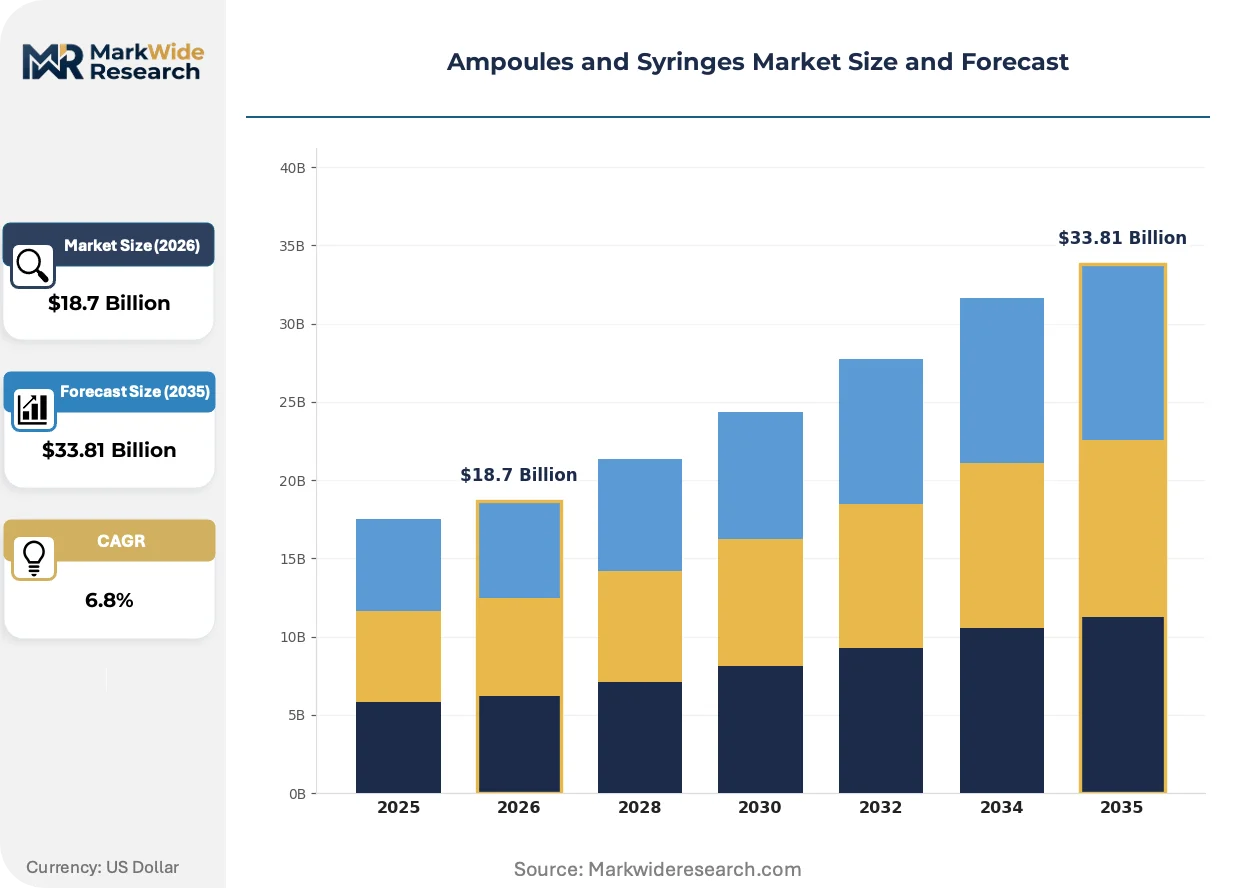
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ampoules, Pre-filled Syringes, Disposable Syringes, Safety Syringes Material: Glass, Plastic, Polypropylene, PVC End User: Hospitals, Clinics, Homecare, Laboratories Application: Vaccination, Drug Delivery, Blood Sampling, Diagnostics |
| Companies Covered | Becton, Dickinson and Company, Gerresheimer AG, Schott AG, West Pharmaceutical Services, Inc., Terumo Corporation, B. Braun Melsungen AG, Nipro Corporation, Stevanato Group, Hindustan Syringes & Medical Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ampoules and Syringes Market Emerging Trajectories
Primary packaging is undergoing material science and digital integration shifts that redefine how containment systems demonstrate value beyond basic sterility assurance.
Connected delivery devices with embedded sensors and wireless transmission modules are digitizing how adherence data flows from patient to prescriber. Chronic disease management programs at integrated health systems are piloting these formats for injectable therapies with narrow therapeutic indices. The data infrastructure is compressing traditional feedback loops between pharmaceutical sponsors and real-world usage patterns.
REACH chemical registration requirements in Europe are tightening scrutiny of polymer additives and lubricants used in plunger coatings. Manufacturers must now document substance volumes and hazard classifications across complex supply chains. Small-volume parenteral applications face disproportionate compliance burden relative to batch scale.
Hospital procurement consortia are consolidating their vendor panels for high-volume generic injectables, favoring suppliers with dual-source glass and polymer capabilities. Group purchasing organizations are unbundling device assembly from drug filling services, creating disintermediation pressure on vertically integrated players. Germany's hospital sector exhibits this pattern most acutely due to Diagnosis-Related Group pricing compression.
Ampoules and Syringes Market Segmentation
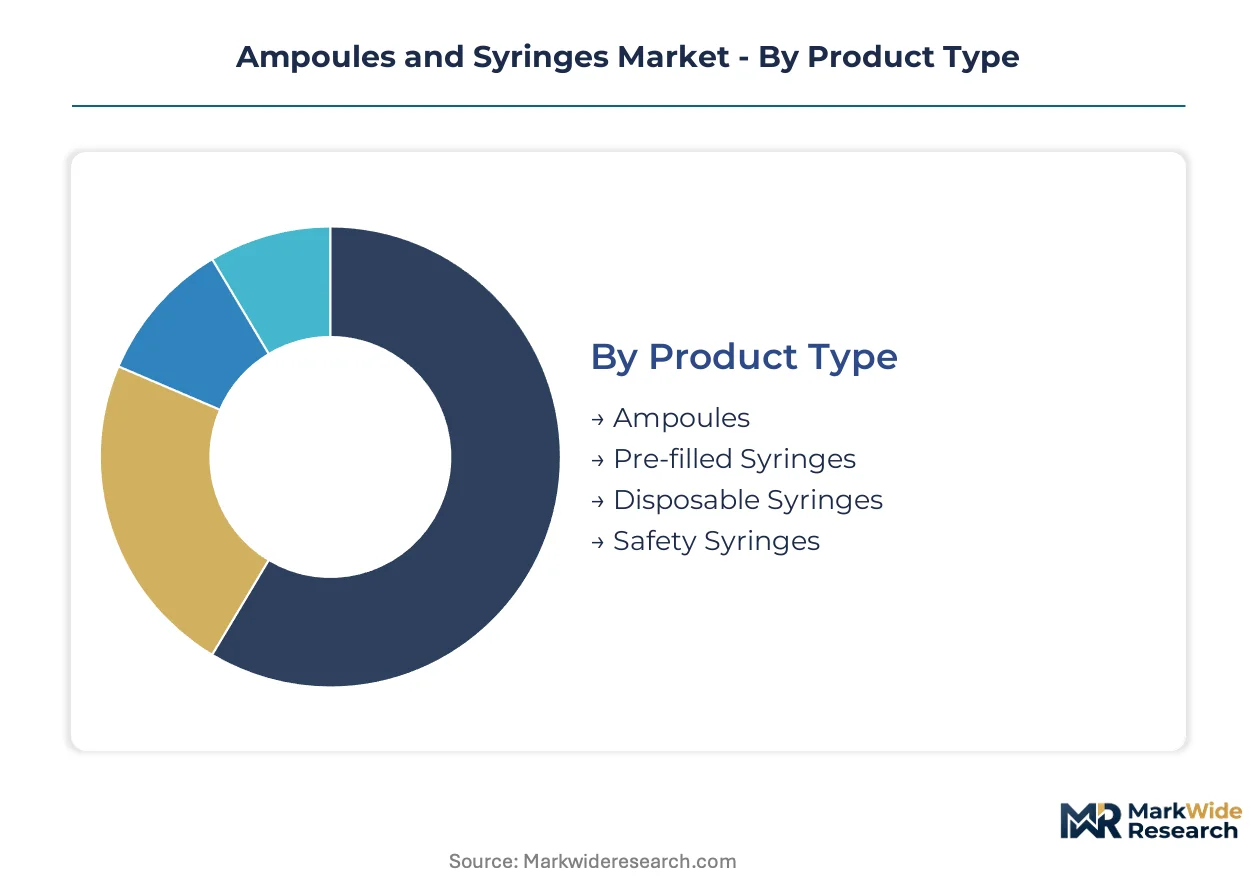
Segmentation in the ampoules and syringes market reveals how technical specifications and regulatory requirements fragment procurement patterns across therapeutic areas. Material compatibility with biologic formulations and sterilization protocols drives vendor selection more than unit economics alone.
Product Type:
After-sales service intensity varies sharply across product formats, with combination products requiring field technical support that commodity disposables do not.
- Pre-filled Syringes:Drug-device combinations with integrated plunger-rod systems and lubricated elastomer stoppers demand extractables-validated components for protein therapeutics. Demand concentrates in Germany and Switzerland where EMA MDR technical documentation requirements favor suppliers with established clinical evidence libraries.
- Ampoules:Single-dose borosilicate glass containers with break-open neck designs serve cost-sensitive vaccination programs and generic injectable supply chains. Demand clusters in India and Brazil where cold-chain infrastructure favors established glass formats over polymer alternatives.
- Safety Syringes:Passive needlestick protection mechanisms integrated into disposable platforms address OSHA bloodborne pathogen mandates in US healthcare settings.
- Disposable Syringes:Luer-lock or slip-tip polymer designs dominate high-volume generic administration where procurement consortia prioritize supply security over feature differentiation.
Pre-filled syringes hold the largest share; momentum sits with safety syringes as occupational safety regulations tighten across OECD healthcare systems.
Material:
Cost tier segmentation separates premium inert formulations from commodity polymer grades with distinct qualification burdens.
- Glass:Borosilicate Type I tubing with hydrolytic resistance certification serves as the regulatory reference standard for parenteral stability studies. FIOLAX-grade production concentrates in Germany, creating supply vulnerability to energy cost volatility.
- Plastic:Engineered polymers including cyclic olefin polymers and copolymers offer break resistance for patient-administered therapies, though EMA extractables thresholds limit adoption in high-value biologics.
- Polypropylene:Cost-effective barrel and plunger-rod material for standard disposable platforms where USP <661> chemical resistance testing applies.
- PVC:Declining use in plunger components due to REACH chemical registration requirements and plasticizer migration concerns in European markets.
Glass commands the premium tier; polymer alternatives are climbing fastest in homecare and self-administration segments.
End User:
Customer type segmentation maps to reimbursement pathways and procurement authority concentration.
- Hospitals:Integrated health systems with centralized pharmacy operations drive demand for pre-filled formats that reduce compounding errors and nursing labor time.
- Homecare:Self-administration protocols for chronic conditions require patient-centric designs with integrated adherence tracking and connectivity features.
- Clinics:Outpatient settings favor disposable platforms with lower capital equipment requirements than multi-dose vial systems.
- Laboratories:Blood collection and diagnostic applications demand precision-manufactured components with tight dimensional tolerances for automated handling equipment.
Hospitals account for the dominant volume; homecare is gaining share fastest as biologics migrate to subcutaneous administration routes.
Application:
Application segmentation aligns with regulatory filing pathways and clinical evidence requirements.
- Drug Delivery:Parenteral administration of biologics and small molecules drives the most stringent container closure integrity standards under FDA USP <1207>.
- Vaccination:Mass immunization programs favor single-dose ampoules and pre-filled formats that eliminate multi-dose vial contamination risks.
- Blood Sampling:Vacuum tube and syringe systems for diagnostic specimen collection require hemolysis-resistant interior surfaces.
- Diagnostics:Molecular and immunodiagnostic applications demand low-extractables containers for reagent stability.
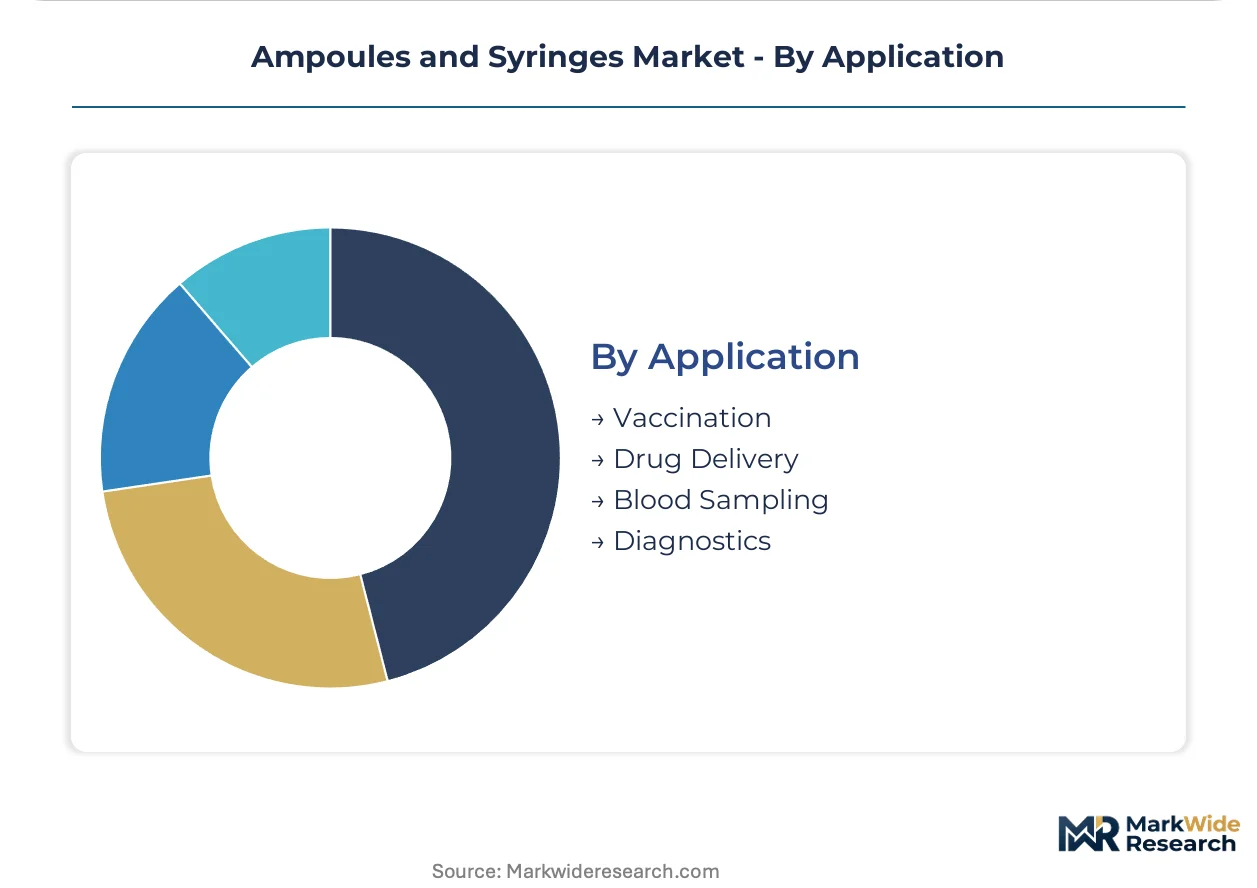
Drug delivery represents the largest application segment; vaccination shows the steepest expansion trajectory as national immunization programs scale polymer pre-filled adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopharmaceutical manufacturers concentrate their procurement authority in Germany, the United States, India, and Japan, with purchasing decisions increasingly centralized through hospital consortia and national tender programs.
Germany
Gerresheimer and Schott anchor specialized glass tubing and polymer conversion capacity serving European drug makers. EMA MDR compliance requirements elevate clinical evidence documentation burdens for device constituent parts in combination products. The Rhine-Main cluster around Frankfurt and Mainz houses validated cleanroom assembly operations for pre-filled syringe systems.
United States
Integrated health systems drive demand for pre-filled formats that reduce compounding errors and nursing labor time in hospital pharmacy operations. FDA enforces stringent container closure integrity standards under USP <661> and <1207> for parenteral packaging materials. The Boston-Cambridge biotech corridor generates specialized demand for extractables-validated elastomer components in protein therapeutic delivery.
India
Mass immunization programs and generic injectable manufacturing favor cost-sensitive single-dose ampoule formats over polymer alternatives. CDSCO alignment with ISO 11040 quality benchmarks tightens market access for imported pre-filled syringe devices. Gujarat and Maharashtra host expanding conversion capacity for borosilicate glass and disposable polymer platforms serving domestic and export markets.
Japan
Aging demographics and self-administration protocols for chronic conditions pull demand toward patient-centric delivery formats with integrated safety features. PMDA maintains rigorous biocompatibility and sterility assurance standards for primary drug containment systems. The Kansai region around Osaka retains precision manufacturing clusters for high-integrity parenteral packaging components.
China
Domestic biopharmaceutical capacity expansion creates upstream demand for validated pre-fillable syringe systems and specialized glass tubing. NMPA implementation of GMP Annex 1 revisions elevates contamination control requirements for sterile medicinal products. The Yangtze River Delta around Shanghai concentrates contract manufacturing and primary packaging assembly operations for regional drug makers.
Ampoules and Syringes Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where scale-driven multinationals, vertically integrated regional champions, and focused component specialists each occupy distinct competitive positions. The vendor base separates into three strategic archetypes: full-system integrators controlling elastomer-to-device supply chains, glass-dominant tubing specialists with proprietary material technologies, and regional disposable manufacturers competing on cost and local regulatory alignment. Dominant competitive moves include backward integration into raw material production and capacity expansion in ISO 5 classified cleanroom facilities.
Among the full-system integrators, Becton, Dickinson and Company and Gerresheimer AG exemplify archetypes of deep supply chain control and European glass-to-polymer diversification respectively. Schott AG occupies a position as the reference-standard borosilicate tubing supplier through proprietary FIOLAX technology. These three entities anchor the premium tier where regulatory technical documentation libraries and validated manufacturing infrastructure create defensive positioning against commodity competition.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Gerresheimer AG |
| Schott AG |
| West Pharmaceutical Services, Inc. |
| Terumo Corporation |
| B. Braun Melsungen AG |
| Nipro Corporation |
| Stevanato Group |
| Hindustan Syringes & Medical Devices |
| Others |
Supply Flow & Price Mechanics
Underutilization in European borosilicate glass tubing capacity is pressuring contract manufacturers to accept longer-term offtake commitments at indexed rates, compressing margins for converters while stabilizing input costs for integrated drug-device assemblers.
Pricing Analysis
Cost-plus contracts with FIOLAX-grade borosilicate indexation dominate long-term supply agreements between tubing producers and syringe converters. Pricing stratifies across premium, standard, and economy tiers based on extractables certification depth and ISO 5 cleanroom finishing. Cost compression in polymer disposable platforms is intensifying because hospital procurement consortia are consolidating vendor panels. Generic injectable manufacturers exhibit the highest price sensitivity, while biologics sponsors prioritize elastomer validation libraries over unit cost.
Supply Chain Analysis
Export-control restrictions on advanced polymer extrusion equipment limit technology transfer to emerging conversion markets, constraining local capacity buildout in India and Brazil. Supply concentrates in Germany, China, and the United States for borosilicate tubing, engineered elastomer formulations, and precision molding tooling. The value chain draws from petroleum-derived cyclic olefin monomers, platinum-cured silicone elastomers, and hydrolytic-resistant glass sand. Single-source vulnerability clusters around FIOLAX-grade tubing production in Mainz. Distribution runs through pharmaceutical contract manufacturers and hospital group purchasing organizations with direct-to-filling-site logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from cyclical destocking in biopharma inventory management, with CDSCO alignment in India and EMA MDR implementation in Europe driving replacement demand for qualified primary packaging systems.
For Market Incumbents: Harden technical documentation libraries against EMA MDR clinical evidence requirements by investing in extractables testing infrastructure. Expand backward integration into elastomer compounding to secure supply during energy price volatility in German production clusters. Channel control through exclusive filling partnerships with top-20 biologics sponsors defends margin position against polymer substitution threats.
For New Entrants and Emerging Players: Mid-scale polymer conversion capacity in Gujarat and Maharashtra represents the most penetrable entry point for CDSCO-certified pre-filled syringe supply. Safety syringe platforms for US OSHA compliance offer second-mover advantage with lower regulatory qualification burdens than biologics-grade formats. A go-to-market strategy anchored to domestic Indian vaccine manufacturers' export programs accelerates volume ramp without competing directly with Schott and Gerresheimer in European glass tubing.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across ISO 5 classified cleanroom assembly operations due to 18-24 month commissioning cycles and specialized HVAC infrastructure. Five-to-ten year viability favors acquisition targets with validated combination product dossiers and established technical service presence in at least two regulatory jurisdictions. The signal to watch is CDSCO inspection backlog clearance rates as an indicator of import substitution momentum in Indian pre-filled syringe demand.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA MDR Technical Documentation Investment | Clinical evidence libraries for device constituent parts secure premium positioning in European combination product filings. |
| Backward Integration into Elastomer Compounding | In-house production of platinum-cured silicone stoppers reduces extractables validation burden and supply disruption risk. |
| ISO 11040 Quality Benchmark Alignment | CDSCO compliance creates first-mover advantage in Indian pre-filled syringe procurement tenders. |
| Cleanroom Capacity Expansion in Rhine-Main Cluster | Proximity to Gerresheimer and Schott tubing supply shortens logistics lead times for European drug-device assembly. |
| Integrated Safety System Development | Passive needlestick protection with connectivity modules addresses OSHA mandates and reimbursement tracking requirements. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 483 observations, EMA MDR guidance documents, and CDSCO import alert databases. Primary interviews captured perspectives from regulatory affairs directors at biopharmaceutical sponsors, procurement managers at hospital group purchasing organizations, and technical sales leads at primary packaging converters. Secondary validation drew from USP <661> and <1207> pharmacopeial standards, ISO 11040 series specifications, and REACH chemical registration disclosures. Bottom-up demand modeling triangulated against top-down supply capacity assessments across German, Indian, and Chinese production clusters.
Forecast inputs include drug-device combination product approval trajectories, biologics pipeline migration to subcutaneous administration, and regional regulatory alignment timelines. Segmentation dimensions span material type, product format, end-user setting, and therapeutic application with geographic regulatory cluster overlays. CAGRs were derived from elasticity-adjusted volume projections and value-per-unit trends across premium and standard tiers. Industry-specific inputs incorporate EMA MDR implementation pace and CDSCO inspection capacity expansion.
Practitioners should monitor CDSCO clearance backlogs, EMA notified body capacity constraints, and FIOLAX-grade energy input costs for early signals of supply-demand inflection. Forecasts reflect assumptions regarding sustained biologics pipeline growth and stable pharmacopeial extractables thresholds. Material shifts in USP <661> chemical resistance standards or REACH additive restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Endoscope Protective Barrier Covers Market
Medical Supplies
OTC Braces and Supports Market
Medical Supplies
Amniotic Products Market
Medical Supplies
Veterinary Suture Kit Market
Medical Supplies
Global Adhesive Bandages Market
Medical Supplies
Emesis Bag Market
Medical Supplies
Children's Antipyretic Patch Market
Medical Supplies
Powder-Free Disposable Medical Gloves Market
Medical Supplies
Global Hospital Supplies Market
Medical Supplies
Autoclaving Trays Market
Medical Supplies
Global Urinary Drainage Bags Market
Medical Supplies
Middle East and Africa Hospital Supplies Market
Medical Supplies
Knife Sterilizer Market
Medical Supplies
Surgical Amniotics Market
Medical Supplies
Europe Medical Clothing Market
Medical Supplies
Serum-Free Media Market