
 Plasma Separation Tubes Market | 2026-2036
Plasma Separation Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Plasma Separation Tubes Market Analytics
Phlebotomy technician shortages across North American healthcare networks is redrawing procurement priorities toward pre-analytical automation and single-use consumable reliability. Becton, Dickinson and Company leverages its integrated manufacturing footprint to sustain supply continuity for high-volume hospital systems. Greiner Bio-One International GmbH competes through specialized vacuum tube engineering that dominates European diagnostic laboratory specifications.
Plasma separation tubes are evacuated blood collection devices containing thixotropic separator gels and clot activators, engineered to yield platelet-poor plasma through standardized centrifugation at 1,000–3,000 g for 10–15 minutes. Their primary commercial purpose centers on preserving analyte stability for downstream clinical chemistry, immunoassay, and molecular diagnostic testing. Plastic tubes lead material demand due to breakage resistance and cost scalability, while microfluidics represents the fastest-growing technology segment as point-of-care platforms miniaturize plasma processing. Diagnostic laboratories anchor end-user consumption, though blood banks occupy higher-margin niches requiring specialized additive formulations.
FDA 510(k) clearance pathways and ISO 13485 quality management standards govern tube biocompatibility and performance validation, directly shaping product development timelines and market access costs. The EPA regulates disposal of blood-contaminated plastic consumables, influencing material recyclability investments. Stakeholders must monitor evolving CLSI guidelines for pre-analytical variables as laboratories consolidate and standardize across integrated delivery networks.
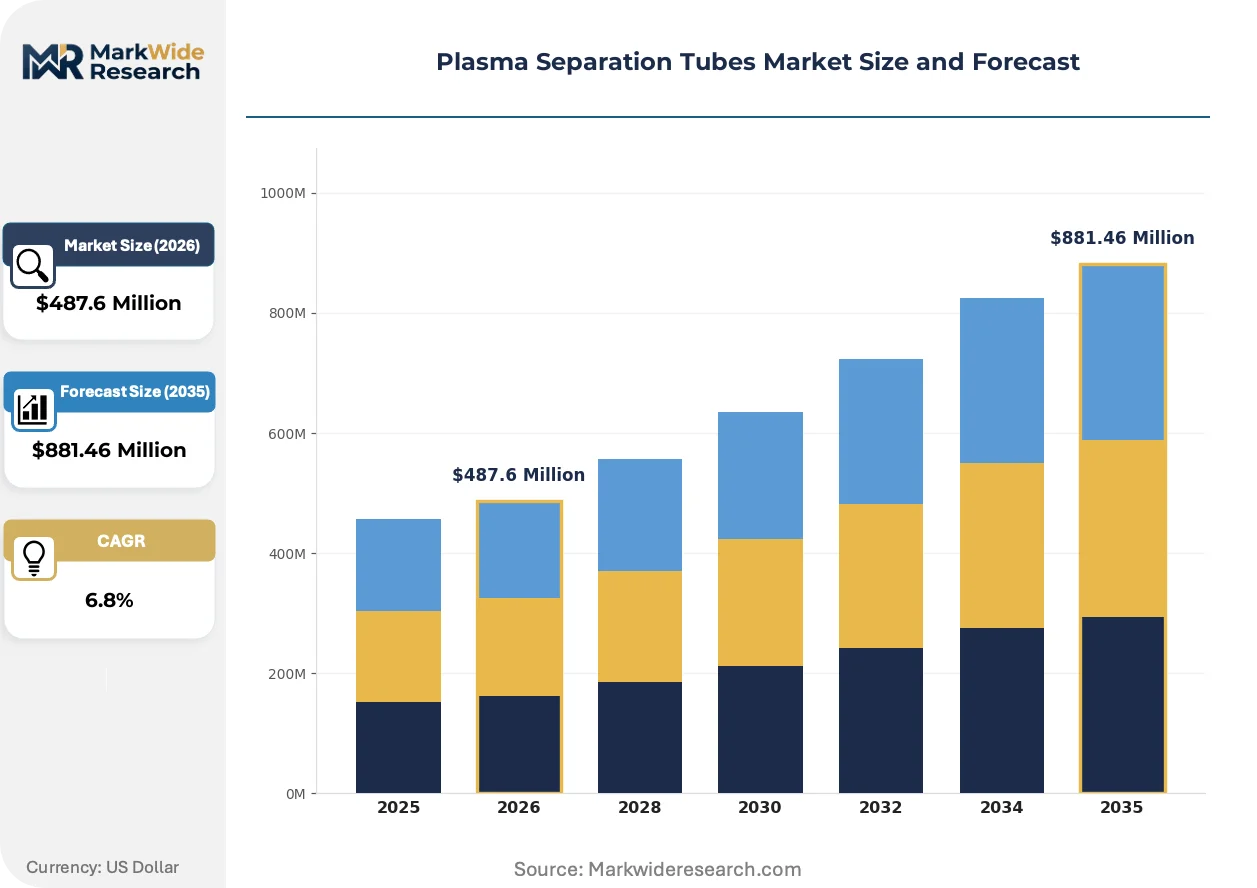
Market Dynamics
Centralized laboratory consolidation across integrated delivery networks is compressing procurement cycles and forcing standardization of consumable specifications, while automated pre-analytical workflows are displacing manual tube handling protocols in high-throughput diagnostic facilities.
Growth Catalysts
- Pre-analytical automation mandates:Hospital systems in the United States are retrofitting core laboratories with robotic sample handling systems that require compatible evacuated tube formats.
- CE marking under EU MDR:Updated medical device regulations in Europe are accelerating replacement cycles for legacy tube inventories as laboratories seek compliant consumable supplies.
- Thixotropic gel chemistry advances:Reformulated separator gel densities are improving plasma yield consistency for molecular diagnostic applications.
Market Restraints
- Petroleum-derived plastic feedstock volatility:Polypropylene and polyethylene resin prices fluctuate with crude oil benchmarks, squeezing margin stability for tube manufacturers.
- Single-source additive dependencies:Proprietary clot activator formulations concentrate supply risk with limited qualified chemical suppliers in Western Europe.
- Silicone contamination thresholds:Stringent analyte recovery requirements for immunosuppressant drug monitoring restrict acceptable separator gel chemistries.
Strategic Opportunities
- Point-of-care microfluidic platforms:Miniaturized plasma separation cartridges for decentralized testing in rural health clinics represent unpenetrated volume.
- Blood bank specialized formulations:Custom additive profiles for transfusion medicine screening command premium positioning in donor center networks.
- Extended stability transport tubes:Cold-chain-independent gel formulations enable specimen referral networks in tropical climates lacking reliable refrigeration infrastructure.
Industry Challenges
- Phlebotomy technician workforce gaps:North American healthcare systems face critical shortages of skilled venipuncture personnel, elevating training costs and error rates.
- ISO 13485 certification timelines:New market entrants encounter 12-18 month quality management system validation periods before commercial access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plasma Separation Tubes Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tube, Syringe, Container, Cartridge Material: Plastic, Glass, Silicone, Polypropylene Technology: Centrifugation, Filtration, Magnetic Separation, Microfluidics End User: Hospitals, Diagnostic Laboratories, Blood Banks, Research Institutions |
| Companies Covered | Becton, Dickinson and Company, Greiner Bio-One International GmbH, SARSTEDT AG & Co. KG, FL Medical S.r.l., Terumo Corporation, Medtronic plc, Sekisui, Guangzhou Improve Medical Instruments Co., Ltd., QIAGEN N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plasma Separation Tubes Market Evolving Landscape
Convergence of materials science and diagnostic workflow engineering is redefining performance benchmarks for evacuated blood collection systems. Three developments warrant particular attention.
Microfluidic plasma separation architectures are decomposing the conventional centrifugation-dependent workflow into cartridge-based formats suitable for near-patient deployment. Community health centers and urgent care chains are piloting these platforms for rapid chemistry panels. The shift is compressing infrastructure requirements for plasma processing and enabling diagnostic access outside traditional laboratory footprints.
REACH restrictions on persistent organic pollutants are compelling reformulation of separator gel plasticizers and tube closure elastomers. Manufacturers serving European diagnostic networks must validate alternative chemistries that maintain thixotropic performance without restricted phthalate compounds. Blood collection tube suppliers with integrated polymer compounding capabilities are accelerating substitution timelines ahead of regulatory deadlines.
Consolidated procurement through group purchasing organizations is compressing supplier negotiation cycles and unbundling technical service from consumable pricing. Integrated delivery networks in the United States are awarding multi-year sole-source contracts predicated on supply continuity guarantees. The restructuring elevates logistics performance and inventory management capabilities above product differentiation in vendor selection criteria.
Plasma Separation Tubes Market Segmentation
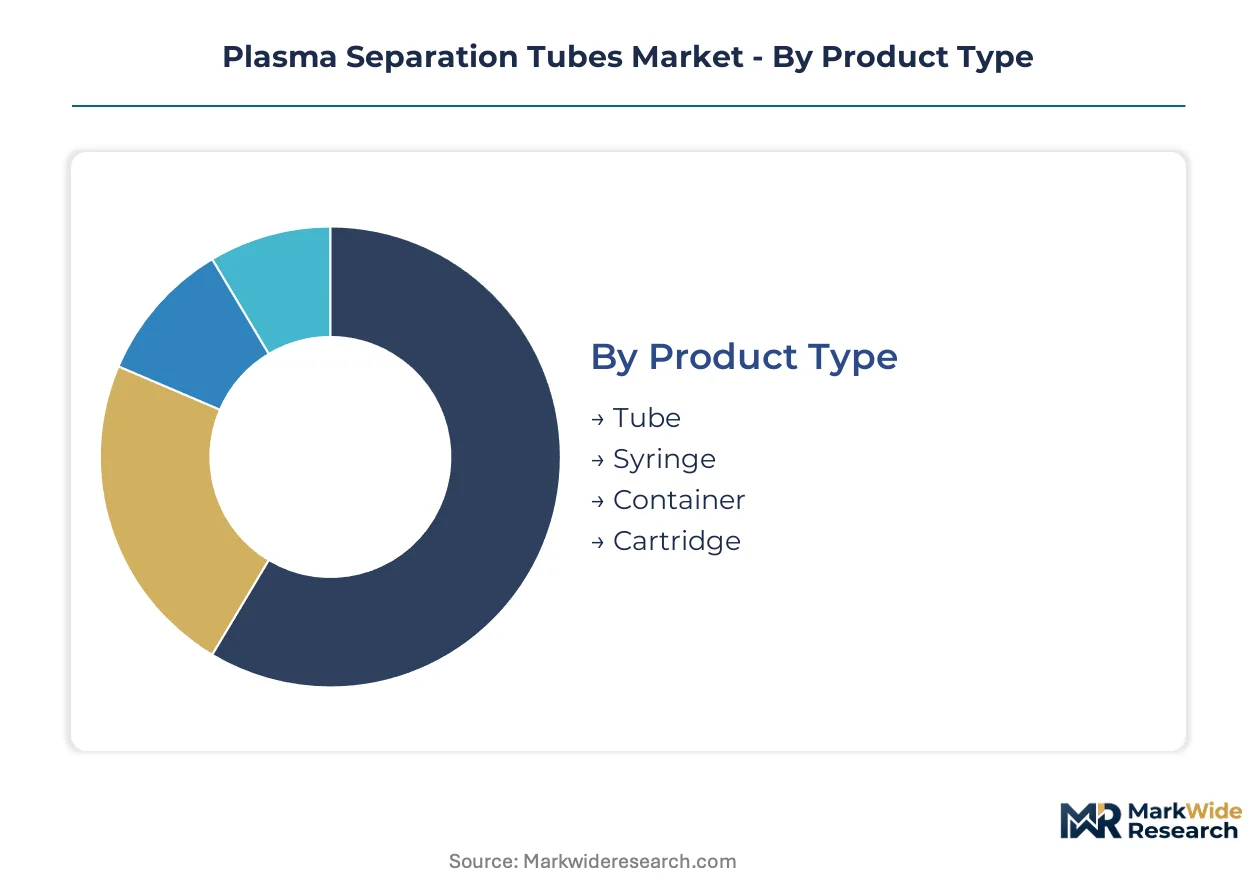
Segmentation in plasma separation tubes reveals how regulatory requirements, workflow automation, and end-use specifications create distinct procurement criteria across product categories. Understanding these divisions enables manufacturers to align formulation investments with validated use cases and compliance pathways.
Product Type:
FDA 510(k) clearance pathways and EU MDR conformity assessments differentiate tube formats based on intended use claims and sterility assurance levels, directly shaping commercial access costs and development timelines.
- Tube:Evacuated cylindrical vessels containing thixotropic separator gels and clot activators remain the dominant format for high-throughput diagnostic laboratories in Germany and the United States. Centralized laboratory networks in these countries specify standardized tube dimensions to ensure compatibility with automated pre-analytical handling systems.
- Syringe:Manual aspiration devices with integrated separation capabilities serve point-of-care settings and phlebotomy technician workflows where vacuum tube systems prove impractical. Rural health clinics in India and community health centers across Brazil prioritize syringe formats for their operational flexibility with limited infrastructure.
- Container:Open-collection vessels for bulk plasma processing accommodate specialized blood bank protocols and research-scale specimen pooling. These formats command premium positioning in donor center networks requiring custom additive profiles.
- Cartridge:Disposable microfluidic housings for miniaturized plasma separation integrate with near-patient testing platforms. Pilot deployments in urgent care chains and tropical climate referral networks validate cold-chain-independent gel formulations.
Established volume favors Tube; emerging adoption favors Cartridge.
Material:
Cost tiers stratify across breakage resistance, chemical compatibility, and recyclability performance, with petroleum-derived feedstock volatility compressing margin stability for polymer-based formats.
- Plastic:Polypropylene and polyethylene formulations dominate commercial procurement due to cost scalability and shatter resistance during automated handling. REACH restrictions on persistent organic pollutants are compelling European manufacturers to reformulate plasticizers and closure elastomers ahead of regulatory deadlines.
- Glass:Borosilicate constructions retain preference for specialized immunosuppressant drug monitoring where silicone contamination thresholds restrict acceptable separator gel chemistries. Blood banks in Switzerland and Japan specify glass for transfusion medicine screening requiring premium analyte recovery.
- Silicone:Elastomer components in tube closures and gel matrices face increasing scrutiny under ECHA substance evaluation protocols. Alternative thixotropic chemistries are accelerating substitution timelines for suppliers with integrated polymer compounding capabilities.
- Polypropylene:Homopolymer and copolymer grades offer tailored clarity and centrifugation stability for molecular diagnostic applications. Resin price fluctuations with crude oil benchmarks concentrate supply risk among manufacturers lacking backward integration into polymer production.
Plastic commands current procurement volume; glass maintains niche premium positioning.
Technology:
Application requirements determine whether laboratories prioritize throughput efficiency, specimen integrity, or decentralized accessibility in plasma processing workflows.
- Centrifugation:Standardized gravitational separation at 1,000–3,000 g for 10–15 minutes anchors clinical chemistry and immunoassay protocols in hospital core laboratories. Automated centrifuge integration in United States health systems mandates compatible tube formats for robotic sample handling.
- Microfluidics:Cartridge-based architectures decompose conventional workflows into miniaturized formats suitable for point-of-care deployment. Community health centers and urgent care chains are piloting these platforms for rapid chemistry panels outside traditional laboratory footprints.
- Filtration:Membrane-based separation accommodates specialized research protocols requiring platelet-depleted plasma without centrifugation infrastructure. Research institutions in academic medical centers specify filtration for proteomics and cell-free DNA applications.
- Magnetic Separation:Paramagnetic bead systems enable targeted cell isolation concurrent with plasma extraction. Blood banks in Saudi Arabia and South Korea are evaluating magnetic approaches for donor screening workflows requiring concurrent cellular component processing.
Centrifugation retains institutional dominance; microfluidics is climbing the fastest among emerging modalities.
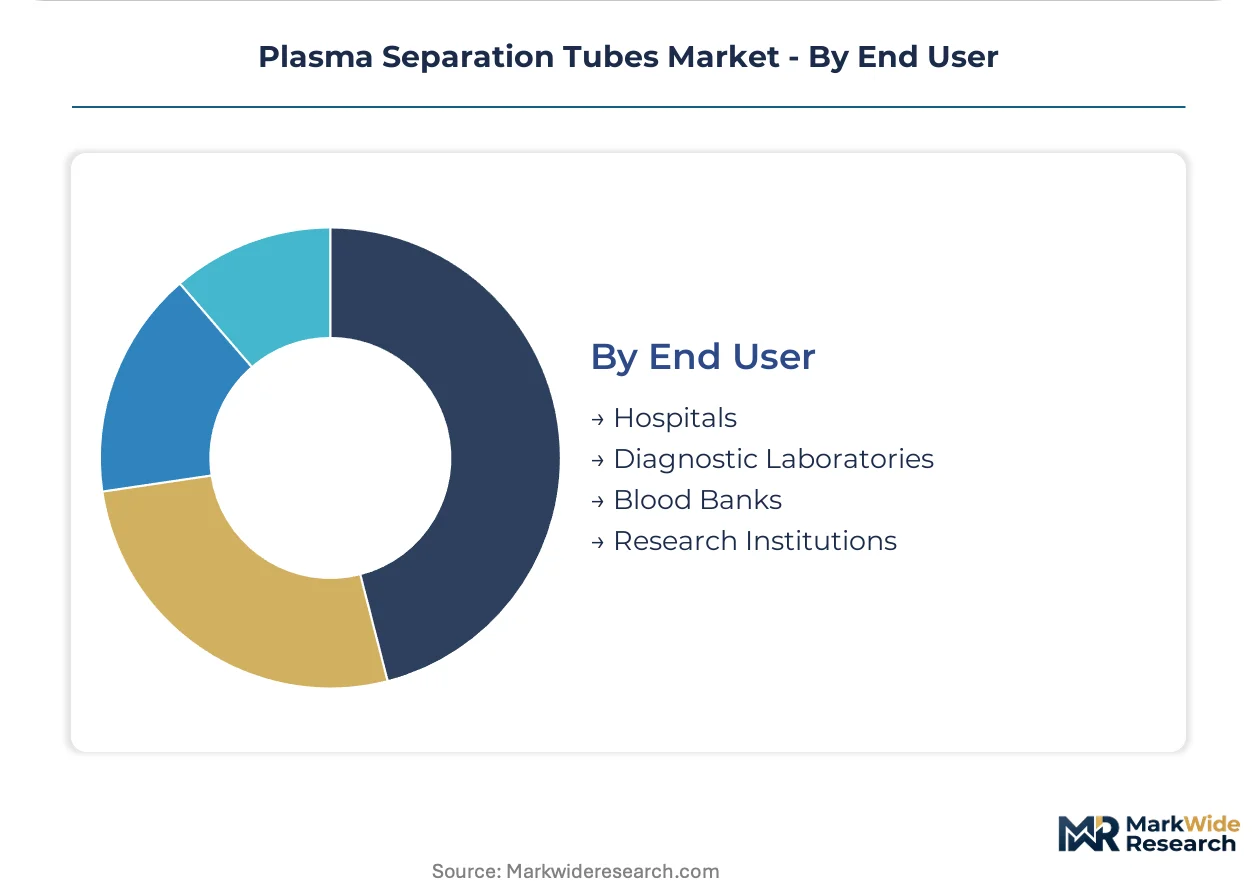
End User:
Customer type dictates specification stringency, with diagnostic laboratories driving standardization while blood banks and research institutions command specialized additive formulations.
- Diagnostic Laboratories:High-throughput facilities in integrated delivery networks consolidate procurement through group purchasing organizations, compressing supplier negotiation cycles and elevating logistics performance above product differentiation. CLSI guideline compliance for pre-analytical variables shapes consumable specifications.
- Hospitals:Inpatient and emergency department phlebotomy workflows face critical technician workforce gaps, redrawing priorities toward single-use consumable reliability and error reduction. United States hospital systems are retrofitting core laboratories with pre-analytical automation requiring compatible evacuated tube formats.
- Blood Banks:Transfusion medicine screening requires specialized additive profiles for donor infectious disease testing and blood component qualification. Custom formulations command premium positioning in donor center networks across Germany, France, and Canada.
- Research Institutions:Academic and commercial research protocols demand extended stability transport tubes for specimen referral networks and multi-site clinical trials. Tropical climate deployments in Brazil and India validate cold-chain-independent gel formulations for unreliable refrigeration infrastructure.
Diagnostic laboratories anchor commercial volume; blood banks capture margin concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. German diagnostic laboratories prioritize standardized tube formats for automated workflows, while Indian rural clinics favor manual syringe systems for infrastructure flexibility. Brazilian research networks drive demand for extended-stability transport solutions in tropical climates.
United States
Hospital systems retrofit core laboratories with robotic sample handling systems that mandate compatible evacuated tube formats. FDA 510(k) clearance pathways govern biocompatibility validation and directly shape product development timelines. The Greater Boston cluster anchors molecular diagnostic applications requiring premium analyte recovery specifications.
Germany
Centralized laboratory networks drive standardization of consumable specifications across integrated delivery systems. EU MDR conformity assessments accelerate replacement cycles for legacy tube inventories as facilities seek compliant supplies. The Rhine-Ruhr metropolitan region concentrates transfusion medicine screening requiring specialized additive formulations.
India
Community health centers prioritize syringe formats for operational flexibility with limited centrifugation infrastructure. CDSCO medical device regulations govern import licensing and quality certification for foreign manufacturers. Maharashtra's diagnostic laboratory networks in Mumbai and Pune pilot microfluidic platforms for decentralized rural testing.
Brazil
Research institutions and multi-site clinical trials validate cold-chain-independent gel formulations for unreliable refrigeration infrastructure. ANVISA pharmaceutical and medical device oversight shapes registration requirements for imported consumables. São Paulo's academic medical centers anchor proteomics and cell-free DNA applications demanding specialized filtration protocols.
Japan
Blood banks specify glass tube constructions for immunosuppressant drug monitoring where silicone contamination thresholds restrict acceptable separator gel chemistries. PMDA quality management standards enforce rigorous performance validation for transfusion medicine applications. The Kansai region around Osaka concentrates donor center networks commanding premium custom formulations.
Plasma Separation Tubes Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the plasma separation tubes market. The upper tier commands supply continuity guarantees through captive polymer compounding and integrated manufacturing footprints. Specialist competitors occupy niche positions through vacuum tube engineering expertise or regional distribution density. Consolidation pressures intensify as group purchasing organizations compress negotiation cycles and elevate logistics performance above product differentiation in vendor selection.
Among integrated multinational manufacturers, Becton, Dickinson and Company and Greiner Bio-One International GmbH exemplify scale-driven archetypes with established quality management certifications. SARSTEDT AG & Co. KG occupies a position within the specialist tier emphasizing engineering precision for European diagnostic specifications. These three anchors represent contrasting strategic postures: vertically integrated supply security versus technical specialization versus regional market depth.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Greiner Bio-One International GmbH |
| SARSTEDT AG & Co. KG |
| FL Medical S.r.l. |
| Terumo Corporation |
| Medtronic plc |
| Sekisui |
| Guangzhou Improve Medical Instruments Co., Ltd. |
| QIAGEN N.V. |
| Others |
Value Network & Pricing Analysis
Sixty-day safety stock requirements for thixotropic gel precursors concentrate procurement leverage with polymer compounders in Germany and the United States, translating directly into tiered pricing power across standard and specialized tube formulations.
Pricing Analysis
Long-term offtake agreements dominate procurement between integrated delivery networks and incumbent manufacturers, with three-year sole-source contracts locking volume commitments in exchange for supply continuity guarantees. Price differentiation separates ISO 13485-certified premium formulations from standard clinical chemistry tubes, while customization levels for blood bank additive profiles command additional positioning. Cost compression in standard plastic formats is intensifying because petroleum-derived resin volatility squeezes margin stability. Hospital systems with automated pre-analytical workflows exhibit lowest price sensitivity, whereas rural community health centers in India and Brazil face acute budget constraints.
Supply Chain Analysis
Proprietary clot activator formulation supply concentrates with qualified chemical suppliers in Western Europe, creating single-source vulnerability for manufacturers lacking backward integration into additive production. Polypropylene resin production draws from petrochemical complexes in Germany, the United States, and Saudi Arabia, with feedstock costs tethered to crude oil benchmarks. Distribution runs through group purchasing organization networks that compress supplier negotiation cycles and elevate logistics performance metrics. REACH restrictions on persistent organic pollutants compound reformulation timelines for European market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
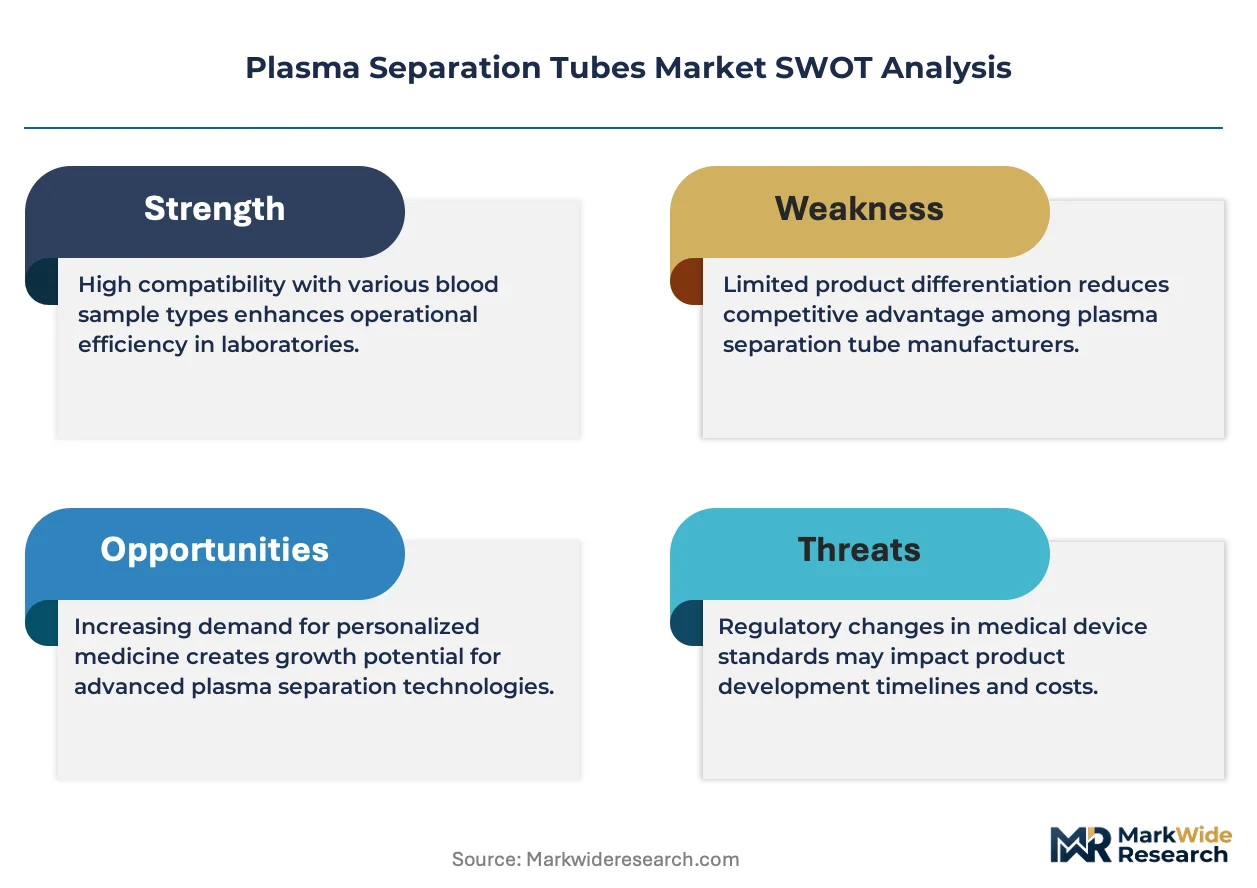
Interoperability between automated pre-analytical handling systems and evacuated tube formats is consolidating procurement around platform-compatible suppliers, rewarding ecosystem depth over standalone product performance.
For Market Incumbents: Secure captive polymer compounding capabilities to insulate margin stability from resin price volatility and accelerate substitution timelines ahead of REACH regulatory deadlines. Defend hospital system relationships through ISO 13485 certification maintenance and supply continuity guarantees that emerging entrants cannot match. Prioritize integration with robotic sample handling platforms to deepen switching costs.
For New Entrants and Emerging Players: Differentiate on microfluidic cartridge architectures for point-of-care deployment where incumbent tube formats prove incompatible with miniaturized workflows. Target urgent care chains and tropical climate referral networks lacking centrifugation infrastructure. Pursue CDSCO and ANVISA registration pathways to access price-sensitive procurement in India and Brazil.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical device parents with under-optimized blood collection divisions lacking integrated polymer capabilities. Long-term viability centers on regulatory navigation expertise and automation compatibility rather than commodity volume scale. Watch FDA 510(k) clearance timelines for microfluidic platforms as signal of platform-shift inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity accelerates replacement cycles for legacy tube inventories across German laboratory networks. |
| Backward Integration into Polymer Compounding | Captive resin formulation insulates margin stability from petroleum feedstock volatility and REACH restriction timelines. |
| Hospital System Partnership | Sole-source contracts with integrated delivery networks lock volume through supply continuity guarantees and automation compatibility. |
| Software Companion Development | Pre-analytical workflow integration with laboratory information systems deepens switching costs for robotic handling platforms. |
| Reimbursement Strategy | Cold-chain-independent gel formulations enable specimen referral network expansion in tropical climates lacking reliable refrigeration. |
Research Methodology
The analysis maps tube, syringe, container, and cartridge sub-sectors, each validated through procurement directors at diagnostic laboratories, biomedical engineers at hospital systems, and regulatory affairs leads at manufacturers. Primary interviews with group purchasing organization contract managers and blood bank technical specialists combined with secondary validation against FDA 510(k) filings, EU MDR conformity assessments, and hospital procurement databases. Bottom-up volume modeling and top-down market sizing triangulated through CLSI guideline documentation and trade flow analysis.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include product format, material grade, separation technology, and end-user specification stringency. CAGRs derived from historical growth rate analysis adjusted for automation adoption curves and regulatory replacement cycle acceleration. Forecast inputs incorporated phlebotomy workforce gap projections and microfluidic platform pilot deployment timelines.
Forecasts assume regulatory continuity in FDA 510(k) and EU MDR regimes; material policy shifts would require re-modeling of commercial access timelines and quality management validation periods. Revision becomes warranted when microfluidic cartridge adoption crosses thresholds that displace conventional centrifugation workflows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Anti-Adhesion Barrier Gels Market
Medical Supplies
Global Needles Market
Medical Supplies
Elbow Splints Market
Medical Supplies
Global Swab and Viral Transport Medium Market
Medical Supplies
Nasal Oxygen Cannula Market
Medical Supplies
Anti Venom Market
Medical Supplies
Chlorhexidine Gluconate (CHG) Wipes Market
Medical Supplies
Luer Plug Market
Medical Supplies
Nasal Splints Market
Medical Supplies
Antibacterial Haemostatic Gels Market
Medical Supplies
Global Medical Foam Market
Medical Supplies
Safety Lancet Market
Medical Supplies
Nitrile Gloves Market
Medical Supplies
Tattoo Needles Market
Medical Supplies
Global Surgical Pledgets Market
Medical Supplies
Micro Vials Market