
 Chlorhexidine Gluconate (CHG) Wipes Market | 2026-2036
Chlorhexidine Gluconate (CHG) Wipes Market Size, Share, and Industry Trends Forecast 2026-2036
Chlorhexidine Gluconate (CHG) Wipes Market Outlook
ISO 13485 certification for medical device quality management is unwinding the competitive landscape, filtering out suppliers lacking validated manufacturing systems. PDI Healthcare leverages extensive hospital distribution networks to sustain placement in surgical prep protocols. 3M anchors its position through proprietary adhesive and antiseptic formulation expertise. Cardinal Health competes on scale, offering CHG wipes within broader infection prevention bundles that reduce procurement complexity for integrated delivery networks.
Chlorhexidine Gluconate wipes are non-woven substrates impregnated with CHG solution, typically at concentrations between 0.5% and 4.0%, designed for preoperative skin antisepsis and ongoing patient bathing to reduce microbial bioburden. The wipes function through sustained antimicrobial activity against gram-positive and gram-negative organisms, with residual protection lasting several hours post-application. Preoperative application leads product type segmentation due to mandatory surgical site infection prevention protocols, while daily care use in intensive care units represents the fastest-growing segment as hospitals adopt universal decolonization strategies. Hospitals dominate end user channels with centralized purchasing power, though home healthcare is gaining traction as post-acute care shifts toward outpatient settings.
FDA 510(k) clearance requirements govern CHG wipes marketed with medical device claims, while EPA regulates disinfectant-only positioning under FIFRA, creating dual jurisdictional complexity for manufacturers. EMA's Medical Device Regulation in Europe imposes additional clinical evidence standards that favor established players with robust quality systems. Healthcare procurement teams must monitor evolving CMS hospital-acquired condition penalty structures, as reimbursement shifts directly influence antiseptic protocol investment and supplier selection criteria.
Market Dynamics
Integrated delivery networks in the United States are consolidating surgical prep procurement into bundled infection prevention contracts, forcing CHG wipe suppliers to demonstrate total protocol cost reduction rather than unit price competitiveness.
Growth Catalysts
- CMS Hospital-Acquired Condition Reduction Program:Financial penalties for surgical site infections drive mandatory preoperative CHG bathing protocols in acute care facilities.
- Non-woven substrate innovations:Advanced fabric engineering improves CHG solution retention and skin adhesion during extended wear periods.
- Intensive care unit decolonization:Universal daily bathing with CHG wipes reduces bloodstream infection rates in mechanically ventilated patients.
Market Restraints
- Isopropyl alcohol supply volatility:Fluctuating petrochemical feedstock costs compress margins for combination CHG-alcohol formulations.
- FDA 510(k) pathway complexity:Dual medical device and disinfectant jurisdiction creates extended regulatory timelines for new product entrants.
- Chlorhexidine allergy prevalence:Documented contact dermatitis cases in surgical populations limit universal patient applicability.
Strategic Opportunities
- Home healthcare transition:Post-surgical patients discharged to outpatient settings require portable antiseptic solutions for incision care.
- EPA Safer Choice certification:Environmental profile differentiation opens institutional procurement channels with sustainability mandates.
- Combination antimicrobial substrates:Integration of CHG with silver nanoparticles or quaternary ammonium compounds addresses resistant organism spectra.
Industry Challenges
- ISO 13485 quality system implementation:Medical device classification demands validated manufacturing processes that smaller suppliers struggle to fund.
- Legacy electronic health record integration:Antiseptic protocol documentation must interface with hospital infection surveillance databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chlorhexidine Gluconate (CHG) Wipes Market |
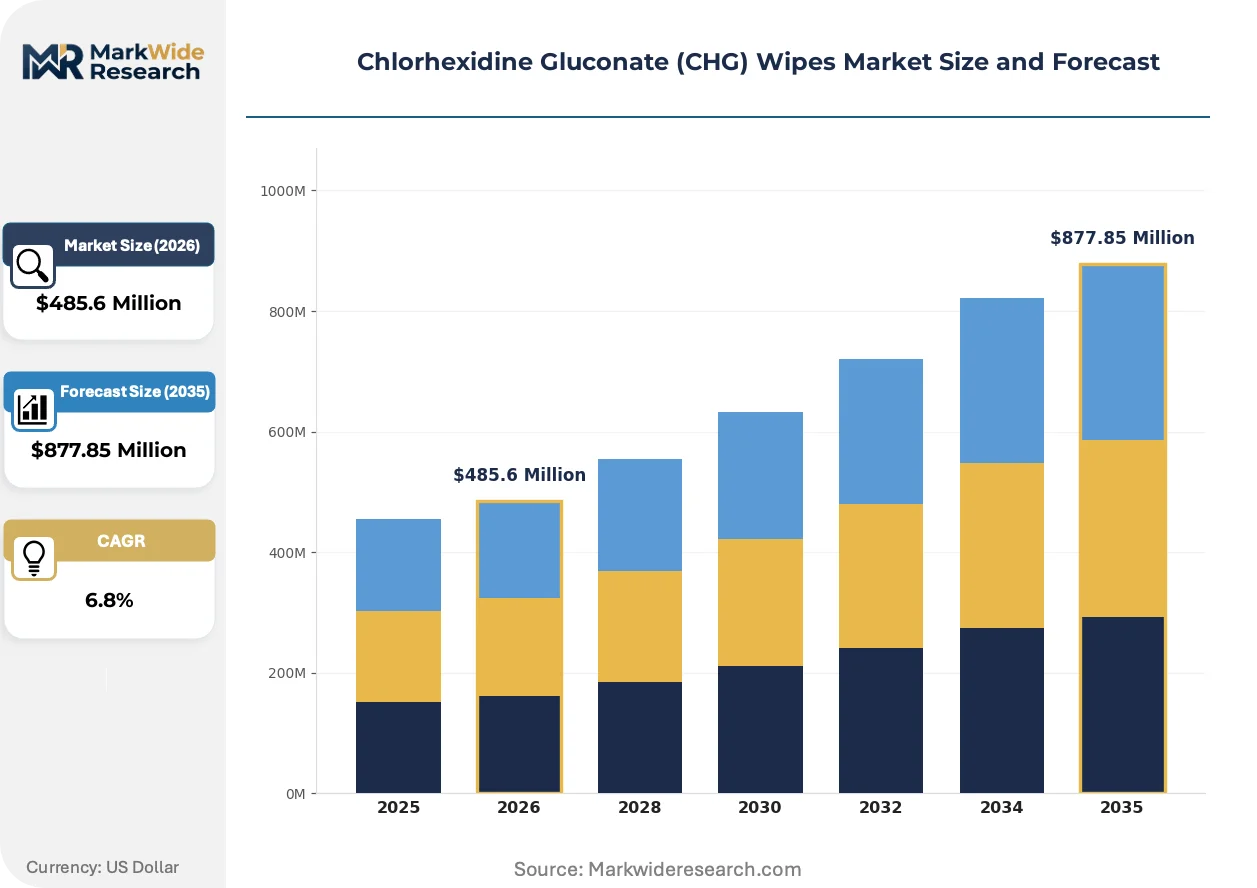
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $877.85 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Preoperative, Postoperative, Daily Care, Infection Control Application: Surgical Prep, Skin Cleansing, Antiseptic Use, Wound Care End User: Hospitals, Clinics, Long-term Care Facilities, Home Healthcare Packaging Type: Individual Packets, Bulk Packs, Canisters, Sachets |
| Companies Covered | Medline Industries, PDI Healthcare, 3M, Ecolab, GAMA Healthcare, Cardinal Health, Becton Dickinson and Company, Johnson & Johnson MedTech, Stryker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chlorhexidine Gluconate (CHG) Wipes Market Strategic Shifts
Antiseptic formulation science and substrate engineering are converging to extend CHG wipe efficacy beyond traditional surgical prep into continuous patient bathing applications.
Water-activated dry wipe formats impregnated with stabilized CHG precursors are displacing pre-moistened towelettes in hospital logistics chains. These products reduce shipping weight, eliminate solution evaporation during storage, and activate upon contact with sterile water at point of care. Supply chain managers in multi-facility systems are adopting dry formats to standardize inventory across climate-variable distribution networks.
EPA's emerging disinfectant resistance monitoring framework is tightening efficacy claim substantiation requirements for surface-compatible CHG products. Manufacturers must now generate kill-time data against specific healthcare-associated pathogens rather than generic gram-positive and gram-negative categories. Wipes positioned for both skin antisepsis and environmental disinfection face dual evidentiary burdens that favor laboratories with established GLP testing infrastructure.
Hospital materials management departments are consolidating antiseptic purchasing through prime vendor distribution agreements that subsume CHG wipes within broader infection prevention categories. This contract structure reduces direct supplier relationships and shifts negotiation leverage toward distributors with formulary control. The concentration of buying authority through group purchasing organizations is most pronounced in the United States, where three major GPOs administer procurement for over seventy percent of acute care beds.
Chlorhexidine Gluconate (CHG) Wipes Market Segmentation
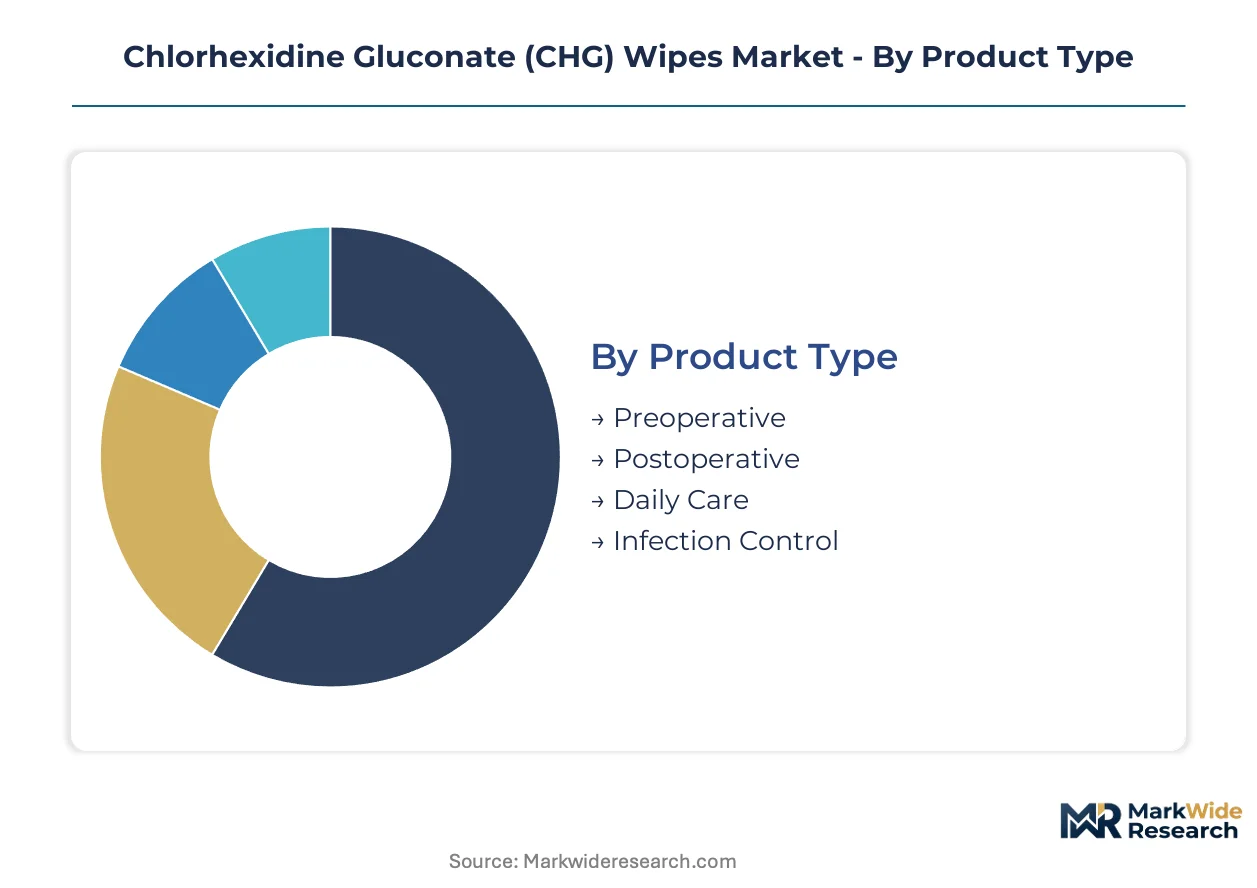
CHG wipe purchasing patterns diverge sharply across clinical settings, with acute care facilities prioritizing bulk efficiency while outpatient and home channels demand portable formats. Understanding these segment boundaries clarifies where formulation investments and distribution partnerships generate returns.
Product Type:
Preoperative wipes dominate domestic hospital procurement, while daily care formats increasingly serve export markets targeting universal decolonization protocols.
- Preoperative:CHG concentrations between 2% and 4% impregnated into non-woven substrates deliver sustained antimicrobial activity for surgical site preparation. United States integrated delivery networks mandate these wipes in bundled infection prevention contracts, with CMS penalty structures directly reinforcing protocol compliance.
- Daily Care:Lower-concentration formulations designed for repeated patient bathing in intensive care units reduce bloodstream infections in mechanically ventilated populations. European hospital systems are adopting these products fastest as EMA Medical Device Regulation clinical evidence requirements favor established suppliers with validated quality systems.
- Postoperative:Transition formats bridging hospital discharge and home recovery address incision site maintenance during wound healing phases.
- Infection Control:Surface-compatible wipes carrying dual skin and environmental claims face EPA FIFRA efficacy substantiation requirements.
Preoperative formats command the established base. The steepest expansion runs through daily care applications.
Application:
Surgical prep concentrates in high-volume tertiary centers, whereas wound care applications fragment across post-acute and retail channels with divergent margin profiles.
- Surgical Prep:Preoperative skin antisepsis requiring FDA 510(k) clearance for medical device claims represents the revenue anchor. United States hospitals consolidate purchasing through prime vendor agreements that subsume these products within broader infection prevention categories.
- Wound Care:Post-surgical incision maintenance and chronic wound management drive outpatient demand. Home healthcare agencies specify portable packaging formats as post-acute care shifts away from institutional settings.
- Skin Cleansing:General patient hygiene applications precede invasive procedures in emergency and ambulatory departments.
- Antiseptic Use:Broad-spectrum microbial reduction for catheter insertion sites and injection preparation spans clinical and consumer segments.
Surgical prep generates volume concentration. Wound care is climbing the fastest as discharge protocols accelerate.
End User:
Hospital procurement centralization contrasts with home healthcare fragmentation, where distributor relationships and reimbursement pathways determine access.
- Hospitals:Centralized materials management departments with formulary control leverage group purchasing organization contracts covering over seventy percent of acute care beds. Three major GPOs dominate United States purchasing, compressing direct supplier relationships.
- Home Healthcare:Post-surgical patients discharged to outpatient settings require portable antiseptic solutions reimbursed through Medicare home health benefit structures.
- Clinics:Ambulatory surgical centers and physician offices with limited storage capacity favor compact packaging configurations.
- Long-term Care Facilities:Skilled nursing facilities managing catheter-associated infection risks adopt daily bathing protocols with variable compliance monitoring.
Hospitals anchor procurement volume. Home healthcare is gaining share fastest as length-of-stay compression continues.
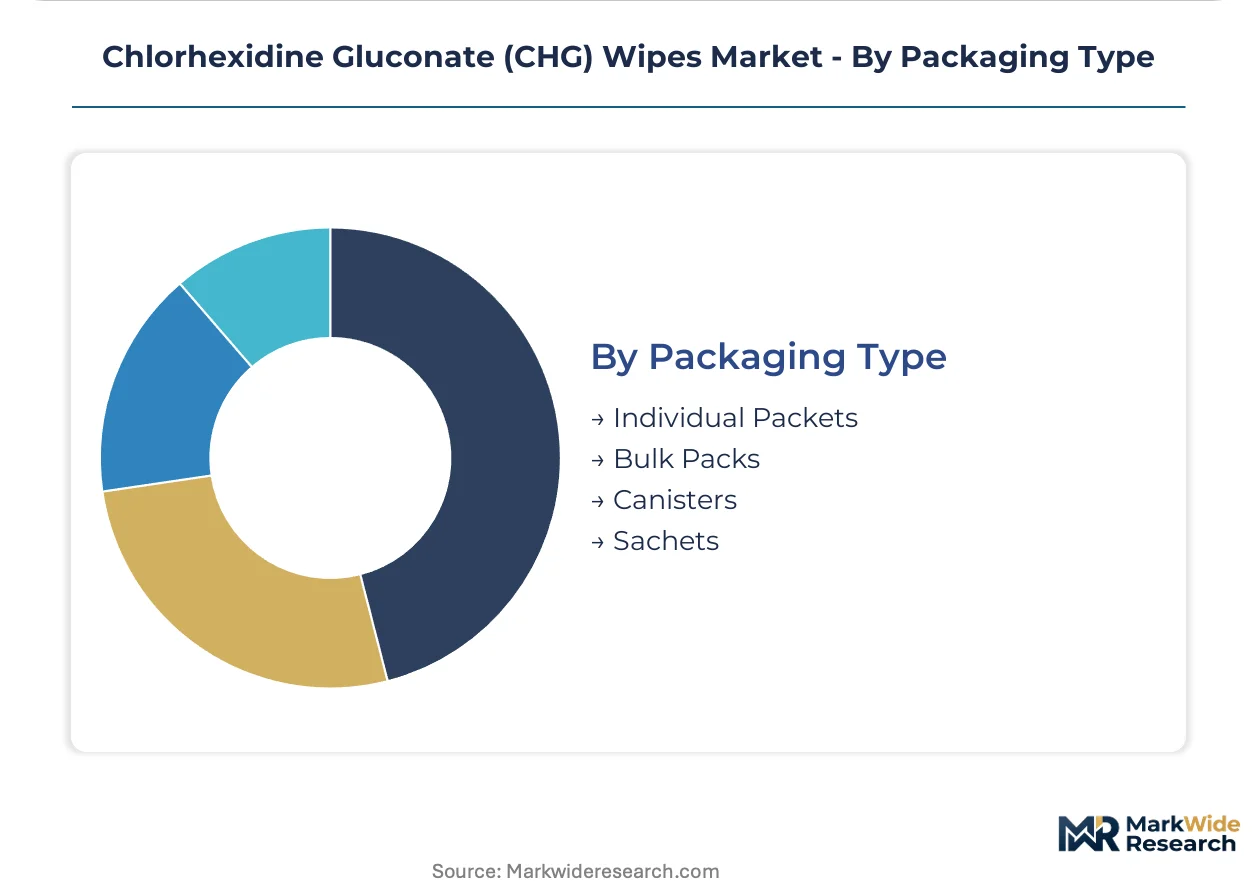
Packaging Type:
Bulk formats align with hospital logistics standardization, while individual packets address climate-variable distribution challenges in extended supply chains.
- Individual Packets:Single-use sterile units eliminate cross-contamination risks in operating theaters. Water-activated dry wipe formats impregnated with stabilized CHG precursors are displacing pre-moistened towelettes to reduce shipping weight and eliminate evaporation.
- Bulk Packs:Multi-count configurations serve high-throughput surgical departments with predictable consumption patterns. These formats minimize per-unit packaging costs but require climate-controlled storage.
- Canisters:Resealable containers with solution reservoirs suit high-frequency access points in nursing stations and emergency departments.
- Sachets:Compact foil packets target travel and retail channels with shelf-stable convenience positioning.
Bulk packs dominate institutional procurement. Individual packets are expanding most quickly as dry formats penetrate multi-facility distribution networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated delivery networks in the United States concentrate CHG wipe procurement through group purchasing organizations covering over seventy percent of acute care beds. Hospital materials management departments in Germany and the United Kingdom are consolidating infection prevention purchasing into prime vendor agreements. Japanese medical device distributors are expanding CHG wipe placement through surgical kit bundling contracts.
United States
CMS Hospital-Acquired Condition Reduction Program penalties drive mandatory preoperative CHG bathing protocols across acute care facilities. FDA 510(k) clearance requirements govern medical device claims for surgical prep wipes, creating extended regulatory timelines for new entrants. The Cleveland Clinic and Mayo Clinic health systems are standardizing CHG wipe protocols across multi-state surgical networks.
Germany
EMA Medical Device Regulation clinical evidence standards favor established suppliers with validated ISO 13485 quality systems for hospital procurement. The German Social Code Book V reimbursement framework incentivizes surgical site infection prevention investments in acute care. Baden-Württemberg's medical technology cluster around Tübingen and Stuttgart hosts CHG wipe distribution hubs serving Central European hospital networks.
United Kingdom
NHS England infection prevention guidelines mandate CHG-based skin antisepsis for high-risk surgical procedures in acute trusts. MHRA medical device registration requirements align with EU MDR standards post-Brexit, maintaining stringent clinical evidence demands. London's teaching hospital consortiums are piloting water-activated dry CHG wipe formats to reduce supply chain weight and storage costs.
Japan
PMDA medical device approval processes require extensive clinical documentation for CHG wipes marketed with surgical prep claims. METI healthcare cost containment policies push hospitals toward bundled infection prevention procurement contracts. The Osaka-Kobe medical device manufacturing corridor supplies CHG-impregnated substrates to domestic hospital distributors and Southeast Asian export markets.
India
CDSCO medical device registration rules are tightening quality standards for imported CHG wipes in tertiary care hospitals. Ayushman Bharat insurance expansion drives surgical volume growth requiring standardized preoperative antisepsis protocols. Maharashtra's Mumbai-Pune hospital corridor represents the highest concentration of CHG wipe consumption in private healthcare facilities.
Chlorhexidine Gluconate (CHG) Wipes Market Competitive Environment
Player mix skews toward diversified medical device conglomerates with established hospital distribution networks. The competitive structure concentrates around three tiers: multinational infection prevention specialists with full protocol portfolios, regional distributors leveraging prime vendor relationships, and emerging dry-format innovators attacking logistics cost structures. Dominant competitive moves include backward integration into non-woven substrate manufacturing and strategic partnerships with group purchasing organizations for formulary placement.
Within the diversified medical device tier, 3M and Cardinal Health exemplify scale-driven positioning through proprietary formulation expertise and bundled infection prevention contracts. PDI Healthcare occupies a specialist position anchored in hospital distribution networks for surgical prep protocol placement. Medline Industries represents the integrated distributor archetype with vertical control over logistics chains serving multi-facility health systems.
| Leading Market Players |
|---|
| Medline Industries |
| PDI Healthcare |
| 3M |
| Ecolab |
| GAMA Healthcare |
| Cardinal Health |
| Becton Dickinson and Company |
| Johnson & Johnson MedTech |
| Stryker |
| Others |
Value Chain & Pricing Dynamics
Prime vendor distribution agreements with group purchasing organizations lock in multi-year formulary placement and price visibility for CHG wipe suppliers serving United States integrated delivery networks. These contract structures bundle antiseptic products into infection prevention categories, compressing direct supplier relationships while securing volume commitments that stabilize manufacturing capacity utilization.
Pricing Analysis
Cost-plus contracts indexed to isopropyl alcohol feedstock costs dominate combination CHG-alcohol formulations, transferring petrochemical volatility risk to hospital buyers. Pricing stratifies across FDA 510(k)-cleared surgical prep tiers, ISO 13485-certified medical device grades, and standard disinfectant-only positioning. Cost compression in economy-grade disinfectant wipes is intensifying as EPA FIFRA claim substantiation requirements raise testing burdens. Ambulatory surgical centers exhibit the highest price sensitivity due to limited storage capacity and sporadic consumption patterns, while tertiary hospitals with centralized materials management prioritize protocol compliance over unit cost.
Supply Chain Analysis
The United States and Germany anchor non-woven substrate manufacturing for CHG wipe production, with Japan supplying specialized fabric engineering for water-activated dry formats. Supply chains draw from petrochemical feedstocks for isopropyl alcohol, cellulose pulp for substrate bases, and pharmaceutical-grade CHG active pharmaceutical ingredients. Single-source vulnerability concentrates in FDA-registered contract manufacturing organizations with validated sterile production lines. Distribution runs through three major group purchasing organizations administering procurement for over seventy percent of United States acute care beds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where FDA 510(k) clearance and ISO 13485 certification create switching costs that protect incumbent positions. Hospital formulary control and GPO contract concentration amplify this defensive moat.
For Market Incumbents: Secure backward integration into non-woven substrate manufacturing to capture margin compression from petrochemical volatility. Deepen prime vendor relationships with multi-facility health systems before EPA disinfectant resistance monitoring frameworks tighten evidentiary requirements for dual skin-environment claims. For New Entrants and Emerging Players: Differentiate on water-activated dry wipe formats that reduce shipping weight and eliminate climate-controlled storage requirements. Target home healthcare agencies managing post-surgical incision care through Medicare-reimbursed portable antiseptic solutions, bypassing GPO-controlled hospital procurement. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors ISO 13485-certified specialists with established GLP testing infrastructure. Long-term viability hinges on regulatory compliance capabilities rather than formulation innovation alone. Watch EPA Safer Choice certification adoption rates as the signal indicating sustainability-mandated institutional procurement channel expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Medical device classification unlocks surgical prep formulary placement in United States hospitals. |
| ISO 13485 Quality System Implementation | Certification filters out undercapitalized competitors from European hospital procurement channels. |
| Group Purchasing Organization Partnership | Formulary control through three dominant GPOs secures volume across seventy percent of acute care beds. |
| Water-Activated Dry Format Development | Stabilized CHG precursors reduce logistics costs for multi-facility distribution networks. |
| EPA Safer Choice Certification | Environmental profile differentiation opens procurement channels with institutional sustainability mandates. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EPA FIFRA registrations, hospital procurement databases, and CMS Medicare cost reports. Interviews with infection prevention specialists, biomedical engineers, GPO contracts managers, and supply chain directors at integrated delivery networks informed demand-side validation. Bottom-up triangulation across product type, application, end user, and packaging segments converged with top-down macroeconomic calibration.
Segmentation dimensions modeled include product concentration tiers, clinical application settings, procurement channel structures, and regional regulatory frameworks across the analysis window. CAGRs derive from installed base expansion in intensive care unit decolonization protocols and surgical volume growth trajectories. Forecast inputs incorporate CMS hospital-acquired condition penalty structures and EMA Medical Device Regulation compliance timelines.
Material uncertainties — petrochemical feedstock volatility, FDA regulatory pathway delays, chlorhexidine allergy prevalence documentation — sit outside the modeled envelope. Forecasts reflect assumptions about sustained reimbursement pressure for surgical site infection prevention. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Healthcare Adhesive Tapes Market
Medical Supplies
Medical Gloves Market
Medical Supplies
Asia Pacific Medical Rubber and Balloon Product Market
Medical Supplies
Drainage Bottles Market
Medical Supplies
Suture Sleeve Kit Market
Medical Supplies
Dental Emergency Kit Market
Medical Supplies
Amniotic Membrane Market
Medical Supplies
Cryotubes Market
Medical Supplies
Gingival Retraction Kits Market
Medical Supplies
Butterfly Needle Sets Market
Medical Supplies
Trauma Products Market
Medical Supplies
Blood Preparation Market
Medical Supplies
Single-Use Sterilization Wraps Market
Medical Supplies
United States Face Mask Market
Medical Supplies
Scintillation Vials Market
Medical Supplies
Prepackaged Medical Kits and Trays Market