
 Anaesthesia Conduction Kits Market | 2026-2036
Anaesthesia Conduction Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Anaesthesia Conduction Kits Market Outlook
China is reshaping supply dynamics through expanded domestic manufacturing of polymer-based medical components for regional kit assembly. B. Braun Medical leverages captive injection-molding capacity to control raw material flows across European distribution. Teleflex Incorporated anchors its position through specialized catheter technology embedded within nerve block configurations. Smiths Medical competes on automated assembly lines that reduce particulate contamination risks in cleanroom environments.
Anaesthesia conduction kits are sterile, pre-configured procedural packages containing needles, catheters, syringes, drapes, and antimicrobial skin preparation agents assembled for peripheral nerve block or neuraxial anaesthesia delivery. These kits integrate hydrophobic barrier materials and Luer-lock compatibility standards to maintain aseptic technique during ultrasound-guided or landmark-based regional anaesthesia. Single-use kits dominate volume due to infection control mandates, while ultrasound-guided technology captures premium positioning as visualization adoption spreads across teaching hospitals. Pain management applications sustain faster expansion than general surgery segments, reflecting outpatient clinic diversification and chronic pain protocol expansion.
FDA 510(k) clearance pathways and EMA Medical Device Regulation (MDR) classification rules determine market entry timelines and clinical evidence requirements for kit manufacturers. ISO 13485 quality management certification operates as a baseline procurement filter across integrated health systems in Germany and the United States. Stakeholders must monitor evolving EPA sterilization gas emissions rules and state-level surgical center licensing standards that could alter kit configuration requirements and distribution economics.
Market Dynamics
Ultrasound-guided regional anaesthesia is collapsing the traditional landmark-based procedural paradigm, forcing kit manufacturers to reconfigure needle and catheter geometries for real-time visualization compatibility while ambulatory surgical centers absorb procedural volume shifts from inpatient settings.
Growth Catalysts
- Outpatient procedural expansion:Ambulatory surgical centers in the United States are standardizing nerve block protocols for same-day discharge orthopaedic procedures, driving kit consumption per facility upward.
- EMA MDR sterilization mandates:Stricter ethylene oxide residual limits and packaging integrity requirements are accelerating replacement cycles for legacy kit inventories across European hospital systems.
- Polymer barrier technology:Hydrophobic drape materials with integrated antimicrobial zones are penetrating teaching hospital procurement specifications, differentiating premium kit configurations from commodity alternatives.
Market Restraints
- Ethylene oxide supply volatility:EPA emissions restrictions on sterilization gas production are constraining terminal sterilization capacity for polypropylene-based kit components, particularly affecting mid-tier manufacturers without captive ethylene oxide sources.
- Chinese polymer concentration:Domestic production of medical-grade polypropylene and polycarbonate for regional kit assembly has concentrated upstream supply risk within East Asian chemical processing corridors.
- Reusable instrument substitution:Metal spinal needles with autoclavable handles retain footholds in cost-constrained public hospital systems in India and Brazil, limiting single-use kit penetration.
Strategic Opportunities
- Chronic pain clinic diversification:Dedicated pain management facilities in Germany and Australia are expanding neuraxial catheter placement for long-term opioid-sparing protocols, creating demand for extended-dwell kit configurations.
- FDA 510(k) streamlined review:Predicate device pathways for ultrasound-compatible needle designs are compressing regulatory timelines for kit innovators targeting the United States market entry.
- Direct-to-facility distribution:Integrated delivery networks are consolidating vendor relationships, creating openings for manufacturers with ERP-integrated inventory management systems to displace distributor intermediaries.
Industry Challenges
- Cleanroom technician scarcity:Automated assembly line operation and particulate monitoring in ISO 14644 Class 7 environments require specialized workforce training that outpaces technical education pipeline output in Midwestern United States manufacturing clusters.
- ISO 13485 certification timeline:Quality management system audits for kit manufacturers expanding into European distribution face 12-18 month backlogs at notified bodies, delaying market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anaesthesia Conduction Kits Market |
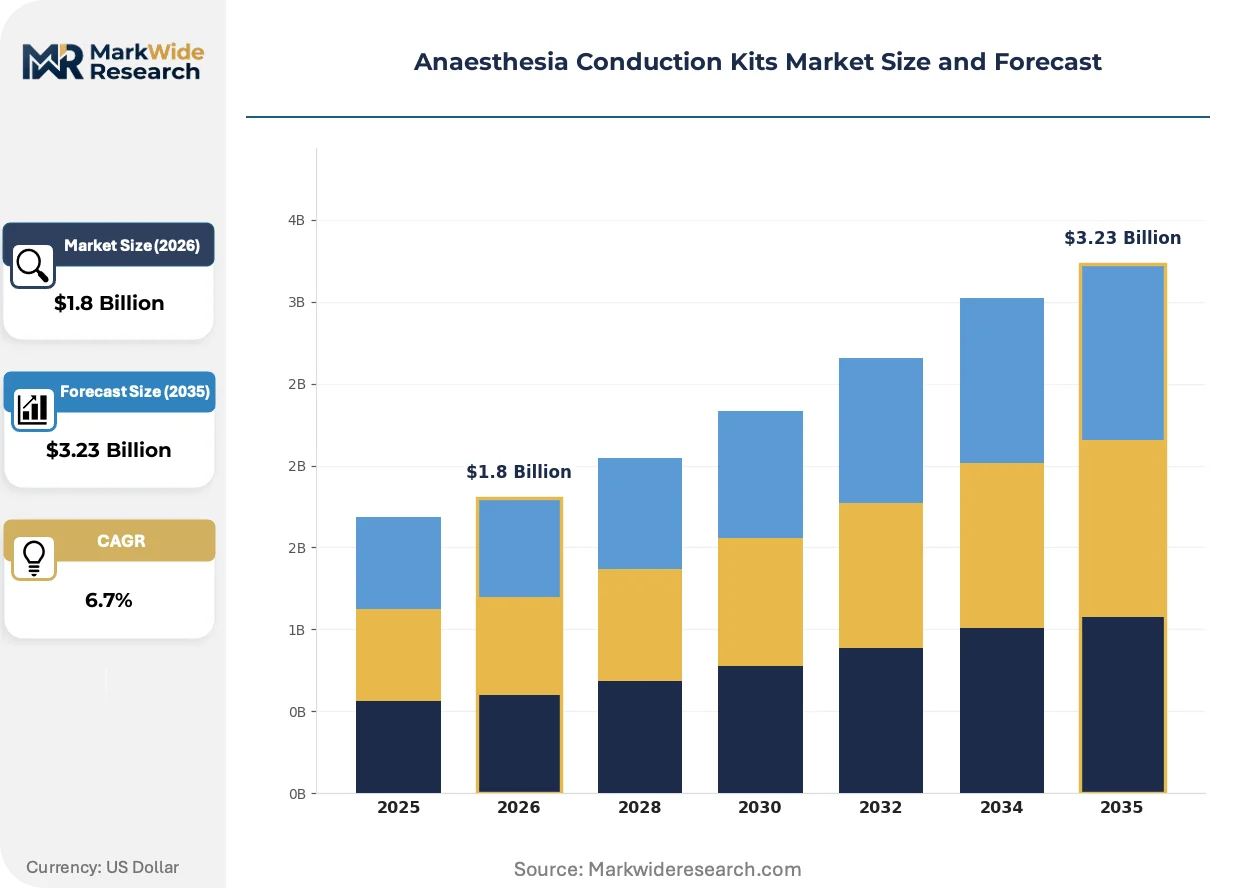
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use Kits, Reusable Kits, Specialty Kits, Pediatric Kits Application: General Surgery, Orthopedic Surgery, Dental Procedures, Pain Management End User: Hospitals, Surgical Centers, Dental Clinics, Pain Clinics Technology: Ultrasound-Guided, Textbook Techniques, Nerve Blocks, Intravenous Techniques |
| Companies Covered | B. Braun Medical, Epimed International, Teleflex Incorporated, Smiths Medical, Koninklijke Philips, BK Ultrasound, Medtronic, Ambu, ICU Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anaesthesia Conduction Kits Market Strategic Shifts
Real-time visualization technology is collapsing the skill barrier for regional anaesthesia placement, while regulatory sterilization standards and procurement consolidation are simultaneously reshaping kit configuration economics and distribution pathways.
Echo-enhancing needle coatings with microscopic air-entrapment surfaces are collapsing the tactile feedback dependency that historically defined procedural training curves. Teaching hospitals in the United States and United Kingdom are adopting these configurations for resident education programs, compressing the learning interval for femoral and brachial plexus blocks from months to weeks. The structural consequence is enabling ambulatory surgical centers to deploy regional anaesthesia protocols without dedicated academic anaesthesia departments.
EMA Medical Device Regulation classification rules are reclassifying neuraxial kits from Class I to Class IIa, imposing clinical evidence requirements that smaller manufacturers cannot satisfy without notified body partnerships. German and French hospital procurement consortiums are responding by consolidating supplier lists to five or fewer approved vendors, filtering out regional kit assemblers lacking MDR technical documentation resources. The segment most affected is mid-tier spinal anaesthesia configurations, where documentation gaps are forcing portfolio rationalization.
Integrated delivery networks are consolidating anaesthesia supply contracts across multi-hospital systems, replacing individual facility purchasing autonomy with centralized formulary committees. Distributor relationships are compressing as direct manufacturer agreements capture volume commitments, particularly visible in United States Midwest and Southeast regional networks where IDN penetration exceeds sixty percent of acute care beds. The channel shift is privileging kit manufacturers with national logistics infrastructure over regional distributors.
Anaesthesia Conduction Kits Market Segmentation
Kit configuration diversity reflects divergent clinical workflows across inpatient and outpatient settings. Manufacturers must align sterile barrier specifications, needle geometries, and catheter compatibility with distinct procedural environments and reimbursement structures.
Product Type:
After-sales service intensity varies sharply across product lifecycles, with reusable kits demanding calibration protocols and single-use configurations requiring reverse logistics for expired inventory.
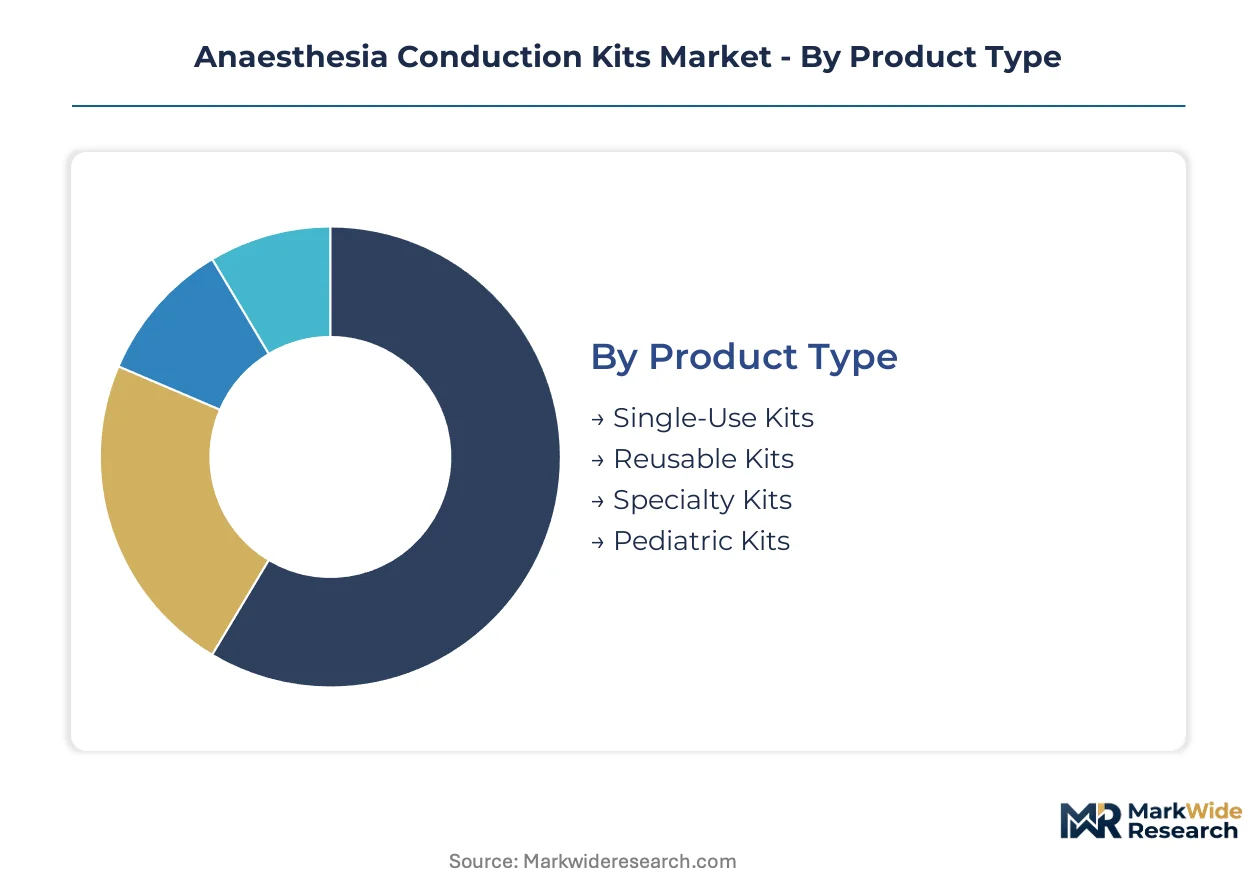
- Single-Use Kits:Pre-sterilized disposable assemblies containing needles, catheters, syringes, and antimicrobial drapes eliminate cross-contamination risks. Demand concentrates in United States ambulatory surgical centers where Joint Commission infection control mandates drive procurement specifications. FDA 510(k) clearance requirements for sterile packaging integrity create compliance barriers for new entrants.
- Reusable Kits:Metal spinal needles with autoclavable handles and detachable catheter components support multi-procedure utilization. Demand persists in Indian and Brazilian public hospital systems where capital constraints override disposable preferences. Autoclave infrastructure availability and technician training gaps limit penetration in rural facilities.
- Specialty Kits:Configurations optimized for neuraxial anesthesia or continuous peripheral nerve blocks incorporate echogenic needles and closed-system catheter connectors.
- Pediatric Kits:Reduced-gauge needles and volume-calibrated syringes address anatomical constraints in neonatal and pediatric populations.
Single-Use Kits holds the largest share; momentum sits with Specialty Kits.
Application:
Cost tier stratification separates high-volume commoditized procedures from premium-priced chronic pain interventions requiring extended catheter dwell capabilities.
- General Surgery:Standardized spinal and epidural configurations dominate laparotomy and cesarean section workflows. Demand concentrates in German university hospitals where EMA MDR Class IIa reclassification has consolidated supplier lists to five approved vendors. Sterilization documentation requirements filter out mid-tier assemblers lacking notified body partnerships.
- Pain Management:Extended-dwell neuraxial catheter kits with antimicrobial impregnation support opioid-sparing protocols in chronic pain clinics. Australian and German dedicated pain facilities are expanding neuraxial placement volumes. Reimbursement coding for outpatient catheter management creates sustainable revenue streams distinct from acute care episodes.
- Orthopedic Surgery:Ultrasound-guided peripheral nerve block kits facilitate same-day discharge protocols for joint replacement and fracture repair.
- Dental Procedures:Inferior alveolar nerve block configurations with short-bevel needles address maxillofacial anesthesia requirements.
General Surgery commands volume leadership; Pain Management is climbing the fastest.
End User:
Customer type determines purchasing autonomy, with integrated delivery networks centralizing formulary decisions while independent clinics retain direct vendor relationships.
- Hospitals:Multi-specialty acute care facilities maintain diverse kit inventories across neuraxial, peripheral, and central line configurations. United States Midwest and Southeast regional networks where IDN penetration exceeds sixty percent of acute care beds are consolidating contracts. ERP-integrated inventory management capabilities privilege manufacturers with national logistics infrastructure over regional distributors.
- Surgical Centers:Ambulatory facilities standardizing nerve block protocols for orthopedic same-day discharge are driving per-facility consumption upward. United States outpatient procedural volume shifts from inpatient settings accelerate kit utilization. Ultrasound-guided technology adoption spreads without dedicated academic anesthesia departments.
- Pain Clinics:Dedicated facilities in Germany and Australia expanding neuraxial catheter placement for long-term protocols.
- Dental Clinics:Standalone oral surgery practices with localized procurement autonomy.
Hospitals retain procurement volume dominance; Surgical Centers are gaining share fastest.
Technology:
Volume concentration tilts toward visualization-enabled methods as ultrasound equipment penetration reshapes training curricula and procedural competency requirements.
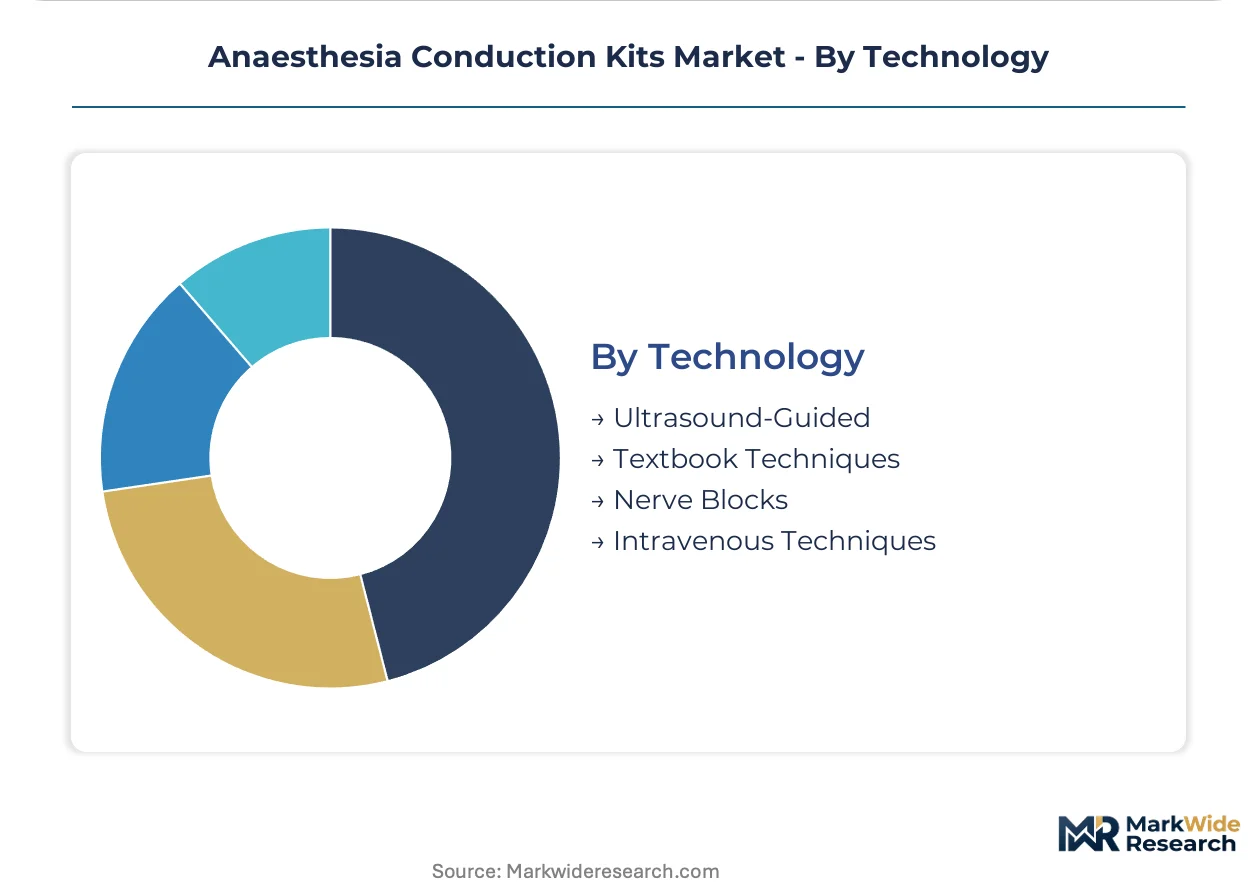
- Ultrasound-Guided:Real-time visualization compatibility demands echogenic needle coatings and catheter geometries optimized for probe manipulation. Teaching hospitals in the United States and United Kingdom are adopting echo-enhancing configurations for resident education. The structural consequence enables ambulatory surgical centers to deploy regional anesthesia without academic department infrastructure.
- Nerve Blocks:Landmark-based peripheral techniques retain utility in resource-constrained settings lacking ultrasound capital investment. Indian and Brazilian public systems limit single-use kit penetration through metal needle autoclavable alternatives. Tactile feedback dependency historically defined procedural training curves now compressing with visualization adoption.
- Textbook Techniques:Palpation-based anatomical landmark approaches for neuraxial access.
- Intravenous Techniques:Bier block and intravenous regional anesthesia configurations for extremity procedures.
Nerve Blocks maintains installed base leadership; Ultrasound-Guided shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States acute care networks deploy anaesthesia conduction kits at triple the per-procedure intensity of German university hospitals, driven by ambulatory surgical center expansion and ultrasound-guided protocol standardization rather than inpatient neuraxial volume alone.
United States
Integrated delivery networks across the Midwest and Southeast consolidate formulary decisions for sixty percent of acute care beds, privileging manufacturers with ERP-integrated inventory systems. FDA 510(k) clearance pathways for ultrasound-compatible needle designs compress regulatory timelines for market entrants. The Greater Boston medical device corridor anchors catheter technology development for nerve block configurations.
Germany
University hospitals drive demand for extended-dwell neuraxial kits supporting chronic pain opioid-sparing protocols. EMA MDR reclassification from Class I to Class IIa imposes clinical evidence requirements that filter supplier lists to five approved vendors. The Rhine-Ruhr manufacturing belt concentrates polymer processing capacity for medical-grade polypropylene kit components.
China
Domestic production of medical-grade polymers for regional kit assembly reshapes upstream supply dynamics away from import dependency. NMPA medical device registration rules tighten sterilization documentation requirements for ethylene oxide residual limits. The Yangtze River Delta chemical processing corridor concentrates polypropylene and polycarbonate production for East Asian kit manufacturers.
Australia
Dedicated pain management facilities expand neuraxial catheter placement volumes for long-term outpatient protocols. TGA medical device standards align with ISO 13485 quality management certification as baseline procurement filters across public hospital systems. Sydney and Melbourne metropolitan clusters concentrate chronic pain clinic infrastructure driving kit consumption.
India
Public hospital systems retain metal spinal needle autoclavable alternatives, constraining single-use kit penetration through capital constraints rather than clinical preference. CDSCO medical device rules increasingly harmonize with ISO standards for sterile barrier packaging integrity. Maharashtra and Gujarat industrial corridors develop domestic polymer conversion capacity for regional kit assembly.
Anaesthesia Conduction Kits Market Competitive Environment
Capability concentration sits with catheter technology specialists; scale advantage sits with diversified medical device conglomerates possessing captive polymer processing and continental distribution infrastructure. The vendor base stratifies across three tiers: integrated multinationals with backward polymer control, mid-cap regional assemblers with notified body partnerships, and commodity distributors lacking sterile manufacturing certification. Dominant competitive moves include M&A activity targeting ultrasound-compatible needle technology and capacity expansion into ISO 14644 Class 7 cleanroom environments for automated kit assembly.
Within the diversified medical technology tier, B. Braun Medical and Teleflex Incorporated exemplify archetypes of polymer supply chain control and specialized catheter positioning respectively. Smiths Medical occupies a position representing automated manufacturing scale for particulate-sensitive cleanroom production. These three entities anchor the competitive structure through distinct capability vectors rather than overlapping strategic positioning.
| Leading Market Players |
|---|
| B. Braun Medical |
| Epimed International |
| Teleflex Incorporated |
| Smiths Medical |
| Koninklijke Philips |
| BK Ultrasound |
| Medtronic |
| Ambu |
| ICU Medical |
| Others |
Value Chain & Pricing Dynamics
Chinese medical-grade polypropylene concentration in the Yangtze River Delta chemical corridor anchors upstream cost structures for kit manufacturers, concentrating margin pools with European and North American assemblers possessing captive sterilization infrastructure and MDR technical documentation capabilities.
Pricing Analysis
Long-term offtake agreements between integrated delivery networks and kit manufacturers dominate procurement structures, compressing spot-market participation to emergency replenishment scenarios. Three-tier pricing structure across premium, standard, and economy levels separates ultrasound-compatible echogenic configurations from commodity landmark-based kits, with ISO 13485 certification and FDA 510(k) clearance acting as tier gatekeepers. Pricing pressure stems from EMA MDR compliance costs filtering mid-tier assemblers from approved vendor lists. Ambulatory surgical centers exhibit highest price sensitivity due to fixed reimbursement ceilings, while German university hospitals absorb premium positioning for extended-dwell neuraxial configurations.
Supply Chain Analysis
Export-control scrutiny on advanced polymer processing equipment limits technology transfer to emerging kit assembly markets, constraining sterilization-grade polypropylene production expansion outside established chemical corridors. China, Germany, and the United States concentrate medical-grade polymer feedstock supply for regional kit manufacturing. Raw material flows draw from propylene cracking capacity, ethylene oxide sterilization gas production, and hydrophobic barrier film extrusion. Single-source vulnerability concentrates in Chinese polycarbonate supply for catheter hubs. Distribution runs through integrated delivery network ERP-integrated inventory systems displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue streams from catheter management protocols and sterile barrier compliance consulting expand faster than hardware kit sales, creating recurring revenue architectures that outpace transactional procurement cycles.
For Market Incumbents: Entrench position through backward integration into ethylene oxide sterilization capacity and ISO 14644 Class 7 cleanroom automation, countering EPA emissions restrictions that threaten terminal sterilization access for competitors lacking captive gas sources. Expand MDR technical documentation partnerships to absorb mid-tier assemblers exiting European markets due to notified body audit backlogs. For New Entrants and Emerging Players: Pursue white-space opportunities in Australian chronic pain clinic neuraxial catheter placement and Indian domestic polymer conversion for regional kit assembly, where capital constraints limit incumbent penetration. Target pain management applications with extended-dwell configurations, leveraging streamlined FDA 510(k) predicate pathways for ultrasound-compatible needle designs to compress regulatory timelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated cleanroom assembly lines, favoring acquisition targets with existing ISO 13485 certification and notified body relationships over greenfield capacity builds. Monitor EPA ethylene oxide emissions rulemaking as inflection signal for sterilization capacity scarcity and distressed asset availability among mid-tier manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Partnership | EMA Class IIa reclassification filters supplier lists to five approved vendors across German hospital procurement consortiums. |
| Captive Ethylene Oxide Sterilization | EPA emissions restrictions constrain terminal sterilization capacity for polypropylene-based kit components without captive gas sources. |
| ERP-Integrated Inventory Management | Integrated delivery networks consolidate vendor relationships, privileging manufacturers with direct-to-facility distribution capabilities. |
| Echogenic Needle Coating Development | Echo-enhancing configurations compress resident training intervals from months to weeks across United States teaching hospitals. |
| Extended-Dwell Catheter Configuration | Australian and German pain clinics expand neuraxial placement volumes for long-term opioid-sparing protocols. |
Study Parameters
Operator-level perspectives from anaesthesiologists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers anchored the qualitative base, triangulated against FDA 510(k) clearance databases, EMA MDR technical documentation filings, hospital procurement contract records, and ISO 13485 certification registries. Bottom-up facility-level kit consumption estimates combined with top-down polymer feedstock demand analysis across medical-grade polypropylene and polycarbonate processing corridors.
Scenario-bracketing around EPA sterilization gas emissions trajectories and EMA notified body audit backlog durations framed the analytical approach across the projection horizon. Segmentation dimensions modeled include kit configuration type, procedural application, end-user facility category, and visualization technology adoption pattern. CAGRs derived from procedure volume elasticity to ambulatory surgical center expansion and ultrasound equipment penetration curves.
Sensitivities concentrate around EPA ethylene oxide production restrictions, Chinese polymer export licensing shifts, and EMA MDR implementation enforcement intensity. Material shifts in sterilization capacity availability or regulatory classification thresholds would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Emergency Transfer Vacuum Mattress Market
Medical Supplies
Arterial Blood Collection Market
Medical Supplies
Amniotic Membrane Market
Medical Supplies
Australia Hospital Supplies Market
Medical Supplies
Pressure Monitoring Extension Tubing Sets Market
Medical Supplies
Western Europe Sterile Gloves Market
Medical Supplies
Medical Procedure Tray Market
Medical Supplies
Thermal Printable Wristband Market
Medical Supplies
Centrifuge Bottles Market
Medical Supplies
Europe Ultrasound Gels Market
Medical Supplies
Ear and Nasal Packing Market
Medical Supplies
Disposable Medical Gloves Market
Medical Supplies
Flexible Packaging for Healthcare Market
Medical Supplies
Sterile IV Containers Market
Medical Supplies
Single-Use Syringe Market
Medical Supplies
Asia-Pacific N95 Mask Market