
 Europe Medical Clothing Market | 2026-2036
Europe Medical Clothing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Medical Clothing Market Foresight
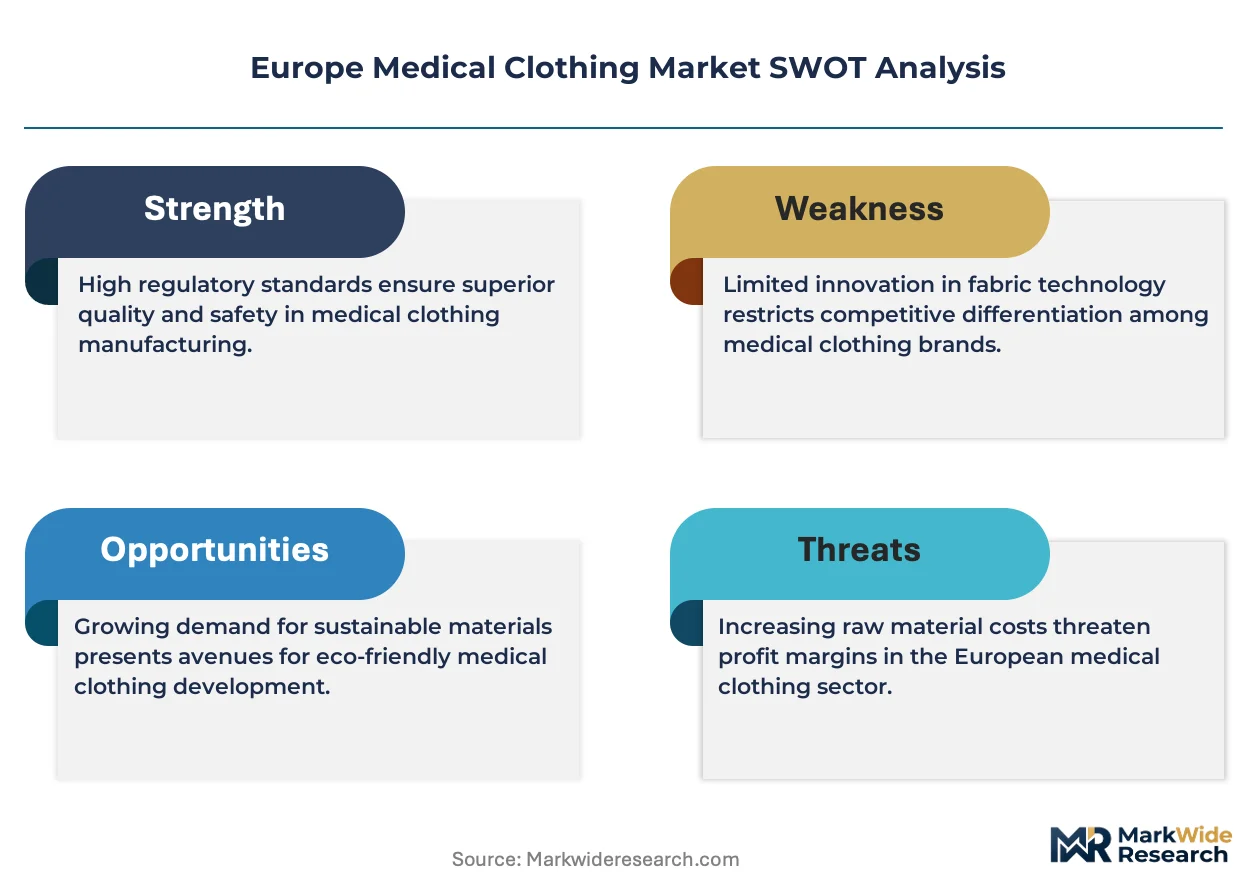
Asset-light leasing models for surgical textile services are reshaping competitive dynamics in Europe. Mölnlycke Health Care leverages its Nordic manufacturing base to sustain high-volume gown supply chains. Paul Hartmann anchors its position through backward integration into non-woven fabric production. Cardinal Health competes via direct hospital contracting networks that bypass traditional distributor markups.
Medical clothing encompasses garments engineered for infection prevention, fluid barrier protection, and occupational safety in clinical environments, typically constructed from spunbond-meltblown-spunbond polypropylene laminates or treated cotton-polyester blends meeting EN 13795 standards for surgical drapes and gowns. Surgical gowns command the largest revenue pool due to mandatory single-use protocols in invasive procedures, while scrubs represent the fastest-growing category as outpatient surgical volumes expand across European day clinics. Non-woven fabrics dominate material selection for critical zones where liquid penetration resistance is paramount, though cotton-polyester blends retain share in lower-risk settings where breathability and repeated sterilization cycles matter.
EMA coordinates pharmacovigilance frameworks that indirectly shape clinical apparel standards, while the EU MDR and CE marking requirements enforce biocompatibility and barrier performance testing for garments classified as medical devices. REACH compliance constrains chemical treatments used in antimicrobial fabric finishes, pushing manufacturers toward physical barrier innovations rather than biocidal coatings. Stakeholders must monitor how the EU AI Act and impending digital product passport mandates will trace supply chain provenance for reusable textile fleets.
Market Dynamics
Hospital procurement teams across Germany, France, and the UK are consolidating vendor relationships around asset-light leasing models for surgical textile services, compressing traditional distributor margins while elevating manufacturers with direct contracting capabilities and Nordic manufacturing scale.
Growth Catalysts
- EU MDR compliance mandates:The Medical Device Regulation tightens conformity requirements for protective apparel classified as medical devices, forcing hospital systems to upgrade inventory and creating replacement demand for certified garments meeting biocompatibility and barrier performance standards.
- Day clinic expansion:Outpatient surgical volumes across France, Spain, and Italy are accelerating scrub consumption as ambulatory care centers multiply and require high-turnover apparel for rotating clinical staff.
- Reusable gown program adoption:German acute care facilities are expanding circular textile services to reduce waste disposal costs and align with EU Green Deal circular economy targets, sustaining demand for durable cotton-polyester blends.
Market Restraints
- Polypropylene feedstock volatility:Spunbond-meltblown-spunbond laminate production depends on petrochemical inputs whose price swings compress margin predictability for non-woven surgical gown manufacturers.
- REACH chemical constraints:The European Chemicals Agency restricts antimicrobial fabric finishes, eliminating biocidal coating options and forcing investment into physical barrier R&D with uncertain performance equivalence.
- Single-use protocol lock-in:Invasive procedure standards in UK and French hospitals maintain disposable gown requirements, limiting addressable market for reusable textile service providers despite sustainability pressures.
Strategic Opportunities
- Digital product passport readiness:Impending EU mandates for supply chain traceability will reward early movers with RFID-tagged reusable textile fleets and blockchain-verified sterilization records.
- Eastern European hospital modernization:Polish and Romanian healthcare infrastructure investment is opening day clinic and acute care procurement channels previously dominated by Western European suppliers.
- EU AI Act integration:Automated quality inspection systems for gown barrier testing can capture compliance documentation advantages as artificial intelligence regulation tightens medical device verification requirements.
Industry Challenges
- CE marking timeline compression:EU MDR transition deadlines are straining notified body capacity, extending certification queues for new gown designs and freezing product launch schedules.
- Legacy ERP integration friction:Hospital procurement platforms require API connectivity for real-time inventory tracking, forcing textile service providers to rebuild software stacks around HL7 FHIR standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Medical Clothing Market |
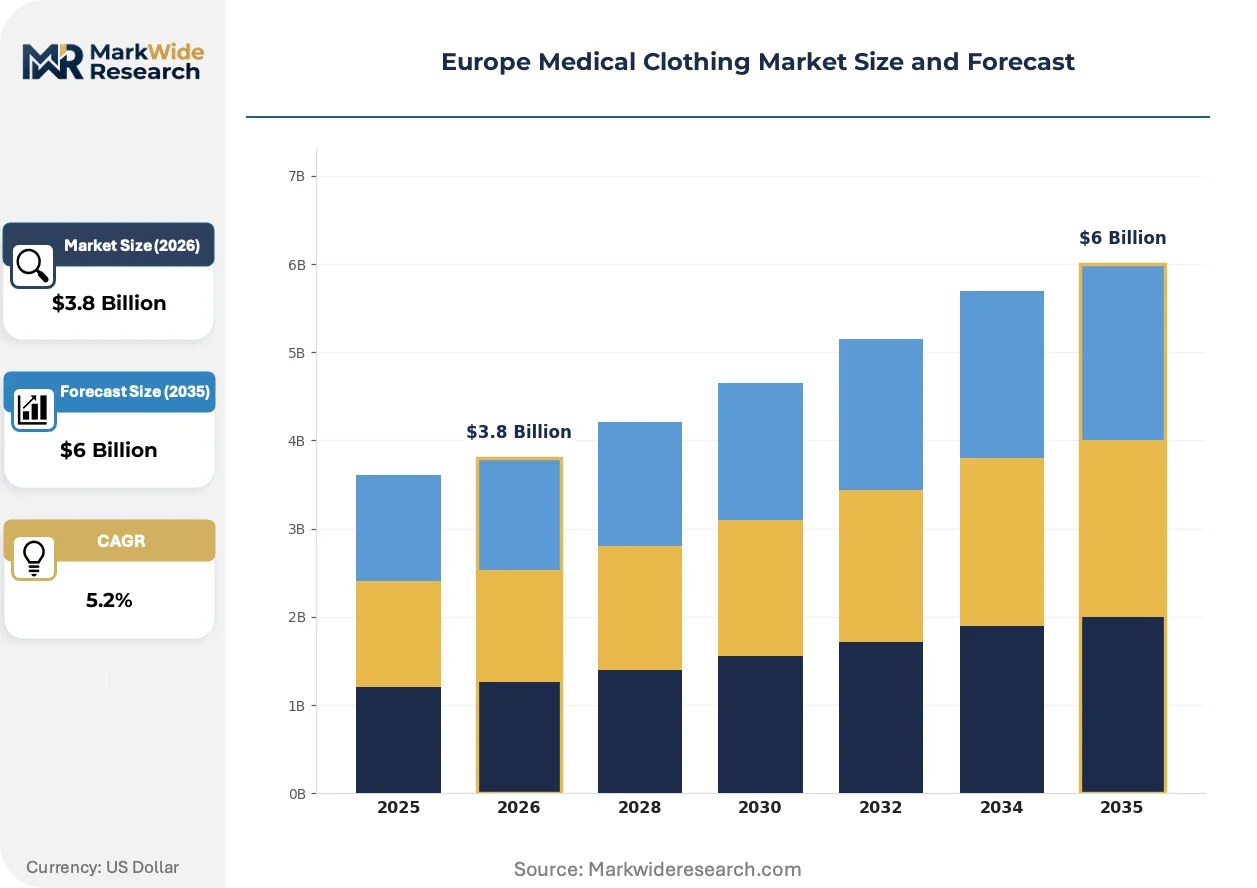
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Gowns, Scrubs, Lab Coats, Isolation Gowns End User: Hospitals, Clinics, Laboratories, Home Care Distribution Channel: Online Retail, Direct Sales, Wholesalers, Pharmacies Material: Cotton, Polyester, Non-Woven Fabrics, Blends |
| Companies Covered | Mölnlycke Health Care, Semperit AG Holding, Smith & Nephew, B. Braun Melsungen, Cardinal Health, Drägerwerk, Paul Hartmann, Lohmann & Rauscher, Surgical Holdings, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Medical Clothing Market Shifts & Advancements
Material science breakthroughs and regulatory digitization are converging to reshape competitive positioning in European medical apparel, with sustainability mandates and procurement centralization acting as twin accelerants of vendor consolidation.
Biodegradable spunbond-meltblown-spunbond laminates derived from polylactic acid are collapsing the waste disposal cost structure for single-use surgical gowns. German university hospitals in Berlin and Munich are piloting these materials at scale. The technology is collapsing landfill diversion timelines from decades to months, enabling compliance with national packaging waste regulations ahead of schedule.
REACH is tightening restrictions on per- and polyfluoroalkyl substances used in liquid-repellent textile treatments. Industrial laundries serving Dutch and Belgian hospital networks are accelerating plasma-based hydrophobic finishing as a substitute chemistry. Surgical gown manufacturers with captive coating capabilities are absorbing reformulation costs faster than outsourced producers, widening competitive gaps.
Centralized purchasing cooperatives in France and Italy are disintermediating regional distributors through direct manufacturer contracts with price-indexed volume commitments. The Groupement des Achats Hospitaliers in Paris and Consip in Rome are consolidating scrub and gown procurement for multi-hospital systems. French public hospital networks are visibly consolidating supplier panels from twelve vendors to three preferred partners with integrated logistics coverage.
Europe Medical Clothing Market Segmentation
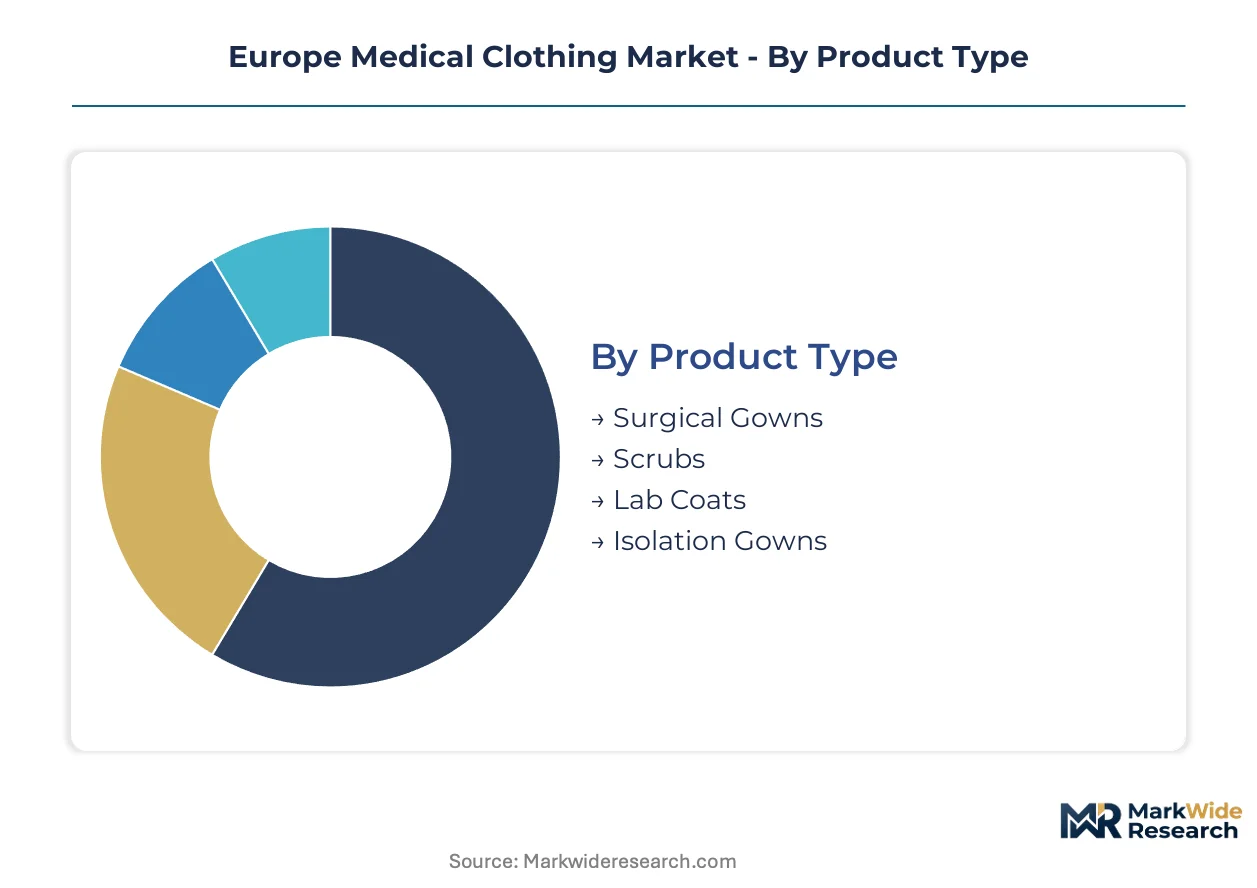
Segmentation in European medical clothing reveals how procurement priorities diverge across clinical settings. Material selection and distribution channel choices directly reflect infection control protocols, sustainability mandates, and supply chain restructuring pressures.
Product Type:
Use-case spectrum spans sterile invasive procedures through general clinical protection, with barrier performance requirements dicting material investment and replacement frequency.
- Surgical Gowns:Spunbond-meltblown-spunbond polypropylene laminates meeting EN 13795 critical zone standards. German acute care facilities drive demand through mandatory single-use protocols in operating theaters, though reusable programs are gaining traction under EU Green Deal targets.
- Scrubs:Cotton-polyester blends or non-woven disposables designed for high-turnover outpatient environments. Day clinics across France, Spain, and Italy are expanding scrub consumption fastest as ambulatory surgical volumes multiply and staff rotation intensifies.
- Lab Coats:Mid-weight cotton or treated polyester providing basic fluid resistance for diagnostic and research settings. Laboratories in UK university hospitals maintain steady replacement cycles.
- Isolation Gowns:Non-woven disposable or reusable woven barriers for contact precaution scenarios. Demand concentrates in infectious disease wards responding to seasonal respiratory surges.
Established volume favors surgical gowns; emerging adoption favors scrubs.
End User:
Customer type determines procurement scale, with consolidated purchasing power reshaping vendor relationships across facility tiers.
- Hospitals:Multi-department procurement coordinating surgical, scrub, and isolation apparel through centralized contracts. German hospital networks are consolidating vendor panels to capture volume discounts and streamline CE marking compliance documentation.
- Clinics:Smaller-scale purchasing with higher price sensitivity and faster delivery requirements. French and Italian day surgery centers are expanding most quickly, driving scrub category expansion.
- Laboratories:Specialized demand for chemical-resistant and static-controlled garments. Research clusters in Cambridge and Leiden sustain niche procurement channels.
- Home Care:Emerging segment for protective apparel in domiciliary nursing and patient self-management. Growth remains constrained by reimbursement fragmentation across EU member states.
Procurement concentration sits with hospitals; flexibility requirements favor clinics.
Distribution Channel:
Margin structure shifts as direct manufacturer contracting displaces traditional distributor intermediaries.
- Direct Sales:Manufacturer-to-hospital contracts with price-indexed volume commitments and integrated logistics. Groupement des Achats Hospitaliers in Paris and Consip in Rome are accelerating this channel.
- Online Retail:E-procurement platforms enabling small-lot ordering with transparent pricing. Growing fastest among independent clinics and home care segments seeking procurement autonomy.
- Wholesalers:Traditional regional distributors facing margin compression as hospital systems consolidate purchasing. Surviving players are adding sterilization and inventory management services.
- Pharmacies:Limited channel for consumer-facing protective apparel and basic scrubs. Retail pharmacy networks in Germany retain minor share for individual healthcare workers.
Direct sales capture volume; online retail captures fragmentation.
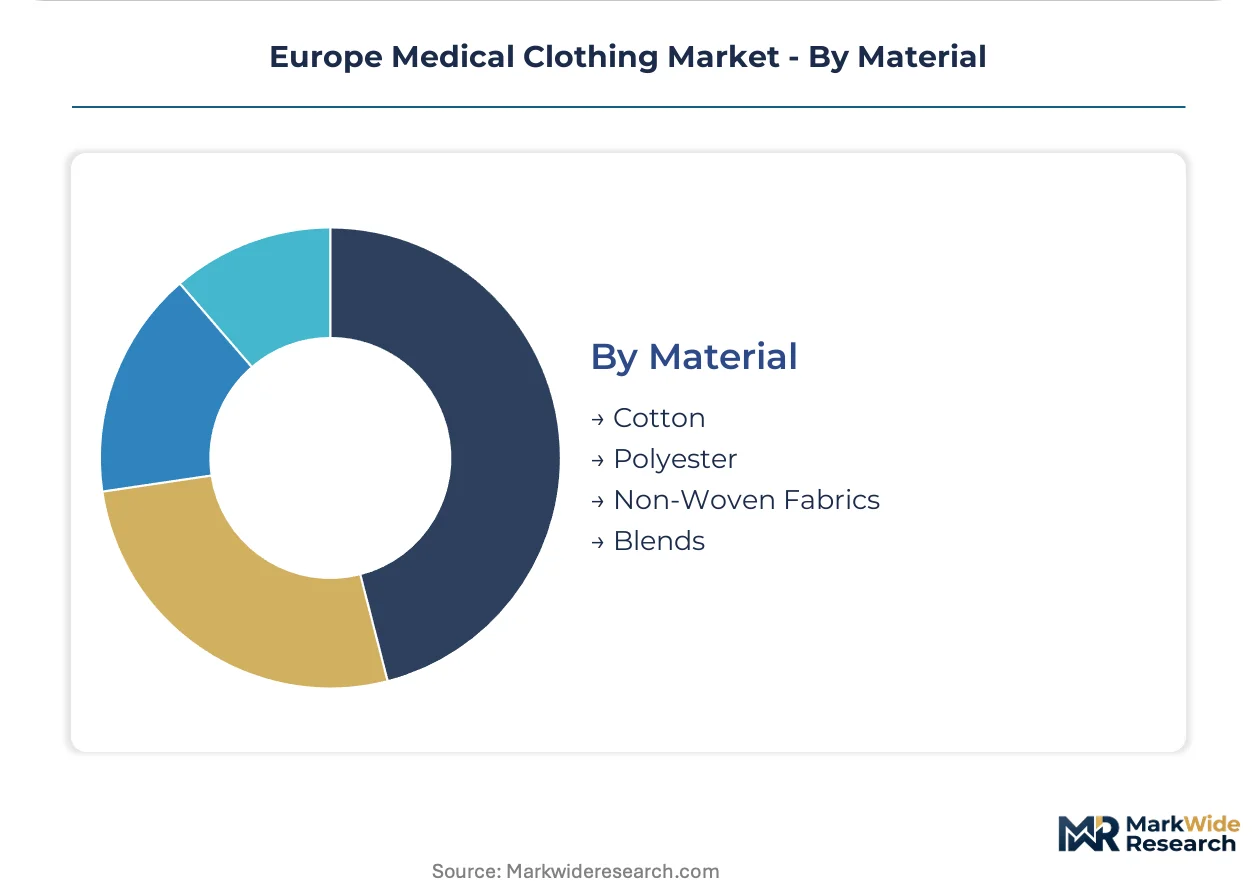
Material:
Cost tier and performance trade-offs define material selection, with regulatory chemistry constraints forcing innovation in barrier technologies.
- Non-Woven Fabrics:Spunbond-meltblown-spunbond polypropylene laminates delivering liquid penetration resistance for critical zones. REACH restrictions on per- and polyfluoroalkyl substances are forcing plasma-based hydrophobic finishing investments.
- Blends:Cotton-polyester combinations balancing breathability with repeated sterilization durability. German reusable gown programs favor this material for circular textile service models.
- Cotton:Natural fiber retaining share in lower-risk settings where comfort and launderability outweigh barrier performance. Dutch hospital laundries process significant cotton-polyester volumes.
- Polyester:Synthetic base for chemical-resistant and static-controlled applications in laboratory environments. Leiden research facilities specify polyester-dominant lab coats.
Non-woven fabrics dominate critical protection; blends dominate sustainability transitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal circular economy targets and EU MDR compliance deadlines are redirecting procurement budgets toward certified reusable textile services and biodegradable single-use alternatives across member state hospital systems.
Germany
Acute care facilities in Berlin and Munich are scaling reusable surgical gown programs to meet national packaging waste reduction mandates. The EU MDR transition is forcing hospital procurement teams to consolidate vendor panels for CE marking documentation efficiency. Bavarian medical textile laundries are investing in RFID-tracked circular fleets to capture digital product passport readiness.
France
The Groupement des Achats Hospitaliers is disintermediating regional distributors through direct manufacturer contracts with price-indexed volume commitments. REACH restrictions on per- and polyfluoroalkyl substances are accelerating plasma-based hydrophobic finishing adoption in Lyon textile processing clusters. Day surgery centers in Paris and Marseille are expanding scrub consumption fastest as ambulatory volumes multiply.
United Kingdom
NHS procurement consolidation is compressing traditional distributor margins while elevating manufacturers with direct contracting capabilities. Single-use protocol lock-in for invasive procedures maintains disposable gown requirements in London teaching hospitals. Cambridge research laboratories sustain niche demand for chemical-resistant lab coats.
Italy
Consip in Rome is consolidating scrub and gown procurement for multi-hospital systems under centralized purchasing cooperatives. Outpatient surgical volumes in Milan and Rome day clinics are accelerating high-turnover apparel demand. Italian hospital networks are visibly reducing supplier panels from twelve vendors to three preferred partners with integrated logistics coverage.
Netherlands
Industrial laundries serving Dutch hospital networks are absorbing REACH-driven reformulation costs faster than outsourced producers. Rotterdam and Eindhoven textile service providers are piloting blockchain-verified sterilization records for impending digital product passport mandates. Plasma-based finishing investments are widening competitive gaps between captive coating manufacturers and dependent suppliers.
Europe Medical Clothing Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a consolidating vendor base where direct hospital contracting capabilities determine margin capture. The market structure tiers between Nordic-scale manufacturers with integrated logistics and regional fabricators serving fragmented clinic demand. Three archetypes dominate: asset-light textile service operators, backward-integrated non-woven producers, and distributor-dependent regional suppliers. Competitive moves center on M&A for sterilization service networks and capacity expansion into Eastern European hospital modernization corridors.
Among established European manufacturers, Mölnlycke Health Care and Paul Hartmann occupy distinct positioning archetypes. Mölnlycke exemplifies the Nordic manufacturing scale model with captive supply chain control. Hartmann represents backward integration into fabric production, absorbing REACH-driven reformulation costs internally. Cardinal Health anchors the direct contracting archetype, bypassing traditional distributor markups through hospital system relationships. These three players illustrate how channel control, vertical integration depth, and geographic manufacturing base combine to determine competitive resilience under tightening EU MDR and sustainability mandates.
| Leading Market Players |
|---|
| Mölnlycke Health Care |
| Semperit AG Holding |
| Smith & Nephew |
| B. Braun Melsungen |
| Cardinal Health |
| Drägerwerk |
| Paul Hartmann |
| Lohmann & Rauscher |
| Surgical Holdings |
| Others |
Supply & Pricing Matrix
Rotterdam textile service clusters anchor European medical clothing supply capacity, with their industrial laundry networks and captive coating capabilities translating into pricing power over hospital procurement teams negotiating long-term service contracts.
Pricing Analysis
Certification level (EN 13795/CE marking tier) creates the primary spread between premium and standard surgical gown offerings. Three-tier pricing structure separates critical-zone laminates from general-procedure disposables from economy-grade scrubs. Cost compression in the mid-tier is intensifying because REACH-driven reformulation expenses are absorbing margin without commensurate price recovery. Day clinics and independent ambulatory centers exhibit highest price sensitivity; German acute care networks with consolidated purchasing show lowest.
Supply Chain Analysis
Polypropylene resin feedstock draws from petrochemical complexes in Belgium, the Netherlands, and Germany. Spunbond-meltblown-spunbond laminate production rests on propylene monomer supply, specialized meltblown equipment, and plasma-based hydrophobic finishing chemistry. Single-source vulnerability concentrates in Nordic non-woven fabric producers serving multiple gown manufacturers. Distribution runs through direct manufacturer-to-hospital contracts and centralized purchasing cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of notified body capacity for EU MDR conformity assessment is constraining new product launches and consolidating advantage around incumbents with established certification pipelines.
For Market Incumbents: Build regulatory moats through captive notified body relationships and pre-validated sterilization service networks. Absorb REACH-driven reformulation costs faster than outsourced competitors to widen competitive gaps. Deepen backward integration into non-woven fabric production to secure polypropylene laminate supply against feedstock volatility. For New Entrants and Emerging Players: Polish and Romanian hospital modernization corridors offer underpenetrated procurement channels with less consolidated vendor relationships than Western European systems. Target day clinic scrub supply with rapid-turn e-procurement platforms bypassing traditional distributor networks. Lead with biodegradable spunbond-meltblown-spunbond alternatives to capture EU Green Deal compliance premiums. For Investors and Strategic Acquirers: Long-term, this sits as a circular-economy infrastructure play because reusable textile service models are displacing disposable volume under sustainability mandates. Acquisition targets should combine RFID-tracked fleet management with captive industrial laundry networks. Monitor notified body capacity expansion announcements as inflection signal for new product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | Notified body pre-submission accelerates EU MDR transition timelines for surgical gown portfolios. |
| Hospital System Partnership | Direct contracting with Groupement des Achats Hospitaliers locks multi-year volume commitments. |
| Backward Integration into Non-Woven Fabric | Captive polypropylene laminate production insulates margin from petrochemical feedstock swings. |
| RFID Fleet Tracking Deployment | Blockchain-verified sterilization records prepare reusable textile services for digital product passport mandates. |
| Biodegradable Material Transition | Polylactic acid-based laminates collapse landfill diversion timelines for single-use gown compliance. |
Research Methodology
A spread of perspectives from hospital procurement managers, industrial laundry operators, biomedical engineers, and notified body auditors converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against EMA guidance documents, EU MDR implementing acts, REACH restriction updates, and hospital GPO contract databases. Bottom-up demand modeling triangulated against top-down macroeconomic indicators.
Demand-supply balance dynamics shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, end-user facility tier, material composition, and distribution channel structure. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and procurement consolidation patterns. Forecast inputs incorporated outpatient surgical volume projections and circular textile service adoption curves.
Practitioners should monitor notified body capacity utilization rates and polypropylene feedstock price indices for early signals of certification queue lengthening or margin compression. Forecasts reflect assumptions about EU MDR transition timelines and EU Green Deal implementation pacing. Cross-checking against national packaging waste reduction targets and hospital procurement database trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Cryotubes Market
Medical Supplies
Europe Hospital Supplies Market
Medical Supplies
Surgical Amniotics Market
Medical Supplies
Swab Cups Market
Medical Supplies
Medical Liners Market
Medical Supplies
Premixed IV Minibags Market
Medical Supplies
Blood Preparation Market
Medical Supplies
Global Medical Supplies Market
Medical Supplies
Pre-Packaged Medical Supplies Market
Medical Supplies
Global Respiratory and Anesthesia Disposables Market
Medical Supplies
Hospital Consumables Market
Medical Supplies
Disposable Oxygen Masks Market
Medical Supplies
Glass Pasteur Pipettes Market
Medical Supplies
Petri Dishes Market
Medical Supplies
Diagnostic Vials Market
Medical Supplies
Ultrasound Gels Market