
 Endoscope Tip Protectors Market | 2026-2036
Endoscope Tip Protectors Market Size, Share, and Industry Trends Forecast 2026-2036
Endoscope Tip Protectors Market Foresight
Hospital procurement consolidation is restructuring demand patterns across the endoscope tip protectors market. Olympus leverages its integrated endoscopy ecosystem to sustain bundled accessory sales, while Aspen Surgical competes through specialized surgical accessory portfolios. Medline Industries anchors hospital supply contracts through extensive distribution networks that control channel access for disposable tip protectors.
Endoscope tip protectors are sterile sheaths or caps engineered to shield delicate distal lens assemblies and instrument channels from mechanical damage, contamination, and optical degradation during transport, storage, and reprocessing cycles. Silicone formulations dominate premium applications where autoclavability and biocompatibility per ISO 10993 prove essential, while polyethylene variants occupy high-volume disposable segments driven by cost-sensitive diagnostic procedures. The surgical application category generates concentrated margin pools due to stringent sterility requirements, whereas the diagnostic segment extends volume through outpatient endoscopy expansion.
FDA reprocessing guidelines and EU MDR device classification frameworks shape material selection and validation requirements for manufacturers seeking market access. The EPA regulates sterilization byproduct emissions, influencing facility-level procurement decisions between reusable and disposable protector strategies. ISO 13485 quality management standards govern supplier qualification protocols that filter vendor participation across regulated channels. Stakeholders must monitor evolving single-use plastics legislation and reprocessing validation costs to calibrate product mix decisions between durable and disposable protector platforms.
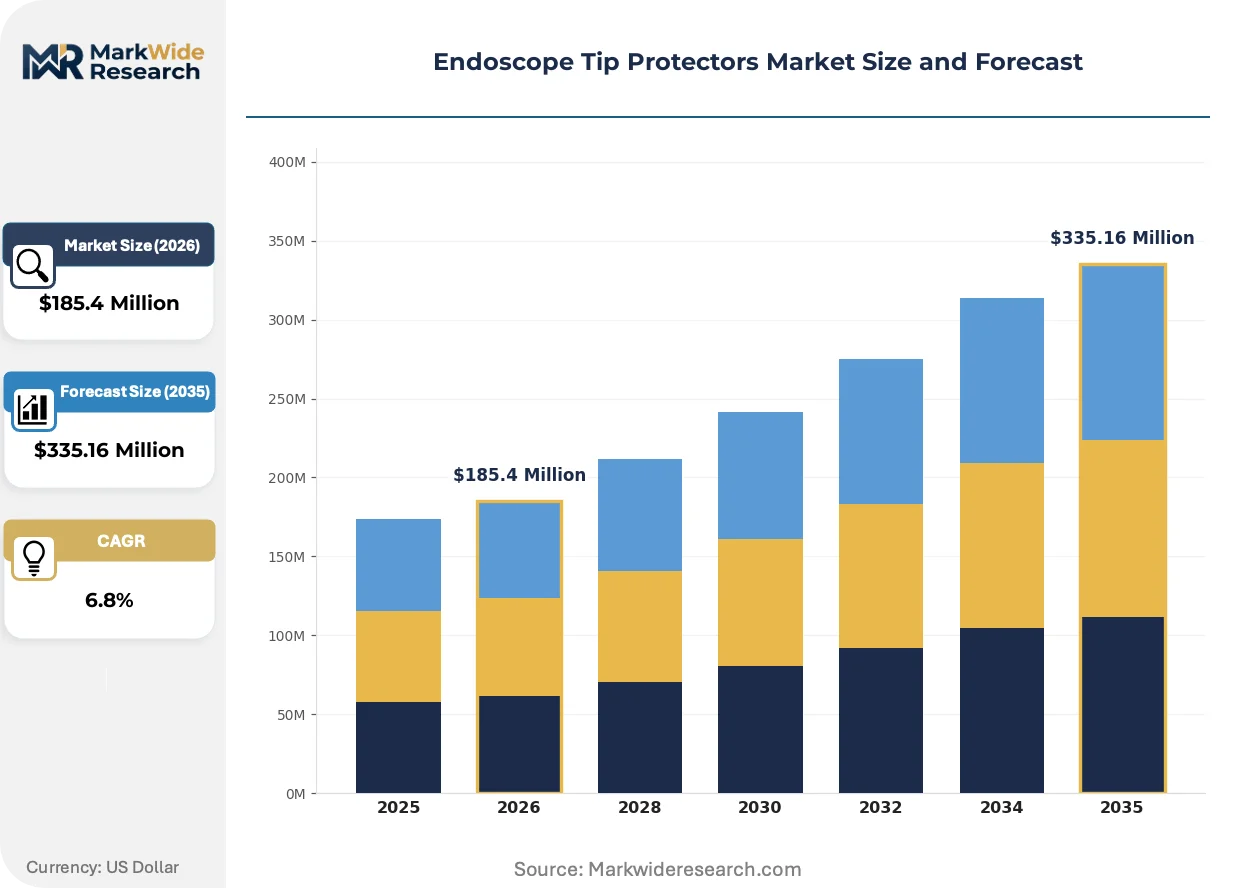
Market Dynamics
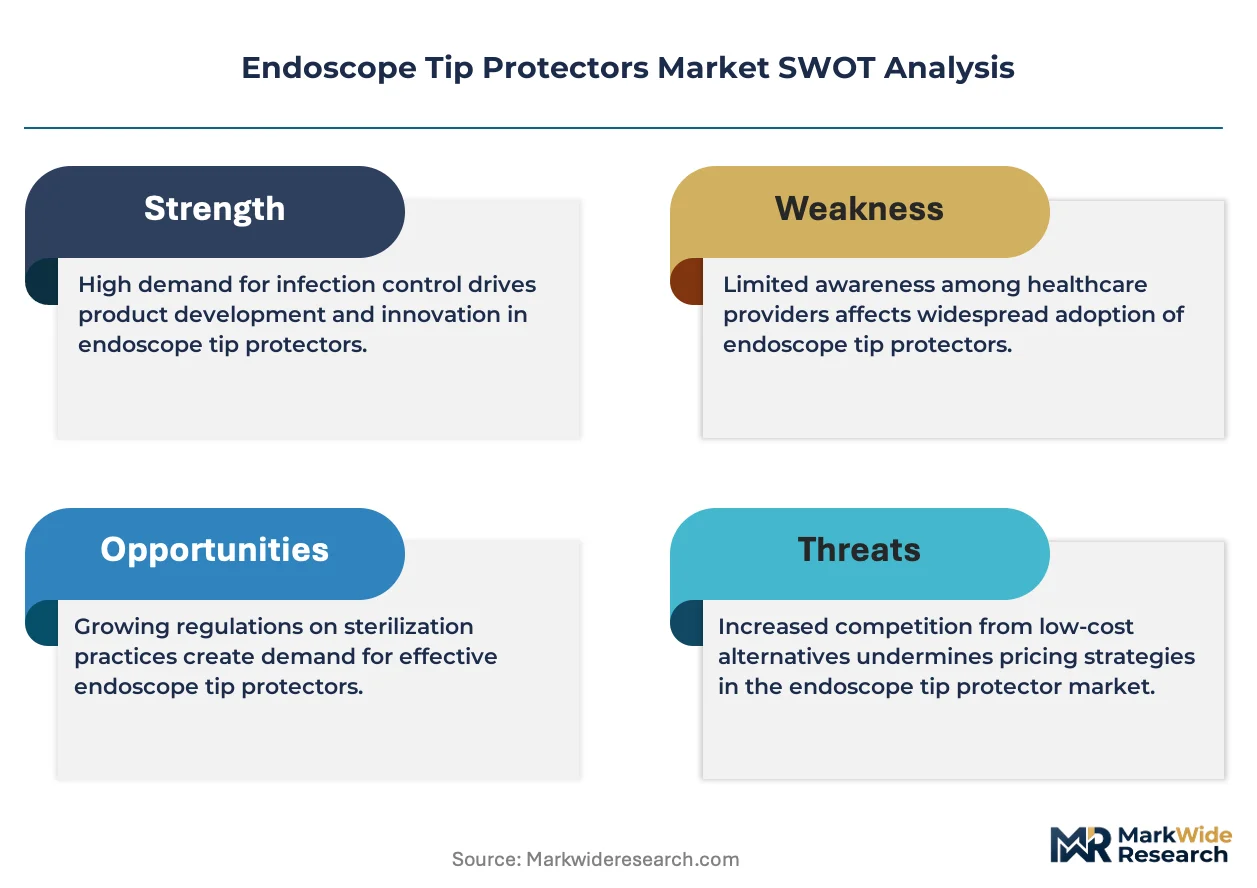
Hospital procurement consolidation is compressing vendor margins while simultaneously elevating technical compliance requirements for endoscope tip protectors across integrated delivery networks.
Growth Catalysts
- FDA Reprocessing Guidelines:Stringent validation protocols for reusable medical devices are accelerating hospital migration toward validated disposable tip protector platforms that eliminate reprocessing liability.
- Silicone Material Advancement:High-performance autoclavable silicone formulations are capturing surgical suite preference where ISO 10993 biocompatibility certification proves non-negotiable for patient contact applications.
- United States Surgical Corridor:Concentrated demand from ambulatory surgical centers and hospital operating rooms in the US Midwest and Southeast is driving volume commitments from national distributors.
Market Restraints
- Petrochemical Input Volatility:Medical-grade silicone and polyethylene resin prices fluctuate with crude oil derivatives, compressing margin predictability for manufacturers locked into annual hospital contracts.
- Single-Use Plastics Legislation:Emerging restrictions on disposable medical plastics in California and New York are creating compliance fragmentation that complicates national product line standardization.
- Reusable Endoscope Systems:Advanced flexible endoscope designs with integrated distal cap protection are reducing attachable tip protector attachment rates in certain diagnostic procedure categories.
Strategic Opportunities
- EU MDR Certification Gap:Smaller manufacturers lacking notified body relationships for EU MDR technical documentation create acquisition targets for firms seeking European market expansion.
- Outpatient Endoscopy Expansion:Freestanding endoscopy centers in Texas and Florida are deploying high-throughput disposable protector strategies that favor polyethylene cost structures over silicone premiums.
- Sterilization Byproduct Regulation:EPA emission limits on ethylene oxide sterilization are incentivizing hospital transitions to pre-sterilized disposable protectors that bypass on-site sterilization infrastructure.
Industry Challenges
- Biocompatibility Validation Timeline:ISO 10993 cytotoxicity and sensitization testing protocols extend product development cycles, delaying market entry for novel material formulations.
- Legacy Endoscope Compatibility:Proprietary distal tip geometries across Olympus, Pentax, and Karl Storz endoscope portfolios fragment protector SKUs, complicating inventory management for distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endoscope Tip Protectors Market |
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $335.16 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable, Disposable, Customizable, Sterilizable Material: Silicone, Polyethylene, PVC, Rubber Application: Surgical, Diagnostic, Therapeutic, Veterinary End User: Hospitals, Clinics, Laboratories, Homecare |
| Companies Covered | Olympus, Aspen Surgical, Medline Industries, Meditech Endoscopy, Medtrica Solutions, STERIS, Cogentix Medical, Exact Medical, Cover S.r.l, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endoscope Tip Protectors Market Shifts & Advancements
Material science convergence with regulatory compliance automation is redefining competitive differentiation in endoscope tip protector manufacturing and procurement workflows.
Autoclavable liquid silicone rubber is consolidating premium segment positioning by enabling 100+ sterilization cycles without optical degradation or dimensional drift. Academic medical centers in Massachusetts and Pennsylvania are specifying this material for robotic-assisted surgical endoscopy suites where instrument turnover demands maximum reuse cycles. The technology is consolidating supplier relationships around vertically integrated silicone compounders capable of in-house platinum-catalyzed curing and ISO 13485 lot traceability.
EU MDR device classification frameworks are elevating clinical evidence requirements for tip protectors marketed as sterile barriers rather than simple transport accessories. Manufacturers must now compile biocompatibility documentation and post-market surveillance protocols previously exempt under MDD rules. German and French notified bodies are enforcing these standards most aggressively, filtering non-compliant vendors from hospital tender processes across the European Union.
Centralized procurement through group purchasing organizations is displacing individual hospital contracting autonomy in the United States. Integrated delivery networks in Illinois and Ohio are consolidating annual tip protector spend into single-source agreements that bundle endoscope accessories across multiple procedure categories. This concentration is visible most acutely in the diagnostic segment where standardized polyethylene protectors face intense price compression against generic alternatives.
Endoscope Tip Protectors Market Segmentation
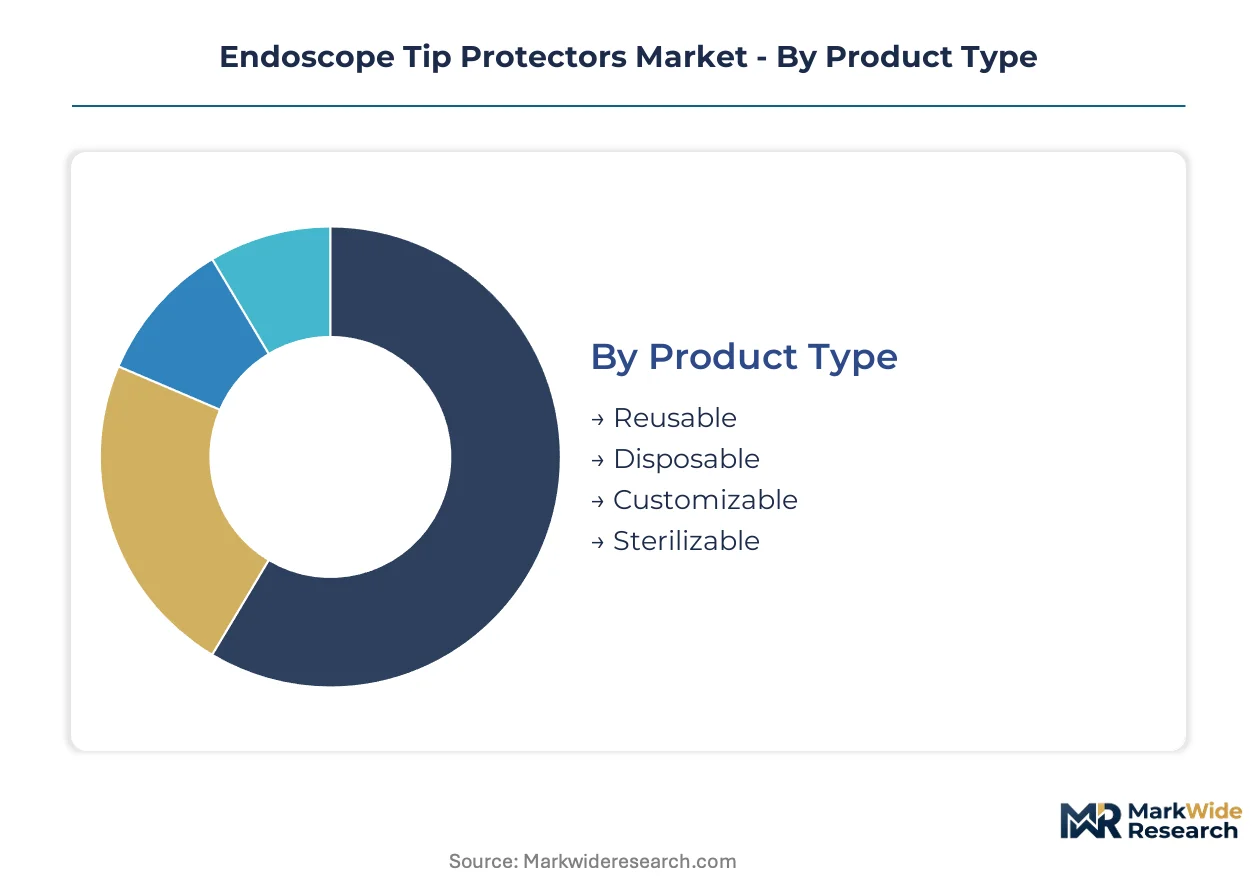
Segmentation in the endoscope tip protectors market reveals distinct procurement patterns tied to sterilization infrastructure and procedure volume economics. Material selection and reusability specifications diverge sharply between high-throughput diagnostic centers and capital-intensive surgical suites.
Product Type:
Upgrade cycles for sterilization equipment and reprocessing validation protocols are reshaping hospital preferences across product categories.
- Reusable:Autoclavable silicone designs withstand 100+ sterilization cycles per ISO 17665 standards. Massachusetts General Hospital and Cleveland Clinic surgical suites specify these for robotic-assisted procedures where instrument turnover demands maximum cycle durability.
- Disposable:Single-use polyethylene variants eliminate reprocessing liability under FDA validation guidelines. Texas and Florida ambulatory surgery centers deploy these in high-volume colonoscopy workflows where throughput economics favor per-procedure disposability.
- Customizable:Proprietary distal tip geometries for Olympus, Pentax, and Karl Storz endoscopes require SKU-specific molding.
- Sterilizable:Pre-validated gamma-irradiated packaging meets EU MDR sterile barrier requirements for direct-to-field deployment.
Volume placements concentrate in Disposable; the faster expansion belongs to Reusable.
Material:
Cost tier differentiation separates premium autoclavable formulations from commodity single-use resins.
- Silicone:Platinum-cured liquid silicone rubber delivers ISO 10993 biocompatibility certification essential for patient contact applications. Academic medical centers in Pennsylvania and Ohio specify medical-grade silicone for surgical endoscopy suites where optical clarity across repeated sterilization cycles is non-negotiable.
- Polyethylene:High-density polyethylene resin dominates cost-sensitive diagnostic procedures. Outpatient endoscopy centers in Illinois and Georgia source these in bulk through group purchasing organization contracts that prioritize unit economics over cycle durability.
- PVC:Plasticized polyvinyl chloride occupies mid-tier pricing for veterinary and non-critical applications.
- Rubber:Natural and synthetic rubber compounds serve legacy equipment compatibility requirements in secondary markets.
Silicone captures the premium tier; polyethylene commands the volume tier.
Application:
Procedure reimbursement rates and sterility requirements create divergent margin structures across clinical settings.
- Surgical:Operating room protocols mandate autoclavable silicone protectors validated for sterile field maintenance. Ambulatory surgical centers in the US Southeast specify these for laparoscopic and arthroscopic procedures where joint commission standards enforce instrument traceability.
- Diagnostic:Gastroenterology and pulmonology suites drive polyethylene volume through screening colonoscopy and bronchoscopy expansion. Freestanding endoscopy centers in Texas deploy single-use strategies that minimize reprocessing staff overhead.
- Therapeutic:ERCP and EUS procedures require specialized tip geometries for therapeutic instrument channel access.
- Veterinary:Companion animal and equine endoscopy applications favor cost-optimized rubber and PVC formulations.
Surgical applications anchor margin concentration; diagnostic procedures extend volume scale.
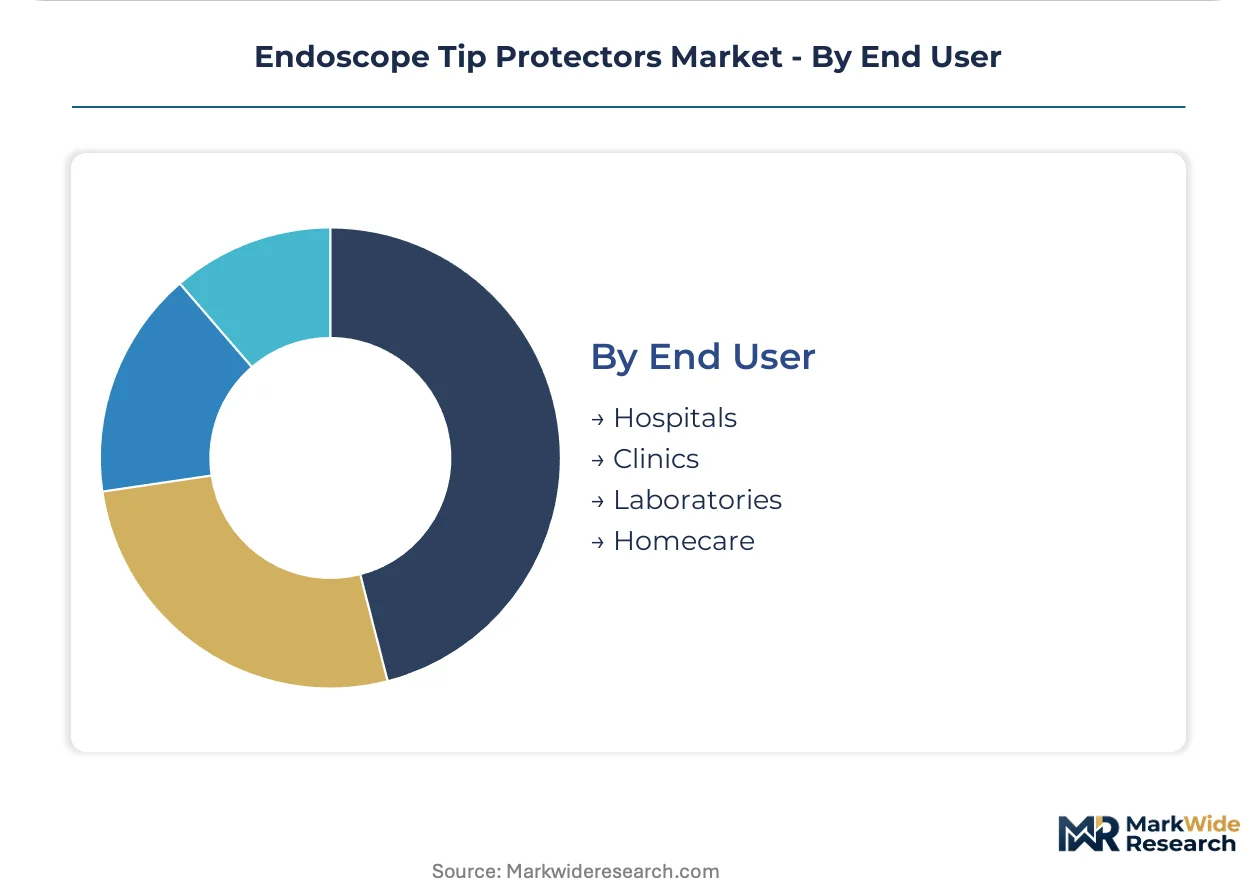
End User:
Customer type determines contract structure, with integrated delivery networks consolidating procurement differently than independent facilities.
- Hospitals:IDN consolidation in Illinois and Ohio compresses vendor margins through multi-year bundled agreements. Hospital procurement committees specify autoclavable silicone for surgical suites and disposable polyethylene for endoscopy units within the same contract framework.
- Clinics:Independent gastroenterology practices in Florida and Arizona favor disposable protectors to minimize capital investment in sterilization infrastructure.
- Laboratories:Research and veterinary pathology facilities source customizable protectors for non-standard endoscope configurations.
- Homecare:Emerging enteral feeding and respiratory endoscopy applications drive demand for pre-sterilized single-use packaging.
Hospitals dominate contract value; clinics represent the fastest volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States surgical endoscopy corridors concentrate demand for autoclavable silicone tip protectors, while European regulatory frameworks reshape material validation requirements. Hospital procurement consolidation and outpatient expansion create divergent growth vectors across major markets.
United States
Ambulatory surgical centers in Texas and Florida drive polyethylene volume through high-throughput colonoscopy workflows. FDA reprocessing guidelines for reusable medical devices accelerate hospital migration toward validated disposable platforms. The US Midwest and Southeast surgical corridors anchor premium silicone demand from academic medical centers.
Germany
Notified bodies in Berlin and Munich enforce EU MDR sterile barrier requirements most aggressively, filtering non-compliant vendors from hospital tenders. German academic medical centers specify platinum-cured liquid silicone rubber for robotic-assisted surgical suites. The Baden-Württemberg medical technology cluster concentrates autoclavable formulation expertise.
Japan
PMDA device classification frameworks elevate clinical evidence requirements for tip protectors marketed as sterile barriers. METI industrial policy supports domestic silicone compounders with platinum-catalyzed curing capabilities. The Kanto region around Tokyo anchors integrated endoscopy ecosystem procurement.
United Kingdom
NHS procurement consolidation compresses vendor margins through multi-year bundled agreements across integrated care systems. MHRA post-market surveillance requirements extend biocompatibility documentation obligations. The Greater Manchester and London hospital networks specify ISO 10993-certified materials for surgical suites.
India
CDSCO medical device rules create compliance fragmentation for imported tip protector platforms. Cost-sensitive diagnostic centers in Maharashtra and Karnataka favor polyethylene disposables over silicone premiums. The Delhi-NCR corridor concentrates private hospital procurement for premium surgical applications.
Endoscope Tip Protectors Market Competitive Landscape
United States producers anchor the premium tier through integrated endoscopy ecosystems; European specialists hold regulatory certification advantages. The vendor base stratifies across three tiers: diversified medical device conglomerates with bundled accessory portfolios, specialized surgical accessory manufacturers, and regional disposable suppliers. Two dominant competitive moves define positioning: backward integration into silicone compounding for cycle durability claims, and strategic partnerships with group purchasing organizations for IDN contract access.
Within the diversified conglomerate tier, Olympus and STERIS represent integrated ecosystem approaches that bundle tip protectors with endoscope system sales. Aspen Surgical occupies a position among specialized surgical accessory portfolios competing through procedure-specific product lines. Medline Industries anchors the distribution-intensive segment, exemplifying extensive hospital supply contract networks that control channel access for disposable platforms.
| Leading Market Players |
|---|
| Olympus |
| Aspen Surgical |
| Medline Industries |
| Meditech Endoscopy |
| Medtrica Solutions |
| STERIS |
| Cogentix Medical |
| Exact Medical |
| Cover S.r.l |
| Others |
Supply & Pricing Matrix
Backward integration into platinum-catalyzed silicone compounding anchors pricing power for autoclavable tip protector manufacturers serving academic medical centers in Massachusetts and Pennsylvania. Captive control over medical-grade resin formulations insulates premium-tier suppliers from petrochemical volatility while locking hospital procurement committees into multi-year contracts.
Pricing Analysis
High-volume polyethylene disposables compete on unit economics against premium silicone reusables validated for 100+ sterilization cycles. Price differentiation rests on ISO 10993 biocompatibility certification tier and bundled GPO contract access. Cost compression in the diagnostic segment intensifies as Texas and Florida ambulatory surgery centers prioritize throughput over cycle durability. Clinics exhibit highest price sensitivity; robotic-assisted surgical suites in Ohio academic medical centers show lowest.
Supply Chain Analysis
ISO 13485 quality management certification gates supplier participation across regulated distribution channels in the United States, Germany, and Japan. Medical-grade silicone and polyethylene resin feed from petrochemical derivatives in Texas and Louisiana production corridors. Single-source vulnerability concentrates in platinum-catalyst supply for liquid silicone rubber curing. Distribution runs through Medline Industries and hospital supply networks controlling IDN contract access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The endoscope tip protector market is becoming a vertical-integration race, with control over platinum-catalyzed silicone compounding emerging as the decisive upstream lever for premium-tier positioning.
For Market Incumbents: Hedge against polyethylene commoditization by deepening captive silicone formulation capabilities and securing multi-year GPO contracts before EU MDR documentation requirements filter non-compliant vendors. Defend margin position through ISO 10993 testing infrastructure investments that extend biocompatibility validation timelines for challengers. For New Entrants and Emerging Players: Launch via direct-to-clinic distribution models targeting independent gastroenterology practices in Arizona and Florida that lack sterilization infrastructure. Exploit underpenetrated outpatient endoscopy expansion in Texas with pre-sterilized disposable platforms bypassing hospital procurement consolidation. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified medical device conglomerates seeking bundled accessory portfolios. Long-term viability hinges on regulatory certification moats rather than manufacturing scale. Watch EU MDR notified body backlog clearance as the signal for European market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Compounding | Captive platinum-catalyzed curing capabilities secure ISO 13485 lot traceability for Massachusetts surgical suites. |
| EU MDR Technical Documentation Investment | Notified body relationships in Berlin and Munich unlock hospital tender access across German academic medical centers. |
| GPO Contract Consolidation | Single-source agreements with Illinois and Ohio IDNs displace fragmented hospital-level procurement autonomy. |
| Pre-Sterilized Disposable Platform Launch | Gamma-irradiated packaging bypasses EPA ethylene oxide emission constraints for Texas ambulatory centers. |
| Proprietary Distal Tip Geometry Licensing | Olympus and Karl Storz compatibility agreements reduce SKU fragmentation for distributor inventory management. |
Research Methodology
FDA 510(k) filings, hospital procurement databases, and GPO contract disclosures formed the secondary backbone, supplemented by primary interviews with biomedical engineers, hospital purchasing committees, GPO contracts managers, and regulatory affairs leads at silicone compounders. Bottom-up and top-down triangulation validated segment-level demand assumptions across reusable, disposable, and sterilizable product categories.
The analytical lens combined bottom-up procedure volume modeling with top-down endoscope installed base estimates across the projection horizon. Segmentation dimensions included material type, reusability specification, application setting, and end-user facility tier. CAGRs derived from regression analysis against historical hospital capital expenditure cycles and reprocessing validation cost trajectories. Industry-specific inputs incorporated FDA reprocessing guideline enforcement timelines and EU MDR transition completion rates.
Petrochemical input volatility, single-use plastics legislation passage, and reusable endoscope system adoption are the dominant revision risks to demand forecasts. A model refresh is warranted upon material change in EPA sterilization byproduct emission limits.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Germany Hospital Supplies Market
Medical Supplies
Ultrasound Gels Market
Medical Supplies
Global Chromatography Syringes Market
Medical Supplies
Emesis Bag Market
Medical Supplies
Global Sharps Containers Market
Medical Supplies
Powder-Free Disposable Medical Gloves Market
Medical Supplies
Middle East and Africa Medical Rubber and Balloon Products Market
Medical Supplies
Bile Collection Bags Market
Medical Supplies
Global Safety Syringes Market
Medical Supplies
Medical and Industrial Gloves Market
Medical Supplies
Autoclaving Trays Market
Medical Supplies
Menthol Patches Market
Medical Supplies
Anesthesia Disposables Market
Medical Supplies
Pharmacy Accessory Bagging System (PABS) Market
Medical Supplies
Port Access Needles Market
Medical Supplies
Catgut Sutures Market