
 Medical Filter Market | 2026-2036
Medical Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Filter Market Insights
ASTM-level bioburden control specifications is redrawing procurement benchmarks across infusion and hemodialysis applications. Pall Corporation leverages in-house membrane manufacturing to sustain supply security for blood processing clients. Sartorius AG anchors European demand through deep specialization in single-use filtration assemblies for biopharmaceutical production. Danaher competes on analytical validation capabilities that shorten regulatory clearance cycles for diagnostic filter integrations.
A medical filter is a porous barrier device engineered from polyethersulfone, polyvinylidene fluoride, or regenerated cellulose with controlled pore ratings typically spanning 0.04 to 10 microns, designed to remove particulates, microorganisms, or endotoxins from fluids and gases in clinical settings. Membrane filtration occupies the highest value tier due to precision requirements in sterile drug manufacturing and cell therapy processing. Depth filtration sustains volume leadership in pre-filtration and clarification steps where high dirt-holding capacity outweighs absolute retention demands. Hemodialysis application segments command premium pricing as clinic networks prioritize pyrogen-free dialysate circuits to reduce patient complication rates.
FDA 21 CFR Part 211, EMA GMP Annex 1, and ISO 13485 collectively mandate validated filtration performance for pharmaceutical and device manufacturers, creating compliance-driven replacement cycles that stabilize recurring revenue pools. The EU MDR and impending IVDR recast intensify documentation burdens for filter suppliers serving European diagnostic and transfusion device markets. Stakeholders must monitor evolving endotoxin detection thresholds and single-use system sustainability mandates as the next vectors of product differentiation and sourcing risk.
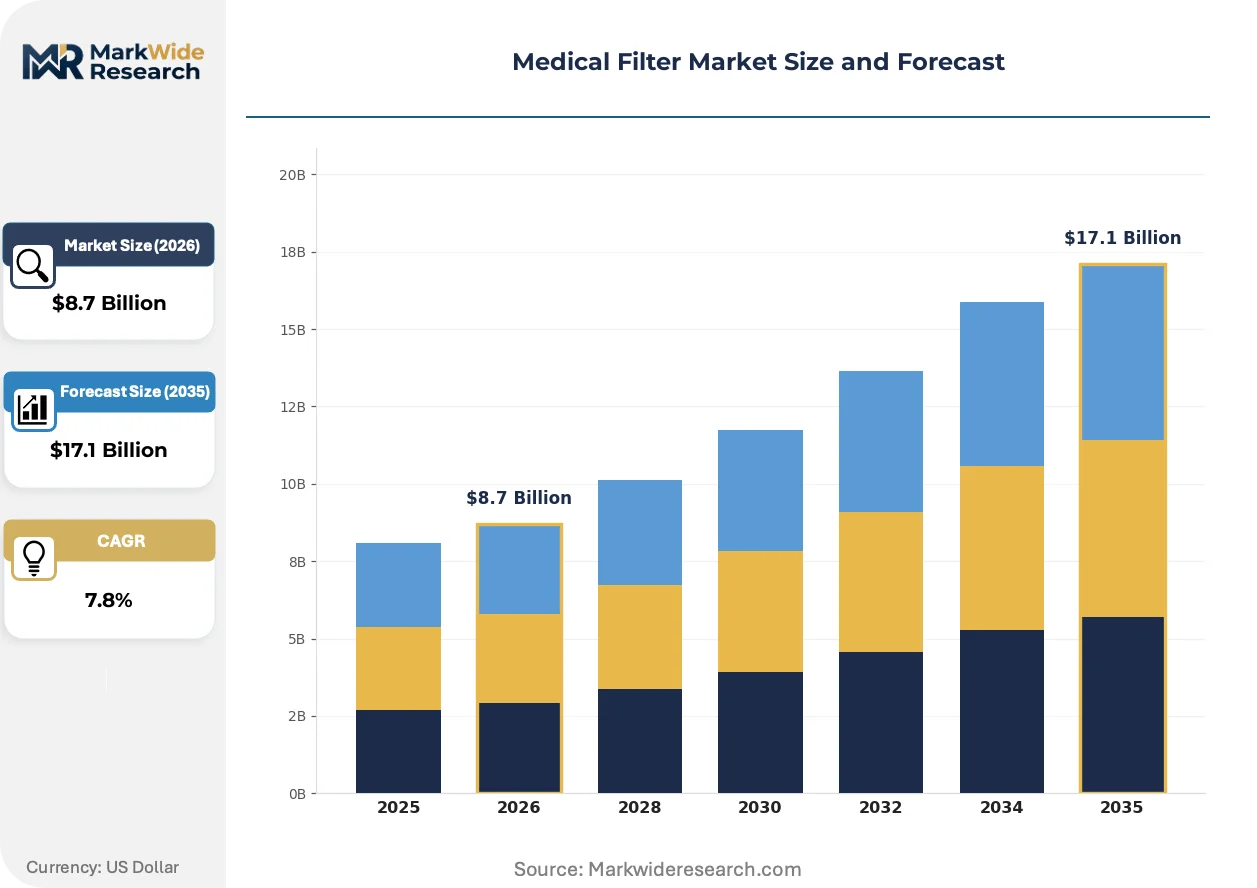
Market Dynamics
FDA and EMA sterility assurance tightening is forcing hospital procurement departments to requalify entire filtration portfolios, compressing replacement cycles and elevating validation documentation to a primary vendor selection criterion.
Growth Catalysts
- EMA GMP Annex 1 revision:The updated sterile manufacturing guidance mandates continuous particle monitoring in aseptic processing, driving membrane filter upgrades across European parenteral drug facilities.
- Cell therapy manufacturing expansion:Commercial-scale autologous cell production requires single-use filtration trains with validated endotoxin clearance, creating dedicated demand for 0.1-micron-rated assemblies.
- Japan's hemodialysis clinic consolidation:METI-backed regional dialysis center networks are standardizing on pyrogen-free dialysate filtration systems to reduce patient complication liability.
Market Restraints
- Polyethersulfone resin concentration:Three chemical conglomerates control pharmaceutical-grade PES supply, exposing filter manufacturers to input cost volatility and allocation risk during polymer production disruptions.
- EU MDR technical documentation burden:The recast Medical Device Regulation requires extensive clinical evidence for filter components integrated into Class IIb and III devices, extending time-to-market by 12-18 months for European diagnostic applications.
- Depth filtration performance ceiling:Nominal retention ratings and media migration limits prevent depth filters from displacing membrane systems in final sterile filtration steps, constraining premium pricing potential in high-value applications.
Strategic Opportunities
- India's biopharmaceutical manufacturing expansion:CDSCO's accelerated approval pathways for biosimilars are attracting contract manufacturing investment, creating demand for validated single-use filtration assemblies in Hyderabad and Bangalore production clusters.
- Sustainability-linked procurement mandates:EU Green Deal circular economy requirements are creating preference for filter suppliers offering take-back programs and bio-based housing materials in German and French hospital systems.
- Point-of-care diagnostic integration:Microfluidic filtration modules combined with lateral flow assay platforms enable sample preparation automation, opening ambulatory and home testing channels previously served by central laboratories.
Industry Challenges
- Membrane casting technician scarcity:Precision phase-inversion manufacturing requires 5-7 year skill development periods, constraining capacity expansion at specialized production facilities in the United States and Germany.
- Legacy equipment compatibility friction:New single-use filtration assemblies must interface with stainless steel processing trains installed under earlier GMP regimes, creating validation documentation complexity and installation engineering costs.
- Endotoxin testing standard divergence:LAL assay variability between USP, EP, and JP pharmacopeial methods creates lot release disputes between filter manufacturers and pharmaceutical customers, requiring redundant testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Filter Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Filters, Blood Filters, IV Filters, Urinary Filters Technology: Membrane Filtration, Depth Filtration, Microfiltration, Nanofiltration Application: Diagnostics, Hemodialysis, Transfusion, Infusion Therapy End User: Hospitals, Clinics, Laboratories, Home Care |
| Companies Covered | Pall Corporation, Merck KGaA, Sartorius AG, 3M (Solventum), Danaher, Asahi Kasei Medical Co., Ltd., Medtronic, GVS Filter Technology, Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Filter Market Trends and Innovations
Sterile processing workflows are converging on single-use architectures, with membrane technology, regulatory validation protocols, and procurement contracting models all pivoting toward disposability and supply security.
Track-etched polycarbonate membranes with precisely cylindrical pore geometries are displacing conventional cast membranes in critical sterile filtration applications. Gene therapy vector manufacturers in Boston and Basel are specifying 0.1-micron track-etched products for mycoplasma retention assurance. The technology is displacing revenue from traditional PES membrane suppliers in high-value bioprocessing segments where absolute retention validation is mandatory.
REACH restriction proposals on per- and polyfluoroalkyl substances are compelling filter manufacturers to reformulate PVDF membrane wetting agents and housing lubricants. The European Chemicals Agency's 2023 PFAS restriction roadmap threatens existing product registrations for hydrophobic vent filters and gas filtration cartridges. German and Swiss device manufacturers are accelerating validation of alternative hydrophilization chemistries to maintain CE marking continuity.
Hospital consortiums are consolidating filtration procurement through group purchasing organizations with pre-negotiated technical specifications and sole-source commitments. The University HealthSystem Consortium and similar European buying groups are displacing individual hospital tender processes for high-volume infusion and dialysis filter categories. This concentration is most visible in the United States, where three GPOs control 80 percent of acute care filtration spend and extract multi-year price commitment guarantees from suppliers.
Medical Filter Market Segmentation
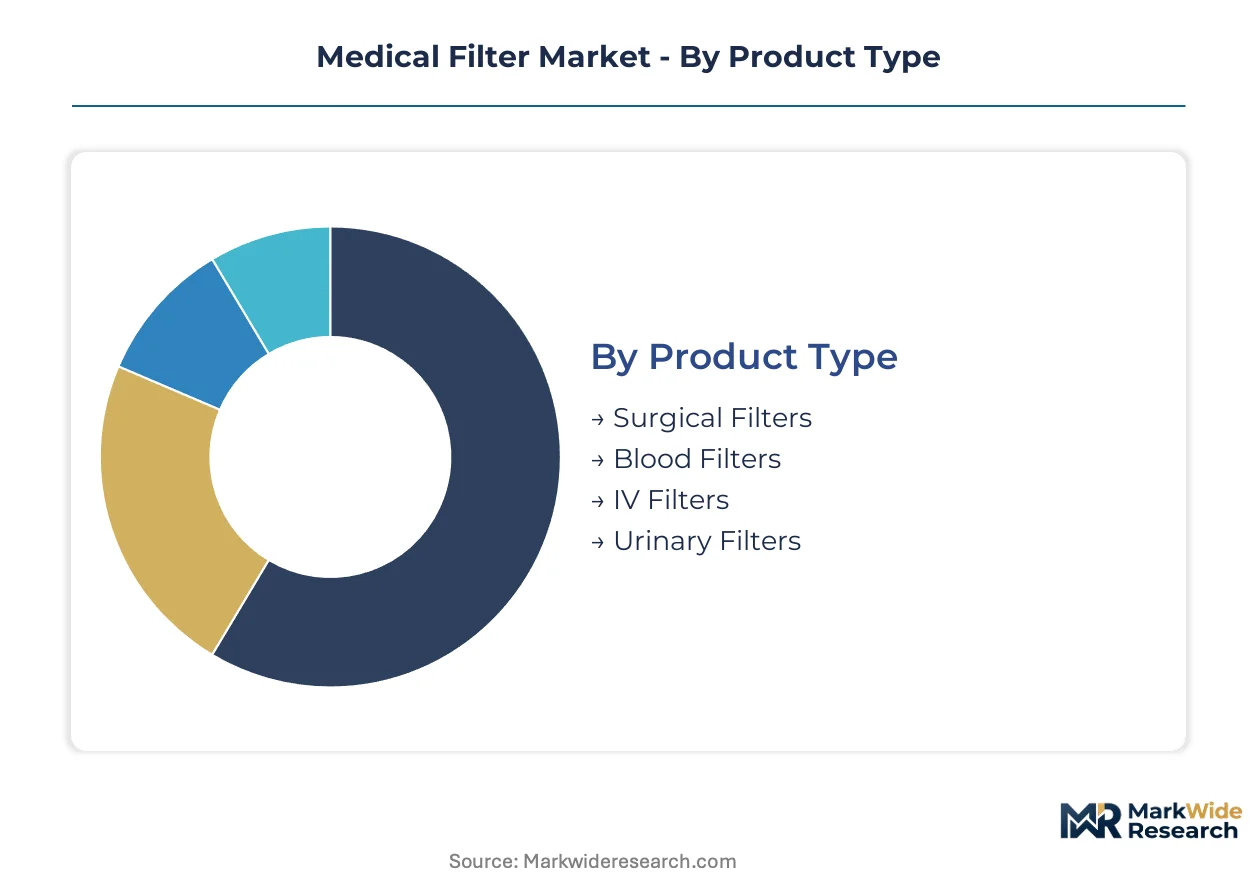
Medical filter procurement varies sharply by clinical environment and regulatory exposure, with membrane-based systems commanding premium positioning in sterile manufacturing while depth filtration retains volume dominance in pre-treatment workflows. Segment boundaries increasingly blur as single-use architectures displace stainless steel trains across multiple application categories.
Product Type:
Surgical filters and IV filters concentrate in domestic hospital supply chains across the United States, Germany, and Japan, while blood and urinary filters show stronger export orientation toward emerging manufacturing clusters.
- Surgical Filters:Constructed from hydrophobic polyvinylidene fluoride membranes with 0.2-micron absolute ratings for operating room gas and liquid sterility assurance. Demand clusters in metropolitan hospital systems across the United States and Germany where ASC-level infection control protocols mandate validated filtration documentation for every procedure.
- Blood Filters:Deploy multi-layer depth media with leukocyte depletion capability for transfusion safety. Procurement concentrates in Japanese hemodialysis clinic networks and European blood banking infrastructure where METI-backed consolidation drives standardization on pyrogen-free circuit designs.
- IV Filters:Integrate 0.22-micron polyethersulfone membranes into infusion sets for particulate and microbial retention.
- Urinary Filters:Employ hydrophilic cellulose ester media for drainage bag and catheter applications in long-term care settings.
Blood filters command the established base. The steepest expansion runs through surgical filters.
Technology:
Membrane and nanofiltration systems sit at the premium cost tier with validated endotoxin clearance specifications, while depth and microfiltration occupy standard and economy positioning based on retention certainty requirements.
- Membrane Filtration:Phase-inversion cast polyethersulfone or track-etched polycarbonate with precise cylindrical pore geometries. Boston and Basel gene therapy manufacturers specify 0.1-micron-rated products for mycoplasma retention, displacing conventional cast membranes in high-value sterile processing.
- Depth Filtration:Nominal-rated graded-density polypropylene or cellulose media with high dirt-holding capacity for clarification and pre-filtration steps. Volume leadership persists in biopharmaceutical harvest and plasma fractionation where absolute retention validation is not mandatory.
- Microfiltration:Cross-flow or dead-end configurations with 0.1 to 10 micron ratings for cell separation and bioburden reduction.
- Nanofiltration:Thin-film composite membranes with molecular weight cut-offs below 1000 Daltons for endotoxin and viral clearance in parenteral drug manufacturing.
Depth filtration commands the established base. The steepest expansion runs through nanofiltration.
Application:
Diagnostics and hemodialysis applications generate the highest margin profiles due to regulatory documentation intensity, while transfusion and infusion therapy segments compete on volume scale and GPO contract positioning.
- Diagnostics:Microfluidic filtration modules integrated with lateral flow and molecular assay platforms for sample preparation automation. Point-of-care expansion in ambulatory and home testing channels drives specification of miniaturized membrane assemblies with validated flow characteristics.
- Hemodialysis:Pyrogen-free dialysate filtration with endotoxin retention below 0.03 EU/mL. Clinic networks in Japan and Germany prioritize liability reduction through standardized circuit designs, sustaining premium pricing for validated single-use filtration trains.
- Transfusion:Leukocyte reduction and bacterial detection filtration for blood component safety.
- Infusion Therapy:In-line 0.22-micron filters for parenteral medication administration in acute care settings.
Infusion therapy commands the established base. The steepest expansion runs through diagnostics.
End User:
Hospitals and laboratories concentrate procurement through consolidated buying groups with pre-negotiated technical specifications, while clinics and home care segments fragment across regional distributors with variable validation requirements.
- Hospitals:Acute care systems in the United States route 80 percent of filtration spend through three dominant GPOs with multi-year price commitment guarantees. EMA GMP Annex 1 compliance drives membrane filter upgrades in European parenteral drug compounding operations.
- Laboratories:Central and reference labs with automated analytical platforms requiring validated sample preparation filtration. CDSCO accelerated approval pathways for Indian biosimilars attract contract manufacturing investment, creating demand for single-use assemblies in Hyderabad and Bangalore clusters.
- Clinics:Outpatient dialysis and infusion centers with standardized circuit protocols.
- Home Care:Patient-operated devices with simplified filtration interfaces for peritoneal dialysis and subcutaneous infusion.
Hospitals command the established base. The steepest expansion runs through home care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical filter trade flows reveal a pronounced export surplus from German and Japanese manufacturing clusters toward emerging biopharmaceutical production zones in India and Southeast Asia. Import dependency concentrates in sterile membrane categories where domestic casting capacity remains insufficient.
United States
Hospital group purchasing organizations consolidate filtration procurement through multi-year sole-source contracts with pre-negotiated technical specifications. FDA 21 CFR Part 211 enforcement drives membrane filter upgrades across parenteral drug compounding facilities. Boston gene therapy manufacturers specify track-etched polycarbonate products for mycoplasma retention validation.
Germany
EMA GMP Annex 1 revision mandates continuous particle monitoring in aseptic processing, accelerating membrane replacement cycles across pharmaceutical facilities. EU Green Deal circular economy requirements create preference for suppliers offering take-back programs and bio-based housing materials. Baden-Württemberg device manufacturers accelerate validation of alternative hydrophilization chemistries to maintain CE marking continuity.
Japan
METI-backed regional dialysis center networks standardize on pyrogen-free dialysate filtration systems to reduce patient complication liability. PMDA sterility assurance guidelines tighten validation documentation requirements for filter-integrated devices. Osaka and Tokyo clinic networks prioritize liability reduction through standardized circuit designs.
India
CDSCO accelerated approval pathways for biosimilars attract contract manufacturing investment from multinational pharmaceutical firms. Hyderabad and Bangalore production clusters generate demand for validated single-use filtration assemblies in commercial-scale bioprocessing. Domestic membrane casting capacity remains concentrated in import-dependent sterile filtration categories.
Switzerland
Swissmedic device regulation harmonization with EU MDR extends technical documentation burdens for filter components integrated into diagnostic platforms. Basel gene therapy vector manufacturers drive specification of 0.1-micron-rated track-etched membranes for mycoplasma retention assurance. Precision manufacturing clusters sustain premium positioning in high-value sterile processing segments.
Medical Filter Market Competitive Landscape
Listed leaders compete with private specialists across validation documentation capabilities and supply security dimensions. The vendor base stratifies into three tiers: diversified conglomerates with analytical validation platforms, membrane manufacturing specialists with in-house casting operations, and regional fabricators serving domestic hospital supply chains. Strategic moves concentrate on backward integration into pharmaceutical-grade resin supply and capacity expansion in track-etched membrane production.
Among diversified technology conglomerates, Danaher and Thermo Fisher Scientific occupy positions emphasizing analytical validation capabilities that shorten regulatory clearance cycles. Sartorius AG exemplifies the European membrane specialist archetype with deep specialization in single-use filtration assemblies. Pall Corporation anchors the in-house manufacturing tier through captive membrane production for blood processing applications.
| Leading Market Players |
|---|
| Pall Corporation |
| Merck KGaA |
| Sartorius AG |
| 3M (Solventum) |
| Danaher |
| Asahi Kasei Medical Co., Ltd. |
| Medtronic |
| GVS Filter Technology |
| Thermo Fisher Scientific Inc. |
| Others |
Pricing and Supply Chain Analysis
Ninety-to-120-day membrane casting lead times for pharmaceutical-grade polyethersulfone tether pricing power to resin allocation security, concentrating margin leverage with manufacturers holding captive polymer supply or strategic stockpile positions.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on FDA 510(k) clearance tier and validated endotoxin documentation depth. Pricing pressure stems from GPO consolidation extracting multi-year price commitment guarantees. Academic medical centers show highest price sensitivity; gene therapy contract manufacturers show lowest.
Supply Chain Analysis
Strategic stockpile preferences dominate among Japanese hemodialysis clinic networks and European blood banking infrastructure facing PES resin allocation risk. Supply concentrates in the United States, Germany, and Japan for precision casting capacity. Raw material dependencies include pharmaceutical-grade polyethersulfone resin, track-etched polycarbonate substrates, and hydrophilic wetting agents. Single-source vulnerability runs through three chemical conglomerates controlling PES supply. Distribution runs through hospital group purchasing organizations and regional biopharmaceutical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Validation documentation services and recurring membrane replacement contracts expand faster than hardware sales, positioning aftermarket attach rates as the primary margin expansion vector.
For Market Incumbents: Compound defensive positioning through backward integration into pharmaceutical-grade resin supply and capacity expansion in track-etched membrane production. Gene therapy vector manufacturers in Boston and Basel are displacing conventional cast membrane suppliers, threatening revenue pools in high-value sterile processing segments. Certification investment in EU MDR technical documentation capabilities extends competitive moats against mid-tier challengers. For New Entrants and Emerging Players: Lead with sustainability-linked procurement mandates in German and French hospital systems as the entry wedge. India's biopharmaceutical manufacturing expansion in Hyderabad and Bangalore production clusters offers the most penetrable geography. Position around bio-based housing materials and take-back program bundling to differentiate against established membrane specialists. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because FDA and EMA sterility assurance tightening compresses replacement cycles and elevates validation documentation to a primary vendor selection criterion. Target membrane manufacturing specialists with in-house casting operations and deep single-use assembly expertise. Watch for endotoxin detection threshold revisions and PFAS restriction enforcement as inflection indicators for product reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive PES polymer access insulates margin structures from allocation disruptions at German and Japanese chemical conglomerates. |
| Track-Etched Membrane Capacity Expansion | Gene therapy manufacturers in Boston and Basel specify 0.1-micron-rated products for mycoplasma retention assurance. |
| EU MDR Technical Documentation Investment | CE marking continuity for filter-integrated Class IIb and III devices requires extensive clinical evidence portfolios. |
| Sustainability Program Development | EU Green Deal circular economy requirements create preference for bio-based housing materials in hospital procurement. |
| Point-of-Care Diagnostic Partnership | Microfluidic filtration modules with lateral flow assay platforms open ambulatory and home testing channels. |
Research Methodology
A standing panel of biomedical engineers, hospital GPO contracts managers, regulatory affairs leads at filter manufacturers, and pharmaceutical quality assurance directors provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EMA GMP Annex 1 guidance documents, ISO 13485 certification databases, and hospital procurement contract records. Bottom-up segment sizing triangulated against top-down industry aggregate benchmarks.
Consistency checks validated volume and value outputs against external regulatory filing trajectories and capital expenditure disclosures across the modeling period. The analytical framework segmented by product type, technology tier, application, and end-user channel, with additional modeling across regional regulatory clusters. CAGRs derived from regression analysis of historical replacement cycle compression and procurement consolidation patterns, incorporating EMA GMP Annex 1 revision implementation timelines and METI-backed dialysis clinic consolidation schedules as industry-specific inputs.
Underlying assumptions cover sterility assurance guideline stability and polymer supply continuity, with deviation risk concentrated in REACH PFAS restriction enforcement and single-source resin allocation disruptions. Revision becomes warranted when endotoxin detection threshold harmonization across USP, EP, and JP pharmacopeial methods crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Contact Lens Inspection Equipment Market
Medical Equipment
CO2 Medical Laser Systems Market
Medical Equipment
Sanitary Napkin Equipment Market
Medical Equipment
Global Medical Refrigerators Market
Medical Equipment
Global Cardiopulmonary Stress Testing Systems Market
Medical Equipment
Mercury Thermometer Market
Medical Equipment
Medical Whirlpool Market
Medical Equipment
ECG Equipment and Management Systems Market
Medical Equipment
Brazil Massage Equipment Market
Medical Equipment
US ECG Equipment Market
Medical Equipment
Global Operating Table Mattresses Market
Medical Equipment
Tanning Units Market
Medical Equipment
Medical Pediatric Bed Market
Medical Equipment
Global Indirect Calorimeter Market
Medical Equipment
Sterilization Equipment Market
Medical Equipment
Refurbished Medical Equipment Market