
 PMMA Healthcare Market | 2026-2036
PMMA Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
PMMA Healthcare Market Insights
Polycarbonate is realigning competitive economics in transparent medical housing as device makers weigh optical clarity against sterilization durability. Evonik Industries leverages captive methacrylate monomer supply to sustain margin control across implant-grade resin lines. Mitsubishi Chemical anchors Asian supply through integrated acrylic acid chains, while SABIC competes on high-heat polymer portfolios that challenge PMMA in autoclave-intensive settings.
PMMA in healthcare denotes implant-grade polymethyl methacrylate formulated to ISO 10993 biocompatibility standards, typically polymerized from ultra-high-purity methyl methacrylate monomer to achieve light transmission above 92% and flexural strength near 90 MPa for load-bearing orthopedic and dental applications. Intraocular lenses and bone cements dominate current volume, with molding technology leading fabrication throughput for standard geometries while 3D printing captures fastest growth in patient-specific cranial implants and dental prosthetics where anatomical matching commands premium positioning. Co-extrusion occupies narrower but defensible territory in multi-layer catheter shafts requiring graduated stiffness profiles.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations shape product development timelines and testing expenditures for PMMA device entrants. Japan's PMDA imposes additional clinical data thresholds on permanent implant classifications that filter smaller suppliers from premium segments. Stakeholders must monitor evolving sterilization validation protocols as gamma and electron-beam tolerance specifications tighten across notified bodies.
Market Dynamics
Patient-specific manufacturing requirements are compressing production cycles across PMMA implant workflows, forcing dental laboratories and orthopedic device makers to retool for additive fabrication methods that bypass traditional molding lead times.
Growth Catalysts
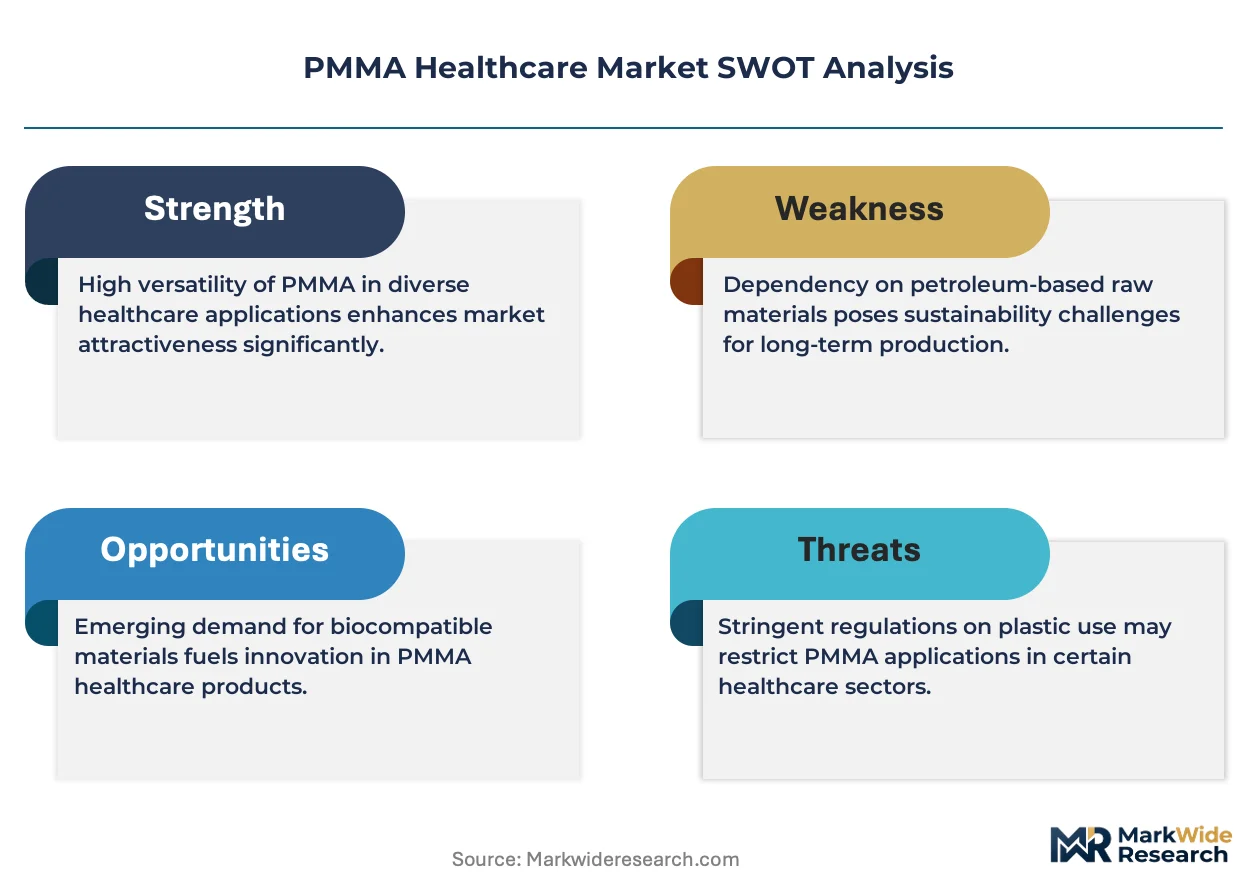
- EU MDR biocompatibility mandates:Stricter ISO 10993 testing protocols for permanent implants are filtering out lower-grade resins and consolidating demand around certified PMMA suppliers with established technical documentation.
- 3D printing adoption in cranial reconstruction:Anatomically matched implants command premium positioning as surgeons prioritize fit precision over standard geometry inventory.
- Aging dental patient populations:Germany and Japan are expanding full-arch denture base production to address edentulism prevalence among cohorts over 65.
Market Restraints
- Methyl methacrylate monomer price volatility:Acrylic acid supply disruptions and energy input costs create margin pressure for non-integrated compounders lacking captive monomer production.
- Gamma sterilization degradation thresholds:PMMA's sensitivity to high-dose radiation limits reprocessing cycles and forces single-use configurations in certain catheter applications.
- Polycarbonate substitution in autoclave settings:Device makers facing repeated steam sterilization requirements are migrating transparent housings to higher-heat polymers despite optical transmission trade-offs.
Strategic Opportunities
- India's medical device PLI scheme:Domestic manufacturing incentives for implant-grade polymers are attracting compounders to establish localized compounding operations near Mumbai and Hyderabad surgical device clusters.
- Co-extrusion in neurovascular catheters:Multi-layer shafts requiring graduated stiffness profiles represent underpenetrated territory where PMMA's bondability with thermoplastic elastomers enables functional gradients.
- Japan PMDA fast-track pathways:Streamlined review for regenerative medicine products is opening channels for PMMA scaffolds in bone void filler applications.
Industry Challenges
- ISO 10993-5 cytotoxicity testing bottlenecks:Extended turnaround times at accredited laboratories are delaying product launch timelines for mid-tier device entrants lacking in-house biocompatibility screening.
- Cleanroom compounding capacity scarcity:Implant-grade resin production requires ISO 8 or better environments, and qualified facility expansion demands 18-24 month construction cycles with substantial capital outlay.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PMMA Healthcare Market |
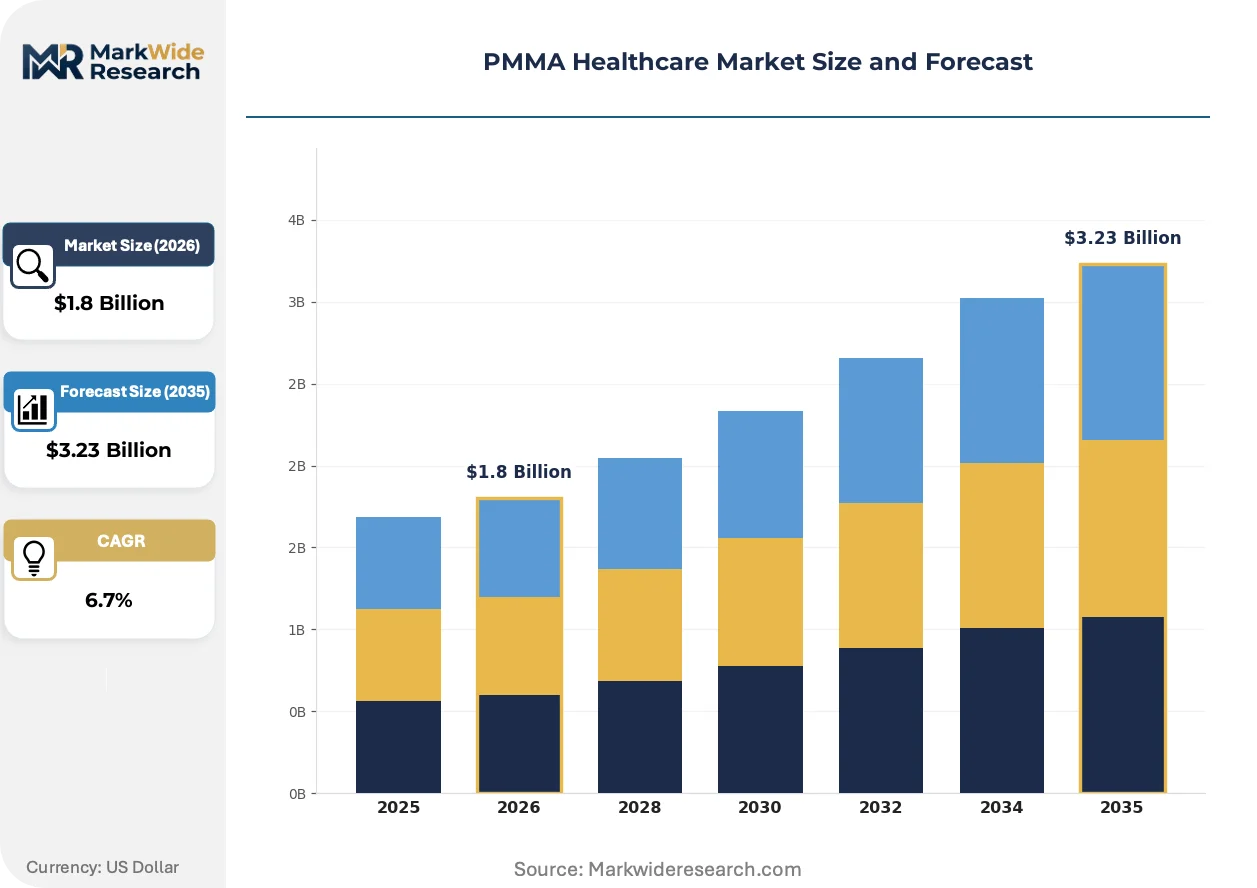
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthopedic Implants, Dental Products, Surgical Instruments, Drug Delivery Systems End User: Hospitals, Clinics, Laboratories, Rehabilitation Centers Application: Bone Cements, Intraocular Lenses, Prosthetics, Coatings Technology: Molding, 3D Printing, Co-extrusion, Casting |
| Companies Covered | Evonik Industries, Mitsubishi Chemical Corporation, BASF SE, Rohm and Haas, Asahi Kasei Corporation, SABIC, Sumitomo Chemical, Lucite International, Arkema Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PMMA Healthcare Market Trends and Innovations
Digitization of anatomical workflows is collapsing the traditional separation between diagnostic imaging and implant fabrication, with software-native production methods now governing how PMMA devices are designed, validated, and delivered.
Photopolymerization-based vat printing is overtaking fused filament fabrication for patient-specific dental prosthetics and cranial plates. Dental laboratories in Germany are adopting this technology to eliminate wax pattern labor and same-day delivery of definitive restorations. The compression of chairside turnaround from weeks to hours is restructuring laboratory economics and reducing inventory carrying requirements.
EU MDR technical documentation obligations are extending validation requirements for legacy PMMA implant products previously cleared under the Medical Device Directive. Manufacturers must now generate clinical evaluation reports and post-market surveillance data that the Directive did not mandate. Spinal implant suppliers with 510(k) clearance in the United States face parallel but non-identical evidentiary demands that complicate transatlantic product strategies.
Hospital procurement consolidation is concentrating purchasing power among integrated delivery networks that negotiate polymer supply contracts across multiple device categories. Orthopedic buyers in the United States are unbundling bone cement from kit configurations and sourcing PMMA separately to capture volume discounts. This disintermediation of traditional supplier relationships is compressing distributor margins and forcing compounders to develop direct commercial infrastructure.
PMMA Healthcare Market Segmentation
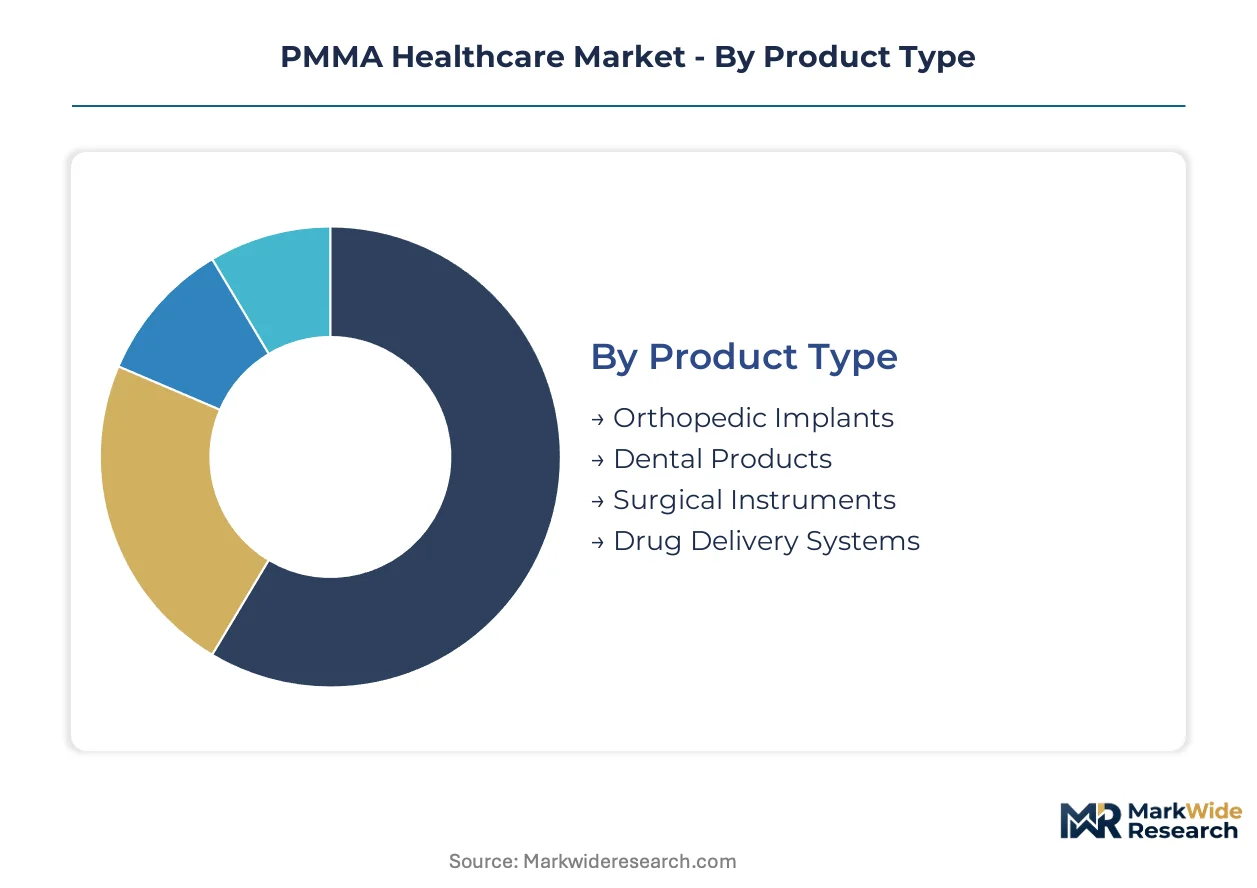
PMMA healthcare applications fragment across fabrication technologies, clinical settings, and anatomical targets, with each axis commanding distinct specification requirements and commercial pathways. Device makers must match material grade to sterilization tolerance, load-bearing demands, and regulatory jurisdiction simultaneously.
Product Type:
Material specification intensity varies by implant permanence and mechanical load requirements.
- Orthopedic Implants:High-viscosity bone cements and spinal spacers formulated to ISO 5833 standards dominate volume, with demand concentrating in United States ambulatory surgery centers where CMS reimbursement codes for cemented arthroplasty have stabilized procedural economics.
- Dental Products:Denture bases and provisional crowns leverage PMMA's polishability and tissue compatibility, with German dental laboratories expanding full-arch production under EU MDR technical documentation obligations that filter lower-grade suppliers.
- Surgical Instruments:Transparent retractors and instrument housings exploit optical clarity for visualization, though gamma sterilization limits restrict reprocessing cycles in certain configurations.
- Drug Delivery Systems:Reservoir housings for implantable pumps require barrier properties against permeation, with silicone-PMMA hybrids capturing niche applications in neurostimulation devices.
Orthopedic implants lead on scale; dental products lead on momentum.
End User:
Procurement authority and volume concentration shift dramatically across the care continuum.
- Hospitals:Integrated delivery networks in the United States negotiate polymer supply contracts across orthopedic and ophthalmic service lines, unbundling bone cement from kit configurations to capture volume leverage.
- Clinics:Outpatient ophthalmology practices in Japan drive intraocular lens consumption through PMDA-cleared premium toric and multifocal designs that command reimbursement differentials.
- Laboratories:Dental laboratories in Germany and Japan are retooling for photopolymerization-based vat printing, collapsing chairside turnaround from weeks to hours and eliminating wax pattern labor.
- Rehabilitation Centers:Prosthetic socket fabrication represents fragmented demand with lower specification barriers, though patient-specific 3D printing is penetrating this tier.
Hospitals concentrate purchasing power; laboratories are expanding most quickly through digital workflow adoption.
Application:
Anatomical site determines biocompatibility testing burden and sterilization protocol selection.
- Bone Cements:Antibiotic-loaded formulations for infection prophylaxis in joint replacement dominate orthopedic volume, with United States surgeons favoring pre-mixed cement with tobramycin or gentamicin.
- Intraocular Lenses:Foldable PMMA designs with square-edge profiles for posterior capsular opacification prevention represent premium positioning, with Japanese and United States markets driving toric and extended depth-of-focus iterations.
- Prosthetics:Cranial plates and facial reconstruction implants exploit 3D printing for anatomical matching, with patient-specific geometries commanding price premiums over standard inventory.
- Coatings:Drug-eluting layers on cardiovascular and orthopedic devices occupy narrower territory, with PMMA serving as carrier matrix for sirolimus or other active agents.
Bone cements anchor volume; prosthetics gain share fastest through additive manufacturing penetration.
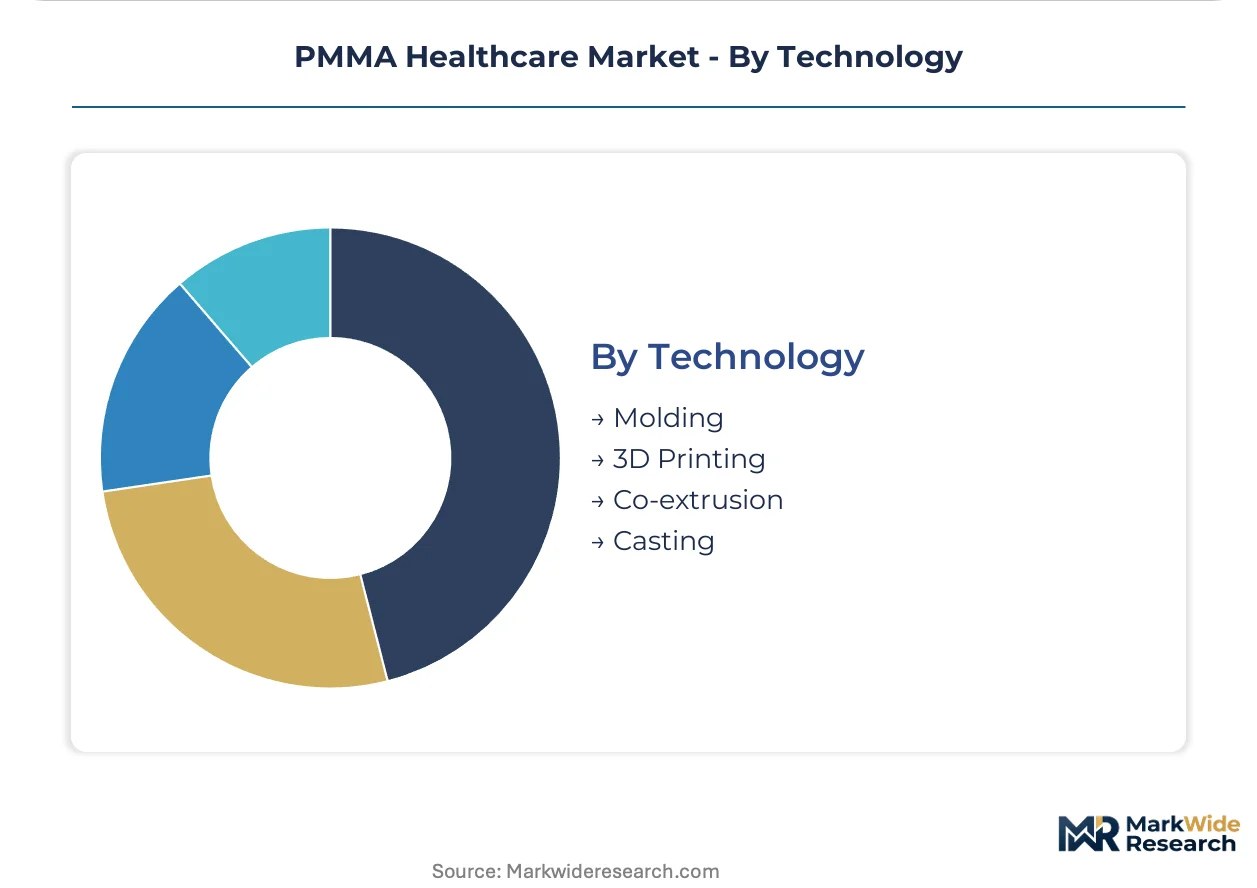
Technology:
Fabrication method governs lead time, geometric complexity, and economic threshold for patient-specific production.
- Molding:Injection and compression molding sustain throughput for standard geometries, with German and United States compounders operating ISO 8 cleanrooms for implant-grade resin production.
- 3D Printing:Photopolymerization-based vat printing is overtaking fused filament fabrication for dental prosthetics and cranial plates, with software-native design-to-fabrication workflows restructuring laboratory economics.
- Co-extrusion:Multi-layer catheter shafts requiring graduated stiffness profiles represent underpenetrated territory where PMMA's bondability with thermoplastic elastomers enables functional gradients.
- Casting:Legacy denture base production persists in cost-sensitive markets, though digital substitution is accelerating.
Molding dominates current throughput; 3D printing shows steepest expansion trajectory as patient-specific requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's dental laboratory clusters in North Rhine-Westphalia and Bavaria anchor European PMMA healthcare demand through precision prosthetics manufacturing and EU MDR compliance infrastructure.
United States
FDA 510(k) pathways for PMMA spinal implants have streamlined commercial access, concentrating orthopedic bone cement demand in ambulatory surgery centers across Texas and Florida. Hospital procurement consolidation among integrated delivery networks is unbundling cement from kit configurations to capture volume leverage.
Germany
Dental laboratories in Cologne and Munich are expanding full-arch denture base production under EU MDR technical documentation obligations that filter lower-grade resin suppliers. Stricter ISO 10993 testing protocols for permanent implants are consolidating demand around certified compounders with established biocompatibility documentation.
Japan
PMDA fast-track pathways for regenerative medicine products are opening channels for PMMA scaffolds in bone void filler applications, with Tokyo and Osaka ophthalmology clinics driving intraocular lens consumption through premium toric designs. Additional clinical data thresholds on permanent implant classifications filter smaller suppliers from premium segments.
India
Domestic manufacturing incentives under the medical device PLI scheme are attracting compounders to establish localized compounding operations near Mumbai and Hyderabad surgical device clusters. CDSCO regulatory harmonization efforts are reducing import dependency for implant-grade polymers in joint replacement procedures.
China
NMPA streamlined review pathways for innovative medical devices are accelerating PMMA intraocular lens approvals, with Shanghai and Suzhou emerging as precision molding centers for export-oriented orthopedic components. GB standards alignment with ISO 10993 is elevating biocompatibility requirements for domestic manufacturers.
PMMA Healthcare Market Competitive Landscape
Capacity expansion dominates the current landscape as compounders invest in ISO 8 cleanroom infrastructure to meet implant-grade resin demand. The vendor base stratifies between integrated petrochemical conglomerates with captive methacrylate supply and specialized medical polymer compounders lacking upstream integration. Three archetypes define positioning: integrated chemical majors controlling monomer-to-resin value chains, regional compounders serving dental laboratory clusters, and additive manufacturing material specialists. M&A activity and strategic partnerships represent the dominant competitive moves as mid-tier players seek biocompatibility certification capabilities.
Among European chemical majors, Evonik Industries and BASF SE exemplify integrated archetypes with methacrylate monomer capabilities, while Mitsubishi Chemical Corporation anchors Asian supply through acrylic acid chain integration. These three occupy positions where backward integration into monomer production sustains margin control across implant-grade resin lines.
| Leading Market Players |
|---|
| Evonik Industries |
| Mitsubishi Chemical Corporation |
| BASF SE |
| Rohm and Haas |
| Asahi Kasei Corporation |
| SABIC |
| Sumitomo Chemical |
| Lucite International |
| Arkema Group |
| Others |
Pricing and Supply Chain Analysis
Photopolymerization-based vat printing is collapsing traditional molding economics while simultaneously redistributing supply concentration toward dental laboratory clusters in Germany and Japan that command premium positioning through same-day turnaround capabilities.
Pricing Analysis
Methyl methacrylate monomer cost pass-through dominates pricing dynamics for non-integrated compounders lacking captive acrylic acid supply. Pricing stratifies across ISO 10993-certified implant grades, standard dental resins, and economy denture bases differentiated by biocompatibility documentation depth. Cost compression in economy tiers is intensifying because Indian PLI scheme entrants are scaling localized compounding near Mumbai surgical device clusters. Hospital procurement committees exhibit highest price sensitivity through unbundled cement sourcing, while cranial implant surgeons demonstrate lowest sensitivity due to anatomical matching premiums.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese dental laboratory clusters that anchor EU MDR-compliant resin demand. Supply concentrates in Germany, Japan, and the United States for implant-grade PMMA, with methyl methacrylate monomer, acrylic acid, and ultra-high-purity initiators as critical inputs. Tariff exposure on Asian methacrylate imports threatens margin structures for European compounders lacking backward integration. Distribution runs through integrated delivery networks in the United States and specialized dental laboratory distributors in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on digitization-driven workflow compression and premium-tier patient-specific implants displacing standard geometry inventory.
For Market Incumbents: Deploy captive monomer supply leverage to sustain margin control as polycarbonate substitution threatens autoclave-intensive transparent housing applications. Expand ISO 8 cleanroom capacity near Texas and Florida ambulatory surgery centers to secure orthopedic cement supply contracts. Fortify biocompatibility documentation depth against EU MDR technical documentation obligations that filter lower-grade resin suppliers from permanent implant segments.
For New Entrants and Emerging Players: Enter via photopolymerization material formulations for dental laboratories retooling in North Rhine-Westphalia and Bavaria. Target India's medical device PLI scheme zones near Hyderabad for localized competing operations with CDSCO regulatory harmonization tailwinds. Pursue hospital system partnership models that bypass traditional distributor relationships compressed by procurement consolidation.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional dental laboratory compounders lacking ISO 10993 certification capabilities. Long-term viability favors integrated chemical majors with methacrylate monomer control and additive manufacturing material specialists capturing patient-specific workflow economics. Monitor PMDA fast-track approval velocity for PMMA scaffolds in bone void filler applications as inflection signal for regenerative medicine premium tier expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 8 Cleanroom Capacity Expansion | Implant-grade resin production requires qualified facilities with 18-24 month construction cycles near United States surgical clusters. |
| Photopolymerization Material Development | Vat printing formulations for German dental laboratories eliminate wax pattern labor and compress chairside turnaround from weeks to hours. |
| Backward Integration into Methyl Methacrylate | Captive monomer supply insulates margin control against acrylic acid price volatility and energy input cost fluctuations. |
| Hospital System Direct Partnership | Integrated delivery networks unbundling bone cement from kit configurations create channel bypass opportunities for compounders. |
| PMDA Fast-Track Regulatory Pathway | Streamlined review for regenerative medicine products opens premium positioning for PMMA scaffolds in Tokyo and Osaka bone void filler markets. |
Research Methodology
Direct dialogue with dental laboratory technicians, orthopedic device procurement managers, biomedical engineers at ambulatory surgery centers, and PMMA compounder R&D directors grounded qualitative findings. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, PMDA approval registries, and customs trade data on methyl methacrylate monomer flows. Bottom-up and top-down triangulation cross-checked volume estimates against capacity disclosures and end-use consumption patterns.
Top-down modeling anchored macro healthcare polymer demand to procedure volume projections across joint replacement, spinal fusion, and cataract surgery categories. Segmentation dimensions included fabrication technology, implant permanence classification, anatomical application site, and regional regulatory cluster. CAGRs were derived from slope analysis of historical penetration rates adjusted for technology substitution effects and reimbursement code stability in United States CMS frameworks.
Inputs from PMDA, FDA, and EMA regulatory filings were available through the study window; gaps in private dental laboratory production data introduce uncertainty bands around photopolymerization adoption velocity assumptions. Forecasts reflect documented assumptions on sterilization protocol evolution and gamma degradation tolerance specifications. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Cell Washer Market
Medical Equipment
Medical Physics Market
Medical Equipment
ECG Equipment Market
Medical Equipment
Medical Equipment Reimbursement Market
Medical Equipment
Medical Automation Market
Medical Equipment
Global Gynecological Examination Chairs Market
Medical Equipment
Operating Table Market
Medical Equipment
Terminal Sterilization Market
Medical Equipment
North America Medical Carts Market
Medical Equipment
Global Laminar Airflow Cabinets Market
Medical Equipment
Surgical Lighting System Market
Medical Equipment
Auditory Brainstem Response Analyzers Market
Medical Equipment
Medical Linear Accelerators (MLA) Market
Medical Equipment
Global Blood Viscometer Market
Medical Equipment
Asia-Pacific Medical Carts Market
Medical Equipment
Global Medical Lasers Market