
 Operating Table Parts Market | 2026-2036
Operating Table Parts Market Size, Share, and Industry Trends Forecast 2026-2036
Operating Table Parts Market Outlook
Ambulatory surgical centers is unwinding the historical dominance of large hospital systems in operating table parts procurement. Getinge leverages its integrated sterilization and surgical infrastructure portfolio to sustain recurring parts demand across installed bases. Stryker anchors its position through proprietary table platform architectures that lock in replacement part cycles. Mizuho OSI specializes in neurosurgical and orthopedic table configurations, occupying a defensible niche in complex procedure settings.
Operating table parts comprise the mechanical, electromechanical, and structural subsystems that enable patient positioning, height adjustment, tilt articulation, and load-bearing stability during surgical interventions. These components typically integrate electric motors delivering torque outputs exceeding 3,500 Nm, precision-machined table tops with radiolucent panels, and sealed hydraulic actuators rated for biocompatibility under IEC 60601-1 standards. Stainless steel components command the largest material share due to sterilization durability requirements, while composite segments are gaining traction where weight reduction and radiolucency intersect. Electric motor assemblies represent the fastest-growing component category as motorized positioning displaces manual crank mechanisms in mid-tier installations.
The FDA enforces 21 CFR Part 820 quality system regulations that mandate design controls and supplier qualification for table part manufacturers seeking US market access. EMA's Medical Device Regulation imposes stricter clinical evidence and post-market surveillance obligations across European supply chains, reshaping documentation burdens for component vendors. ISO 13485 certification has become a baseline qualification for tier-one procurement channels rather than a differentiator. Stakeholders must monitor how evolving cybersecurity annexes to medical device standards will reshape motor control and connectivity subsystems in next-generation table architectures.
Market Dynamics
The transition from manual crank mechanisms to motorized positioning systems is restructuring procurement patterns across hospital systems and ambulatory surgical centers, compressing replacement cycles and elevating electric motor assemblies to the fastest-growing component category.
Growth Catalysts
- FDA 21 CFR Part 820:The quality system regulation mandates validated supplier qualification, creating pull for certified component vendors with documented traceability.
- Radiolucent composites:These materials enable intraoperative imaging without patient repositioning, accelerating adoption in orthopedic and neurosurgical table configurations.
- Germany's hospital infrastructure renewal:Federal state-level procurement programs sustain premium component demand through precision engineering clusters in Baden-Württemberg and Bavaria.
Market Restraints
- Stainless steel price volatility:Nickel and chromium input cost swings compress margin stability for sterilization-grade structural components.
- EMA MDR documentation burdens:The Medical Device Regulation's clinical evidence requirements extend certification timelines for European component suppliers.
- Hydraulic actuator obsolescence:Electric linear actuators are displacing sealed hydraulic systems in mid-tier installations, stranding legacy supplier capabilities.
Strategic Opportunities
- Cybersecurity annexes to IEC 60601-1:Network-connected motor control subsystems create white space for vendors with embedded security architectures.
- India's PLI scheme for medical devices:Production-linked incentives attract component manufacturing investment toward domestic hospital procurement expansion.
- Modular table system leasing:Ambulatory surgical centers are adopting subscription-based access models, shifting revenue from unit sales to recurring parts and service streams.
Industry Challenges
- IEC 60601-1 third edition testing:Electromagnetic compatibility validation for motorized assemblies extends product development cycles by 8-14 months.
- Legacy table platform integration:Proprietary communication protocols from installed base manufacturers block aftermarket component interoperability.
- Precision machining workforce scarcity:Radiolucent panel fabrication requires specialized CNC programming skills concentrated in aging German and Swiss labor pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Operating Table Parts Market |
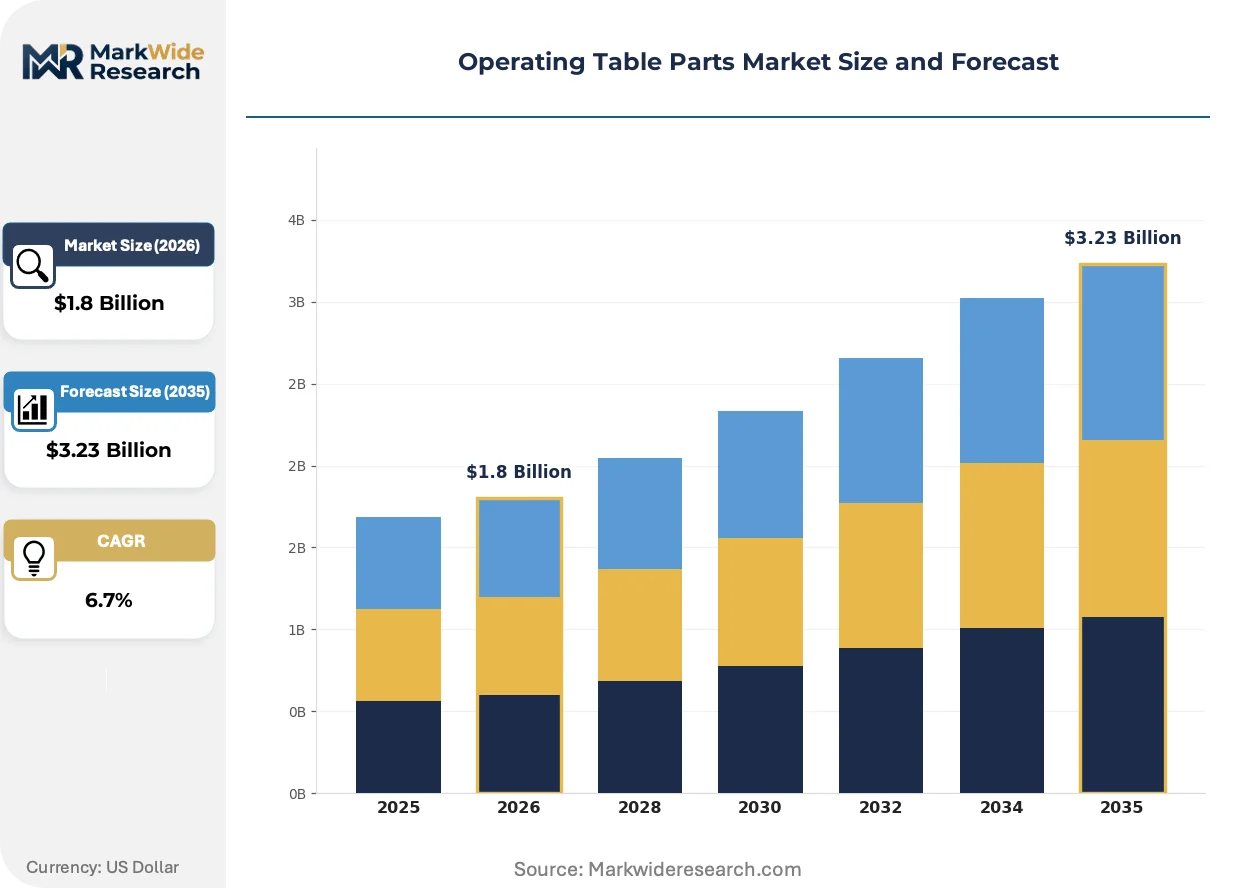
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Table Base, Table Top, Electric Motor, Hydraulic System Material: Stainless Steel, Aluminum, Plastic, Composite Application: Orthopedic Procedures, Surgical Procedures, Emergency Care, Patient Transport End User: Hospitals, Surgical Centers, Clinics, Ambulatory Care Facilities |
| Companies Covered | Getinge, Stryker, STERIS Healthcare, Baxter, Mizuho OSI, Skytron, ALVO Medical, Merivaara Corp, medifa GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Operating Table Parts Market Strategic Shifts
Digital connectivity and material science advances are compressing the boundary between mechanical positioning hardware and integrated surgical infrastructure, enabling real-time telemetry and predictive maintenance capabilities.
Brushless DC motor assemblies with integrated encoder feedback are miniaturizing drive mechanisms while maintaining torque outputs above 3,500 Nm. Ambulatory surgical centers in the United States and Germany are specifying these compact actuators for space-constrained procedure rooms. The technology is miniaturizing control cabinet footprints and enabling distributed motor architectures that reduce cable routing complexity.
EMA's Medical Device Regulation imposes Unique Device Identification mandates across European supply chains, forcing component vendors to restructure labeling and traceability systems. Manufacturers serving EU hospital procurement channels must now maintain post-market surveillance databases linking individual parts to finished device registrations. Motor control and connectivity subsystems face heightened documentation scrutiny as cybersecurity annexes expand.
After-sales service unbundling is separating parts procurement from OEM maintenance contracts, enabling independent distributors to capture replacement cycles. Hospital materials management departments in Germany and the United States are negotiating direct component sourcing agreements, bypassing integrated sterilization and surgical infrastructure vendors. This pattern concentrates price pressure on electric motor assemblies and precision-machined table tops while elevating ISO 13485 certification to baseline qualification status.
Operating Table Parts Market Segmentation
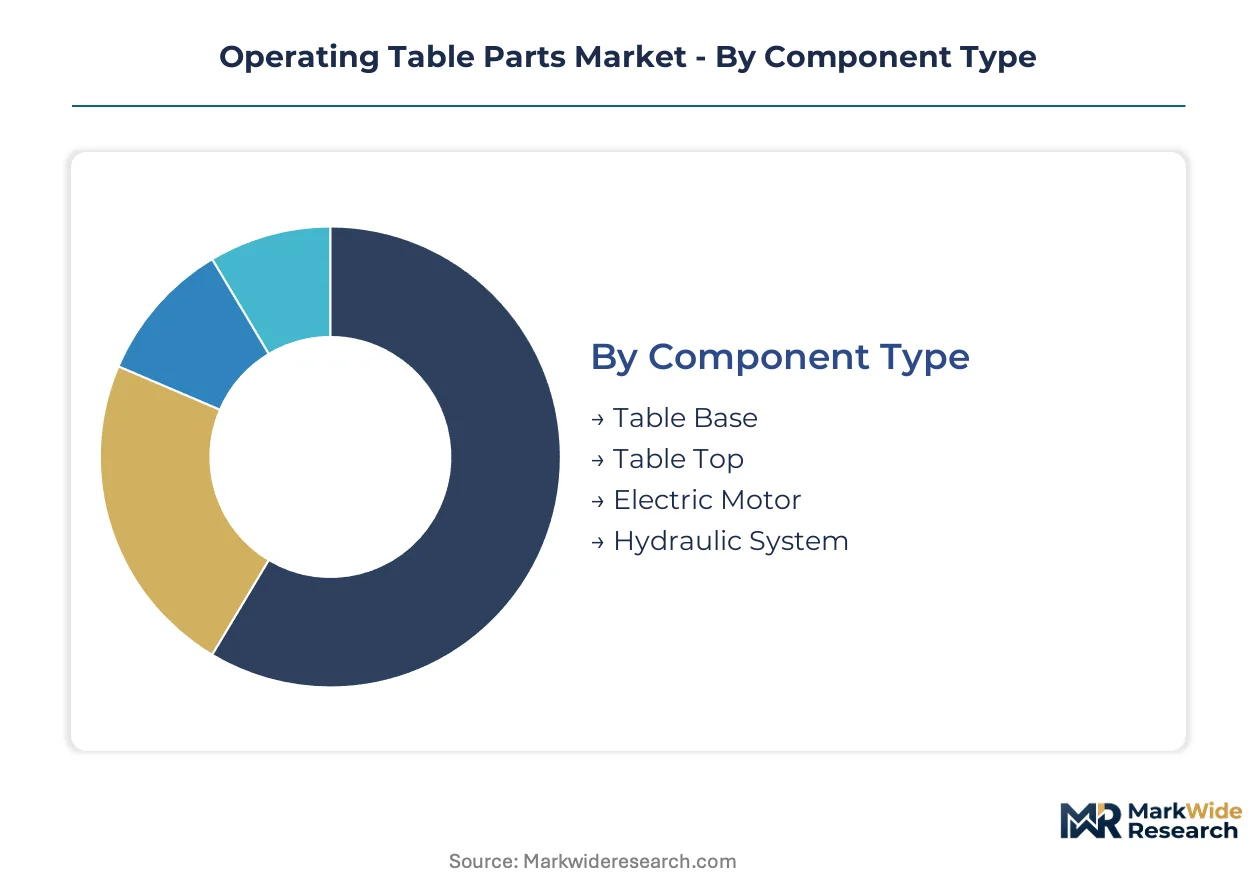
Operating table parts procurement flows through distinct channel configurations that shape margin structures and vendor relationships. Component type and material selection drive tier-one supplier qualification, while end-user scale determines whether parts move through integrated OEM contracts or independent distribution.
Component Type:
Channel concentration varies sharply across mechanical versus electromechanical subsystems, with motorized assemblies commanding premium sourcing pathways.
- Electric Motor:Brushless DC assemblies with integrated encoder feedback deliver torque outputs exceeding 3,500 Nm for motorized positioning. Demand concentrates in ambulatory surgical centers across Germany and the United States as these facilities specify compact actuators for space-constrained procedure rooms.
- Table Top:Precision-machined surfaces incorporate radiolucent panels enabling intraoperative imaging without patient repositioning. German hospital infrastructure renewal programs sustain premium sourcing for these components through Baden-Württemberg engineering clusters.
- Table Base:Structural load-bearing frames anchor stability during surgical interventions.
- Hydraulic System:Sealed actuators rated for biocompatibility under IEC 60601-1 standards face displacement pressure from electric linear alternatives.
By volume, table base and hydraulic systems lead installed base replacement. By growth pace, electric motor assemblies are expanding most quickly.
Material:
Cost tier stratification separates sterilization-durable metals from lightweight composites, with procurement channels diverging at the certification threshold.
- Stainless Steel:Nickel-chromium alloys dominate structural components requiring repeated sterilization cycles. FDA 21 CFR Part 820 validation requirements lock in qualified supplier relationships for these materials.
- Composite:Carbon-fiber and polymer matrices enable radiolucency combined with weight reduction. Orthopedic and neurosurgical table configurations in German precision engineering clusters drive specification of these advanced materials.
- Aluminum:Lightweight structural elements serve secondary load-bearing applications.
- Plastic:Polymer housings and cable management components complete subsystem enclosures.
By installed base, stainless steel dominates. By specification momentum, composite materials are gaining share fastest.
Application:
Procedure complexity dictates performance tier requirements, with imaging-intensive specialties commanding premium component integration.
- Orthopedic Procedures:Traction-enabled table configurations require precision-machined tops with integrated radiolucent panels. German federal state-level procurement programs sustain demand for these specialized assemblies.
- Surgical Procedures:General operating theater applications span the full component spectrum from basic manual tables to fully motorized systems.
- Emergency Care:Rapid-deployment table systems prioritize durability and simplified maintenance protocols.
- Patient Transport:Mobile stretcher-to-table integration demands lightweight structural materials.
By revenue concentration, orthopedic procedures lead. By expansion trajectory, emergency care applications show steepest growth.
End User:
Customer scale determines procurement modality, with large hospital systems leveraging integrated contracts against ambulatory facilities adopting modular leasing.
- Ambulatory Care Facilities:Outpatient surgery volumes are compressing replacement cycles for motorized positioning systems. Subscription-based access models in the United States are shifting these facilities toward recurring parts and service revenue streams.
- Hospitals:Large integrated delivery networks negotiate direct component sourcing agreements, bypassing OEM maintenance contracts for electric motor assemblies and precision-machined tops.
- Surgical Centers:Specialized procedure facilities concentrate demand for neurosurgical and orthopedic table configurations.
- Clinics:Smaller-scale settings prioritize cost-optimized manual table systems with extended replacement intervals.
By procurement volume, hospitals lead. By contract modality innovation, ambulatory care facilities are pulling ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering clusters export high-grade table components to hospital systems across the United States and Western Europe, while Chinese manufacturers supply cost-optimized structural parts to emerging procurement channels in Southeast Asia and the Middle East.
United States
Ambulatory surgical centers in Texas and Florida are compressing replacement cycles for motorized positioning systems. FDA 21 CFR Part 820 mandates validated supplier qualification, locking in relationships with certified component vendors. The Greater Boston medical device corridor concentrates design and testing capabilities for next-generation motor control architectures.
Germany
Federal state-level hospital infrastructure renewal programs sustain premium demand for radiolucent table tops and precision-machined surfaces. EMA Medical Device Regulation imposes Unique Device Identification mandates, forcing component vendors to restructure traceability systems. Baden-Württemberg engineering clusters anchor stainless steel fabrication and composite panel machining for orthopedic table configurations.
China
Domestic hospital procurement expansion drives volume demand for electric motor assemblies and structural table bases. NMPA medical device registration requirements extend certification timelines for component suppliers seeking market access. The Yangtze River Delta manufacturing belt concentrates cost-competitive fabrication of hydraulic actuators and polymer housings for regional supply chains.
India
Production-linked incentive schemes attract component manufacturing investment toward domestic hospital procurement growth. CDSCO medical device rules impose quality system obligations on table part importers and local manufacturers. Maharashtra and Gujarat industrial zones host emerging fabrication capabilities for stainless steel structural components and electric drive subsystems.
Japan
Aging hospital infrastructure replacement sustains demand for precision-machined table tops and sealed actuator systems. PMDA quality management system requirements align with global ISO 13485 standards for component vendor qualification. The Chubu region around Nagoya maintains specialized CNC machining capabilities for radiolucent composite panels used in neurosurgical applications.
Operating Table Parts Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and certification depth, producing a tiered structure where scale-driven OEMs anchor premium procurement channels while mid-cap fabricators capture aftermarket replacement cycles. Three archetypes dominate: integrated surgical infrastructure vendors with captive parts demand, precision engineering specialists serving orthopedic and neurosurgical niches, and contract manufacturers supplying cost-optimized structural components. Consolidation pressure operates through M&A targeting installed base service rights and geographic expansion into ambulatory care procurement channels.
Among integrated surgical infrastructure vendors, Getinge and Stryker exemplify archetypes that sustain recurring parts demand across installed bases through proprietary platform architectures. Mizuho OSI occupies a specialist position within the precision-engineering tier, representing the neurosurgical and orthopedic configuration segment where complex procedure requirements sustain premium component sourcing. These three companies anchor the competitive landscape across distinct value chain positions without overlapping strategic emphasis.
| Leading Market Players |
|---|
| Getinge |
| Stryker |
| STERIS Healthcare |
| Baxter |
| Mizuho OSI |
| Skytron |
| ALVO Medical |
| Merivaara Corp |
| medifa GmbH |
| Others |
Value Chain & Pricing Dynamics
Electric linear actuator displacement of sealed hydraulic systems simultaneously concentrates supply geography in German precision engineering clusters and compresses pricing economics for legacy actuator suppliers unable to pivot motor control architectures.
Pricing Analysis
Technology-generation pricing gaps separate brushless DC motor assemblies with integrated encoder feedback from legacy hydraulic actuators and emerging smart motor platforms. Three-tier pricing structure across premium certified, standard compliant, and economy unbranded levels stratifies procurement channels, with FDA 21 CFR Part 820 validation and ISO 13485 certification driving price differentiation between tiers. Cost compression in mid-tier electric motor assemblies intensifies because Chinese manufacturers are scaling brushless DC production for domestic hospital procurement expansion. Ambulatory surgical centers in the United States exhibit highest price sensitivity due to subscription-based leasing models, while German hospital infrastructure renewal programs sustain lowest sensitivity through federal state-level premium component sourcing.
Supply Chain Analysis
Inventory lead times for precision-machined radiolucent panels extend disproportionately versus standardized structural components due to specialized CNC programming workforce scarcity. Supply concentrates in Germany for composite panel machining and stainless steel fabrication, in China for electric motor assemblies and polymer housings, and in Japan for sealed actuator systems. Raw material dependencies rest on nickel-chromium alloys for sterilization-grade components, carbon-fiber matrices for radiolucent applications, and rare-earth magnets for brushless DC motors. Single-source vulnerability concentrates in Baden-Württemberg precision engineering clusters where aging workforce demographics constrain radiolucent panel fabrication capacity. Distribution runs through integrated OEM service contracts for hospital systems and independent distributors for aftermarket replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a defensive moat anchored in regulatory entrenchment: FDA 21 CFR Part 820 validation requirements and EMA MDR documentation burdens create multi-year certification timelines that lock out unqualified competitors.
For Market Incumbents: Shield installed base service rights by deepening backward integration into brushless DC motor assembly production and capturing direct sourcing agreements with hospital materials management departments bypassing OEM maintenance contracts. Electric linear actuator substitution threatens legacy hydraulic suppliers. Certification investment in IEC 60601-1 third edition electromagnetic compatibility validation extends product development cycles but secures tier-one procurement channel access. For New Entrants and Emerging Players: Aftermarket cybersecurity retrofit services for network-connected motor control subsystems represent a service-layer gap where incumbents under-serve legacy installed bases. India's PLI scheme for medical devices offers the most penetrable geography for component manufacturing investment toward domestic hospital procurement growth. Independent distributors capturing unbundled parts procurement from hospital materials management departments provide the clearest go-to-market angle outside integrated OEM contracts. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed precision engineering specialists in German orthopedic and neurosurgical table configuration niches. Long-term viability across the five-to-ten year window hinges on cybersecurity annex compliance capabilities and ambulatory surgical center subscription model participation. Watch for FDA enforcement patterns on 21 CFR Part 820 supplier qualification as the inflection indicator for consolidation pressure on uncertified component vendors.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 21 CFR Part 820 Compliance Pathway | Validated supplier qualification locks in tier-one hospital procurement channel access. |
| EMA MDR Unique Device Identification Implementation | Traceability system restructuring separates qualified European component vendors from marginal suppliers. |
| Hospital System Direct Sourcing Partnership | Bypassing OEM maintenance contracts captures replacement cycle revenue from materials management departments. |
| Cybersecurity Annex Engineering Investment | Embedded security architectures in motor control subsystems create white space for next-generation table platforms. |
| Modular Table System Leasing Model | Subscription-based access shifts revenue from unit sales to recurring parts and service streams in ambulatory surgical centers. |
Study Parameters
The analysis maps electric motor assemblies, precision-machined table tops, sealed hydraulic actuators, and structural table bases, each validated through biomedical engineers, hospital purchasing committee members, GPO contracts managers, and aftermarket service heads. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EMA medical device registration databases, hospital procurement records, and ISO 13485 certification registries. Bottom-up component demand modeling and top-down hospital infrastructure spending analysis provided triangulation across data sources.
Consistency checks validated volume and value outputs against external benchmarks including customs trade data for stainless steel and composite material flows, regional hospital capital expenditure disclosures, and ambulatory surgical center construction permitting records. Segmentation dimensions modeled span component type, material grade tier, application complexity, and end-user scale across the projection horizon. CAGRs derived from installed base replacement cycle analysis, motorized positioning adoption curves, and outpatient surgery volume trajectories. Industry-specific forecast inputs include brushless DC motor torque specification trends and radiolucent panel fabrication capacity constraints.
Underlying assumptions cover FDA enforcement continuity on 21 CFR Part 820, EMA MDR implementation timelines, and German federal state-level hospital infrastructure renewal funding stability, with deviation risk concentrated in nickel and chromium input cost volatility and precision machining workforce availability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Radiation Therapy Equipment Market
Medical Equipment
Biomedical Refrigerators and Freezers Market
Medical Equipment
Manufacturing on Demand for Medical Market
Medical Equipment
Tissue Culture Incubator Market
Medical Equipment
US Medical Carts Market
Medical Equipment
Dual Energy X-Ray Absorptiometry (Dexa) Equipment Market
Medical Equipment
Global Latex Medical Gloves Market
Medical Equipment
Medical Oxygen Cylinders Market
Medical Equipment
China Radiotherapy Market
Medical Equipment
North America Radiotherapy Market
Medical Equipment
Equine Operating Tables Market
Medical Equipment
Medical Gas Cylinders Market
Medical Equipment
Global Portable Beds Market
Medical Equipment
Cryochambers Market
Medical Equipment
US Durable Medical Equipment Market
Medical Equipment
Home Medical Equipment Market