
 Global Portable Beds Market | 2026-2036
Global Portable Beds Market Size, Share, and Industry Trends Forecast 2026-2036
Global Portable Beds Market Outlook
Vietnamese metal fabrication clusters is hardening as a supply base for portable bed frames and folding mechanisms. BESTAR Inc. leverages Canadian manufacturing scale to dominate North American institutional contracts. Jay-Be Ltd. anchors British demand through specialized folding bed engineering for hospitality and healthcare channels. Coleman competes in outdoor inflatable segments with channel control across mass retail and specialty camping distributors.
Portable beds are collapsible or inflatable sleeping platforms engineered for temporary deployment, typically incorporating steel or aluminum frames with fabric or air-chamber support surfaces rated for specific load capacities and cycle-fold durability. Their primary commercial purpose spans emergency healthcare provisioning, hospitality overflow capacity, recreational camping, and residential space optimization. Folding beds command the largest revenue pool among product types due to institutional repeat purchasing, while inflatable beds represent the fastest-expanding segment as air-chamber polymers improve puncture resistance and thermal retention. Metal-framed units sustain premium positioning in hospital and hotel end-use channels where sanitation protocols and load-bearing standards exceed residential requirements.
FDA 510(k) clearance requirements govern hospital-grade portable beds sold in the United States, while the EU Medical Device Regulation and CE marking framework shape product access across European healthcare procurement channels. ISO 13485 quality management standards further constrain manufacturer eligibility for clinical tenders, filtering supplier pools toward vertically integrated producers with certified testing laboratories. Stakeholders must monitor evolving fire-retardant fabric standards and weight-capacity disclosure mandates as regulators tighten safety expectations for both institutional and consumer segments.
Market Dynamics
EU Medical Device Regulation tightening is forcing ISO 13485-certified manufacturers to absorb elevated testing costs while Vietnamese metal clusters capture frame fabrication share from legacy European suppliers.
Growth Catalysts
- EU MDR compliance mandates:Hospital-grade portable bed procurement now requires CE marking under stricter safety protocols, filtering tenders toward certified producers with captive testing laboratories.
- Home healthcare expansion:Aging demographics in Germany and Japan are accelerating institutional purchasing of foldable patient beds for residential medical deployment.
- Polymer thermal retention:Air-chamber polymers with improved puncture resistance are displacing traditional coil-spring mechanisms in recreational camping segments.
Market Restraints
- Steel input volatility:Aluminum frame producers face margin compression when ferrous metal prices spike, constraining substitution economics for lightweight hospital-grade units.
- FDA 510(k) timeline friction:United States market entry requires 90-180 day clearance windows that deter smaller fabricators from clinical channel participation.
- Folding mechanism durability thresholds:Cycle-fold testing standards exceed capabilities of non-specialized metalworking suppliers, concentrating certified production in established clusters.
Strategic Opportunities
- Indian hospitality retrofit:Budget hotel chains in Maharashtra and Karnataka are adopting space-optimizing folding beds for seasonal occupancy surge capacity.
- Fire-retardant fabric mandates:Evolving NFPA 701 and BS 5852 standards create specification windows for textile suppliers with certified coating capabilities.
- Direct-to-institution digital channels:Hospital procurement platforms in the United States are disintermediating traditional medical distributor networks for standardized portable bed SKUs.
Industry Challenges
- Welding certification scarcity:ISO 3834-compliant aluminum frame fabrication requires specialized operator credentials that Vietnamese clusters are racing to scale.
- Legacy hospital infrastructure:Older United States medical facilities lack electrical compatibility with motorized adjustable portable beds, forcing manual-model substitutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Portable Beds Market |
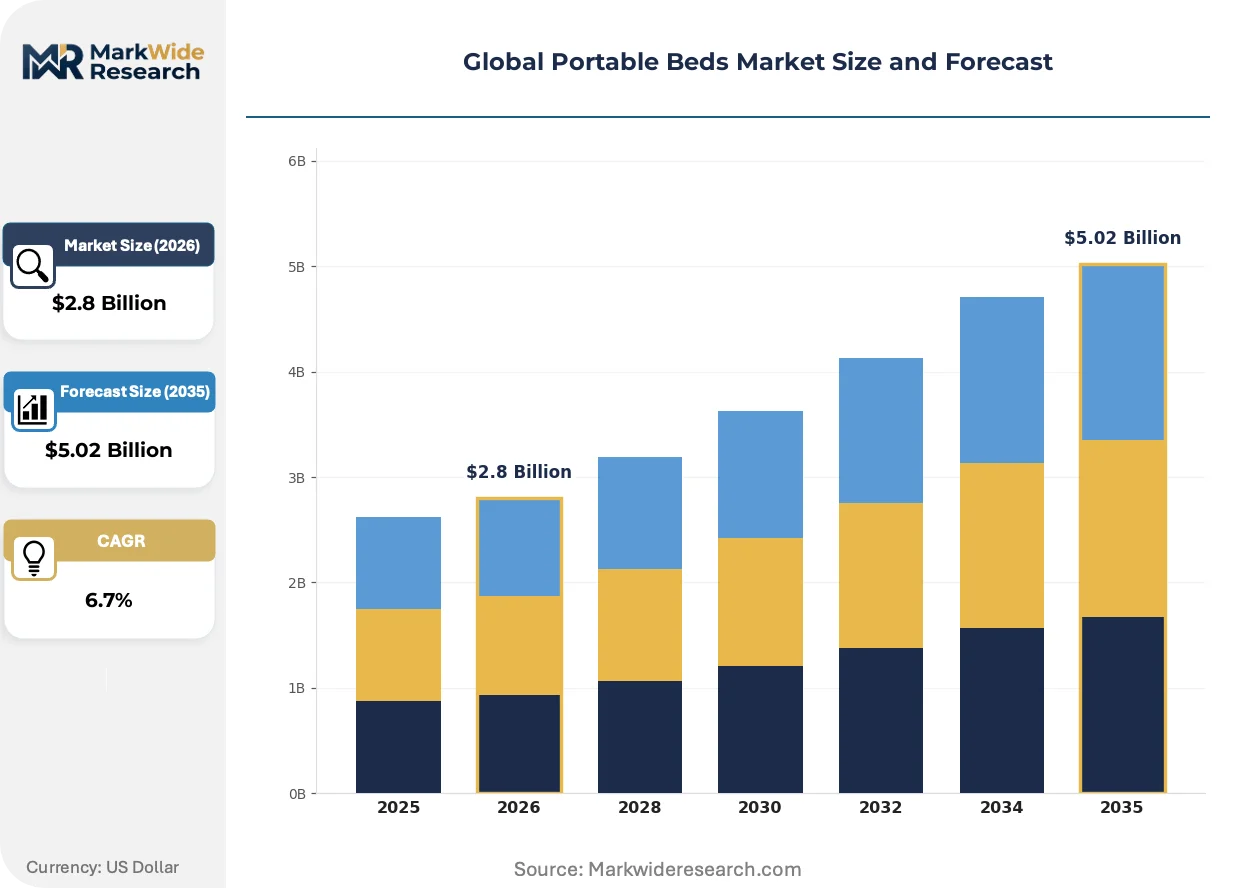
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folding Beds, Inflatable Beds, Rollaway Beds, Futons Material: Metal, Wood, Plastic, Fabric End User: Hotels, Hospitals, Camping, Home Use Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | BESTAR Inc., Jay-Be Ltd., Millard Brands, SICO Inc., Newell Brands Inc., IKEA, Coleman, Intex, Zinus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Portable Beds Market Strategic Shifts
Material science advances and procurement digitization are compressing traditional supplier hierarchies while regulatory fragmentation across healthcare jurisdictions creates certification complexity.
Modular aluminum extrusion systems with snap-fit joint technology are decentralizing portable bed assembly from centralized factories to regional fulfillment nodes. Hospital systems in Texas and Florida are piloting rapid-deployment inventory models that source flat-packed frames for on-site assembly. This distributed manufacturing architecture compresses logistics costs and accelerates emergency surge capacity deployment.
REACH chemical restrictions on flame-retardant additives are compelling textile suppliers to reformulate coating compounds for EU market access. Industrial consequences include 12-18 month reformulation cycles and elevated R&D allocation for bedding fabric producers. German and French hospital procurement channels are prioritizing suppliers with pre-certified Oeko-Tex Standard 100 compliance to preempt regulatory friction.
Subscription-based equipment leasing is displacing capital purchase models for hospitality overflow capacity. Hotel operators in Tokyo and Osaka are contracting seasonal bed fleets through third-party logistics providers rather than owning depreciating assets. This consumption-pattern shift transfers maintenance liability to fleet operators while compressing manufacturer margins through volume-commitment negotiations.
Global Portable Beds Market Segmentation
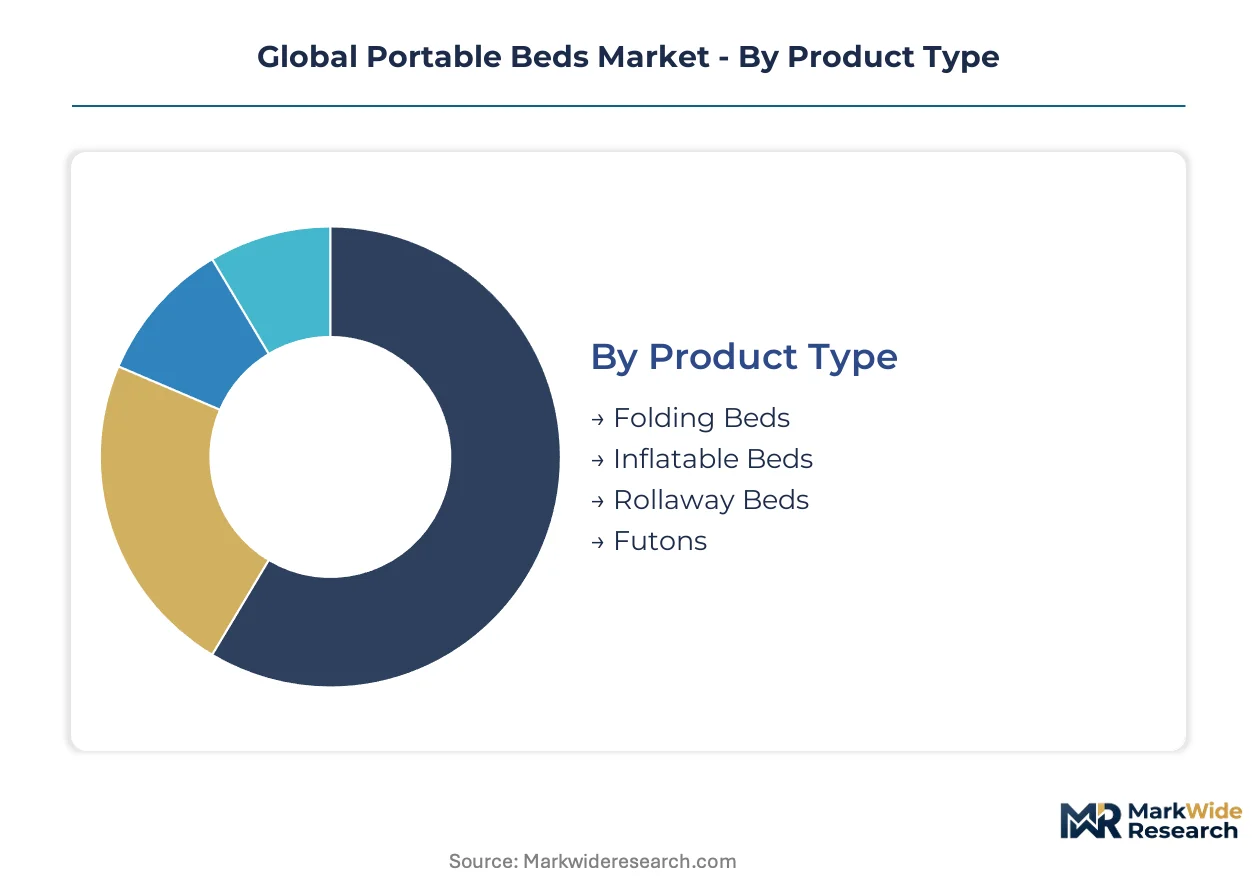
Certification requirements fragment portable bed procurement across healthcare, hospitality, and consumer channels. Each segment carries distinct regulatory burdens that filter supplier eligibility and shape margin structures.
Product Type:
FDA 510(k) clearance and EU MDR CE marking requirements concentrate most heavily on hospital-grade segments, while recreational categories face lighter conformity obligations.
- Folding Beds:Steel or aluminum frames with fabric support surfaces engineered for cycle-fold durability exceeding institutional testing thresholds. Hospital systems in Germany and Japan command repeat procurement volumes for residential medical deployment, though ISO 13485 certification requirements exclude non-specialized fabricators from clinical tenders.
- Inflatable Beds:Air-chamber polymer construction with puncture-resistant thermal retention layers displacing coil-spring mechanisms. Camping distributors across the United States and mass retail channels in Canada are expanding SKU breadth as polymer chemistry improves cold-weather performance.
- Rollaway Beds:Collapsible frame systems with caster-mounted mobility for hospitality overflow capacity.
- Futons:Convertible cushion-and-frame hybrids serving residential space optimization in Japanese and Korean urban markets.
Leading the category by volume: Folding Beds. Growing fastest: Inflatable Beds.
Material:
Cost tier stratification separates premium institutional specifications from economy consumer offerings, with certification-grade metals commanding price multiples over standard alternatives.
- Metal:Aluminum and steel alloys rated for load-bearing capacity and sanitation protocol compatibility in clinical environments. EU MDR compliance mandates and FDA 510(k) pathways filter procurement toward ISO 3834-certified welding operations, with Vietnamese fabrication clusters racing to scale operator credentials.
- Fabric:Support surfaces and upholstery textiles subject to evolving fire-retardant standards including NFPA 701 and BS 5852. REACH chemical restrictions in Europe are compelling 12-18 month reformulation cycles for coating compounds, with German hospital procurement prioritizing pre-certified Oeko-Tex Standard 100 suppliers.
- Wood:Frame construction for hospitality and residential segments with lower cycle-fold durability requirements.
- Plastic:Injection-molded components for lightweight recreational and economy-tier institutional applications.
Premium positioning concentrates in Metal. Fastest material transition: Fabric certification upgrades.
End User:
Application-specific durability standards and deployment frequency create divergent procurement patterns across institutional and consumer segments.
- Hospitals:Motorized and manual adjustable beds for residential medical deployment requiring electrical compatibility and load-rated frame certification. Aging demographics in Japan and Germany are accelerating institutional purchasing, though legacy United States medical facilities lack infrastructure for motorized units.
- Hotels:Space-optimizing folding and rollaway systems for seasonal occupancy surge capacity. Budget chains in Maharashtra and Karnataka are adopting fleet-based procurement models, while Tokyo and Osaka operators are shifting toward subscription-based equipment leasing.
- Camping:Recreational inflatable and lightweight folding platforms for outdoor temporary deployment.
- Home Use:Residential space optimization and guest accommodation solutions across urban density markets.
Procurement volume leader: Hospitals. Demand trajectory steepest: Hotels.
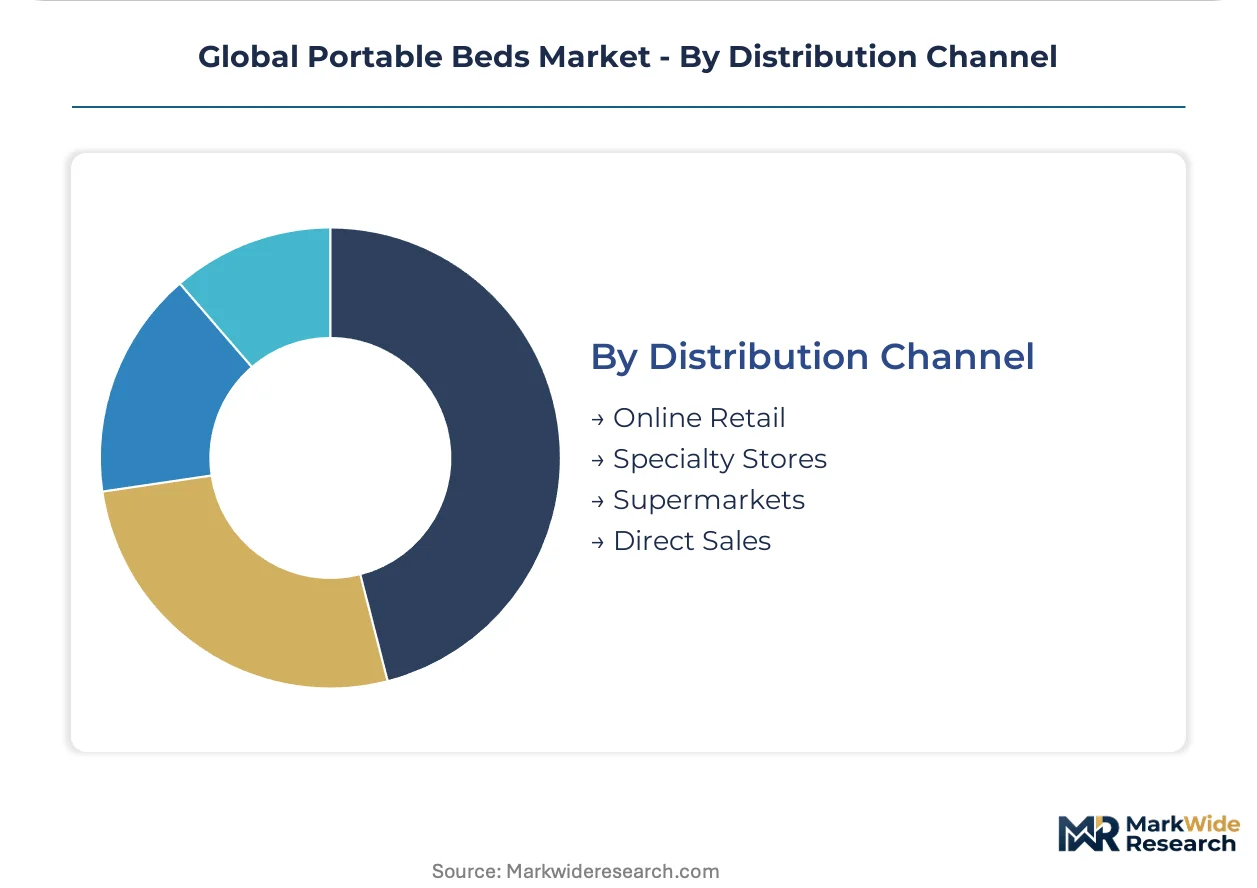
Distribution Channel:
Customer type and purchase scale determine channel selection, with institutional buyers disintermediating traditional networks through digital procurement platforms.
- Direct Sales:Hospital procurement platforms in the United States are disintermediating traditional medical distributor networks for standardized portable bed SKUs, compressing margin capture for intermediary layers. Contracting authorities in Texas and Florida are piloting rapid-deployment inventory models sourcing flat-packed frames for on-site assembly.
- Online Retail:Mass-market consumer access for camping and residential segments with specification transparency and comparative pricing. Specialty camping distributors and mass retail chains in North America maintain channel control for inflatable segment placement.
- Specialty Stores:Curated selection for hospitality and healthcare procurement with consultation and customization services.
- Supermarkets:Economy-tier consumer access for occasional-use residential and recreational applications.
Channel concentration: Direct Sales for institutional volume. Fastest channel shift: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnamese steel fabrication clusters in Binh Duong and Dong Nai provinces are hardening as the primary supply base for portable bed frames and folding mechanisms serving institutional buyers worldwide.
United States
Aging demographics in Florida and Texas are accelerating hospital procurement of motorized adjustable beds for residential medical deployment. FDA 510(k) clearance requirements filter clinical tenders toward ISO 13485-certified manufacturers with captive testing laboratories. Dallas and Houston health systems are piloting rapid-deployment inventory models sourcing flat-packed frames for on-site assembly.
Germany
Home healthcare agencies in Bavaria and North Rhine-Westphalia are expanding repeat purchasing of foldable patient beds for outpatient medical deployment. EU Medical Device Regulation CE marking mandates under tightened safety protocols are filtering procurement toward certified producers. Stuttgart-based metalworking operations are absorbing elevated testing costs while maintaining ISO 3834-compliant aluminum frame fabrication.
Japan
Tokyo and Osaka hotel operators are contracting seasonal bed fleets through third-party logistics providers rather than owning depreciating assets. METI industrial standards shape product specifications for hospitality and healthcare channels. Nagoya manufacturing clusters are scaling production of space-optimizing folding systems for institutional overflow capacity.
India
Budget hotel chains in Maharashtra and Karnataka are adopting space-optimizing folding beds for seasonal occupancy surge capacity. BIS certification requirements are emerging as procurement filters for institutional buyers. Pune and Bengaluru metal fabrication clusters are developing frame production capabilities for domestic hospitality retrofit demand.
Vietnam
Ho Chi Minh City and Hanoi industrial zones are capturing frame fabrication share from legacy European suppliers through cost-competitive steel and aluminum processing. Export-oriented manufacturers are racing to scale ISO 3834-compliant welding operator credentials. Binh Duong province clusters are consolidating as the dominant supply base for North American and European institutional contract fulfillment.
Global Portable Beds Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue adjacent space in polymer-based recreational segments and subscription-based hospitality fleet models. The vendor base stratifies across three tiers: ISO-certified institutional specialists, mass-market consumer fabricators, and regional hospitality suppliers. Two dominant competitive moves are reshaping positioning: backward integration into captive metal fabrication and direct-to-institution digital channel development.
Among North American institutional contractors, BESTAR Inc. and SICO Inc. occupy positions within the certified healthcare-hospitality tier, exemplifying scale-driven manufacturing archetypes with captive production capabilities. Jay-Be Ltd. anchors British demand through specialized engineering positioning for hospitality and healthcare channels. These three entities represent contrasting geographic anchoring strategies—Canadian manufacturing scale, British engineering specialization, and North American institutional contract concentration—while sharing compliance-forward postures toward tightening EU and US regulatory frameworks.
| Leading Market Players |
|---|
| BESTAR Inc. |
| Jay-Be Ltd. |
| Millard Brands |
| SICO Inc. |
| Newell Brands Inc. |
| IKEA |
| Coleman |
| Intex |
| Zinus |
| Others |
Value Chain & Pricing Dynamics
ISO 3834-certified welding operators concentrated in Binh Duong and Dong Nai provinces generate labor-cost differentials that widen pricing spreads between hospital-grade aluminum frames and economy steel alternatives. Vietnamese fabrication clusters capture institutional contract volumes at 30-40% below legacy European supplier quotes while EU MDR compliance costs force certified manufacturers to absorb elevated testing overhead.
Pricing Analysis
Warranty bundling separates premium institutional tiers from unbundled consumer offerings. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service inclusion. Pricing pressure stems from Vietnamese metal cluster competition compressing margins on non-certified frames. Hospital procurement committees demonstrate lowest price sensitivity due to regulatory compliance mandates, while budget hospitality chains in India exhibit highest sensitivity driving spot-market sourcing.
Supply Chain Analysis
Certification gating through ISO 13485 and EU MDR CE marking filters supplier eligibility toward vertically integrated producers with captive testing laboratories. Frame fabrication concentrates in Vietnam, Germany, and Canada. Raw material dependencies center on aluminum alloys, steel coil, and fire-retardant textile coatings. Single-source vulnerability runs through Vietnamese welding certification bottlenecks as clusters race to scale ISO 3834-compliant operator credentials. Distribution runs through direct-to-institution digital platforms disintermediating traditional medical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EU Medical Device Regulation tightening constructs barrier-to-entry moats favoring pre-certified manufacturers with captive testing infrastructure.
For Market Incumbents: Anticipate margin compression from Vietnamese metal cluster expansion by deepening backward integration into aluminum extrusion and welding operations. Defend hospital contract renewals through ISO 13485 certification maintenance and rapid-deployment inventory models piloted in Texas and Florida health systems. Channel control through direct procurement platform relationships offers the strongest defensive lever against distributor disintermediation. For New Entrants and Emerging Players: Budget hotel chains in Maharashtra and Karnataka represent the most penetrable buyer archetype for non-certified frame suppliers. White-space targets include subscription-based hospitality fleet leasing models displacing capital purchases in Tokyo and Osaka, and Indian domestic hospitality retrofit demand served through Pune and Bengaluru fabrication clusters. Go-to-market execution should prioritize BIS certification investment to unlock institutional procurement channels. For Investors and Strategic Acquirers: Re-rating potential sits with ISO 13485-certified mid-cap specialists given EU MDR compliance timeline acceleration filtering tenders toward pre-qualified suppliers. Long-term viability over a 5-10 year horizon favors vertically integrated manufacturers with Vietnamese production footprints and European testing laboratory access. The signal to watch is welding certification scale-up velocity in Binh Duong province clusters as inflection indicator for supply base consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Unlocks EU MDR CE marking pathway for hospital-grade portable bed tenders. |
| Backward Integration into Aluminum Extrusion | Captures margin compression from Vietnamese metal cluster competition. |
| Direct-to-Institution Digital Platform Development | Disintermediates traditional medical distributor networks in United States hospital procurement. |
| Rapid-Deployment Inventory Model Pilot | Sources flat-packed frames for on-site assembly in Texas and Florida health systems. |
| Subscription-Based Hospitality Fleet Leasing | Captures Tokyo and Osaka hotel operator shift from capital purchase to seasonal equipment contracting. |
Study Parameters
Trade databases, hospital procurement records, and regulatory filing repositories formed the secondary backbone of this study. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and metal fabrication plant managers combined with secondary validation through customs records and ISO certification registries. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Historical trendline analysis across shipment volumes, certification registrations, and procurement contract awards informed projection frameworks. Segmentation dimensions modeled include product type, material grade, end-user application, and distribution channel complexity. CAGRs were derived through regression analysis of historical growth patterns applied to regulatory timeline assumptions and demographic demand drivers including aging population profiles in Germany and Japan.
Revisions become necessary when EU MDR implementation timelines accelerate, Vietnamese welding certification scale-up exceeds or falls below modeled velocity, or hospital infrastructure electrical compatibility standards shift toward motorized adjustable bed mandates. A model refresh is warranted upon material change in steel and aluminum input price volatility affecting frame fabrication economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Medical Equipment Rental Market
Medical Equipment
Medical Oxygen Concentrators and Oxygen Cylinders Market
Medical Equipment
Bone Marrow Processing Systems Market
Medical Equipment
Surgical Lighting System Market
Medical Equipment
North America Medical Automation Market
Medical Equipment
Medical Equipment Leasing Market
Medical Equipment
Global Mortuary Equipment Market
Medical Equipment
Diathermy Equipment Market
Medical Equipment
Medical Automation Market
Medical Equipment
Global Optometry Equipment Market
Medical Equipment
Asia-Pacific Medical Device Reprocessing Market
Medical Equipment
Biomedical Refrigerators and Freezers Market
Medical Equipment
Terminal Sterilization Market
Medical Equipment
PCR Plate Sealer Market
Medical Equipment
Medical Air Sterilizer Market
Medical Equipment
Defibrillator Analyzers Market