
 Sodium Hydrogen Sulphite Market | 2026-2036
Sodium Hydrogen Sulphite Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Hydrogen Sulphite Market Analytics
Continuous crystallization technology is tilting manufacturing economics toward producers with integrated sulphur dioxide supply chains. BASF SE leverages backward integration into sulphur derivatives to sustain margin stability across European supply contracts. Chemtrade Logistics anchors North American availability through its regional terminal network and rail-served production sites. Qingdao Tianya Chemical competes on cost positioning via captive sulphuric acid capacity serving domestic textile processors.
Sodium hydrogen sulphite (NaHSO3), an inorganic salt formed by saturating sodium carbonate with sulphur dioxide gas and crystallizing the resulting solution, functions primarily as a reducing agent, oxygen scavenger, and preservative across industrial and food systems. The compound typically assays 58-67% NaHSO3 by weight in technical grades, with food-grade specifications demanding heavy metal limits below 10 ppm lead and arsenic thresholds aligned with Codex Alimentarius parameters. Industrial grade dominates current volume flows, reflecting entrenched demand from pulp bleaching sequences and municipal water dechlorination, while pharmaceutical grade commands premium pricing tied to USP-NF certification requirements and limited qualified manufacturing capacity.
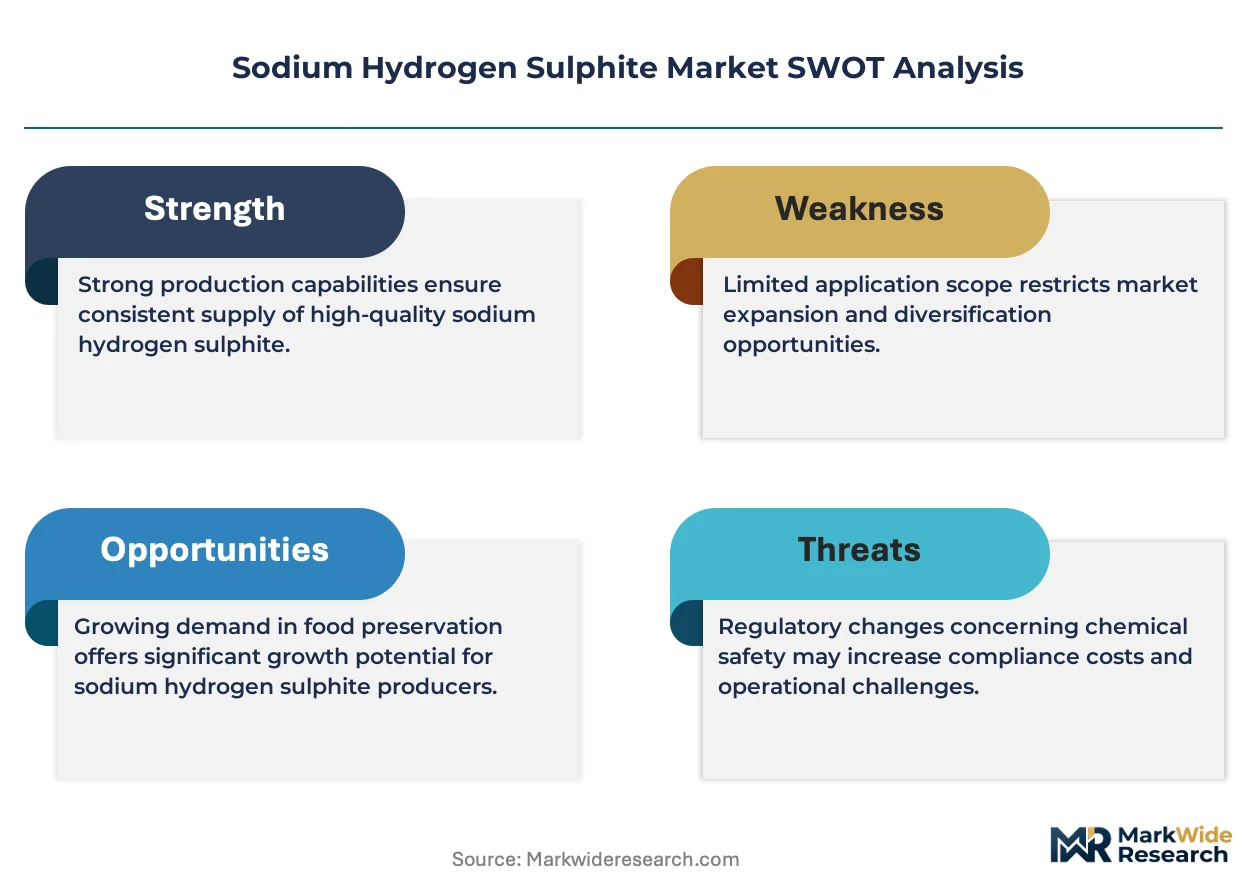
EPA drinking water standards and FDA food additive regulations in the United States, alongside REACH registration mandates and EFSA purity specifications in Europe, collectively elevate compliance costs for cross-border suppliers and favor producers with certified multi-jurisdictional production assets. China's GB 25590-2010 food additive standard and evolving MEE effluent discharge rules further fragment qualification requirements across major consumption centers. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate where certification investments will yield sustainable market access versus stranded compliance expenditure.
Market Dynamics
Continuous crystallization technology is compressing unit economics for sodium hydrogen sulphite producers, privileging manufacturers with captive sulphur dioxide supply chains and forcing asset-light competitors into tolling arrangements or exit.
Growth Catalysts
- REACH registration mandates:ECHA compliance requirements in Europe are filtering out uncertified suppliers and consolidating volume among qualified multi-jurisdictional producers with certified production assets.
- Pulp bleaching sequences:Kraft mill dechlorination stages consume substantial sodium hydrogen sulphite volumes as oxygen scavengers, with technical grade specifications dominating industrial procurement.
- China's textile processing belt:Shandong and Jiangsu province mills source heavily from domestic producers with integrated sulphuric acid capacity, anchoring regional demand concentration.
Market Restraints
- Sulphur dioxide price volatility:Input cost swings tied to petroleum refining byproduct availability and sulphur mining output compress margins for non-integrated manufacturers.
- Supply concentration in East Asia:Qingdao and Tianjin production clusters control substantial exportable surplus, creating single-source vulnerability for Atlantic basin buyers.
- Peracetic acid substitution:Food processors in North America and Western Europe are piloting peracetic acid systems for some antimicrobial applications, displacing sulphite chemistry in select use cases.
Strategic Opportunities
- India's FSSAI food additive expansion:Formal adoption of Codex-aligned sulphite specifications is opening import pathways for certified producers as domestic food processing capacity scales.
- Pharmaceutical grade certification:USP-NF qualified manufacturing capacity remains limited, creating premium pricing capture for producers who complete validation protocols.
- MEA water treatment mandates:Saudi Arabia's SFDA and UAE's MOHAP are tightening municipal dechlorination standards, generating specification-grade demand from desalination operators.
Industry Challenges
- Multi-jurisdictional certification timelines:Parallel FDA, EFSA, and GB 25590-2010 qualification processes extend market entry cycles and strain regulatory affairs staffing.
- Legacy batch crystallization assets:Older production lines face yield disadvantages against continuous flow systems, requiring substantial capex for competitive retrofit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Hydrogen Sulphite Market |
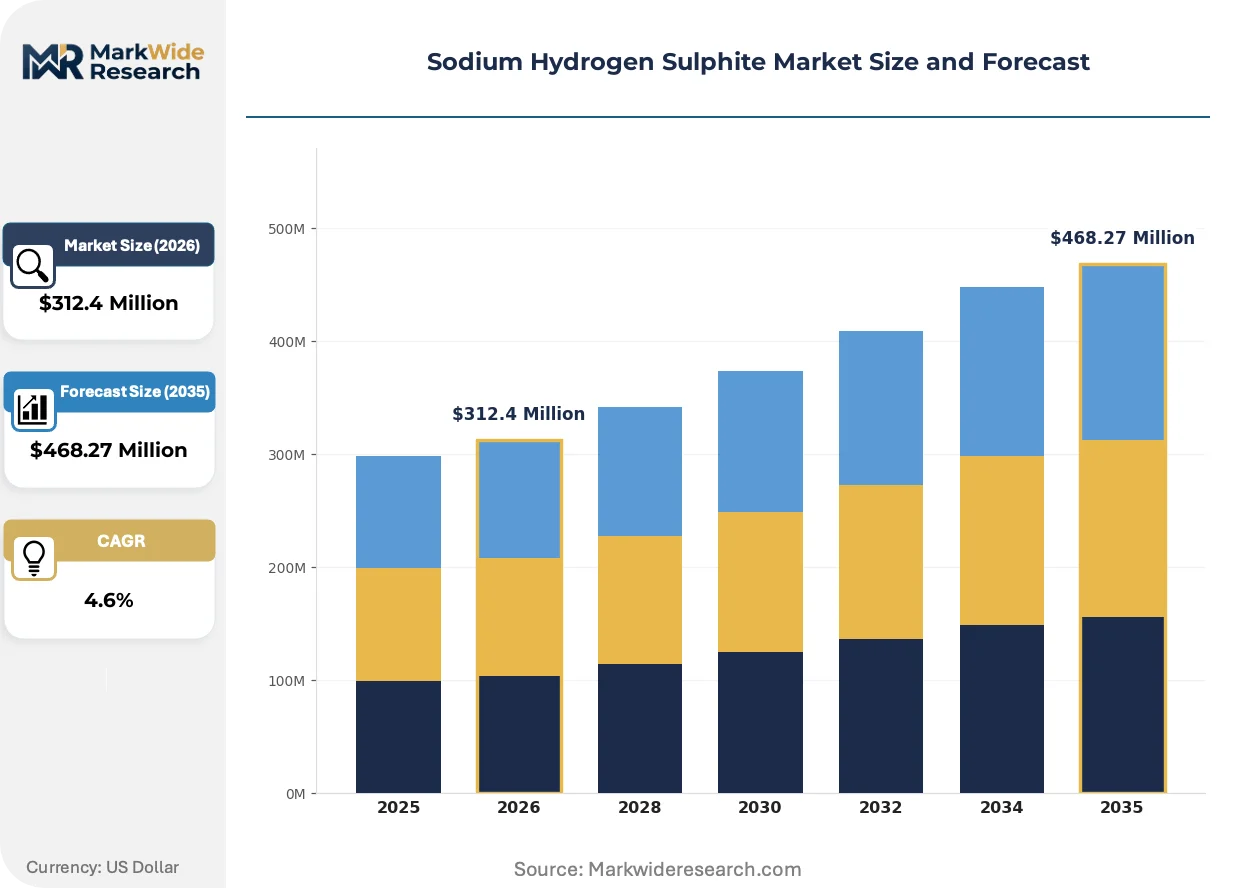
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $468.27 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Cosmetic Grade Application: Preservative, Reducing Agent, Bleaching Agent, Water Treatment End User: Food Processing, Pharmaceuticals, Cosmetics, Textile Distribution Channel: Online, Offline, Direct Sales, Distributors |
| Companies Covered | BASF SE, Arkema, Evonik, Chemtrade Logistics, Calabrian Corporation, Hydrite Chemical, Qingdao Tianya Chemical, Shakti Chemicals, Holland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Hydrogen Sulphite Market Evolving Landscape
Process intensification and regulatory stringency are jointly reshaping sodium hydrogen sulphite manufacturing, with technology adoption patterns diverging sharply between integrated chemical complexes and standalone producers.
Membrane filtration systems for sulphite liquor purification are hybridizing traditional crystallization sequences with cross-flow microfiltration stages. European and North American producers with food-grade certification requirements are retrofitting existing lines at measured pace. This hybridizing architecture is compressing heavy metal contamination rates below 5 ppm while extending batch cycle times modestly.
China's MEE effluent discharge rules are tightening sulphite manufacturing wastewater parameters, forcing producers to install sulphur recovery scrubbers or face production suspensions. The regulatory burden falls heaviest on small-scale Shandong province operators lacking captive environmental infrastructure. These facilities are consolidating into larger chemical parks with centralized treatment capacity.
Specification-driven procurement is consolidating buyer relationships around certified producers with multi-jurisdictional regulatory coverage. North American food processors are reducing supplier counts and demanding comprehensive documentation packages. This pattern is most visible in the United States, where FDA enforcement discretion has shifted toward preventive control verification rather than reactive inspection.
Sodium Hydrogen Sulphite Market Segmentation
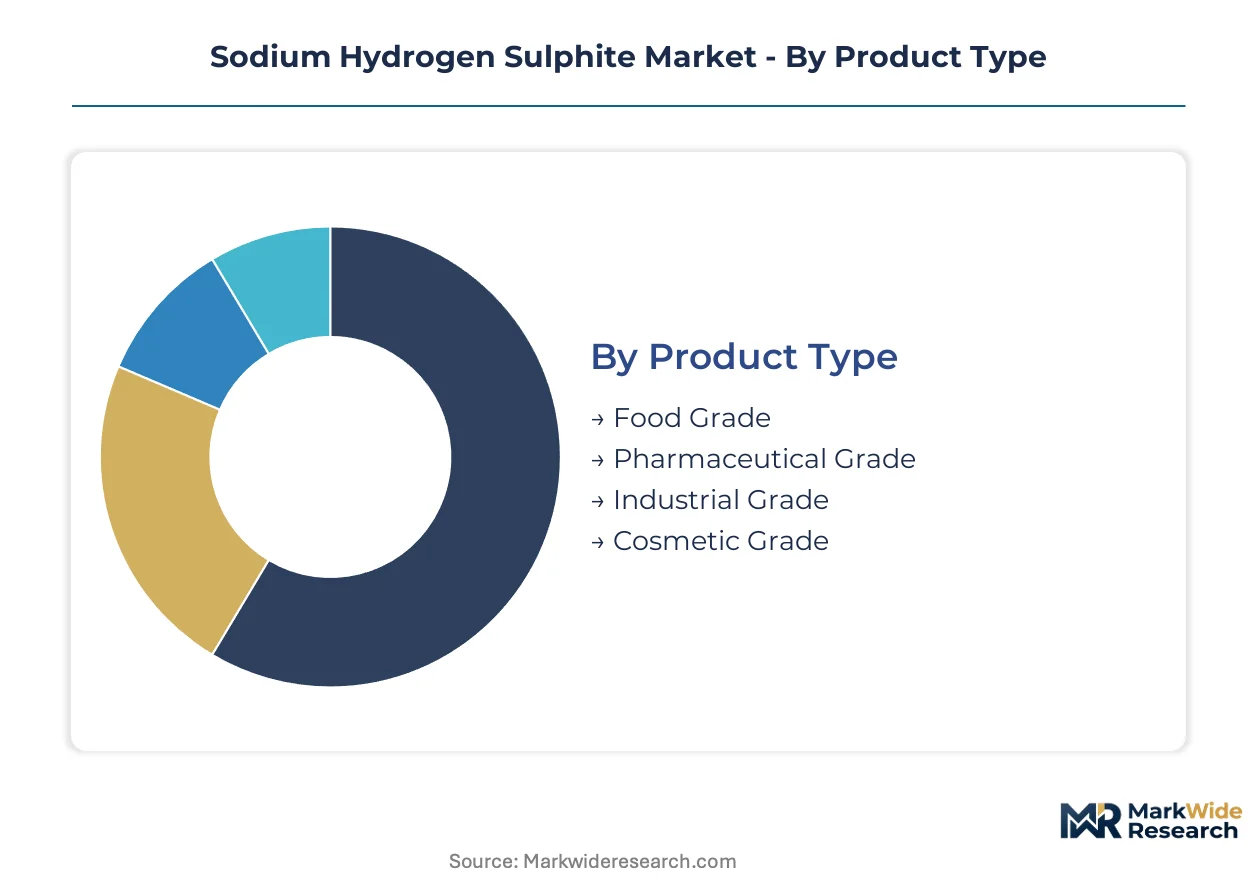
Sodium hydrogen sulphite procurement cycles vary dramatically across grades and end-uses, with industrial buyers negotiating annual contracts while pharmaceutical qualification processes extend 18-24 months. Understanding these velocity differences helps suppliers align inventory positioning with cash conversion requirements.
Product Type:
Food-grade and industrial-grade materials turn inventory fastest, cycling every 6-8 weeks at major distributors, while pharmaceutical-grade stock rotates quarterly due to validation documentation burdens.
- Industrial Grade:Technical specifications typically assay 58-67% NaHSO3 by weight with tolerance for higher heavy metal content. Pulp mills in Shandong province and municipal water treatment facilities across the United States consume substantial volumes under annual procurement frameworks with indexed sulphur dioxide pass-through clauses.
- Food Grade:Heavy metal limits must register below 10 ppm lead and arsenic thresholds aligned with Codex Alimentarius parameters. North American processors demand comprehensive FDA documentation packages, compressing supplier counts and extending qualification timelines for new entrants.
- Pharmaceutical Grade:USP-NF certification requirements limit qualified manufacturing capacity.
- Cosmetic Grade:Purity standards sit between food and pharmaceutical tiers.
Industrial grade anchors the volume base while food grade gains share at the steepest rate.
Application:
Cost tiers separate commodity oxygen scavenging from premium antimicrobial systems, with water treatment commanding lowest unit economics and preservative applications extracting highest margins.
- Water Treatment:Municipal dechlorination consumes substantial sodium hydrogen sulphite volumes as EPA standards tighten residual chlorine limits. Desalination operators in Saudi Arabia and UAE source specification-grade material under MOHAP and SFDA procurement guidelines.
- Preservative:Food processors leverage sulphite chemistry for antimicrobial control in dried fruits and wine production. FDA enforcement discretion has shifted toward preventive control verification, elevating documentation requirements for supplier qualification.
- Reducing Agent:Textile and paper mills deploy sulphites for bleaching sequence support.
- Bleaching Agent:Kraft pulp dechlorination stages represent entrenched demand concentration.
Water treatment anchors the volume base while preservative applications climb the fastest on regulatory-driven substitution barriers.
End User:
Customer type determines margin capture potential, with pharmaceutical manufacturers accepting 40-60% premiums over industrial buyers for certified supply security.
- Food Processing:Codex-aligned sulphite specifications under India's FSSAI are opening import pathways as domestic processing capacity scales. European buyers demand REACH-registered supply chains with EFSA purity documentation.
- Textile:Shandong and Jiangsu province mills source heavily from domestic producers with integrated sulphuric acid capacity, anchoring regional demand concentration and compressing import penetration.
- Pharmaceuticals:USP-NF validation protocols create substantial entry barriers.
- Cosmetics:Formulation trends favor milder preservative systems.
Textile processing anchors the volume base while food processing expands most quickly on emerging market capacity buildouts.
Distribution Channel:
Supply concentration favors direct relationships at volume scale, with distributor networks serving fragmented small-batch buyers at 15-25% markups.
- Direct Sales:Integrated chemical complexes with captive sulphur dioxide supply chains prefer direct contracting with Kraft mills and municipal water authorities. BASF SE leverages backward integration into sulphur derivatives to sustain margin stability across European supply contracts.
- Distributors:Regional terminal networks and rail-served production sites anchor North American availability for mid-tier buyers lacking tank car receiving infrastructure.
- Online:Digital procurement penetration remains limited to sample quantities and laboratory reagents.
- Offline:Traditional brokerage persists in spot market clearing.
Direct sales anchors the volume base while distributor relationships strengthen fastest on buyer consolidation trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Exportable surplus concentrates in East Asian production clusters while Atlantic basin buyers face single-source vulnerability. Shandong province mills and Tianjin port terminals anchor the dominant supply position. Import-dependent markets in North America and Europe compete for qualified volumes against Middle Eastern desalination operators.
China
Shandong and Jiangsu province textile mills consume substantial sodium hydrogen sulphite volumes for bleaching and dechlorination sequences. MEE effluent discharge rules are forcing sulphur recovery scrubber installations or production suspensions. Qingdao and Tianjin production clusters control exportable surplus, consolidating regional supply dominance.
United States
Municipal water treatment facilities deploy specification-grade material as EPA drinking water standards tighten residual chlorine limits. FDA food additive regulations elevate documentation requirements for supplier qualification. Gulf Coast chemical complexes with captive sulphur dioxide supply chains anchor domestic manufacturing capacity.
Germany
REACH registration mandates are filtering out uncertified suppliers and consolidating volume among qualified multi-jurisdictional producers. EFSA purity specifications elevate compliance costs for cross-border suppliers. BASF SE leverages backward integration into sulphur derivatives to sustain margin stability across European supply contracts.
India
FSSAI formal adoption of Codex-aligned sulphite specifications is opening import pathways as domestic food processing capacity scales. Textile processors in Gujarat and Maharashtra source from expanding regional chemical parks. Shakti Chemicals and domestic producers compete for qualification-driven procurement from multinational food manufacturers.
Saudi Arabia
SFDA tightening of municipal dechlorination standards is generating specification-grade demand from desalination operators. Red Sea and Arabian Gulf coastal facilities source through MOHAP procurement guidelines. Jeddah and Jubail industrial zones anchor regional consumption concentration for water treatment applications.
Sodium Hydrogen Sulphite Market Competitive Landscape
On the supply side, the industry is consolidating around integrated chemical complexes with captive sulphur dioxide supply chains and certified multi-jurisdictional production assets. Asset-light competitors face margin compression and tolling arrangement pressures. Three archetypes dominate: backward-integrated sulphur derivative producers, regional terminal network operators, and cost-positioned domestic specialists. Capacity expansion and qualification-driven portfolio diversification represent the dominant competitive moves.
Among European integrated producers, BASF SE exemplifies the backward-integrated archetype with sulphur derivative control. Chemtrade Logistics anchors North American availability through regional terminal infrastructure. Qingdao Tianya Chemical occupies the cost-positioned domestic specialist tier serving Shandong province textile mills.
| Leading Market Players |
|---|
| BASF SE |
| Arkema |
| Evonik |
| Chemtrade Logistics |
| Calabrian Corporation |
| Hydrite Chemical |
| Qingdao Tianya Chemical |
| Shakti Chemicals |
| Holland Company |
| Others |
Value Network & Pricing Analysis
Tianjin port freight corridors connecting Shandong production clusters to Atlantic basin buyers impose cost structures that amplify regional price spreads. Sulphur dioxide pass-through clauses in annual Kraft mill contracts compress margins for non-integrated suppliers while captive producers extract premium stability.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure with indexed raw material adjustments. Price differentiation rests on certification tier—REACH-registered supply commands 15-25% premiums over uncertified alternatives—and volume scale, with tank-car direct delivery securing lowest unit economics. Cost compression in technical grades is intensifying because Qingdao exporters are absorbing freight differentials to defend market share. Municipal water authorities exhibit highest price sensitivity due to budget-constrained procurement frameworks, while pharmaceutical manufacturers accept substantial premiums for USP-NF qualified supply security.
Supply Chain Analysis
Export-control regimes on dual-use chemical processing equipment limit technology transfer to emerging producers, constraining capacity buildouts outside established clusters. Supply concentrates in China, Germany, and the United States, with Shandong province and Gulf Coast chemical complexes anchoring global output. Raw material dependencies draw from petroleum refining byproduct sulphur, sulphuric acid, and sodium carbonate feedstocks. Single-source vulnerability pervades Atlantic basin procurement, as Tianjin and Qingdao terminals control exportable surplus. Distribution runs through integrated chemical complexes with direct rail and tank-car infrastructure, supplemented by regional terminal networks for fragmented buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sodium hydrogen sulphite procurement fragmentation creates entry niches as food processors consolidate supplier relationships around multi-jurisdictional certifiers. Specification-driven buyer mandates reward qualified capacity over commodity volume.
For Market Incumbents: Insulate margin stability through backward integration into sulphur derivative production and captive sulphur dioxide supply chains. Peracetic acid substitution in North American antimicrobial applications threatens sulphite volume retention, demanding defensive certification investments in pharmaceutical-grade capacity to capture premium pricing tiers. For New Entrants and Emerging Players: Establish a beachhead in India's FSSAI-aligned food additive segment as domestic processing capacity scales and import pathways open. Pharmaceutical-grade manufacturing remains penetrable given limited USP-NF qualified capacity. A certification-first go-to-market angle—front-loading FDA and EFSA qualification—secures sustainable market access against commodity competitors. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with stranded sodium hydrogen sulphite assets lacking regulatory certification depth. Long-term viability hinges on regulatory moat sustainability rather than cost position alone. Watch ECHA enforcement discretion against uncertified European suppliers as the inflection signal for consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulphur Derivatives | BASF SE leverages captive SO2 supply to sustain margin stability across REACH-registered European contracts. |
| Pharmaceutical Grade Certification | USP-NF validation protocols create premium pricing capture and limit qualified manufacturing competition. |
| Regional Terminal Network Expansion | Chemtrade Logistics anchors North American availability through rail-served production sites and distribution infrastructure. |
| Long-term Supply Agreement | Indexed sulphur dioxide pass-through clauses in Kraft mill contracts stabilize revenue for integrated producers. |
| Joint Venture in Emerging Markets | India's FSSAI adoption opens import pathways for certified producers partnering with domestic food processors. |
Research Methodology
Operator-level perspectives from plant managers at integrated sulphur derivative complexes, procurement leads at downstream textile and pulp mills, distribution channel partners in regional terminal networks, and technical R&D directors at food-grade certification facilities anchored the qualitative base. Secondary validation drew from customs and trade flow databases, ACC and Cefic industry reports, SEC 10-K filings of listed chemical producers, and MEE effluent discharge compliance records. Bottom-up volume estimates from production facility capacities were triangulated against top-down demand aggregation across end-use segments.
Scenario-bracketing framed the analytical approach across the projection horizon, with base, upside, and downside cases reflecting regulatory enforcement intensity and substitution technology penetration. Segmentation dimensions modeled included grade tier (industrial, food, pharmaceutical), end-use industry (water treatment, food processing, textiles, pulp), packaging format, and regional production hub. CAGRs were derived from historical volume trajectories and elasticity-adjusted demand projections, with sulphur dioxide price volatility and REACH registration timelines as key forecast inputs.
Stress conditions across sulphur input cost swings, ECHA enforcement discretion, and peracetic acid substitution velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory stability and technology adoption curves. Material shifts in EU food additive purity specifications or China's MEE discharge rule stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Paraxylene(PX) Market
Bulk Chemicals
Glacial Acrylic Acid (GAA) Market
Bulk Chemicals
Global Silica Flour Market
Bulk Chemicals
Thiodiglycol Market
Bulk Chemicals
4-Diisopropylbenzene Market
Bulk Chemicals
Sulfur Palletized Plant and Granulator Market
Bulk Chemicals
North America Copper Sulphate Market
Bulk Chemicals
Barium Sulfite Market
Bulk Chemicals
Electronic Batio3 Powder Market
Bulk Chemicals
Mancozeb Market
Bulk Chemicals
Sulfamic Acid Market
Bulk Chemicals
Metallurgical Coke Market
Bulk Chemicals
Asia-Pacific Lithium Chloride Market
Bulk Chemicals
Ammonium Bromide Market
Bulk Chemicals
Europe Caustic Potash Market
Bulk Chemicals
Ethylene Dichloride Market