
 Hydrocarbon Tester Market | 2026-2036
Hydrocarbon Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrocarbon Tester Market Outlook
Multi-source procurement for hydrocarbon testing components is rebalancing toward vertically integrated domestic suppliers. Thermo Fisher Scientific leverages its captive optical component production to control lead times on infrared detector modules. Emerson anchors its position through embedded software ecosystems that lock in protocol compatibility across refinery distributed control systems. SICK AG competes on laser spectroscopy miniaturization for drone-mounted methane detection platforms.
A hydrocarbon tester is an analytical instrument that quantifies saturated and aromatic hydrocarbon concentrations in gaseous or liquid matrices, typically achieving detection thresholds below one part per million through optical absorption or chromatographic separation methods. These devices serve critical compliance and safety functions across upstream extraction, midstream transport, and downstream refining operations. Fixed station equipment dominates capital deployment at major facilities, while portable analyzers capture the fastest expansion as field crews replace grab-sample lab workflows with real-time perimeter screening. Gas chromatography systems retain premium pricing in custody-transfer applications where compositional accuracy determines commercial settlements.
EPA Method 25A and NHTSA fuel evaporative emission standards shape product certification requirements for instruments sold into US environmental compliance channels. OSHA Process Safety Management rules mandate periodic hydrocarbon monitoring around fired heaters and flare systems, creating recurring replacement demand for sensor heads and calibration gases. ASTM D6420 and ISO 8178 provide international method references that facilitate cross-border equipment qualification. Stakeholders must weigh the capital efficiency of cloud-connected analyzer fleets against the cybersecurity exposure of networked process analytical technology.
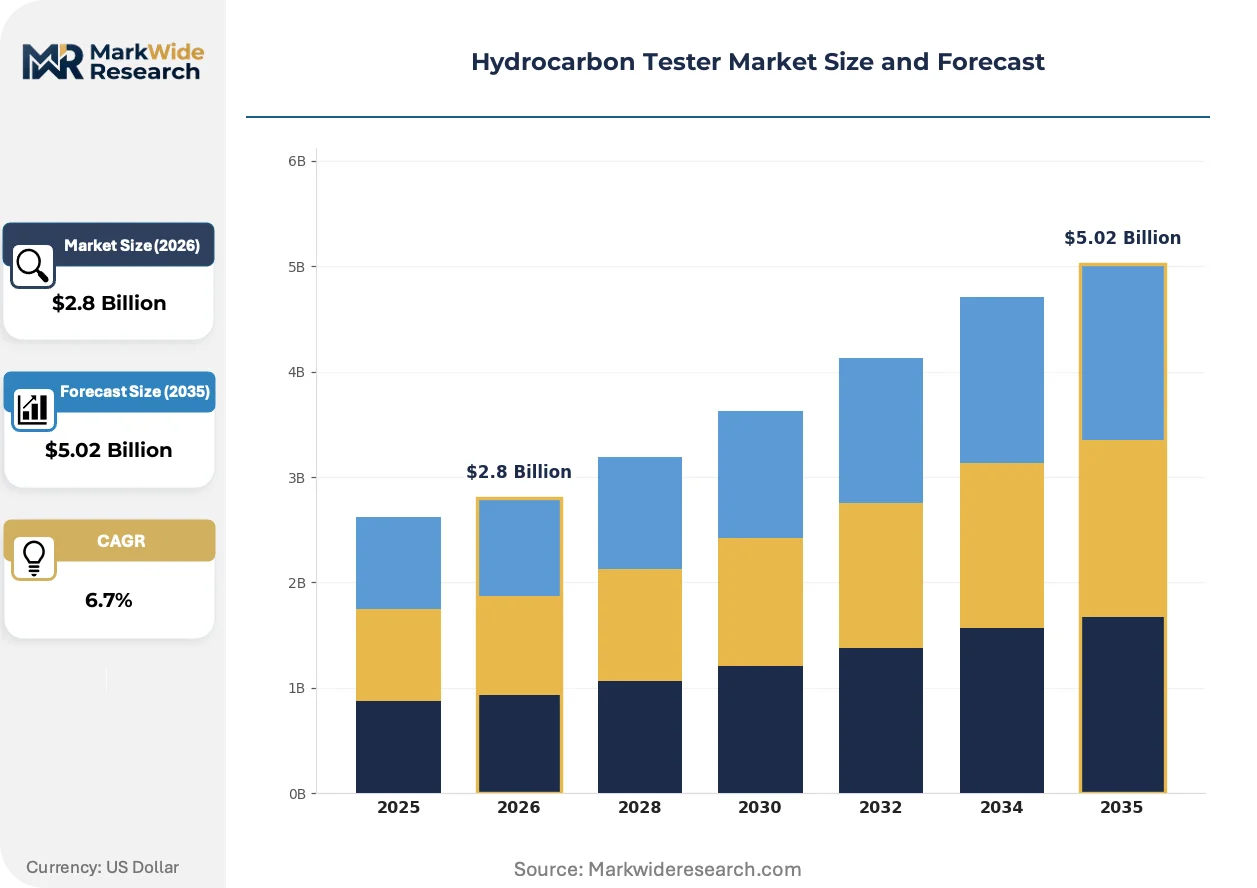
Market Dynamics
EPA's tightened emissions standards for oil refineries are forcing capital redeployment toward continuous monitoring infrastructure, compressing replacement cycles for fixed-station analyzers and accelerating portable unit procurement for perimeter screening.
Growth Catalysts
- EPA Method 25A compliance deadlines:Refineries along the Gulf Coast are replacing batch sampling with continuous emission monitoring systems to meet forthcoming standards.
- Drone-mounted detection platforms:Midstream operators deploy laser spectroscopy miniaturized for aerial methane leak surveys across pipeline corridors.
- California's AB 32 extensions:State-level air quality mandates exceed federal baselines, creating premium demand for sub-ppm detection thresholds in the San Joaquin Valley.
Market Restraints
- Optical component supply concentration:Infrared detector modules rely on limited domestic foundry capacity, extending lead times for portable analyzer manufacturers.
- Helium scarcity for carrier gases:Gas chromatography systems face input cost volatility as federal helium reserve auctions tighten.
- OSHA calibration gas logistics:Periodic sensor head replacement requires certified reference material supply chains that concentrate in Texas and Louisiana.
Strategic Opportunities
- Permian Basin flaring reduction mandates:Texas Railroad Commission enforcement creates demand for real-time hydrocarbon quantification at wellhead sites.
- Cloud-connected analyzer fleets:Refinery operators seek networked process analytical technology despite cybersecurity exposure trade-offs.
- Biofuel blending verification:ASTM D6420-compliant portable units address emerging renewable diesel custody-transfer applications.
Industry Challenges
- Spectroscopy technician scarcity:Field crews lack training on tunable diode laser absorption spectroscopy maintenance protocols.
- Legacy DCS integration complexity:Embedded software ecosystems must maintain protocol compatibility across decades-old refinery distributed control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrocarbon Tester Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Analyzers, Laboratory Analyzers, Fixed Station Equipment, Handheld Testers Application: Environmental Monitoring, Oil & Gas Exploration, Quality Control, Wastewater Treatment End User: Oil Refineries, Environmental Agencies, Research Laboratories, Government Bodies Technology: Infrared Spectroscopy, Gas Chromatography, Mass Spectrometry, Conductivity Measurement |
| Companies Covered | Thermo Fisher Scientific, Emerson, Teledyne Analytical Instruments, SICK AG, Agilent Technologies, AMETEK, PerkinElmer, HORIBA, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrocarbon Tester Market Strategic Shifts
Infrared spectroscopy miniaturization is compressing form factors while expanding deployment contexts, enabling migration from fixed stations to mobile platforms across extraction and transport operations.
Tunable diode laser absorption spectroscopy is integrating into palm-sized enclosures for drone-mounted methane detection. Pipeline operators in the Permian Basin deploy these units for aerial corridor surveys that replace ground crew walking inspections. The technology is integrating leak detection response times from days to hours, compressing incident discovery windows.
EPA's pending refinery sector rule revisions are tightening continuous monitoring requirements for benzene fence-line communities. Facilities in Texas and Louisiana must upgrade from quarterly grab sampling to real-time optical systems. Catalytic cracking units face the steepest compliance burden, driving analyzer procurement toward multi-species infrared platforms.
Service unbundling is fragmenting traditional analyzer vendor relationships. Refinery procurement teams now separate hardware acquisition from calibration gas supply and cloud data hosting. This pattern concentrates in California where air district enforcement creates demand for third-party audit trails independent of original equipment manufacturers.
Hydrocarbon Tester Market Segmentation
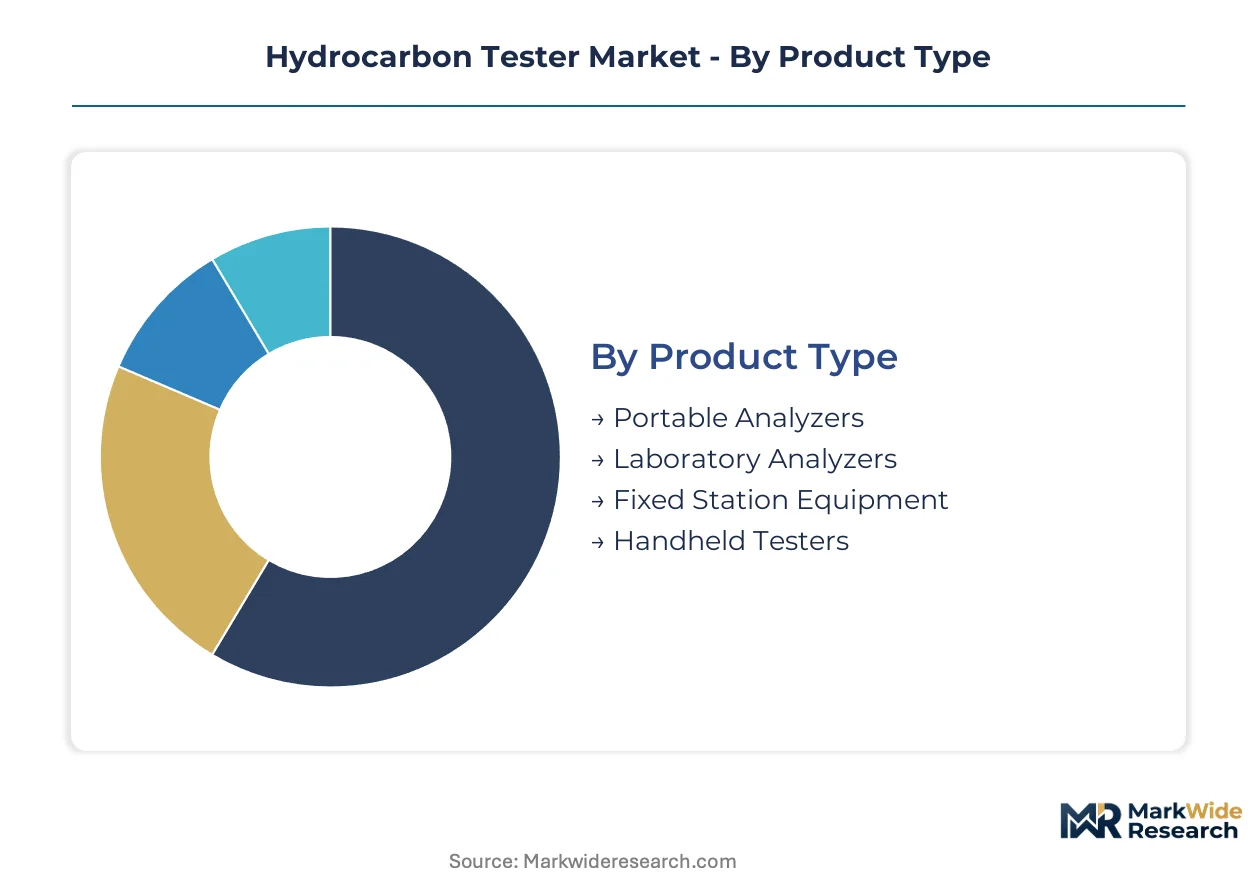
Segmentation in the hydrocarbon tester market reveals distinct procurement patterns across product tiers and deployment contexts. Refinery operators balance capital-intensive fixed installations against flexible portable units for regulatory compliance. Technology selection increasingly hinges on detection threshold requirements rather than historical vendor relationships.
Product Type:
Customization intensity spans from standardized handheld units to engineered fixed-station systems requiring site-specific calibration protocols.
- Portable Analyzers:Battery-powered infrared spectroscopy units achieve sub-ppm detection thresholds in field conditions. Demand concentrates along Texas and Louisiana pipeline corridors where EPA Method 25A compliance drives replacement of grab-sampling workflows with real-time perimeter screening.
- Fixed Station Equipment:Rack-mounted gas chromatography systems deliver custody-transfer accuracy for refinery flare monitoring and benzene fence-line compliance. California's AB 32 extensions mandate continuous emission monitoring at catalytic cracking units, accelerating procurement of multi-species optical platforms.
- Laboratory Analyzers:Benchtop mass spectrometry systems serve research laboratories and third-party environmental testing facilities requiring ASTM D6420 certification for renewable diesel verification.
- Handheld Testers:Palm-sized conductivity measurement devices support rapid field screening by midstream operators in the Permian Basin.
Leading the category by volume: Portable Analyzers. Growing fastest: Fixed Station Equipment.
Application:
Cost tier differentiation separates premium custody-transfer applications from compliance-driven monitoring mandates.
- Environmental Monitoring:Continuous emission monitoring systems for refinery fence-line communities require real-time benzene quantification. California air districts enforce sub-ppm detection thresholds that exceed federal baselines, driving optical analyzer procurement in the San Joaquin Valley.
- Oil & Gas Exploration:Wellhead flaring reduction mandates from the Texas Railroad Commission create demand for tunable diode laser absorption spectroscopy at extraction sites. Real-time hydrocarbon quantification replaces periodic manual sampling.
- Quality Control:ASTM D6420-compliant portable units verify renewable diesel blend ratios at biofuel terminals.
- Wastewater Treatment:Industrial discharge monitoring employs conductivity measurement for saturated hydrocarbon detection in refinery effluent streams.
Environmental Monitoring commands the largest capital deployment. Oil & Gas Exploration exhibits the steepest expansion trajectory.
End User:
Customer type determines procurement authority and replacement cycle cadence across the installed base.
- Oil Refineries:Integrated operators along the Gulf Coast deploy mixed fleets of fixed and portable analyzers under OSHA Process Safety Management rules. Catalytic cracking units face the tightest benzene monitoring requirements.
- Environmental Agencies:State-level regulators in California and Texas specify detection thresholds and calibration protocols for third-party audit trails independent of equipment manufacturers.
- Research Laboratories:Academic and government facilities drive demand for mass spectrometry systems with method development capabilities.
- Government Bodies:Federal enforcement agencies reference EPA Method 25A for equipment qualification in refinery inspection programs.
Oil Refineries dominate absolute unit demand. Environmental Agencies are gaining procurement influence through tightened state mandates.
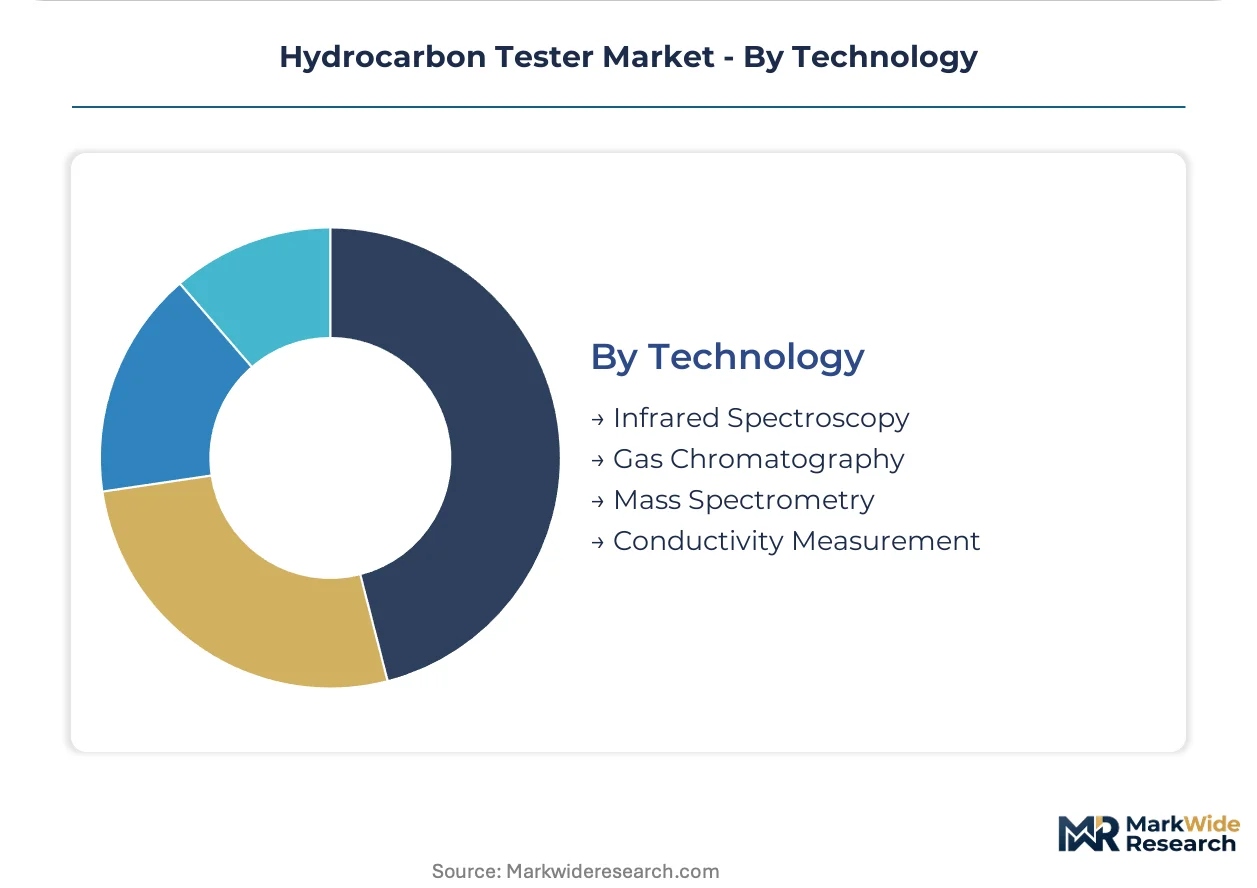
Technology:
Supply concentration in optical component foundries shapes availability and lead time differentiation across detection methods.
- Infrared Spectroscopy:Miniaturized tunable diode laser platforms enable drone-mounted methane detection for aerial pipeline surveys. Infrared detector module supply concentrates in limited domestic foundry capacity, extending lead times for portable analyzer manufacturers.
- Gas Chromatography:Helium-dependent carrier gas systems face input cost volatility as federal helium reserve auctions tighten. Premium pricing persists in custody-transfer applications where compositional accuracy determines commercial settlements.
- Mass Spectrometry:Research-grade systems deliver molecular identification for complex hydrocarbon matrices in laboratory environments.
- Conductivity Measurement:Simplified detection architecture supports cost-sensitive handheld deployment for rapid field screening.
Infrared Spectroscopy leads technology deployment by unit volume. Gas Chromatography retains the highest average selling prices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petroleum basins along the Gulf Coast anchor hydrocarbon tester procurement, with Permian Basin extraction activity and Gulf Coast refining capacity concentrating demand for emission monitoring equipment across upstream and downstream operations.
United States
EPA Method 25A compliance deadlines drive refinery capital redeployment toward continuous monitoring systems. OSHA Process Safety Management rules mandate periodic hydrocarbon surveillance around fired heaters and flare systems. Texas and Louisiana host the densest analyzer deployments, with catalytic cracking units in the Houston Ship Channel facing tightened benzene fence-line requirements.
Canada
Alberta oil sands operators deploy portable infrared units for fugitive emission surveys across expansive extraction sites. Environment and Climate Change Canada regulations align with provincial mandates in Alberta and British Columbia. Calgary-based midstream companies integrate drone-mounted detection for pipeline corridor monitoring across the Western Canadian Sedimentary Basin.
Germany
REACH compliance and the EU Green Deal accelerate optical analyzer adoption at chemical complexes along the Rhine. The Federal Emission Control Act mandates continuous monitoring at refineries in the Cologne-Düsseldorf industrial corridor. BASF and Bayer facilities in Ludwigshafen and Leverkusen drive premium demand for multi-species detection platforms.
China
Dual carbon goals and MEE emission standards force petrochemical complexes in the Yangtze River Delta toward real-time monitoring infrastructure. State-owned refineries in Zhejiang and Jiangsu provinces upgrade from periodic sampling to continuous optical systems. The Ningbo-Zhoushan petrochemical cluster represents the fastest analyzer procurement growth in Asia-Pacific.
Saudi Arabia
Saudi Aramco's flaring reduction commitments under Vision 2030 create demand for wellhead hydrocarbon quantification. The Presidency of Meteorology and Environment enforces air quality standards exceeding Gulf Cooperation Council baselines. Jubail Industrial City and Yanbu host concentrated deployments across integrated refining and petrochemical complexes.
Hydrocarbon Tester Market Competitive Environment
Global majors compete with regional champions across technology platforms and service unbundling dimensions. The vendor base organizes into three tiers: diversified analytical instrument conglomerates, process automation specialists with embedded software ecosystems, and laser spectroscopy miniaturization specialists. Consolidation pressure intensifies as refinery procurement teams separate hardware acquisition from calibration gas supply and cloud data hosting. Dominant competitive moves include backward integration into optical component production and strategic partnerships for drone platform integration.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Agilent Technologies represent archetypal positions anchored by captive supply chains and premium laboratory-grade positioning. Emerson exemplifies the process automation specialist archetype through protocol compatibility lock-in across refinery distributed control systems. SICK AG occupies the miniaturization specialist position, with its German engineering heritage supporting laser spectroscopy compression for aerial deployment platforms. These three anchors illustrate how competitive positioning fragments across technology specialization rather than consolidating around full-stack dominance.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Emerson |
| Teledyne Analytical Instruments |
| SICK AG |
| Agilent Technologies |
| AMETEK |
| PerkinElmer |
| HORIBA |
| ABB |
| Others |
Value Chain & Pricing Dynamics
Helium auction prices from the Federal Helium Reserve cascade through gas chromatography system costs, compressing margins on premium custody-transfer equipment while infrared detector module shortages extend lead times and inflate pricing power for domestic foundry operators.
Pricing Analysis
Service unbundling separates hardware acquisition from calibration gas supply and cloud data hosting. Three-tier pricing structure across premium, standard, and economy levels stratifies by detection threshold certification and after-sales service bundling. Cost compression in portable analyzer tiers intensifies because semiconductor foundry capacity constraints inflate infrared detector module costs. Environmental agencies in California exhibit lowest price sensitivity due to mandate-driven procurement authority, while midstream operators in the Permian Basin show highest sensitivity to per-unit capital outlays.
Supply Chain Analysis
Photonics technician scarcity in Massachusetts and California manufacturing hubs constrains production scaling for tunable diode laser platforms. Optical component fabrication concentrates in the United States, Germany, and Japan, while helium refining for carrier gases draws from federal reserve auctions and Qatari export terminals. Single-source vulnerability in indium antimonide detector substrates threatens analyzer production continuity. Distribution runs through refinery procurement departments and third-party environmental service firms with certified reference material logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Method 25A compliance deadlines erect a cost-of-compliance barrier that rewards incumbents with certified equipment portfolios while screening out undercapitalized entrants lacking continuous emission monitoring system validation infrastructure.
For Market Incumbents: To counter optical component supply concentration, deepen backward integration into captive infrared detector production or secure long-term offtake agreements with domestic foundry operators. Channel control through embedded software ecosystems that lock protocol compatibility across refinery distributed control systems preserves replacement part revenue streams against third-party calibration gas suppliers. For New Entrants and Emerging Players: Drone-mounted laser spectroscopy miniaturization offers a technology-first wedge into midstream pipeline corridor surveys where incumbent process automation specialists lack aerial platform integration. Target Permian Basin flaring reduction enforcement zones with palm-sized tunable diode laser units and partner with oilfield service firms for field crew training on maintenance protocols. For Investors and Strategic Acquirers: Distressed-cycle entries favor laser spectroscopy miniaturization specialists with German engineering heritage and established drone platform partnerships in the Ningbo-Zhoushan petrochemical cluster. Long-term viability hinges on cloud-connected analyzer fleet recurring revenue streams displacing transactional hardware sales. Watch Texas Railroad Commission enforcement intensity as the inflection indicator for wellhead real-time monitoring demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Components | Captive infrared detector production insulates Thermo Fisher Scientific from foundry lead time volatility. |
| Drone Platform Partnership | SICK AG's laser spectroscopy miniaturization integrates with aerial survey contractors for Permian Basin pipeline coverage. |
| Embedded Software Ecosystem Expansion | Emerson's protocol compatibility lock-in secures recurring calibration and replacement revenue across Gulf Coast refineries. |
| Cloud Data Hosting Unbundling | Third-party audit trail independence addresses California air district enforcement requirements separate from OEM relationships. |
| Helium Carrier Gas Substitution | Hydrogen or nitrogen alternative development mitigates Federal Helium Reserve auction price volatility for gas chromatography systems. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with refinery environmental compliance officers, optical component procurement managers, drone platform integration engineers, and third-party calibration gas distributors. EPA enforcement databases, OSHA incident reports, ASTM method certification records, and state air district procurement disclosures provided cross-validation. Bottom-up unit deployment estimates triangulated against top-down capital expenditure tracking across petroleum refining and midstream transport sectors.
Data-stream reconciliation across product type, application, end user, and technology dimensions modeled demand evolution over the projection horizon. Detection threshold requirements, regulatory compliance deadlines, and replacement cycle cadences informed segment-level expansion rates. CAGRs derived from weighted average of historical deployment trajectories and mandate-driven procurement schedules, with optical component supply constraints and helium cost volatility as industry-specific forecast modifiers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EPA refinery sector rule revisions or extended helium reserve auction disruptions. Projections reflect assumptions about regulatory enforcement continuity and semiconductor foundry capacity expansion. Material deviation in Texas Railroad Commission flaring mandate intensity or California AB 32 extension scope warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Material Testing Market
Testing Equipment
Chlorine Meter Market
Testing Equipment
Adhesive Tester Market
Testing Equipment
Europe Non-Destructive Testing Market
Testing Equipment
Chloride Reagents Kits Market
Testing Equipment
Rheology Controller Market
Testing Equipment
High Performance Liquid Chromatography (HPLC) Market
Testing Equipment
Hydrometer Market
Testing Equipment
Flammability Test Chamber Market
Testing Equipment
Gas Chromatography Columns Market
Testing Equipment
Leather Testing Machine Market
Testing Equipment
Materials Testing Equipment Market
Testing Equipment
Ultrasonic Testing Market
Testing Equipment
Water Penetration Tester Market
Testing Equipment
Global Liquid Process Analyzer Market
Testing Equipment
Heavy Metal Testing Market