
 Top Coated Direct Thermal Printing Films Market | 2026-2036
Top Coated Direct Thermal Printing Films Market Size, Share, and Industry Trends Forecast 2026-2036
Top Coated Direct Thermal Printing Films Market Analytics
Asset-light leasing models for coating lines are reshaping competitive entry in top coated direct thermal films, allowing mid-scale converters to access barrier-coated capacity without capital-intensive buildouts. UPM-Kymmene leverages its integrated pulp-to-film supply chain to secure raw material continuity across Nordic operations. SATO Holdings anchors its position through specialized thermal coating R&D centers in Japan. Avery Dennison competes by controlling distribution channels across North American retail and healthcare end users.
Top Coated Direct Thermal Printing Films are polymer substrates—typically biaxially oriented polypropylene or polyethylene terephthalate—bearing a heat-sensitive color-developing layer protected by an ultraviolet-resistant topcoat, manufactured through slot-die or gravure coating processes to produce labels, tags, and tickets without ribbon consumables. Synthetic Films command premium positioning due to moisture resistance and durability requirements in cold-chain logistics, while Direct Thermal Labels sustain volume leadership across retail point-of-sale applications. Coated Paper occupies the economy tier where shelf-life demands remain moderate, constraining margin expansion.
The EPA regulates volatile organic compound emissions from solvent-based coating operations in the United States, compelling domestic manufacturers to migrate toward aqueous or electron-beam curing systems. REACH restricts certain phenolic developers in European thermal coatings, reshaping formulation roadmaps for exporters serving EU healthcare and food-contact labeling. The FDA's indirect food additive regulations govern migration limits for topcoat components in direct thermal labels applied to packaged goods. Stakeholders must monitor regulatory divergence between jurisdictions to avoid compliance-driven supply chain fragmentation.
Market Dynamics
Asset-light leasing models for coating lines are compressing capital barriers for mid-scale converters, while REACH and EU Green Deal mandates force rapid reformulation of BPA-free topcoat chemistries across European supply chains.
Growth Catalysts
- E-commerce fulfillment infrastructure:Logistics providers in Germany, China, and the United States deploy direct thermal labels for last-mile tracking at scale. Cold-chain logistics operators specify synthetic films for moisture-resistant durability.
- REACH compliance mandates:European converters accelerate migration toward phenolic-developer-free thermal coatings to maintain healthcare and food-contact labeling access. BPA-free formulation roadmaps now anchor R&D spending.
- Solvent-to-aqueous coating transition:EPA volatile organic compound regulations push domestic manufacturers toward electron-beam curing systems. Aqueous coating lines reduce emission compliance costs.
Market Restraints
- Raw material concentration:Biaxially oriented polypropylene feedstock supply concentrates among integrated petrochemical producers in the Middle East and East Asia. Price volatility transmits directly to film converters.
- Technical performance ceiling:Direct thermal chemistry exhibits finite image stability under ultraviolet exposure and elevated temperature. Archive-grade applications require thermal transfer alternatives.
- Substitution pressure:Radio-frequency identification tags displace barcode labels in high-value asset tracking. RFID inlays penetrate pharmaceutical and automotive supply chains.
Strategic Opportunities
- Underpenetrated cold-chain segments:Latin American perishable logistics networks lack synthetic film labeling infrastructure. Regional cold storage buildouts create first-mover positioning.
- FDA food-contact expansion:Indirect food additive regulations for topcoat migration limits create certified-supplier scarcity. Compliant converters capture packaged goods labeling volume.
- Digital printing convergence:Inkjet-over-thermal hybrid systems enable variable-data printing on direct thermal substrates. Pharmaceutical serialization mandates drive pilot deployments.
Industry Challenges
- Coating chemistry talent scarcity:Formulation expertise in ultraviolet-resistant topcoats and developer stability concentrates among retiring specialists. Technical training pipelines remain underdeveloped.
- Multi-jurisdiction compliance synchronization:Divergent EPA, REACH, and FDA migration limit frameworks force parallel certification tracks. Product variants multiply inventory complexity.
- Legacy thermal printer compatibility:Next-generation topcoat formulations require validation across installed base of Zebra, Honeywell, and TSC printheads. Qualification cycles extend commercialization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Top Coated Direct Thermal Printing Films Market |
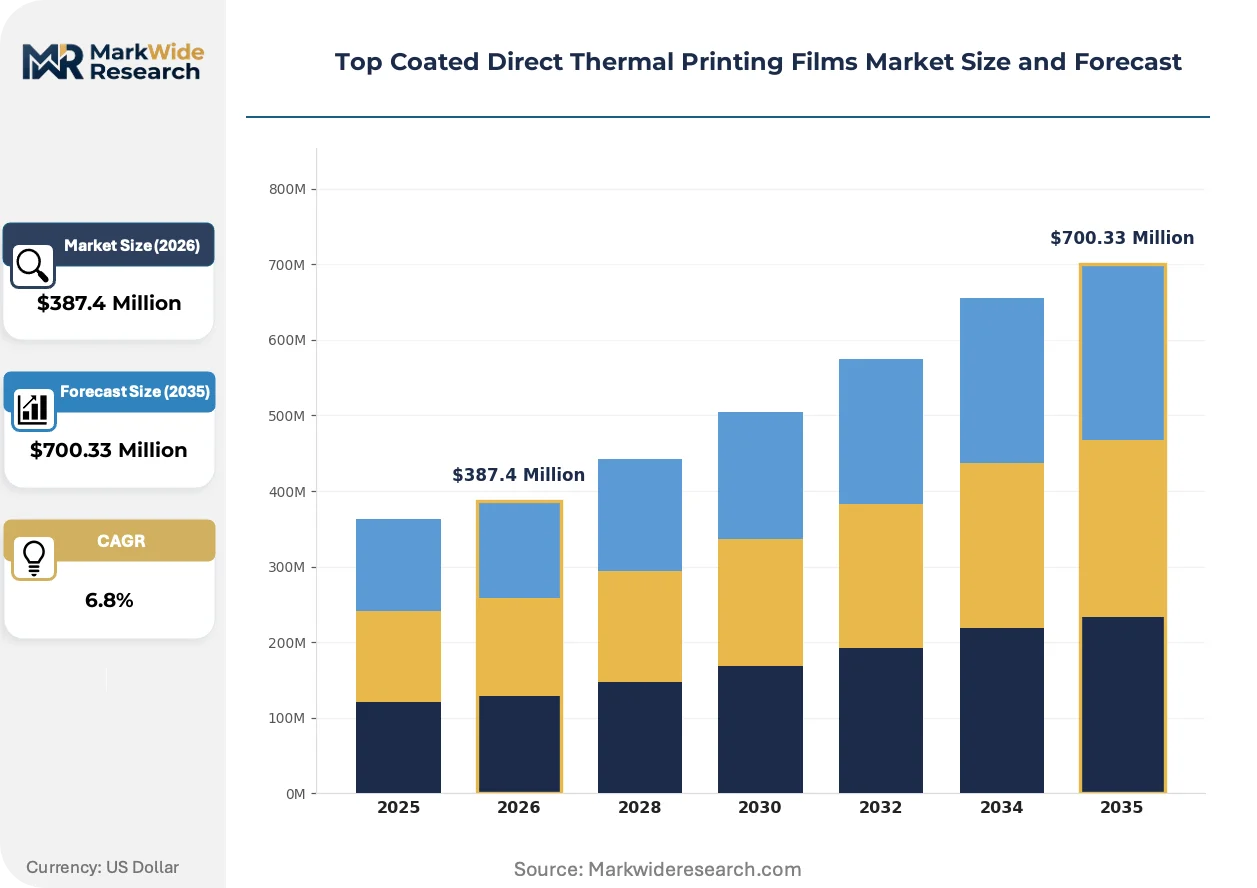
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $700.33 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Transfer Films, Direct Thermal Labels, Coated Paper, Synthetic Films End User: Retail, Logistics, Healthcare, Manufacturing Application: Labeling, Packaging, Ticketing, Identification Technology: Inkjet, Laser, Thermal, Digital Printing |
| Companies Covered | UPM-Kymmene, 3M, Avery Dennison, SATO Holdings, Zebra Technologies, Cosmo Films, Fujifilm, Ricoh, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Top Coated Direct Thermal Printing Films Market Evolving Landscape
Formulation science and regulatory chemistry are overtaking mechanical engineering as the primary axes of product differentiation, with coating performance and compliance certification now determining supplier selection ahead of substrate specifications.
Water-based ultraviolet-curable topcoats are rendering obsolete solvent-borne coating systems in North American manufacturing. Mid-scale converters adopting aqueous slot-die lines achieve EPA emission compliance without thermal oxidizer capital expenditure. The technology is rendering obsolete the historical advantage of integrated petrochemical players with captive solvent supply.
REACH Annex XVII restrictions on phenolic developers are compelling European thermal coating reformulation ahead of scheduled compliance deadlines. Exporters serving EU healthcare labeling must validate BPA-free color-developing layers through ECHA-recognized laboratories. German and French pharmaceutical label converters now specify certified-clean supply chains to preempt regulatory enforcement.
Consolidated buying by Amazon, Walmart, and regional grocery chains compresses supplier qualification cycles from eighteen months to ninety days. Procurement teams unbundle coating specification from substrate sourcing, awarding separate contracts to specialized topcoat applicators and film extruders. The United States and China exhibit the most pronounced procurement model fragmentation, with third-party logistics providers intermediating specification decisions.
Top Coated Direct Thermal Printing Films Market Segmentation
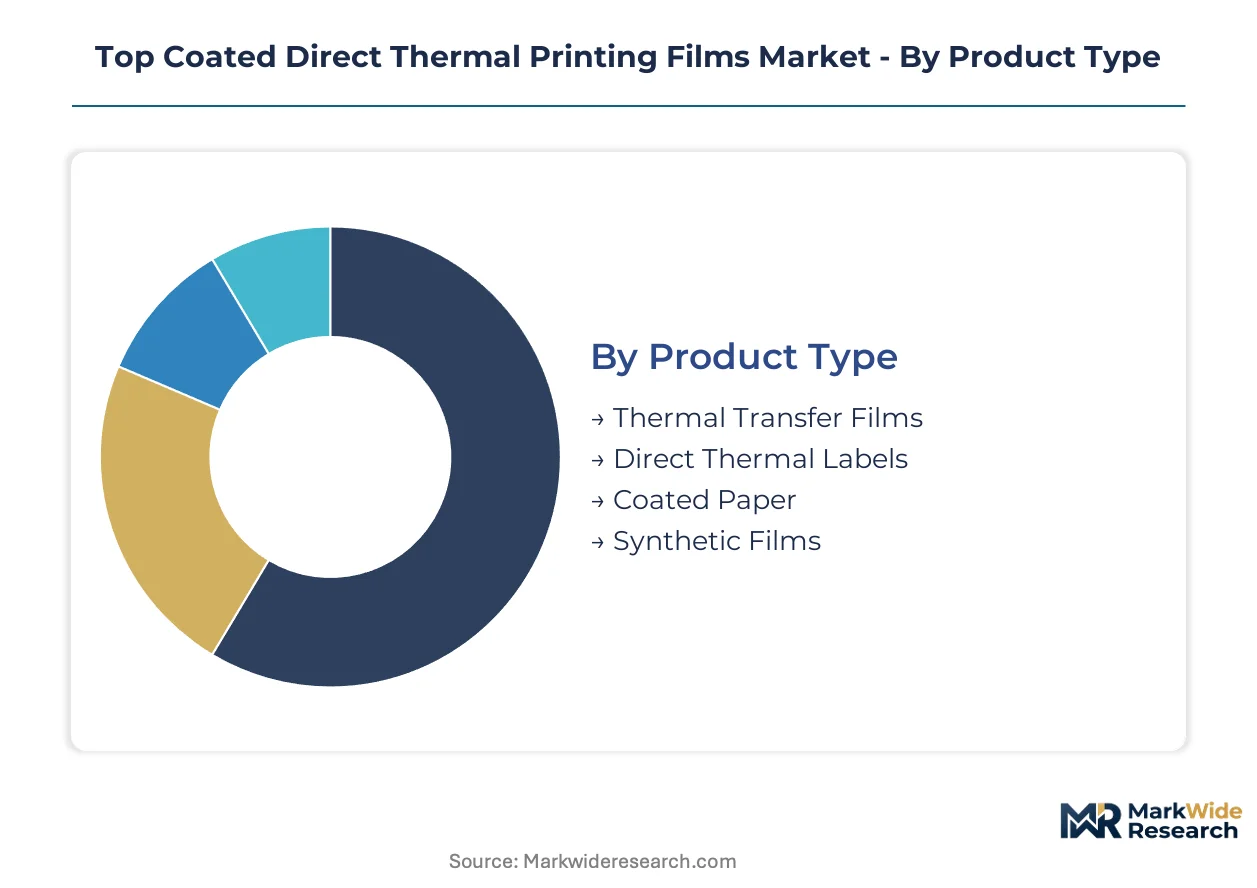
Segmentation in top coated direct thermal printing films reveals how substrate chemistry, end-use durability requirements, and print technology compatibility create distinct competitive arenas. Each dimension governs margin structure, regulatory exposure, and capital intensity differently.
Product Type:
Mature applications anchor volume while emerging specifications reshape premium tiers.
- Direct Thermal Labels:Polymer or paper substrates bearing heat-activated color-developing layers protected by ultraviolet-resistant topcoats. Retail point-of-sale systems in Germany and the United States consume this format at scale for receipt and price-marking applications where ribbon-free operation reduces total cost of ownership.
- Synthetic Films:Biaxially oriented polypropylene or polyethylene terephthalate constructions with moisture-barrier topcoats. Cold-chain logistics operators in China specify these for perishable tracking labels requiring freezer-grade adhesion and condensation resistance.
- Thermal Transfer Films:Ribbon-dependent substrates for archive-grade image stability. Healthcare record-keeping in France maintains demand despite higher consumable costs.
- Coated Paper:Economy-tier substrates with moderate shelf-life performance. Short-haul logistics in India deploy these where environmental exposure remains limited.
Direct Thermal Labels retain volume leadership; Synthetic Films hold the steepest expansion curve.
End User:
Customer type determines specification stringency and procurement consolidation patterns.
- Logistics:Third-party fulfillment providers and express carriers driving last-mile tracking label consumption. Amazon's consolidated buying power in the United States compresses supplier qualification cycles and unbundles coating from substrate sourcing decisions.
- Healthcare:Hospitals, pharmacies, and diagnostic laboratories requiring FDA-compliant migration limits for patient identification and specimen labeling. German pharmaceutical converters now mandate certified-clean supply chains to preempt REACH enforcement.
- Retail:Grocery chains and mass merchandisers deploying point-of-sale labels and shelf-edge pricing. Walmart's procurement centralization in North America fragments specification authority toward specialized coating applicators.
- Manufacturing:Automotive and electronics producers using work-in-process and asset-tracking labels. Japanese automotive supply chains favor synthetic films for barcode durability through paint-shop and assembly environments.
Logistics commands the largest addressable spend; Healthcare exhibits the most rapid compliance-driven specification upgrading.
Application:
Use-case durability requirements stratify across archive, transactional, and environmental exposure tiers.
- Labeling:Primary adhesive-backed applications for product, shipping, and identification purposes. E-commerce fulfillment infrastructure in China deploys direct thermal shipping labels at massive scale.
- Ticketing:Event admission, transportation passes, and lottery applications requiring thermal-printed durability. Synthetic films penetrate this segment where mechanical abrasion resistance proves critical.
- Packaging:Direct thermal elements integrated into flexible and corrugated packaging. FDA food-contact migration limits constrain topcoat chemistry selection for packaged goods labeling in the United States.
- Identification:Patient wristbands, asset tags, and security credentials. Healthcare identification in France and Germany accelerates BPA-free formulation adoption under REACH Annex XVII pressure.
Labeling absorbs the highest unit volume; Identification faces the most stringent regulatory reformulation timelines.
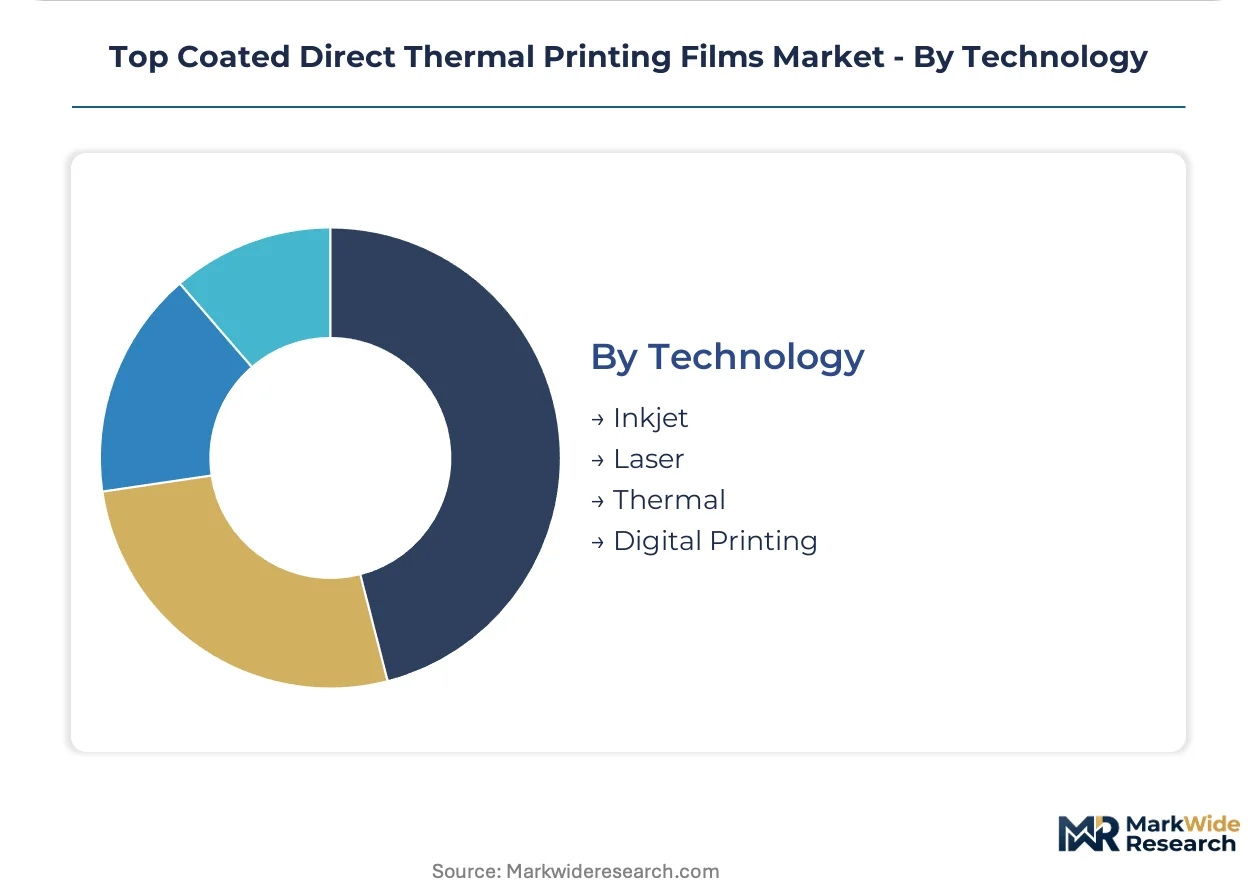
Technology:
Print mechanism compatibility governs substrate surface energy and coating receptivity specifications.
- Thermal:Direct thermal and thermal transfer printheads requiring heat-sensitive coatings with precise activation thresholds. Zebra and Honeywell printhead validation cycles extend commercialization timelines for next-generation topcoat formulations.
- Inkjet:Aqueous and solvent ink systems demanding controlled surface tension and porosity. Hybrid inkjet-over-thermal systems enable variable-data pharmaceutical serialization pilots in Japan.
- Laser:Toner fusion processes requiring thermal stability in substrate and coating. Limited penetration in direct thermal markets due to competing technology economics.
- Digital Printing:Electrophotographic and production inkjet systems for short-run customization. Label converters in the United States adopt digital workflows to reduce plate costs for seasonal packaging campaigns.
Thermal dominates installed base; Digital Printing climbs fastest in flexible-run packaging applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Third-party logistics providers and e-commerce fulfillment operators concentrate purchasing power in Germany, China, and the United States. These buyers drive specification standardization across cold-chain logistics, retail point-of-sale, and last-mile tracking applications.
United States
Amazon and Walmart consolidate procurement for direct thermal shipping labels and shelf-edge pricing systems. EPA volatile organic compound regulations push converters toward aqueous coating lines and electron-beam curing systems. The Midwest industrial corridor hosts specialty coating applicators serving pharmaceutical serialization mandates.
Germany
Pharmaceutical label converters in Baden-Württemberg and Bavaria accelerate BPA-free formulation adoption under REACH Annex XVII restrictions. ECHA-recognized laboratory certification now anchors supplier qualification for healthcare and food-contact applications. The Rhine-Main logistics cluster deploys synthetic film labels for perishable cold-chain tracking.
China
E-commerce fulfillment infrastructure in the Yangtze River Delta and Pearl River Delta consumes direct thermal labels at massive scale for last-mile delivery tracking. MIIT standards govern barcode print quality for cross-border shipments. Synthetic film demand concentrates in Shanghai and Shenzhen cold storage networks.
Japan
Automotive supply chains in Aichi Prefecture and the Kanto region specify synthetic thermal films for work-in-process labeling through paint-shop environments. METI technical standards influence thermal coating performance specifications. SATO Holdings maintains specialized R&D operations in Tokyo for next-generation developer chemistry.
France
Hospital and pharmacy networks in Île-de-France mandate certified-clean supply chains for patient identification wristbands under ANSM guidance. Healthcare label converters preempt REACH enforcement through BPA-free thermal coating validation. The Lyon pharmaceutical cluster drives specification upgrading for diagnostic specimen labeling.
Top Coated Direct Thermal Printing Films Market Competitive Landscape
Channel-controlling players compete with product-specialist players across distinct value-capture vectors. Consolidated buying by Amazon, Walmart, and regional grocery chains compresses supplier qualification cycles and fragments specification authority. Three archetypes dominate: integrated pulp-to-film producers securing raw material continuity, specialized thermal coating R&D operators, and distribution-channel controllers. Capacity expansion through asset-light leasing models and strategic partnerships for aqueous coating technology represent the dominant competitive moves.
Among Nordic integrated producers, UPM-Kymmene anchors the captive supply chain archetype through pulp-to-film operations. Japanese specialists SATO Holdings and Fujifilm occupy positions within the thermal coating R&D tier, with SATO exemplifying concentrated formulation expertise. Avery Dennison represents the North American channel-control model, leveraging distribution infrastructure across retail and healthcare end users. These three companies illustrate the structural segmentation between upstream integration, technology specialization, and downstream access.
| Leading Market Players |
|---|
| UPM-Kymmene |
| 3M |
| Avery Dennison |
| SATO Holdings |
| Zebra Technologies |
| Cosmo Films |
| Fujifilm |
| Ricoh |
| Mondi Group |
| Others |
Value Network & Pricing Analysis
Overcapacity in aqueous coating lines across the United States Midwest is compressing contract margins for mid-scale converters while simultaneously lowering barriers for new entrants seeking EPA-compliant capacity. This utilization dynamic rewards asset-light leasing models and punishes legacy solvent-based operators facing thermal oxidizer retrofit costs.
Pricing Analysis
Certification level creates the primary spread between premium and economy tiers, with FDA food-contact validation and ECHA-recognized BPA-free certification commanding substantial premiums over uncertified alternatives. Three-tier pricing structure separates REACH-compliant healthcare grades from standard logistics specifications and uncoated paper economy options. Cost compression in standard logistics grades is intensifying because Amazon and Walmart procurement teams unbundle coating from substrate sourcing. Healthcare and pharmaceutical converters exhibit the least price sensitivity due to regulatory compliance requirements and patient safety liability exposure.
Supply Chain Analysis
Biaxially oriented polypropylene feedstock concentrates among integrated petrochemical producers in Saudi Arabia, South Korea, and China, with price volatility transmitting directly to film converters in Germany and the United States. Coating chemistry inputs draw from specialty chemical suppliers in Japan and Germany, while topcoat formulation expertise rests on a shrinking base of retiring specialists. Single-source vulnerability concentrates in phenolic-developer supply chains subject to REACH Annex XVII restrictions. Distribution runs through third-party logistics providers and specialized label converters rather than direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as procurement unbundling by consolidated buyers creates specialized niches for coating applicators, film extruders, and certification laboratories that integrated players cannot serve cost-effectively.
For Market Incumbents: Pre-empt margin erosion in standard logistics grades by securing captive BOPP supply through long-term offtake agreements with Middle Eastern producers. Accelerate ECHA-recognized laboratory certification for BPA-free formulations before REACH enforcement tightens, locking out smaller competitors from healthcare and food-contact segments.
For New Entrants and Emerging Players: Pursue Latin American cold-chain infrastructure buildouts where synthetic film labeling penetration remains underdeveloped relative to perishable logistics growth. Target certified-clean supply chain status for European pharmaceutical converters as a beachhead, then expand into adjacent food-contact applications through regulatory equivalence strategies.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized coating applicators with multi-year service contracts to pharmaceutical and healthcare end users. Long-term viability hinges on formulation chemistry talent pipelines and regulatory certification moats rather than substrate manufacturing scale. Monitor ECHA enforcement patterns as the critical inflection indicator for BPA-free formulation adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Asset-Light Coating Capacity Expansion | Leasing aqueous slot-die lines enables EPA compliance without thermal oxidizer capital expenditure. |
| REACH-Compliant Formulation Investment | BPA-free thermal coating R&D secures access to EU healthcare and food-contact labeling volumes. |
| Backward Integration into BOPP Feedstock | Captive polypropylene supply insulates converters from Middle East and East Asian price volatility. |
| Third-Party Logistics Partnership | Direct relationships with Amazon and regional fulfillment providers bypass fragmented distributor networks. |
| Hybrid Inkjet-Over-Thermal Development | Variable-data printing capability captures pharmaceutical serialization mandates in Japan and the United States. |
Research Methodology
A spread of perspectives from coating line operators, pharmaceutical label converters, third-party logistics procurement managers, and thermal printer OEM technical directors converged on the working assumptions. Primary fieldwork combined with secondary validation from customs trade data, SEC filings of listed film producers, EPA emission compliance databases, and ECHA substance restriction notifications. Bottom-up capacity utilization estimates triangulated against top-down demand modeling from e-commerce fulfillment infrastructure deployment.
Demand-supply balance dynamics across substrate chemistry, coating technology, and end-use durability requirements anchored the analytical framework. Segmentation dimensions modeled include product type, end user vertical, application durability tier, and print technology compatibility. CAGRs derived from installed base growth rates, printer hardware shipment patterns, and regulatory compliance transition timelines. Forecast inputs incorporated cold-chain logistics buildout trajectories and REACH reformulation adoption curves.
Sensitivities concentrate around ECHA enforcement intensity, BOPP feedstock price volatility, and RFID substitution rates in high-value asset tracking. Cross-checking against Zebra and Honeywell printhead validation cycle disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals & Materials
Dioctyl Phthalate Market
Chemicals & Materials
Leather Glue Market
Chemicals & Materials
Global Chelated Trace Minerals Market
Chemicals & Materials
Europe Barium Carbonate Market
Chemicals & Materials
Global Self-Adhesive Vinyl Films Market
Chemicals & Materials
Chloroethylene Market
Chemicals & Materials
Superabrasive Electroplated Grinding Wheel Market
Chemicals & Materials
Photoluminescent Paints Market
Chemicals & Materials
Debonding-on-Demand Adhesive Tapes for Electronics Dismantling Market
Chemicals & Materials
Barium Sulphate Market
Chemicals & Materials
Sulfur Market
Chemicals & Materials
1-Decene Market
Chemicals & Materials
Global Gravure Printing Inks Market
Chemicals & Materials
Global Wood Preservative Chemicals and Coatings Active Ingredients Market
Chemicals & Materials
Medical Grade Silicone Rubber Market
Chemicals & Materials
Global Methyl Tertiary Butyl Ether Market