
 Alunite Market | 2026-2036
Alunite Market Size, Share, and Industry Trends Forecast 2026-2036
Alunite Market Analysis
Water treatment and agriculture end-use verticals is recalibrating demand profiles across the alunite value chain. Det-Al Aluminium leverages its captive bauxite-alumina infrastructure to secure raw material continuity. Sunminerals anchors South Asian supply through specialized refining capabilities. Pacer Corporation competes on ceramic-grade purity specifications in North American markets.
Alunite is a hydrated aluminum potassium sulfate mineral with the chemical formula KAl3(SO4)2(OH)6, typically formed through sulfuric acid alteration of feldspar-bearing rocks in volcanic environments; it serves primarily as an alumina source for non-bauxite aluminum production and as a feedstock for potassium sulfate fertilizer manufacturing. Powder and refined grades capture premium margin pools due to stringent particle-size distribution requirements in specialty ceramics and high-purity chemical synthesis. Granular formulations lead volume throughput in agricultural broadcasting applications where dissolution kinetics matter less than handling logistics. Crude alunite occupies a mature, price-sensitive niche in bulk metallurgical fluxing where impurity tolerance remains high.
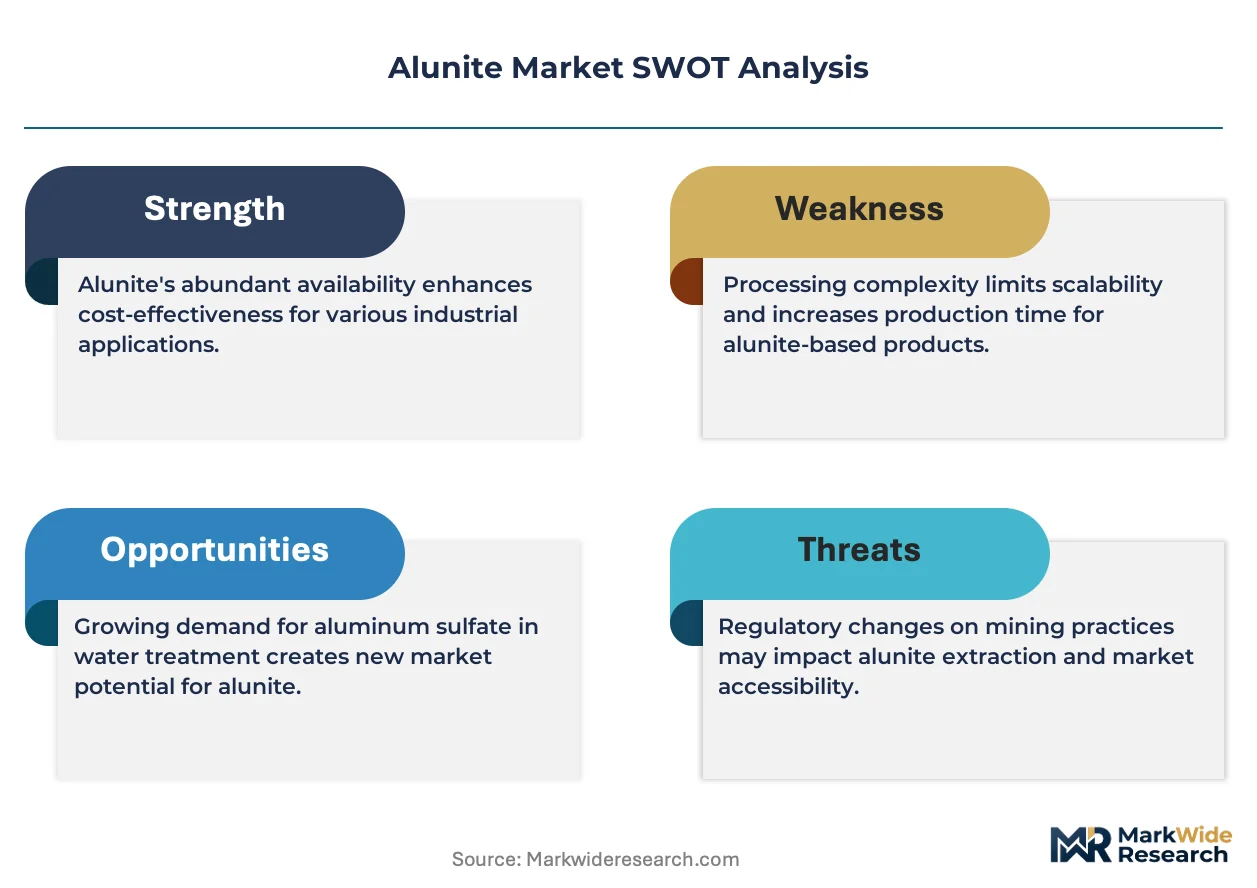
China's MEE enforces extraction quotas and tailings standards that constrain unlicensed alunite mining capacity. The EPA monitors sulfur dioxide release thresholds from alunite calcination operations in the United States. ISO 9001 quality certification increasingly gates market access for refined grades destined to European ceramics manufacturers. Stakeholders must weigh regulatory compliance capital against the margin compression risk from substitute alumina sources before committing to greenfield extraction investments.
Market Dynamics
Alunite supply chains are tightening around China's dual carbon enforcement, which is electrifying capital allocation toward cleaner calcination technologies and away from legacy sulfur-emitting facilities. The mineral's alumina content competes directly with bauxite in specialty ceramics, creating a pricing tension that rewards purity differentiation.
Growth Catalysts
- Sulfate-based soil amendments:Farmers across East Asian rice belts are substituting synthetic potassium fertilizers with alunite-derived sulfate products. China's agricultural extension services promote these amendments under soil health improvement mandates.
- GB standards on industrial emissions:China's tightening extraction protocols are forcing consolidation among licensed miners, improving feedstock quality consistency for downstream refiners. MEE enforcement creates premium tiering between compliant and non-compliant supply.
- Alumina-rich ceramics clusters:Jingdezhen and Arita ceramics manufacturers specify ultra-low iron alunite for high-temperature porcelain glazes. Their procurement volumes anchor refined-grade pricing premiums.
Market Restraints
- Energy-intensive calcination:Natural gas price volatility in European processing hubs compresses margins for alumina extraction from alunite. Operators cannot pass full fuel cost swings to ceramics buyers locked in annual contracts.
- Deposit concentration:Economic alunite reserves cluster in volcanic belts across eastern China and southwestern United States, creating geographic supply risk. Single-source dependency exposes processors to localized environmental shutdowns.
- Bauxite substitution:Guinea and Australian bauxite miners are expanding low-carbon alumina refining capacity, threatening alunite's niche in non-metallurgical alumina markets. Their scale economies outmatch alunite on unit cost.
Strategic Opportunities
- Water treatment applications:Municipal utilities in Germany and Netherlands are piloting alunite-derived coagulants for phosphate removal. ECHA registration pathways for mineral-based water treatment chemicals are streamlining market entry.
- Circular sulfur recovery:Smelter off-gas capture technologies are converging with alunite synthesis, enabling synthetic alunite production from industrial waste streams. This bypasses geological mining constraints entirely.
- Specialty fertilizer channels:Direct-to-farm digital platforms in South Korea and Japan are disintermediating traditional agrochemical distributors for sulfate fertilizer sales. Alunite processors can capture margin previously lost to wholesale markups.
Industry Challenges
- ISO 9001 certification timelines:European ceramics manufacturers require 12-18 month quality system audits before approving new refined-grade suppliers. Smaller miners lack documentation infrastructure to accelerate these approvals.
- Legacy calciner integration:Retrofitting existing rotary kilns for SO2 scrubbing demands capital outlays that strain mid-tier processors. Equipment lead times from specialized engineering firms now stretch beyond 24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alunite Market |
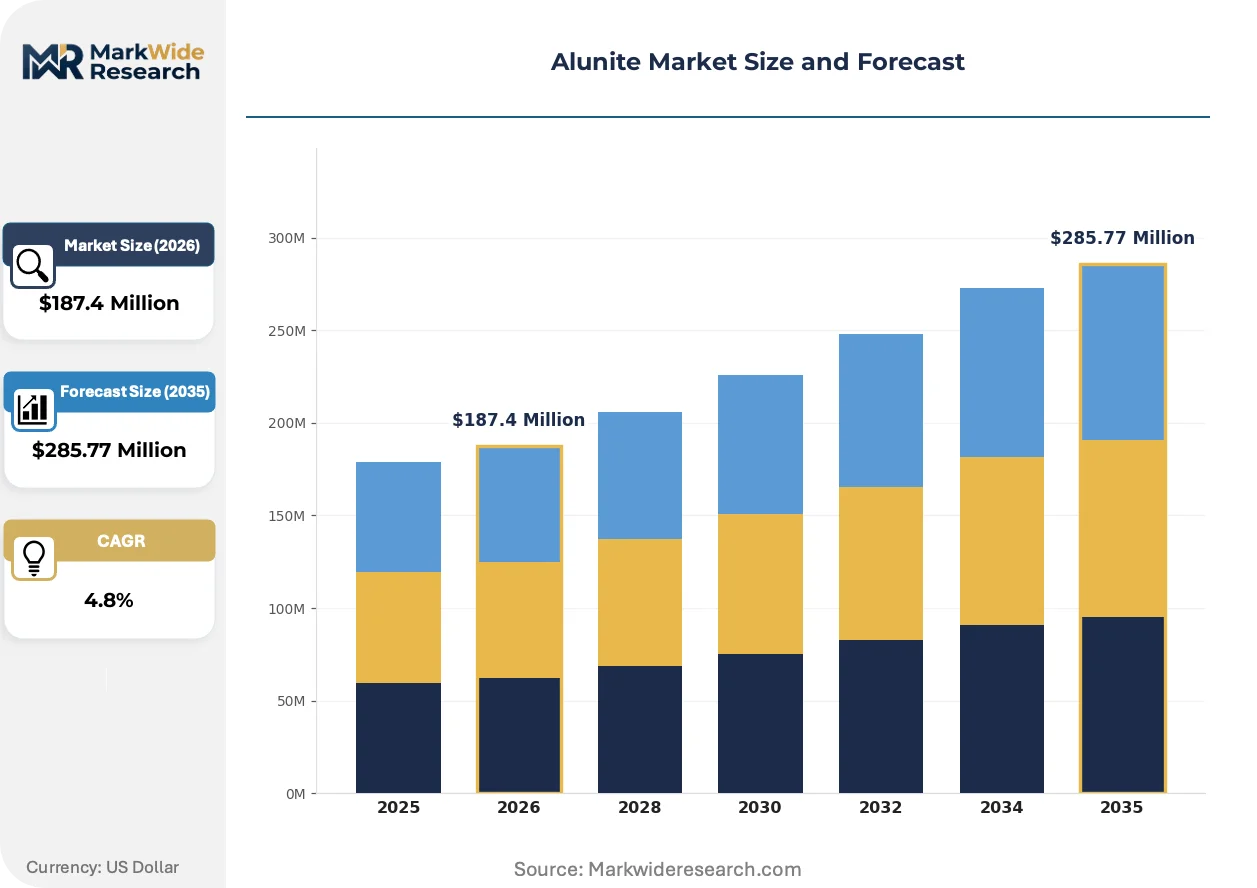
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granular, Crude, Refined Application: Metallurgy, Agriculture, Chemical Industry, Ceramics End User: Manufacturers, Farmers, Researchers, Construction Packaging Type: Bags, Drums, Bulk Containers, Loose |
| Companies Covered | Alunite Pretoria, Det-Al Aluminium, Sunminerals, New Mont Corporation, Lincoln, Imerys Ceramics, Baslini, Alunite Gold, Pacer Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alunite Market Emerging Trajectories
Processing technology and regulatory chemistry are reshaping how alunite moves from volcanic rock to finished alumina and sulfate products. Electrification of thermal processing and tightening emissions accounting are forcing asset-level decisions that will determine competitive survival.
Flash calcination systems are electrifying the thermal processing segment, replacing natural gas-fired rotary kilns with plasma arc and induction heating platforms. Japanese ceramics conglomerates are piloting these systems at their Nagoya refining facilities, targeting 40% reduction in Scope 1 emissions. This technology is electrifying capital allocation decisions, compressing payback period calculations for gas-dependent competitors.
REACH authorization requirements for sulfate compounds are tightening traceability obligations across European alunite supply chains. ECHA's 2023 updated guidance demands full life-cycle emission disclosures for alumina feedstocks used in consumer ceramics. German and Italian tableware manufacturers are now requiring batch-level carbon intensity certificates, forcing non-EU miners to invest in third-party verification or lose shelf access.
Long-term offtake contracting is displacing spot market purchases among major ceramics buyers, reversing a decade of procurement decentralization. Jingdezhen porcelain consortiums now negotiate 36-48 month supply agreements directly with licensed Chinese miners, bypassing traditional trading houses. This concentration is most visible in East Asian markets where foundry-grade alumina specifications are tightening and supplier qualification costs favor relationship lock-in over price arbitrage.
Alunite Market Segmentation
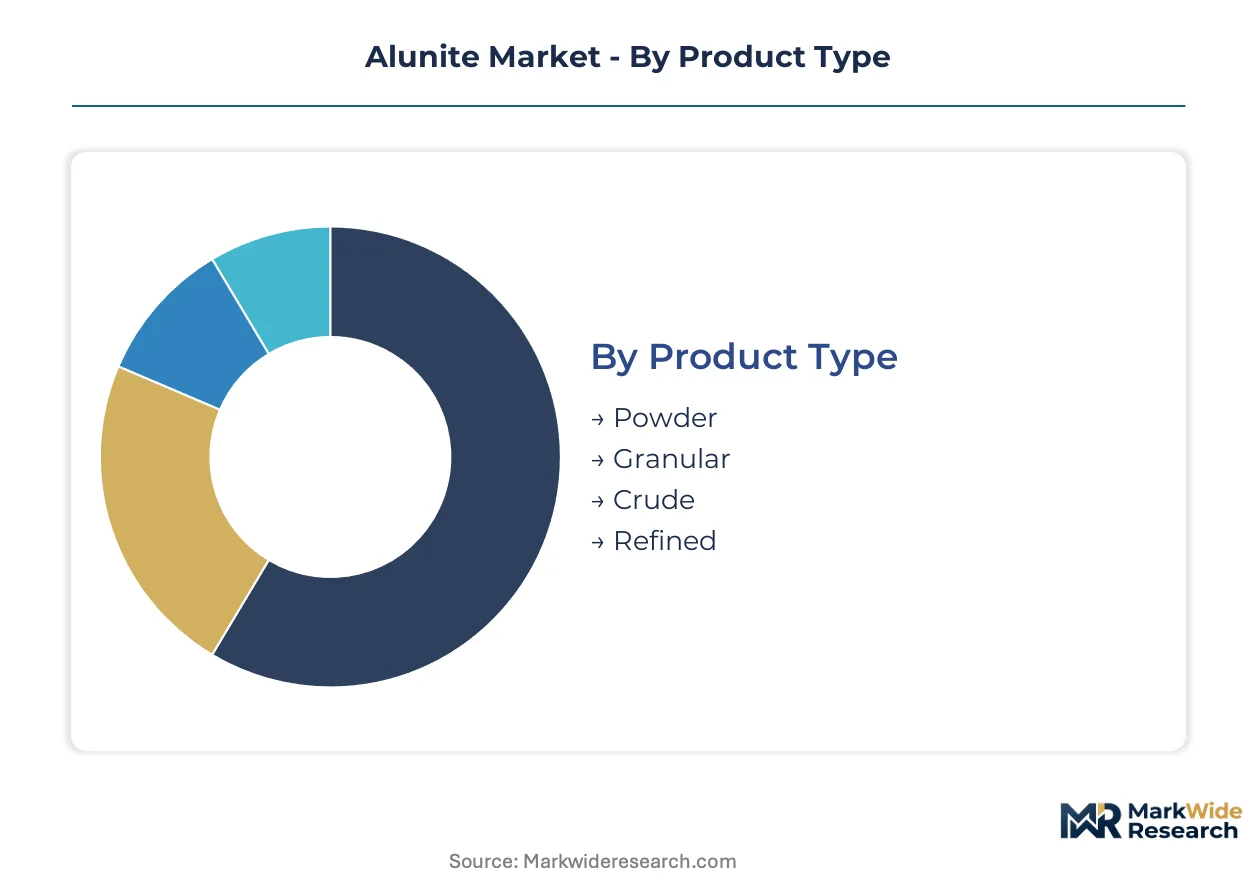
Alunite's value chain fragments across four distinct dimensions where particle physics, thermal processing, and end-use chemistry create divergent margin profiles. Each segmentation axis reveals how purity thresholds and logistics economics partition commercial opportunity.
Product Type:
Powder and refined grades command premium positioning through stringent particle-size distribution protocols, while granular and crude variants anchor volume throughput in cost-sensitive applications.
- Powder:Finely milled material with sub-45 micron particle distribution enables homogeneous dispersion in specialty ceramic glazes. Jingdezhen porcelain manufacturers specify ultra-low iron powder grades for high-temperature vitrification where color consistency determines batch acceptance.
- Refined:Chemically purified alunite with controlled sulfate and alumina ratios serves pharmaceutical-grade alumina extraction and precision fertilizer synthesis. South Korean specialty chemical processors pay substantial premiums for ISO-certified refined grades with documented impurity spectra.
- Granular:Coarse agglomerated form optimized for mechanical handling in agricultural broadcasting equipment. East Asian rice belt cooperatives favor 2-4mm granules for dissolution-controlled nutrient release in paddy flooding regimes.
- Crude:Run-of-mine material with minimal processing serves bulk metallurgical fluxing where alumina content tolerance spans wide ranges. Chinese steel mill procurement accepts variable impurity loads in exchange for delivered cost advantages.
Mature deployment sits with Crude. Newer deployment is concentrated in Refined.
Application:
Ceramics and agriculture absorb the majority of processed volume, while metallurgy and chemical industry applications compete for consistent feedstock quality.
- Ceramics:Alumina-rich alunite replaces bauxite in high-temperature porcelain and technical ceramic manufacturing. Arita and Jingdezhen cluster producers require sub-0.5% iron content for translucent bone china glazes.
- Agriculture:Sulfate-based soil amendments derived from alunite provide potassium and sulfur nutrition without chloride toxicity. China's agricultural extension services promote these products under soil health improvement mandates across rice and tea cultivation zones.
- Metallurgy:Bulk alumina source for non-bauxite aluminum production and steelmaking flux applications. Legacy rotary kiln operators struggle with energy cost pass-through in this price-elastic segment.
- Chemical Industry:Feedstock for potassium sulfate manufacturing and specialty alumina chemical synthesis. ECHA registration requirements for sulfate compounds constrain European market entry for unverified suppliers.
Volume leadership belongs to Agriculture. Margin expansion concentrates in Ceramics.
End User:
Procurement patterns diverge between industrial manufacturers seeking long-term supply security and fragmented agricultural buyers prioritizing delivered cost.
- Manufacturers:Ceramic, chemical, and metallurgical processors negotiate multi-year offtake agreements with licensed miners. Japanese and South Korean industrial buyers now require batch-level carbon intensity certificates under Scope 3 disclosure mandates.
- Farmers:Individual and cooperative agricultural operators purchase through distributor networks or emerging direct-to-farm digital platforms. South Korean and Japanese sulfate fertilizer platforms are disintermediating traditional agrochemical wholesalers.
- Researchers:Academic and government laboratories procure small-batch refined grades for mineralogical and materials science studies. Limited volume but high specification tolerance drives premium pricing.
- Construction:Niche applications in cement additives and specialty concrete formulations where sulfate resistance properties matter. Building material standards in China and Japan define acceptable alumina-sulfate ratios.
Contract sophistication peaks with Manufacturers. Price sensitivity concentrates among Farmers.
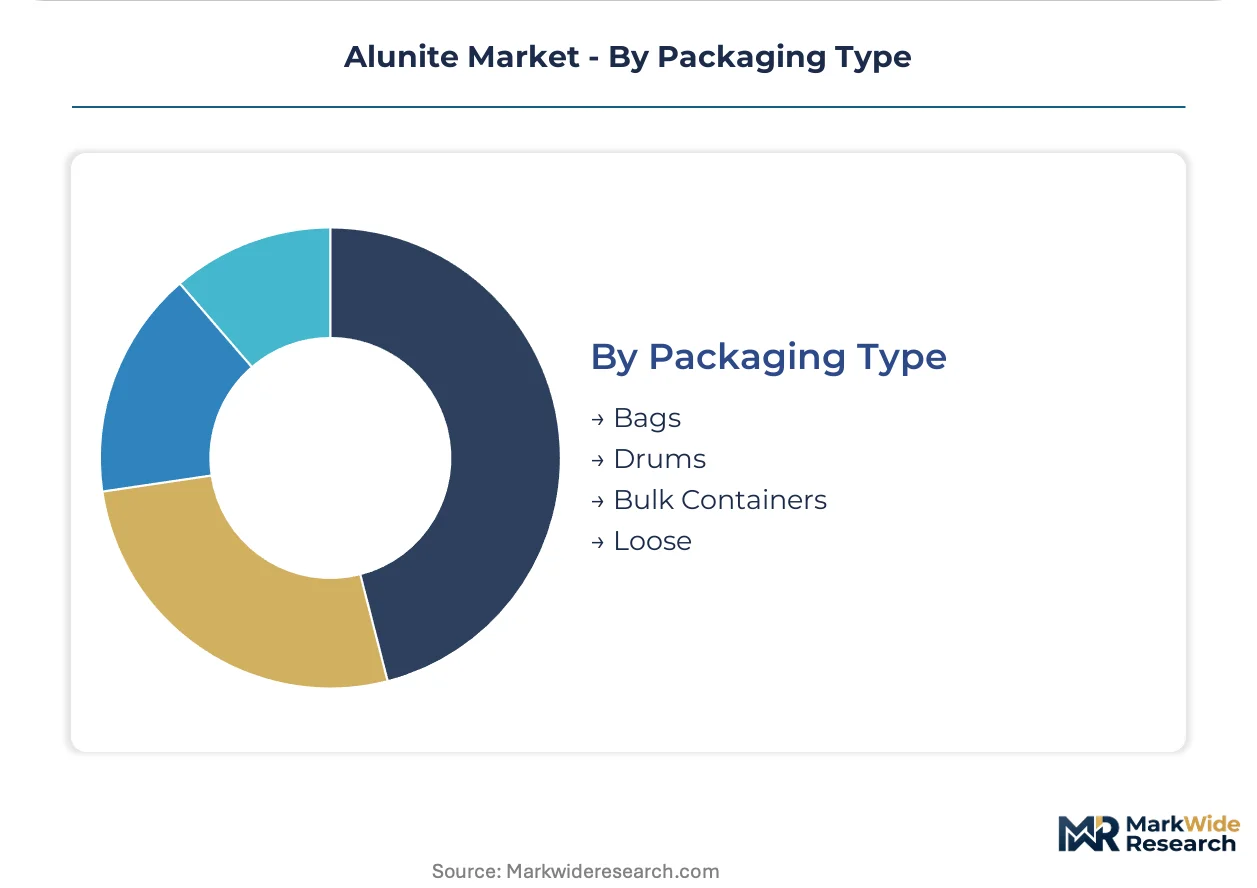
Packaging Type:
Logistics economics and contamination risk determine packaging selection across the value chain, from bulk ocean shipments to laboratory-scale containment.
- Bulk Containers:Intermodal tank containers and flexible intermediate bulk containers dominate refined grade transport to ceramics and chemical processors. ISO tank certification requirements add compliance cost layers for cross-border shipments.
- Bags:Multi-layer paper and woven polypropylene sacks serve agricultural and small-scale industrial distribution. Korean and Japanese fertilizer cooperatives specify moisture-barrier laminates for monsoon-season storage.
- Drums:Steel and fiber drums contain high-purity powder grades for laboratory and specialty manufacturing use. UN certification for hazardous material transport applies to sulfate-rich formulations.
- Loose:Unpackaged bulk delivery via pneumatic trailer and railcar serves integrated processors with captive receiving infrastructure. Chinese steel mills and cement plants accept loose crude alunite at dedicated unloading facilities.
Scale efficiency favors Bulk Containers. Handling flexibility concentrates in Bags.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China dominates alunite extraction capacity while Japan and South Korea absorb refined-grade output for ceramics manufacturing. The United States maintains legacy mining operations serving metallurgical flux markets. Germany and Italy anchor European demand through precision ceramics and water treatment applications.
China
East Asian ceramics clusters and agricultural extension programs drive consumption of sulfate-based soil amendments. The MEE enforces extraction quotas and tailings standards that consolidate licensed mining capacity. Jingdezhen porcelain manufacturers specify ultra-low iron alunite for high-temperature glaze applications.
Japan
Arita ceramics producers and specialty chemical processors command premium refined-grade imports for bone china and pharmaceutical alumina synthesis. METI promotes flash calcination electrification at Nagoya refining facilities. Kansai industrial buyers negotiate long-term offtake agreements with carbon intensity disclosure requirements.
South Korea
Direct-to-farm digital platforms and rice belt cooperatives accelerate sulfate fertilizer adoption under soil health mandates. The MFDS regulates mineral-based feedstock quality for agricultural chemical registration. Seoul Capital Area specialty chemical processors pay substantial premiums for ISO-certified refined grades.
United States
Southwestern volcanic belt deposits supply bulk metallurgical flux markets and steelmaking applications. The EPA monitors sulfur dioxide release thresholds from calcination operations. Pacer Corporation competes on ceramic-grade purity specifications in North American specialty markets.
Germany
Municipal utilities pilot alunite-derived coagulants for phosphate removal in water treatment applications. ECHA REACH authorization requirements demand full life-cycle emission disclosures for alumina feedstocks. North Rhine-Westphalia ceramics manufacturers require batch-level carbon intensity certificates from suppliers.
Alunite Market Vendor Landscape
Top-tier vendors anchor premium refined-grade supply, while mid-tier processors compete on volume throughput in agricultural and metallurgical segments. The vendor base stratifies across purity certification tiers, with ISO 9001 accreditation increasingly gating European market access. Three archetypes dominate: integrated miners with captive refining infrastructure, specialty chemical processors focused on high-purity alumina extraction, and regional distributors serving fragmented agricultural demand. Capacity expansion and backward integration into mining assets represent the dominant competitive moves as processors seek feedstock security.
Among Asia-Pacific-based operators, Sunminerals anchors South Asian supply through specialized refining capabilities, while Det-Al Aluminium leverages its captive bauxite-alumina infrastructure to secure raw material continuity. Pacer Corporation occupies a position exemplifying North American specialty-grade competition focused on ceramic purity specifications.
| Leading Market Players |
|---|
| Alunite Pretoria |
| Det-Al Aluminium |
| Sunminerals |
| New Mont Corporation |
| Lincoln |
| Imerys Ceramics |
| Baslini |
| Alunite Gold |
| Pacer Corporation |
| Others |
Supply Flow & Price Mechanics
Natural gas procurement costs for rotary kiln calcination cascade through the alunite value chain, compressing margins for European processors while Chinese operators with coal-to-gas conversion subsidies maintain cost advantages in refined-grade exports. This energy cost asymmetry stratifies pricing tiers between electrified flash calcination facilities and legacy thermal operators.
Pricing Analysis
Margin tightening in granular agricultural grades reflects natural gas price volatility that legacy rotary kiln operators cannot pass through to rice belt cooperatives locked in seasonal contracts. Three-tier pricing structure across premium refined, standard ceramic-grade, and economy crude levels separates ISO-certified South Korean chemical processors from Jingdezhen porcelain manufacturers and Chinese steel mill flux buyers. Pricing pressure intensifies in metallurgical segments as Guinean bauxite miners expand low-carbon alumina capacity. Farmers remain most price-sensitive, while Arita ceramics producers absorb premiums for sub-0.5% iron specifications.
Supply Chain Analysis
Dual-sourcing mandates from Japanese and South Korean industrial buyers require qualified suppliers across both Chinese licensed mining operations and southwestern United States volcanic belt deposits. Feedstock draws from feldspar-bearing volcanic rock, sulfuric acid alteration reagents, and natural gas or electricity for thermal processing. Single-source vulnerability concentrates in eastern China's MEE-licensed extraction zones where environmental shutdowns cascade downstream. Distribution runs through long-term offtake agreements directly from miners to ceramics consortiums, displacing traditional trading house intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flash calcination electrification is displacing natural gas-fired rotary kilns, compressing payback periods for incumbent operators while opening entry points for capital-backed new entrants with clean-sheet facility designs.
For Market Incumbents: Anticipate bauxite substitution threats from Guinean and Australian miners by deepening backward integration into captive alunite deposits in China's volcanic belts. Prioritize ISO 9001 certification investments to maintain European ceramics access against ECHA REACH tightening. Lock in 36-48 month offtake agreements with Jingdezhen and Arita manufacturers before new entrants qualify.
For New Entrants and Emerging Players: The premium-to-economy price gap in refined grades offers white-space entry through synthetic alunite production from smelter off-gas sulfur recovery, bypassing geological mining constraints entirely. Target German municipal water treatment pilots for alunite-derived phosphate removal coagulants. Pursue direct-to-farm digital platform partnerships in South Korean rice belts to disintermediate traditional agrochemical distributors.
For Investors and Strategic Acquirers: MEE enforcement creating premium tiering between compliant and non-compliant Chinese supply is the leading indicator that consolidation returns will favor licensed miners with documented tailings standards. Five-to-ten year viability hinges on electrified processing technology deployment. Watch for flash calcination equipment order backlogs stretching beyond 24 months as the inflection signal for capacity-constrained supply.
| Strategic Initiative | Industry Significance |
|---|---|
| Flash Calcination Electrification | Plasma arc and induction heating platforms at Nagoya facilities target 40% Scope 1 emissions reduction. |
| Backward Integration into Mining | Captive bauxite-alumina infrastructure secures raw material continuity against MEE extraction quota tightening. |
| ISO 9001 Certification Investment | Quality system documentation gates European ceramics market access under ECHA traceability mandates. |
| Direct-to-Farm Platform Partnership | Digital disintermediation in South Korean and Japanese sulfate fertilizer channels captures wholesale margin. |
| Synthetic Alunite from Waste Streams | Smelter off-gas sulfur recovery converges with mineral synthesis, bypassing geological deposit constraints. |
Methodological Framework
Multi-period observation of MEE extraction quota enforcement, GB standards compliance rates, and flash calcination technology adoption anchored the trend analysis, supplemented by interviews with Chinese licensed mining operators, Japanese ceramics procurement directors, South Korean specialty chemical processors, German municipal water treatment engineers, and US metallurgical flux buyers. Secondary validation drew from MEE regulatory filings, ECHA REACH guidance updates, METI technology roadmaps, customs trade data for alumina feedstocks, and SEC filings from disclosed market participants. Bottom-up volume modeling across powder, refined, granular, and crude grades triangulated against top-down macroeconomic demand projections.
Input-output matrices mapped alunite flow from volcanic belt extraction through calcination processing to ceramics, agriculture, metallurgy, and chemical industry end-uses across the analysis window. Segmentation dimensions included product type purity tiers, application-specific alumina content requirements, end-user contract sophistication levels, and packaging format logistics economics. CAGRs were derived from regression analysis of historical consumption patterns against regulatory enforcement intensity and substitution elasticity with bauxite alternatives. Forecast inputs incorporated natural gas price volatility scenarios and electrification capital expenditure cycles.
Inputs from MEE licensing databases, ECHA registration filings, and METI facility surveys were available through the study window; gaps in real-time carbon intensity verification infrastructure introduce uncertainty bands around Scope 3 disclosure compliance timelines. Deviation in China's dual carbon policy enforcement velocity or Guinea-Australia bauxite low-carbon refining scale-up would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Carbamide Market
Bulk Chemicals
Zinc Gluconate Granules Market
Bulk Chemicals
Stilbene Market
Bulk Chemicals
2,4-Dichlorophenoxyacetic Market
Bulk Chemicals
Brassylic Acid Market
Bulk Chemicals
Lithium Chloride Market
Bulk Chemicals
Middle East Formaldehyde Market
Bulk Chemicals
Europe Calcium Chloride Market
Bulk Chemicals
Global Sodium Percarbonate Market
Bulk Chemicals
Propionaldehyde Market
Bulk Chemicals
Europe Lithium Chloride Market
Bulk Chemicals
Europe Castor Oil Market
Bulk Chemicals
Calcium Nitrate Market
Bulk Chemicals
Dithiocarbamates Market
Bulk Chemicals
Asia-Pacific Choline Chloride Market
Bulk Chemicals
Global Sodium Phosphate Market