
 Microplastics Particle Size and Shape Characterization Systems Market | 2026-2036
Microplastics Particle Size and Shape Characterization Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Microplastics Particle Size and Shape Characterization Systems Market Insights
Equipment leasing and pay-per-test service models are reshaping competitive access for mid-sized environmental laboratories that previously could not justify capital outlays for electron microscopy suites. Malvern Panalytical leverages its installed base of laser diffraction hardware to cross-sell integrated microplastic workflows. HORIBA anchors its position through Raman spectroscopy platforms optimized for automated polymer identification. Thermo Fisher Scientific sustains breadth across electron microscopy and mass spectrometry combinations that span research and regulatory use cases.
Microplastics particle size and shape characterization systems comprise analytical instruments that measure physical dimensions, surface morphology, and chemical identity of synthetic polymer fragments below five millimeters, typically employing light scattering, electron beam imaging, or vibrational spectroscopy to distinguish polyethylene, polystyrene, and polypropylene debris by dimensional class and spectral signature. Their primary purpose is to quantify contamination burdens and trace pollution sources across aqueous, biological, and consumer matrices. Raman spectroscopy leads in polymer-specific identification accuracy while electron microscopy dominates dimensional resolution below one micron. Environmental monitoring applications command the largest current spend though pharmaceutical quality control represents the fastest-growing demand pool as USP and EP chapters on particulate matter expand to encompass microplastic adulterants.
The US EPA has advanced standardized methods for microplastic quantification in drinking water under the Safe Drinking Water Act framework, while the EU Water Framework Directive and REACH restrictions on intentionally added microplastics compel member state laboratories to adopt validated particle characterization protocols. Japan's MEE has issued technical guidelines for marine microplastic survey methods that reference specific size fractionation thresholds. Stakeholders must monitor which analytical modalities achieve regulatory method validation status, as this designation determines instrument procurement eligibility for government contract laboratories and shapes competitive positioning across the vendor landscape.
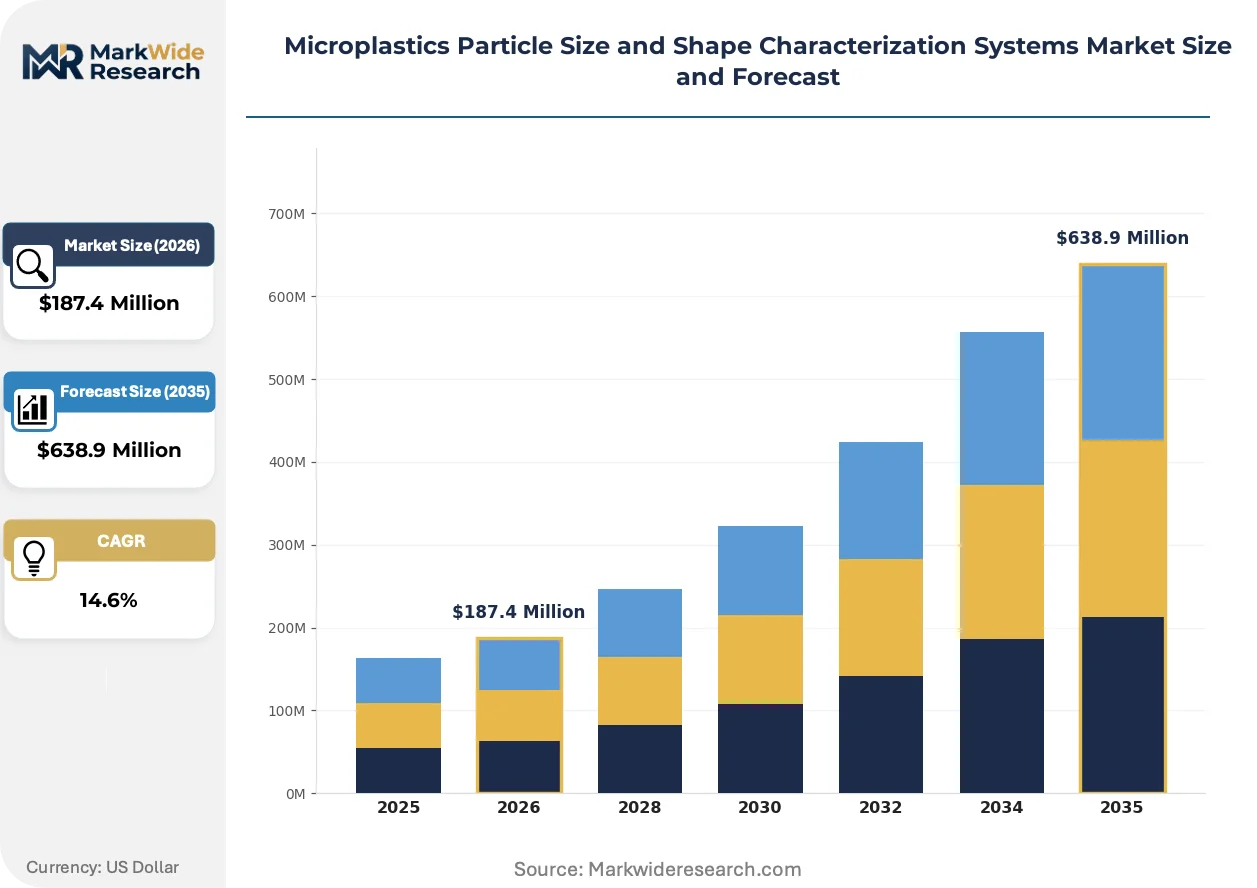
Market Dynamics
Equipment leasing models and pay-per-test service structures are compressing capital barriers for mid-sized environmental laboratories that previously could not justify electron microscopy suite investments, redistributing competitive access across the vendor landscape.
Growth Catalysts
- EU REACH restrictions on intentionally added microplastics:Member state laboratories must adopt validated particle characterization protocols, mandating procurement of Raman and electron microscopy systems for compliance testing across polymer, cosmetics, and agricultural sectors.
- Wastewater treatment infrastructure:Utilities across Japan, South Korea, and Australia face tightening discharge rules that require continuous monitoring of microplastic effluent loads, driving recurring instrument demand and service contract expansion.
- Laser diffraction hardware installed base:Existing particle size analysis platforms in pharmaceutical quality control labs enable cross-sell pathways for integrated microplastic workflows as USP and EP chapters expand to cover polymer adulterants.
Market Restraints
- Electron microscopy consumables and maintenance:Specialized sample preparation reagents, filament replacements, and vacuum system servicing create recurring cost burdens that strain operational budgets of municipal environmental laboratories.
- Raman spectroscopy reference library limitations:Incomplete spectral databases for weathered, biofouled, or additive-laden polymers reduce identification confidence for environmental samples relative to pristine polymer standards.
- Metrology standardization gaps:Absence of harmonized size fractionation thresholds between EPA, EU, and MEE protocols forces laboratories to maintain multiple analytical workflows, duplicating capital expenditure and training overhead.
Strategic Opportunities
- Pharmaceutical quality control expansion:USP and EP chapters on particulate matter are extending scope to encompass microplastic adulterants in parenteral and ophthalmic preparations, opening validated method development contracts for instrument vendors.
- Portable and field-deployable Raman systems:Convergence of miniaturized spectrometer hardware with automated polymer identification algorithms enables real-time source tracking during river basin surveys and industrial discharge inspections.
- Service model innovation:Subscription-based access to cloud-hosted spectral libraries and AI-assisted particle classification reduces upfront capital requirements for smaller environmental consultancies and academic research groups.
Industry Challenges
- Cross-disciplinary analytical expertise:Effective microplastic characterization demands simultaneous competence in polymer chemistry, electron optics, and environmental sampling protocols, creating recruitment bottlenecks for contract laboratories.
- Legacy LIMS integration complexity:Particle size and shape data formats from Raman and electron microscopy platforms often require custom middleware development to connect with established laboratory information management systems in government facilities.
- Proficiency testing and accreditation timelines:Achieving ISO/IEC 17025 recognition for microplastic methods involves extended inter-laboratory comparison studies that delay revenue generation for newly equipped testing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microplastics Particle Size and Shape Characterization Systems Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Dynamic Light Scattering, Electron Microscopy, Raman Spectroscopy, Atomic Force Microscopy, Laser Diffraction Application: Environmental Monitoring, Wastewater Analysis, Food Safety, Cosmetic Testing, Pharmaceutical Quality Control End User: Academic Research, Government Laboratories, Private Testing Labs, Environmental Agencies, Quality Assurance Units Deployment: Laboratory-Based, Onsite Testing, Portable Units, Automated Systems, Manual Instrumentation |
| Companies Covered | Agilent Technologies, Bruker, Thermo Fisher Scientific, HORIBA, Shimadzu, Oxford Instruments, Renishaw, ZEISS Group, Malvern Panalytical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microplastics Particle Size and Shape Characterization Systems Market Trends and Innovations
Analytical workflows are converging around multi-modal platforms that combine dimensional and chemical characterization, while regulatory method validation races determine instrument procurement eligibility across government contract laboratories.
Automated Raman spectroscopy platforms equipped with machine learning classification algorithms are hybridizing traditional polymer identification with real-time morphometric analysis. Wastewater utilities in Japan and Australia are deploying these integrated systems for continuous discharge monitoring. The technology is compressing the distinction between research-grade and routine regulatory instrumentation, enabling smaller laboratories to perform polymer-specific quantification previously requiring centralized facilities.
REACH restrictions on intentionally added microplastics are compelling cosmetics and detergent formulators to validate zero-content claims through third-party testing. Industrial laboratories across Germany, France, and the Netherlands are accelerating method development for particles below ten microns. Cosmetics quality control departments represent the fastest-growing procurement segment as brand owners seek defensible documentation against enforcement actions.
Service unbundling is fragmenting traditional capital-equipment sales into component offerings including instrument access, spectral library subscriptions, and certified analyst training. Environmental consultancies in the Rhine River basin are adopting pay-per-test arrangements rather than owning electron microscopy suites. Germany and the Netherlands display the most advanced service-market development, with contract research organizations now competing directly with instrument vendors for routine compliance testing revenue.
Microplastics Particle Size and Shape Characterization Systems Market Segmentation
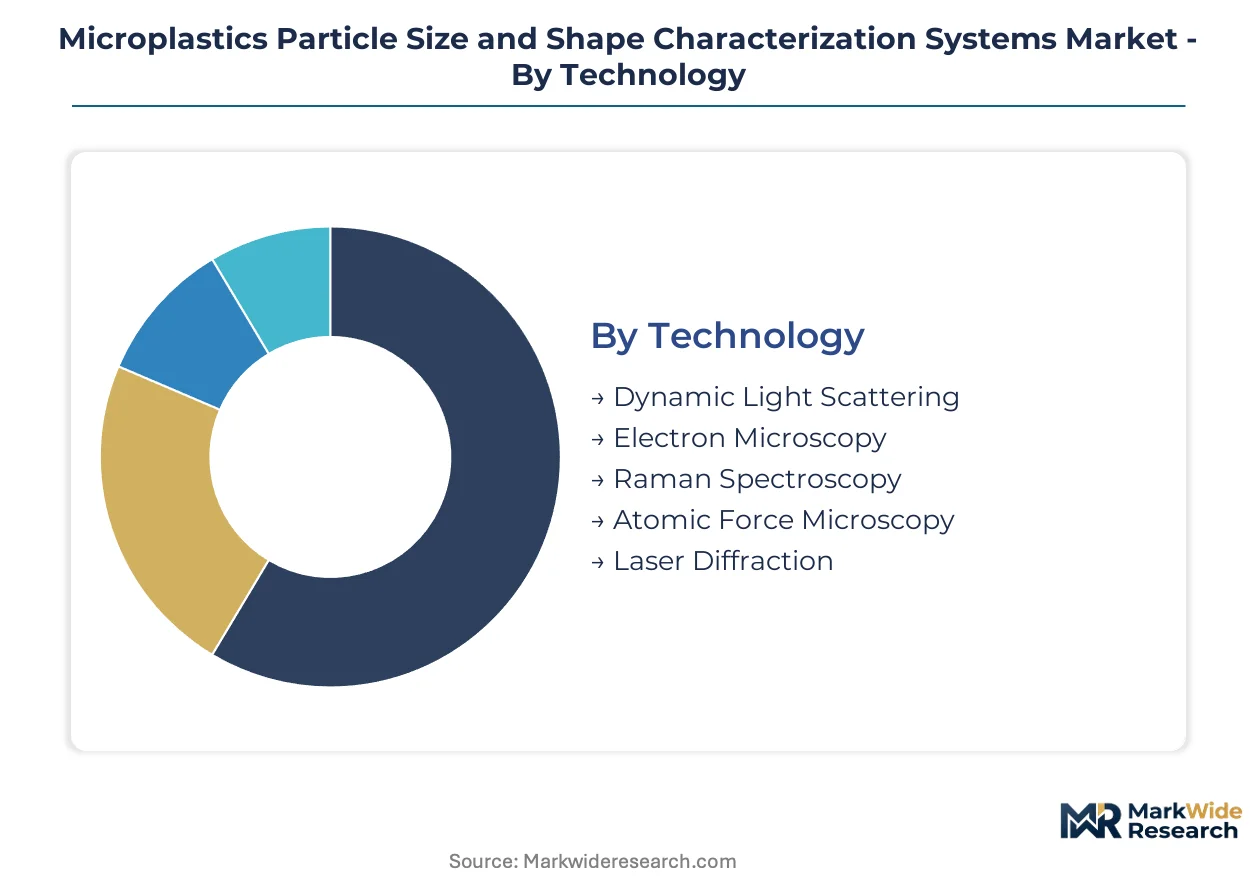
Technology modality determines capital intensity and analytical capability for microplastic characterization, while application focus shapes regulatory compliance requirements and service model preferences across end-user categories.
Technology:
Cost tier stratification separates research-grade platforms from routine compliance instrumentation, with capital outlays ranging from portable field units to multi-million-electron-volt microscopy suites.
- Raman Spectroscopy:Vibrational spectroscopy platforms equipped with automated polymer identification algorithms enable simultaneous chemical fingerprinting and morphometric classification. Demand concentrates in wastewater utilities across Japan, South Korea, and Australia where discharge monitoring mandates require polymer-specific quantification.
- Electron Microscopy:Scanning and transmission configurations deliver sub-micron dimensional resolution essential for fragment morphology documentation in regulatory submissions. Academic research institutions in Germany and the Netherlands anchor procurement for method development studies under EU Water Framework Directive protocols.
- Laser Diffraction:Established particle size distribution hardware in pharmaceutical quality control laboratories enables cross-sell pathways for integrated microplastic workflows.
- Dynamic Light Scattering:Brownian motion-based sizing suits aqueous suspension analysis for environmental sample screening.
- Atomic Force Microscopy:Three-dimensional surface topology mapping supports nanoplastic research applications requiring angstrom-scale height resolution.
Raman spectroscopy commands the established base. The steepest expansion runs through electron microscopy as sub-micron regulatory thresholds proliferate.
Application:
Regulatory scope variation across jurisdictions creates divergent instrumentation requirements, with some sectors demanding continuous monitoring while others prioritize batch validation.
- Environmental Monitoring:River basin surveys and marine ecosystem assessments require field-deployable platforms with automated size fractionation. Germany's Rhine River basin compliance programs under EU Water Framework Directive specifications drive recurring instrument demand.
- Pharmaceutical Quality Control:USP and EP chapter expansions on particulate matter now encompass microplastic adulterants in parenteral preparations. Quality assurance units in injectables manufacturing face new validation requirements for polymer contamination detection.
- Wastewater Analysis:Treatment plant effluent monitoring for microplastic load quantification supports discharge permit compliance.
- Cosmetic Testing:REACH restrictions on intentionally added microplastics compel zero-content claim validation through third-party analysis.
- Food Safety:Packaging migration studies and beverage contamination screening apply particle characterization for consumer protection.
Environmental monitoring retains the largest installed base. Pharmaceutical quality control is climbing the fastest as compendial standards expand.
End User:
Customer type determines procurement modality preferences, from capital acquisition in government facilities to service contracts and leasing arrangements in commercial laboratories.
- Government Laboratories:National reference laboratories require validated methods for enforcement support and inter-laboratory comparison studies. EPA contract labs in the United States and EU member state facilities prioritize instrumentation achieving regulatory method designation status.
- Private Testing Labs:Commercial service providers adopt pay-per-test arrangements and equipment leasing to compress capital barriers. Mid-sized environmental consultancies in the Rhine River basin increasingly access electron microscopy through service contracts rather than ownership.
- Academic Research:University laboratories focus on method development and spectral library expansion for weathered polymer identification.
- Environmental Agencies:Field inspection units require portable systems for industrial discharge verification and source tracking.
- Quality Assurance Units:In-house pharmaceutical and cosmetics manufacturing labs perform batch release testing for microplastic contamination.
Government laboratories anchor procurement volume. Private testing labs are gaining share fastest through service model innovation.
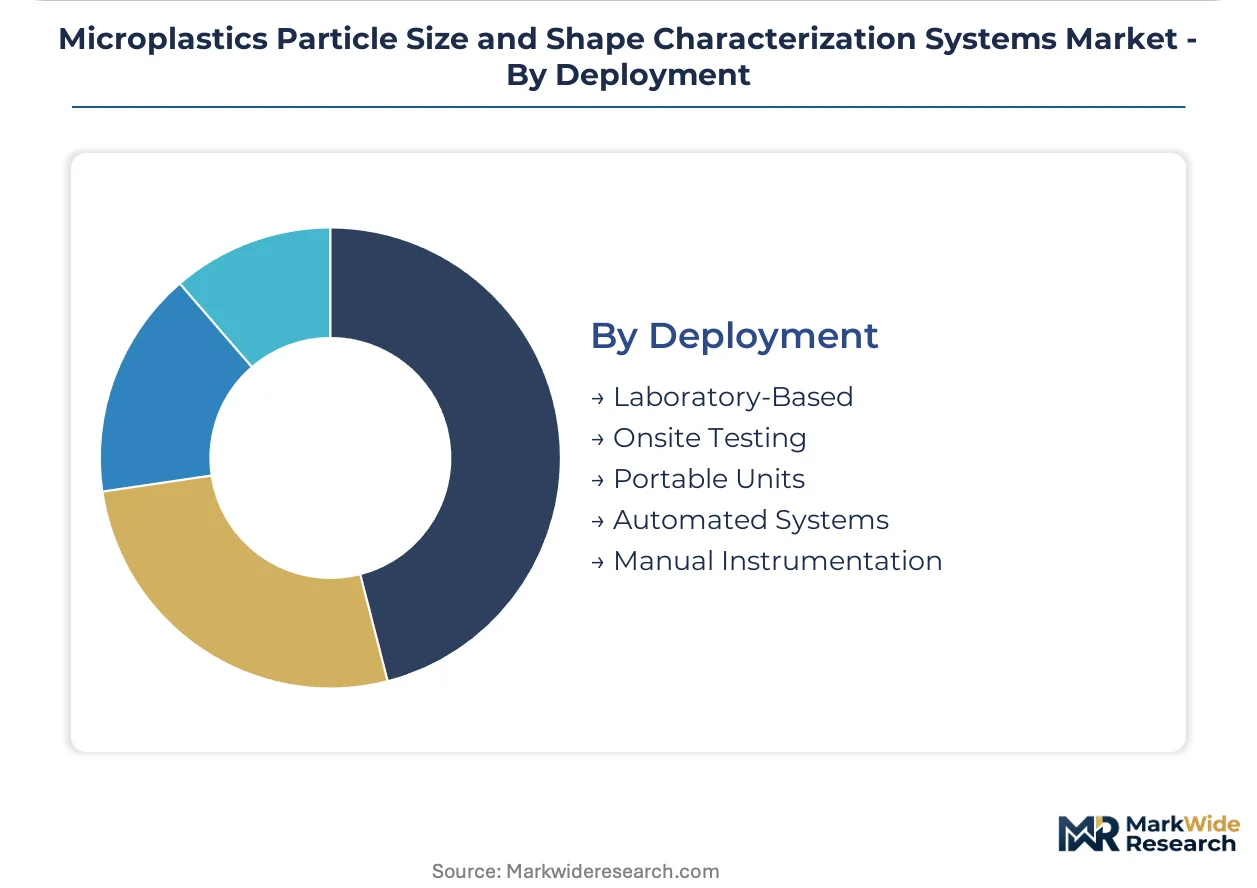
Deployment:
Supply concentration in automated platform manufacturing contrasts with distributed demand for portable and manual configurations across field inspection applications.
- Laboratory-Based:Fixed installations with climate-controlled environments and specialized sample preparation infrastructure support high-throughput regulatory testing. Centralized facilities in Germany, France, and the Netherlands process Rhine River basin compliance samples under standardized protocols.
- Automated Systems:Robotic sample handling and AI-assisted particle classification reduce analyst time per sample for routine monitoring applications.
- Portable Units:Miniaturized Raman spectrometers enable real-time polymer identification during river basin surveys and industrial inspections.
- Onsite Testing:Containerized laboratories deploy to wastewater treatment facilities for continuous discharge monitoring.
- Manual Instrumentation:Operator-dependent platforms suit research applications requiring customized analytical protocols.
Laboratory-based systems dominate current installations. Automated systems show the steepest expansion trajectory as labor cost pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in analytical instrumentation tilt toward net-importing jurisdictions with stringent environmental enforcement. Germany, Japan, and the United States absorb the highest per-capita instrument density, while South Korea and Australia emerge as fastest-growing procurement markets for discharge monitoring systems.
Germany
Rhine River basin compliance programs under the EU Water Framework Directive drive recurring demand for validated particle characterization protocols. ECHA enforcement of REACH restrictions on intentionally added microplastics compels cosmetics and detergent laboratories to adopt Raman and electron microscopy systems. Industrial clusters in North Rhine-Westphalia and Baden-Württemberg host the densest concentration of contract research organizations offering third-party zero-content validation.
Japan
MEE technical guidelines for marine microplastic survey methods establish specific size fractionation thresholds that shape instrument procurement specifications. Wastewater utilities in Tokyo Bay and Osaka Bay watersheds deploy continuous monitoring systems for effluent microplastic load quantification. The Kanto and Kansai regions concentrate pharmaceutical quality control laboratories adapting to expanded USP and EP chapters on particulate matter.
United States
EPA standardized methods for microplastic quantification in drinking water under the Safe Drinking Water Act framework determine instrument eligibility for government contract laboratories. California and Massachusetts environmental agencies pilot field-deployable Raman systems for industrial discharge inspections. The Boston-Cambridge corridor anchors academic method development for sub-micron regulatory thresholds.
South Korea
Tightening wastewater discharge rules from the national environmental ministry drive utility investment in automated polymer identification platforms. Busan-Ulsan industrial complexes require continuous effluent monitoring for microplastic contamination. Seoul Capital Area quality control laboratories serve cosmetics exporters seeking REACH-compliant documentation for European market access.
Australia
Marine ecosystem protection mandates from the national environmental regulator accelerate procurement of portable spectroscopy systems for coastal survey programs. Sydney and Melbourne wastewater treatment facilities implement service-contract models for microplastic load monitoring. The Great Barrier Reef Marine Park Authority deploys field instrumentation for source tracking during river basin assessments.
Microplastics Particle Size and Shape Characterization Systems Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying lasers, detectors, and spectral libraries. The vendor landscape stratifies between diversified analytical instrumentation conglomerates and focused spectroscopy houses. Three archetypes dominate: full-workflow providers bundling hardware with method validation support, modular platform vendors enabling customer-configured combinations, and service-layer specialists offering cloud-hosted analysis without capital ownership. Consolidation pressures intensify as regulatory method validation status becomes the primary procurement filter for government laboratories.
Among diversified analytical instrumentation conglomerates, Thermo Fisher Scientific, HORIBA, and Agilent Technologies occupy positions spanning electron microscopy, Raman spectroscopy, and mass spectrometry combinations. These entities exemplify the full-workflow archetype through cross-technology portfolios that address both research and regulatory use cases. Bruker and Shimadzu represent the modular platform approach, with established installed bases in adjacent particle characterization markets enabling cross-sell pathways into microplastic-specific workflows. Malvern Panalytical and ZEISS Group anchor the dimensional resolution segment, leveraging legacy laser diffraction and electron optics expertise respectively.
| Leading Market Players |
|---|
| Agilent Technologies |
| Bruker |
| Thermo Fisher Scientific |
| HORIBA |
| Shimadzu |
| Oxford Instruments |
| Renishaw |
| ZEISS Group |
| Malvern Panalytical |
| Others |
Pricing and Supply Chain Analysis
The Rotterdam-Antwerp freight corridor's volatile container rates compress margins for German electron microscopy suite manufacturers while amplifying price differentiation between premium Raman spectroscopy platforms and economy-tier laser diffraction systems. Supply concentration in Japanese detector fabrication and German precision optics feeds downstream pricing power asymmetries across environmental monitoring and pharmaceutical quality control buyer segments.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in this market. Price differentiation rests on certification grade—ISO/IEC 17025 validated platforms command substantial premiums over research-grade configurations—and vertical integration depth in spectral library development. Cost compression in economy-tier laser diffraction hardware is intensifying because Chinese component suppliers are scaling detector manufacturing capacity. Municipal environmental laboratories exhibit the highest price sensitivity due to fixed public procurement budgets, while multinational pharmaceutical quality control units demonstrate the least sensitivity given compliance-driven replacement cycles.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now standard among Japanese spectrometer component suppliers are straining working capital for mid-sized European system integrators. Manufacturing concentration in Germany, Japan, and the United States feeds from specialized inputs including single-mode laser diodes, electron beam filament assemblies, and cryogenically cooled CCD detectors. Single-source vulnerability in diffractive optical element fabrication from a concentrated German supplier base creates systemic exposure. Distribution runs through authorized technical distributors with certified service capabilities rather than direct OEM sales for sub-million-dollar instrument tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market occupies early-cycle expansion territory as regulatory method validation races across EPA, ECHA, and MEE jurisdictions accelerate instrument procurement eligibility thresholds faster than vendor certification capacity can match.
For Market Incumbents: Build regulatory method validation moats by securing EPA contract laboratory designation status and ECHA reference laboratory recognition before emerging spectroscopy entrants achieve comparable certification breadth. Consolidate position through backward integration into AI-assisted particle classification algorithm development, countering the threat of cloud-native analysis startups unbundling hardware from software. Expand service contract penetration in Japan's wastewater utility sector where discharge monitoring mandates create recurring revenue stickiness. For New Entrants and Emerging Players: Mid-sized environmental consultancies in Australia's coastal survey programs represent the most penetrable entry point, as these buyers prioritize portable Raman field units over capital-intensive electron microscopy ownership. Private testing laboratories in South Korea's Busan-Ulsan industrial corridor offer secondary white-space given tightening national discharge rules and limited incumbent service coverage. A subscription-based spectral library access model with certified analyst training bundles enables go-to-market traction without requiring full instrument platform development. For Investors and Strategic Acquirers: Specialist AI-assisted polymer identification software developers with validated spectral libraries for weathered and biofouled samples present the most compelling acquisition target archetype given persistent identification confidence gaps in environmental sample analysis. Long-term viability hinges on regulatory method validation status becoming the primary procurement filter across government contract laboratories. Watch for ECHA enforcement action intensity against REACH non-compliance in cosmetics and detergents as the decisive inflection signal for third-party testing service demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Method Validation Investment | EPA and ECHA designation status determines government contract laboratory procurement eligibility and competitive positioning. |
| AI-Assisted Spectral Library Expansion | Machine learning classification algorithms for weathered polymer identification address persistent Raman reference database limitations. |
| Service Model Unbundling | Pay-per-test arrangements and equipment leasing compress capital barriers for mid-sized environmental consultancies. |
| Portable Field System Development | Miniaturized Raman platforms enable real-time polymer identification during river basin surveys and industrial discharge inspections. |
| Pharmaceutical QC Method Development | USP and EP chapter expansions on particulate matter create validated workflow demand for parenteral preparation contamination detection. |
Research Methodology
Initial hypotheses were tested against primary input from instrument vendor product managers, environmental laboratory directors, regulatory affairs specialists at wastewater utilities, and pharmaceutical quality control executives, then refined through secondary validation. Primary engagement combined structured interviews with technical specification discussions and procurement process mapping. Secondary sources encompassed EPA method development documentation, ECHA restriction dossiers, MEE technical guideline publications, and inter-laboratory comparison study archives. Bottom-up instrument shipment tracking and top-down regulatory compliance spending estimates were triangulated to anchor market sizing.
Demand-supply-balance framing shaped the analytical framework across the analysis window, with segmentation dimensions spanning technology modality, application focus, end-user category, and deployment configuration. Modeled variables included regulatory method validation status achievement rates, service contract renewal frequencies, and cross-technology platform adoption patterns. CAGRs were derived from instrument procurement pipeline analysis and compliance mandate implementation timelines. Industry-specific forecast inputs incorporated EU Water Framework Directive enforcement schedules and USP chapter revision publication cycles.
Macroeconomic conditions sit as an overlay; deviation in public infrastructure spending cycles and research grant allocation patterns would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and method standardization harmonization progress. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
High-Temperature Corrosion and Creep Testing Equipment for Process Industries Market
Testing Equipment
Hydrogen Gas Analyzers Market
Testing Equipment
Water Analysis Instruments Market
Testing Equipment
FTIR Fuel Analyzer Market
Testing Equipment
2D Chromatography Market
Testing Equipment
Cone Calorimeter Market
Testing Equipment
Chemical Warfare Agent Detectors Market
Testing Equipment
Carbon Black Content Tester Market
Testing Equipment
Magnesium Testing Reagents Market
Testing Equipment
Global Online Coal Ash Analyzers Market
Testing Equipment
Chemisorption Analyzer Market
Testing Equipment
Global Insulation Testers Market
Testing Equipment
Chemical Reaction Monitoring Equipment Market
Testing Equipment
Supercritical Fluid Chromatography (SFC) System Market
Testing Equipment
Material Tester Market
Testing Equipment
Gold Purity Tester Market