
 North America Malic Acid Market | 2026-2036
North America Malic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
North America Malic Acid Market Insights
FDA enforcement of 21 CFR food additive standards is pivoting the cost-of-entry calculus for new malic acid suppliers. Bartek Ingredients leverages backward integration into apple-derived feedstock to sustain margin control across Canadian and U.S. pharmaceutical accounts. Fuso Chemical anchors its North American position through fermentation-based production scale, while Polynt competes on petrochemical-synthetic cost structures in industrial applications.
Malic acid is a dicarboxylic acid with the molecular formula C₄H₆O₅, existing as L-malic acid in natural sources and as DL-malic acid in synthetic production, primarily functioning as an acidulant, flavor enhancer, and pH buffer across food, pharmaceutical, and chemical industries. Food Grade material dominates volume throughput given its integration into beverage acidulation and confectionery tartness systems, while Pharmaceutical Grade commands premium positioning due to USP certification burdens and excipient purity thresholds. The Beverages application channel shows the steepest trajectory as carbonated and functional drink formulators replace citric acid with malic acid for smoother sour perception and extended flavor stability.
The FDA, EPA, and USDA collectively govern malic acid through food safety, environmental discharge, and agricultural input pathways, with FDA 21 CFR 184.1069 directly prescribing identity and purity specifications for food-grade material. Health Canada and PMRA maintain parallel but non-identical additive approval lists that create cross-border formulation complexity for multinational food manufacturers. Stakeholders must monitor emerging PFAS contamination scrutiny in chemical processing wastewater, as EPA enforcement expansion could reshape synthetic production economics faster than fermentation alternatives can scale.
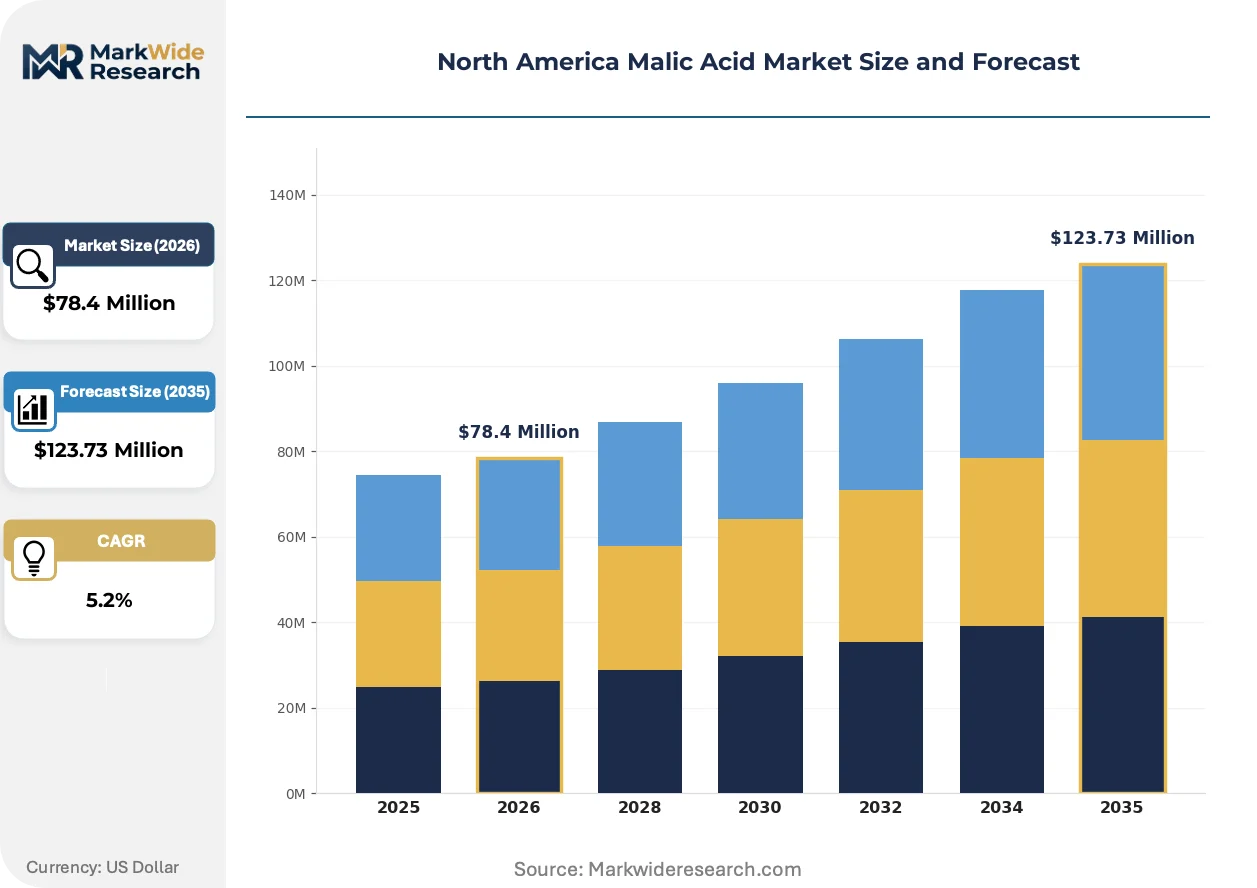
Market Dynamics
FDA 21 CFR 184.1069 enforcement is tightening purity thresholds for malic acid suppliers, forcing fermentation-based producers to recalibrate quality systems while petrochemical-synthetic routes face heightened scrutiny over residual contaminants.
Growth Catalysts
- Clean-label beverage mandates:U.S. and Canadian formulators are substituting citric acid with malic acid for smoother tartness profiles in carbonated and functional drinks, accelerating procurement volumes across the Great Lakes manufacturing corridor.
- 21 CFR 184.1069 compliance pathways:FDA's codified identity specifications create definable qualification standards that favor suppliers with established pharmaceutical-grade certification, streamlining vendor selection for multinational food manufacturers.
- Fermentation technology maturation:Biological production methods utilizing renewable carbohydrate feedstocks are achieving cost parity with synthetic routes, expanding viable supply capacity without petrochemical price exposure.
Market Restraints
- Apple-derived feedstock volatility:Natural L-malic acid production depends on crop yields concentrated in Washington State and Ontario, exposing margin structures to climate-driven supply interruptions.
- Cross-border formulation complexity:Health Canada's Food and Drug Regulations and PMRA additive lists diverge from FDA classifications, forcing dual-compliance testing for products distributed across the U.S.-Canada border.
- Citric acid price competition:Established citric acid suppliers leverage decades of fermentation scale and distribution density, maintaining cost advantages in commodity acidulant procurement decisions.
Strategic Opportunities
- Mexico food processing expansion:Underpenetrated beverage and confectionery manufacturing clusters in Guanajuato and Jalisco present first-mover positioning for malic acid suppliers establishing regional distribution nodes.
- Pharmaceutical excipient certification:USP-grade malic acid for tablet disintegration and pH buffering commands premium positioning as generic drug manufacturers seek qualified secondary suppliers beyond incumbent relationships.
- EPA PFAS discharge scrutiny:Emerging enforcement against synthetic production wastewater creates competitive opening for fermentation-based producers with cleaner effluent profiles and lower remediation capital requirements.
Industry Challenges
- USP certification timeline compression:Pharmaceutical-grade qualification requires 18-24 month validation cycles that strain working capital for mid-scale suppliers targeting dual food-pharma positioning.
- Legacy ERP integration with batch traceability:FDA food safety modernization mandates for electronic record-keeping force costly system overhauls at established plants operating on decades-old manufacturing execution platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Malic Acid Market |
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $123.73 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Cosmetic Grade Application: Beverages, Confectionery, Bakery, Pharmaceuticals End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Firms, Chemical Producers Distribution Channel: Online Sales, Specialty Stores, Wholesale, Direct Sales |
| Companies Covered | The Chemical Company, Fuso Chemical, Bartek Ingredients, Yongsan Chemicals, Isegen South Africa, Prinova Group, Miles Chemical, Spectrum Chemical, Polynt, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Malic Acid Market Trends and Innovations
Biological production pathways and regulatory disclosure requirements are restructuring competitive advantage in malic acid supply, with fermentation scale and clean-label positioning overtaking petrochemical cost engineering as primary differentiators.
Fermentation-derived L-malic acid is expanding into pharmaceutical excipient and premium food-grade applications previously dominated by synthetic DL-malic acid. Contract manufacturers serving U.S. generic drug producers are accelerating qualification timelines for biologically sourced material. This technology is expanding into high-purity segments where residual solvent concerns and chiral specificity requirements previously favored petrochemical routes.
EPA expansion of PFAS enforcement under the Clean Water Act is elevating wastewater compliance burdens for synthetic malic acid facilities in Texas and Louisiana. Industrial discharge permits now require expanded analytical testing for fluorinated compounds used in process equipment. Petrochemical-based producers in the U.S. Gulf Coast corridor are most affected, with several facilities evaluating biological process retrofits to preempt regulatory action.
Beverage formulators are consolidating acidulant procurement around dual-certified suppliers capable of serving both food and pharmaceutical accounts. Large CPG manufacturers in the U.S. Midwest are reducing vendor counts from six to three qualified sources, prioritizing suppliers with integrated fermentation capacity and documented supply chain transparency. This concentration pattern is most visible among carbonated and functional drink producers in Michigan and Ohio seeking simplified audit and qualification overhead.
North America Malic Acid Market Segmentation
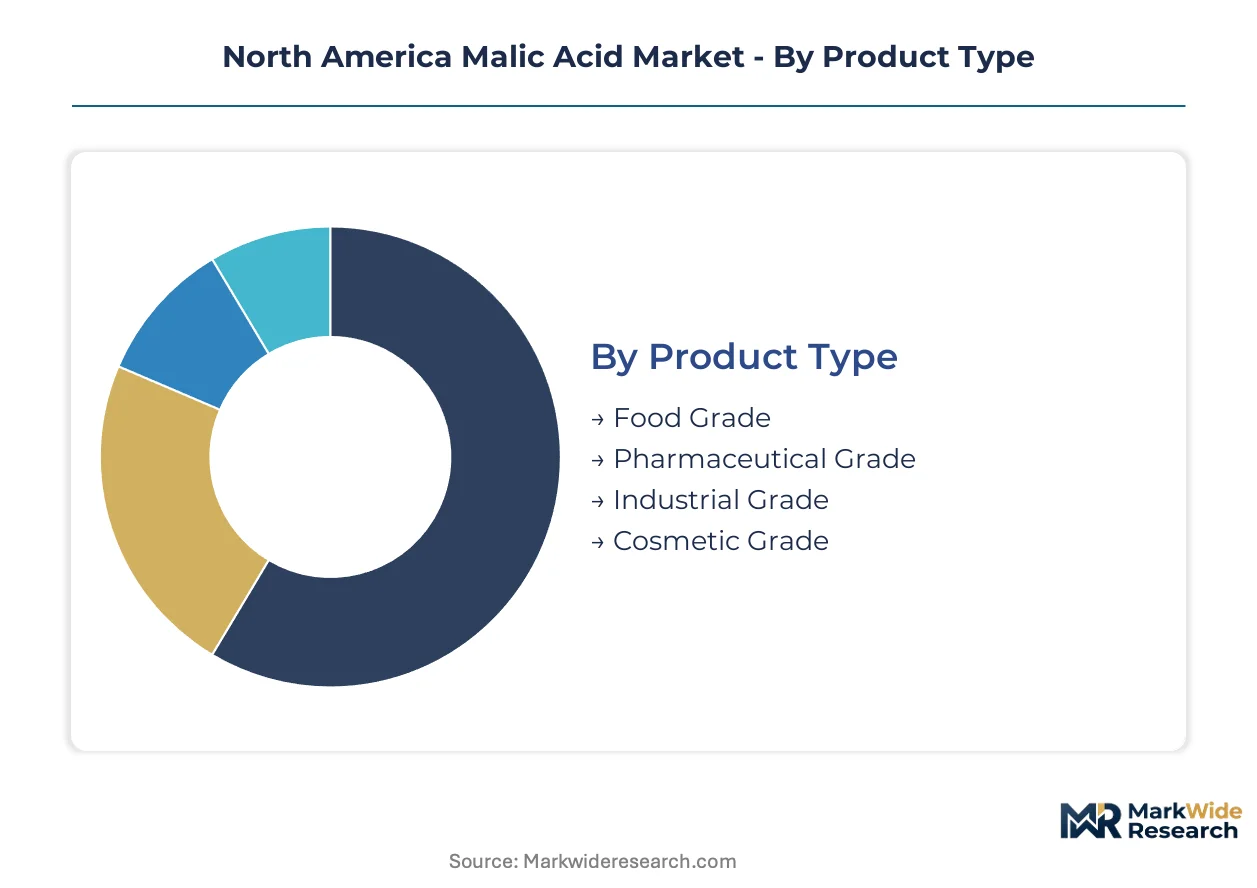
Malic acid segmentation reflects divergent purity thresholds and regulatory pathways across North American supply chains. Product grade distinctions determine FDA compliance burden, while application channels concentrate demand in distinct manufacturing corridors.
Product Type:
Specification tiers separate food-safe material from excipient-grade and industrial variants through identity testing protocols.
- Food Grade:Meets FDA 21 CFR 184.1069 identity specifications for acidulant and flavor enhancement functions. Beverage formulators across Michigan and Ohio procurement corridors specify this grade for clean-label carbonated drinks seeking smoother tartness profiles than citric acid alternatives.
- Pharmaceutical Grade:Satisfies USP-NF monograph requirements for tablet disintegration and pH buffering excipients. Generic drug manufacturers in New Jersey and Puerto Rico drive qualification demand for this grade given its 18-24 month certification cycles and premium positioning.
- Industrial Grade:Serves metal finishing and chemical synthesis applications with reduced purity thresholds.
- Cosmetic Grade:Addresses pH adjustment needs in personal care formulations with intermediate purity requirements.
Food Grade leads on scale; Pharmaceutical Grade leads on momentum.
Application:
End-use channels concentrate procurement in distinct regional manufacturing clusters with specialized formulation requirements.
- Beverages:Carbonated and functional drink producers in the Great Lakes corridor specify malic acid for extended flavor stability and reduced metallic aftertaste versus citric acid. Clean-label mandates from major CPG manufacturers accelerate volume procurement.
- Pharmaceuticals:Tablet and capsule formulators utilize malic acid for controlled-release matrix systems and excipient compatibility. USP certification requirements create vendor consolidation toward dual-food-pharma qualified suppliers.
- Confectionery:Hard candy and sour gummy manufacturers deploy malic acid for intense, rapid tartness onset.
- Bakery:Leavening acid and preservative functions in packaged baked goods applications.
Beverages commands volume concentration; Pharmaceuticals delivers margin expansion.
End User:
Customer archetypes determine procurement scale, certification burden, and supply chain transparency requirements.
- Food Manufacturers:Multinational CPG producers with integrated beverage and confectionery operations consolidate vendor counts from six to three qualified sources. Audit simplification and batch traceability drive supplier selection beyond unit economics.
- Pharmaceutical Firms:Generic drug producers and contract manufacturers prioritize USP-grade material with documented excipient master files. Secondary supplier qualification timelines compress as incumbent relationships face capacity constraints.
- Cosmetic Companies:Personal care formulators with regional manufacturing in California and Texas.
- Chemical Producers:Industrial derivative and specialty chemical synthesis operations.
Food Manufacturers anchor procurement volume; Pharmaceutical Firms drive specification intensity.
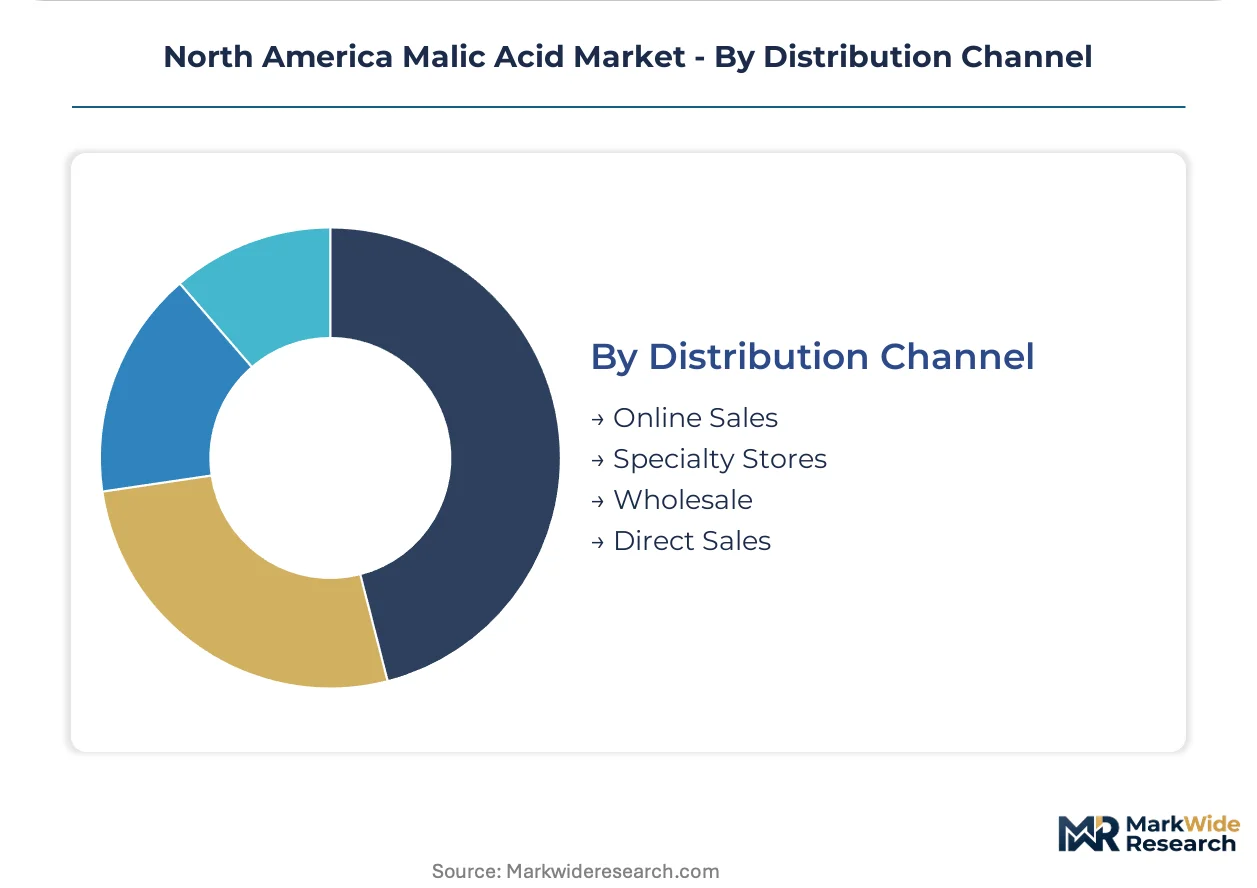
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and geographic proximity to manufacturing clusters.
- Direct Sales:Large-volume beverage and pharmaceutical accounts negotiate long-term supply agreements with fermentation-based producers. Integrated quality systems and dedicated technical support justify premium positioning over intermediary channels.
- Wholesale:Regional distributors serve mid-tier food manufacturers and industrial compounders with consolidated chemical procurement. Inventory pooling reduces working capital requirements for buyers without direct supplier qualification resources.
- Online Sales:Small-batch cosmetic and specialty food producers with spot purchase requirements.
- Specialty Stores:Artisanal and craft formulators seeking packaged quantities with immediate availability.
Direct Sales captures contract value; Wholesale extends geographic reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized fermentation technicians and chemical process engineers concentrate in the Great Lakes industrial corridor, anchoring North American malic acid production capacity and technical service capabilities for food and pharmaceutical accounts.
United States
Beverage formulators in Michigan and Ohio specify malic acid for clean-label carbonated drinks seeking smoother tartness profiles than citric acid alternatives. FDA 21 CFR 184.1069 enforcement tightens purity thresholds, forcing suppliers to recalibrate quality systems for food-grade certification. The Great Lakes manufacturing corridor anchors regional consumption, with pharmaceutical-grade demand concentrated in New Jersey and Puerto Rico generic drug facilities.
Canada
Apple-derived L-malic acid production depends on crop yields concentrated in Ontario, exposing natural production to climate-driven supply interruptions. Health Canada and PMRA maintain additive approval lists that diverge from FDA classifications, creating cross-border formulation complexity for multinational food manufacturers. Toronto and Montreal serve as distribution nodes for fermentation-based material serving both domestic beverage producers and U.S. border-state accounts.
Mexico
Underpenetrated beverage and confectionery manufacturing clusters in Guanajuato and Jalisco present first-mover positioning for suppliers establishing regional distribution nodes. Mexican food safety regulators align with CODEX standards while maintaining distinct additive registration requirements that complicate direct importation. Mexico City Metro anchors logistics coordination for malic acid moving into Central American processing corridors.
North America Malic Acid Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three discernible tiers. The vendor base organizes around fermentation-scale leaders, petrochemical-synthetic cost optimizers, and regional distribution intermediaries. Strategic archetypes include backward-integrated feedstock controllers, multi-acidulant portfolio diversifiers, and pharmaceutical-grade certification specialists. Competitive moves concentrate on capacity expansion in fermentation assets and geographic expansion into underpenetrated Mexican processing clusters.
Among Asia-Pacific-based chemical specialists, Fuso Chemical occupies a position exemplifying fermentation-scale leadership, while Yongsan Chemicals represents the synthetic production archetype. Bartek Ingredients anchors the North American specialist tier with Canadian operational roots. These three companies illustrate the competitive tension between biological and petrochemical production philosophies that defines supplier selection criteria for multinational food and pharmaceutical manufacturers.
| Leading Market Players |
|---|
| The Chemical Company |
| Fuso Chemical |
| Bartek Ingredients |
| Yongsan Chemicals |
| Isegen South Africa |
| Prinova Group |
| Miles Chemical |
| Spectrum Chemical |
| Polynt |
| Others |
Pricing and Supply Chain Analysis
EPA PFAS discharge enforcement under the Clean Water Act gates qualified supply for fermentation-based producers while reserving premium-tier pricing access for suppliers with documented wastewater compliance and USP-grade certification pathways.
Pricing Analysis
Bundled technical service and certification support commands premium positioning over unbundled commodity transactions. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade levels reflects USP certification burden, FDA compliance documentation, and volume scale. Cost compression in synthetic production corridors is intensifying because petrochemical feedstock volatility and wastewater remediation capital requirements erode margin structures. Generic drug manufacturers exhibit lowest price sensitivity given 18-24 month qualification timelines and excipient master file dependencies, while mid-tier food manufacturers drive hardest unit economics negotiations.
Supply Chain Analysis
Freight cost differentials between Great Lakes manufacturing clusters and Gulf Coast petrochemical corridors reshape procurement geography for beverage formulators. Supply concentrates in the United States, Canada, and Mexico, with Ontario apple-derived feedstock and Texas synthetic production anchoring dual sourcing pathways. Raw material dependencies center on carbohydrate feedstocks for fermentation, petrochemical derivatives for synthetic routes, and specialized enzyme preparations for biological conversion. Single-source vulnerability runs through Washington State and Ontario crop yields for natural L-malic acid. Distribution runs through direct sales agreements for pharmaceutical accounts and wholesale channels for regional food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
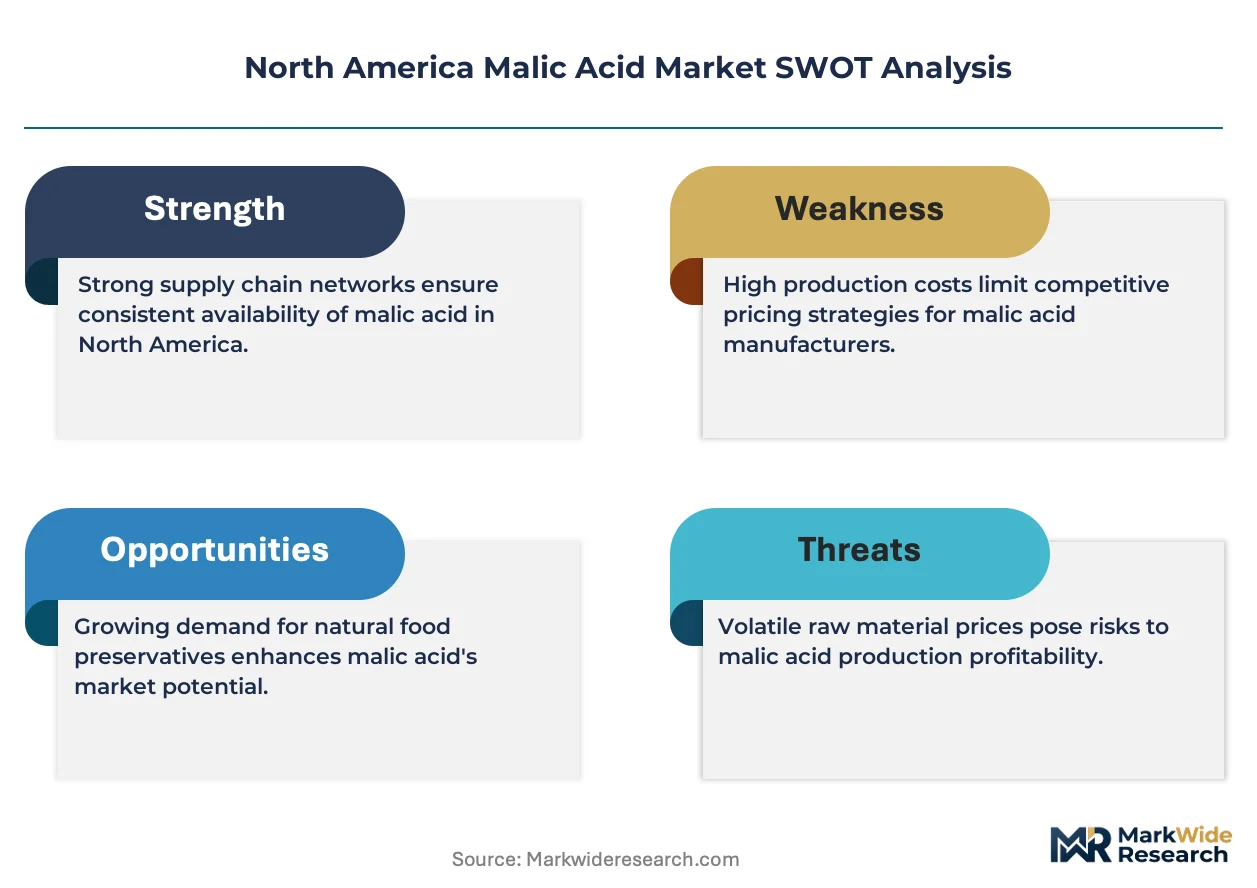
This market operates as a regulatory compounder where FDA 21 CFR 184.1069 enforcement tightens purity thresholds and extends qualification timelines, directly expanding demand for certified suppliers capable of spanning food and pharmaceutical grade specifications.
For Market Incumbents: Anchor defensive positioning through backward integration into apple-derived feedstock in Ontario and fermentation capacity expansion in the Great Lakes corridor. Citric acid substitution momentum and emerging PFAS scrutiny threaten synthetic route viability; incumbents should prioritize USP certification maintenance and electronic batch traceability system upgrades to sustain vendor consolidation benefits among multinational CPG manufacturers. For New Entrants and Emerging Players: Enter via underpenetrated beverage processing clusters in Guanajuato and Jalisco, Mexico, where CODEX-aligned regulators and limited qualified supply create first-mover positioning. Pharmaceutical excipient qualification for generic drug manufacturers in Puerto Rico offers the most penetrable premium segment; new entrants should lead with fermentation-based production credentials and documented supply chain transparency to differentiate from petrochemical incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale fermentation specialists with dual food-pharma certification capabilities and captive carbohydrate feedstock arrangements. Long-term viability over a 5-10 year horizon favors biological production routes as EPA enforcement expands; acquisition targets should demonstrate clean effluent profiles and established pharmaceutical customer relationships. The signal to watch is EPA PFAS discharge permit expansion affecting synthetic production economics in Texas and Louisiana.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Ontario apple orchard partnerships secure natural L-malic acid supply against climate volatility. |
| USP Certification Investment | 18-24 month qualification cycles create vendor stickiness among New Jersey generic drug producers. |
| Fermentation Capacity Expansion | Great Lakes biological production assets achieve cost parity with synthetic Gulf Coast routes. |
| Regional Distribution Node Establishment | Guanajuato and Jalisco nodes capture Mexican beverage manufacturing growth ahead of incumbent positioning. |
| Electronic Traceability System Upgrade | FDA food safety modernization mandates force legacy ERP replacement at decades-old production facilities. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market informing demand calibration and supply mapping. The approach combines structured interviews with fermentation plant managers, procurement leads at beverage and pharmaceutical manufacturers, distribution channel partners, and technical R&D directors with secondary validation through FDA 21 CFR filings, EPA discharge permit databases, Health Canada additive approval lists, and SEC financial disclosures. Bottom-up volume builds from individual facility capacities and customer procurement patterns triangulate against top-down market sizing from trade flow analysis and industry association data.
Granularity-level modeling operates at product grade tier, end-use application channel, and regional manufacturing cluster dimensions across the projection horizon. Analytical framework derives CAGRs from segment-specific volume trajectories weighted by price-tier mix shifts, with pharmaceutical-grade momentum and beverage substitution elasticity as primary industry-specific forecast inputs. Cross-sectional validation against customs trade data and production capacity announcements ensures consistency.
The model holds under continued FDA enforcement of 21 CFR 184.1069 specifications and stable carbohydrate feedstock pricing; deviation in EPA PFAS regulatory expansion timing or Washington State apple crop yields would shift supply availability and grade-level pricing spreads. Forecasts reflect documented assumptions about qualification timeline compression and vendor consolidation patterns. Stakeholders should weight assumptions against their own operating context and regulatory compliance burden.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Ethylene and Propylene Market
Bulk Chemicals
Cresylic Acid Market
Bulk Chemicals
Green Petroleum Coke and Calcined Petroleum Coke Market
Bulk Chemicals
Asia-Pacific Solid Sulfur Market
Bulk Chemicals
Middle East Formaldehyde Market
Bulk Chemicals
Calcined Petcoke Market
Bulk Chemicals
Cyclamate Market
Bulk Chemicals
Acrylamide Market
Bulk Chemicals
North America Titanium Dioxide Market
Bulk Chemicals
Aluminum Sulfate Market
Bulk Chemicals
Magnesium Lactate Market
Bulk Chemicals
Sodium Selenite Market
Bulk Chemicals
Global GABA Market
Bulk Chemicals
North America Polyvinyl Chloride (PVC) Market
Bulk Chemicals
Potassium Fluoborate Market
Bulk Chemicals
Commodity Plastics Market