
 Rubidium Bromide Market | 2026-2036
Rubidium Bromide Market Size, Share, and Industry Trends Forecast 2026-2036
Rubidium Bromide Market Analytics
ISO 17025 accreditation is collapsing as the baseline qualification for suppliers bidding into pharmaceutical and electronics contract streams. American Elements leverages vertical integration from elemental rubidium through bromide salt finishing to secure qualification with prime contractors. Merck KGaA anchors European supply through its established analytical-grade distribution network. Sigma-Aldrich competes on catalog breadth and same-day fulfillment density in North American research corridors.
Rubidium bromide is an ionic salt compound of rubidium and bromine, typically synthesized through direct elemental combination or aqueous precipitation, with purity grades distinguished by trace metal content below 10 ppm for spectroscopic and semiconductor applications. High Purity grades command premium positioning due to stringent tolerances in optoelectronic device fabrication, while Reagent Grade sustains volume leadership across academic and government research laboratories. The Electronics Industry end-user segment concentrates margin pools where material qualification cycles extend eighteen to thirty-six months and switching costs protect incumbent positions.
EPA hazardous substance reporting thresholds and REACH SVHC candidate list reviews govern rubidium bromide import, handling, and end-use disclosure obligations in the United States and European Union respectively. Japan's METI chemical substance control framework imposes additional pre-market notification requirements on importers serving domestic electronics manufacturers. Stakeholders must monitor regulatory alignment between diverging jurisdictional chemical inventories as qualification mismatches threaten cross-border supply continuity.
Market Dynamics
Qualification-driven procurement is compressing the supplier base for rubidium bromide as electronics manufacturers extend material certification cycles and research institutions tighten purity specifications. This structural force favors vertically integrated chemical processors over trading intermediaries.
Growth Catalysts
- Electronics qualification cycles:Semiconductor fabricators in Taiwan and South Korea now mandate eighteen-month stability testing for optical coating precursors, locking in qualified suppliers.
- REACH SVHC disclosure:ECHA's expanding candidate list forces downstream users to document bromide salt provenance, redirecting volume toward compliant European distributors.
- Photonic device miniaturization:Infrared window manufacturers are adopting sub-5-ppm trace-metal rubidium bromide for quantum sensor substrates.
Market Restraints
- Rubidium metal supply concentration:Over eighty percent of elemental feedstock originates from Chinese lepidolite processing, exposing converters to export license volatility.
- High-purity synthesis capex:Achieving semiconductor-grade specifications requires inert-atmosphere recrystallization infrastructure that smaller regional labs cannot justify.
- Caesium bromide substitution:Some spectroscopic applications tolerate the heavier alkali halide where optical transmission requirements permit.
Strategic Opportunities
- Indian pharmaceutical R&D expansion:CDSCO's streamlined clinical trial approvals are attracting multinational drug discovery operations that consume analytical-grade reagents.
- Domestic Japanese supply:METI's critical materials designation creates procurement preference for locally finished bromide salts serving domestic electronics clusters.
- Direct-to-laboratory e-commerce:Specialty chemical platforms are disintermediating traditional distributor markups for small-lot research orders.
Industry Challenges
- ISO 17025 auditor scarcity:Accreditation bodies face eighteen-month backlogs for laboratory chemical supplier certification, delaying market entry.
- Cross-border harmonization gaps:Divergent EPA and ECHA substance inventory classifications complicate unified safety documentation for multinational research contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubidium Bromide Market |
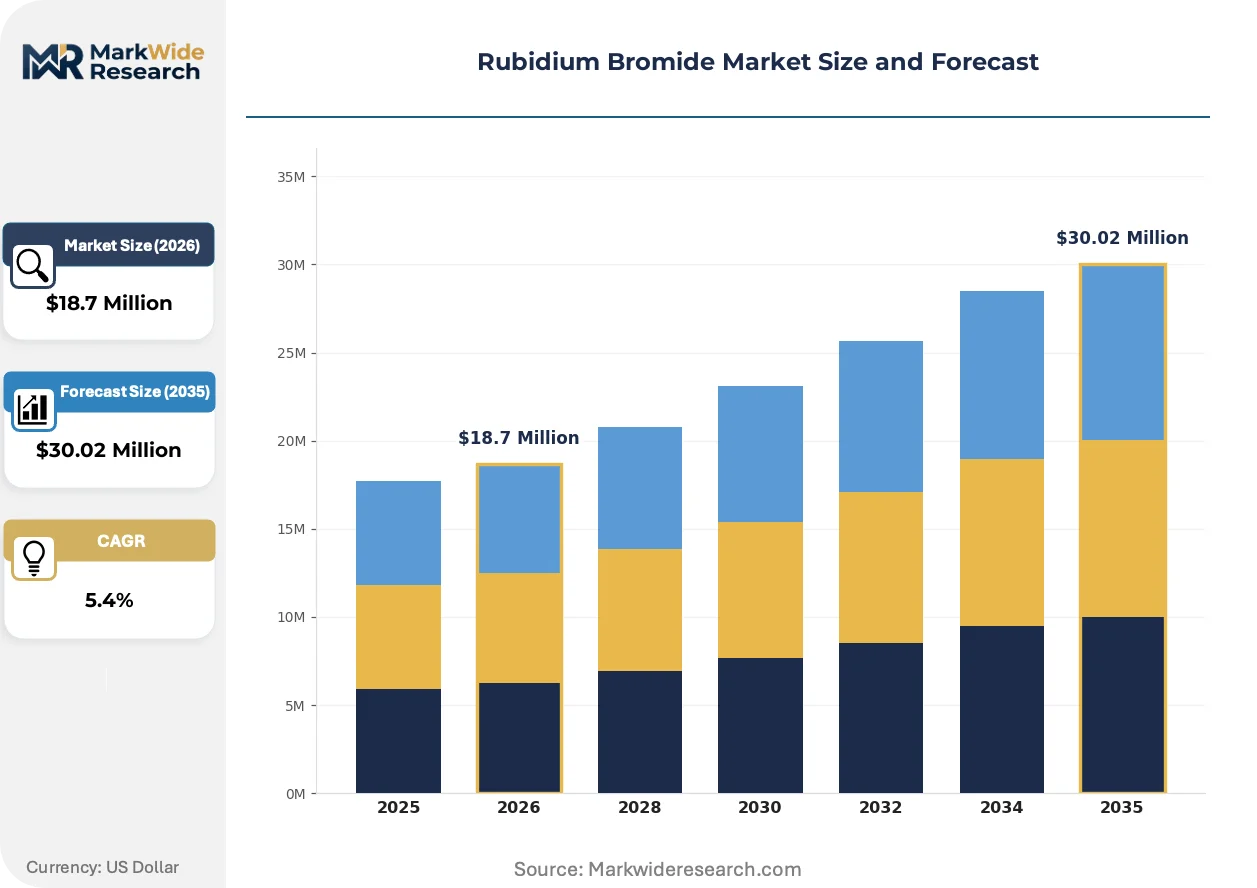
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $30.02 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Purity, Analytical Grade, Technical Grade, Reagent Grade End User: Chemical Manufacturers, Electronics Industry, Research Laboratories, Pharmaceuticals Application: Manufacturing, Research & Development, Analytical Chemistry, Drug Formulation Distribution Channel: Direct Sales, Online Retail, Wholesale Distribution, Specialty Chemical Suppliers |
| Companies Covered | American Elements, Merck KGaA, Sigma-Aldrich, Alfa Aesar, Tokyo Chemical Industry, Strem Chemicals, Otto Chemie Pvt. Ltd., TCI Chemicals (India), VWR International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubidium Bromide Market Evolving Landscape
Synthesis and purification methods for rubidium bromide are diverging sharply between mass-production and boutique-lot paradigms. This technological schism is reshaping competitive positioning across the value chain.
Zone-refined crystal growth is bifurcating the high-purity segment from conventional aqueous precipitation. Optoelectronics manufacturers in Germany and Japan now specify zone-refined material for quantum cascade laser substrates. The technology is compressing acceptable supplier lists to those with in-house crystal pulling capability.
ECHA's 2024 update to REACH Annex XVII restricted substances is tightening bromine compound handling protocols across European analytical laboratories. Industrial consequence includes mandatory substitution assessments for legacy bromide salt stocks. Academic research consortia in France and the Netherlands are accelerating supplier audits to preempt enforcement actions.
Consolidated procurement through university system purchasing cooperatives is displacing individual laboratory catalog orders. The University of California system and German Helmholtz Association now negotiate framework agreements directly with manufacturers. This concentration is most visible in North American and Central European research corridors where annual reagent volumes exceed ten-thousand-kilogram thresholds.
Rubidium Bromide Market Segmentation
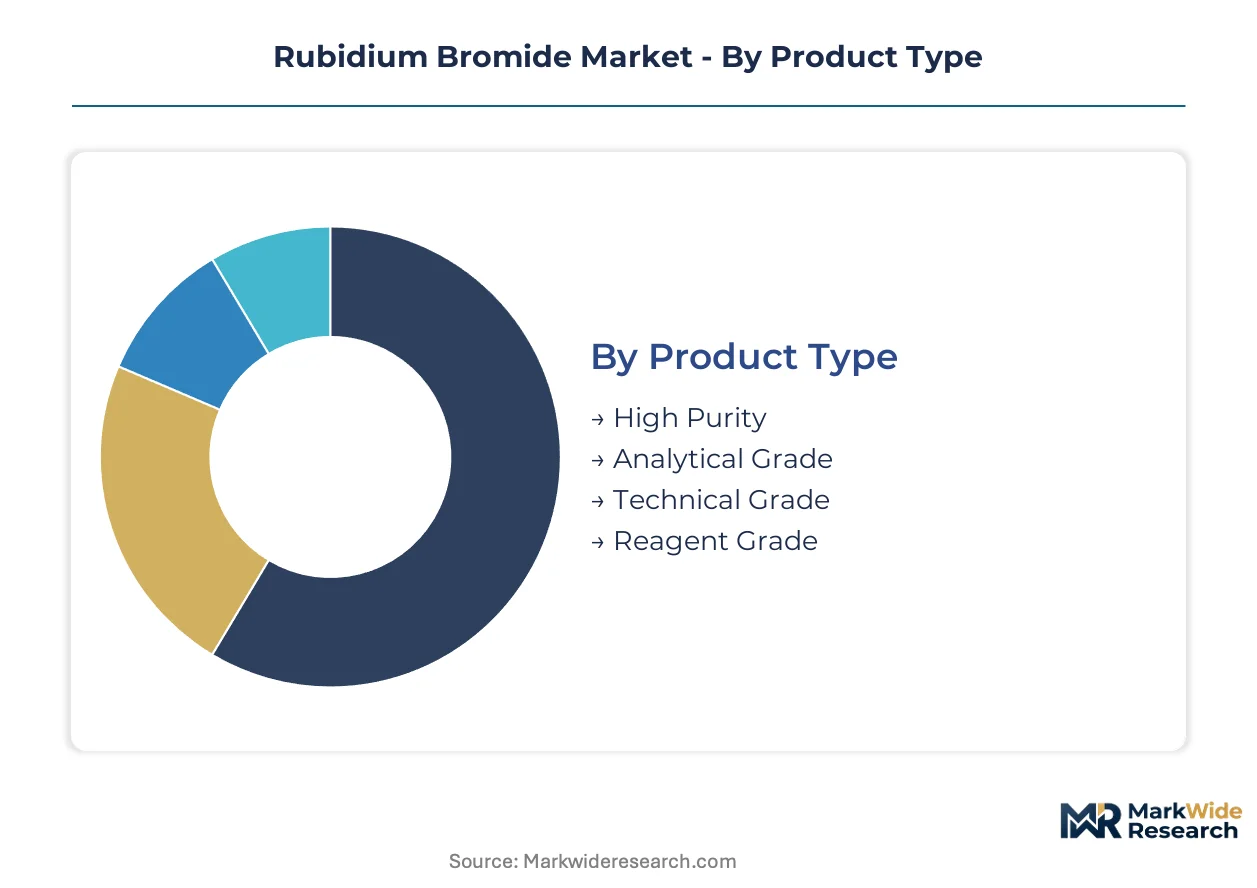
Rubidium bromide procurement splits sharply across purity tiers and end-use specifications, with qualification requirements from EPA and ECHA driving divergence between semiconductor-grade and general laboratory supply chains. Electronics manufacturers now mandate eighteen-month stability protocols that disqualify commodity-grade suppliers from premium contract streams.
Product Type:
REACH SVHC disclosure obligations and EPA hazardous substance reporting thresholds create distinct compliance burdens across purity grades, with semiconductor specifications demanding trace-metal documentation below 10 ppm.
- High Purity:Zone-refined crystal growth achieves sub-5-ppm trace-metal specifications for quantum cascade laser substrates and infrared window fabrication. German and Japanese optoelectronics clusters now require in-house crystal pulling capability as a baseline qualification. Demand concentrates where eighteen-month material certification cycles protect incumbent positions.
- Analytical Grade:Aqueous precipitation methods deliver consistent batch-to-batch reproducibility for spectroscopic applications. Research laboratories in the United States and Germany prioritize ISO 17025-accredited suppliers for quantitative analysis workflows. CDSCO-aligned pharmaceutical R&D operations in India are expanding procurement volumes for this tier.
- Technical Grade:Standard precipitation synthesis serves industrial process applications with moderate purity tolerances.
- Reagent Grade:Academic and government laboratories sustain volume throughput for routine synthetic chemistry and teaching applications.
Reagent Grade handles the majority of throughput; High Purity is gaining share fastest as photonic device miniaturization accelerates.
End User:
Customer procurement sophistication varies dramatically, with electronics fabricators imposing capital-intensive qualification regimes that research institutions cannot replicate.
- Electronics Industry:Taiwan and South Korean semiconductor fabricators mandate extended stability testing for optical coating precursors, locking supply relationships for thirty-six-month cycles. METI's critical materials designation in Japan creates additional procurement preference for locally finished salts serving domestic clusters.
- Research Laboratories:University system purchasing cooperatives in California and the German Helmholtz Association now negotiate framework agreements directly with manufacturers, bypassing traditional distributor markups. ECHA's 2024 REACH Annex XVII updates are accelerating supplier audits across French and Dutch academic consortia.
- Pharmaceuticals:Multinational drug discovery operations consume analytical-grade reagents under CDSCO's streamlined clinical trial approval framework.
- Chemical Manufacturers:Downstream processors source technical grades for intermediate synthesis and bulk formulation applications.
Research Laboratories dominate current volume; Electronics Industry shows the steepest expansion trajectory as qualification cycles lengthen.
Application:
Functional requirements dictate purity specifications, with analytical chemistry workflows demanding reproducibility that manufacturing applications can relax.
- Analytical Chemistry:Quantitative spectroscopic methods require batch-certified trace-metal profiles below regulatory detection limits. EPA reporting thresholds and ECHA SVHC candidate list reviews force documented provenance for every lot consumed in United States and European Union facilities.
- Research & Development:Exploratory synthesis programs prioritize catalog breadth and same-day fulfillment density over single-source qualification. Sigma-Aldrich competes aggressively in North American research corridors on fulfillment speed.
- Manufacturing:Optical coating and crystal growth processes integrate rubidium bromide as a feedstock for downstream device fabrication.
- Drug Formulation:Pharmaceutical developers employ high-purity grades for salt selection studies and bioavailability optimization.
Research & Development absorbs the largest share; Analytical Chemistry is climbing the fastest as regulatory documentation requirements tighten.
Distribution Channel:
Channel economics fragment between high-touch qualification support and transactional efficiency for small-lot orders.
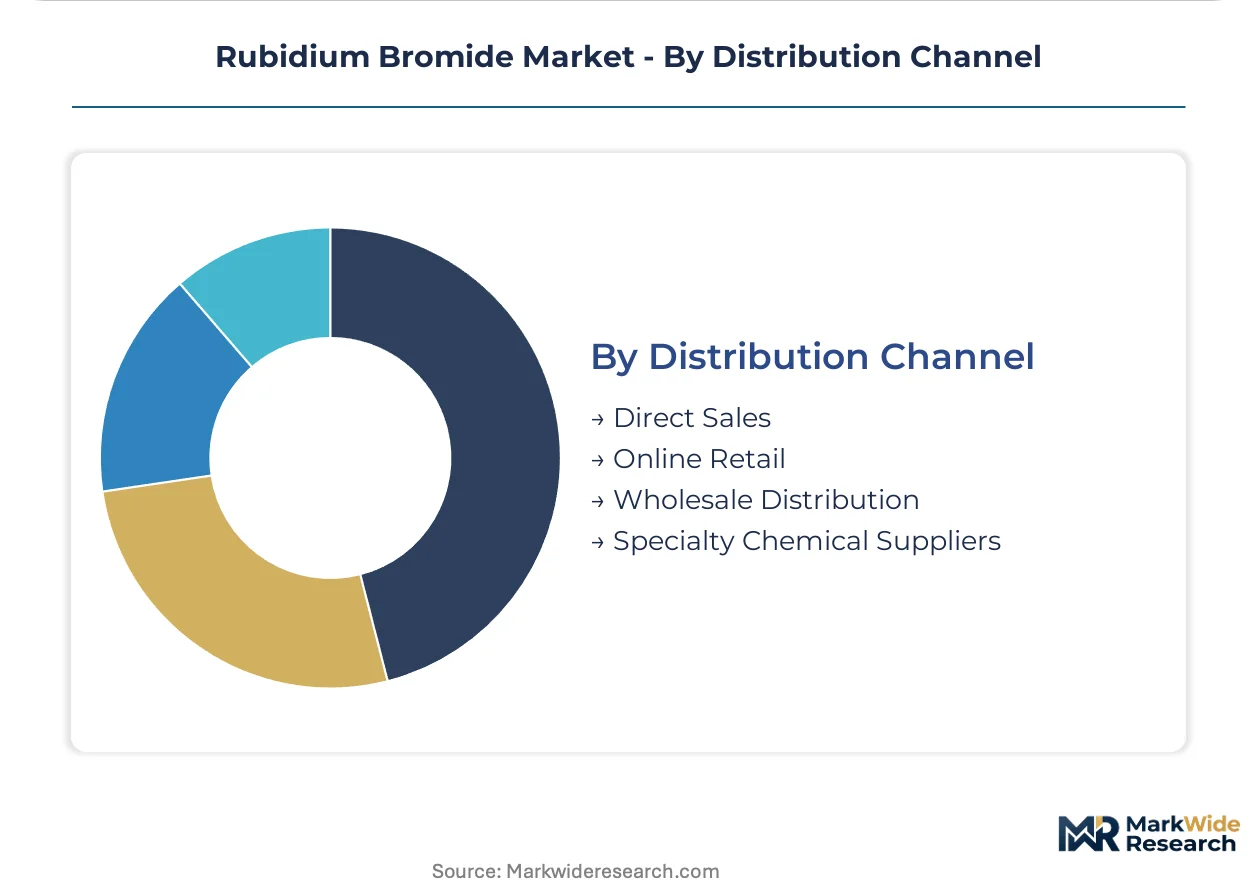
- Specialty Chemical Suppliers:American Elements leverages backward integration from elemental rubidium through bromide salt finishing to secure prime contractor status. Vertical control over feedstock insulates against Chinese lepidolite export license volatility.
- Online Retail:Direct-to-laboratory e-commerce platforms are disintermediating traditional distributor markups for sub-kilogram research orders. Consolidated procurement through university cooperatives is compressing margins for catalog distributors.
- Direct Sales:Electronics manufacturers negotiate multi-year supply agreements with qualified processors.
- Wholesale Distribution:Regional intermediaries serve smaller laboratories lacking volume to qualify for manufacturer-direct pricing.
Specialty Chemical Suppliers control the dominant share; Online Retail is expanding most quickly as purchasing cooperatives aggregate fragmented demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electronics fabricators and pharmaceutical R&D clusters drive rubidium bromide procurement across concentrated geographic corridors, with regulatory compliance requirements varying sharply by jurisdiction.
Germany
Optoelectronics manufacturers in Bavaria and Baden-Württemberg specify zone-refined rubidium bromide for quantum cascade laser substrates. REACH Annex XVII restrictions on bromine compound handling force documented substitution assessments for legacy laboratory stocks. The Munich-Frankfurt corridor anchors European demand through vertically integrated chemical processors serving precision electronics clusters.
Japan
Domestic electronics fabricators in the Kanto and Kansai regions consume high-purity grades for infrared optical coating applications. METI's critical materials designation creates procurement preference for locally finished bromide salts, insulating domestic suppliers from import volatility. Osaka-based crystal growth specialists now qualify directly with Taiwan and South Korean semiconductor foundries.
United States
Research laboratories across California and Massachusetts sustain volume throughput for analytical chemistry and spectroscopic applications. EPA hazardous substance reporting thresholds tighten documentation requirements for bromide salt provenance in academic and government facilities. The Greater Boston biotech corridor drives analytical-grade consumption through ISO 17025-accredited supplier frameworks.
India
Multinational pharmaceutical R&D operations in Maharashtra and Telangana expand procurement of analytical-grade reagents under CDSCO's streamlined clinical trial approval framework. The national pharmaceutical regulator's alignment with ICH guidelines accelerates qualification timelines for imported specialty chemicals. Hyderabad's drug discovery cluster now negotiates direct manufacturer relationships bypassing traditional distributor channels.
South Korea
Semiconductor fabricators in the Seoul Capital Area and Busan-Ulsan corridor mandate eighteen-month stability testing protocols for optical coating precursors. The country's chemical substance control framework requires pre-market notification for high-purity bromide salt imports serving domestic electronics manufacturers. Samsung and SK Hynix supplier qualification programs lock qualified material streams for thirty-six-month contract cycles.
Rubidium Bromide Market Competitive Landscape
Player mix skews toward vertically integrated elemental processors and catalog distributors with dense fulfillment networks. Market structure concentrates around three to five qualified suppliers per major geography, with ISO 17025 accreditation collapsing as the baseline entry barrier. Two strategic archetypes dominate: backward-integrated chemical processors controlling feedstock from lepidolite through finished salt, and broad-catalog distributors competing on same-day availability. Competitive moves center on multi-year supply agreements with electronics manufacturers and direct-to-laboratory e-commerce platforms disintermediating traditional markups.
Among North American fabricators, American Elements exemplifies the backward-integrated archetype through captive control of elemental rubidium supply. Merck KGaA anchors European distribution through its analytical-grade network spanning German research corridors. Sigma-Aldrich occupies a position in catalog breadth and fulfillment density across United States academic markets.
| Leading Market Players |
|---|
| American Elements |
| Merck KGaA |
| Sigma-Aldrich |
| Alfa Aesar |
| Tokyo Chemical Industry |
| Strem Chemicals |
| Otto Chemie Pvt. Ltd. |
| TCI Chemicals (India) |
| VWR International |
| Others |
Value Network & Pricing Analysis
Eighteen-month qualification cycles for semiconductor-grade material create pricing power asymmetries that favor backward-integrated processors over trading intermediaries in the rubidium bromide market. Inventory buffers at German and Japanese optoelectronics clusters typically extend to ninety days, insulating qualified suppliers from spot-price volatility while locking out unqualified competitors.
Pricing Analysis
Cost-plus contracts indexed to Chinese lepidolite export license fees dominate long-term supply agreements between elemental processors and electronics manufacturers. Pricing stratifies across semiconductor-grade, analytical-grade, and technical-grade tiers, with trace-metal certification below 5 ppm commanding substantial premia over standard laboratory grades. Cost compression in technical-grade segments is intensifying because Indian pharmaceutical R&D expansion is aggregating demand through purchasing cooperatives. Research laboratories exhibit highest price sensitivity due to budget constraints, while semiconductor fabricators prioritize qualification security over unit cost.
Supply Chain Analysis
Ninety-day inventory positions at Japanese electronics clusters reflect deliberate buffering against Chinese lepidolite export volatility. Elemental feedstock concentrates in Chinese lithium mica processing, German zone-refining capability, and Japanese crystal growth specialization. Raw material dependencies encompass lepidolite ore, bromine brine extraction, and inert-atmosphere recrystallization infrastructure. Single-source vulnerability in Chinese elemental supply creates systemic exposure to export license restrictions. Distribution runs through vertically integrated specialty chemical suppliers for qualified electronics volumes, with e-commerce platforms capturing fragmented research laboratory demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Caesium bromide substitution in spectroscopic applications presents a material displacement threat that incumbent suppliers must actively counter through performance differentiation and customer lock-in mechanisms.
For Market Incumbents: Secure multi-year supply agreements with Taiwan and South Korean semiconductor fabricators before qualification cycles reset, insulating revenue streams from caesium bromide substitution in infrared applications. Invest in ISO 17025 accreditation capacity to collapse auditor backlogs that delay competitor market entry. Backward integration into elemental rubidium refining mitigates Chinese export license volatility. For New Entrants and Emerging Players: ISO 17025 fast-track programs through European accreditation bodies offer the most viable entry path for regional laboratories seeking qualification with university purchasing cooperatives. Target Indian pharmaceutical R&D clusters in Hyderabad and Pune where CDSCO-aligned operations are expanding analytical-grade consumption and distributor relationships remain underdeveloped. Direct-to-laboratory e-commerce platforms provide disintermediation leverage against established catalog distributors. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized zone-refining capacity and dormant electronics industry qualifications. Long-term viability hinges on sustained photonic device miniaturization and quantum sensor substrate adoption. Monitor ECHA REACH SVHC candidate list expansion as a regulatory inflection signal that would redirect volume toward compliant European distributors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elemental Feedstock | Captive rubidium supply from lepidolite processing insulates against Chinese export license volatility. |
| ISO 17025 Accreditation Expansion | Eighteen-month auditor backlogs create first-mover advantage for qualified laboratory chemical suppliers. |
| Direct-to-Laboratory E-Commerce Platform | Disintermediation of distributor markups captures aggregated demand from university purchasing cooperatives. |
| Zone-Refined Crystal Growth Capacity Addition | In-house pulling capability satisfies German and Japanese optoelectronics specifications for quantum cascade laser substrates. |
| Long-Term Supply Agreement with Semiconductor Fabricators | Thirty-six-month contract cycles with Samsung and SK Hynix lock in qualified material streams. |
Research Methodology
Initial hypotheses were tested against primary input from specialty chemical procurement managers, semiconductor materials qualification engineers, pharmaceutical R&D directors, and university laboratory supply coordinators and refined through secondary validation against customs trade data, ECHA REACH registration databases, SEC chemical company filings, and Japanese METI critical materials reports. Bottom-up demand modeling across purity grades and end-use segments was cross-checked against top-down elemental rubidium consumption estimates.
Variance decomposition across grade tier, end-use industry, geographic production hub, and certification level shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by purity-adjusted pricing. Forecast inputs incorporated photonic device miniaturization adoption curves, REACH SVHC disclosure expansion timelines, and Indian pharmaceutical R&D cluster formation patterns.
Decision-makers should treat outputs as directional under assumptions of sustained electronics qualification cycle extension and stable Chinese lepidolite export policy; material deviation in either factor would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Bitumen Market
Bulk Chemicals
Acetyl Tributyl Citrate Market
Bulk Chemicals
Ammonium Nitrate Market
Bulk Chemicals
Chlor Alkali Market
Bulk Chemicals
Sodium Bromide Market
Bulk Chemicals
Triazine Market
Bulk Chemicals
Europe Castor Oil Market
Bulk Chemicals
Nickel Nitrate Hexahydrate Market
Bulk Chemicals
Aniline Market
Bulk Chemicals
Oman Sodium Hydroxide Market
Bulk Chemicals
Mercaptan Market
Bulk Chemicals
FT Wax Market
Bulk Chemicals
Isatoic Acid Anhydride Market
Bulk Chemicals
Mercaptan Scavenger Market
Bulk Chemicals
Meta Tartaric Acid Market
Bulk Chemicals
Chemical Warehousing Market