
 Sulfur Market | 2026-2036
Sulfur Market Size, Share, and Industry Trends Forecast 2026-2036
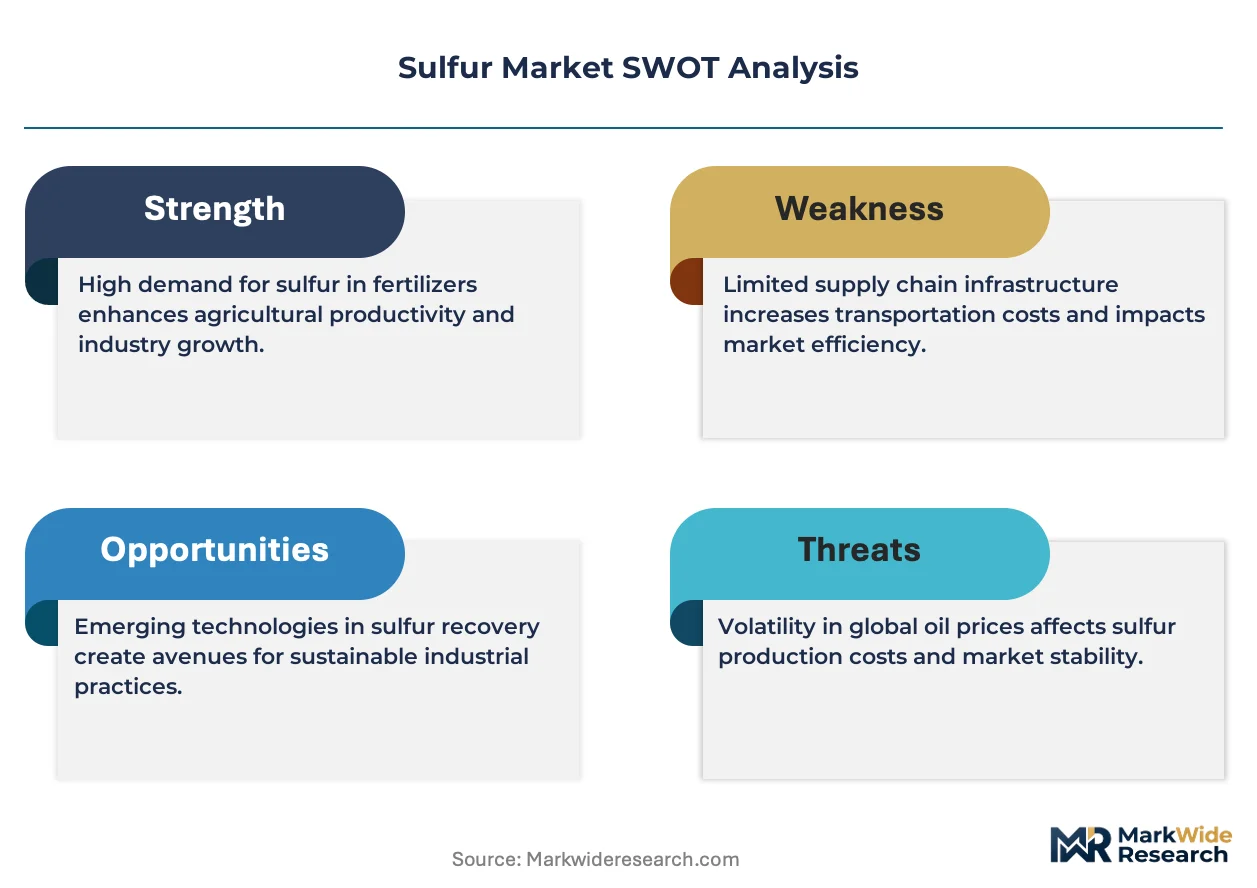
Sulfur Market Analysis
Middle East capacity expansion is rewriting supply geography for elemental sulfur. Saudi Aramco leverages integrated sour gas processing at Ghawar and Safaniya fields to dominate bulk export volumes. ADNOC anchors downstream sulfuric acid capacity at Ruwais Derivatives Complex, while Gazprom sustains European pipeline deliveries through Black Sea terminals.
Sulfur is a nonmetallic chemical element with atomic number 16, occurring naturally in volcanic deposits and as a byproduct of hydrocarbon desulfurization, with commercial grades typically exceeding 99.5% purity for industrial use. Its primary commercial purpose centers on sulfuric acid production, which consumes over 80% of mined and recovered supply for phosphate fertilizer manufacture and metal ore leaching. Elemental sulfur and sulfuric acid together occupy the largest value pools given their irreplaceable role in agricultural nutrient systems and base metal extraction. Sulfur hexafluoride and thiol compounds represent faster-growing specialty segments where semiconductor etching and polymer cross-linking applications command premium pricing.
EPA sulfur recovery standards under the Clean Air Act mandate 95%+ capture efficiency at US refineries, while MEE enforcement in China tightens SO2 emission ceilings for smelters and coal chemical complexes. REACH registration requirements in Europe constrain sulfur derivative imports through substance volume thresholds and hazard classification protocols. Stakeholders must monitor regulatory divergence between Gulf state export incentives and OECD import compliance burdens when siting new derivative capacity.
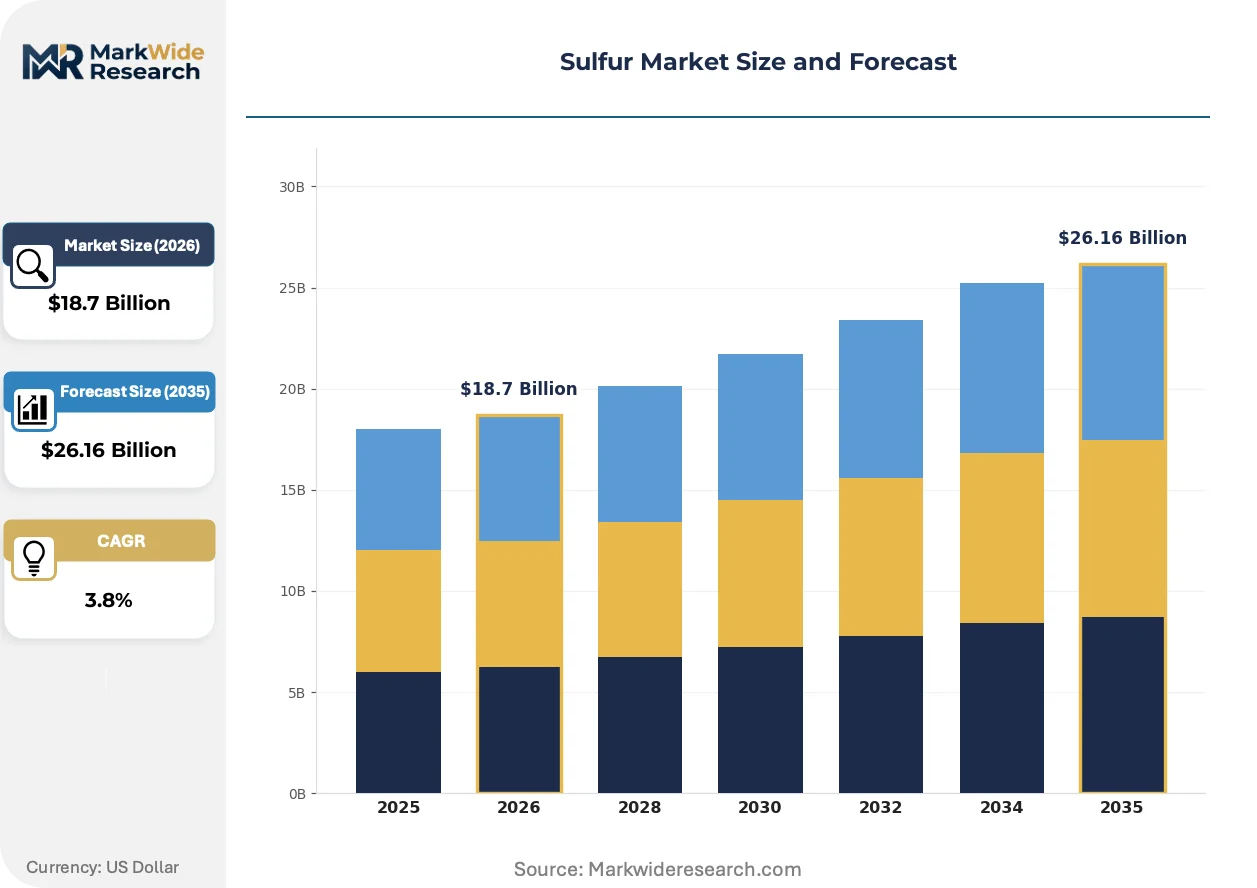
Market Dynamics
Sour gas processing expansion across Middle Eastern petrochemical corridors is concentrating elemental sulfur supply in proximity to phosphate fertilizer demand centers, compressing logistics arbitrage windows and rewiring long-haul trade routes.
Growth Catalysts
- MEE emission ceilings:China's Ministry of Ecology and Environment mandates SO2 capture at coal chemical complexes, forcing smelters to recover sulfur as a marketable byproduct rather than venting it as waste.
- Phosphate fertilizer pull:Indian fertilizer producers expand sulfuric acid consumption to process imported phosphate rock, driving bulk sulfur procurement through long-term offtake contracts.
- Claus unit retrofits:Refineries deploy advanced amine-based acid gas removal systems that boost sulfur recovery rates while handling heavier sour crude slates.
Market Restraints
- Gulf supply concentration:Saudi Aramco and ADNOC control bulk export volumes from integrated gas processing, creating single-source dependency for Asian derivative manufacturers.
- Hydrogen sulfide handling costs:Toxicity protocols mandate specialized railcars and dedicated terminal infrastructure, inflating delivered costs for inland consumers.
- Lithium battery chemistry substitution:Phosphate-based cathode materials compete with sulfur-intensive leaching routes in copper and rare earth recovery, eroding metal extraction demand.
Strategic Opportunities
- Brazilian agriculture expansion:Cerrado soybean and corn cultivation drives sulfuric acid demand for phosphate processing, opening import corridors from Middle Eastern exporters.
- Semiconductor etching gases:Sulfur hexafluoride purification for 3nm chip fabrication commands pricing multiples above commodity sulfur, attracting specialty chemical investment.
- EU F-Gas Regulation phase-down:Controlled substitution timelines for SF6 in switchgear create transitional supply windows for high-purity sulfur derivatives.
Industry Challenges
- Claus process engineering expertise:Talent scarcity in thermal reactor design and tail gas treatment limits operational uptime at complex sour gas facilities.
- REACH substance registration:ECHA compliance timelines for sulfur derivative imports extend 18-24 months, delaying European market entry for new suppliers.
- Molten sulfur storage integrity:Tank corrosion and solidification risks require continuous heating infrastructure, elevating working capital intensity for traders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sulfur Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Elemental Sulfur, Sulfuric Acid, Sulfur Hexafluoride, Thiol Compounds Application: Fertilizers, Pharmaceuticals, Chemical Manufacturing, Rubber Production End User: Agriculture, Energy, Healthcare, Manufacturing Delivery Mode: Bulk Transport, Liquid Transport, Packed Transport, Others |
| Companies Covered | Saudi Aramco, Abu Dhabi National Oil Company (ADNOC), Gazprom, Shell, Marathon Petroleum Corporation, Kuwait Petroleum Corporation, Suncor Energy, Canadian Natural Resources, Qatar Petroleum, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sulfur Market Emerging Trajectories
Digital instrumentation and predictive maintenance systems are penetrating sulfur handling infrastructure, converting bulk commodity logistics into data-rich operations that optimize inventory turns and reduce contamination incidents.
Advanced process control software is digitizing Claus unit operations across refinery and gas processing installations. Operators at ADNOC's Ruwais complex deploy real-time thermodynamic modeling to stabilize conversion efficiency. This capability compresses unplanned shutdown intervals and tightens product quality bands for acid-grade sulfur.
EPA sulfur recovery standards under the Clean Air Act now mandate 95 percent capture efficiency with continuous emissions monitoring. US refiners face capital allocation decisions between tail gas unit upgrades and hydrogen production integration. The Gulf Coast refining cluster responds by consolidating sulfur handling through shared pipeline networks and third-party terminal access.
Long-term offtake contracting is displacing spot market exposure among Indian fertilizer manufacturers. Rashtriya Chemicals and Fertilizers anchors procurement through five-year supply agreements with Middle Eastern exporters, transferring price volatility risk to integrated producers. This pattern concentrates purchasing power with state-backed processors while marginalizing independent trading houses.
Sulfur Market Segmentation
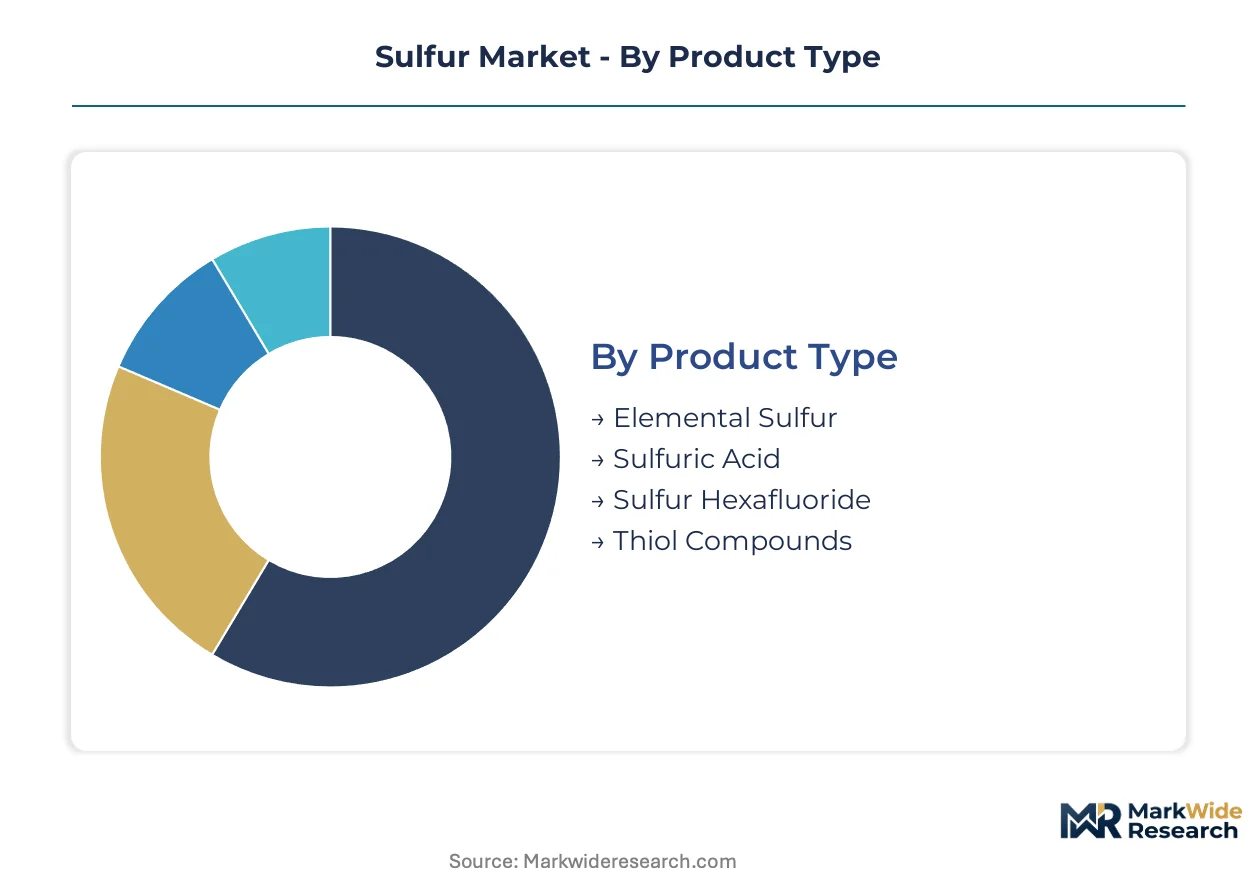
Sulfur market segmentation reveals divergent margin structures across product grades and delivery modes. Technical specifications and logistics infrastructure requirements create distinct competitive arenas that reward specialized handling capabilities.
Product Type:
After-sales service intensity varies sharply across sulfur derivatives, with acid-grade products demanding continuous technical support for storage and dilution systems while commodity elemental sulfur requires minimal post-delivery engagement.
- Elemental Sulfur:Recovered from sour gas processing and oil refining through Claus units, typically formed into prills or pellets for bulk handling. Indian phosphate fertilizer producers at Paradeep and Hazira anchor procurement volumes through annual tender processes tied to monsoon planting cycles.
- Sulfuric Acid:Manufactured via contact process oxidation of sulfur dioxide, with commercial grades spanning 93-98% concentration for industrial use. Smelter operators in China's Shandong province expand captive acid plants to satisfy MEE emission mandates while supplying leaching operations for copper cathode production.
- Sulfur Hexafluoride:High-purity gas for electrical insulation and semiconductor etching, synthesized through fluorination of sulfur with cobalt trifluoride catalysts.
- Thiol Compounds:Organosulfur molecules serving as polymerization regulators and odorants for natural gas distribution networks.
By volume, elemental sulfur leads. By growth pace, sulfur hexafluoride is ahead.
Application:
Cost tier stratification separates commodity fertilizer applications from premium pharmaceutical grades, with specification purity driving order-of-magnitude price differentials.
- Fertilizers:Sulfuric acid digests phosphate rock into soluble superphosphate and phosphoric acid intermediates. Brazilian soybean growers in Mato Grosso drive import demand through domestic sulfur deficits that Middle Eastern exporters fill via Santos terminal deliveries.
- Pharmaceuticals:Thiol cross-linking agents and sulfonamide intermediates require GMP-certified sulfur derivatives with documented impurity profiles. European manufacturers face REACH registration delays that constrain supply chain flexibility for novel active pharmaceutical ingredients.
- Chemical Manufacturing:Sulfonation reactions and chlorosulfonic acid production consume merchant acid for surfactant and dye intermediate synthesis.
- Rubber Production:Vulcanization accelerators and rubber processing chemicals incorporate sulfur cross-linking chemistry for tire and industrial goods manufacturing.
Fertilizer applications dominate tonnage. Pharmaceutical applications command the steepest expansion trajectory.
End User:
Customer type segmentation distinguishes price-sensitive agricultural cooperatives from specification-driven healthcare manufacturers with divergent contracting behaviors.
- Agriculture:Fertilizer blenders and direct application services purchase bulk sulfur and acid for soil amendment and nutrient delivery. Indian state-owned enterprises at Rashtriya Chemicals and Fertilizers negotiate five-year offtake agreements that transfer price volatility to integrated Middle Eastern suppliers.
- Energy:Oil refineries and gas processors operate Claus units as environmental compliance infrastructure, marketing recovered sulfur as byproduct revenue.
- Healthcare:Pharmaceutical manufacturers and medical device producers require sulfur derivatives with validated supply chain documentation and batch-level traceability.
- Manufacturing:Diverse industrial consumers spanning battery materials, pigments, and explosives production.
Agriculture consumes the greatest volumes. Healthcare is climbing the fastest.
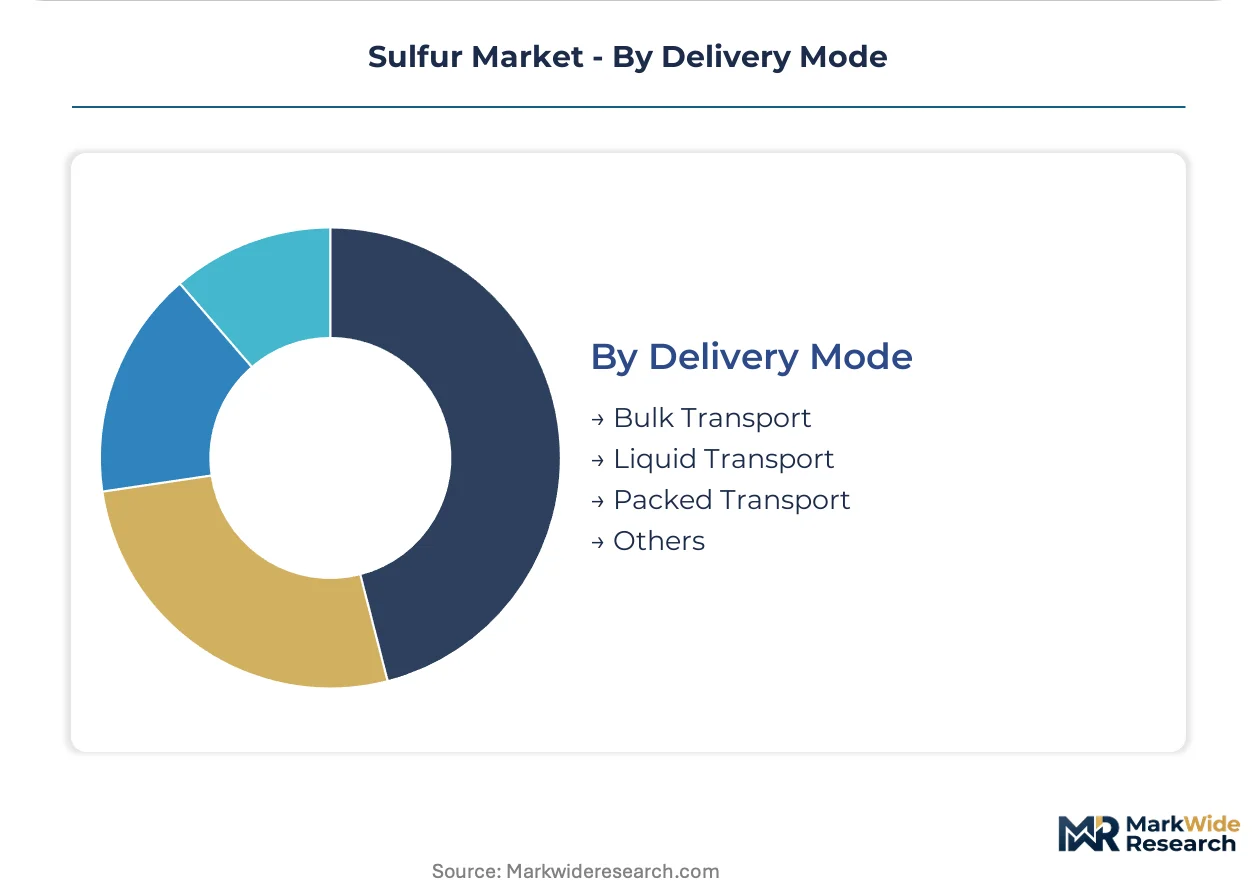
Delivery Mode:
Supply concentration in Gulf export corridors shapes logistics economics, with molten sulfur pipelines offering cost advantages over packaged alternatives for high-volume consumers.
- Bulk Transport:Dedicated vessels and railcars handle prilled elemental sulfur in 25,000-tonne parcel sizes. ADNOC's Ruwais terminal loads capesize vessels for Asian fertilizer producers, achieving lowest unit costs through scale economies.
- Liquid Transport:Heated tank trucks and insulated railcars maintain molten sulfur above 115°C to prevent solidification. EPA spill prevention regulations mandate secondary containment for inland liquid sulfur movements.
- Packed Transport:25-50 kg bags and intermediate bulk containers serve dispersed small-scale consumers with intermittent demand patterns.
- Others:Specialized handling for hazardous sulfur derivatives including compressed gas cylinders and cryogenic containers.
Bulk transport handles the greatest tonnage. Liquid transport is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE emission ceilings in China anchor the dominant regulatory geography, reshaping supply flows across fertilizer corridors and sour gas processing networks worldwide.
China
Coal chemical complexes in Shandong province drive sulfur recovery as MEE mandates tighten SO2 emission ceilings. Smelters at Zibo and Dongying convert captured sulfur into merchant acid for phosphate processing. The Yangtze River Delta clusters phosphate fertilizer demand near sulfuric acid terminals.
India
State-owned enterprises at Paradeep and Hazira anchor procurement through five-year offtake agreements with Middle Eastern exporters. Fertilizer producers expand sulfuric acid consumption to process imported phosphate rock ahead of monsoon planting cycles. The Gujarat industrial corridor concentrates acid storage infrastructure at Hazira.
Saudi Arabia
Saudi Aramco leverages integrated sour gas processing at Ghawar and Safaniya fields to dominate bulk export volumes. The Kingdom's petrochemical corridors concentrate elemental sulfur supply in proximity to Asian fertilizer demand centers. The Eastern Province hosts integrated Claus unit operations at scale.
United States
EPA sulfur recovery standards under the Clean Air Act mandate 95 percent capture efficiency at Gulf Coast refineries. The Texas-Louisiana refining cluster consolidates sulfur handling through shared pipeline networks and third-party terminal access. Houston Ship Channel infrastructure supports molten sulfur export logistics.
Brazil
Cerrado soybean and corn cultivation drives sulfuric acid demand for phosphate processing at Mato Grosso blending facilities. Santos terminal deliveries anchor import corridors from Middle Eastern exporters. The Brazilian agriculture sector opens long-haul trade routes for Gulf-origin sulfur derivatives.
Sulfur Market Vendor Landscape
Integrated national oil companies and independent refiners split the market between captive supply and merchant trading positions. Saudi Aramco and ADNOC control bulk export volumes through sour gas processing integration, while Marathon Petroleum and Suncor Energy operate within North American refining corridors. Three archetypes dominate: state-backed upstream integrators with pipeline-to-port infrastructure, merchant traders with molten sulfur storage assets, and fertilizer producers with backward integration into acid manufacturing. Capacity expansion across Gulf petrochemical corridors and strategic partnerships for long-term offtake contracting represent the dominant competitive moves reshaping supply security.
Within the state-backed upstream integrator tier, Saudi Aramco exemplifies captive supply dominance through field-to-terminal infrastructure control. Abu Dhabi National Oil Company (ADNOC) occupies a parallel position anchoring downstream sulfuric acid capacity at Ruwais. Gazprom represents the pipeline-delivered alternative sustaining European supply through Black Sea terminal networks.
| Leading Market Players |
|---|
| Saudi Aramco |
| Abu Dhabi National Oil Company (ADNOC) |
| Gazprom |
| Shell |
| Marathon Petroleum Corporation |
| Kuwait Petroleum Corporation |
| Suncor Energy |
| Canadian Natural Resources |
| Qatar Petroleum |
| Others |
Supply Flow & Price Mechanics
Houston Ship Channel molten sulfur movements compress delivered cost spreads between Gulf Coast exporters and Asian fertilizer buyers, concentrating pricing power with integrated producers while forcing traders to absorb inventory heating costs and terminal access fees.
Pricing Analysis
Freight differentials between Middle Eastern export terminals and Indian discharge ports exceed acid-grade sulfur quality premiums, compressing margins for non-integrated traders. Contract-based long-term offtake dominates, with five-year agreements transferring volatility risk from Indian state-owned enterprises to Saudi Aramco and ADNOC. Price differentiation rests on molten versus prilled delivery format and dedicated terminal access rights. Fertilizer blenders in Mato Grosso exhibit highest price sensitivity due to domestic sulfur deficits, while semiconductor etching gas purchasers accept steep premiums for six-nines purity sulfur hexafluoride.
Supply Chain Analysis
Sour gas feedstock from Ghawar, Safaniya, and North Field reservoirs anchors global elemental sulfur availability, with Saudi Arabia, Qatar, and the UAE controlling bulk export volumes. Claus unit catalysts, specialized railcar fleets, and heated storage tanks constitute critical input dependencies. Single-source vulnerability concentrates around ADNOC's Ruwais terminal and Saudi Aramco's integrated field-to-port infrastructure. Distribution runs through dedicated capesize vessel charters for Asian fertilizer corridors and shared pipeline networks for Gulf Coast refiners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Molten sulfur storage and terminal logistics services expand faster than commodity sulfur production, creating recurring revenue pools that reward infrastructure ownership over trading positions.
For Market Incumbents: Harden captive supply positions through backward integration into sour gas processing or dedicated terminal capacity additions at Hazira and Paradeep. Lock in five-year offtake extensions with Indian fertilizer producers before MEE enforcement peaks in Shandong province. Priority lever: molten sulfur pipeline networks that foreclose trader arbitrage. For New Entrants and Emerging Players: Build out specialty sulfur hexafluoride purification capabilities for semiconductor foundries, where six-nines specification gaps persist outside established gas majors. Brazilian Cerrado agriculture presents the most penetrable bulk sulfur corridor via Santos terminal partnerships. Go-to-market angle: technical service bundles covering storage heating systems and acid dilution infrastructure. For Investors and Strategic Acquirers: Carve-out targets emerge from national oil company non-core sulfur trading desks and independent refinery byproduct marketing units stranded without pipeline access. Five-to-ten year viability favors assets with dedicated export terminal positions and long-term Indian offtake coverage. Signal to watch: ADNOC or Qatar Petroleum sulfur subsidiary IPO filings indicating monetization pressure on state-owned logistics assets.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Rashtriya Chemicals and Fertilizers anchors procurement through five-year Middle Eastern offtake contracts. |
| Backward Integration | Indian phosphate producers acquire acid manufacturing capacity to process imported rock at Hazira. |
| Capacity Expansion | ADNOC scales downstream sulfuric acid output at Ruwais Derivatives Complex for Asian export. |
| Joint Venture | Santos terminal operators partner with Gulf exporters to secure Cerrado agriculture corridor access. |
| Green Manufacturing Transition | Claus unit retrofits deploy amine-based acid gas removal to boost recovery rates under MEE mandates. |
Methodological Framework
A spread of perspectives from refinery operations managers, fertilizer procurement leads at Indian state-owned enterprises, sulfur terminal logistics coordinators, and specialty gas sales directors converged on the working assumptions. Secondary validation drew from EPA enforcement databases, MEE emission compliance filings, Indian customs import records, and ACC sulfur production surveys. Bottom-up capacity modeling triangulated against top-down fertilizer demand projections across the analysis window.
Demand-supply balance modeling segmented the market by product grade, end-use application, delivery mode, and regional production hub. CAGRs derived from fitted trend lines applied to historical trade flows and announced capacity additions. Forecast inputs incorporated Claus unit retrofit timelines, Indian monsoon planting cycle correlations, and semiconductor capital expenditure trajectories for etching gas demand.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese coal chemical complexes to expand merchant acid exports would shift outcomes beyond modeled ranges. Cross-checking against EIA refinery sulfur recovery data and Indian fertilizer ministry procurement disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Magnesium Nitrate Hexahydrate Market
Bulk Chemicals
Dicyclopentadiene (DCPD) Market
Bulk Chemicals
Global Sodium Lactate Market
Bulk Chemicals
India Chlorine Market
Bulk Chemicals
Sodium Tetraborate Market
Bulk Chemicals
Meta Tartaric Acid Market
Bulk Chemicals
Barium Sulfite Market
Bulk Chemicals
Triammonium Citrate Market
Bulk Chemicals
Europe Carbon Black Market
Bulk Chemicals
Asia-Pacific Ammonia Market
Bulk Chemicals
Sodium Hydrosulfide Market
Bulk Chemicals
India Carbon Black Market
Bulk Chemicals
Global Recovered Carbon Black Market
Bulk Chemicals
Ammonium Dichromate Market
Bulk Chemicals
Nickel Carbonate Market
Bulk Chemicals
Carbonate Market