
 Sodium Sulfide Market | 2026-2036
Sodium Sulfide Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Sulfide Market Analysis
ISO 9001 certification is rotating as a baseline qualifier for sodium sulfide suppliers serving multinational chemical buyers. Solvay S.A. leverages its integrated alkali-chemical platform to sustain supply security across European textile markets. Sichuan Shenhong Chemical Industry Co., Ltd. anchors production scale in China's western chemical corridor, while Tessenderlo Group competes through specialized derivatives for leather processing.
Sodium sulfide is an inorganic alkali metal sulfide compound, typically produced via reduction of sodium sulfate with carbon at temperatures exceeding 900°C, yielding Na₂S with variable crystal water content; it functions primarily as a reducing agent, depilatory, and flotation reagent across heavy industry. Flake and crystalline grades dominate volume due to handling efficiency in textile dyeing vats and tannery drums, while solution formulations are gaining traction in automated mining flotation circuits where dosing precision matters. Pulp and paper applications remain structurally mature with limited margin expansion, whereas mining end-use is attracting reformulated low-iron grades that command price premiums.
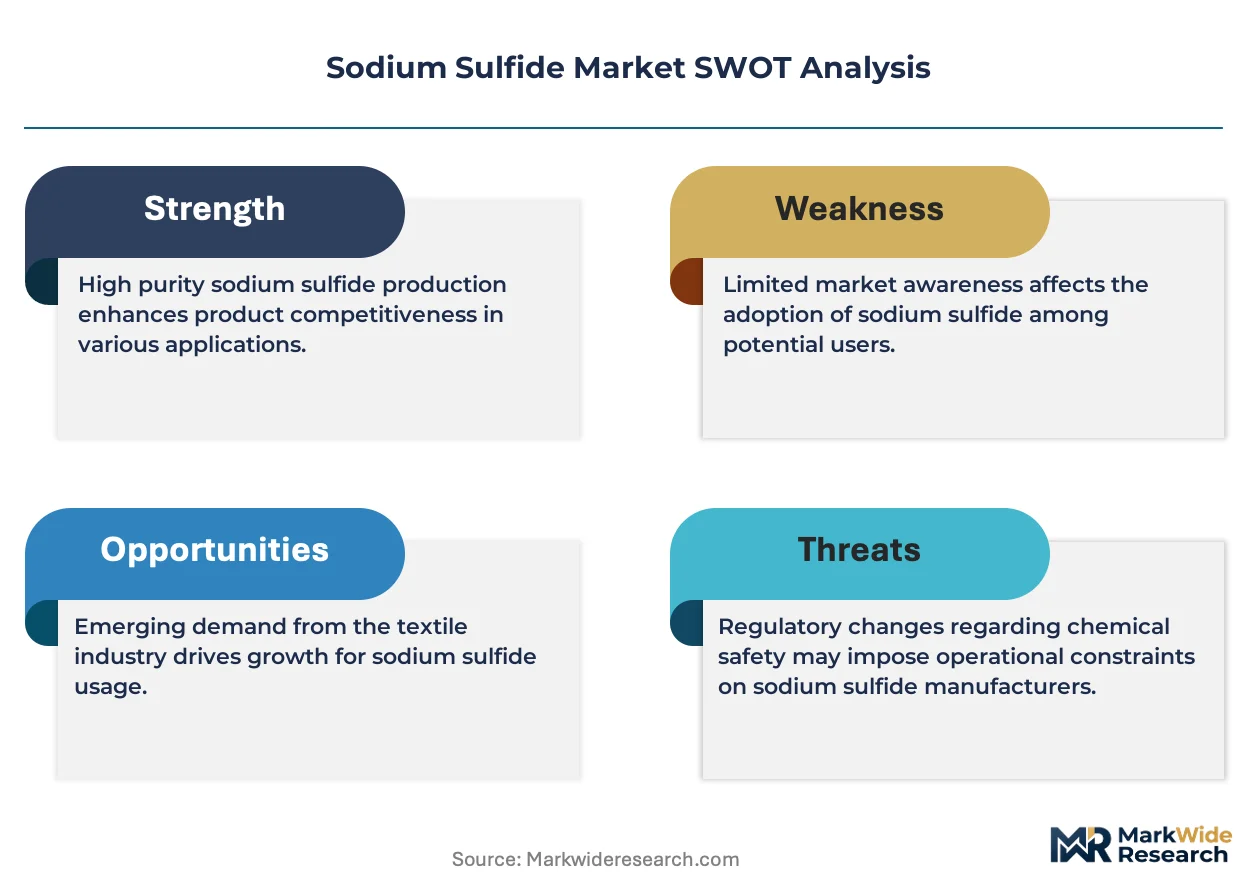
REACH registration requirements in Europe, EPA hazardous substance reporting in the United States, and China's GB standards for industrial chemical purity collectively constrain market entry for uncertified producers and elevate compliance costs across export channels. India's BIS certification for textile chemicals and the EU F-Gas Regulation's indirect pressure on competing sulfur chemistry pathways further reshape procurement criteria for downstream buyers. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate which product grades will retain cross-border market access.
Market Dynamics
REACH compliance in Europe is compressing the supplier base for sodium sulfide by disqualifying uncertified producers from export channels, while leather tanneries in India's western belt accelerate flake-grade consumption for dehairing operations.
Growth Catalysts
- Leather processing expansion:Tanneries in Gujarat and Tamil Nadu are scaling dehairing operations, pulling flake-grade volumes from domestic chemical corridors. India's BIS certification for textile chemicals reinforces quality-linked procurement.
- REACH registration deadlines:ECHA's substance evaluation protocols are consolidating import channels toward ISO 9001-certified suppliers, filtering out uncertified Asian producers from European textile markets.
- Low-iron grade innovation:Mining flotation circuits are adopting reformulated sodium sulfide with reduced iron content, commanding price premiums in automated dosing systems across copper and molybdenum recovery operations.
Market Restraints
- Energy-intensive reduction process:Sodium sulfate reduction with carbon at 900°C-plus temperatures exposes producers to volatile natural gas and electricity costs, squeezing margin stability.
- Western China supply concentration:Sichuan-based production clusters dominate global flake-grade output, creating geographic single-point vulnerability for international buyers.
- Biological depilatory substitution:Enzymatic dehairing formulations in European tanneries are displacing chemical sulfide processes under EU Green Deal pressure.
Strategic Opportunities
- Automated mining flotation:Solution-grade sodium sulfide is penetrating copper and gold recovery circuits in Chile and Peru where precision dosing systems replace manual handling.
- EU F-Gas Regulation tailwind:Restrictions on competing sulfur chemistry pathways are redirecting textile processors toward compliant sulfide reduction agents.
- Textile belt expansion:Bangladesh's garment chemical supply chain is absorbing surplus flake capacity as dyeing operations migrate from saturated Indian clusters.
Industry Challenges
- ISO 9001 certification timelines:Smaller Chinese producers face 12-to-18-month compliance gaps to meet multinational chemical buyer qualification requirements.
- Legacy tannery equipment retrofit:Indian dehairing drums require mechanical modifications to handle solution-grade formulations, delaying adoption of automated dosing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Sulfide Market |
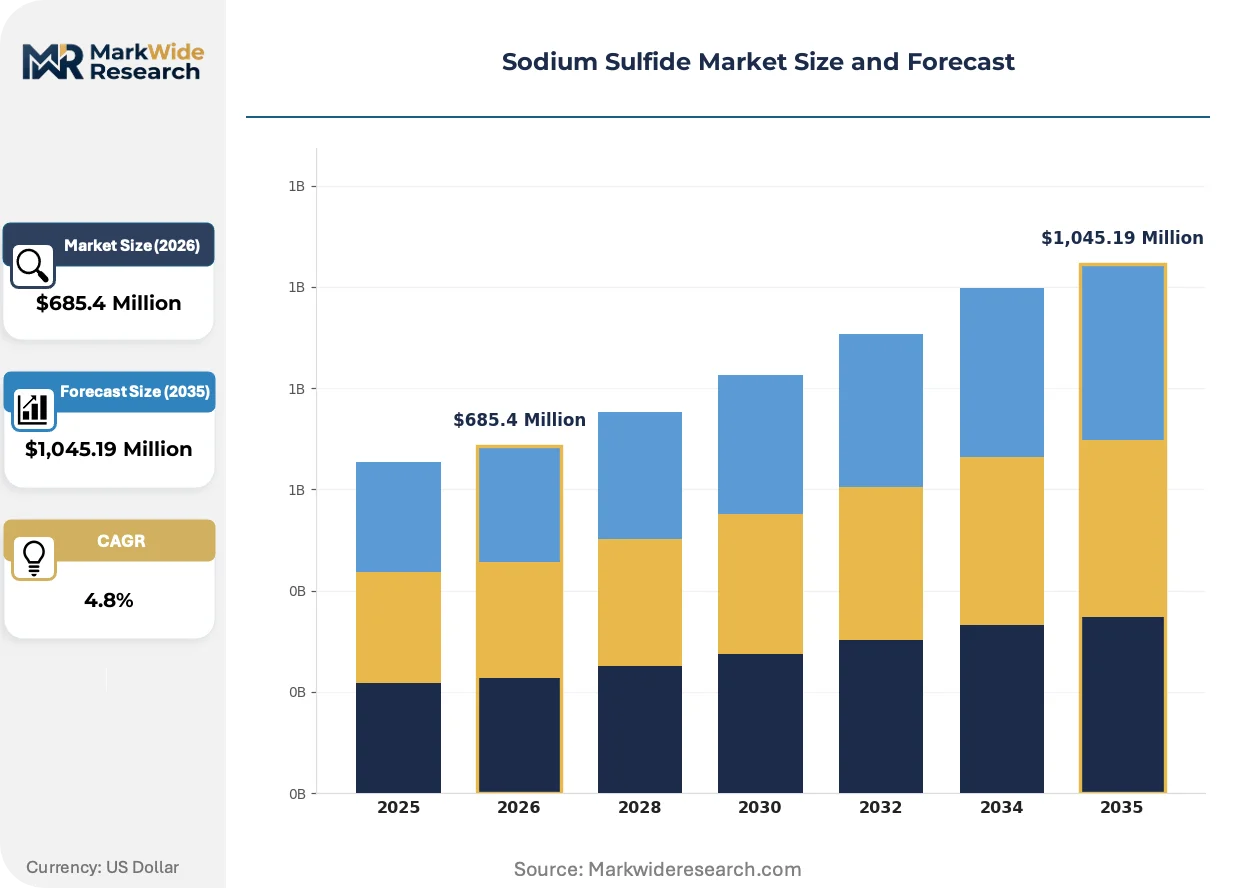
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flakes, Granules, Powder, Solutions Application: Textile, Pulp & Paper, Mining, Leather End User: Manufacturers, Chemical Companies, Textile Mills, Mining Firms Packaging Type: Bag, Drum, Bulk, Canister |
| Companies Covered | TIB Chemicals AG, Sichuan Shenhong Chemical Industry Co., Ltd., Solvay S.A., Rongyuan Chemical Co., Ltd., Shaanxi Fuhua Chemical Co., Ltd., Nippon Chemical Industrial Co., Ltd., American Elements, NaFine Chemical Industry Group Co., Ltd., Tessenderlo Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Sulfide Market Emerging Trajectories
Process intensification and regulatory chemistry are reshaping sodium sulfide value creation, with purification technology and compliance automation emerging as decisive competitive differentiators.
Membrane filtration systems for iron removal are miniaturizing. Mining chemical suppliers are installing skid-mounted purification units at flotation sites, eliminating transport of low-iron grades from distant refineries. This distributed production model is compressing logistics costs and enabling just-in-time sulfide generation at mine mouths.
ECHA's updated REACH substance evaluation criteria are tightening purity documentation for imported sodium sulfide. European textile dye houses are now requiring batch-level certificates of analysis from suppliers. German and Italian chemical distributors are consolidating procurement toward integrated alkali producers with captive testing laboratories.
Buyers are unbundling chemical supply from technical service contracts. Large Indian tanneries are negotiating direct flake purchases while sourcing application expertise separately from regional technical consultants. This disintermediation is eroding traditional distributor margins in Ahmedabad and Chennai chemical trading hubs.
Sodium Sulfide Market Segmentation
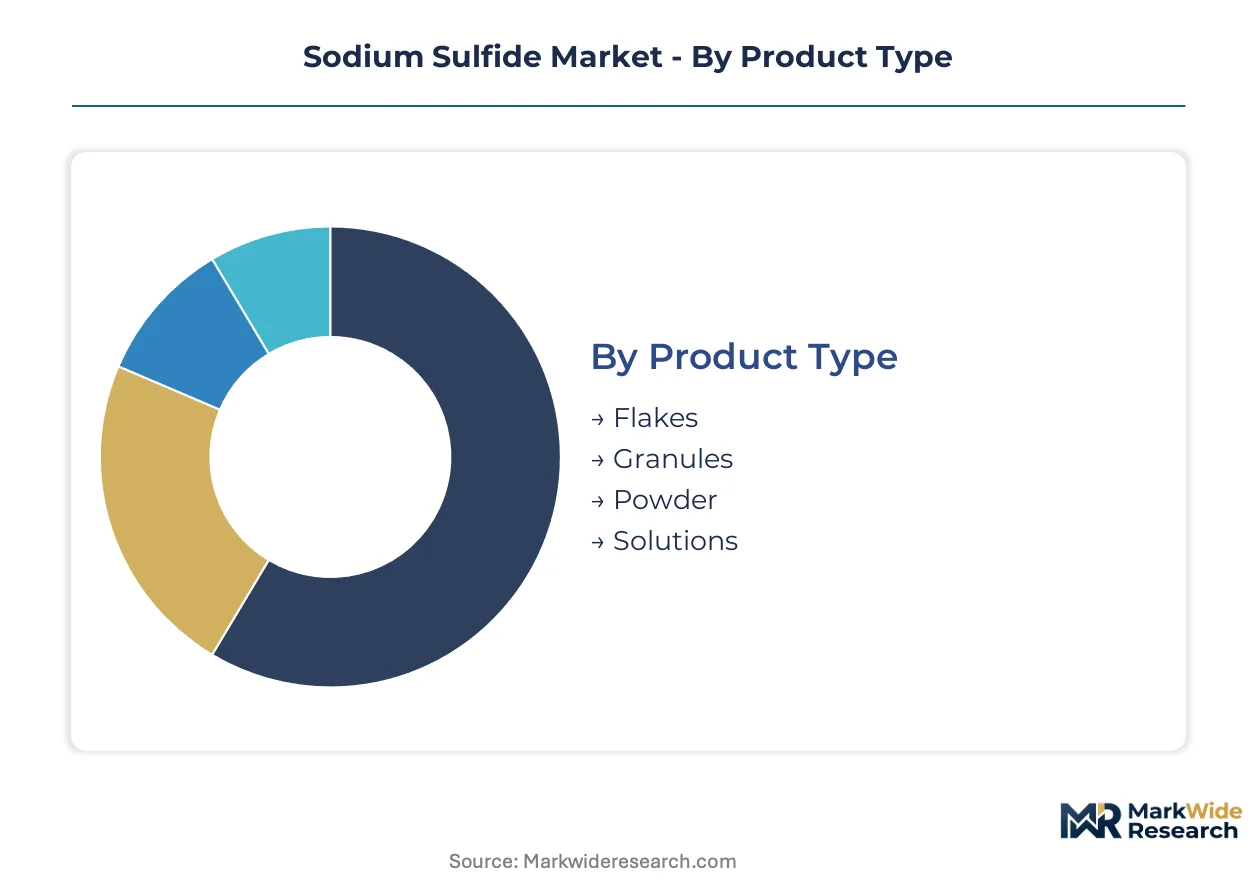
Sodium sulfide procurement patterns diverge sharply across product grades and packaging configurations. Leather tanneries in Gujarat favor flake formulations for drum handling efficiency, while automated mining circuits in Chile pull solution grades for precision dosing systems.
Product Type:
Flake and crystalline grades dominate export channels from Sichuan production clusters, whereas solution formulations serve domestic mining corridors with just-in-time delivery requirements.
- Flakes:Sodium sulfide flakes contain variable crystal water content, typically 30-60% Na₂S by weight. Tanneries in Tamil Nadu specify flake geometry for mechanical drum compatibility, with BIS-certified suppliers capturing procurement contracts from export-oriented leather units.
- Solutions:Aqueous sodium sulfide solutions, standardized at 30-60% concentration, enable automated dosing in copper flotation circuits. Mining chemical distributors in Peru install skid-mounted units at mine mouths, eliminating transport of purified grades from distant refineries.
- Granules:Dense granular sodium sulfide reduces dust exposure during handling; textile dye houses in Bangladesh specify granules for vat-fed continuous processing lines.
- Powder:Fine-ground powder serves specialty chemical synthesis and laboratory reagent markets with premium pricing for high-purity specifications.
Flakes hold the largest share; momentum sits with solutions as mining automation expands.
Application:
Cost tier stratification separates mature pulp applications from premium-priced mining formulations with reduced iron content.
- Leather:Dehairing operations consume flake-grade sodium sulfide as a depilatory agent, breaking disulfide bonds in keratin structures. Gujarat's tannery belt generates concentrated demand, though enzymatic substitution pressure under EU Green Deal compliance constrains European volume.
- Mining:Flotation reagent applications require low-iron sodium sulfide for sulfide mineral recovery. Chilean copper concentrators specify iron content below 50 ppm to prevent collector interference, commanding price premiums over standard industrial grades.
- Textile:Vat dye reduction and sulfur dye processing utilize standard-grade flakes; Bangladesh's garment chemical supply chain absorbs surplus capacity as dyeing migrates from saturated Indian clusters.
- Pulp & Paper:Kraft process applications for pulping liquor recovery remain structurally mature with limited margin expansion and stable volume trajectories.
Leather processing commands the greatest volume concentration; mining applications are climbing the fastest on premium-grade penetration.
End User:
Customer type determines procurement sophistication, with multinational chemical buyers imposing ISO 9001 qualification barriers that filter uncertified producers.
- Chemical Companies:Integrated alkali producers with captive sodium sulfide units supply downstream formulation markets; Solvay S.A. leverages its European platform to sustain REACH-compliant supply security.
- Textile Mills:Large dye houses in Ahmedabad and Chennai negotiate direct flake purchases while unbundling technical service contracts to regional consultants.
- Mining Firms:Copper and gold recovery operations specify batch-level certificates of analysis, consolidating procurement toward distributors with captive testing laboratories.
- Manufacturers:Industrial chemical blenders serve fragmented leather processor demand through bagged and drum packaging configurations.
Chemical companies retain the deepest backward integration; mining firms are gaining share fastest on specification intensity.
Packaging Type:
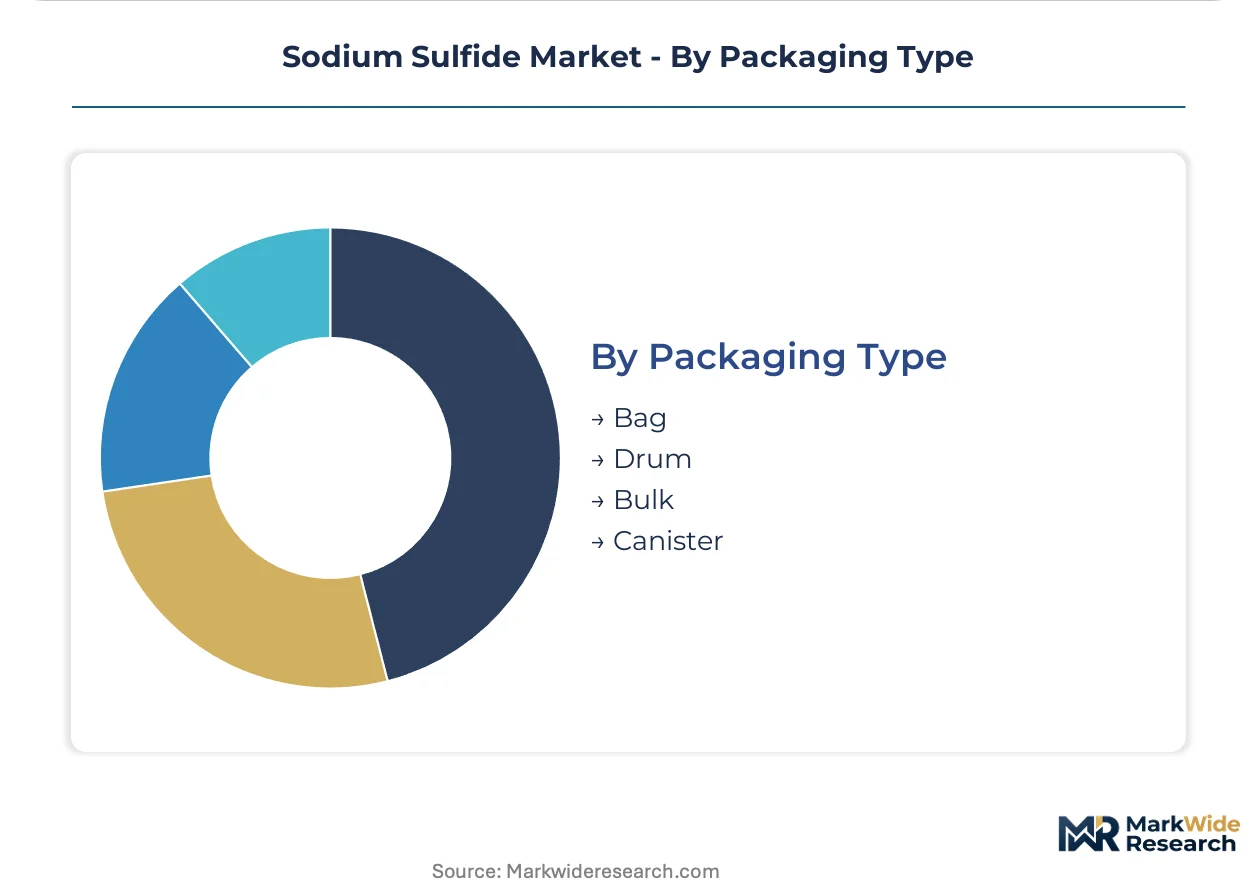
Volume scale dictates packaging selection, with bulk configurations serving automated mining circuits and bagged units addressing tannery drum feeding.
- Bag:Multi-layer laminated bags, typically 25-50 kg capacity, protect hygroscopic flake grades from moisture absorption during monsoon-season transport to Indian textile belt destinations.
- Drum:Steel and fiber drums contain solution-grade sodium sulfide for chemical company bulk transfer operations; UN-certified configurations satisfy hazardous material shipping protocols.
- Bulk:Tanker and hopper-car deliveries serve mining flotation sites with dedicated storage infrastructure, compressing per-unit logistics costs for high-volume consumers.
- Canister:Small-format canisters address laboratory reagent and specialty synthesis markets with gram-scale packaging precision.
Bulk configurations dominate mining procurement; bagged formats retain the broadest geographic reach across fragmented tannery demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Leather tanneries in Gujarat and Tamil Nadu pull the greatest procurement volumes, while copper flotation circuits in Chile and Peru drive premium-grade specifications. Mining automation in South America and textile migration into Bangladesh are redrawing regional demand maps.
China
Sichuan-based production clusters supply the majority of global flake-grade output for textile and leather applications. GB standards for industrial chemical purity constrain export channel access for uncertified producers. Western chemical corridors around Chengdu anchor manufacturing scale for both domestic consumption and international shipment.
India
Gujarat's tannery belt generates concentrated flake-grade demand for dehairing operations in export-oriented leather units. BIS certification for textile chemicals reinforces quality-linked procurement criteria. Dye houses in Ahmedabad and Chennai are unbundling technical service contracts from direct chemical purchases.
Chile
Copper concentrators specify low-iron sodium sulfide below 50 ppm to prevent collector interference in flotation circuits. Mining chemical distributors install skid-mounted purification units at mine mouths for just-in-time generation. Antofagasta and Santiago mining corridors command premium pricing for automated dosing compatibility.
Germany
Textile dye houses require batch-level certificates of analysis under ECHA's updated REACH substance evaluation protocols. German chemical distributors consolidate procurement toward integrated alkali producers with captive testing laboratories. Industrial clusters in North Rhine-Westphalia filter supply toward ISO 9001-certified channels.
Bangladesh
Garment chemical supply chains absorb surplus flake capacity as dyeing operations migrate from saturated Indian clusters. Dhaka-Chittagong industrial zones drive volume absorption without stringent purity requirements. Local processors favor granule formulations for vat-fed continuous processing lines.
Sodium Sulfide Market Vendor Landscape
Player mix skews toward integrated alkali producers and regional chemical specialists with captive reduction capacity. Structure concentrates around Sichuan-based production clusters serving Asian export markets and European REACH-compliant suppliers defending textile channels. Three archetypes dominate: integrated alkali platforms with backward sulfide control, regional mining chemical distributors with on-site purification, and specialty leather processors with derivative formulation expertise. Competitive moves center on capacity consolidation in western China and certification acceleration for European market access.
Among integrated alkali platforms, Solvay S.A. occupies a position exemplifying REACH-compliant supply security across European textile markets. Sichuan Shenhong Chemical Industry Co., Ltd. anchors production scale within China's western chemical corridor. Tessenderlo Group represents specialized derivative positioning for leather processing applications.
| Leading Market Players |
|---|
| TIB Chemicals AG |
| Sichuan Shenhong Chemical Industry Co., Ltd. |
| Solvay S.A. |
| Rongyuan Chemical Co., Ltd. |
| Shaanxi Fuhua Chemical Co., Ltd. |
| Nippon Chemical Industrial Co., Ltd. |
| American Elements |
| NaFine Chemical Industry Group Co., Ltd. |
| Tessenderlo Group |
| Others |
Supply Flow & Price Mechanics
REACH registration deadlines gate both European market access and price differentiation, compressing the supplier base toward ISO 9001-certified producers who command premiums while uncertified competitors retreat to spot markets in Asia and Latin America.
Pricing Analysis
Long-term offtake contracts with natural gas indexation dominate procurement between Sichuan producers and Indian textile buyers, insulating volume commitments from energy volatility while spot transactions in mining chemicals track iron-content specifications. Price differentiation hinges on certification grade and purity documentation, with low-iron mining grades capturing substantial premiums over standard flake formulations. Pricing pressure stems from enzymatic depilatory substitution in European tanneries under EU Green Deal compliance, compressing margins for standard-grade suppliers. Small leather processors in Bangladesh exhibit the highest price sensitivity, whereas Chilean copper concentrators prioritize specification compliance over unit cost.
Supply Chain Analysis
Yangtze River basin logistics chokepoints constrain flake-grade export flows from Sichuan production clusters, forcing buyers to maintain buffer inventories during monsoon-season disruptions. Supply concentrates in China, India, and Germany, with raw material dependencies on sodium sulfate feedstock, metallurgical coke reductant, and natural gas for process heat. Single-source vulnerability runs through western China's chemical corridor, where concentrated reduction capacity creates geographic exposure for international buyers. Distribution feeds from integrated alkali platforms through chemical distributors to end-use tanneries and mining operations, with direct procurement eroding traditional trading margins in Ahmedabad and Chennai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified laboratory capacity for batch-level purity certification represents the critical scarce capability, separating REACH-compliant suppliers from commodity competitors as European textile dye houses demand documentation rigor that smaller producers cannot satisfy.
For Market Incumbents: Shield European textile market share by accelerating captive testing laboratory investments ahead of ECHA's updated substance evaluation protocols, while consolidating procurement relationships in Gujarat's tannery belt through technical service bundling that resists disintermediation pressure from regional consultants. For New Entrants and Emerging Players: Anchor in Bangladesh's garment chemical supply chain where specification requirements remain less stringent than Indian BIS certification standards, penetrating through granule formulations for vat-fed continuous processing lines while building volume credibility for eventual European qualification. For Investors and Strategic Acquirers: REACH registration deadline acceleration reshapes the acquisition landscape toward integrated alkali platforms with captive reduction capacity and existing laboratory infrastructure, positioning these assets for sustained premium capture as compliance costs filter out commodity competitors; monitor ECHA substance evaluation queue depth as the signal for timing entry into European supply channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sodium Sulfate Feedstock | Captive supply of reduction feedstock insulates Solvay and Shenhong from commodity chemical price swings. |
| Skid-Mounted Purification Unit Deployment | On-site iron removal at Chilean mine mouths eliminates transport costs for low-iron grades. |
| ISO 9001 Certification Acceleration | Twelve-to-eighteen-month compliance timelines filter smaller Chinese producers from multinational buyer pools. |
| Long-Term Supply Agreement with Mining Distributors | Peruvian copper concentrators lock in automated dosing compatibility through dedicated solution-grade contracts. |
| Joint Venture in Bangladesh Textile Belt | Surplus flake capacity from India finds absorption in Dhaka-Chittagong garment chemical supply chains. |
Methodological Framework
The analysis maps leather processing, mining flotation, textile dyeing, and pulp applications, each validated through procurement managers at tanneries, technical directors at mining chemical distributors, and plant managers at integrated alkali facilities, combining primary interviews with customs trade data, Cefic chemical industry reports, SEC 10-K filings, and BIS certification records through bottom-up volume triangulation and top-down market sizing reconciliation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeling across grade tier, end-use industry, packaging format, and regional production hub. CAGRs derive from slope analysis of annualized growth trajectories, incorporating energy cost trajectories for reduction processes and regulatory timeline acceleration for REACH compliance as industry-specific forecast inputs.
Material uncertainties — energy price volatility, enzymatic substitution penetration rates, and REACH evaluation timeline shifts — sit outside the modeled envelope, with forecasts reflecting assumptions about certification completion rates and tannery equipment retrofit adoption. Practitioners should keep alternative scenarios live as EU Green Deal enforcement intensity and Bangladesh textile migration patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Encapsulated Sodium Bicarbonate Market
Bulk Chemicals
Benzyl Chloride Market
Bulk Chemicals
United States Fumaric Acid Market
Bulk Chemicals
North America and Europe Palm Derivatives Market
Bulk Chemicals
Global Lithium Carbonate Market
Bulk Chemicals
Global Boric Acid Market
Bulk Chemicals
Sodium Hydrosulfide Market
Bulk Chemicals
North America Carbon Black Market
Bulk Chemicals
Europe Hydrogen Bromide Market
Bulk Chemicals
Bio-Succinic Acid Market
Bulk Chemicals
Valeric Acid Market
Bulk Chemicals
Metallurgical Coke Market
Bulk Chemicals
Para Nitrophenol Market
Bulk Chemicals
Barium Nitrate Market
Bulk Chemicals
Asia Pacific Dry PVC Compound Market
Bulk Chemicals
Barium Chloride Market