
 Plastic Pigments Market | 2026-2036
Plastic Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Pigments Market Intelligence
The EU's Regulation (EU) No 10/2011 for plastic materials intended for food contact is bifurcating the market between certified, high-purity grades and standard industrial grades. Clariant leverages its portfolio of food-contact-approved pigments to serve the premium packaging segment. BASF SE specializes in high-performance organic and inorganic pigments for demanding automotive applications. Cabot Corporation dominates the carbon black pigment category, essential for conductivity and UV protection in plastics.
Plastic pigments are insoluble organic or inorganic colorants dispersed within a polymer matrix to impart color. These materials are defined by properties like heat stability and lightfastness, which determine their suitability for processes like extrusion or injection molding. Inorganic pigments, including titanium dioxide and iron oxides, constitute the largest volume segment due to cost-effectiveness. The packaging materials application remains the dominant end-use, while automotive components demand high-performance organic and effect pigments for superior aesthetics.
The regulatory environment is defined by controls on heavy metal content and chemical safety, enforced by bodies like the US EPA and Europe's ECHA. In China, national GB standards for food-contact and toy safety dictate permissible pigment formulations, influencing market access. Stakeholder decisions will center on balancing performance requirements with the escalating need for circular economy-compatible and bio-based pigment solutions.
Market Dynamics
The central dynamic in the plastic pigments market is the tension between the automotive industry's demand for high-performance aesthetic effects and the stringent regulatory frameworks, like the EU's REACH, governing chemical safety and environmental impact.
Growth Catalysts
- Automotive Lightweighting:Demand from automotive OEMs for lightweight plastic components with premium finishes, such as metallic and pearlescent effects, drives consumption of high-performance and special effect pigments.
- Food-Contact Regulations:The enforcement of standards like the EU's Regulation (EU) No 10/2011 creates a distinct, high-value market for certified pigments used in food packaging, commanding premium pricing.
- Polymer Production in China:China's status as the world's largest producer and consumer of polymers provides a massive, captive demand base for commodity and specialty plastic pigments across various end-use industries.
Market Restraints
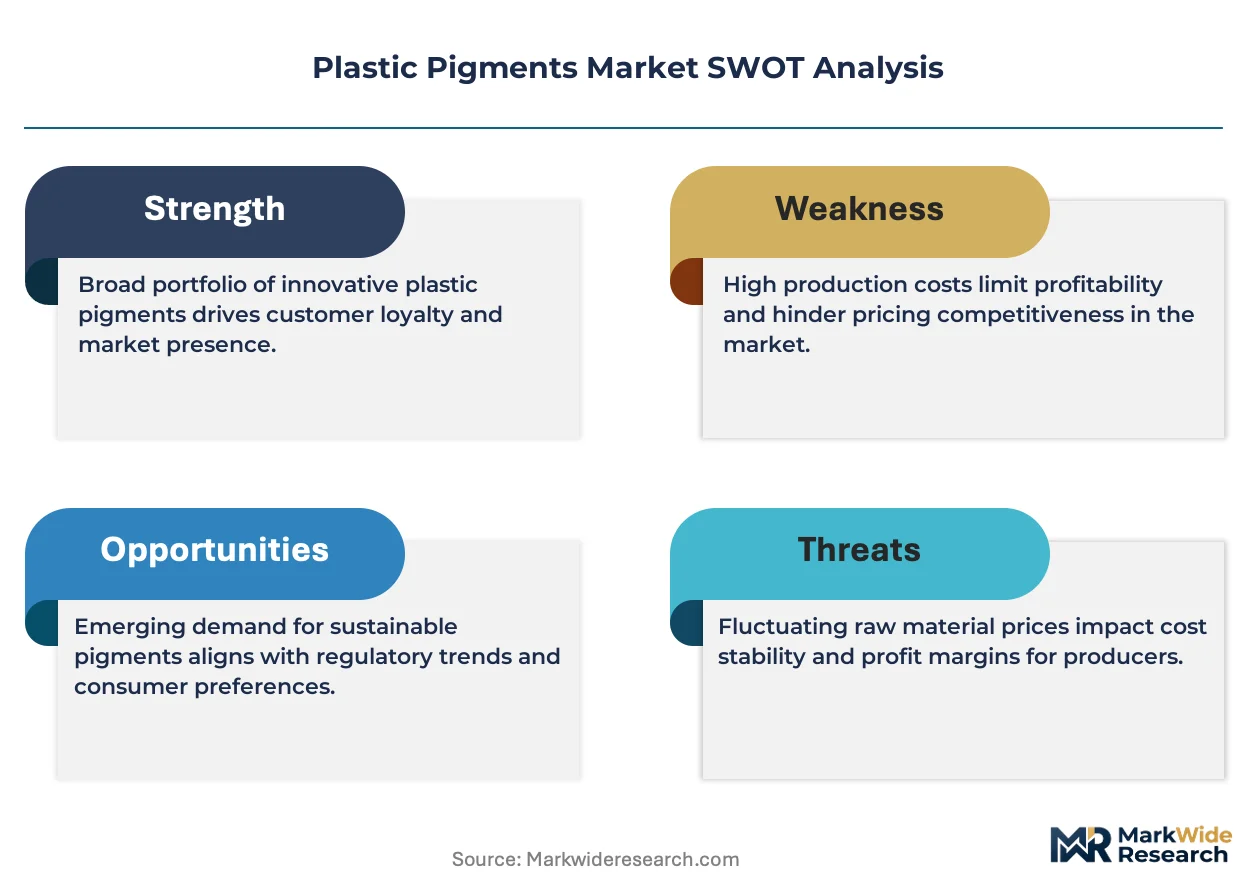
- Raw Material Volatility:Fluctuations in the cost and availability of key feedstocks, particularly titanium dioxide and complex organic intermediates, directly impact pigment manufacturing costs and final pricing.
- Heavy Metal Restrictions:Regulations such as the EU's RoHS directive, which limit the use of lead, cadmium, and other heavy metals, force costly reformulation of many traditional, cost-effective inorganic pigments.
- Performance-Cost Trade-off:A persistent technical gap exists between low-cost, high-volume inorganic pigments with limited heat stability and the expensive, high-performance organic pigments required for demanding engineering plastics.
Strategic Opportunities
- Circular Economy Pigments:Developing pigment formulations that are compatible with recycled polymer streams and do not interfere with automated sorting processes, such as NIR-detectable black pigments.
- Functional Pigment Integration:Expanding into pigments that offer properties beyond coloration, including laser-marking additives, temperature-indicating pigments, and materials that enhance UV or thermal stability.
- Bio-Polymer Coloration:Formulating pigments specifically designed for bio-based plastics like PLA and PHA, addressing unique challenges related to their lower processing temperatures and chemical sensitivities.
Industry Challenges
- Certification Timelines:The protracted and expensive process of obtaining food-contact certifications from bodies like the FDA or EFSA creates a significant barrier to entry and slows the commercialization of new pigment technologies. *Supply Chain Transparency: Verifying the provenance of raw materials to comply with sustainability mandates and conflict mineral regulations adds complexity and cost to the supply chain for global pigment manufacturers.
- Color Standardization Gaps:A lack of globally harmonized color measurement standards across different polymer types and processing methods leads to inconsistencies and disputes between suppliers and end-users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Pigments Market |
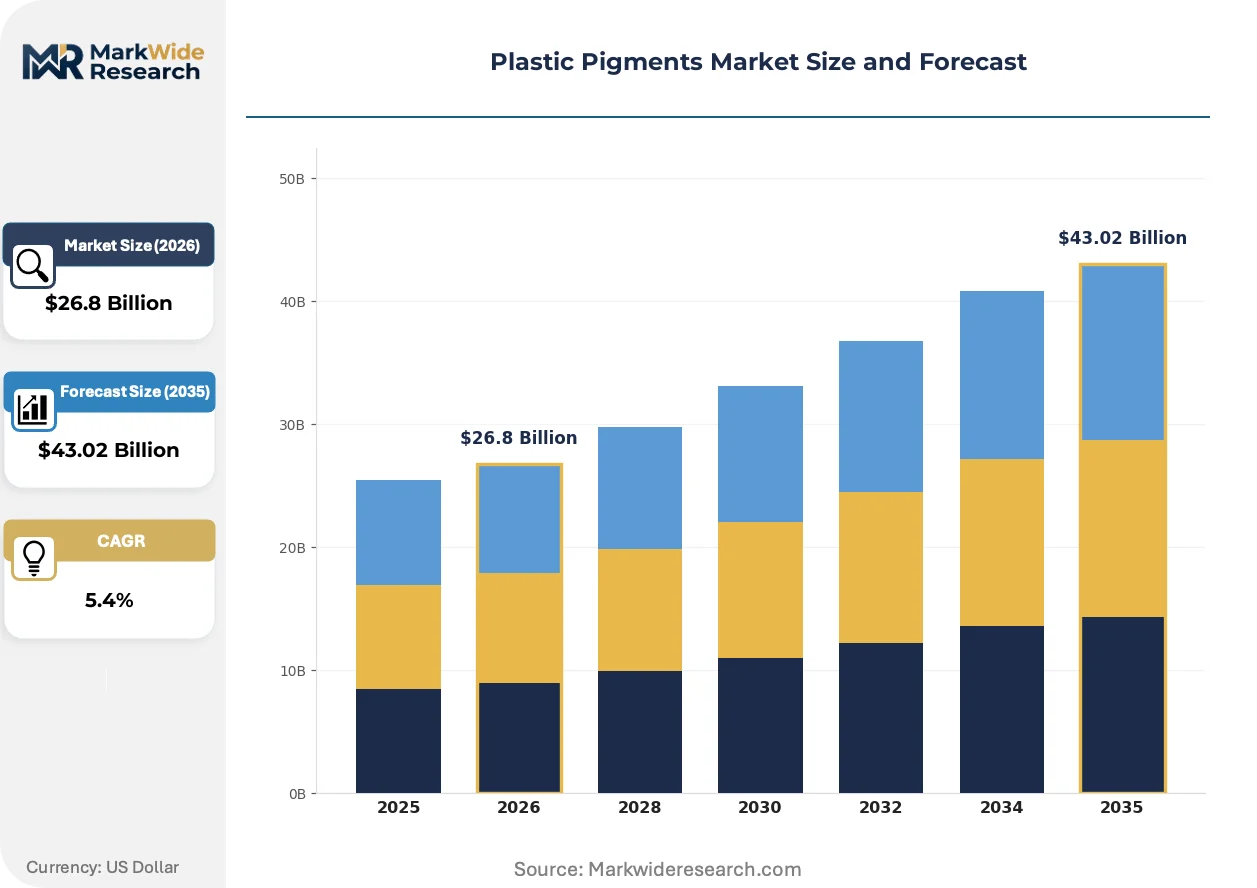
| Market Size in 2026 | $26.8 Billion |
| Market Size in 2035 | $43.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Pigments, Inorganic Pigments, Dye-Based Pigments, Fluorescent Pigments, Pearlescent Pigments Application: Packaging Materials, Electrical & Electronics, Automotive Components, Consumer Goods, Construction Materials End User: Polymer Manufacturers, Plastic Fabricators, Coating Companies, Composite Producers, Masterbatch Suppliers Form: Powder, Granules, Liquid, Paste, Pellets |
| Companies Covered | Lanxess, Cabot Corporation, BASF SE, Huntsman Corporation, Sun Chemical, Clariant, Avient Corporation, Heubach GmbH, DIC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Pigments Market Strategic Shifts & Innovations
The market's evolution is defined by a dual pursuit of sustainability and enhanced functionality. Innovation is concentrating on developing pigments that not only comply with environmental regulations but also add tangible performance value beyond simple coloration.
High-performance effect pigments, including pearlescent and metallic flakes, deliver unique visual aesthetics that are critical for product differentiation. The automotive and premium consumer goods sectors are the primary adopters, using these pigments to create distinctive finishes. This trend is miniaturizing the pigment particles themselves, enabling the creation of thinner, more brilliant coatings and complex color-flop effects within the polymer matrix.
China's national GB standards for materials in contact with food and for toy safety create a distinct regulatory hurdle for market access. These rules compel global manufacturers to develop specific, compliant formulations to participate in the country's vast consumer market. The packaging and electronics sectors are most impacted, driving a shift toward pre-certified masterbatches and pigments that have undergone testing by Chinese authorities.
A significant behavioral shift among brand owners involves specifying pigments that are compatible with modern recycling infrastructure. This preference for "design-for-recycling" is leading to the substitution of colorants, like conventional carbon black in PET packaging, that hinder automated NIR sorting processes. This change is most pronounced in Europe, where packaging producers are aligning with EU Green Deal objectives and circular economy principles.
Plastic Pigments Market Segmentation
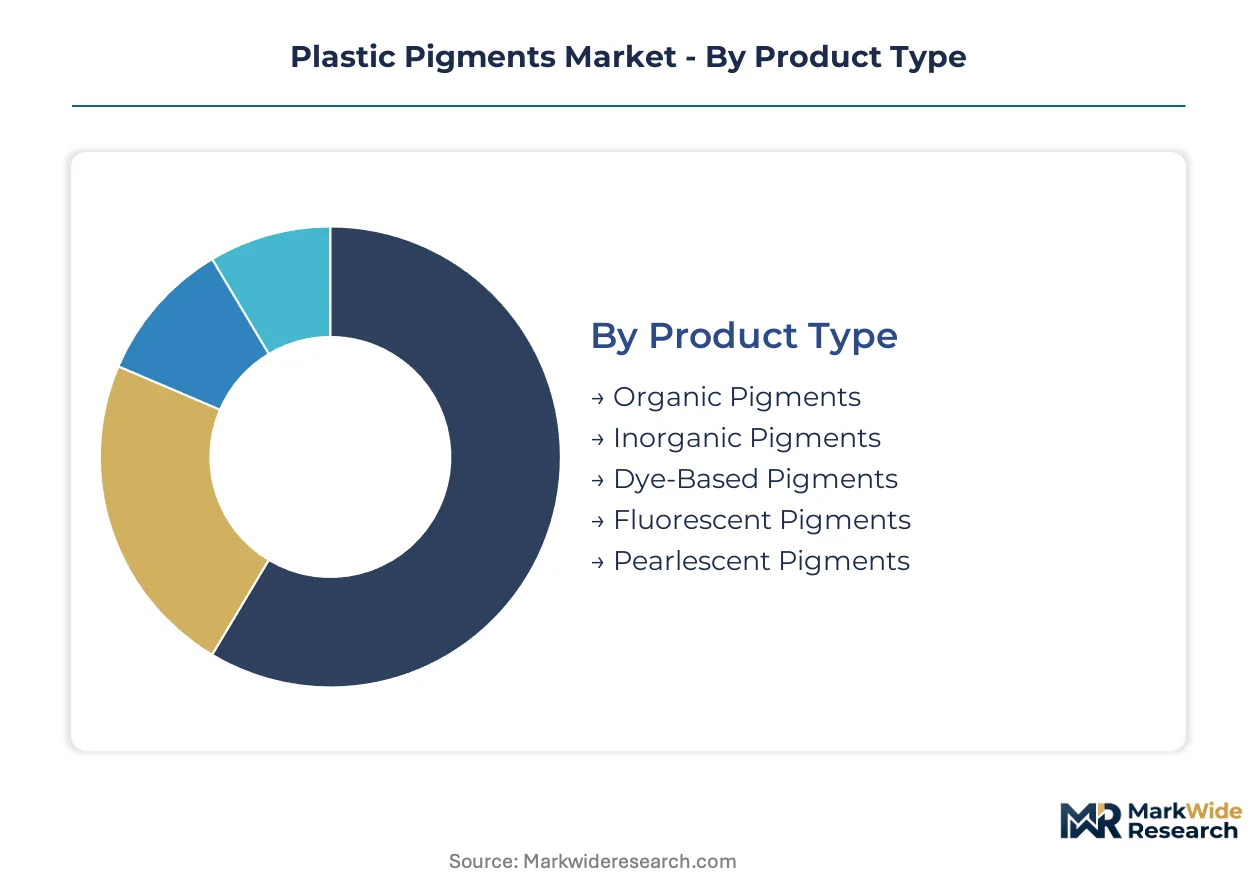
The plastic pigments market comprises distinct product types, applications, end-users, and physical forms. Understanding these divisions helps stakeholders identify value pockets and navigate specific regulatory landscapes. Each segment offers unique performance characteristics and market dynamics.
Product Type:
Geographic production often dictates primary markets, with some pigment categories serving local polymer manufacturing and others functioning as export-driven specialty items.
- Organic Pigments:These carbon-based compounds offer high tinting strength and brilliant colors, essential for aesthetic applications in consumer goods and automotive interiors. European and North American automotive sectors drive demand for vibrant, high-performance hues.
- Inorganic Pigments:Comprising metal oxides like titanium dioxide, these pigments provide excellent opacity, heat stability, and weather fastness at lower costs. China's vast polymer production drives significant volume consumption across commodity plastics.
- Dye-Based Pigments:Soluble colorants offering high transparency and intense color, often used in clear plastics for bottles or films.
- Fluorescent Pigments:These pigments absorb ultraviolet light and re-emit it as visible light, creating vivid effects for safety applications and toys.
- Pearlescent Pigments:Mica flakes coated with metal oxides impart shimmering, iridescent effects, highly valued in premium packaging and automotive finishes.
Inorganic Pigments commands the established base. The steepest expansion runs through Pearlescent Pigments.
Application:
Application segments reflect distinct performance requirements and regulatory compliance needs, influencing pigment selection and formulation across diverse end-use sectors.
- Packaging Materials:This largest end-use for plastic pigments is driven by brand differentiation and food contact safety. EU 10/2011 compliance is critical for food packaging pigments in Europe.
- Automotive Components:High-performance organic and effect pigments are crucial for plastic parts, requiring superior heat stability, lightfastness, and aesthetic appeal. OEMs in Germany and Japan demand stringent consistency.
- Electrical & Electronics:Pigments for this sector need flame retardancy compatibility and UV stability for casings and connectors.
- Consumer Goods:Includes toys and household items, where color durability and safety standards like China's GB standards are paramount.
- Construction Materials:Pigments provide color and UV protection for PVC profiles and pipes, requiring long-term weather resistance.
Packaging Materials represents the largest volume consumption. Automotive Components are gaining share fastest as aesthetics become prioritized.
End User:
The end-user landscape shows varied value addition points within the plastic pigments supply chain, from raw polymer production to specialized compounding.
- Polymer Manufacturers:These companies integrate pigments directly into virgin polymer resins, offering pre-colored materials to downstream processors. Large-scale operations in China and the US drive significant captive demand.
- Masterbatch Suppliers:Specializing in highly concentrated pigment formulations, masterbatch suppliers provide efficient coloring solutions for plastic fabricators. Their expertise serves a diverse customer base.
- Plastic Fabricators:These firms process pre-colored resins or masterbatches into finished plastic products through molding or extrusion.
- Coating Companies:Use pigments for plastic film lamination or specialized plastic finishes, complementing their primary surface coating focus.
- Composite Producers:Pigments are incorporated into fiber-reinforced plastics and other composite materials for aesthetics and UV protection.
Polymer Manufacturers form the base of consumption. Masterbatch Suppliers are expanding quickly by offering specialized services.
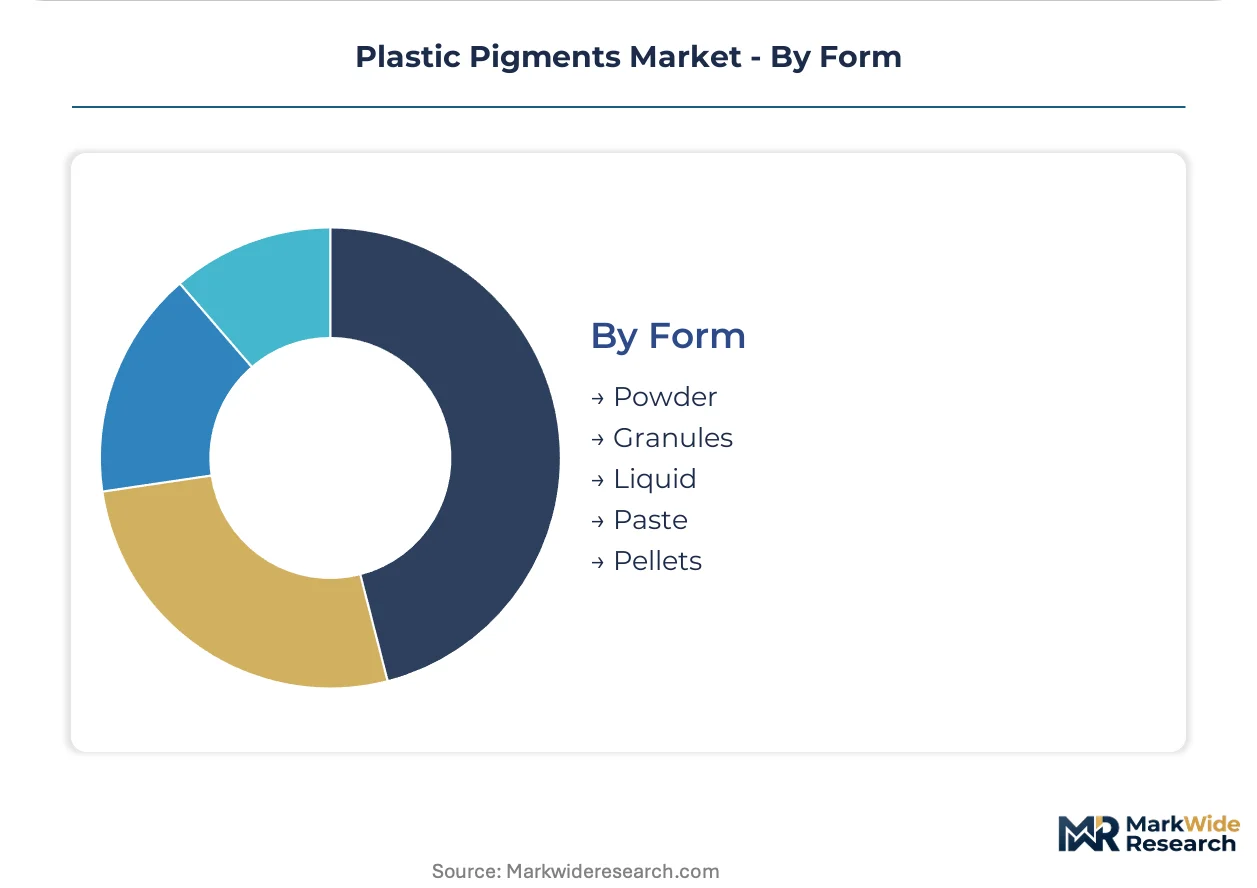
Form:
The physical form of plastic pigments significantly impacts processing efficiency, dispersion quality, and suitability for various polymer types and manufacturing techniques.
- Powder:This traditional form offers cost-effectiveness and high pigment concentration, requiring careful dispersion to avoid agglomeration. Powder pigments are widely used across commodity plastics manufacturing.
- Liquid:Liquid pigment dispersions provide excellent dispersibility and ease of dosing, beneficial for automated coloring systems and precise color matching in engineering plastics. Demand is rising in precision molding.
- Granules:Granular pigments, often pre-dispersed in a polymer carrier, reduce dusting and improve handling safety during processing.
- Paste:Pigment pastes offer good dispersion, typically used in specific applications like plastisols or PVC compounding.
- Pellets:Pelletized pigments, similar to masterbatches, provide a clean, easy-to-handle form ensuring consistent color distribution in molding.
Powder pigments maintain the highest volume due to their versatility. Liquid forms are climbing the fastest, driven by automation trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta in China, a critical manufacturing and logistics hub, underwrites the region's dominant role in global plastic pigment consumption. Regional dynamics reflect diverse regulatory pressures and industrial growth patterns.
China
China's vast polymer production and consumer goods industries drive immense demand for both commodity and specialty plastic pigments. National GB standards for food-contact materials and toy safety influence permissible pigment formulations. Industrial clusters around Shanghai and Guangzhou require compliant, high-volume pigment supply.
Germany
The Port of Hamburg, a major European trade gateway, facilitates the import and export of advanced plastic pigments for Germany's manufacturing sector. Automotive OEMs in Germany demand high-performance organic and effect pigments for superior aesthetics. The EU's REACH framework mandates stringent chemical safety and environmental impact assessments. Chemical production centers in Ludwigshafen and Leverkusen innovate in sustainable pigment solutions.
United States
The Port of Houston, a critical petrochemical hub, supports the extensive chemical and polymer manufacturing base across the United States. Strong demand from packaging and automotive sectors drives consumption of both inorganic and organic pigments. The US EPA regulates chemical substances, influencing pigment composition and manufacturing processes. Major plastic compounding facilities in the Midwest and Southeast integrate diverse pigment types.
Japan
Tokyo Bay, a dense industrial and logistics corridor, underpins Japan's advanced materials and automotive industries. Japanese automotive manufacturers prioritize lightfastness and heat stability for plastic components. METI guidelines encourage the development of eco-friendly and high-performance pigment technologies. Precision molding operations in Aichi Prefecture utilize high-performance organic pigments.
India
Mundra Port, a significant trade gateway, supports India's expanding manufacturing base, including its growing plastics processing industry. Packaging materials and consumer goods sectors are driving demand for cost-effective and compliant plastic pigments. BIS standards for various plastic products ensure quality and safety in pigment applications. Industrial corridors of Gujarat and Maharashtra demonstrate rising pigment consumption.
Plastic Pigments Market Key Industry Players
Listed leaders compete with private specialists across the full spectrum of plastic pigment production, from basic inorganic compounds to advanced effect pigments. The market exhibits a tiered structure, with a few large multinational chemical companies dominating high-volume segments and numerous specialized firms serving niche applications. Strategic archetypes include integrated chemical giants, focused pigment producers, and masterbatch specialists. Dominant competitive moves involve portfolio diversification into sustainable offerings and strategic partnerships for regional market access.
Specialists in high-performance and functional pigments, such as Switzerland-based Clariant AG, exemplify innovation in food-contact-approved formulations for premium packaging, addressing stringent regulatory requirements. German chemical conglomerate BASF SE occupies a strong position in high-performance organic and inorganic pigments, catering to demanding automotive applications and other industrial uses requiring superior performance. US-based Cabot Corporation anchors the carbon black pigment category, essential for conductivity and UV protection in plastics, and maintains a significant global footprint in this foundational pigment type.
| Leading Market Players |
|---|
| Lanxess |
| Cabot Corporation |
| BASF SE |
| Huntsman Corporation |
| Sun Chemical |
| Clariant |
| Avient Corporation |
| Heubach GmbH |
| DIC Corporation |
| Others |
Cost & Logistics Intelligence
Long-term supply agreements in the plastic pigments market lock in both supply access and price visibility for high-volume customers. These contracts mitigate raw material volatility for both pigment producers and large-scale polymer manufacturers.
Pricing Analysis
Volume-discount tiering structures dominate the plastic pigments market, rewarding large-scale procurement. Price differentiation stems from certification level, particularly for food-contact approved grades, and specialized performance attributes for automotive applications. Pricing softness reflects raw material volatility and intense competition among commodity pigment producers. Polymer manufacturers and masterbatch suppliers buying in bulk are highly price-sensitive, while specialized automotive OEMs prioritize performance over cost.
Supply Chain Analysis
Extended lead times for specialty pigments often necessitate strategic inventory holding by masterbatch suppliers and large fabricators. Supply concentrates in China, Germany, and the United States, reflecting major chemical production hubs. The industry relies on titanium dioxide, organic intermediates, and carbon black as key raw materials. Commodity price volatility for these inputs presents a significant structural risk. Distribution runs through a network of masterbatch producers and direct sales from pigment manufacturers to polymer processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plastic pigments market presents a service-attach opportunity, with masterbatch formulation and technical support services expanding faster than basic pigment sales. These specialized services provide crucial value-add for complex application requirements and regulatory compliance.
For Market Incumbents:Secure long-term supply contracts for critical raw materials like titanium dioxide to mitigate cost volatility. Expand into bio-based pigment R&D to counter the threat of new sustainable alternatives. Invest in certification for food-contact applications, leveraging this lever to differentiate from smaller players. Consolidate market share through strategic acquisitions of specialized pigment producers.
For New Entrants and Emerging Players:Customized color matching services for niche engineering plastics represent a significant service-layer gap. Focus on developing circular economy-compatible pigments for the European packaging segment, which is highly penetrable due to "design-for-recycling" mandates. Offer transparent supply chain verification as a go-to-market angle to appeal to sustainability-conscious brand owners. Target bio-polymer coloration solutions for emerging bioplastic applications.
For Investors and Strategic Acquirers:Capital is best deployed toward specialized pigment producers with strong intellectual property in functional or sustainable formulations. The long-term viability of this market hinges on innovation in non-toxic and circular economy-compatible solutions. Target masterbatch suppliers with established food-contact certification portfolios as attractive acquisition archetypes. The signal to watch is the rate of regulatory adoption for bio-based plastic mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Reduces environmental impact and ensures compliance with EU Green Deal objectives for chemical production. |
| Capacity Expansion in China | Addresses the immense demand from China's polymer production and consumer goods industries. |
| Portfolio Diversification into Bio-Pigments | Captures emerging opportunities in bio-based plastics like PLA and PHA. |
| Certification Investment for Food Contact | Unlocks premium market segments for packaging materials requiring EU 10/2011 compliance. |
| Strategic Partnership for NIR-Detectable Pigments | Supports brand owners' "design-for-recycling" initiatives in automated sorting processes. |
Research Approach
Initial hypotheses were tested against primary input from pigment R&D directors, polymer procurement leads, and masterbatch formulators, then refined through iterative analysis. This combined in-depth interviews with extensive secondary validation from customs data, chemical industry reports, and company 10-K filings. A robust bottom-up and top-down triangulation approach ensured data consistency.
Variance decomposition identified key market drivers and restraints, informing the analytical framework over the projection horizon. Segmentation dimensions modeled included product type, application, end-user, physical form, and regional regulatory compliance. Compound annual growth rates were derived from historical trends, expert consultations, and projected technological advancements. Forecast inputs included polymer production volumes and regulatory timelines for food-contact materials.
Underlying assumptions cover stable geopolitical conditions and consistent regulatory enforcement, with deviation risk concentrated in raw material supply disruptions or sudden shifts in environmental mandates. Forecasts reflect these assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Iron Oxide Pigments Market
Dyes and Pigments
Acid Dyes Market
Dyes and Pigments
Asia Pacific Hair Colorants Market
Dyes and Pigments
Organic Lake Pigments Market
Dyes and Pigments
Indigo Carmine Market
Dyes and Pigments
Iridescent Pigments Market
Dyes and Pigments
Middle East and Africa Hair Colorants Market
Dyes and Pigments
Aluminum Pigments Market
Dyes and Pigments
Europe Hair Colorants Market
Dyes and Pigments
Photochromic Pigments Market
Dyes and Pigments
Petroleum-Fuel Dyes and Markers Market
Dyes and Pigments
Phthalocyanine Pigments Market
Dyes and Pigments
Carmine Market
Dyes and Pigments
Dyestuff (Black Color) Market
Dyes and Pigments
Erythrosine Market
Dyes and Pigments
Inorganic Cosmetics Pigments Market