
 Malathion Market | 2026-2036
Malathion Market Size, Share, and Industry Trends Forecast 2026-2036
Malathion Market Analysis
The capital-intensity divergence between integrated manufacturers and formulation-only specialists is unwinding competitive stability across the malathion value chain. Bayer AG leverages backward integration into active ingredient synthesis to sustain margin control amid feedstock volatility. UPL Limited anchors its position through geographic dominance in South Asian distribution networks. FMC Corporation differentiates via specialized formulation expertise for public health vector control applications.
Malathion is an organophosphate insecticide synthesized through the reaction of diethyl maleate with O,O-dimethyl phosphorodithioate, yielding a compound with broad-spectrum acetylcholinesterase inhibitory activity against agricultural and public health pests. Its primary commercial purpose centers on cost-effective control of aphids, leafhoppers, and mosquitoes in crop protection and disease vector management programs. Technical grade material commands the dominant volume position, while vector control applications represent the fastest-expanding demand segment as malaria and dengue eradication programs intensify. Liquid formulations occupy the largest share of end-user procurement, though granule formats gain traction in mechanized farming systems where precision application reduces operator exposure.
EPA re-registration reviews under FIFRA impose chronic toxicity and ecological risk benchmarks that reshape product labeling and buffer zone requirements for US market access. India's Central Insecticides Board enforces stringent residue limit protocols under the Insecticides Act that govern both domestic sale and export qualification for agrochemical manufacturers. The EU's REACH framework and persistent organic pollutant screening criteria constrain formulation imports and drive reformulation investments among suppliers serving European public health agencies. Stakeholders must monitor regulatory divergence between jurisdictions to align product development pipelines with divergent toxicity acceptance thresholds.
Market Dynamics
EPA re-registration requirements under FIFRA are compressing product lifecycles and forcing reformulation investments that reshape competitive positioning across the malathion value chain. Active ingredient manufacturers face chronic toxicity benchmarks that elevate compliance costs while vector control agencies demand residue profiles compatible with integrated pest management protocols.
Growth Catalysts
- Indian vector control mandates:Government malaria and dengue eradication programs sustain procurement volumes for public health applications. State-level spraying contracts anchor demand predictability.
- REACH compliance investments:European reformulation requirements are accelerating product stewardship capabilities among exporters. Technical grade suppliers upgrade purification processes to meet persistent organic pollutant screening criteria.
- Precision application equipment:Drone-mounted spraying systems in Brazilian soybean farming reduce operator exposure while expanding treatable acreage per labor hour.
Market Restraints
- Phosphorus pentasulfide feedstock volatility:Key intermediate cost swings compress formulation margins during sulfur price spikes.
- Chinese technical grade concentration:Three provinces dominate active ingredient synthesis, creating supply vulnerability during environmental enforcement surges.
- Pyrethroid substitution in residential pest control:Lower mammalian toxicity profiles displace malathion in consumer-facing aerosol formulations.
Strategic Opportunities
- Ethiopian agricultural extension programs:Smallholder grain protection education creates first-time insecticide adoption in highland farming communities.
- IR-4 minor crop residue clearances:US specialty crop registration expansion opens tree nut and vegetable applications previously blocked by data gaps.
- WHO prequalification pathways:Vector control product listing for indoor residual spraying qualifies suppliers to multilateral procurement pools.
Industry Challenges
- Acute toxicity study completion timelines:EPA data call-ins demand 18-month neurotoxicity assessments that stall label amendments.
- Legacy formulation equipment incompatibility:Existing spray tank corrosion requires stainless steel retrofit investments for emulsifiable concentrate users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malathion Market |
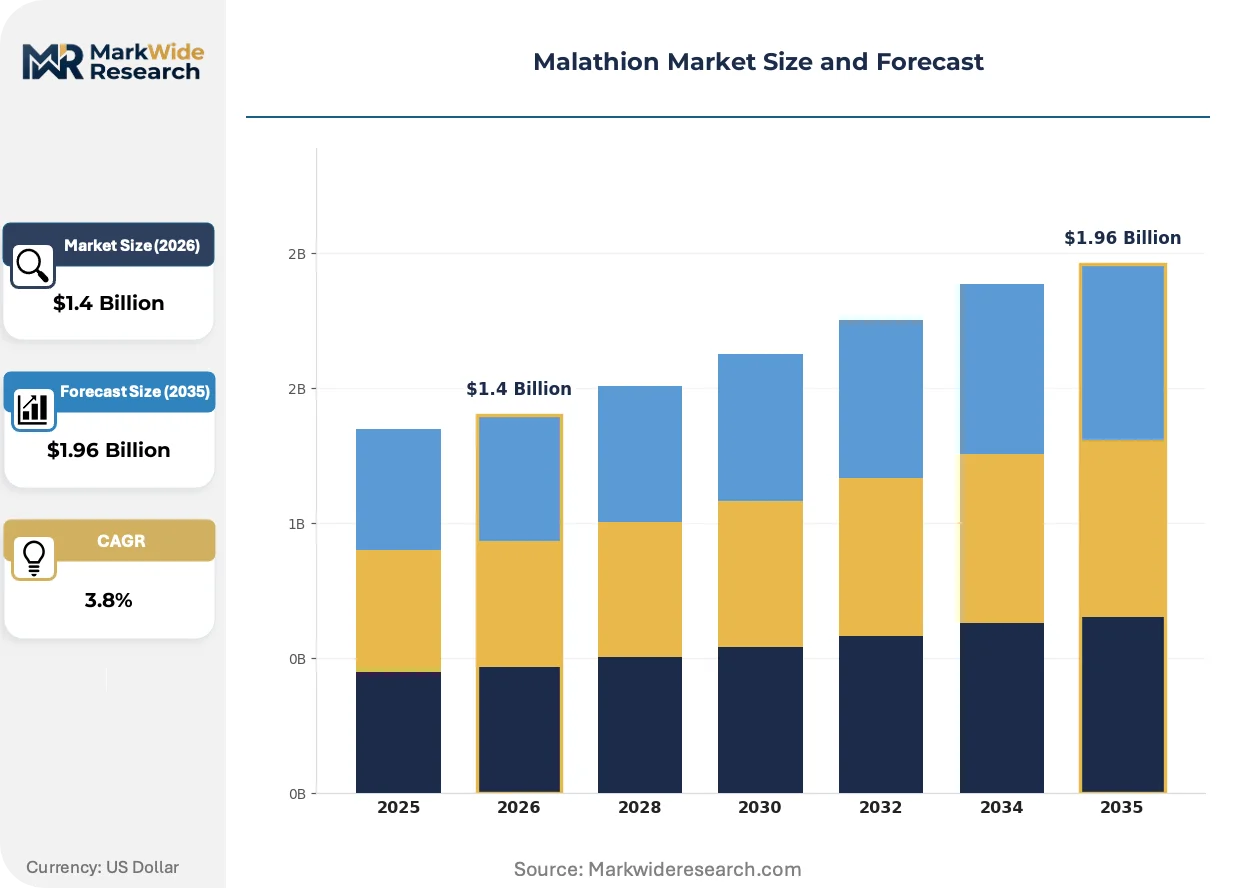
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $1.96 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Technical Grade, Formulation, Liquid, Granules Application: Agricultural Pesticide, Public Health Insecticide, Residential Use, Vector Control End User: Agriculturists, Pest Control Operators, Farmers, Government Agencies Distribution Channel: Online Retail, Distributors, Agrochemical Stores, Wholesale |
| Companies Covered | Bayer AG, Syngenta AG, BASF SE, FMC Corporation, Dow Agrosciences, Sumitomo Chemical Co., Ltd., UPL Limited, ADAMA Agricultural Solutions Ltd., American Vanguard Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malathion Market Emerging Trajectories
Formulation chemistry and application methodology are converging to reduce environmental persistence while maintaining acetylcholinesterase inhibitory efficacy against target pest populations. Product development pipelines prioritize residue profile optimization over raw toxicity metrics.
Microencapsulation technology is supplanting conventional emulsifiable concentrates in aerial application programs. Brazilian cotton growers and Southeast Asian rice cooperatives are adopting polymer-coated granules at accelerating rates. This shift is compressing the market share of solvent-heavy formulations while extending residual activity windows and reducing non-target organism exposure.
EPA's ecological risk assessments under FIFRA are mandating expanded aquatic toxicity data packages for reregistration eligibility. Buffer zone requirements for surface water protection are expanding from 25 to 100 feet in sensitive watersheds. Agricultural applicators in the Corn Belt and California Central Valley are responding with precision nozzle selection and drift reduction adjuvant investments.
Public health procurement is consolidating toward prequalified supplier lists with integrated resistance monitoring capabilities. National malaria control programs in sub-Saharan Africa and South Asia now require entomological surveillance data as contract performance conditions. This behavioral pivot favors formulation specialists with captive field research infrastructure over commodity trading houses.
Malathion Market Segmentation
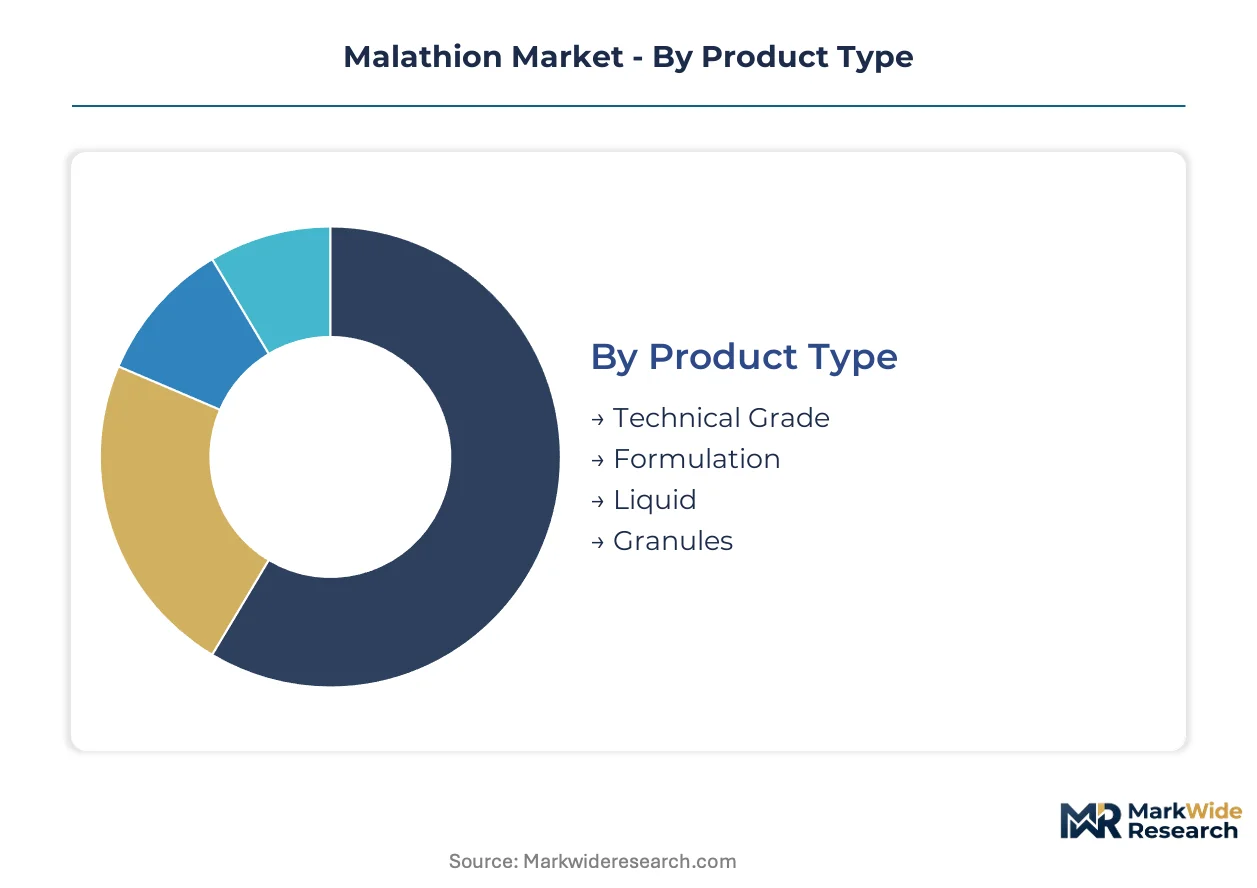
Malathion's regulatory fragmentation across EPA, REACH, and India's Insecticides Act creates divergent product specifications that reshape how manufacturers segment their portfolios. Technical grade purity requirements and formulation registration pathways vary sharply by jurisdiction, forcing suppliers to maintain parallel product lines.
Product Type:
EPA chronic toxicity benchmarks under FIFRA and REACH persistent organic pollutant screening impose divergent purity thresholds that segment the value chain into distinct compliance tiers.
- Technical Grade:Active ingredient synthesis yields diethyl maleate-derived material at 95-98% purity for downstream formulation. Indian technical grade suppliers dominate volume throughput, serving both domestic agrochemical manufacturers and export markets facing REACH-compliant purification upgrades.
- Formulation:Emulsifiable concentrates, wettable powders, and ultra-low volume preparations blend technical grade with surfactants and carriers. Brazilian cotton cooperatives and Southeast Asian rice farming systems drive procurement for aerial application compatibility.
- Liquid:Solvent-based emulsifiable concentrates and aqueous solutions occupy the largest procurement share among end-users. Public health spraying programs in India and sub-Saharan Africa specify liquid formats for thermal fogging and ultra-low volume equipment.
- Granules:Polymer-coated and clay-based granule formats reduce operator exposure in mechanized farming. Precision application equipment in Brazilian soybean operations accelerates adoption for reduced drift and extended residual windows.
Technical grade handles the majority of throughput; granules are expanding most quickly on share as precision agriculture equipment proliferates.
Application:
Cost-tier differentiation separates commodity agricultural procurement from premium public health contracts with entomological surveillance requirements.
- Agricultural Pesticide:Broad-spectrum control of aphids, leafhoppers, and caterpillars in grain, oilseed, and cotton production. Indian smallholder farming and Brazilian large-scale soybean operations anchor procurement volumes for foliar spray programs.
- Public Health Insecticide:Malaria and dengue vector control through indoor residual spraying and larviciding. WHO prequalification pathways and national malaria control program contracts impose resistance monitoring obligations that favor integrated formulation specialists.
- Residential Use:Consumer-facing aerosol and ready-to-use formulations for household pest control. Pyrethroid substitution is compressing this segment as lower mammalian toxicity alternatives displace malathion in retail channels.
- Vector Control:Specialized applications targeting mosquitoes, flies, and disease vectors in urban and peri-urban environments. Government procurement consolidation toward prequalified supplier lists is reshaping competitive access.
Agricultural pesticide procurement absorbs the dominant cost-tier volume; vector control contracts command the steepest expansion trajectory as disease eradication programs intensify.
End User:
Customer-type segmentation reflects divergent technical sophistication, with government agencies and pest control operators demanding integrated resistance data while farmers prioritize unit economics.
- Agriculturists:Commercial farming enterprises with mechanized application infrastructure. Brazilian cotton growers and Southeast Asian plantation operators specify microencapsulated formulations for aerial spraying compatibility.
- Pest Control Operators:Licensed applicators serving commercial and residential contracts. EPA certification requirements and buffer zone compliance training differentiate this segment from farmer self-application.
- Farmers:Smallholder and mid-scale producers purchasing through agrochemical retail networks. Indian state subsidy programs and extension education shape procurement patterns in highland grain farming communities.
- Government Agencies:National malaria control programs, vector control boards, and agricultural extension services. Contract performance conditions now mandate entomological surveillance data and resistance monitoring capabilities.
Farmers move the highest unit volumes through retail channels; government agencies are climbing fastest on contract value as procurement consolidates toward prequalified supplier pools.
Distribution Channel:
Supply concentration in Chinese technical grade synthesis and Indian formulation capacity shapes channel economics, with distributor networks capturing margin in fragmented last-mile delivery.
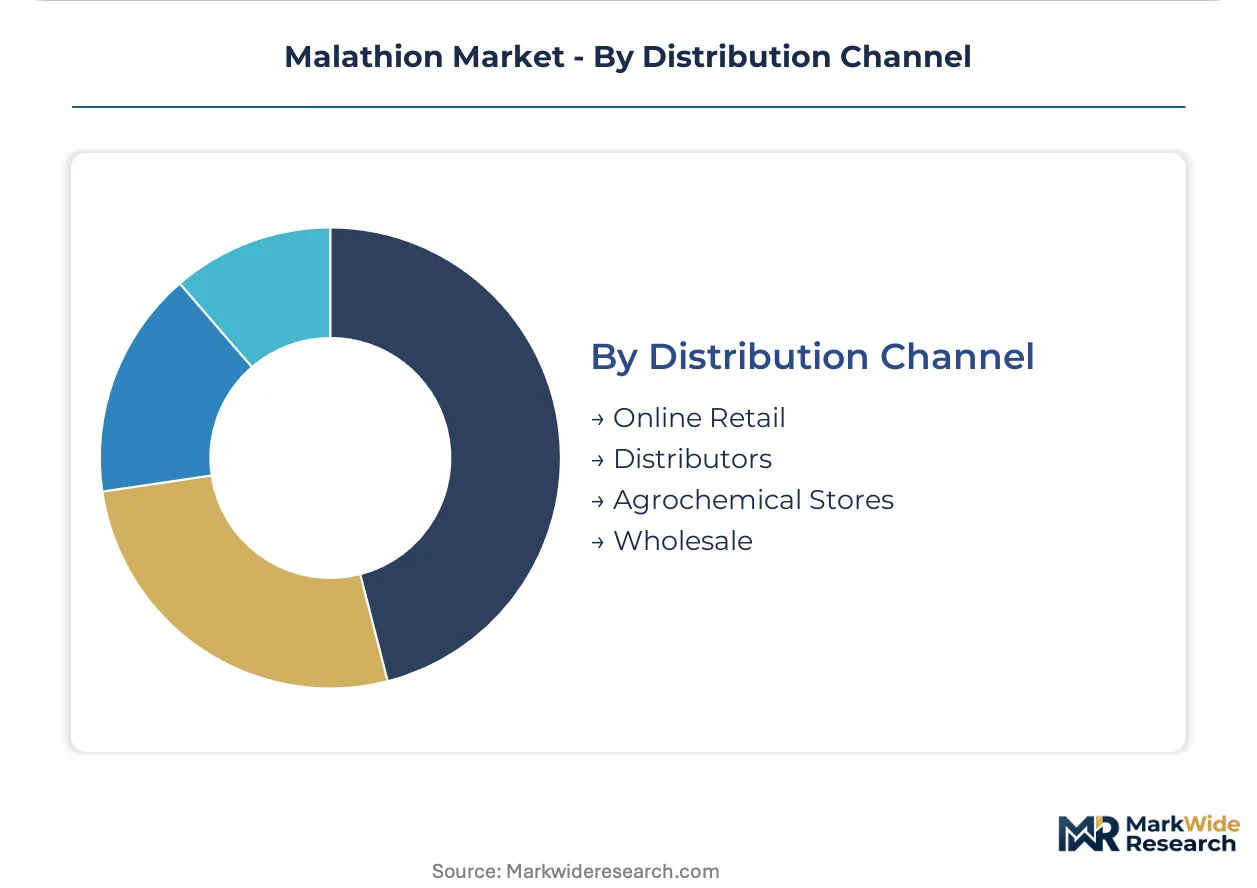
- Online Retail:E-commerce platforms serving residential and small-scale agricultural purchasers. Regulatory restrictions on restricted-use pesticide shipping constrain growth relative to general agricultural inputs.
- Distributors:Regional agrochemical wholesalers with warehousing and credit extension capabilities. Indian distribution networks dominate South Asian market access, with state-level licensing requirements creating barrier to entry.
- Agrochemical Stores:Brick-and-mortar retail with technical advisory services for farmer customers. Extension relationships and demonstration plot programs anchor loyalty in Ethiopian and Indian smallholder markets.
- Wholesale:Volume procurement for government tenders and large farming cooperatives. Tender specifications for WHO-prequalified material and resistance monitoring data favor established formulation specialists.
Distributors handle the majority of throughput; wholesale channels are gaining share fastest as government vector control procurement consolidates toward direct contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smallholder farmers in India exhibit extreme price sensitivity, purchasing through subsidized retail channels, while Brazilian commercial operators absorb premium formulation costs for aerial application compatibility. Government vector control programs in sub-Saharan Africa represent intermediate elasticity, balancing WHO prequalification requirements against budget constraints.
United States
Corn Belt and California Central Valley agricultural applicators drive emulsifiable concentrate procurement for broad-spectrum insect control. EPA reregistration reviews under FIFRA mandate expanded aquatic toxicity data packages and 100-foot buffer zones in sensitive watersheds. Precision nozzle selection and drift reduction adjuvant investments concentrate in Iowa and Illinois farming cooperatives.
India
State-level malaria and dengue eradication programs sustain public health procurement volumes through national vector control mandates. The Central Insecticides Board enforces stringent residue limit protocols under the Insecticides Act governing domestic sale and export qualification. Formulation capacity clusters in Maharashtra and Gujarat serve South Asian distribution networks with state-level licensing barriers.
Brazil
Large-scale soybean and cotton operations adopt microencapsulated formulations and polymer-coated granules for mechanized precision application. ANVISA registration requirements align with WHO prequalification pathways for vector control product listing. Drone-mounted spraying systems expand treatable acreage per labor hour across Mato Grosso and Goiás farming belts.
China
Three provinces dominate active ingredient synthesis, creating supply vulnerability during environmental enforcement surges under MEE oversight. Technical grade purification upgrades target REACH-compliant persistent organic pollutant screening criteria for European export qualification. Yangtze River Delta chemical clusters face feedstock volatility from phosphorus pentasulfide intermediate cost swings.
Germany
Bayer AG leverages backward integration into active ingredient synthesis to sustain margin control amid European regulatory fragmentation. ECHA REACH framework and persistent organic pollutant screening constrain formulation imports, driving reformulation investments among suppliers serving public health agencies. Industrial chemical expertise concentrates in North Rhine-Westphalia and BASF SE's Ludwigshafen operations.
Malathion Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the malathion value chain. Integrated manufacturers with captive active ingredient synthesis compete against formulation-only specialists dependent on technical grade procurement. Three strategic archetypes dominate: backward-integrated multinationals, geographic distribution anchors, and public health formulation specialists. Competitive moves center on purification process upgrades for regulatory compliance and microencapsulation technology licensing for aerial application markets.
Among integrated agrochemical conglomerates, Bayer AG exemplifies backward-integrated control over synthesis and margin stability. UPL Limited anchors geographic dominance through South Asian distribution network density. FMC Corporation occupies a position exemplifying specialized formulation expertise for vector control applications with resistance monitoring capabilities.
| Leading Market Players |
|---|
| Bayer AG |
| Syngenta AG |
| BASF SE |
| FMC Corporation |
| Dow Agrosciences |
| Sumitomo Chemical Co., Ltd. |
| UPL Limited |
| ADAMA Agricultural Solutions Ltd. |
| American Vanguard Corporation |
| Others |
Supply Flow & Price Mechanics
EPA re-registration requirements under FIFRA simultaneously gate supply qualification for US market access and stratify price differentiation across technical grade purity tiers. REACH-compliant purification upgrades for European export markets impose parallel cost thresholds that separate premium-grade suppliers from commodity formulation houses. Buyers in government vector control programs absorb certification-driven premiums while Indian smallholder farmers prioritize subsidized economy-grade procurement through state distribution networks.
Pricing Analysis
After-sales service contracts for resistance monitoring and entomological surveillance drive lifetime value in public health procurement. Three-tier pricing structure across premium, standard, and economy levels segments by technical grade purity and formulation registration breadth. Premium tiers command sustained margins from WHO-prequalified suppliers with integrated field research infrastructure. Price compression runs through economy-grade technical grade channels as Chinese synthesis capacity expands feedstock conversion volumes. Government agencies in malaria control programs exhibit lowest price sensitivity due to prequalification mandates, while Indian retail channel farmers demonstrate highest elasticity to unit cost fluctuations.
Supply Chain Analysis
Strait of Malacca transit routes for phosphorus pentasulfide intermediates underpin formulation cost stability across Southeast Asian manufacturing nodes. Active ingredient synthesis concentrates in China's Jiangsu, Shandong, and Zhejiang provinces, while formulation capacity clusters in India's Maharashtra and Gujarat states. Technical grade production draws from diethyl maleate and O,O-dimethyl phosphorodithioate feedstocks with sulfur price volatility exposure. Single-source vulnerability concentrates in Yangtze River Delta environmental enforcement jurisdictions. Distribution runs through Indian state-level licensed wholesalers with credit extension capabilities for smallholder farmer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Resistance monitoring service contracts and entomological surveillance subscriptions expand faster than technical grade commodity sales, reframing competitive advantage around data-attach revenue streams. Microencapsulation formulation licensing and precision application equipment compatibility represent recurring-revenue layers with superior retention economics.
For Market Incumbents: Consolidate formulation registration portfolios through REACH-compliant purification upgrades and captive microencapsulation technology licensing. Pyrethroid substitution pressure in residential channels demands defensive repositioning toward vector control service contracts with resistance monitoring obligations. Backward integration into phosphorus pentasulfide intermediate sourcing mitigates feedstock volatility compression on standard-grade margins. For New Entrants and Emerging Players: Anchor in Ethiopian agricultural extension programs and highland grain farming communities with first-time insecticide adoption potential. IR-4 minor crop residue clearance pathways in US tree nut and vegetable applications present penetrable regulatory white space. WHO prequalification investment for indoor residual spraying contracts unlocks multilateral procurement pool access with entrenched incumbent bypass. For Investors and Strategic Acquirers: EPA neurotoxicity data call-in deadlines reshape the acquisition landscape toward formulation specialists with completed chronic toxicity dossiers. Long-term viability hinges on regulatory compliance asset durability rather than commodity volume scale. Acquisition target archetype: mid-tier formulation houses with captive field research infrastructure and prequalified supplier status. Signal to watch: state-level malaria control program tender consolidation toward direct contracting with resistance surveillance requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Intermediate Synthesis | Captive phosphorus pentasulfide supply insulates margin stability from sulfur price spikes. |
| REACH-Compliant Purification Upgrade | European export qualification opens persistent organic pollutant-screened formulation channels. |
| Microencapsulation Technology Licensing | Brazilian aerial application compatibility extends residual activity windows for cotton cooperatives. |
| WHO Prequalification Investment | Indoor residual spraying listing qualifies suppliers to sub-Saharan African procurement pools. |
| Resistance Monitoring Service Expansion | Entomological surveillance subscriptions attach recurring revenue to government vector control contracts. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with agrochemical plant managers, Indian state vector control procurement officers, Brazilian cotton cooperative technical directors, and distribution channel partners with South Asian market access. Secondary validation drew from EPA reregistration filings under FIFRA, ECHA REACH substance dossiers, Indian Central Insecticides Board residue limit notifications, customs trade data for technical grade imports, and SEC 10-K disclosures from integrated agrochemical conglomerates. Bottom-up volume triangulation across formulation types and top-down value reconciliation against agricultural pesticide expenditure surveys ensured cross-verified outputs.
Across the projection horizon, the analytical framework modeled segmentation dimensions including technical grade purity tiers, formulation chemistry platforms, application method compatibility, and end-user procurement sophistication. CAGRs were derived from regression analysis against historical agricultural input expenditure patterns and vector control program budget trajectories. Forecast inputs incorporated phosphorus pentasulfide feedstock price indices, EPA data call-in completion timelines, and WHO prequalification pathway progression rates.
Material uncertainties — regulatory revocation actions, resistance development velocity in target pest populations, and environmental enforcement intensity in Chinese synthesis clusters — sit outside the modeled envelope. Forecasts reflect documented assumptions on substitution elasticity and procurement consolidation trajectories. Practitioners should keep alternative scenarios live as pyrethroid resistance patterns and climate-driven vector range expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Sodium Bromate Market
Bulk Chemicals
Sodium Perborate Market
Bulk Chemicals
North America Vinyl Chloride Monomer Market
Bulk Chemicals
Cresylic Acid Market
Bulk Chemicals
Propionic Acid Market
Bulk Chemicals
Propionic Anhydride Market
Bulk Chemicals
Europe Carbon Black Market
Bulk Chemicals
Alkali Metal Hydroxides Market
Bulk Chemicals
Tributyl Citrate Market
Bulk Chemicals
Asia-Pacific Formaldehyde Market
Bulk Chemicals
Granular Urea Market
Bulk Chemicals
Calcium Hypophosphite Market
Bulk Chemicals
Sulfur Palletized Plant and Granulator Market
Bulk Chemicals
US Carbon Black Market
Bulk Chemicals
Global GABA Market
Bulk Chemicals
Zinc Carbonate Market