
 Sodium Bromate Market | 2026-2036
Sodium Bromate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Bromate Market Analytics
Electrochemical synthesis pathways is fragmenting legacy bromate production methods across the supply base. Shandong Weifang Longwei Industrial Company leverages captive bromine feedstock to sustain cost leadership in granular output. Albemarle Corporation anchors North American supply through integrated bromine derivative chains, while ICL Group competes on specialty-grade crystals for regulated food applications.
Sodium bromate is an inorganic salt with the chemical formula NaBrO3, typically produced through electrolytic oxidation of sodium bromide in aqueous solution at controlled temperature and pH, serving primarily as a powerful oxidizing agent in industrial bleaching, dye fixation, and bromine-based chemical synthesis. Water treatment applications lead volume consumption due to persistent municipal disinfection upgrade cycles, while dyeing segments in textile hubs concentrate demand for powder and granular grades where colorfastness specifications are stringent. Oil drilling represents a smaller but structurally profitable niche where liquid formulations command premium pricing for high-temperature well stimulation.
EPA regulations under the Safe Drinking Water Act limit bromate in finished water to 10 micrograms per liter, forcing utilities toward controlled-dose sodium bromate systems that meet oxidation targets without exceeding thresholds. China's MEE enforces discharge standards on bromate-containing effluents from chemical parks, redirecting capacity toward closed-loop manufacturing. India's BIS certification requirements for food-grade sodium bromate restrict import channels and elevate compliance costs for non-domestic suppliers. Stakeholders must weigh bromate substitution risks against oxidation performance requirements as perchlorate and advanced UV alternatives gain technical traction.
Market Dynamics
Electrochemical synthesis pathways are fragmenting legacy bromate production methods, forcing incumbents to retrofit chlor-alkali infrastructure or cede cost position to membrane-cell specialists with captive bromine access.
Growth Catalysts
- EPA Disinfection Byproduct Rules:Tightened limits on trihalomethanes and haloacetic acids are accelerating municipal adoption of bromate-based oxidation systems across US water treatment utilities.
- Textile Hub Expansion:Granular sodium bromate demand concentrates in Bangladesh and Vietnam where export-oriented dyeing operations require colorfastness specifications that bromate fixation uniquely satisfies.
- Closed-Loop Manufacturing Mandates:China's MEE discharge standards on bromate-containing effluents redirect chemical park capacity toward integrated production, sustaining domestic supply security.
Market Restraints
- Bromine Feedstock Volatility:Elemental bromine supply concentrates in Dead Sea extraction operations and select Chinese salt lake brines, exposing producers to input cost swings.
- Substitution Threat from Perchlorate:Advanced oxidation processes and perchlorate-based alternatives gain technical traction in high-temperature well stimulation, compressing liquid bromate pricing power.
- Regulatory Friction from BIS Certification:India's food-grade import restrictions elevate compliance costs for non-domestic suppliers, fragmenting supply channels.
Strategic Opportunities
- Underpenetrated African Water Infrastructure:Municipal disinfection upgrade cycles in Nigeria and Kenya present first-mover positioning for controlled-dose oxidation system suppliers.
- UV-Bromate Hybrid Convergence:Integration of advanced UV with precision bromate dosing creates premium system architectures for utilities facing multiple contaminant threats.
- PLI Scheme Alignment:India's production-linked incentive framework for specialty chemicals offers capital subsidy pathways for domestic bromate manufacturing scale-up.
Industry Challenges
- Electrochemical Engineering Talent Scarcity:Membrane-cell design and pH-control automation require specialized skill sets concentrated in legacy chlor-alkali regions, constraining greenfield project timelines.
- Food-Grade Certification Timelines:FSSAI and FDA dual-track approval processes for sodium bromate in flour treatment extend commercialization cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Bromate Market |
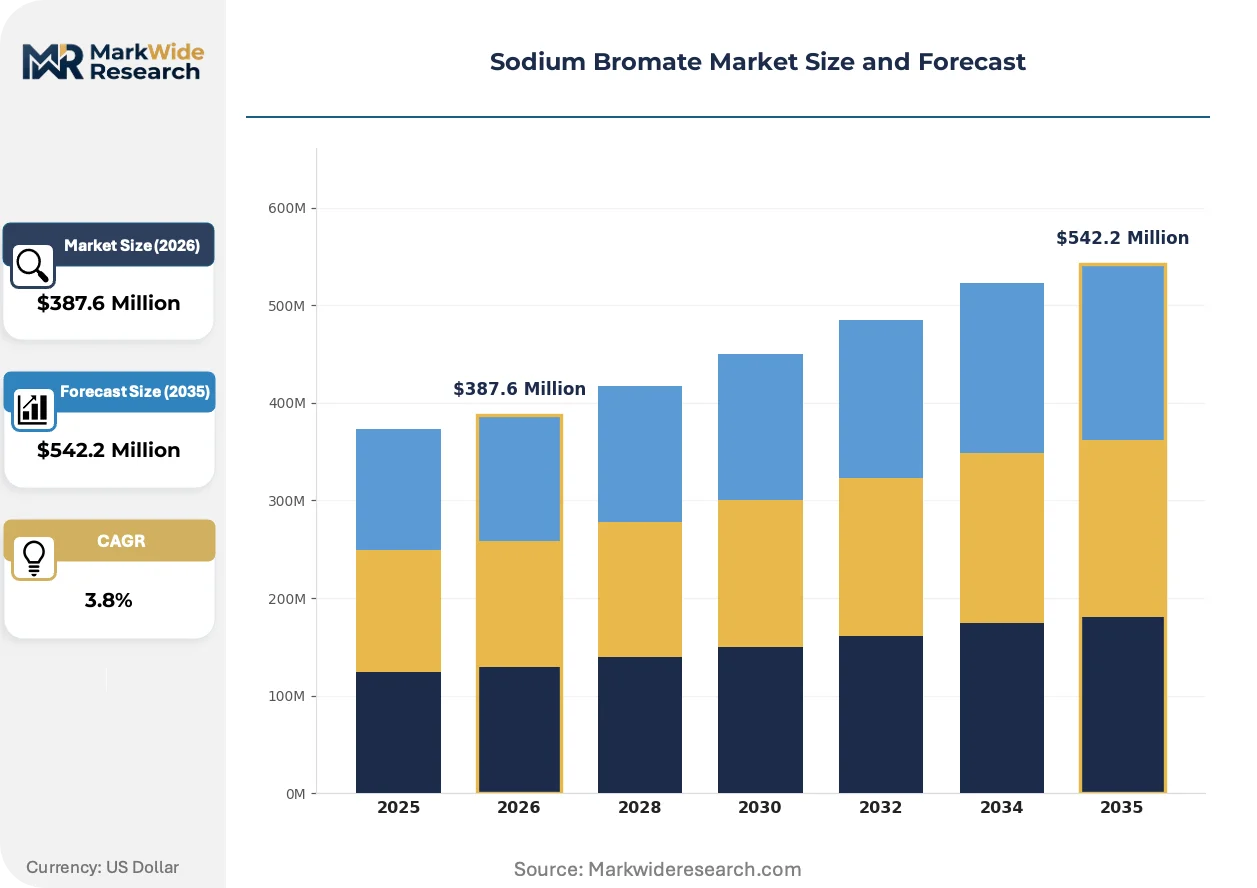
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $542.2 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Baking, Dyeing, Water Treatment, Oil Drilling Product Type: Granular, Powder, Liquid, Crystals End User: Food Industry, Textile Industry, Oil Industry, Chemical Manufacturing Packaging Type: Drums, Bags, Bulk Containers, Jerricans |
| Companies Covered | Shandong Weifang Longwei Industrial Company, Weifang Haihua Yuanda Fine Chemical Company Ltd, India Chemicals Ltd., DL Intrachem Ltd, Emery Oleochemicals Ltd, Albemarle Corporation, ICL Group, Hubei Nunnally Chemical Company, Hubei Kailin Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Bromate Market Evolving Landscape
Membrane electrolysis and digital process control are converging to compress production costs while regulatory stringency reshapes permissible end-uses across water, food, and industrial verticals.
Membrane-cell electrochemical synthesis is rendering obsolete diaphragm-cell bromate production across the supply base. European specialty chemical producers are retrofitting chlor-alkali infrastructure at accelerated pace. This technology shift enables sub-5% bromide conversion loss rates that diaphragm systems cannot match, collapsing unit economics for legacy capacity.
REACH authorization requirements for bromate derivatives are tightening substance volume tracking across EU chemical supply chains. Downstream formulators face enhanced registration obligations for dye-fixation applications. Textile chemical distributors in Germany and Italy are consolidating supplier bases to reduce compliance fragmentation.
Specification-driven procurement now dominates municipal water treatment contracting, displacing spot-market bromate purchases. Utilities in Texas and California are embedding oxidation performance guarantees into multi-year supply agreements. This shift concentrates volume with integrated bromine derivative producers capable of technical service support.
Sodium Bromate Market Segmentation
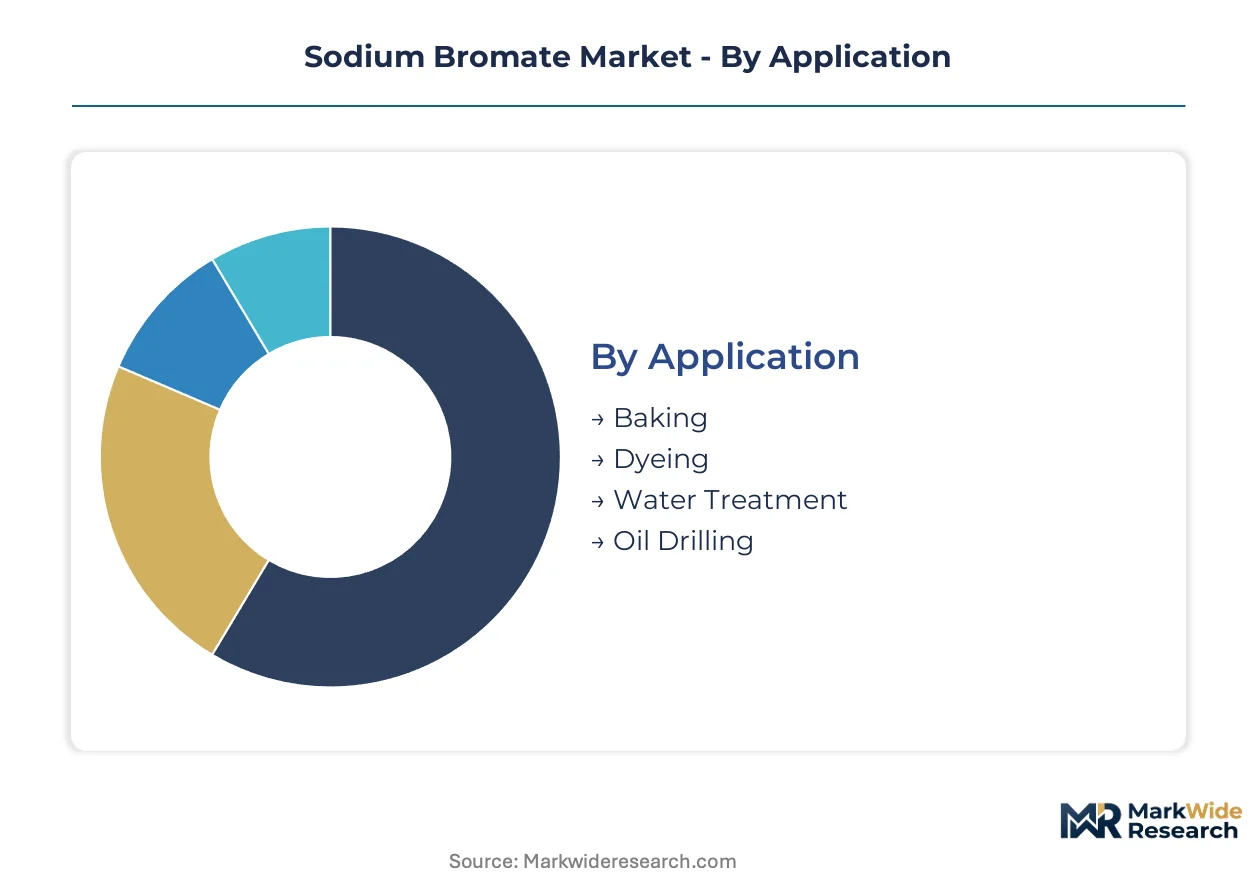
Sodium bromate procurement patterns diverge sharply across end-use verticals, with water utilities demanding multi-year technical service contracts while textile dye houses prioritize spot-market granular flexibility. Specification stringency in food-grade applications creates certification moats that reshape competitive access by segment.
Application:
After-sales service intensity peaks in municipal water contracts where oxidation performance guarantees require embedded technical support teams.
- Water Treatment:Municipal utilities deploy controlled-dose sodium bromate systems to meet EPA disinfection byproduct limits while staying under bromate thresholds. Texas and California utilities now embed oxidation performance guarantees into multi-year supply agreements, concentrating volume with integrated producers capable of on-site technical support.
- Dyeing:Textile operations in Bangladesh and Vietnam specify granular sodium bromate for colorfastness fixation in export-oriented dyeing. Granular grades reduce dust exposure and enable precise dosing in automated batch systems, satisfying stringent buyer compliance requirements from European apparel brands.
- Baking:Flour treatment applications require FSSAI and FDA dual-track approval processes that extend commercialization cycles. Food-grade certification timelines stretch 18-24 months, restricting supplier pools to established players with regulatory navigation capabilities.
- Oil Drilling:High-temperature well stimulation uses liquid formulations where perchlorate alternatives now compete aggressively. Liquid bromate retains niche positioning in formations where corrosion inhibition properties outweigh substitution economics.
By volume, Water Treatment leads. By growth pace, Dyeing is ahead.
Product Type:
Cost tier stratification separates membrane-cell synthesis output from legacy diaphragm production, with specification premiums widening.
- Granular:Free-flowing granules dominate textile hub procurement in Bangladesh and Vietnam where automated dosing systems require consistent particle size distribution. Shandong Weifang Longwei leverages captive bromine feedstock to sustain cost leadership in this grade.
- Powder:Fine-ground material serves legacy dyeing operations and small-batch chemical synthesis where dissolution speed matters. Powder grades face gradual displacement by granular alternatives in modern automated facilities.
- Liquid:Aqueous solutions command premium pricing in oil drilling applications where high-temperature well stimulation demands corrosion-resistant oxidation. Perchlorate substitution threats compress pricing power in this segment.
- Crystals:High-purity crystalline grades satisfy specialty chemical synthesis and regulated food applications. ICL Group competes intensively on specialty-grade crystals where impurity specifications are most stringent.
Granular formulations capture the largest volume share. Crystals are expanding most quickly on food-grade certification premiums.
End User:
Customer type determines contract structure, with chemical manufacturers favoring bulk term agreements and food processors requiring certified batch documentation.
- Chemical Manufacturing:China and India dominate consumption for bromine-based derivative synthesis. China's MEE discharge standards redirect chemical park capacity toward closed-loop integrated production, sustaining domestic supply security.
- Textile Industry:Export-oriented dyeing clusters in Bangladesh and Vietnam concentrate demand for colorfastness-critical applications. REACH authorization requirements for bromate derivatives tighten substance volume tracking across EU-facing supply chains.
- Food Industry:Flour treatment and food processing applications face India's BIS certification requirements that restrict import channels. FSSAI approval processes elevate compliance costs for non-domestic suppliers.
- Oil Industry:High-temperature well stimulation represents a structurally profitable niche despite substitution pressure. Liquid formulations retain positioning where corrosion inhibition properties create technical stickiness.
Chemical Manufacturing leads by volume. Textile Industry shows the steepest expansion trajectory on hub relocation trends.
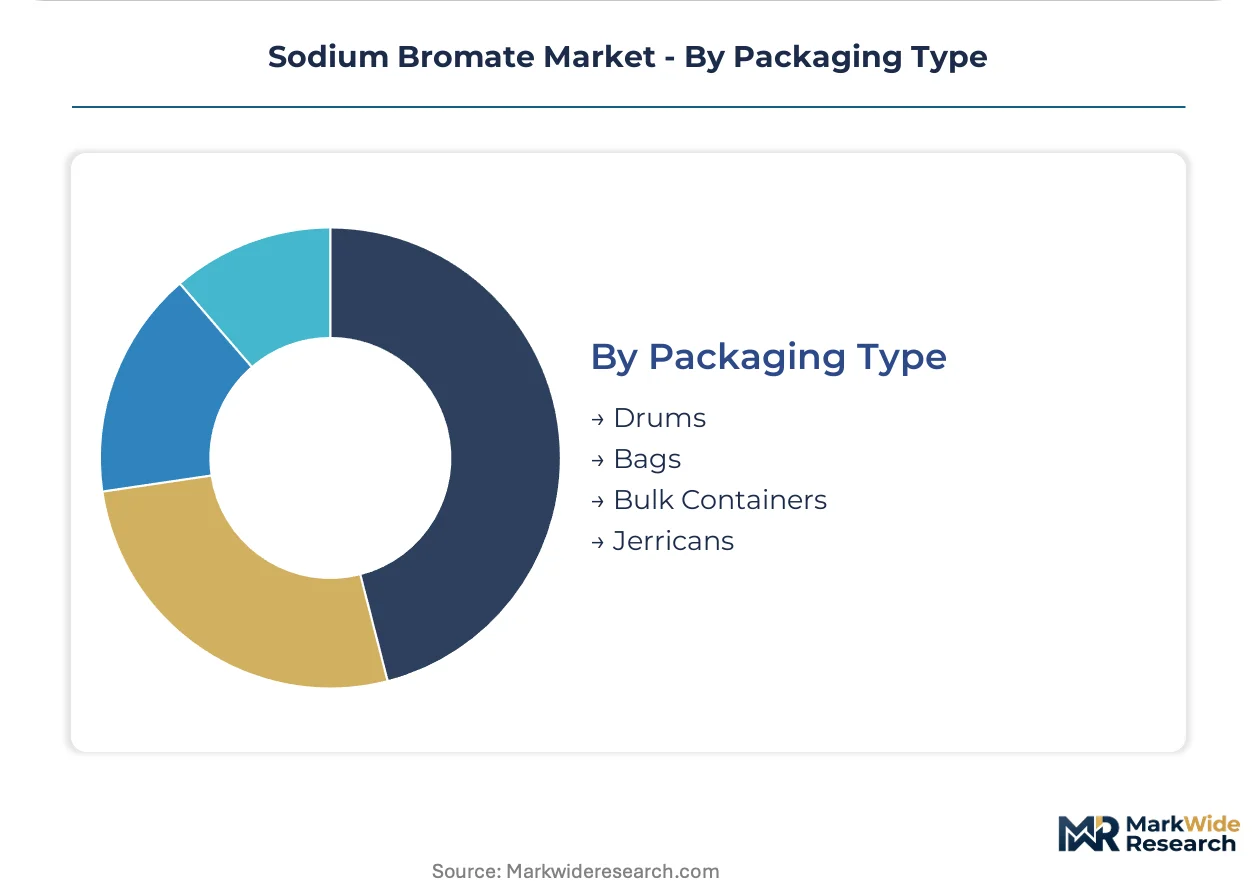
Packaging Type:
Supply concentration in Dead Sea bromine extraction shapes logistics economics, favoring bulk formats for integrated producers and drums for distributed textile procurement.
- Bulk Containers:Tanker and ISO-tank deliveries serve large-scale water treatment utilities and chemical manufacturers with dedicated storage infrastructure. Bulk formats minimize unit logistics costs for high-volume consumers with captive bromine derivative integration.
- Drums:Standard 200-liter drums dominate textile dye house procurement in Bangladesh and Vietnam where batch-scale operations require manageable handling units. Drum logistics enable just-in-time inventory for export-oriented dyeing schedules.
- Bags:Multi-wall paper and woven polypropylene bags serve granular and powder grades in textile and small-batch chemical applications. Bagged formats support spot-market purchasing flexibility that dye houses prioritize.
- Jerricans:Smaller-format containers address laboratory, pilot-scale, and specialty chemical synthesis requirements. Jerrican volumes remain marginal but carry specification premiums for high-purity grades.
Bulk Containers lead by volume. Drums are gaining share fastest on textile hub expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israeli bromine extraction operations supply feedstock to North American water treatment utilities and Asian textile chemical manufacturers, creating a trade-flow corridor that shapes regional pricing dynamics.
United States
Texas and California utilities embed oxidation performance guarantees into multi-year supply agreements, concentrating volume with integrated producers. EPA disinfection byproduct rules under the Safe Drinking Water Act tighten trihalomethane limits, accelerating bromate-based system adoption. Municipal procurement in the Southwest favors specification-driven contracting over spot-market purchases.
China
Shandong Province chemical parks redirect capacity toward closed-loop manufacturing under MEE discharge standards on bromate-containing effluents. Domestic bromine derivative synthesis dominates consumption volume. Weifang industrial clusters sustain cost leadership through captive brine processing and membrane-cell electrochemical infrastructure.
India
Gujarat and Maharashtra chemical manufacturers drive demand for bromine-based derivative synthesis. BIS certification requirements for food-grade sodium bromate restrict import channels and elevate compliance costs for non-domestic suppliers. The PLI scheme for specialty chemicals offers capital subsidy pathways for domestic manufacturing scale-up.
Germany
REACH authorization requirements tighten substance volume tracking for bromate derivatives across EU chemical supply chains. Textile chemical distributors in Baden-Württemberg consolidate supplier bases to reduce compliance fragmentation. Downstream formulators face enhanced registration obligations for dye-fixation applications.
Bangladesh
Export-oriented dyeing operations in Dhaka and Chittagong concentrate demand for granular sodium bromate grades. Colorfastness specifications from European apparel brands drive automated batch system adoption. Drum logistics enable just-in-time inventory for seasonal production schedules.
Sodium Bromate Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a bifurcated structure where integrated bromine derivative producers hold municipal water contracts and regional formulators capture textile hub spot demand. The vendor base organizes around captive feedstock access, electrochemical synthesis capability, and regulatory navigation expertise. Three archetypes dominate: Dead Sea-integrated majors with global logistics networks, Chinese membrane-cell specialists with chemical park co-location, and Indian domestic-certification players leveraging BIS compliance moats. Competitive moves center on chlor-alkali infrastructure retrofitting and multi-year technical service contracting.
Within the integrated-major tier, Albemarle Corporation and ICL Group exemplify producers with upstream bromine control and downstream derivative integration. Shandong Weifang Longwei Industrial Company represents the Chinese membrane-cell specialist archetype with apparent Shandong Province industrial clustering. India Chemicals Ltd. occupies a position within the domestic-certification player segment, likely navigating BIS and FSSAI approval pathways for food-grade market access.
| Leading Market Players |
|---|
| Shandong Weifang Longwei Industrial Company |
| Weifang Haihua Yuanda Fine Chemical Company Ltd |
| India Chemicals Ltd. |
| DL Intrachem Ltd |
| Emery Oleochemicals Ltd |
| Albemarle Corporation |
| ICL Group |
| Hubei Nunnally Chemical Company |
| Hubei Kailin Chemical |
| Others |
Value Network & Pricing Analysis
The Haifa-Rotterdam bulk chemical corridor channels Dead Sea bromine derivatives into European textile formulators and North American water utilities, with freight cost volatility amplifying price spreads between membrane-cell synthesis output and legacy diaphragm production. This logistics artery concentrates pricing power with integrated producers holding captive brine access while forcing spot-market buyers into premium procurement positions.
Pricing Analysis
Membrane-cell electrochemical synthesis commands a 15-20% premium over diaphragm-cell output due to sub-5% bromide conversion loss rates that legacy systems cannot achieve. Three-tier pricing structure across food-grade crystals, technical-grade granular, and industrial liquid formulations tracks certification burden and purity specifications. Cost compression in liquid bromate runs through perchlorate substitution pressure in oil drilling applications. Municipal water utilities exhibit lowest price sensitivity due to embedded technical service requirements, while small textile dye houses in Bangladesh show highest elasticity to spot-market granular fluctuations.
Supply Chain Analysis
Export-control scrutiny on electrochemical process technology limits membrane-cell equipment flows to Chinese chemical parks, constraining capacity expansion outside established production zones. Elemental bromine supply concentrates in Israeli Dead Sea extraction operations, Chinese Shandong salt lake brines, and select Arkansas wellhead operations. Sodium bromide feedstock and membrane-cell electrolyzer components constitute critical input dependencies. Single-source vulnerability in Dead Sea bromine exposes downstream formulators to geopolitical disruption risk. Distribution runs through integrated bromine derivative producers for bulk water treatment contracts, while regional distributors serve textile hub spot demand in drum and bag formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among municipal water utilities embedding multi-year oxidation performance guarantees into supply agreements, fragmenting spot-market access for non-integrated producers. This consolidation favors technical service-capable suppliers while squeezing commodity-only players.
For Market Incumbents: Insulate municipal contract positions by retrofitting chlor-alkali infrastructure to membrane-cell synthesis, cutting unit costs below diaphragm-cell rivals. Secure captive bromine feedstock through backward integration into brine extraction or long-term offtake agreements with Dead Sea operators. Perchlorate substitution in oil drilling and REACH authorization tightening in Europe represent immediate threats requiring R&D pivot toward UV-bromate hybrid systems. For New Entrants and Emerging Players: Mid-size water treatment utilities in Nigeria and Kenya represent the most penetrable entry point, lacking embedded supplier relationships and facing urgent disinfection upgrade cycles. Food-grade certification gaps in India create white-space for domestic producers navigating BIS and FSSAI dual-track approval. Entry through toll manufacturing arrangements with existing membrane-cell operators reduces capital intensity while building regulatory navigation capabilities. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized bromine derivative capacity and weak downstream integration. Long-term viability hinges on electrochemical synthesis IP and regulatory compliance infrastructure rather than commodity scale. The signal to watch is EPA enforcement intensity on trihalomethane limits, which would accelerate municipal contract consolidation and premium pricing for technical service-embedded suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane-Cell Capacity Expansion | Sub-5% conversion loss rates collapse unit economics for diaphragm-cell competitors. |
| Backward Integration into Bromine Feedstock | Captive brine access insulates margin position from Dead Sea supply volatility. |
| Food-Grade Certification Investment | FDA and FSSAI dual-track approval creates 18-24 month moats against import competition. |
| Long-Term Municipal Supply Agreements | Embedded oxidation performance guarantees lock out spot-market rivals in Texas and California. |
| UV-Bromate Hybrid System Development | Integration with advanced UV addresses multiple contaminant threats beyond bromate alone. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with membrane-cell plant managers, water utility procurement officers, and textile chemical distributors; and secondary validation through customs trade records, EPA enforcement databases, and SEC filings from integrated bromine derivative producers. Plant managers at Shandong and Weifang facilities provided production cost benchmarks. Water utility procurement officers in Texas and California detailed contract structure evolution. Triangulation across bottom-up capacity assessments and top-down demand modeling from end-use verticals ensured analytical robustness.
Forecast inputs span grade tier, end-use application, packaging format, and regional production hub across the projection horizon. Segment-level CAGRs derive from elasticity modeling against regulatory enforcement intensity and substitution threat progression. Bromine feedstock cost curves and membrane-cell adoption rates constitute chemical-specific forecast drivers. Price-volume relationships incorporate municipal contract premium structures and textile spot-market volatility patterns.
Practitioners should monitor EPA trihalomethane enforcement actions and MEE discharge standard revisions for early signals of demand acceleration or supply constraint. Forecasts reflect assumptions on electrochemical synthesis diffusion rates and regulatory timeline adherence. Material shifts in bromine extraction geopolitics or breakthrough perchlorate cost reduction would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Cyclopentane Market
Bulk Chemicals
North America Vinyl Chloride Monomer Market
Bulk Chemicals
Ammonium Thiosulfate Market
Bulk Chemicals
Tallow Market
Bulk Chemicals
Acetyl Tributyl Citrate Market
Bulk Chemicals
Global Bitumen Market
Bulk Chemicals
Picric Acid Market
Bulk Chemicals
China Lime Market
Bulk Chemicals
Global Semiconductor Grade Nitric Acid Market
Bulk Chemicals
Global 2-Methylpropene Market
Bulk Chemicals
Global Ground and Precipitated Calcium Carbonate Market
Bulk Chemicals
Global Acrolein Market
Bulk Chemicals
Global Ammonium Sulphate Market
Bulk Chemicals
Global Acrylic Esters Market
Bulk Chemicals
Refined Naphthalene Market
Bulk Chemicals
Hydrogen Bromide Market