
 Global Public Cloud Service Market | 2026-2036
Global Public Cloud Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Public Cloud Service Market Intelligence
The EU AI Act is repositioning the compliance burden for cloud providers offering services to European clients. Amazon Web Services leverages its first-mover advantage and extensive service portfolio to maintain market leadership. Microsoft Azure capitalizes on its deep enterprise relationships and hybrid cloud strengths. Meanwhile, Google Cloud Platform differentiates through its expertise in data analytics, machine learning, and containerization technologies like Kubernetes.
Public cloud services involve the on-demand delivery of computing resources over the internet from a provider's data centers. These services operate on a multi-tenant architecture, where multiple customers share pooled virtualized resources. Infrastructure as a Service (IaaS) forms the foundational layer, while Platform as a Service (PaaS) provides a framework for developers to build applications. Software as a Service (SaaS) represents the largest and most mature segment, delivering complete applications directly to end users in industries like telecommunications and media.
Data sovereignty and privacy regulations, including Europe's GDPR and the US HIPAA, dictate where and how customer data can be stored and processed. Concurrently, international standards like ISO/IEC 27017 provide a code of practice for information security controls applicable to the provision and use of cloud services. Navigating this complex web of national and international regulations remains a critical challenge for both cloud providers and their enterprise customers.
Market Dynamics
The central force shaping the public cloud market is the explosive compute demand from large-scale generative AI models. This requirement for massive, parallel processing power is fundamentally altering data center architecture and resource allocation strategies.
Growth Catalysts
- Generative AI Models:The proliferation of large language models and other generative AI applications creates immense, sustained demand for GPU-intensive compute and storage resources.
- Manufacturing Digitization:Adoption of digital twin technology and factory automation applications within the manufacturing sector drives consumption of IaaS and PaaS for simulation and data processing.
- National Infrastructure Projects:Government initiatives, such as those in India prioritizing digital infrastructure, accelerate public and private sector migration to cloud-based services.
Market Restraints
- Data Sovereignty Laws:Regulations like Europe's GDPR and similar statutes in other countries impose strict rules on data residency, complicating global service delivery models.
- High Energy Costs:The intensive electricity consumption of hyperscale data centers creates significant cost pressures, especially in regions with volatile energy pricing.
- Network Limitations:For certain real-time applications like autonomous vehicle control, network latency between the edge and a central cloud remains a technical barrier.
Strategic Opportunities
- Sovereign Clouds:Developing dedicated sovereign cloud offerings allows providers to meet the specific data residency and security requirements of government agencies and regulated industries.
- Cloud and Edge Convergence:Creating integrated solutions that combine centralized cloud resources with edge computing addresses low-latency requirements for IoT and industrial control systems.
- Service Mesh Adoption:Providing managed service mesh platforms like Istio simplifies secure communication and observability for microservices-based applications running across multiple cloud environments.
Industry Challenges
- Specialized Skills Gap:A persistent shortage of cloud architects and DevOps engineers with expertise in multi-cloud management, container orchestration, and FinOps hinders enterprise adoption.
- Legacy System Integration:Enterprises face significant technical hurdles and costs when attempting to integrate modern, cloud-native applications with their existing on-premise legacy systems.
- Regulatory Navigation:Keeping pace with the complex and diverging web of global security standards, such as ISO/IEC 27017, and national privacy laws is a major compliance burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Public Cloud Service Market |
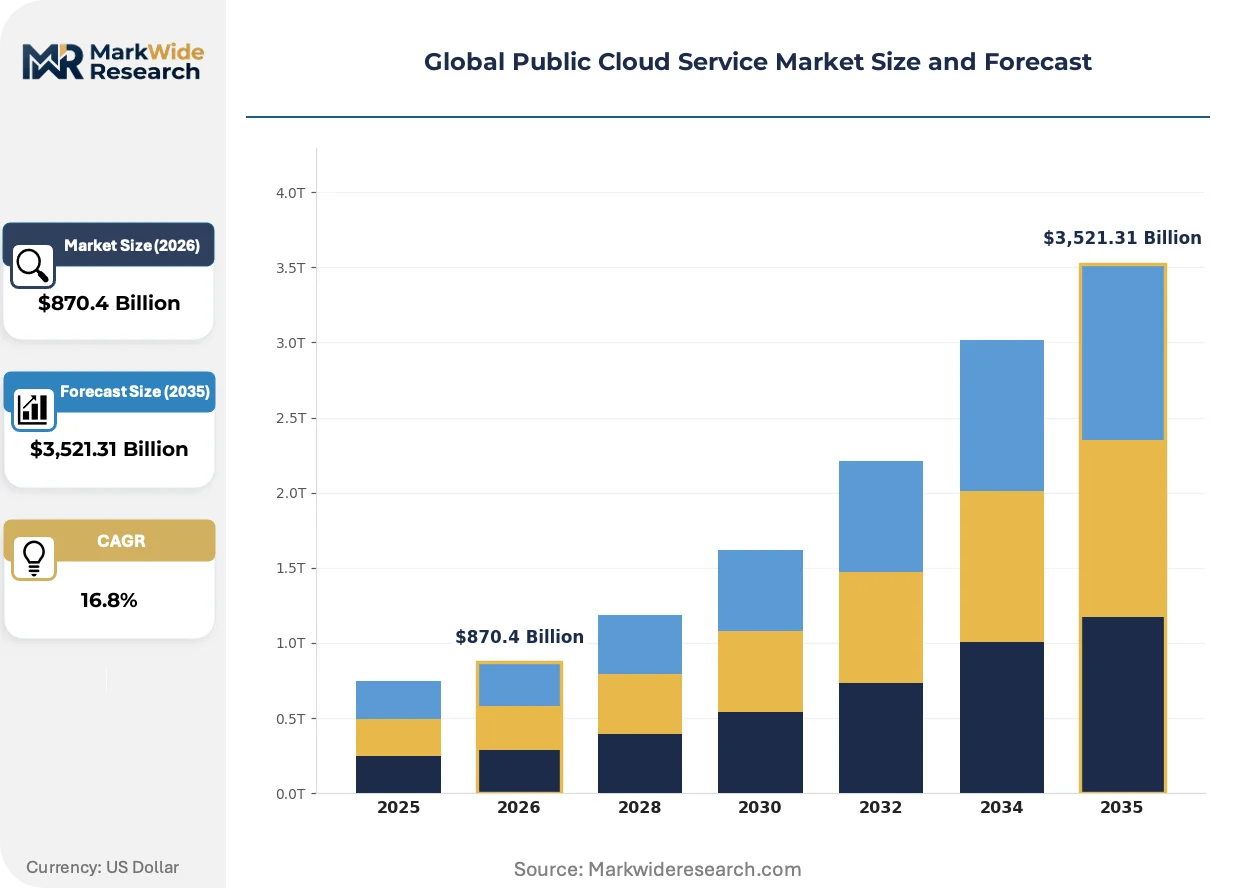
| Market Size in 2026 | $870.4 Billion |
| Market Size in 2035 | $3,521.31 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Model: Infrastructure as a Service, Platform as a Service, Software as a Service, Function as a Service, Database as a Service Deployment Type: Multi-Cloud, Hybrid Cloud, Community Cloud, Public Cloud, Distributed Cloud End User Industry: Information Technology, Telecommunications, Manufacturing, Media & Entertainment, Education Pricing Model: Pay-As-You-Go, Subscription-Based, Reserved Instances, Spot Instances, Enterprise Agreements |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud Platform, Alibaba Cloud, Oracle Cloud, Salesforce, IBM Cloud, SAP, CoreWeave, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Public Cloud Service Market Strategic Shifts & Innovations
The evolution of public cloud services is now defined by workload specialization and the growing influence of non-technical drivers. Architectural decisions are increasingly guided by regulatory mandates and financial governance, not just technical performance.
FinOps Platforms
FinOps platforms provide enterprises with visibility and control over complex cloud expenditures. Large organizations with multi-cloud deployments are rapidly adopting these tools to manage costs. This technology is consolidating resource management under a centralized financial governance framework, shifting accountability from siloed IT teams to a collaborative model.
Impact of the EU AI Act
Europe's AI Act introduces risk-based obligations for artificial intelligence systems, impacting cloud-based AI and machine learning services. This regulation requires providers to ensure transparency and robustness for high-risk applications. Consequently, PaaS providers serving European clients are embedding auditable logging and model explainability features directly into their platforms.
Multi-Cloud Procurement
Enterprises are actively pursuing multi-cloud strategies to avoid vendor lock-in and enhance resilience. The use of container orchestration platforms like Kubernetes is disrupting the traditional, sticky IaaS ecosystem by enabling application portability. This shift is most pronounced in regulated industries such as financial services, where risk diversification is a primary driver for procurement decisions.
Global Public Cloud Service Market Segmentation
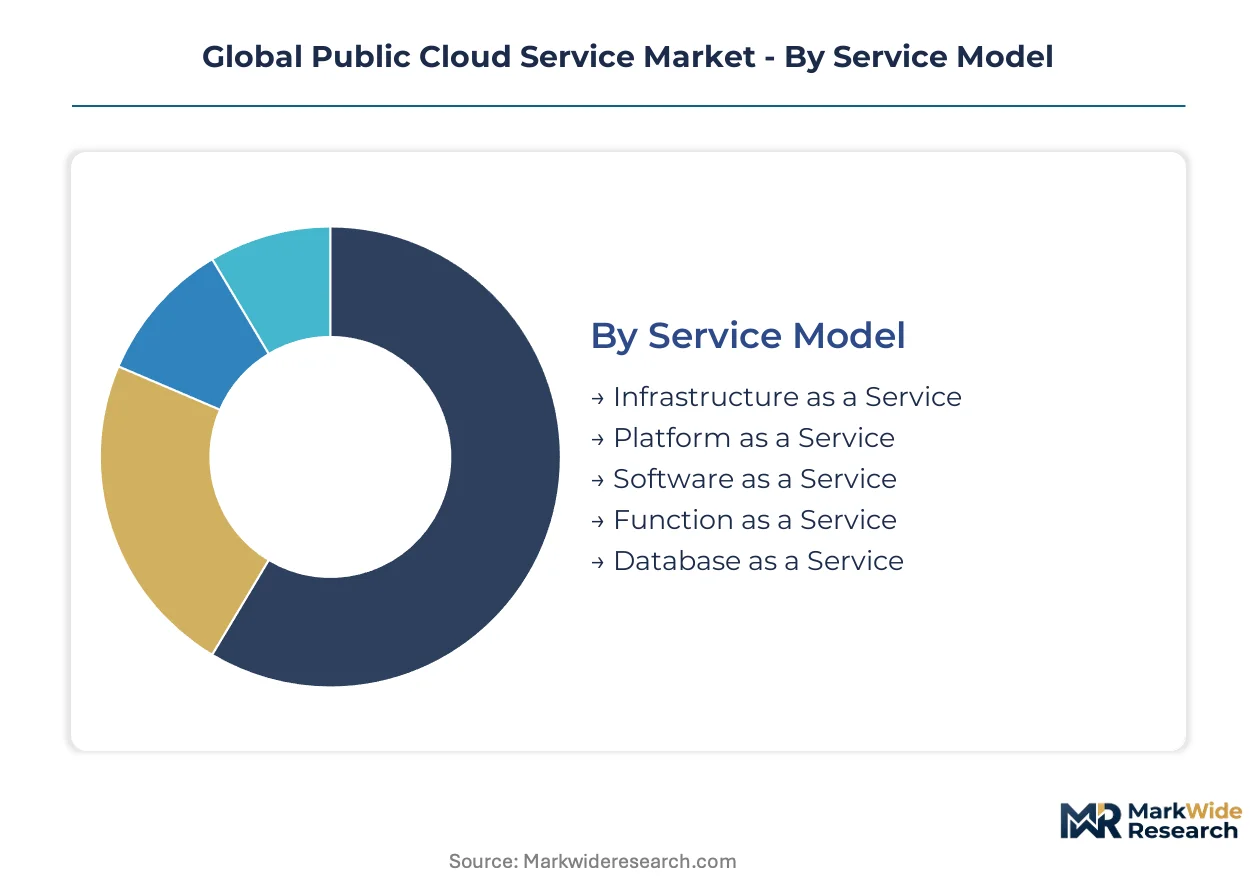
Understanding the segmentation of the global public cloud service market is crucial for identifying key growth vectors and evolving technological adoption cycles. This detailed breakdown clarifies where demand is consolidating and how different service components contribute to overall market expansion, guiding strategic investment decisions.
Service Model:
The public cloud service market's upgrade cycle is significantly influenced by the evolving adoption patterns across different service models.
- Software as a Service:This model delivers complete, ready-to-use applications over the internet, with the provider managing all underlying infrastructure. Demand concentrates in industries like telecommunications and media, driven by the need for rapid deployment and reduced operational overhead for end-user applications.
- Infrastructure as a Service:IaaS provides fundamental computing resources, including virtual machines, networks, and storage, delivered over the internet. Demand is concentrating in the manufacturing sector for digital twin applications, driven by the need for scalable computational power for simulations and data processing.
- Platform as a Service:PaaS offers a development and deployment environment, enabling developers to build and run applications without managing the underlying infrastructure.
- Function as a Service:FaaS allows developers to execute code in response to events without provisioning or managing servers, often used for microservices architectures.
- Database as a Service:DBaaS provides fully managed database capabilities, abstracting infrastructure and operational tasks from the user.
Software as a Service sits at the top of the volume ranking, with Function as a Service climbing the fastest.
Deployment Type:
Application requirements often dictate the preferred deployment type, influencing architectural decisions for enterprises.
- Multi-Cloud:This strategy utilizes multiple public cloud services from different providers, often to avoid vendor lock-in and enhance resilience. Demand is concentrating in regulated industries like financial services, driven by risk diversification strategies and specific workload needs.
- Hybrid Cloud:Hybrid cloud combines public cloud infrastructure with private on-premise resources, allowing data and applications to move seamlessly between them. Demand is concentrating in large enterprises with significant legacy systems, driven by the need to integrate existing IT assets with scalable cloud services.
- Community Cloud:Community cloud represents shared infrastructure used by several organizations with common concerns, typically managed by a third party or the community itself.
- Public Cloud:Public cloud services are delivered over the open internet and available to the general public, characterized by shared resources and self-service provisioning.
- Distributed Cloud:Distributed cloud involves public cloud services running in multiple geographically dispersed locations, including on-premises and edge environments.
Multi-Cloud deployments capture significant enterprise investment, with Distributed Cloud gaining share fastest.
End User Industry:
Diverse customer types within various end-user industries exhibit distinct consumption patterns for public cloud services.
- Information Technology:Businesses primarily focused on IT services, software development, and digital transformation leverage cloud for core operations and innovation. Demand concentrates in regions with strong digital infrastructure like India, driven by national digitalization priorities and software development needs.
- Manufacturing:Industrial enterprises adopt cloud for operational technology, digital twins, and factory automation, optimizing production processes. Demand concentrates in advanced industrial economies, driven by the need for real-time data processing and simulation capabilities for smart factories.
- Telecommunications:Telecommunications providers utilize cloud for network functions virtualization, 5G infrastructure, and customer-facing applications.
- Media & Entertainment:Companies leverage cloud for content creation, streaming, and distribution, requiring scalable storage and compute resources.
- Education:Educational institutions adopt cloud for e-learning platforms, research computing, and administrative systems, enhancing digital learning environments.
Information Technology represents the largest end-user segment, while Manufacturing shows the steepest expansion trajectory.
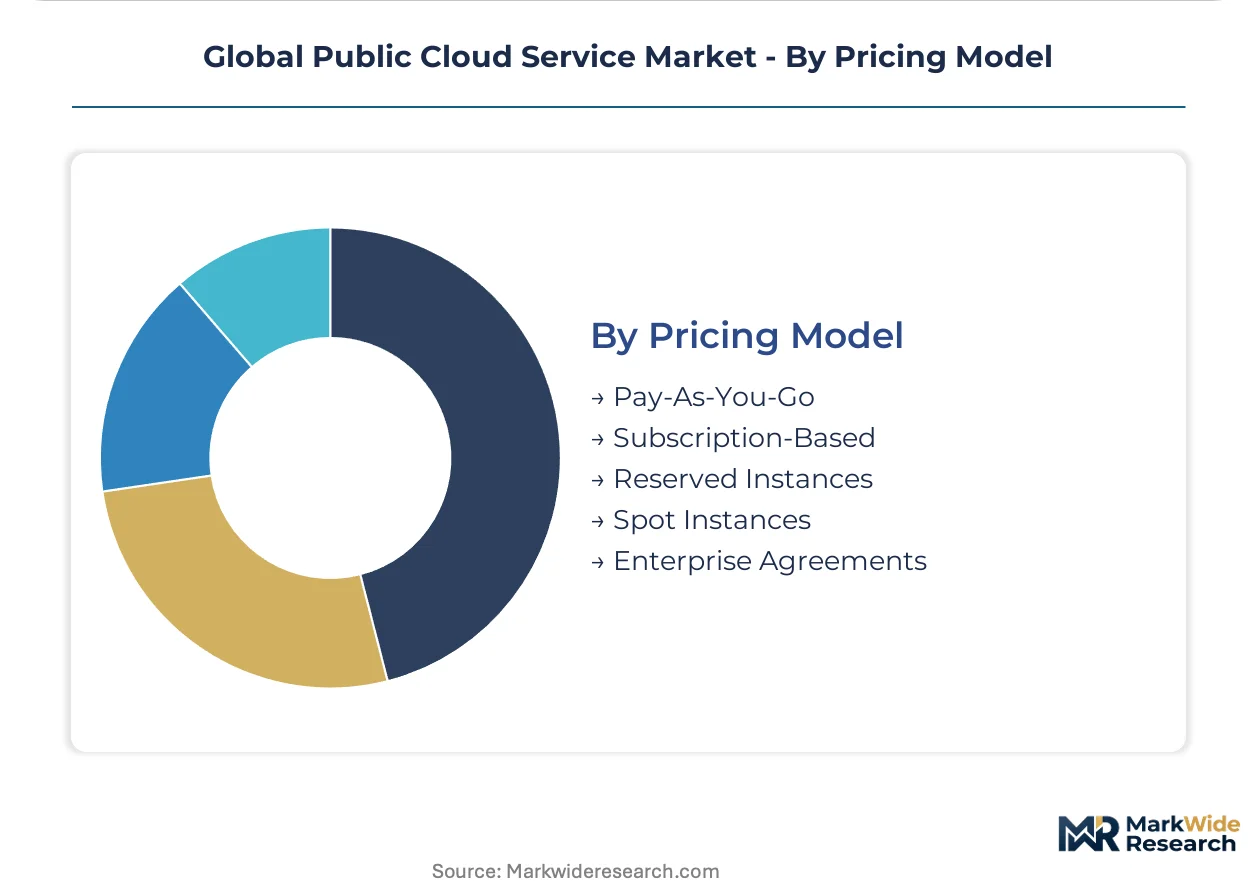
Pricing Model:
Cost tiering and financial governance principles significantly guide enterprise selection of public cloud pricing models.
- Pay-As-You-Go:Customers pay only for the resources consumed, offering maximum flexibility without upfront commitments. Demand concentrates among startups and projects with fluctuating workloads, driven by the need for cost optimization and agile resource scaling.
- Enterprise Agreements:These are long-term contracts between large organizations and cloud providers, often including significant discounts and dedicated support. Demand concentrates in large corporations and government agencies, driven by predictable budgeting and comprehensive service level agreements.
- Subscription-Based:This model involves fixed recurring payments for access to a defined set of services over a specific period, offering budget predictability.
- Reserved Instances:Customers commit to using a specific amount of compute capacity for a one- or three-year term, receiving substantial discounts.
- Spot Instances:Spot instances offer unused cloud capacity at significant discounts, suitable for fault-tolerant and flexible applications that can tolerate interruptions.
Pay-As-You-Go remains a popular choice for flexibility, with Enterprise Agreements expanding most quickly for large deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A skilled workforce in cloud architecture and software development underpins the expansion of public cloud services across key global markets. This talent pool drives innovation and adoption, particularly in regions with strong digital economies. Diverse regulatory environments and infrastructure priorities further shape regional market dynamics.
United States
Highly skilled cloud architects and AI researchers in the United States drive significant demand for public cloud services, especially for generative AI model training. HIPAA mandates stringent data security and privacy for healthcare data in the cloud. Technology hubs like Silicon Valley concentrate innovation in cloud-native applications and advanced analytics.
Germany
Robust engineering talent in Germany fuels demand for public cloud services, particularly for manufacturing digitization and complex data analytics. The EU AI Act and GDPR impose strict compliance requirements on cloud providers. Industrial centers in Bavaria and Berlin actively deploy cloud solutions for smart factory initiatives.
India
India's burgeoning tech talent pool supports extensive demand for public cloud services, driven by national digital infrastructure projects and a thriving IT sector. The Digital India program prioritizes cloud adoption across enterprises. Major IT hubs like Bangalore and Hyderabad serve as epicenters for cloud innovation and large-scale software development.
China
Expansive developer communities in China propel public cloud consumption, especially for large-scale e-commerce platforms and domestic AI development. Data localization requirements from the Cyberspace Administration of China influence cloud deployment strategies. Technology clusters in the Yangtze River Delta and Beijing lead in developing cloud-native applications and AI infrastructure.
Japan
Japan's highly skilled engineering workforce drives enterprise digital transformation initiatives and IoT deployments on public cloud platforms. METI provides guidelines for cloud security and data management. Major metropolitan areas like Tokyo and Osaka host significant cloud infrastructure and advanced research in AI and automation.
Global Public Cloud Service Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the public cloud service market, creating a tiered competitive structure. The market exhibits consolidation at the hyperscale infrastructure layer, while application and platform services remain more fragmented. Strategic archetypes include global hyperscalers, regional cloud providers, and specialized SaaS vendors. Dominant competitive moves involve continuous service portfolio expansion, strategic partnerships with enterprise clients, and capacity expansion to meet AI-driven demand.
Within the global hyperscaler archetype, Amazon Web Services and Microsoft Azure represent established market leaders, leveraging extensive infrastructure and broad service portfolios. Both providers anchor significant enterprise commitments through their hybrid cloud capabilities and deep integration with existing IT ecosystems. Salesforce, a prominent Software as a Service provider, exemplifies the mature application layer of the public cloud market, offering specialized solutions directly to end-users. These players collectively shape the market's direction through continuous innovation and strategic expansion into new geographic regions.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud Platform |
| Alibaba Cloud |
| Oracle Cloud |
| Salesforce |
| IBM Cloud |
| SAP |
| CoreWeave |
| Others |
Cost & Logistics Intelligence
Outsourced infrastructure integration anchors the supply position for most cloud service providers, influencing their ability to offer competitive pricing tiers. This strategic choice allows providers to scale rapidly while managing capital expenditure, directly impacting service cost structures for end-users.
Pricing Analysis
Bundled and unbundled service splits define the public cloud pricing landscape. Pay-As-You-Go remains a popular choice for flexibility, while Enterprise Agreements expand most quickly for large deployments. Price differentiation stems from service level agreements, including uptime guarantees and dedicated support, and the geographic location of data centers. Pricing pressure stems from intense hyperscaler competition and the commoditization of foundational IaaS resources. Enterprises with fluctuating workloads exhibit high price sensitivity, whereas regulated industries prioritize comprehensive service level agreements over marginal cost savings.
Supply Chain Analysis
Data center certification standards, such as ISO/IEC 27017 for information security, gate entry into the public cloud supply chain. Supply chain concentration for critical hardware, including GPUs and high-performance servers, centers in countries like Taiwan, South Korea, and the United States. Key dependencies include advanced semiconductor components, specialized cooling systems, and robust networking equipment. Geopolitical tensions and trade restrictions represent a structural supply chain risk for hardware procurement. Distribution runs primarily through direct contracts between hyperscalers and large enterprises, supplemented by managed service providers for smaller clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a late-cycle quality story, driven by a demand-shift toward highly specialized, secure, and compliant cloud environments for critical workloads.
For Market Incumbents:Acquire specialized AI infrastructure providers to secure access to GPU capacity and accelerate generative AI service development. Deepen integration with enterprise legacy systems to fortify existing customer relationships against emerging multi-cloud platforms. A persistent skills gap in cloud architecture poses a threat to broader adoption. Invest in FinOps platform development to help clients manage complex cloud expenditures.
For New Entrants and Emerging Players:Managed service providers can target underpenetrated mid-market segments with tailored multi-cloud management solutions. Focus on specific regulatory compliance niches, such as sovereign cloud offerings for government agencies and regulated industries. A go-to-market angle focusing on cost optimization through FinOps integration can attract budget-conscious enterprises. The manufacturing sector offers a penetrable application segment for specialized PaaS solutions.
For Investors and Strategic Acquirers:Consolidation pressure builds where specialized compute demands outstrip general-purpose cloud capacity. The long-term viability favors providers capable of delivering highly secure, compliant, and performant platforms for AI and critical enterprise workloads. Acquisition targets should include niche providers of sovereign cloud solutions or advanced data analytics platforms. A signal to watch is the increasing adoption rate of industry-specific PaaS offerings.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in AI Compute | Ensures hyperscalers meet explosive demand from large-scale generative AI model training. |
| Hybrid Cloud Platform Enhancement | Deepens integration between public and private IT assets for large enterprise customers. |
| FinOps Tooling Development | Provides enterprises with critical visibility and control over cloud expenditure. |
| Sovereign Cloud Offering Launch | Addresses stringent data residency and security requirements for government clients. |
| Edge Computing Integration | Enables low-latency applications for IoT and industrial control systems at the network periphery. |
Research Approach
Bottom-up end-user adoption modeling reconciled against top-down hyperscaler infrastructure tracking forms the analytical core of this study. Primary research involved conversations with chief technology officers, IT procurement leads, cloud architects, and FinOps specialists across various industries. Secondary validation drew from publicly available financial filings, government digital infrastructure reports, and industry association publications.
An input-output matrix framing defined the quantitative forecast framework across the analysis window. Segmentation dimensions included service model, deployment type, end-user industry, pricing model, and regional adoption patterns. Compound Annual Growth Rates were derived from historical data trends and projected future demand, incorporating inputs such as AI model development cycles and data center energy costs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory shifts and geopolitical instability. Forecasts reflect assumptions documented regarding technological breakthroughs and market competitive dynamics. A model refresh is warranted upon material change in global digital infrastructure investment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud Microservice and Application Market
Cloud Computing
Global Cloud Migration Market
Cloud Computing
Europe AI Cloud Computing in Automotive Market
Cloud Computing
Platform As a Service (Paas) Market
Cloud Computing
Asia Pacific Multi-Cloud Management Market
Cloud Computing
Hybrid Cloud Computing Market
Cloud Computing
Hyperscale Cloud Market
Cloud Computing
Hybrid Cloud in BFSI Market
Cloud Computing
Cloud Migration Services Market
Cloud Computing
Public Cloud Application Services Market
Cloud Computing
Cloud ECS Market
Cloud Computing
Global Cloud/Mobile Backend AS a Service (Baas) Market
Cloud Computing
Global Cloud Business Email Market
Cloud Computing
High-Performance Computing (HPC) As a Service Market
Cloud Computing
Cloud Data Warehouse Market
Cloud Computing
Cloud Continuum Market