
 Europe AI Cloud Computing in Automotive Market | 2026-2036
Europe AI Cloud Computing in Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
Europe AI Cloud Computing in Automotive Market Insights
Tier-1 suppliers is reorganizing demand patterns as these firms build proprietary AI validation pipelines that bypass traditional OEM cloud procurement. NVIDIA sustains technology leadership through GPU-optimized automotive workloads across European edge facilities. Microsoft Corporation leverages its Azure industrial cloud footprint to secure long-term contracts with German and French automakers. SAP SE anchors enterprise AI integration by embedding automotive-specific modules into existing ERP environments.
Europe AI Cloud Computing in Automotive comprises distributed machine learning infrastructure, high-throughput data lakes, and low-latency inference nodes that process multi-terabyte daily sensor feeds from connected vehicle fleets. The architecture relies on containerized GPU clusters and 5G edge gateways to deliver sub-50ms response times for real-time driving decisions. Cloud Infrastructure dominates current spending as OEMs retrofit legacy data centers for AI training scale. Hybrid Cloud deployments are expanding fastest among Tier-1 suppliers seeking to balance regulatory data sovereignty with burst compute needs. Machine Learning solutions capture concentrated margin pools due to specialized automotive model development and continuous retraining requirements.
The EU AI Act imposes risk-classification obligations on autonomous driving algorithms, compelling cloud providers to maintain auditable training pipelines within European Economic Area boundaries. EMA and national transport regulators in Germany, France, and Italy coordinate type-approval standards that embed cybersecurity and data governance into vehicle AI systems. GDPR restricts cross-border telemetry flows, pushing demand toward localized cloud regions and sovereign data architectures. Stakeholders must monitor evolving liability frameworks that assign responsibility between cloud operators and automotive OEMs when AI-driven systems fail in production traffic.
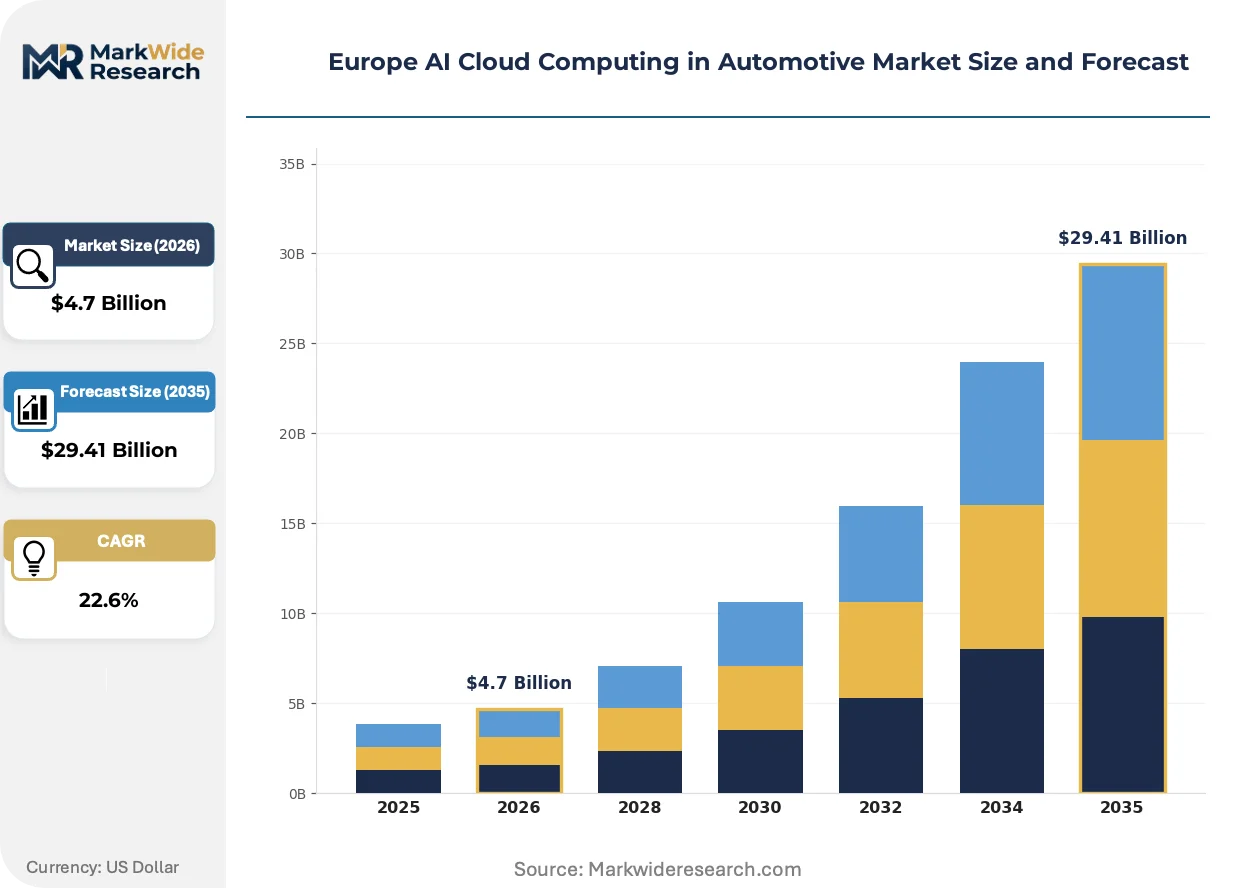
Market Dynamics
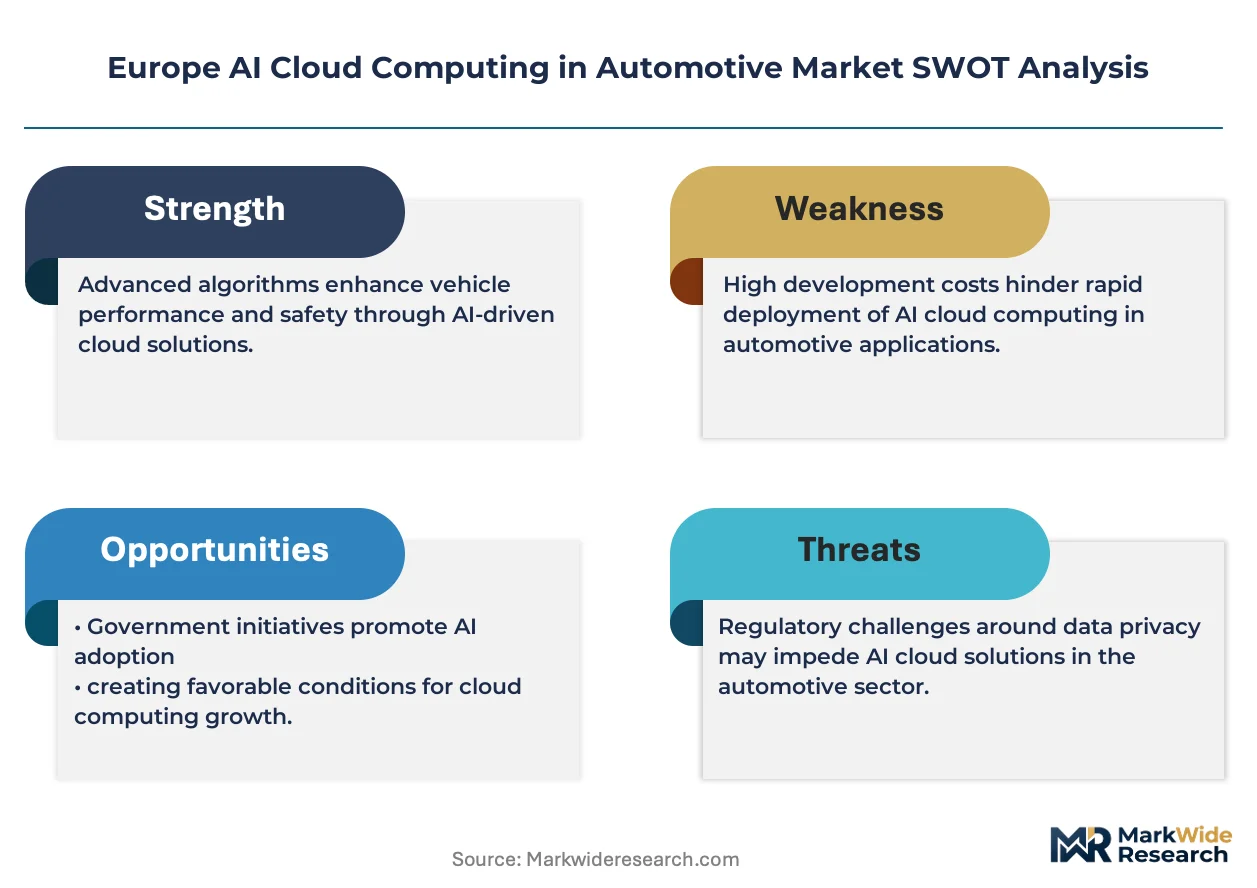
The EU AI Act's risk-classification mandates for autonomous driving algorithms are forcing automotive OEMs to rebuild cloud training pipelines inside European Economic Area boundaries, compressing vendor selection and inflating compliance spend.
Growth Catalysts
- GDPR data localization:Cross-border telemetry restrictions push demand toward sovereign cloud architectures, creating captive markets for EU-based data center operators.
- 5G edge deployment:Sub-50ms latency requirements for real-time driving decisions drive GPU cluster investments at automotive manufacturing hubs in Germany and France.
- Autonomous validation pipelines:Tier-1 suppliers building proprietary AI testing infrastructure bypass traditional OEM procurement channels and accelerate cloud consumption.
Market Restraints
- GPU supply concentration:NVIDIA's dominance in automotive-optimized silicon creates single-source dependency for European edge facilities.
- EMA type-approval timelines:Coordinated cybersecurity and data governance standards between German, French, and Italian transport regulators extend certification cycles.
- Legacy data center retrofit costs:Containerized cluster upgrades for AI training scale strain capital allocation at mid-tier OEMs.
Strategic Opportunities
- Polish and Romanian cloud regions:Lower-cost sovereign infrastructure outside core Western European markets offers expansion paths for Tier-2 suppliers.
- EU Green Deal alignment:Carbon-neutral data center mandates create first-mover advantage for providers with renewable energy contracts.
- Digital twin convergence:Integration of physics simulation with machine learning training loops opens new service categories for industrial software vendors.
Industry Challenges
- Automotive AI talent scarcity:Shortage of engineers with combined vehicle systems and cloud infrastructure expertise constrains pipeline development at OEMs.
- Cross-border liability fragmentation:Unclear fault assignment between cloud operators and vehicle manufacturers under national traffic codes delays deployment decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe AI Cloud Computing in Automotive Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $29.41 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AI Platforms, Cloud Infrastructure, Integration Services, Data Management End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Deployment Model: Private Cloud, Public Cloud, Hybrid Cloud, Multi-Cloud Solution: Machine Learning, Data Analytics, AI Development Tools, Security Solutions |
| Companies Covered | Amazon Web Services, Microsoft Corporation, Google LLC, International Business Machines Corporation, SAP SE, Oracle Corporation, NVIDIA, Volkswagen Group, BMW Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe AI Cloud Computing in Automotive Market Trends and Innovations
Federated learning architectures and sovereign cloud mandates are redrawing competitive boundaries, while procurement patterns tilt toward vertically integrated validation stacks.
Containerized GPU orchestration is fragmenting the traditional separation between training infrastructure and inference deployment. Tier-1 suppliers now deploy unified clusters that handle both model development and real-time vehicle decision-making. This convergence is fragmenting vendor relationships as single-source platform deals replace multi-vendor best-of-breed procurement.
CSRD sustainability disclosure rules now extend to cloud supply chains used by automotive OEMs. Data center energy consumption and carbon intensity must be reported across Scope 3 emissions. German and French automakers are responding by inserting renewable energy clauses into long-term cloud contracts and prioritizing providers with certified green infrastructure.
Buying committees at European OEMs now consolidate cloud procurement under centralized IT governance rather than distributed engineering budgets. This centralization replaces project-based vendor selection with enterprise framework agreements spanning multiple vehicle programs. The shift is most visible at Volkswagen Group and BMW Group, where multi-year cloud commitments now lock in capacity before model launch cycles begin.
Europe AI Cloud Computing in Automotive Market Segmentation
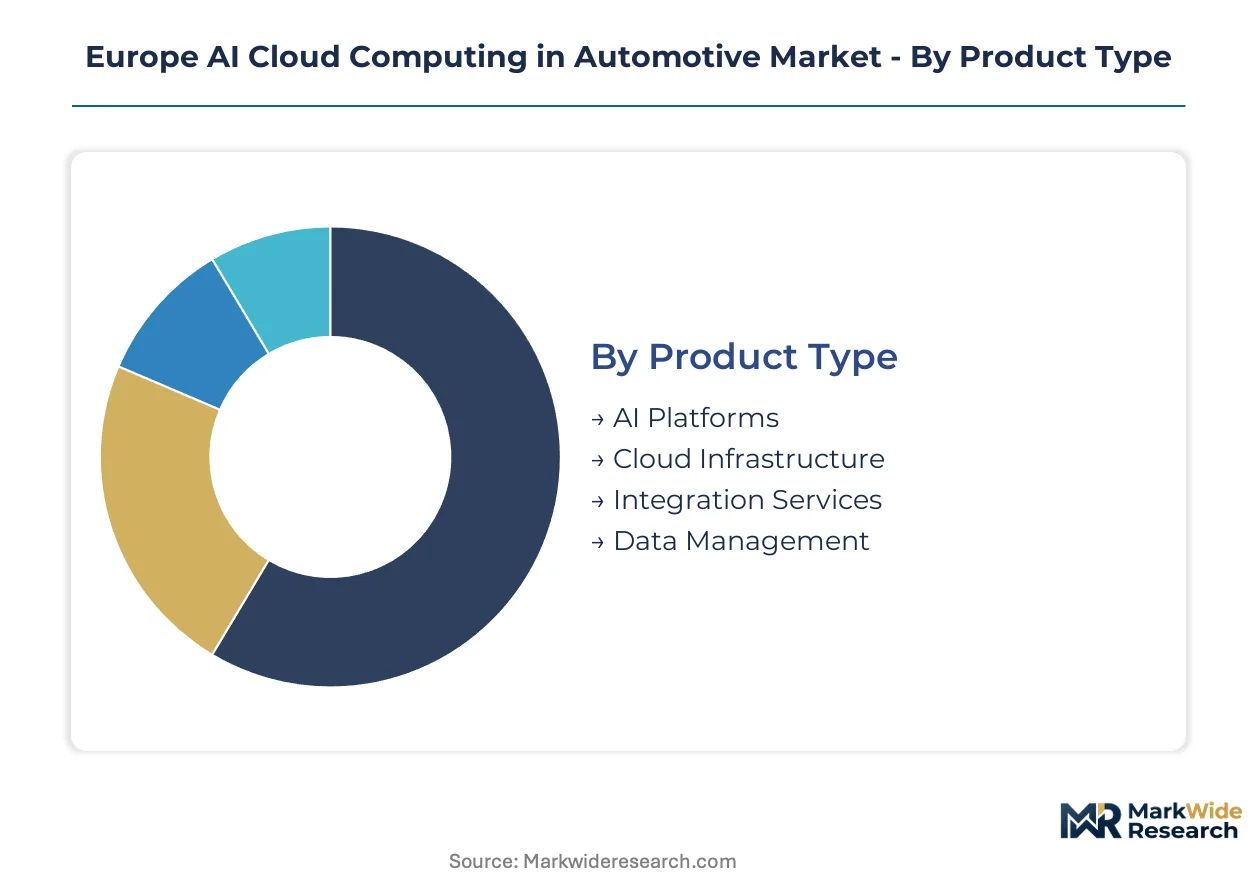
Segmentation reveals how AI cloud spending fragments across competing infrastructure models and buyer types. Each dimension exposes different margin pressures, regulatory exposure, and vendor lock-in dynamics that reshape procurement strategies across European automotive.
Product Type:
Substitution pressure intensifies as AI Platforms displace standalone integration services through bundled functionality.
- AI Platforms:Unified development environments combine model training, inference optimization, and MLOps pipelines into single-vendor stacks. German OEMs concentrate procurement here to satisfy EU AI Act auditability requirements for autonomous driving algorithms.
- Cloud Infrastructure:Containerized GPU clusters and high-throughput storage arrays handle multi-terabyte daily sensor feeds. France and Germany anchor demand as legacy data centers retrofit for AI training scale.
- Integration Services:Custom middleware and API bridging solutions connect automotive ERP systems with cloud AI workloads. Mid-tier vehicle assemblers in Eastern Europe drive residual demand where in-house integration capabilities remain limited.
- Data Management:Sovereign data lakes and GDPR-compliant governance tools manage cross-border telemetry flows. Italian transport regulators now mandate localized storage architectures for connected vehicle fleets.
Cloud Infrastructure anchors the volume base while AI Platforms gains share at the steepest rate.
End User:
Cost tier segmentation separates enterprise-scale buyers from price-sensitive mid-market participants.
- OEMs:Volkswagen Group and BMW Group deploy centralized IT governance frameworks locking in multi-year cloud capacity before model launch cycles. These buyers command pricing leverage through consolidated procurement across vehicle programs.
- Tier-1 Suppliers:Continental and Bosch build proprietary AI validation pipelines that bypass traditional OEM cloud channels. Their burst compute needs favor hybrid architectures balancing regulatory data sovereignty with elastic scaling.
- Aftermarket Providers:Predictive maintenance and fleet optimization vendors consume inference-as-a-service at lower commitment levels. Polish and Romanian cloud regions attract these buyers through cost arbitrage against Western European infrastructure.
- Vehicle Assemblers:Contract manufacturers and niche EV producers adopt pay-as-you-go public cloud models to avoid capital-intensive private infrastructure investments.
OEMs anchor the volume base while Tier-1 Suppliers gains share at the steepest rate.
Deployment Model:
Application logic drives segmentation as latency-critical workloads demand edge-proximate infrastructure.
- Hybrid Cloud:Combines on-premises GPU clusters with burst capacity from sovereign cloud regions. Tier-1 suppliers favor this model to satisfy GDPR localization mandates while accessing elastic training resources.
- Private Cloud:Dedicated infrastructure within OEM-owned or colocation facilities processes sensitive autonomous driving training data. German KBA type-approval requirements reinforce preference for air-gapped environments.
- Public Cloud:Shared infrastructure delivers cost efficiency for non-critical workloads like infotainment personalization and supply chain analytics. Aftermarket providers and smaller assemblers concentrate here.
- Multi-Cloud:Orchestrated workloads across AWS, Azure, and European sovereign providers reduce vendor lock-in. Large OEMs adopt this approach to satisfy EU procurement diversification guidelines.
Private Cloud anchors the volume base while Hybrid Cloud expands most quickly.
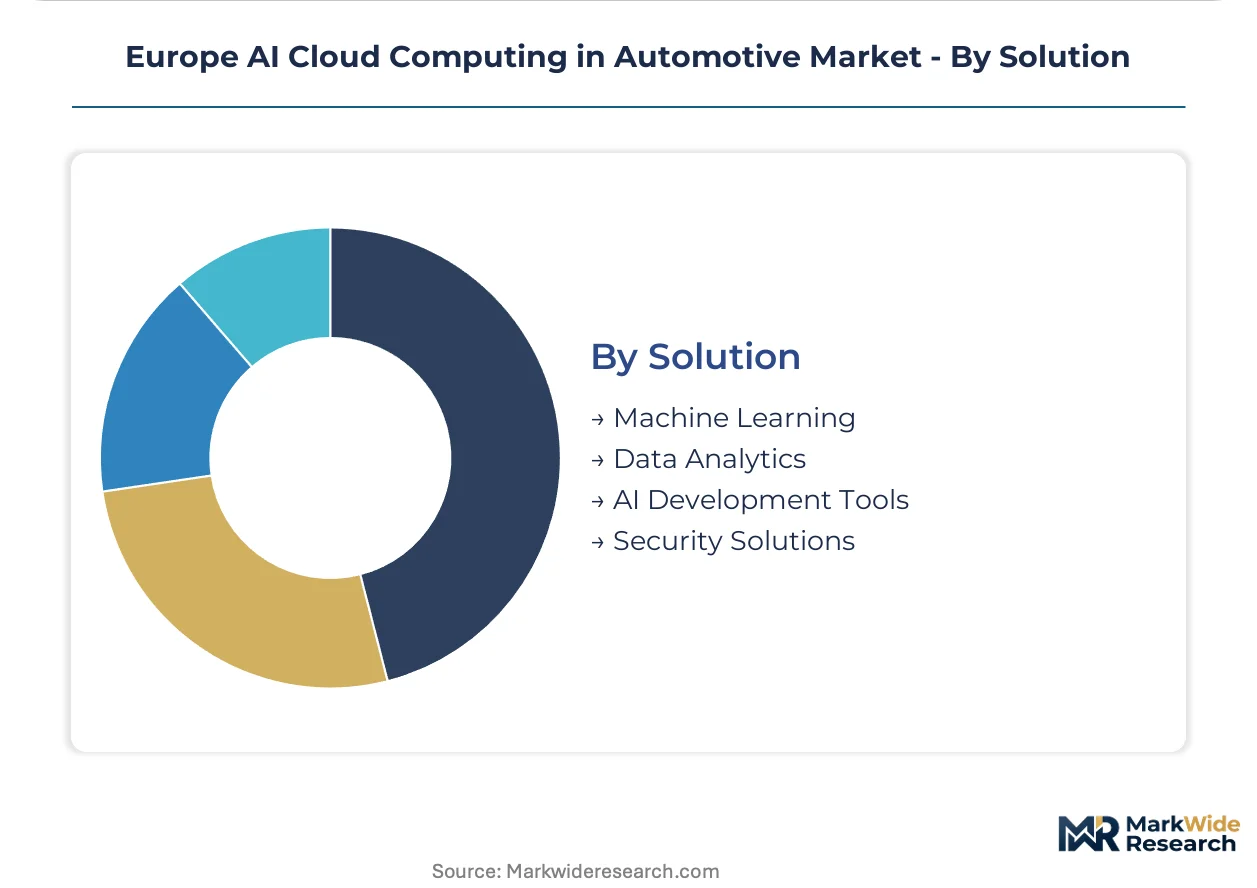
Solution:
Margin concentration follows technical differentiation as specialized automotive model development commands premium pricing.
- Machine Learning:Continuous retraining pipelines for perception, prediction, and planning algorithms consume the majority of cloud AI compute cycles. Specialized automotive model architectures and regulatory validation requirements sustain margin pools above commodity infrastructure.
- Security Solutions:Encrypted training environments, secure multi-party computation, and post-quantum cryptography address EMA cybersecurity mandates. French ANSM and German BSI standards now embed these capabilities into type-approval frameworks.
- Data Analytics:Fleet telemetry aggregation and manufacturing quality optimization leverage standard cloud data warehouse services. Pricing pressure intensifies as these capabilities commoditize across providers.
- AI Development Tools:Low-code model builders and synthetic data generation platforms accelerate prototyping for engineering teams with limited ML expertise. Tier-2 suppliers in Spain and Italy show concentrated adoption.
Machine Learning anchors the volume base while Security Solutions climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure investment clusters around German automotive manufacturing corridors, with sovereign data center expansion radiating outward to France, Italy, and Eastern European cost arbitrage zones. National transport regulators in Germany, France, and Italy coordinate type-approval standards that embed data governance into vehicle AI systems. Each jurisdiction imposes distinct compliance layers on cloud architecture decisions.
Germany
KBA type-approval requirements and the EU AI Act's risk-classification mandates compel Volkswagen Group and BMW Group to maintain auditable training pipelines within national boundaries. The BSI embeds cybersecurity standards into vehicle certification frameworks. Bavaria's Munich-Stuttgart corridor anchors GPU cluster investments at manufacturing hubs processing multi-terabyte daily sensor feeds.
France
ANSM coordination with EMA transport divisions extends cybersecurity validation cycles for autonomous driving algorithms deployed via cloud infrastructure. CSRD sustainability disclosure rules now extend to cloud supply chains, forcing renewable energy clauses into long-term contracts. The Paris-Saclay cluster concentrates AI development talent alongside automotive OEM headquarters in Île-de-France.
Italy
Italian transport regulators mandate localized storage architectures for connected vehicle fleets, pushing aftermarket providers toward sovereign cloud regions. GDPR cross-border telemetry restrictions create captive markets for EU-based data center operators. Turin and Milan anchor Tier-1 supplier engineering centers building proprietary AI validation pipelines.
Poland
Lower-cost sovereign infrastructure outside core Western European markets attracts Tier-2 suppliers and vehicle assemblers seeking pay-as-you-go public cloud models. The country's central location supports latency optimization for Eastern European connected vehicle fleets. Warsaw and Krakow data center zones expand GPU capacity for burst compute needs.
United Kingdom
Post-Brexit regulatory divergence creates parallel compliance tracks for automotive AI systems serving EU and UK markets simultaneously. The Information Commissioner's Office enforces GDPR-equivalent data localization requirements for telemetry flows. Midlands automotive engineering clusters and London cloud regions split workload between training infrastructure and inference deployment.
Europe AI Cloud Computing in Automotive Market Competitive Landscape
Concentration sits with hyperscale cloud providers and specialized silicon vendors that control the underlying compute substrate for automotive AI workloads. The vendor base stratifies across three tiers: infrastructure operators owning physical data center assets, platform vendors bundling development environments, and integration specialists bridging legacy automotive systems. Strategic moves center on multi-year enterprise framework agreements and sovereign cloud region expansion to satisfy data residency mandates.
Within the hyperscale infrastructure tier, Amazon Web Services, Microsoft Corporation, and Google LLC exemplify platform consolidation through GPU-optimized automotive workloads and industrial cloud footprints securing long-term contracts with German and French automakers. NVIDIA occupies a distinct position anchoring specialized silicon supply for European edge facilities. SAP SE represents the enterprise integration archetype embedding automotive-specific modules into existing ERP environments. These players illustrate how vendor relationships fragment as single-source platform deals replace multi-vendor procurement.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Corporation |
| Google LLC |
| International Business Machines Corporation |
| SAP SE |
| Oracle Corporation |
| NVIDIA |
| Volkswagen Group |
| BMW Group |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day lead times for NVIDIA H100 GPU allocations concentrate pricing power with hyperscale cloud providers serving German automotive OEMs, compressing margin capture at Tier-1 suppliers dependent on spot capacity markets. This inventory scarcity reinforces long-term framework agreements as the dominant procurement mechanism across European sovereign cloud regions.
Pricing Analysis
The EU AI Act dictates the pricing tier structure across European automotive cloud markets, mandating auditability premiums for autonomous driving workloads. Pricing stratifies across sovereign-certified, GDPR-compliant, and standard public cloud tiers, with certification level and data residency requirements driving differentiation. Cost compression in standard inference services is intensifying due to commodity GPU availability, while burst compute for training remains price-inelastic. Vehicle assemblers in Eastern Europe exhibit highest price sensitivity; Volkswagen Group and BMW Group command volume leverage that flattens tier premiums.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for Taiwanese and South Korean GPU shipments, extending deployment timelines for European edge facilities. Supply concentration centers on Taiwan for advanced silicon, Ireland and Netherlands for EU-based data center infrastructure, and Germany for automotive systems integration. The chain draws from specialized AI accelerators, liquid cooling components, and sovereign-certified server hardware. Single-source vulnerability around NVIDIA silicon creates structural risk. Distribution runs through hyperscale cloud providers with direct OEM framework agreements, bypassing traditional systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe AI Cloud Computing in Automotive sits in early-cycle expansion driven by EU AI Act compliance deadlines, with procurement volumes accelerating ahead of 2025-2026 model launch cycles.
For Market Incumbents: Compound defensive positioning through captive renewable energy contracts that satisfy CSRD Scope 3 disclosure requirements and lock in sovereign cloud capacity before Polish and Romanian region saturation. Prioritize backward integration into specialized automotive MLOps tooling to offset margin erosion from commoditized infrastructure tiers. The threat of Tier-1 supplier bypass demands vertical control over validation pipeline software. For New Entrants and Emerging Players: Sovereign data lake governance for mid-tier Italian and Spanish vehicle assemblers represents the most penetrable service-layer gap, as hyperscalers under-serve localized GDPR compliance tooling. Target pay-as-you-go inference services for aftermarket fleet optimization vendors concentrated in Polish cloud regions. A channel partnership with established Tier-2 systems integrators accelerates credentialing with risk-averse OEM procurement committees. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because EU AI Act and GDPR mandates create durable moats around compliant infrastructure providers. Acquisition targets should exhibit sovereign certification depth and automotive-specific model development capabilities. Watch EMA-KBA-ANSM regulatory coordination intensity as the inflection signal for compliance spend acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Region Expansion | GDPR localization mandates in Germany and France require EU-boundary data center investments. |
| GPU-Optimized Automotive Workload Partnerships | NVIDIA's silicon dominance forces long-term capacity commitments from Volkswagen Group and BMW Group. |
| CSRD-Aligned Renewable Energy Contracting | German automakers insert carbon-neutral clauses into multi-year cloud infrastructure agreements. |
| Vertical AI Validation Pipeline Integration | Continental and Bosch bypass OEM procurement through proprietary MLOps infrastructure buildouts. |
| 5G Edge Gateway Deployment at Manufacturing Hubs | Sub-50ms latency requirements drive GPU cluster co-location with Stuttgart and Munich automotive corridors. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with cloud procurement officers at German and French OEMs, Tier-1 supplier platform engineers, and sovereign data center operators; and secondary validation against EMA regulatory filings, EU AI Act implementation guidance, hyperscaler capex disclosures, and vehicle production databases from IHS Markit. Stakeholder conversations spanned Volkswagen Group, BMW Group, Continental, and Bosch technical leadership alongside AWS, Microsoft Azure, and Google Cloud automotive vertical teams. Bottom-up capacity deployment estimates triangulated against top-down market sizing from infrastructure investment tracking.
Across the analysis window, forecasts employed a segmented growth framework modeling deployment model adoption curves, solution type margin trajectories, and end-user procurement consolidation patterns. Segmentation dimensions included product type, end user archetype, deployment architecture, and solution category alongside vehicle program scale and regional regulatory cluster intensity. CAGRs derived from capacity expansion pipelines, OEM cloud commitment disclosures, and AI training workload density assumptions. Industry-specific inputs encompassed KBA type-approval timelines and GDPR cross-border telemetry restriction enforcement patterns.
Forecasts assume regulatory continuity in EU AI Act risk-classification regimes and EMA-KBA-ANSM coordination frameworks; material policy shifts or Brexit-related divergence would require re-modeling. Specific risks include GPU supply concentration disruption, legacy data center retrofit cost overruns, and cross-border liability fragmentation under national traffic codes. Practitioners should keep alternative scenarios live as sovereign cloud region buildout timelines and Tier-1 supplier vertical integration intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud CDN Market
Cloud Computing
Global Cloud/Mobile Backend AS a Service (Baas) Market
Cloud Computing
Automotive Cloud Based System Market
Cloud Computing
Automotive Cloud Based Solutions Market
Cloud Computing
Cloud Enterprise Content Management Market
Cloud Computing
Global Multi Cloud Management Market
Cloud Computing
Multi-Cloud Architecture Market
Cloud Computing
France Cloud Computing Market
Cloud Computing
Cloud Directory Services Market
Cloud Computing
Bare Metal Cloud Service Market
Cloud Computing
Cloud IT Service Management (ITSM) Market
Cloud Computing
Cloud Based Backup Services Market
Cloud Computing
Cloud API Market
Cloud Computing
Global Cloud Computing Iaas in Life Science Market
Cloud Computing
Web Service Cloud Market
Cloud Computing
China Cloud Computing Market